
 Hyperscale Computing Market | 2026-2036
Hyperscale Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperscale Computing Market Outlook
Buyer concentration among cloud-native enterprises is hardening as fewer mega-tenants consume disproportionate infrastructure capacity. Amazon Web Services leverages its custom silicon program to reduce reliance on third-party chip suppliers. Microsoft Azure anchors its expansion through strategic data center placements across sovereign cloud zones. Google Cloud Platform differentiates via deep integration of container orchestration with its proprietary networking fabric.
Hyperscale computing denotes distributed IT architectures designed to scale compute, storage, and networking resources horizontally across thousands of commodity servers, typically operating at power densities exceeding 50 kilowatts per rack to support artificial intelligence training and inference workloads. Public cloud deployments command the largest revenue share among deployment models, though multi-cloud configurations are gaining traction as enterprises seek workload portability and vendor risk mitigation. Infrastructure-as-a-Service retains the dominant position within service types, while platform-as-a-service offerings capture expanding margin pools among developers building cloud-native applications.
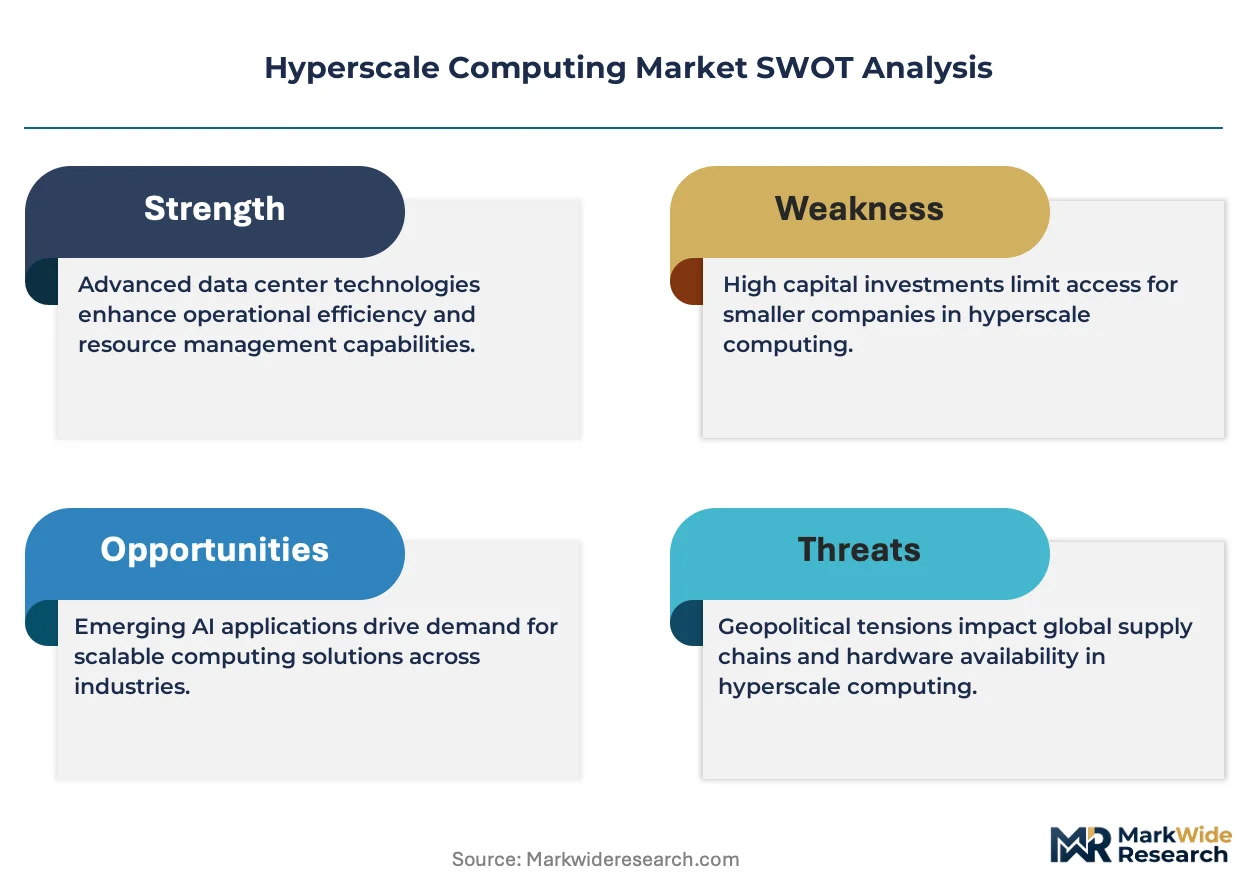
The EU AI Act imposes transparency obligations on hyperscale providers hosting high-risk automated systems, directly affecting product roadmaps and customer onboarding protocols. In the United States, NIST cybersecurity frameworks and state-level data privacy statutes create overlapping compliance matrices that shape infrastructure investment priorities. China's MIIT enforces local data residency mandates through GB standards that restrict cross-border data flows for hyperscale operators. Stakeholders must monitor the divergence between sovereign cloud requirements and unified global architectures as the primary strategic tension.
Market Dynamics
Horizontal scaling architectures are displacing vertical server consolidation as AI training clusters demand power densities exceeding 100 kilowatts per rack, forcing wholesale redesigns of cooling infrastructure and electrical distribution across facility portfolios.
Growth Catalysts
- GPU Cluster Density:Financial services firms deploy real-time risk analytics on thousand-node GPU clusters, consuming hyperscale capacity in Northern Virginia and Dallas-Fort Worth corridors.
- EU AI Act Transparency Mandates:Automated decision-making systems require auditable infrastructure trails, creating compliance-driven refresh cycles for high-risk AI hosting environments.
- Liquid Cooling Adoption:Direct-to-chip and immersion cooling systems enable sustained 50+ kW rack deployments without thermal throttling of AI accelerators.
Market Restraints
- Power Grid Saturation:Utility interconnection queues in Northern Virginia extend 36-48 months, capping facility expansion velocity regardless of capital availability.
- Custom Silicon Concentration:Three vertically integrated cloud providers control 90%+ of AI-optimized accelerator design, creating supply bottleneck risk for multi-tenant operators.
- GB Standards Data Residency:China's MIIT mandates local storage for designated data categories, fragmenting global workload orchestration and duplicating infrastructure footprints.
Strategic Opportunities
- Sovereign Cloud Zones:Germany, France, and Spain require domestic data processing for public sector and regulated industries, creating greenfield facility demand outside established FLAP markets.
- Edge Inference Satellites:5G MEC nodes and factory-floor AI inferencing extend hyperscale architectures into sub-10 millisecond latency zones previously served by centralized facilities.
- Carbon-Free Energy Matching:24/7 carbon-free electricity contracts with utilities and renewable developers differentiate facility offerings for sustainability-mandated enterprise tenants.
Industry Challenges
- Electrical Infrastructure Talent:High-voltage substation design and medium-voltage switchgear commissioning expertise concentrates among retiring utility engineers, constraining project staffing.
- Multi-Cloud Orchestration Complexity:Kubernetes federation across AWS, Azure, and GCP control planes requires specialized platform engineering capabilities scarce outside hyperscale-native enterprises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperscale Computing Market |
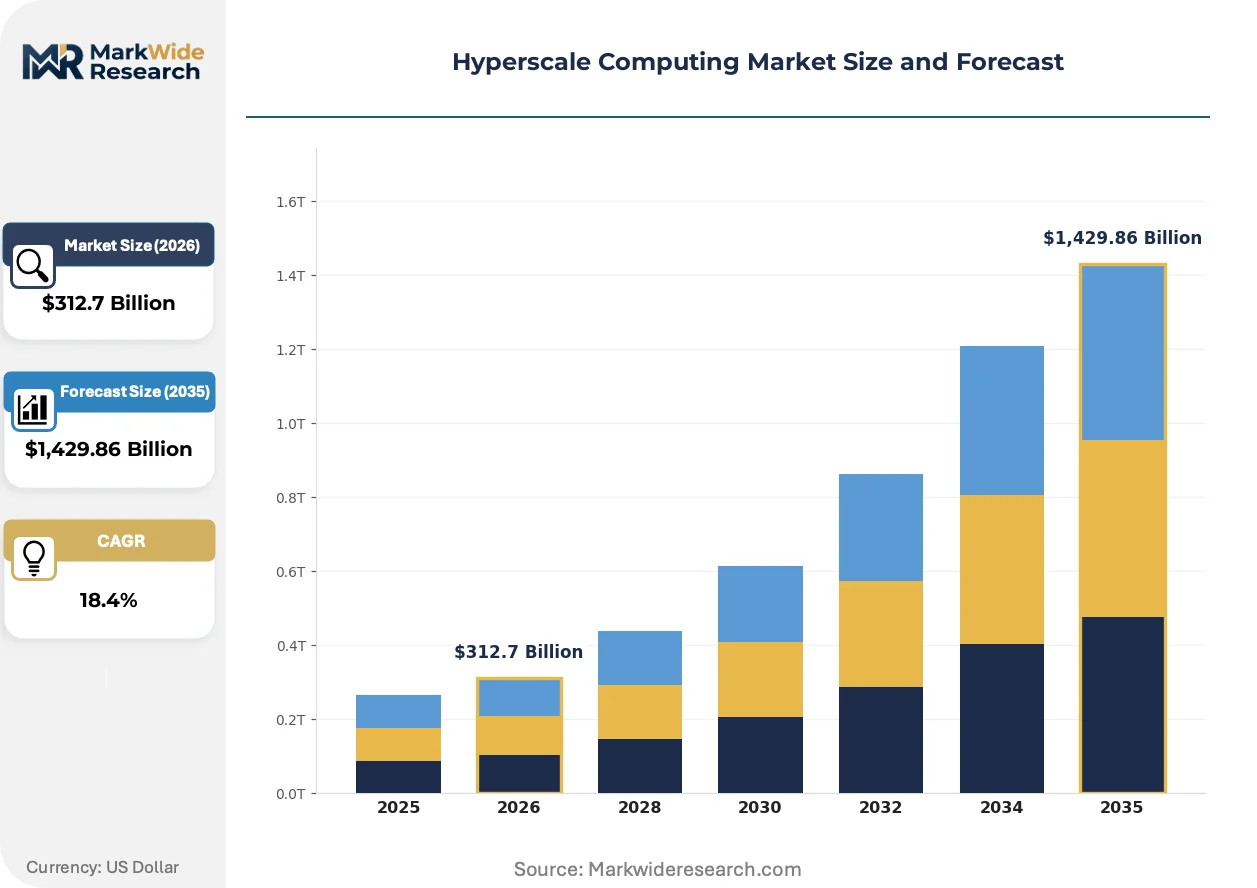
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $1,429.86 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, DaaS End User: Enterprises, Service Providers, Government, Educational Institutions Technology: Containers, Virtualization, Microservices, Edge Computing |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud Platform, Oracle Corporation, Hewlett Packard Enterprise, IBM Corporation, Meta, Apple, Alibaba Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperscale Computing Market Strategic Shifts
Workload portability requirements and sovereign data mandates are fragmenting previously centralized cloud architectures into distributed, compliance-bound infrastructure topologies.
Direct liquid cooling is overtaking air-cooled designs as the default thermal architecture for AI training facilities. Hyperscale operators in Northern Virginia and Phoenix deploy immersion tanks and cold plates to sustain 100+ kW rack densities. This shift is compressing mechanical infrastructure capital intensity while extending facility design lifecycles beyond traditional 15-year depreciation schedules.
The EU AI Act imposes documentation and human oversight requirements on high-risk automated systems hosted in hyperscale environments. Providers must implement model registries, bias testing protocols, and audit trails by deployment type. European financial services and healthcare AI workloads face the steepest compliance ramps, driving demand for sovereign-annotated infrastructure tiers.
Consumption-based contracting now dominates enterprise infrastructure procurement, displacing reserved capacity commitments. Retail, logistics, and media verticals in the United States and Western Europe favor pay-per-compute-second models with automatic scaling boundaries. This pattern concentrates revenue volatility risk with facility operators while transferring demand forecasting burden to tenant workload predictability.
Hyperscale Computing Market Segmentation
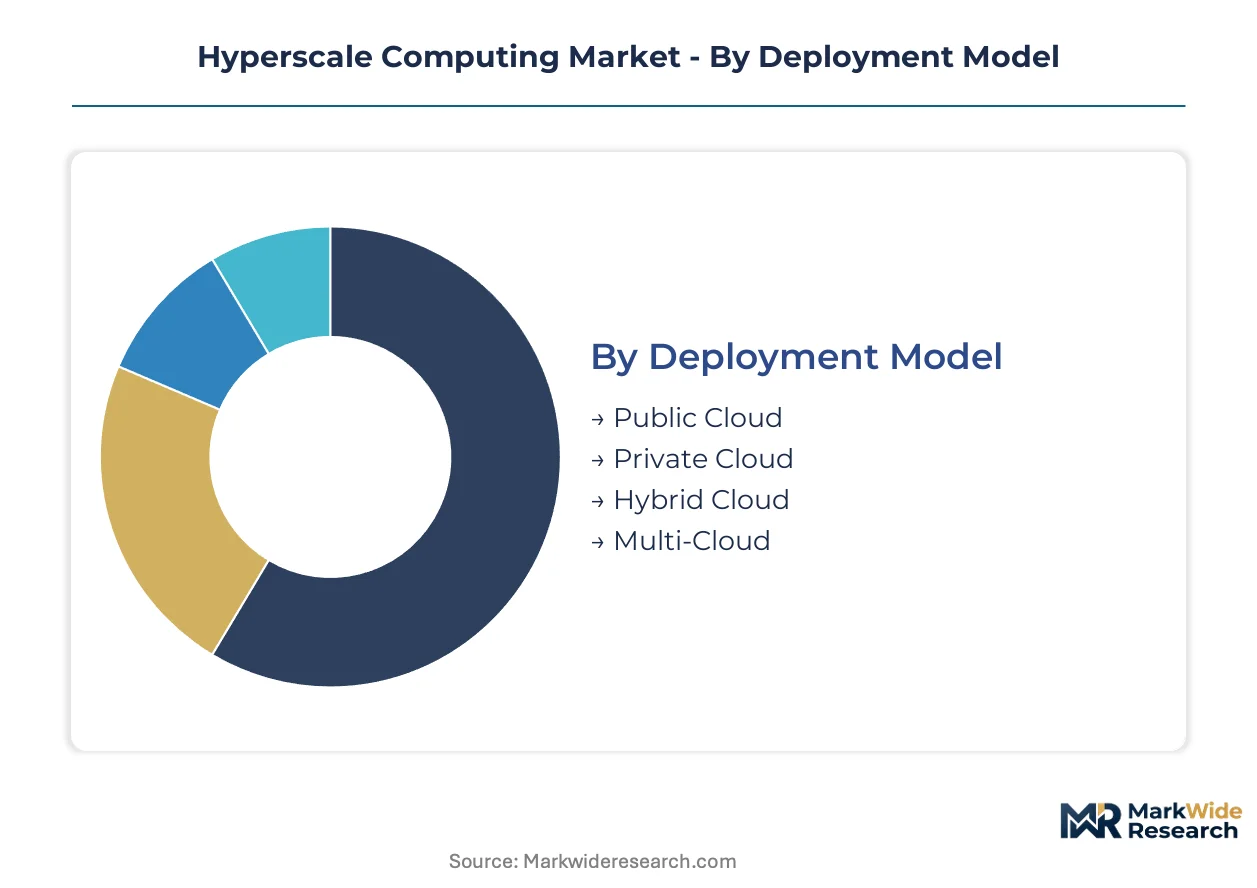
Hyperscale computing infrastructure exhibits divergent capital intensity across deployment architectures and service layers. Procurement patterns concentrate where power density requirements and compliance mandates intersect, creating tiered investment thresholds across the market landscape.
Deployment Model:
Capital intensity escalates dramatically with operational control requirements, from shared public infrastructure to sovereign-annotated private facilities.
- Public Cloud:Shared infrastructure pools deliver compute, storage, and networking through standardized APIs with minimal tenant capital outlay. Financial services firms in Northern Virginia and Dallas-Fort Worth corridors consume disproportionate capacity for real-time risk analytics workloads.
- Multi-Cloud:Workload portability across AWS, Azure, and GCP control planes demands sophisticated orchestration tooling and redundant data egress pathways. Enterprises seeking vendor risk mitigation drive adoption despite elevated platform engineering costs.
- Private Cloud:Dedicated hyperscale facilities serving single tenants require full capital commitment for power, cooling, and server infrastructure.
- Hybrid Cloud:Split architectures combining on-premises capacity with burst-to-cloud elasticity impose dual infrastructure maintenance burdens.
Public cloud absorbs the bulk of installed capacity; multi-cloud is expanding most quickly.
Service Type:
Margin structure varies inversely with abstraction depth, as infrastructure commoditization yields to platform differentiation and software value capture.
- IaaS:Bare-metal compute, storage, and networking resources provisioned through programmatic interfaces. Northern Virginia utility interconnection queues extending 36-48 months constrain expansion velocity for wholesale capacity providers.
- PaaS:Managed runtime environments, container orchestration, and developer tooling abstract infrastructure complexity. Cloud-native application builders in Western Europe favor consumption-based contracting with automatic scaling boundaries.
- SaaS:Fully managed software applications eliminate operational burden through subscription economics.
- DaaS:Desktop virtualization streams compute and graphics workloads to endpoint devices without local processing.
IaaS dominates revenue volume; PaaS demonstrates the steepest margin expansion trajectory.
End User:
Procurement sophistication and compliance burden shape segment-specific infrastructure requirements across tenant categories.
- Enterprises:Large organizations with dedicated platform engineering teams negotiate consumption-based contracts with granular scaling controls. Retail, logistics, and media verticals favor pay-per-compute-second models transferring demand forecasting risk to operators.
- Government:Sovereign data mandates in Germany, France, and Spain require domestic processing facilities for public sector workloads.
- Service Providers:Resellers and managed service operators aggregate demand across downstream tenants.
- Educational Institutions:Research universities deploy GPU clusters for AI training with grant-funded capital cycles.
Enterprises command the largest capacity allocation; government procurement is climbing the fastest.
Technology:
Thermal and latency constraints determine architectural suitability for specific workload profiles.
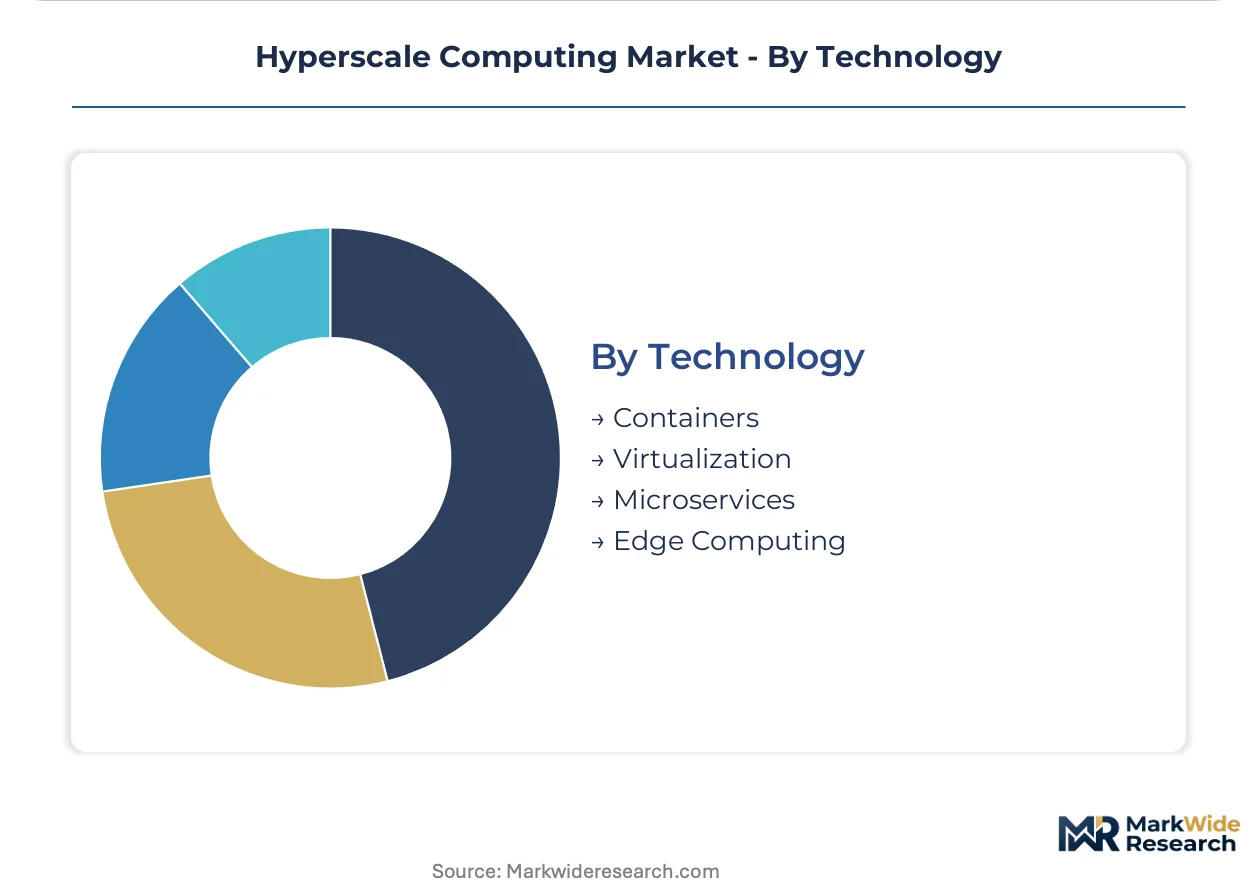
- Containers:Lightweight virtualization packages applications with dependencies for consistent deployment across environments. Direct liquid cooling adoption enables sustained 50+ kilowatt rack densities without thermal throttling of AI accelerators.
- Edge Computing:Distributed processing nodes extend hyperscale architectures into sub-10 millisecond latency zones. 5G MEC deployments and factory-floor inference satellites create greenfield demand outside centralized facility footprints.
- Virtualization:Hypervisor-based resource abstraction remains prevalent for legacy workload migration.
- Microservices:Decoupled application architectures enable independent scaling of functional components.
Container infrastructure represents the dominant deployment paradigm; edge computing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale computing demand concentrates in the United States, where financial services and AI training workloads consume disproportionate infrastructure capacity. Utility interconnection queues and data residency mandates are reshaping facility investment patterns across major markets.
United States
Financial services firms deploy thousand-node GPU clusters for real-time risk analytics in Northern Virginia and Dallas-Fort Worth corridors. NIST cybersecurity frameworks and state-level data privacy statutes create overlapping compliance requirements. Utility interconnection queues in Northern Virginia extend 36-48 months, capping expansion velocity regardless of capital availability.
China
Domestic cloud operators build AI training facilities to serve national artificial intelligence development priorities. MIIT enforces local data residency mandates through GB standards that restrict cross-border data flows. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate hyperscale development under sovereign cloud requirements.
Germany
Sovereign cloud zones attract public sector and regulated industry workloads requiring domestic data processing. EU AI Act transparency obligations reshape compliance requirements for automated decision-making systems. Frankfurt and Munich anchor facility investment outside established FLAP markets.
United Kingdom
Financial services and media technology tenants favor consumption-based contracting with automatic scaling boundaries. GDPR and emerging AI governance frameworks impose documentation requirements on high-risk automated systems. London and Southeast England concentrate demand for low-latency inference workloads.
India
Cloud-native enterprises and managed service providers expand hyperscale deployments to serve domestic digital transformation. TRAI and RBI regulations shape data localization requirements for financial services workloads. Mumbai and Bengaluru anchor facility development for sub-10 millisecond latency zones.
Hyperscale Computing Market Competitive Environment
United States providers anchor the premium tier through custom silicon programs and vertical integration strategies; European and Asian specialists hold positions in sovereign cloud and regional compliance segments. The market structure concentrates around three vertically integrated operators controlling AI-optimized accelerator design, with multi-tenant and regional players occupying specialized niches. Strategic archetypes include full-stack integrators, sovereign cloud specialists, and edge inference operators. Competitive moves center on custom silicon development and sovereign facility placement.
Within the full-stack integrator tier, Amazon Web Services, Microsoft Azure, and Google Cloud Platform exemplify the vertically integrated model through captive supply of AI accelerators and proprietary networking fabrics. These entities occupy positions where infrastructure scale, custom silicon design, and platform services converge. Alibaba Cloud anchors the Asia-Pacific regional specialist archetype, serving domestic data residency requirements through local facility footprints.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud Platform |
| Oracle Corporation |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Meta |
| Apple |
| Alibaba Cloud |
| Others |
Value Chain & Pricing Dynamics
Direct liquid cooling retrofits across Northern Virginia and Dallas-Fort Worth facilities simultaneously compress mechanical capital intensity and concentrate procurement leverage among three vertically integrated cloud operators controlling AI-optimized accelerator design. This production-method transition forces multi-tenant operators into consumption-based contracts that transfer demand forecasting risk downstream while pricing power accumulates with captive silicon suppliers.
Pricing Analysis
Volume concentrates in Infrastructure-as-a-Service tiers while margin expansion accrues to Platform-as-a-Service offerings with managed runtime environments. Three-tier pricing structure across sovereign-annotated, enterprise-grade, and commodity public cloud levels differentiates by compliance certification and latency performance. Cost compression in wholesale capacity is intensifying because utility interconnection queues extend 36-48 months regardless of capital availability. Retail and logistics verticals exhibit highest price sensitivity with pay-per-compute-second preferences; financial services firms show lowest sensitivity due to real-time risk analytics requirements.
Supply Chain Analysis
China's MIIT local-content mandates through GB standards reshape sourcing patterns for cross-border data flows, fragmenting global workload orchestration. Taiwan, South Korea, and the United States anchor supply for advanced AI accelerators, high-bandwidth memory modules, and custom networking fabrics. Raw material dependencies center on neon gas for lithography, cobalt for power distribution, and specialized coolant chemistries for immersion systems. Single-source vulnerability concentrates in high-voltage substation design expertise among retiring utility engineers. Distribution runs through direct hyperscale operator procurement with long-term offtake agreements displacing spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Utility interconnection queues capping facility expansion velocity prop pricing power for existing capacity holders, creating supply-constrained conditions that favor incumbents with secured power allocations over aspirant entrants.
For Market Incumbents: Deepen captive silicon programs to reduce third-party accelerator dependency as custom chip concentration reaches 90% among three vertically integrated operators. Secure 24/7 carbon-free electricity contracts with utilities to differentiate sovereign cloud offerings in Germany, France, and Spain. Expand liquid cooling infrastructure portfolios before thermal throttling limits constrain competitor rack densities. For New Entrants and Emerging Players: Edge inference satellites deploying 5G MEC nodes offer the most penetrable white-space target as latency requirements fragment centralized architectures. Sovereign cloud zones outside established FLAP markets present second-tier entry points with domestic data processing mandates. Target platform engineering capabilities for Kubernetes federation across AWS, Azure, and GCP control planes as scarce talent concentrates demand. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical integration plays by hyperscale operators seeking electrical infrastructure talent and medium-voltage switchgear commissioning expertise. Long-term viability favors facility operators with secured utility interconnection agreements and sovereign-annotated infrastructure tiers. Watch utility queue clearing velocity in Northern Virginia as the primary inflection indicator for expansion capacity availability.| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Development | Captive AI accelerator design reduces dependency on third-party chip suppliers for AWS, Azure, and GCP. |
| Sovereign Cloud Facility Placement | Domestic data processing mandates in Germany, France, and Spain create greenfield demand outside FLAP markets. |
| Liquid Cooling Infrastructure Retrofit | Direct-to-chip and immersion systems enable sustained 100+ kilowatt rack densities without thermal throttling. |
| 24/7 Carbon-Free Energy Contracting | Renewable utility agreements differentiate facility offerings for sustainability-mandated enterprise tenants. |
| Platform Engineering Capability Buildout | Kubernetes federation expertise addresses multi-cloud orchestration complexity scarce outside hyperscale-native enterprises. |
Study Parameters
Document review covered SEC filings from hyperscale operators, EIA power grid data, EU regulatory submissions, and MIIT GB standards documentation, complemented by interviews with data center facility directors, cloud platform engineers, utility interconnection planners, and enterprise IT procurement officers. Secondary validation drew from hyperscaler capex disclosures, FERC interconnection queue reports, and sovereign cloud framework documents. Bottom-up capacity modeling triangulated against top-down market sizing across deployment architectures.
Cross-reference between historical facility deployment patterns and expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, service type abstraction depth, end-user compliance burden, and thermal architecture requirements. CAGRs derived from capacity expansion trajectories, power density evolution curves, and sovereign mandate implementation timelines. AI training cluster density requirements and liquid cooling adoption curves served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen breakthroughs in quantum computing architectures, abrupt shifts in national data residency enforcement, and utility grid modernization accelerations. Forecasts reflect assumptions about sustained AI workload growth, stable regulatory enforcement patterns, and gradual supply chain localization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Global Digital Twin Technology Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
AI Edge Computing Market
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
Metal Additive Manufacturing Systems Market