
 LED Encapsulation Market | 2026-2036
LED Encapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
LED Encapsulation Market Outlook
High-reliability automotive-grade specifications is bifurcating the LED encapsulation landscape into premium thermal-stable tiers and cost-optimized general illumination grades. Dow Inc. leverages its silicone chemistry portfolio to anchor supply relationships with tier-one automotive lighting suppliers. Shin-Etsu Chemical Co., Ltd. sustains dominant positions in high-purity silicone materials through captive organosilicon feedstock control. Wacker Chemie AG differentiates via specialized UV-curable formulations serving European display manufacturers.
LED encapsulation denotes the protective material layer—typically silicone, epoxy, or polyurethane—applied over LED chips to shield against moisture, mechanical stress, and thermal degradation while maintaining optical transparency above 90% in the visible spectrum. The process determines lumen maintenance, color stability, and operating lifespan across display, backlighting, signage, and decorative installations. Silicone encapsulants command the premium tier due to superior thermal conductivity and yellowing resistance in high-flux applications. Epoxy retains cost-sensitive volume in consumer electronics backlighting where thermal loads remain moderate. Resin formulations occupy a narrowing middle ground as polyurethane gains traction in flexible decorative lighting strips.
REACH and RoHS frameworks in Europe restrict hazardous substance content in encapsulant chemistries, while China's MEE enforces volatile organic compound emission controls at formulation plants. The EU F-Gas Regulation indirectly shapes material selection by pressuring manufacturers toward lower-global-warming-potential curing processes. Japan's METI energy efficiency standards for lighting products cascade into stricter thermal performance requirements for encapsulation materials. Stakeholders must monitor evolving chemical compliance thresholds and thermal conductivity benchmarks as automotive electrification intensifies junction temperature demands.
Market Dynamics
Automotive electrification is compressing thermal tolerance windows for LED encapsulants, forcing simultaneous upgrades in thermal conductivity specifications and yellowing resistance without cost inflation. Tier-one automotive lighting suppliers now demand silicone formulations rated for 150°C junction temperatures, a threshold that eliminates legacy epoxy options from headlamp applications.
Growth Catalysts
- China's dual carbon goals:National efficiency mandates accelerate replacement of mercury vapor and halogen fixtures with LED systems, expanding addressable volume for high-reliability encapsulants in commercial and industrial retrofit projects.
- Automotive headlamp electrification:Adaptive driving beam and matrix LED architectures multiply chip counts per vehicle, increasing encapsulant consumption per unit while elevating thermal performance requirements.
- Silicone chemistry advances:Dow Corning and Shin-Etsu have commercialized platinum-catalyzed addition cure systems with thermal conductivity exceeding 1.5 W/mK, enabling thinner encapsulation layers without heat dissipation penalties.
Market Restraints
- Organosilicon feedstock concentration:High-purity chlorosilane production clusters in China's Xinjiang and Japan's Niigata prefecture, creating geographic single-point vulnerability for premium encapsulant supply chains.
- Platinum catalyst cost volatility:Silicone encapsulant formulations depend on platinum group metals for hydrosilylation curing, exposing margin structures to London Metal Exchange price swings.
- Epoxy substitution floor:Consumer electronics backlighting retains cost-optimized epoxy encapsulants for thermal loads below 85°C, capping silicone penetration in high-volume display applications.
Strategic Opportunities
- Mini-LED and micro-LED display fabrication:Chip-scale packaging architectures for television and automotive displays demand precision-dispensed encapsulation with sub-10 micrometer thickness control, opening premium formulation tiers.
- India's PLI scheme for LED manufacturing:Production-linked incentives for domestic lighting component fabrication attract encapsulant formulators to establish compounding operations in Gujarat and Tamil Nadu manufacturing corridors.
- UV-curable silicone development:Wacker Chemie and Momentive have piloted cationic UV cure systems eliminating thermal oven processing, reducing energy consumption and enabling inline coating of flexible LED strips.
Industry Challenges
- Automotive-grade qualification timelines:AEC-Q100 and OEM-specific validation protocols demand 3,000-hour thermal aging tests and 85°C/85%RH humidity exposure, stretching new product introduction cycles to 24-36 months.
- Formulation-to-application process integration:Encapsulant suppliers must coordinate viscosity profiles with customer dispensing equipment—jetting, needle dispensing, or mold transfer—to prevent void formation and delamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Encapsulation Market |
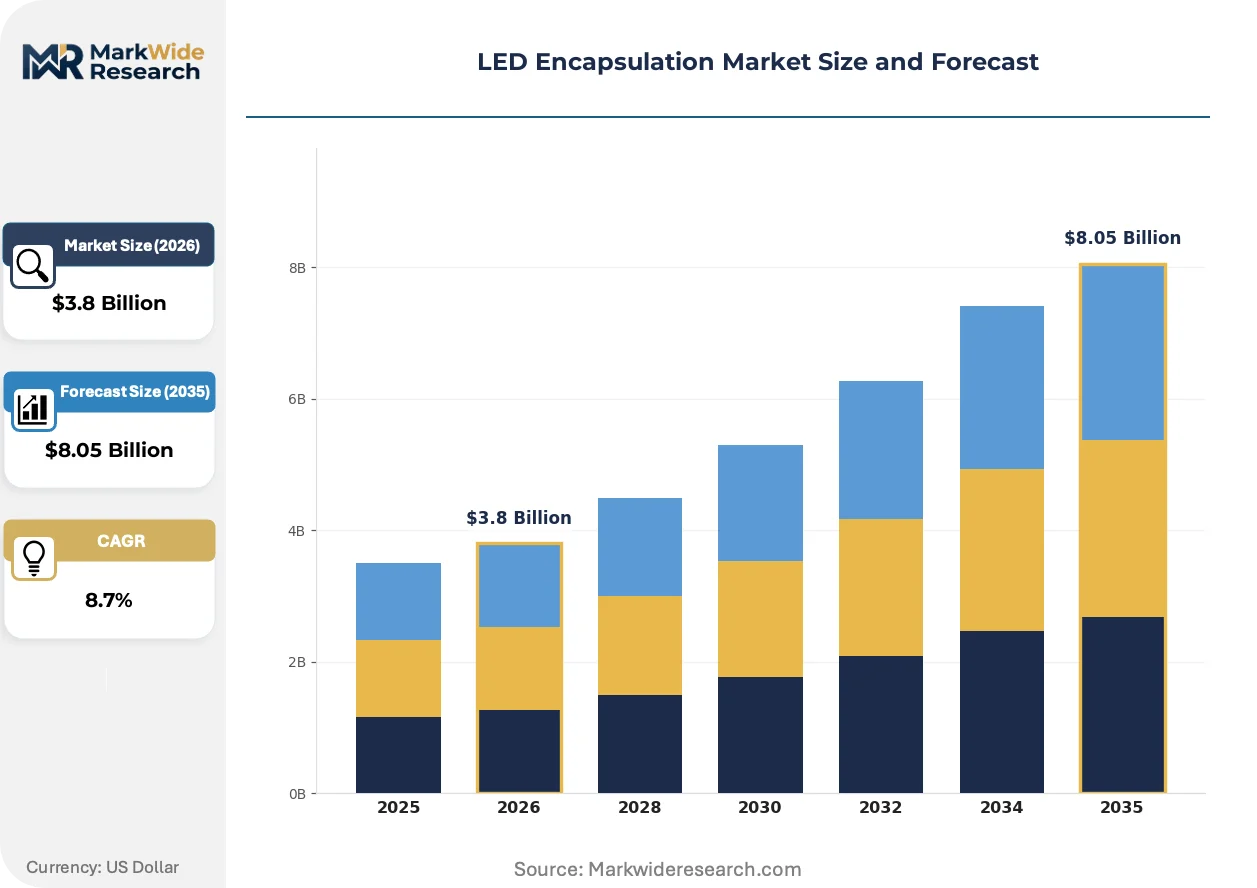
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Epoxy, Polyurethane, Resin Technology: Thermal Conductive, UV Curing, Pressure Sensitive, 3D Printing End User: Lighting, Automotive, Consumer Electronics, Industrial Application: Display, Backlighting, Signage, Decorative |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Dow Inc., Wacker Chemie AG, DuPont de Nemours Inc., Henkel AG & Co. KGaA, H.B. Fuller Company, Momentive, Nitto Denko Corp., CHT Germany GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Encapsulation Market Strategic Shifts
Solid-state lighting architectures are fragmenting into application-specific performance tiers, with automotive and display segments pulling encapsulant specifications in divergent directions. Formulators must now maintain parallel product portfolios rather than universal solutions.
Silicone encapsulation chemistry is miniaturizing through the development of low-viscosity, high-filler-loading formulations that enable thinner protective layers without sacrificing thermal conductivity. Display manufacturers in South Korea and Taiwan are adopting these systems for edge-lit and direct-lit television backlights where mechanical clearance is constrained. The structural consequence is compressing encapsulant volume per square meter of display area even as unit consumption rises.
Europe's F-Gas Regulation is restricting hydrofluorocarbon use in thermal management auxiliary systems, indirectly pressuring LED encapsulant producers to demonstrate lower-global-warming-potential curing chemistries in lifecycle assessments. Formulators serving German automotive OEMs must now document carbon footprint per kilogram of encapsulant delivered. The premium automotive lighting segment is responding by qualifying UV-curable silicone systems that eliminate oven curing energy consumption.
Automotive lighting procurement is consolidating around tier-one suppliers capable of delivering complete headlamp modules rather than discrete components. This buyer concentration is forcing encapsulant producers to integrate technical service capabilities—rheology optimization, dispensing equipment calibration, failure analysis—directly into customer relationships. The shift is most visible in Germany and Japan, where Hella, Koito, and Stanley Electric have reduced their qualified encapsulant supplier bases to two or three partners per region.
LED Encapsulation Market Segmentation
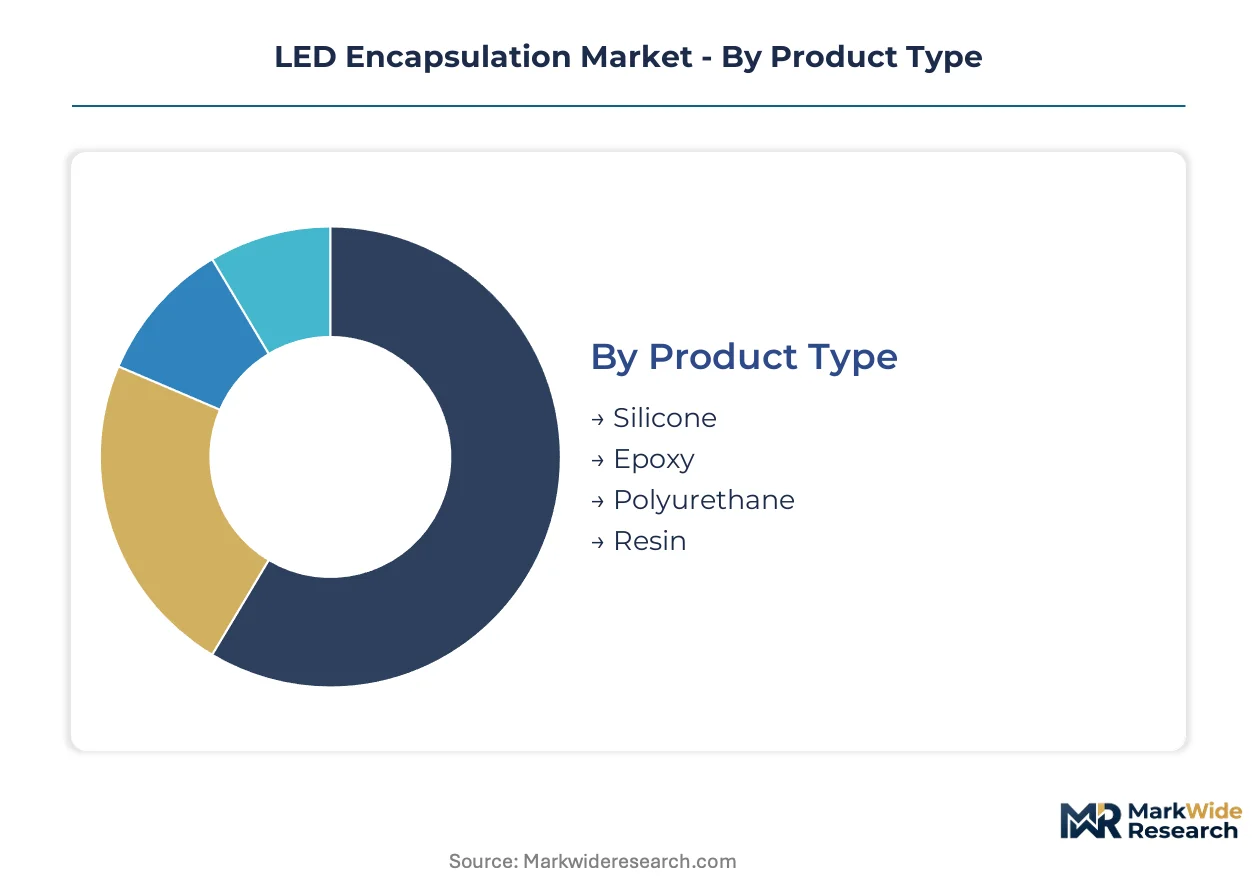
LED encapsulation specifications fragment sharply across thermal load requirements and optical performance tiers, forcing formulators to maintain parallel portfolios rather than universal solutions. Application-specific demands in automotive headlamps versus consumer display backlights create divergent material selection pathways that resist standardization.
Product Type:
Epoxy faces the most acute substitution pressure as silicone thermal conductivity improvements displace legacy formulations from moderate-heat applications previously considered safe territory.
- Silicone:Platinum-catalyzed addition cure systems deliver thermal conductivity exceeding 1.5 W/mK with yellowing resistance above 10,000 hours. Automotive headlamp manufacturers in Germany and Japan specify silicone exclusively for adaptive driving beam modules where junction temperatures reach 150°C.
- Epoxy:Bisphenol-A and cycloaliphatic formulations retain cost advantage in thermal environments below 85°C. Consumer electronics backlighting in South Korean display fabs consumes epoxy volume despite silicone encroachment at the premium tier.
- Polyurethane:Flexible aliphatic systems dominate decorative LED strip applications requiring elongation above 200%.
- Resin:Hybrid epoxy-silicone intermediates occupy narrowing middle ground as polyurethane gains decorative lighting share.
Epoxy anchors the volume base while silicone gains share at the steepest rate.
Technology:
Cost tier separation runs deepest in curing methodology, with thermal oven systems facing energy cost pressure against emerging UV alternatives.
- Thermal Conductive:Boron nitride and aluminum oxide filler loadings above 60% by weight enable heat dissipation in high-flux automotive applications. Chinese encapsulant compounders serving domestic EV manufacturers prioritize this tier under MIIT efficiency mandates.
- UV Curing:Cationic photoinitiator systems eliminate thermal processing energy consumption. Wacker Chemie pilots inline coating for flexible LED strips at European decorative lighting manufacturers.
- Pressure Sensitive:Acrylic and silicone adhesive formulations enable repositionable mounting in temporary signage installations.
- 3D Printing:Photopolymer jetting of encapsulant-grade resins supports custom optic geometries for architectural lighting fixtures.
Thermal conductive formulations command premium pricing while UV curing expands most quickly in energy-conscious European manufacturing.
End User:
Customer type determines qualification burden, with automotive OEMs imposing 24-36 month validation cycles that filter supplier participation.
- Automotive:AEC-Q100 compliance mandates 3,000-hour thermal aging and 85°C/85%RH humidity exposure. Tier-one suppliers Hella, Koito, and Stanley Electric have consolidated qualified encapsulant bases to two or three partners per region.
- Consumer Electronics:Display manufacturers in Taiwan and South Korea drive precision-dispensing requirements for edge-lit television backlights with sub-10 micrometer thickness control.
- Lighting:Commercial and industrial retrofit projects under China's dual carbon goals expand addressable volume for high-reliability encapsulants.
- Industrial:Hazardous location fixtures require encapsulants rated for chemical resistance and extended temperature cycling.
Automotive anchors the qualification-intensive premium tier while consumer electronics drives volume scale through display fabrication.
Application:
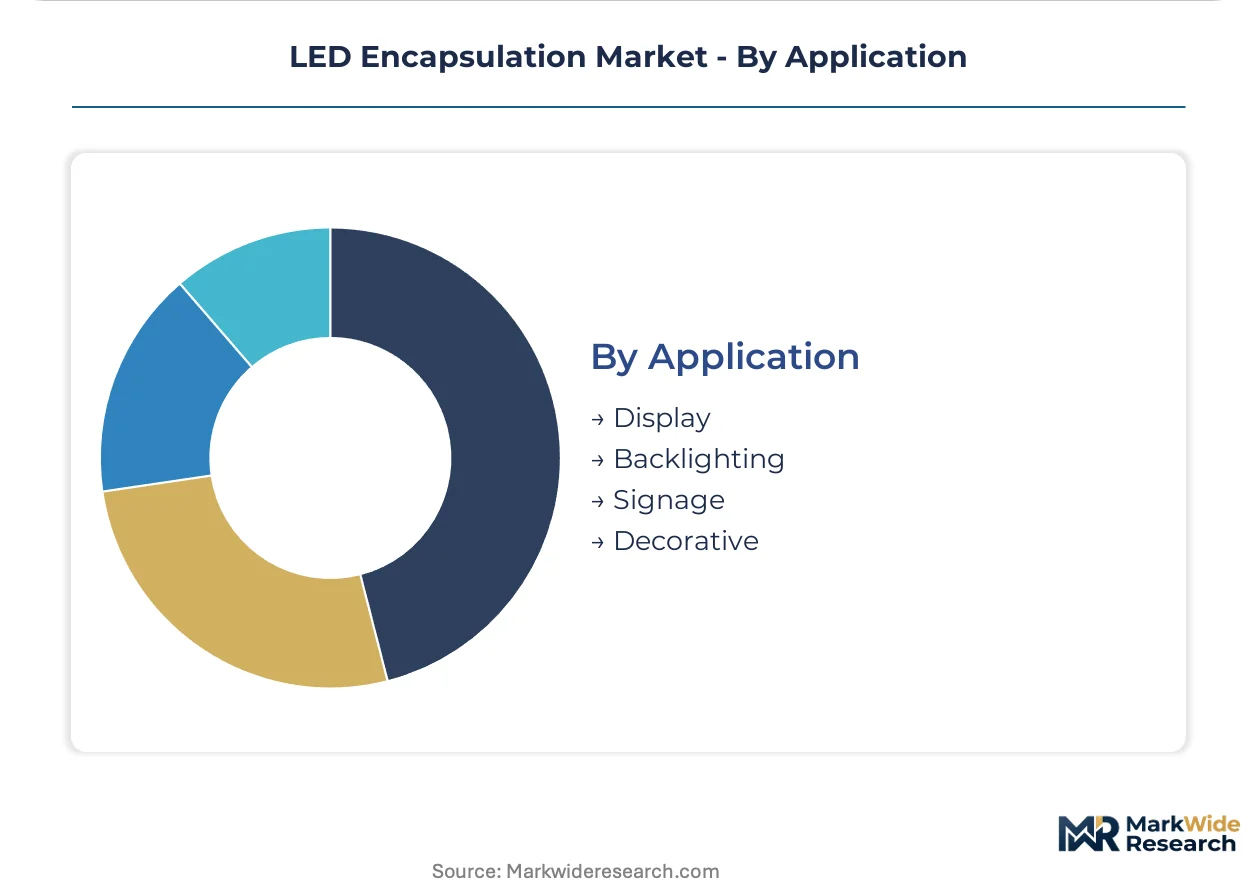
Application maturity varies sharply, with display and automotive pulling specifications in divergent directions while signage and decorative segments consolidate around cost-optimized alternatives.
- Display:Mini-LED and micro-LED chip-scale packaging demands precision encapsulation with optical transparency above 90% across the visible spectrum. South Korean panel manufacturers specify low-viscosity, high-filler-loading silicones for mechanical-constrained direct-lit backlights.
- Backlighting:Edge-lit architectures in notebook and tablet displays consume thinner encapsulation layers per unit area even as display unit production rises.
- Signage:Outdoor digital billboards prioritize weatherability and UV resistance over thermal performance.
- Decorative:Flexible LED strips for architectural accent lighting favor polyurethane flexibility over silicone thermal performance.
Backlighting anchors the volume base while display applications command the steepest specification escalation trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
LED encapsulant trade flows tilt heavily toward net-exporting Asian manufacturing clusters, with China, Japan, and South Korea commanding outbound silicone formulation volumes while Germany and the United States remain net importers of high-specification automotive grades.
China
Domestic EV production and commercial lighting retrofits absorb the bulk of regional silicone encapsulant output. MIIT efficiency mandates and the dual carbon goals accelerate replacement of legacy mercury vapor fixtures with LED systems. Xinjiang and Jiangsu province chemical clusters host chlorosilane feedstock plants supplying premium formulation lines.
Japan
METI energy efficiency standards for lighting products cascade into stricter thermal performance requirements for encapsulation materials. Niigata prefecture maintains captive organosilicon production for high-purity silicone supply. Automotive lighting suppliers in Aichi and Shizuoka prefectures specify platinum-catalyzed systems rated for 150°C junction temperatures.
Germany
EU F-Gas Regulation and REACH frameworks restrict curing chemistries and hazardous substance content in encapsulant formulations. Bavaria and Baden-Württemberg host tier-one automotive lighting module suppliers who have consolidated qualified encapsulant bases to two or three partners per region. UV-curable silicone pilots are advancing at decorative lighting manufacturers seeking lower-global-warming-potential processes.
South Korea
Display manufacturers in Gyeonggi and Chungcheong provinces drive precision-dispensing requirements for mini-LED and micro-LED backlights with sub-10 micrometer thickness control. Government-backed semiconductor material initiatives support domestic encapsulant compounding capacity expansion. Seoul-based panel fabricators specify low-viscosity, high-filler-loading silicones for mechanically constrained direct-lit architectures.
United States
EPA and OSHA frameworks govern volatile organic compound emissions at formulation plants while NHTSA safety standards influence automotive lighting material selection. Michigan and Ohio automotive corridors import high-reliability silicone grades for headlamp module assembly. Southwestern chemical processing clusters in Texas and Louisiana are evaluating domestic organosilicon feedstock investments to reduce import dependency.
LED Encapsulation Market Competitive Environment
Concentration sits with diversified chemical conglomerates and specialized silicone formulators who control captive feedstock or proprietary curing chemistries. The vendor base stratifies into three tiers: integrated petrochemical majors with silicone divisions, mid-cap specialty chemical houses focused on LED-specific formulations, and regional compounders serving cost-optimized general illumination. M&A activity targets UV-curable technology assets, while capacity expansion concentrates in East Asian manufacturing corridors to align with display and automotive customer clusters.
Among Japanese and German chemical majors, Shin-Etsu Chemical Co., Ltd. and Wacker Chemie AG exemplify the feedstock-integrated archetype, occupying positions that leverage captive organosilane supply chains. Dow Inc. represents the diversified materials conglomerate model, sitting within tier-one automotive lighting supply relationships through silicone chemistry breadth. These three companies anchor the premium encapsulant tier where qualification timelines and thermal performance specifications filter participation.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Dow Inc. |
| Wacker Chemie AG |
| DuPont de Nemours Inc. |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Momentive |
| Nitto Denko Corp. |
| CHT Germany GmbH |
| Others |
Value Chain & Pricing Dynamics
Twenty-four to thirty-six month automotive qualification timelines compress supplier switching flexibility, concentrating pricing power with Shin-Etsu Chemical, Dow Inc., and Wacker Chemie AG while forcing tier-one lighting manufacturers into long-term offtake commitments. This lead-time rigidity reinforces three-tier pricing stratification across premium silicone, mid-grade epoxy-silicone hybrids, and cost-optimized epoxy formulations.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with thermal conductivity certification tiers and volume scale driving price differentiation. Platinum catalyst cost volatility exerts upward pressure on silicone encapsulant margins, while consumer electronics backlighting manufacturers retain acute price sensitivity in epoxy procurement. Automotive headlamp suppliers demonstrate lowest price elasticity due to AEC-Q100 qualification barriers and junction temperature performance requirements.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European automotive lighting manufacturers dependent on Japanese and Chinese silicone feedstock. High-purity chlorosilane production clusters in China's Xinjiang and Japan's Niigata prefectures, creating single-source vulnerability for platinum-catalyzed addition cure systems. Distribution runs through qualified supplier bases consolidated to two or three partners per regional automotive corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive lighting module standardization is shifting procurement toward platform economics, with tier-one suppliers demanding encapsulant formulators integrate dispensing equipment calibration and failure analysis into technical service bundles. This interoperability inflection rewards suppliers capable of process-level integration over discrete material sales.
For Market Incumbents: Shield silicone formulation margins by securing captive chlorosilane feedstock through backward integration into Xinjiang or Niigata chemical clusters. Accelerate UV-curable system R&D to preempt REACH and F-Gas regulatory pressure on thermal oven curing processes, while embedding technical service teams directly within Hella, Koito, and Stanley Electric engineering centers. For New Entrants and Emerging Players: Technical service gaps in dispensing process integration present entry vectors for mid-tier compounders willing to co-develop viscosity profiles with regional automotive lighting suppliers. Target India's Gujarat and Tamil Nadu manufacturing corridors under PLI scheme incentives, where domestic LED component fabrication lacks qualified encapsulant supply. Lead with UV-curable polyurethane formulations for flexible decorative lighting strips, bypassing platinum catalyst cost exposure. For Investors and Strategic Acquirers: Long-term, this sits as a materials-platform consolidation play because automotive electrification and display miniaturization are compressing the viable supplier base to feedstock-integrated formulators with qualification capabilities. Monitor platinum group metal price trajectories and MIIT efficiency mandate enforcement intensity as inflection signals for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organosilicon Feedstock | Captive chlorosilane supply from Xinjiang or Niigata insulates margin structures from platinum catalyst volatility. |
| UV-Curable Formulation Scale-Up | Elimination of thermal oven processing aligns with EU F-Gas Regulation carbon footprint documentation requirements. |
| Technical Service Embedding | Direct dispensing equipment calibration support secures position within consolidated tier-one automotive supplier bases. |
| India PLI Corridor Establishment | Domestic compounding operations in Gujarat and Tamil Nadu capture production-linked incentive benefits for LED component manufacturing. |
| Mini-LED Precision Dispensing Development | Sub-10 micrometer thickness control capabilities open premium tiers in South Korean and Taiwanese display fabrication. |
Study Parameters
Cross-validation between primary interviews with silicone formulator R&D directors, tier-one automotive lighting procurement managers, and display manufacturer process engineers anchors the qualitative findings, while customs trade data, MIIT efficiency mandate filings, and SEC 10-K chemical segment disclosures provide secondary validation. Bottom-up encapsulant consumption modeling by application tier triangulates against top-down market size estimates derived from LED chip production volumes and content-per-unit assumptions.
Sensitivity analysis across platinum price scenarios, automotive electrification adoption curves, and regulatory enforcement intensity bounds the projection horizon. Segmentation dimensions include encapsulant chemistry type, curing technology, thermal conductivity grade, end-use industry qualification tier, and regional manufacturing cluster. CAGRs derive from fitted growth curves incorporating EV headlamp penetration rates and mini-LED display transition timelines.
Forecasts assume regulatory continuity in REACH, RoHS, and EU F-Gas frameworks; material policy shifts would require re-modeling encapsulant chemistry viability and curing process compliance costs. Practitioners should keep alternative scenarios live as China's dual carbon goal enforcement intensity and automotive OEM supplier consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
High-Brightness LED Market
LED
Arrow LED Displays Market
LED
Japan Outdoor LED Lighting Market
LED
Dot-Matrix LED Displays Market
LED
Europe Indoor LED Lighting Market
LED
Asia Pacific LED Lighting Market
LED
France Outdoor LED Lighting Market
LED
LED Street Light Drivers Market
LED
Xenon Market
LED
LED Panel Light Drivers Market
LED
Brazil LED Market
LED
China Indoor LED Lighting Market
LED
Global Waterproof LED Module Market
LED
LED Digital Scoreboard Market
LED
Chip on Board LED Market
LED
Middle East and Africa Outdoor LED Lighting Market