
 Chipless RFID Market | 2026-2036
Chipless RFID Market Size, Share, and Industry Trends Forecast 2026-2036
Chipless RFID Market Intelligence
Subscription-based data analytics platforms are pivoting the core value proposition from simple tag sales to recurring revenue streams. Zebra Technologies Corporation leverages its established presence in enterprise asset tracking to integrate these new data services. Avery Dennison Corporation differentiates through expertise in material science and high-volume tag manufacturing. NXP Semiconductors competes on its deep intellectual property in radio frequency engineering and component miniaturization.
Chipless RFID technology provides unique identification without an integrated silicon chip, instead using materials with distinct electromagnetic properties. These tags, often utilizing printed resonant structures, reflect a specific radio frequency signature back to a reader for low-cost tagging of mass-market goods. While supply chain and asset tracking applications form the market's foundation, smart packaging represents the fastest-growing opportunity. Demand from retailers and manufacturers, seeking to optimize inventory and combat counterfeiting, drives adoption across these end uses.
Market access hinges on adherence to radio spectrum regulations, including the FCC's Part 15 rules in the US and directives from China's MIIT. Material composition is constrained by environmental frameworks like the EU's REACH and RoHS, impacting substrate and conductive ink choices. Future investment decisions must weigh the trade-offs between tag manufacturing cost, read range performance, and data capacity for specific high-volume applications.
Market Dynamics
Demand for ultra-low-cost, item-level tracking in mass-market sectors like retail and logistics is the central force shaping the market. This creates a powerful incentive for innovation in material science and high-speed printing to produce tags without silicon chips.
Growth Catalysts
- EU Digital Product Passport:This initiative mandates detailed product lifecycle information, creating compliance-driven demand for unique, item-level identifiers on consumer goods, electronics, and textiles sold within the European Union.
- Fast-Moving Consumer Goods:The FMCG sector requires inexpensive solutions for inventory management, supply chain visibility, and anti-counterfeiting, driving adoption of chipless tags on high-volume, low-margin products.
- Chinese Logistics Sector:China's massive e-commerce and logistics industries are adopting chipless RFID to automate sorting and tracking processes at a scale that demands the lowest possible cost-per-tag.
Market Restraints
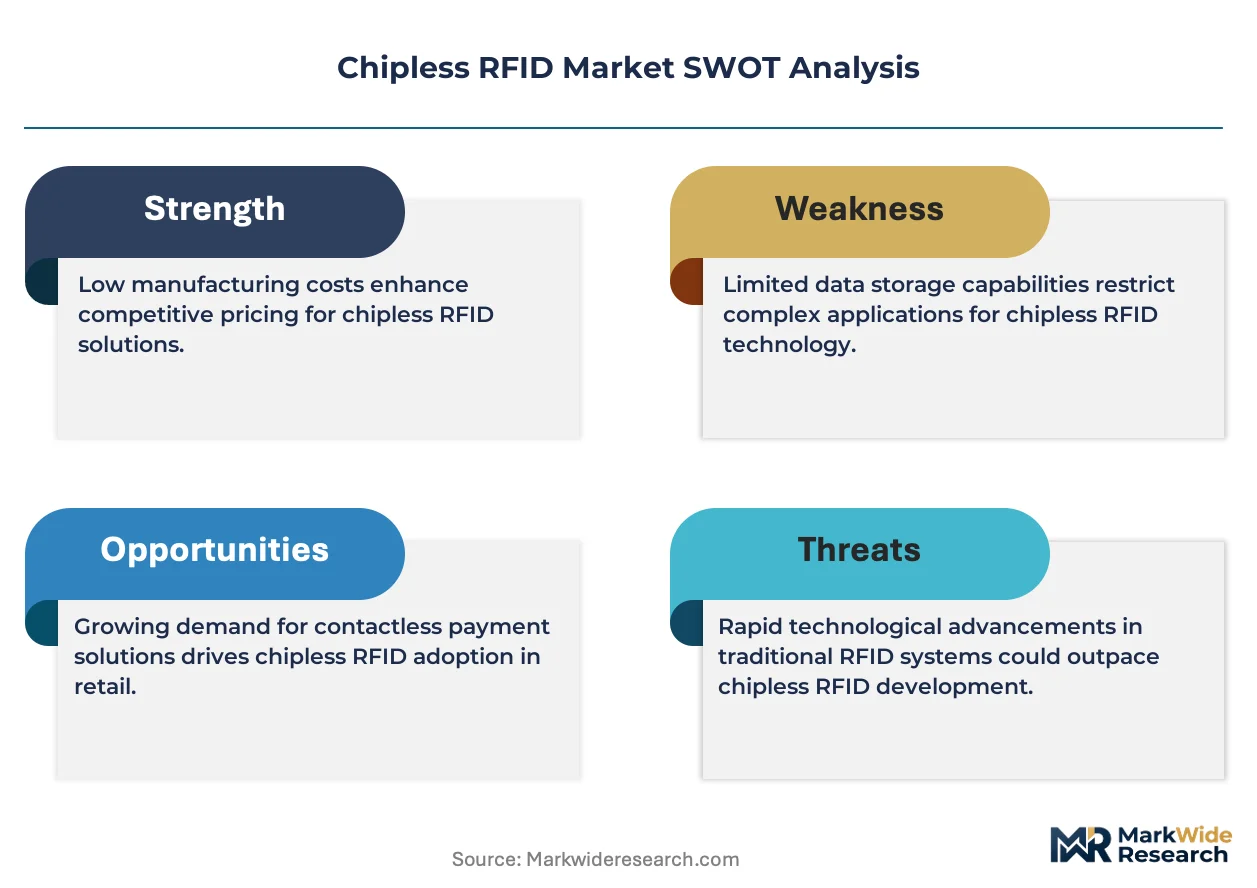
- Technical Performance Limits:Compared to traditional silicon-based RFID, chipless tags exhibit a significantly shorter read range and lower data storage capacity, restricting their use in applications requiring long-distance or data-rich tracking.
- Material Input Costs:Production depends on specialized conductive inks and polymer substrates, whose price and availability can be volatile, creating uncertainty in manufacturing cost structures for tag converters.
- Optical Code Competition:High-density QR codes and advanced barcodes present a persistent substitution threat, offering a mature, lower-cost alternative for basic identification, albeit with fewer security and automation features.
Strategic Opportunities
- Pharmaceutical Packaging:Integrating chipless tags into blister packs or vials offers a new frontier for single-dose authentication and tracking, helping to combat counterfeit drugs and improve patient safety.
- Printed Sensor Integration:Combining chipless RFID with printed sensors for temperature, humidity, or tampering creates value-added solutions for cold chain logistics and high-value asset monitoring without a battery.
- India's Retail Modernization:The expanding organized retail sector in India presents a significant, underpenetrated market for deploying low-cost inventory management and anti-theft systems at scale.
Industry Challenges
- Interoperability Standards:The absence of a single, globally ratified standard for frequency bands, data protocols, and air interfaces for chipless RFID complicates system design and limits interoperability between different vendors' readers and tags.
- Legacy System Integration:Connecting the high-volume data streams from new chipless RFID reader networks into existing enterprise resource planning (ERP) and warehouse management systems (WMS) presents a significant software integration hurdle.
- Manufacturing Process Control:Achieving the required precision and consistency in high-speed, roll-to-roll printing of resonant tag structures to ensure reliable RF performance at an ultra-low cost point remains a key production challenge.
Report Scope
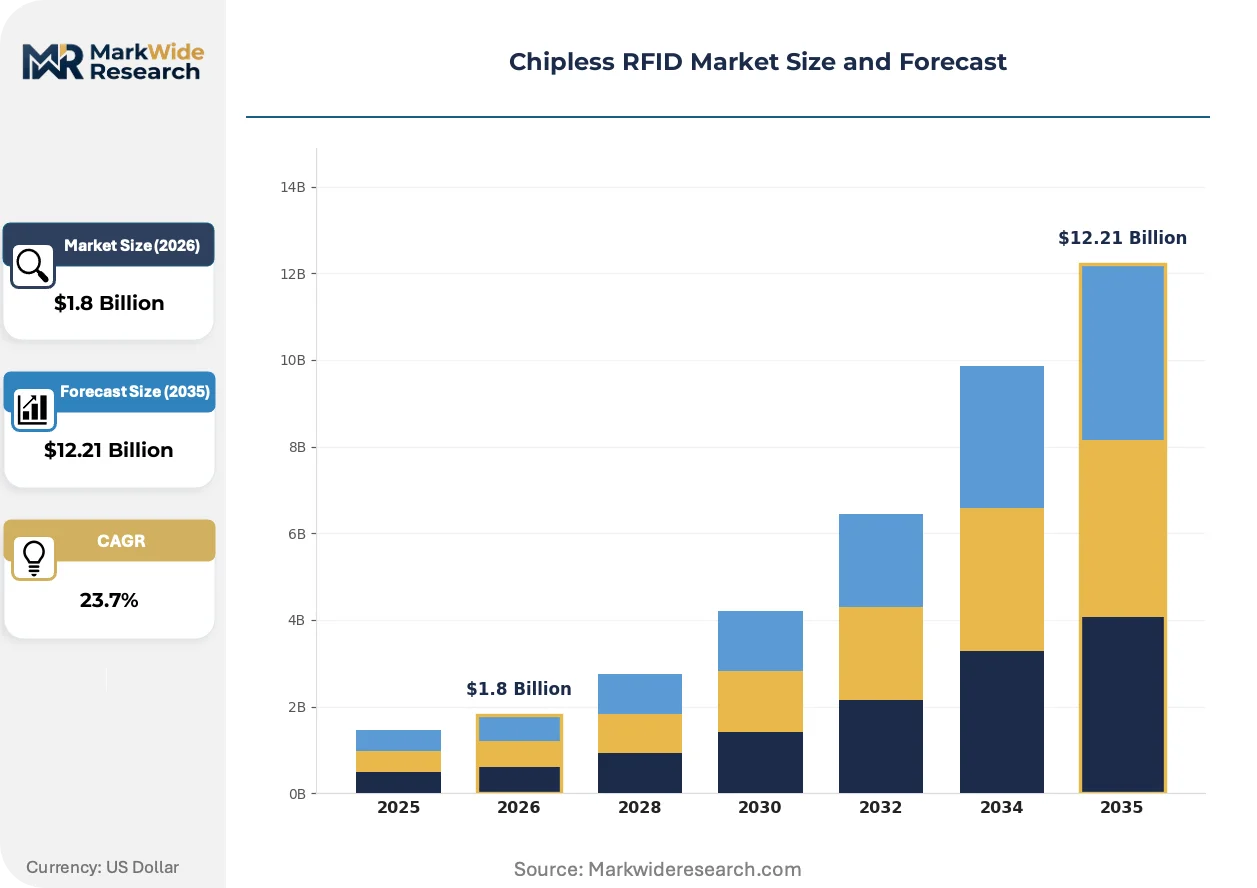
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chipless RFID Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ink-Based, Microstrip Tag, Surface Acoustic Wave, Electromagnetic, Carbon Nanotube Technology: Radio Frequency, Microwave, Optical, Magnetic, Ultrasonic Application: Supply Chain, Asset Tracking, Security & Authentication, Smart Packaging, Document Management End User: Manufacturers, Retailers, Logistics Operators, Government Agencies, Libraries |
| Companies Covered | Zebra Technologies Corporation, Impinj, Inc., NXP Semiconductors, Avery Dennison Corporation, Alien Technology Corporation, HID Global Corporation, Honeywell International Inc., SATO Holdings Corporation, Invengo Information Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chipless RFID Market Strategic Shifts & Innovations
Material science advancements and new regulatory mandates are reshaping the market. These forces are moving the technology from a niche solution toward broader applicability in smart packaging and supply chain automation, creating new value propositions beyond simple identification.
Printed electronics using novel conductive inks based on silver or carbon enable the mass production of flexible, disposable tags on various substrates like paper or plastic. The retail apparel and food and beverage sectors are adopting these tags for inventory accuracy and consumer interaction. This manufacturing capability is integrating material science directly with packaging, converting a simple label into a dynamic data carrier.
The European Union's Digital Product Passport framework, an element of its sustainable products initiative, establishes a new compliance baseline. This regulation compels manufacturers to provide detailed traceability and sustainability data for products, including textiles and electronics. Consequently, the apparel and consumer electronics segments are most affected, embedding item-level identifiers to meet these stringent data-sharing mandates.
A distinct shift from one-time hardware sales to subscription-based data services is redefining the core business model for solution providers. This approach unbundles the physical tag and reader from the more valuable recurring revenue generated by inventory intelligence, anti-counterfeiting verification, and consumer engagement analytics. This model is most prominent within the fast-moving consumer goods vertical, where brands seek continuous supply chain visibility.
Chipless RFID Market Segmentation
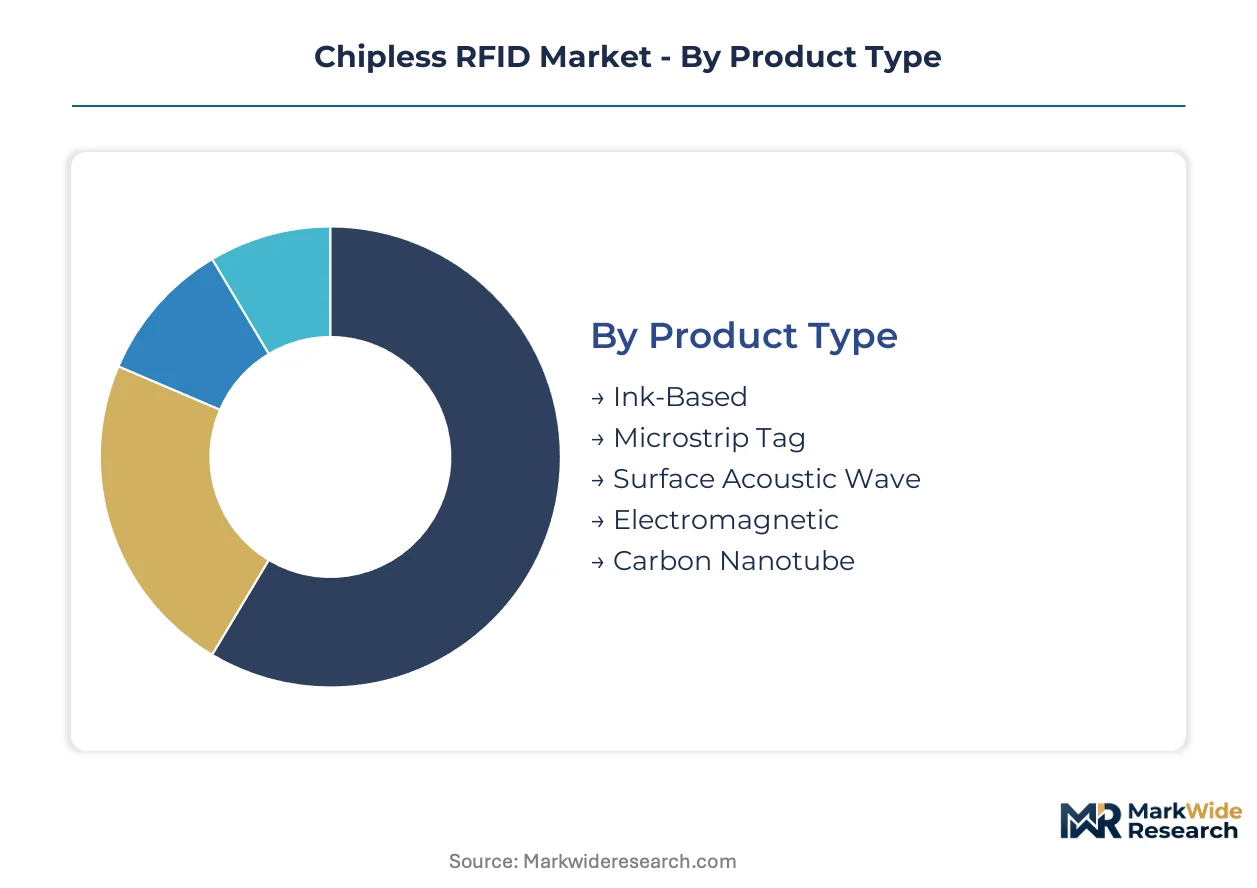
Chipless RFID market segmentation provides a granular view of how technology variants and end-use cases influence adoption patterns. Understanding these segments helps solution providers align product development with specific industry demands. This analysis identifies where value concentrates and where emerging opportunities arise for item-level identification.
Product Type:
Product type segmentation highlights the trade-off between volume manufacturing costs and premium performance characteristics across different tag designs.
- Ink-Based:These tags utilize conductive inks printed onto various substrates, offering a low-cost, flexible, and disposable solution for mass-market goods. Demand concentrates in fast-moving consumer goods and retail apparel for inventory accuracy and anti-counterfeiting measures.
- Microstrip Tag:Consisting of printed resonant structures on a substrate, microstrip tags provide unique electromagnetic signatures for identification. Smart packaging applications in food and beverage drive demand for these cost-effective, high-volume identifiers.
- Surface Acoustic Wave:SAW tags leverage piezoelectric materials to generate unique radio frequency responses, often used in harsh environments or for passive sensing applications.
- Electromagnetic:This broad category encompasses various chipless designs that interact with electromagnetic fields to provide identification without a silicon chip.
- Carbon Nanotube:Utilizing advanced nanomaterials for enhanced conductivity and miniaturization, carbon nanotube tags represent a frontier in ultra-small, high-performance chipless identification.
Mature deployment sits with Ink-Based solutions. Newer deployment is concentrated in Carbon Nanotube research.
Technology:
Technology differentiation focuses on the specific application requirements for signal propagation and interference resilience across various physical principles.
- Radio Frequency:This core technology relies on the interaction of radio waves with printed tag structures to generate unique identification signals. Supply chain visibility and asset tracking form the foundation of its application.
- Microwave:Operating at higher frequencies, microwave chipless technologies offer enhanced data capacity and read range in specific environments, often for industrial asset management.
- Optical:Optical chipless identification uses light-based patterns or material properties for unique recognition, particularly in security and authentication applications where visual inspection is part of the process.
- Magnetic:Magnetic chipless tags exploit distinct magnetic signatures for identification, finding niche applications in environments where radio frequencies are unsuitable.
- Ultrasonic:Ultrasonic chipless methods use sound waves to interrogate and identify tags, suitable for specific material identification or short-range sensing.
Radio Frequency technologies dominate current deployments, while Magnetic methods offer niche capabilities.
Application:
Application segments are driven by the specific operational needs of end-users seeking enhanced visibility and data capture across their value chains.
- Smart Packaging:Integrating chipless tags directly into product packaging provides item-level authentication, inventory management, and consumer engagement opportunities. This application represents the fastest-growing opportunity, especially with the EU Digital Product Passport initiative.
- Supply Chain:Chipless RFID tags enhance traceability and efficiency throughout the entire supply chain, from manufacturing to distribution, by providing low-cost item identification. Demand from China's logistics sector drives significant volume in this segment.
- Asset Tracking:This application involves monitoring the location and status of physical assets, leveraging chipless tags for cost-effective identification of individual items within an enterprise.
- Security & Authentication:Chipless tags offer a unique, non-clonable identifier for combating counterfeiting and ensuring product authenticity in high-value or regulated goods.
- Document Management:Utilizing chipless tags for automated identification and tracking of physical documents in archives or libraries improves retrieval efficiency and security.
Supply Chain applications form the bedrock, with Smart Packaging expanding most quickly.
End User:
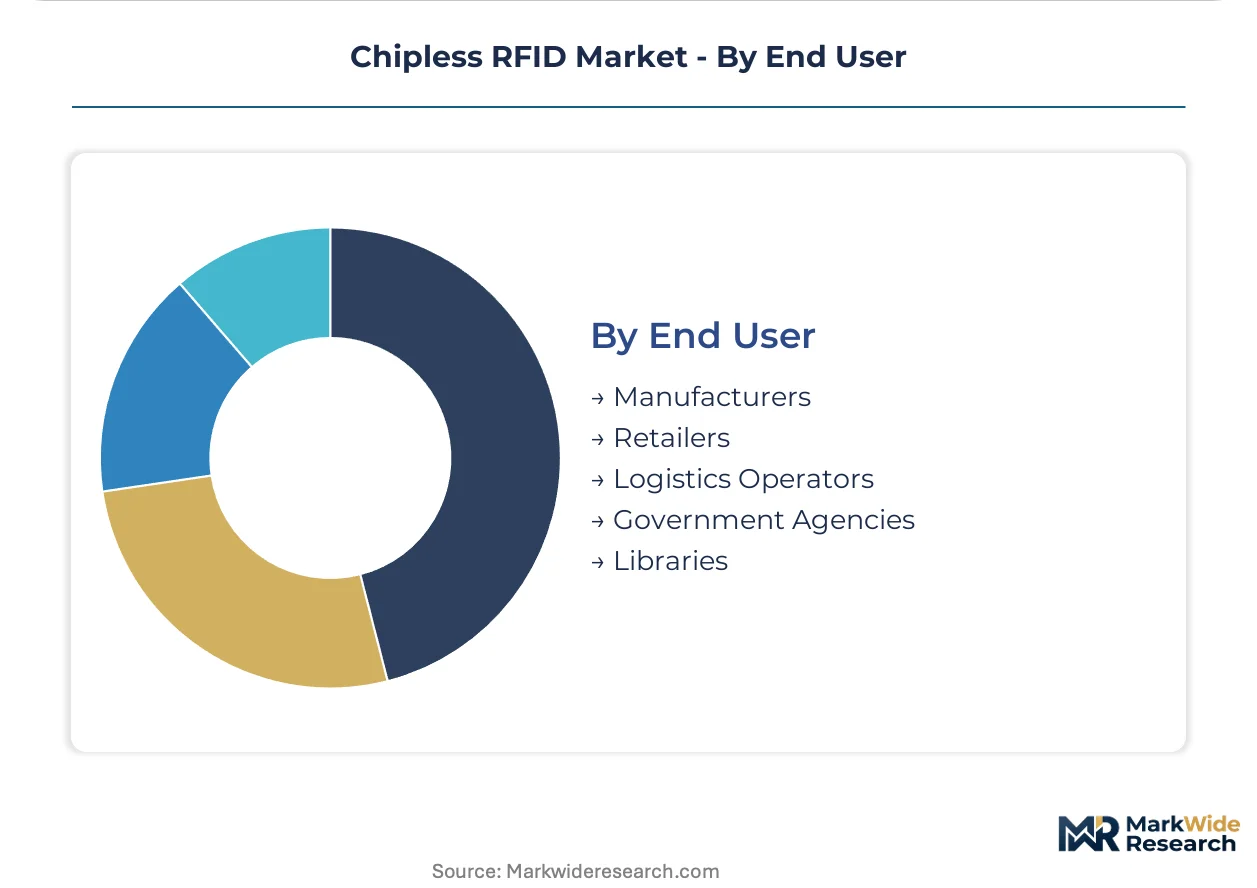
End user categories reflect distinct procurement cycles and integration challenges across diverse operational environments.
- Retailers:Retailers adopt chipless RFID for improved inventory accuracy, loss prevention, and enhanced customer experience through item-level visibility. Massive retail networks in China and India drive significant volumes.
- Logistics Operators:These operators leverage chipless tags to automate sorting, tracking, and proof-of-delivery processes within warehouses and transportation networks, streamlining operations. China's e-commerce boom intensifies demand for these solutions.
- Manufacturers:Manufacturers integrate chipless RFID into their production lines for work-in-progress tracking, quality control, and finished goods inventory management.
- Government Agencies:Government bodies deploy chipless RFID for secure document management, asset tracking in public infrastructure, and certain regulatory compliance applications.
- Libraries:Libraries use chipless RFID for efficient book management, inventory, and automated check-in/check-out processes, reducing manual labor.
Retailers and Logistics Operators represent the largest current demand, with Government Agencies exploring specialized use cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Chipless RFID market exhibits a clear divide between manufacturing hubs and high-consumption regions. Production capabilities for advanced materials and printing technologies often concentrate in specific industrial clusters. Consumption patterns are driven by regulatory mandates and the scale of retail and logistics operations in diverse geographies.
China
China's expansive e-commerce and logistics sectors generate substantial demand for low-cost item-level tracking solutions. The Ministry of Industry and Information Technology (MIIT) encourages the development and application of advanced identification technologies. Manufacturers in the Pearl River Delta region are rapidly integrating chipless tags for automated sorting and supply chain visibility.
India
India's burgeoning organized retail sector presents a significant, underpenetrated market for cost-effective inventory management. The country's national trade policies aim to streamline logistics and promote digital transformation. Retailers in the Delhi-NCR and Mumbai regions are actively exploring chipless RFID for enhanced stock accuracy and loss prevention.
United States
United States enterprises seek supply chain optimization and enhanced asset tracking across various industrial applications. The Federal Communications Commission (FCC) Part 15 rules establish the regulatory framework for chipless RFID device operation. Research centers in Silicon Valley continue to drive advancements in printed electronics and conductive ink formulations.
Germany
German manufacturers are integrating chipless RFID into industrial automation and smart manufacturing processes. The European Union's Digital Product Passport framework mandates detailed product lifecycle information, impacting German exports. Automotive and logistics hubs in Bavaria are investigating chipless tags for component tracking and inventory optimization.
France
French luxury brands and pharmaceutical companies demand robust authentication and traceability solutions. European environmental regulations such as REACH and RoHS influence the material composition of chipless tags. The Île-de-France region sees pilot programs for item-level identification in high-value goods and medical packaging.
Chipless RFID Market Key Industry Players
Top-tier vendors anchor the chipless RFID market, while specialized material science firms and printing solution providers occupy niche segments. The market structure is tiered, reflecting diverse capabilities from component manufacturing to integrated system deployment. Three strategic archetypes include semiconductor specialists, material science innovators, and enterprise solution integrators. Companies are engaging in strategic partnerships and pursuing targeted acquisitions to expand their portfolio diversification and geographic reach, seeking to capture emerging opportunities.
Specialists in different aspects of the value chain influence market development and solution delivery. NXP Semiconductors, a Dutch-based entity, exemplifies deep expertise in radio frequency engineering and component miniaturization, crucial for advanced chipless designs. Avery Dennison Corporation, a US-based materials science innovator, represents high-volume tag manufacturing capabilities and substrate development, enabling cost-effective production. Furthermore, Zebra Technologies Corporation, an American enterprise, anchors the provision of integrated asset tracking solutions and data services, leveraging its established presence to offer comprehensive identification systems within this evolving landscape.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Impinj, Inc. |
| NXP Semiconductors |
| Avery Dennison Corporation |
| Alien Technology Corporation |
| HID Global Corporation |
| Honeywell International Inc. |
| SATO Holdings Corporation |
| Invengo Information Technology Co., Ltd. |
| Others |
Cost & Logistics Intelligence
The European Union's Digital Product Passport initiative mandates detailed product lifecycle information, creating compliance-driven demand for unique item-level identifiers. This regulatory push forces chipless RFID suppliers to adapt manufacturing processes, impacting overall pricing structures.
Pricing Analysis
Cost-down pressure on ink-based chipless tags accelerates because mass-market sectors like FMCG and logistics demand ultra-low-cost solutions. The dominant pricing model remains per-unit transactional for physical tags, complemented by subscription-based data services for analytics. Price differentiation stems from material composition, read range performance, and data capacity. Logistics operators and FMCG brands exhibit the highest price sensitivity, while pharmaceutical packaging applications are less cost-driven.
Supply Chain Analysis
Workforce availability in specialized printing and material science in China and Germany influences production capacity for chipless RFID tags. The supply chain relies heavily on specialized conductive inks, often silver or carbon-based, and polymer substrates. Volatility in these material input costs represents a significant structural risk for tag converters. Distribution runs through direct sales channels for large enterprise integrators and via specialized tag converters for mass-market deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chipless RFID market is increasingly a cost-of-compliance story, driven by regulations such as the EU Digital Product Passport. This framework establishes a significant barrier to entry, favoring established players capable of meeting stringent data-sharing mandates.
For Market Incumbents: Hedge against the persistent threat of optical code competition by integrating advanced data services with established asset tracking platforms. Incumbents should invest in material science R&D, particularly in conductive ink formulations, to overcome current technical performance limits. Leveraging deep intellectual property in radio frequency engineering creates a differentiation advantage. Expanding high-volume tag manufacturing capabilities can also secure market share.
For New Entrants and Emerging Players: A significant price-point gap exists between premium silicon-based RFID and basic optical codes, creating an entry opportunity for chipless solutions. New entrants should target white-space applications like pharmaceutical packaging for single-dose authentication or integrated printed sensors for cold chain logistics. India's expanding organized retail sector represents the most penetrable segment. A go-to-market strategy focused on value-added solutions beyond simple identification will resonate with buyers.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate capabilities in chipless RFID. Long-term viability remains strong for entities addressing compliance-driven demand and mass-market item-level identification. Acquisition targets should include specialized material science firms with novel conductive ink technologies or software analytics platforms offering recurring revenue streams. The emergence of a single, globally ratified interoperability standard will serve as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Data Service Integration | Enhances recurring revenue streams and provides deeper supply chain visibility for FMCG brands. |
| Material Science R&D | Improves read range performance and reduces tag manufacturing costs for mass-market adoption. |
| Regulatory Compliance Consulting | Guides manufacturers in meeting EU Digital Product Passport mandates, creating new service revenue. |
| Printed Sensor Development | Expands chipless RFID into value-added applications like cold chain monitoring without batteries. |
| Geographic Market Penetration | Captures demand from India's modernizing retail sector and China's expansive logistics networks. |
Research Approach
Multi-period observation of chipless RFID tag adoption rates and technology advancements anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research included discussions with RFID tag manufacturers, logistics operators, retail supply chain managers, and material science engineers. Secondary validation drew from MIIT directives, FCC Part 15 rules, EU REACH regulations, and corporate financial filings. A rigorous process of bottom-up and top-down triangulation ensured data integrity.
Segment-weighting across product type, technology, application, end user, and regional regulatory frameworks informed the quantitative model. The analytical framework projected market growth across the analysis window, with compound annual growth rates derived from historical patterns and projected adoption curves. Key industry-specific inputs included conductive ink prices and smart packaging adoption rates. This approach ensured a granular and robust market projection.
Underlying measurement precision varies by segment; established supply chain and retail applications carry tighter precision than emerging pharmaceutical packaging. Forecasts reflect assumptions regarding technological maturation and regulatory enforcement. Material input cost volatility or the absence of global interoperability standards warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Flexible PV Cell Market
Emerging and Next Generation Technologies
Piezoelectric Nanogenerator Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
Terahertz Radiation Devices Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market