
 Global Hybrid Intelligence Market | 2026-2036
Global Hybrid Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hybrid Intelligence Market Foresight
Buyer concentration among large financial services and defense contractors is realigning procurement toward enterprise-grade hybrid intelligence platforms with audit-ready human oversight. Microsoft Corporation leverages its Azure cloud infrastructure to anchor hybrid AI deployments across regulated industries. IBM Corporation competes through Watsonx's governance tooling and vertical specialization in healthcare and financial compliance. Google LLC differentiates via DeepMind research integration and custom silicon for training efficiency.
Hybrid intelligence fuses symbolic reasoning engines with neural network pattern recognition to produce auditable, explainable decisions under human supervision, typically operating through constrained optimization layers that weight statistical confidence against rule-based guardrails. This architecture serves mission-critical applications where black-box automation fails regulatory or safety thresholds. Cloud-based deployment leads solution delivery by reducing capital barriers for mid-market adopters, while edge computing segments expand fastest in manufacturing and telecommunications for latency-sensitive predictive maintenance. Machine learning platforms capture the largest margin pools, though robotic process automation shows accelerating attach rates as enterprises retrofit legacy workflows.
The EU AI Act imposes conformity assessments on high-risk hybrid systems, while FDA guidance shapes clinical decision-support validation requirements in the United States. China's SAMR and MIIT enforce algorithmic transparency rules for consumer-facing and industrial AI applications, creating divergent compliance architectures. ISO standards for AI risk management and IEC protocols for autonomous system safety are emerging as baseline procurement filters across OECD procurement frameworks. Stakeholders must monitor regulatory fragmentation between jurisdictions to avoid architectural lock-in that prevents multi-market deployment.
Market Dynamics
Defense procurement cycles and FDA validation requirements for clinical decision-support systems are tightening accountability frameworks, forcing platform vendors to embed audit-ready human oversight layers into core architectures.
Growth Catalysts
- EU AI Act conformity assessments:High-risk system classifications create procurement mandates for auditable hybrid architectures across financial services and healthcare, accelerating enterprise platform upgrades.
- Edge computing deployment in German automotive manufacturing:Latency constraints in predictive maintenance workflows drive neural-symbolic fusion at the point of data generation.
- Symbolic reasoning engines:Rule-based guardrails satisfy explainability requirements in US defense contracting where black-box neural networks face disqualification.
Market Restraints
- GPU supply concentration:Taiwan-based foundry capacity constraints create training infrastructure bottlenecks for mid-market adopters seeking on-premise deployment.
- ISO/IEC 23053 interoperability gaps:Fragmented AI system safety standards force redundant certification cycles across OECD procurement frameworks.
- Legacy workflow retrofit costs:Robotic process automation attach rates accelerate but require expensive human-in-the-loop redesign of established operational procedures.
Strategic Opportunities
- Saudi Arabia's NEOM and healthcare digitization:Greenfield smart city deployments bypass legacy integration burdens, enabling native hybrid intelligence infrastructure.
- Convergence of constrained optimization layers with federated learning:Distributed training architectures preserve data sovereignty while maintaining centralized audit trails for cross-border financial compliance.
- India's PLI scheme for AI hardware:Domestic manufacturing incentives reduce import dependency for edge deployment chipsets in telecom infrastructure.
Industry Challenges
- Human oversight skill scarcity:Domain experts capable of calibrating confidence thresholds against rule-based guardrails command premium compensation, constraining scale-out velocity.
- FDA 510(k) pathway complexity:Clinical decision-support validation timelines extend 18-24 months, compressing first-mover advantages in healthcare verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hybrid Intelligence Market |
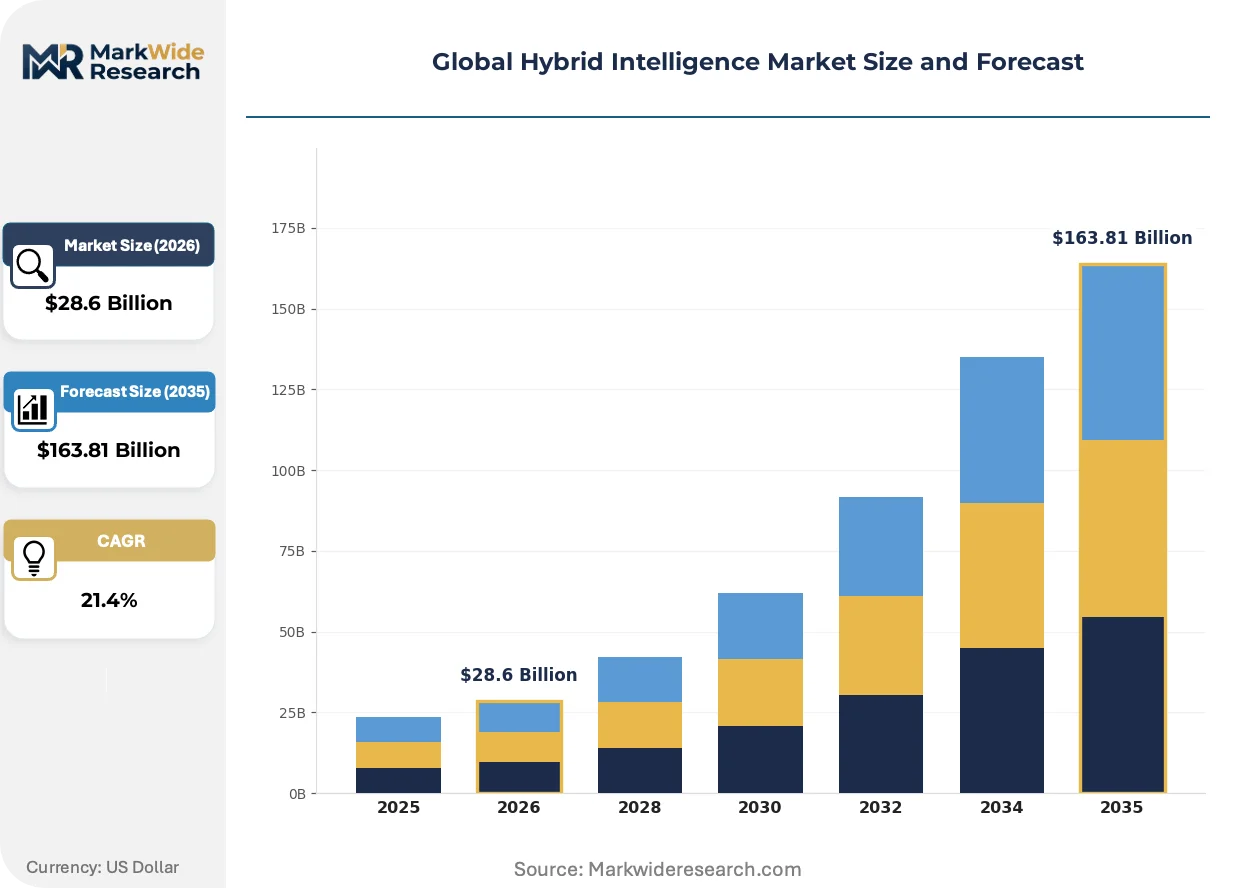
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $163.81 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Edge Computing, Hybrid Cloud Solution Offering: Machine Learning Platforms, Natural Language Processing, Computer Vision, Robotic Process Automation, Expert Systems Use Case: Fraud Detection, Predictive Maintenance, Customer Engagement, Risk Management, Supply Chain Optimization End User Industry: Manufacturing, Telecommunications, Financial Services, Retail Banking, Public Sector |
| Companies Covered | International Business Machines Corporation, Microsoft Corporation, Google LLC, Amazon Web Services Inc., Oracle Corporation, SAP SE, Salesforce Inc., Intel Corporation, Open Text Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hybrid Intelligence Market Shifts & Advancements
Neural-symbolic fusion architectures are displacing pure statistical approaches in mission-critical deployments where regulatory scrutiny demands transparent decision pathways.
Neuro-symbolic reasoning stacks combine deep learning pattern recognition with explicit knowledge graphs to generate auditable inference chains. Financial services compliance teams in London and Singapore deploy these systems for real-time transaction monitoring. The technology is consolidating vendor positioning around governance-first platform design rather than raw predictive accuracy.
The EU AI Act's high-risk system registry imposes pre-market conformity assessments on hybrid intelligence deployed in credit scoring and medical diagnostics. Manufacturers must maintain technical documentation and human oversight protocols subject to third-party audit. German automotive suppliers and Dutch health insurers are front-loading compliance investments to secure early-mover certification advantages.
Enterprise buyers now unbundle software licensing from implementation services, demanding outcome-guaranteed contracts with penalty clauses for failed human-in-the-loop integration. This restructuring compresses vendor margins while shifting risk retention to platform providers. The pattern is most pronounced in US defense contracting and Australian healthcare system modernization programs.
Global Hybrid Intelligence Market Segmentation
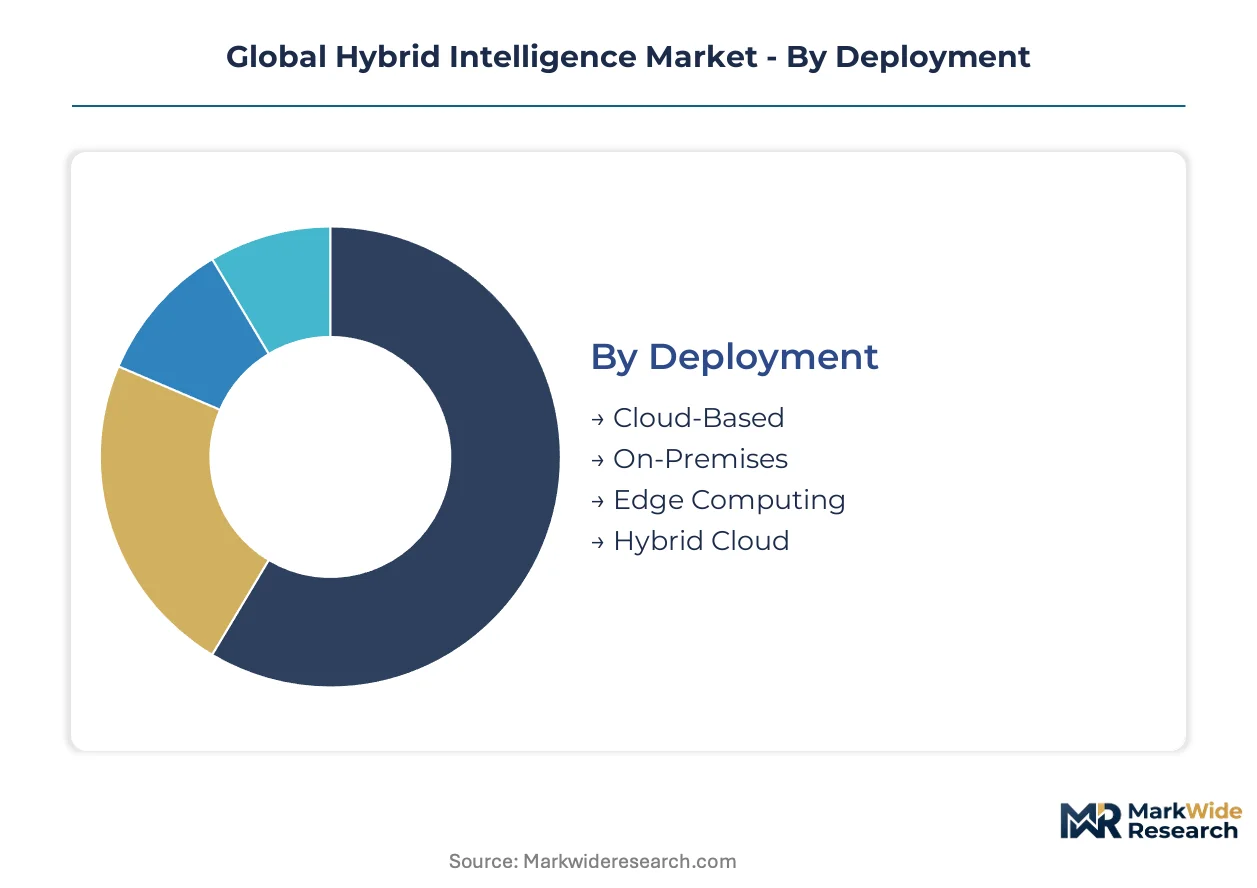
Segmentation in hybrid intelligence markets reveals divergent capital requirements and compliance burdens across deployment architectures, solution layers, and end-use applications. Procurement patterns cluster around audit-ready platforms in regulated industries while latency-sensitive manufacturing drives edge-native adoption.
Deployment:
Capital intensity varies sharply across infrastructure modes, with on-premises deployment demanding the heaviest upfront investment in GPU clusters and dedicated data centers.
- Cloud-Based:Shared infrastructure models eliminate capital expenditure barriers for mid-market financial services firms and healthcare systems. German automotive suppliers and Dutch health insurers favor this mode for rapid scaling of neural-symbolic workloads without dedicated hardware procurement cycles.
- On-Premises:Requires captive investment in NVIDIA H100 clusters, liquid cooling systems, and air-gapped security architectures. US defense contractors and Saudi healthcare digitization projects mandate this deployment for classified or sovereignty-sensitive data processing.
- Edge Computing:Distributed inference nodes serve German automotive predictive maintenance and Indian telecom infrastructure with sub-10ms latency requirements.
- Hybrid Cloud:Orchestrates sensitive training workloads on-premises while pushing inference to public cloud during demand spikes.
Cloud-Based absorbs the bulk of installed capacity; Edge Computing is expanding most quickly.
Solution Offering:
Margin profiles stratify across the technology stack, with foundational platforms commanding premium pricing against commoditized automation tooling.
- Machine Learning Platforms:TensorFlow and PyTorch-based training environments with integrated governance layers for EU AI Act compliance. Financial services firms in London and Singapore deploy these for real-time transaction monitoring with auditable confidence thresholds.
- Natural Language Processing:Transformer architectures with symbolic parsing for contract analysis and regulatory document processing. Legal and compliance departments in US banks drive procurement for SEC filing automation.
- Computer Vision:Neural-symbolic fusion for defect detection in Japanese automotive manufacturing and pharmaceutical quality control.
- Robotic Process Automation:Attaches to legacy ERP systems but requires expensive human-in-the-loop redesign of established workflows.
- Expert Systems:Rule-based inference engines satisfying explainability mandates in FDA-regulated clinical decision support.
Machine Learning Platforms capture the deepest margin pools; Robotic Process Automation shows the steepest expansion trajectory as enterprises retrofit legacy systems.
Use Case:
Application maturity correlates with regulatory pressure intensity, creating divergent adoption timelines across operational domains.
- Fraud Detection:Real-time transaction scoring combining neural pattern recognition with explicit rule engines for SAR filing automation. Singaporean banks and EU payment processors lead deployment under AMLD6 and PSD2 accountability frameworks.
- Predictive Maintenance:Vibration and thermal sensor fusion for German automotive and Japanese steel manufacturing, where unplanned downtime costs exceed platform investment by an order of magnitude.
- Customer Engagement:Conversational agents with human escalation protocols for Australian healthcare system modernization and UAE banking digitization.
- Risk Management:Credit scoring and stress testing under ECB and Fed supervisory scrutiny.
- Supply Chain Optimization:Multi-modal logistics planning constrained by customs regulations and carbon accounting requirements.
Fraud Detection dominates current procurement volumes; Predictive Maintenance is gaining share fastest as industrial IoT sensor density increases.
End User Industry:
Buyer sophistication and compliance readiness fragment demand across sectors with divergent legacy system burdens.
- Financial Services:Trading desks and compliance departments in New York, London, and Singapore procure platforms with pre-built EU AI Act and SEC audit trail modules. Capital markets infrastructure demands sub-millisecond inference with full decision explainability.
- Manufacturing:German automotive suppliers and Japanese electronics assemblers deploy edge-native systems for quality control and predictive maintenance, bypassing cloud dependency for sensitive production data.
- Telecommunications:Indian and Brazilian carriers invest in subscriber churn prediction and network optimization under domestic data localization mandates.
- Retail Banking:Customer-facing credit decisioning with mandatory human override protocols under CFPB and FCA guidance.
- Public Sector:Defense procurement in the United States and healthcare system modernization in Australia and Saudi Arabia drive sovereign cloud requirements.
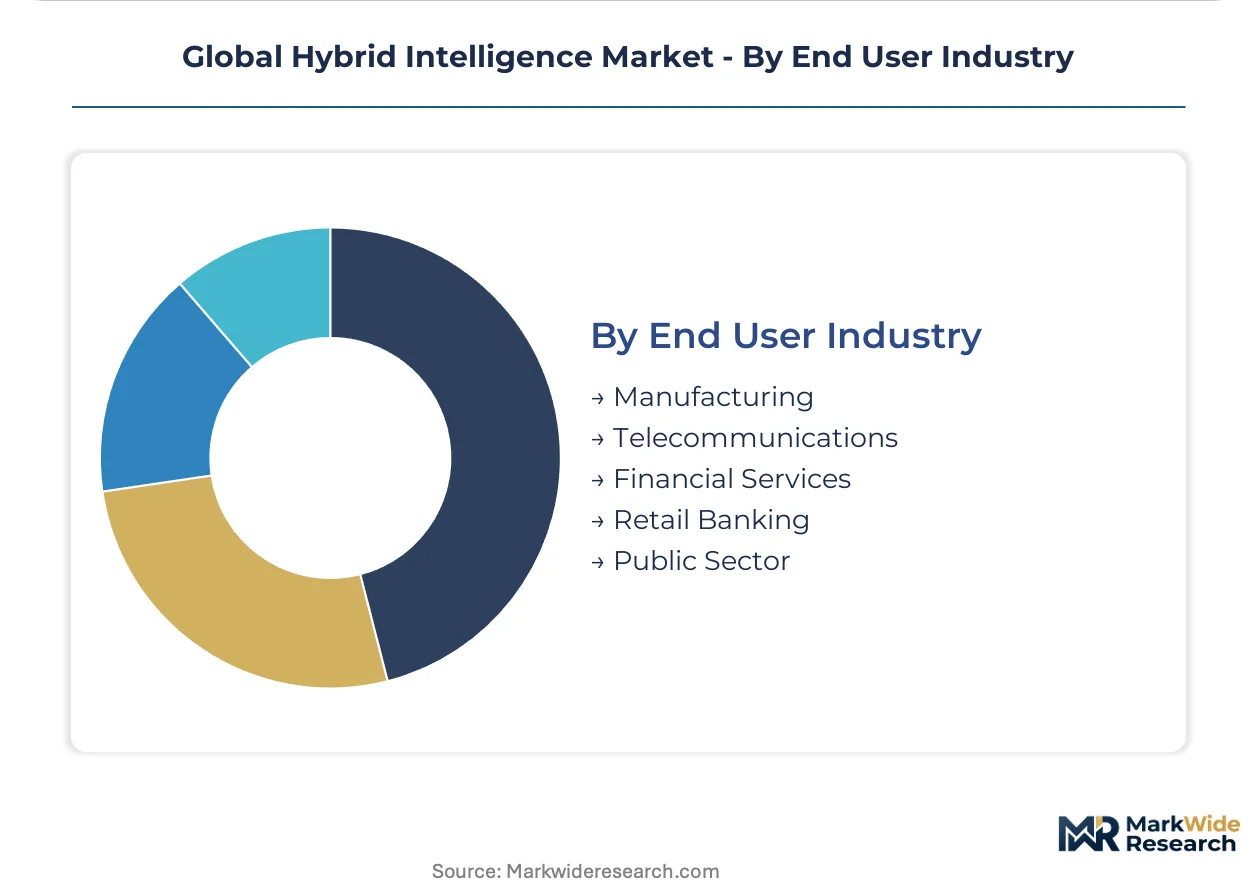
Financial Services commands the largest share of enterprise platform revenue; Public Sector deployment is climbing the fastest on defense and healthcare digitization budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's GPU cluster concentration anchors North American hybrid intelligence infrastructure, while Taiwan's foundry capacity constrains global training hardware availability. Defense procurement in the United States and healthcare digitization in Saudi Arabia concentrate sovereign cloud demand. Regulatory fragmentation between the EU AI Act, FDA guidance, and China's algorithmic transparency rules shapes divergent compliance architectures across jurisdictions.
United States
Defense contractors in Virginia and Maryland drive demand for air-gapped, audit-ready hybrid systems with human-in-the-loop oversight. FDA 510(k) pathways for clinical decision-support systems impose 18-24 month validation timelines that compress first-mover advantages. The Boston healthcare corridor and Seattle cloud engineering clusters anchor enterprise platform development for regulated industries.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg deploy edge-native neural-symbolic fusion for predictive maintenance with sub-10ms latency requirements. EU AI Act conformity assessments mandate pre-market technical documentation for high-risk credit scoring and medical diagnostic applications. Stuttgart's manufacturing engineering ecosystem and Frankfurt's financial compliance centers concentrate procurement of governance-first platforms.
China
MIIT and SAMR enforce algorithmic transparency rules for consumer-facing and industrial AI applications, creating distinct compliance architectures from OECD frameworks. Yangtze River Delta manufacturing clusters and Shenzhen telecom infrastructure projects drive edge computing deployment for latency-sensitive quality control. Domestic foundry investments aim to reduce import dependency for training chipsets.
Saudi Arabia
NEOM smart city construction bypasses legacy integration burdens, enabling native hybrid intelligence infrastructure without retrofit costs. The Public Investment Fund channels sovereign capital into healthcare digitization and defense modernization programs. Riyadh's emerging tech corridor and the Red Sea coastal development zone concentrate greenfield platform deployments.
India
PLI scheme incentives for AI hardware manufacturing reduce import dependency for edge deployment chipsets in telecom infrastructure. RBI and SEBI supervisory frameworks drive demand for auditable risk management systems in Mumbai and Delhi-NCR banking centers. Karnataka's software engineering ecosystem and Tamil Nadu's electronics manufacturing clusters anchor platform development for domestic and export markets.
Global Hybrid Intelligence Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized vertical applications with lighter compliance overhead. The vendor base stratifies across three tiers: cloud hyperscalers with integrated governance stacks, enterprise software incumbents retrofitting legacy platforms, and niche specialists in neural-symbolic fusion. Competitive positioning hardens around audit-ready human oversight capabilities rather than raw predictive accuracy. Consolidation pressure intensifies as outcome-guaranteed contracts with penalty clauses shift risk retention to platform providers.
Within the cloud hyperscaler tier, Microsoft Corporation and Amazon Web Services Inc. anchor enterprise-grade deployment infrastructure across regulated industries. IBM Corporation occupies a distinct position through Watsonx's governance tooling specialization. Google LLC exemplifies research-forward positioning via DeepMind integration and custom silicon development. Oracle Corporation and SAP SE represent enterprise software incumbents retrofitting established ERP footprints with hybrid intelligence layers. Salesforce Inc. sits within the customer engagement specialization vector.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| Microsoft Corporation |
| Google LLC |
| Amazon Web Services Inc. |
| Oracle Corporation |
| SAP SE |
| Salesforce Inc. |
| Intel Corporation |
| Open Text Corporation |
| Others |
Supply & Pricing Matrix
GPU cluster procurement costs cascade through three distinct pricing tiers for hybrid intelligence platforms, with NVIDIA H100 availability constraints at Taiwan-based foundries compressing margins for on-premises deployments while cloud-based consumption models absorb volatility through subscription structures.
Pricing Analysis
Warranty and implementation service bundling now separates premium-tier hybrid intelligence contracts from standard software licensing, with outcome-guaranteed deployments commanding substantial premiums over unbundled SaaS subscriptions. Pricing stratifies across enterprise-grade governance platforms, mid-market cloud tiers, and economy RPA retrofit packages, with certification-grade EU AI Act compliance modules driving the widest spreads. Cost compression in the mid-market tier intensifies as hyperscalers absorb training infrastructure overhead, though defense contractors exhibit minimal price sensitivity due to sovereign cloud mandates. Healthcare systems in Germany and the United States face the steepest procurement constraints from extended FDA 510(k) validation timelines.
Supply Chain Analysis
Advanced GPU and custom AI accelerator supply rests on Taiwan, South Korea, and United States manufacturing capacity, with TSMC foundry allocation cycles determining training hardware availability for enterprise deployments. Photolithography equipment, high-bandwidth memory modules, and liquid cooling systems constitute critical input dependencies with extended procurement lead times. Single-source vulnerability in EUV lithography tooling creates structural bottlenecks for domestic foundry buildouts in India and Saudi Arabia. Distribution runs through direct hyperscaler marketplaces for cloud-based consumption, while on-premises deployments channel through specialized systems integrators with air-gapped security clearances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outcome-guaranteed contracting with penalty clauses is accelerating vendor consolidation, forcing capital-constrained specialists toward acquisition or exit as risk retention shifts to platform providers.
For Market Incumbents: Extend governance-first platform architectures into adjacent compliance verticals, embedding pre-certified EU AI Act and FDA audit trail modules to capture procurement mandates from regulated buyers. Fortify position through backward integration into custom silicon development, reducing dependency on NVIDIA allocation cycles while securing training cost advantages against emerging entrants. For New Entrants and Emerging Players: Launch via sovereign cloud partnerships in Saudi Arabia and India's greenfield digitization projects, where legacy ERP retrofit burdens are absent. Target edge-native predictive maintenance applications in German automotive supplier networks, penetrating through latency-optimized neural-symbolic fusion rather than competing against hyperscaler scale in centralized training. For Investors and Strategic Acquirers: FDA 510(k) clearance receipt for clinical decision-support modules is the leading indicator that specialist vendors have achieved defensible regulatory moats worth premium valuation multiples. Prioritize acquisition targets with pre-built conformity assessment documentation and captive human-in-the-loop calibration expertise, watching for EU AI Act high-risk system registry enrollment as the validation signal for compliance-ready platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Combines Watsonx governance tooling with Azure cloud infrastructure for seamless EU AI Act compliance deployment. |
| Acquisition of Specialist Firm | Absorbs neural-symbolic fusion expertise to satisfy FDA explainability mandates in clinical decision-support. |
| Strategic Partnership | Aligns hyperscaler training capacity with Saudi sovereign cloud requirements for NEOM healthcare digitization. |
| Product Launch | Introduces edge-native inference nodes targeting German automotive predictive maintenance latency thresholds. |
| Geographic Expansion | Establishes India-based AI hardware manufacturing under PLI scheme incentives for telecom infrastructure deployment. |
Research Methodology
Independent corroboration across CTO interviews at financial services firms in London and Singapore, platform engineering leads at German automotive suppliers, and procurement officers at US defense contractors underwrites the qualitative findings. Secondary validation draws from FDA 510(k) submission databases, EU AI Act high-risk system registries, hyperscaler capex disclosures, and OECD AI policy frameworks. Bottom-up segmentation modeling triangulates against top-down regulatory mandate analysis across the analysis window.
Rate-of-change decomposition separates baseline adoption velocity from regulatory acceleration effects and technology substitution dynamics throughout the forecast period. Segmentation dimensions span deployment architecture, solution layer technology stack, end-use application maturity, and regional compliance framework cluster. CAGRs derive from installed base evolution curves weighted against procurement cycle timing and validation timeline constraints specific to FDA-regulated clinical decision-support and EU AI Act conformity assessments.
Foundry capacity allocation disruptions, FDA guidance revisions on human-in-the-loop oversight thresholds, and EU AI Act enforcement intensity variations are the dominant revision risks to modeled outcomes. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
Global Nano Batteries Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Next Generation Processors Market
Emerging and Next Generation Technologies
Printed Electronics Market
Emerging and Next Generation Technologies
Global Terahertz Technology Market
Emerging and Next Generation Technologies
Asia Pacific Quantum Computing Market
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market