
 IGZO Display Market | 2026-2036
IGZO Display Market Size, Share, and Industry Trends Forecast 2026-2036
IGZO Display Market Outlook
Japan is narrowing its historical lead in IGZO TFT substrate production as South Korea and Taiwan expand oxide semiconductor deposition capacity. Sharp Corporation leverages decades of IGZO R&D at its Kameyama facility to sustain technology leadership in large-format panels. Samsung Electronics anchors its premium tablet and laptop display supply through captive IGZO oxide semiconductor lines. AU Optronics Corp competes aggressively in the automotive segment with high-refresh-rate IGZO variants for next-generation cockpit systems.
IGZO (indium gallium zinc oxide) denotes a semiconducting material deposited as a thin-film transistor layer, enabling electron mobility exceeding amorphous silicon by roughly tenfold while maintaining low off-state leakage current. This composition permits thinner transistor channels, higher pixel densities, and reduced power consumption in displays ranging from medical imaging monitors to mobile devices. LCD panels incorporating IGZO backplanes currently occupy the largest revenue share due to mature yield rates and cost-optimized manufacturing infrastructure. OLED-IGZO hybrid architectures represent the fastest-expanding segment as manufacturers seek to merge oxide stability with organic emitter efficiency. Gaming monitors and professional content-creation laptops concentrate margin pools, with buyers prioritizing color accuracy and variable refresh performance over absolute panel cost.
Japan's METI enforces energy-efficiency benchmarks for display equipment sold domestically, directly shaping IGZO product roadmaps toward lower-power oxide variants. South Korea's MFDS and the EU REACH framework regulate indium sourcing and gallium supply-chain transparency, adding compliance layers to raw material procurement. The EU F-Gas Regulation further tightens process gas standards for display fabrication, elevating capital requirements for new entrants. Stakeholders must monitor oxide semiconductor patent expirations and deposition equipment lead times to calibrate capacity commitments against demand inflection points.
Market Dynamics
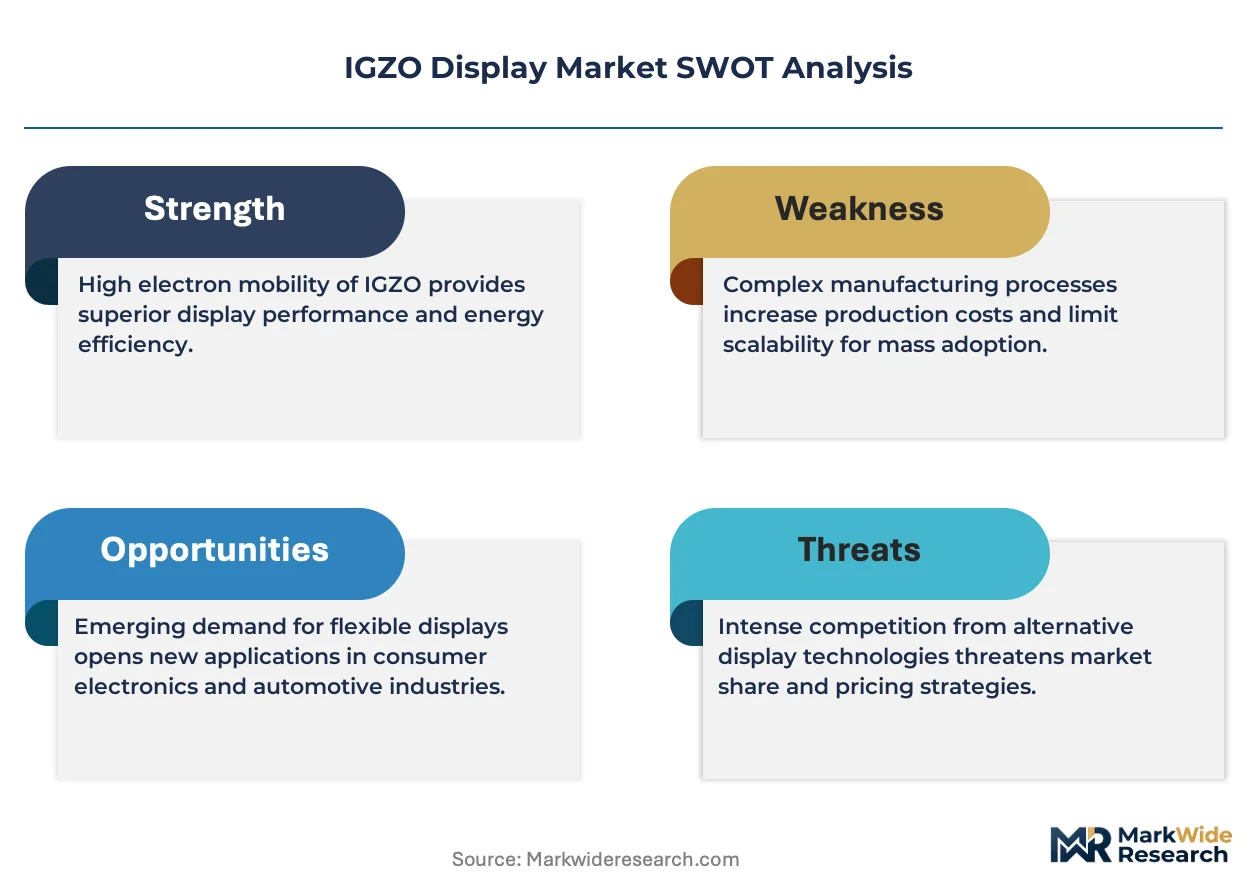
Oxide semiconductor deposition capacity constraints in East Asia are forcing display manufacturers to prioritize IGZO backplanes for high-margin segments over commoditized LCD volume, compressing supply timelines for automotive and medical imaging buyers.
Growth Catalysts
- Automotive cockpit digitization:OEMs in Germany and Japan mandate higher pixel density for instrument clusters and head-up displays, pulling IGZO adoption into vehicle platforms. This demand concentrates in premium electric vehicle lineups where power efficiency directly extends range.
- China's GB 21520-2023 energy efficiency standards:Tightened display power consumption thresholds favor low-leakage oxide semiconductors over amorphous silicon alternatives. Domestic panel makers accelerate IGZO line conversions to maintain market access.
- OLED-IGZO hybrid architectures:The convergence of oxide transistor stability with organic emitter efficiency opens foldable and rollable form factors previously constrained by silicon backplane rigidity.
Market Restraints
- Indium supply concentration:Primary indium refining clusters in China and South Korea create raw material procurement vulnerability for oxide semiconductor fabs outside these geographies.
- EU F-Gas Regulation compliance costs:Process gas restrictions on fluorinated compounds used in IGZO sputtering elevate capital requirements for new deposition equipment, disadvantaging smaller entrants.
- Amorphous silicon cost floor:Mature a-Si manufacturing infrastructure in Taiwan and China maintains price pressure on oxide alternatives in large-format TV panels where pixel density requirements remain modest.
Strategic Opportunities
- India's PLI scheme for display manufacturing:Production-linked incentives for semiconductor and component ecosystems attract IGZO technology licensing agreements as domestic fabs seek differentiated positioning against Chinese volume.
- Medical imaging monitor refresh cycles:Diagnostic display procurement in the US and EU prioritizes color accuracy and grayscale stability, favoring IGZO backplanes for radiology and pathology workstations.
- Dual carbon goals in China:National emissions targets pressure data center and enterprise IT buyers toward lower-power display technologies, creating regulatory tailwinds for IGZO adoption in commercial monitor fleets.
Industry Challenges
- Oxide semiconductor process engineering talent scarcity:Deposition uniformity control and defect management require specialized expertise concentrated in Japan and South Korea, limiting fab expansion timelines.
- Patent licensing complexity:IGZO fundamental patents held by Japanese research consortia and Korean electronics groups create cross-licigation friction for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IGZO Display Market |
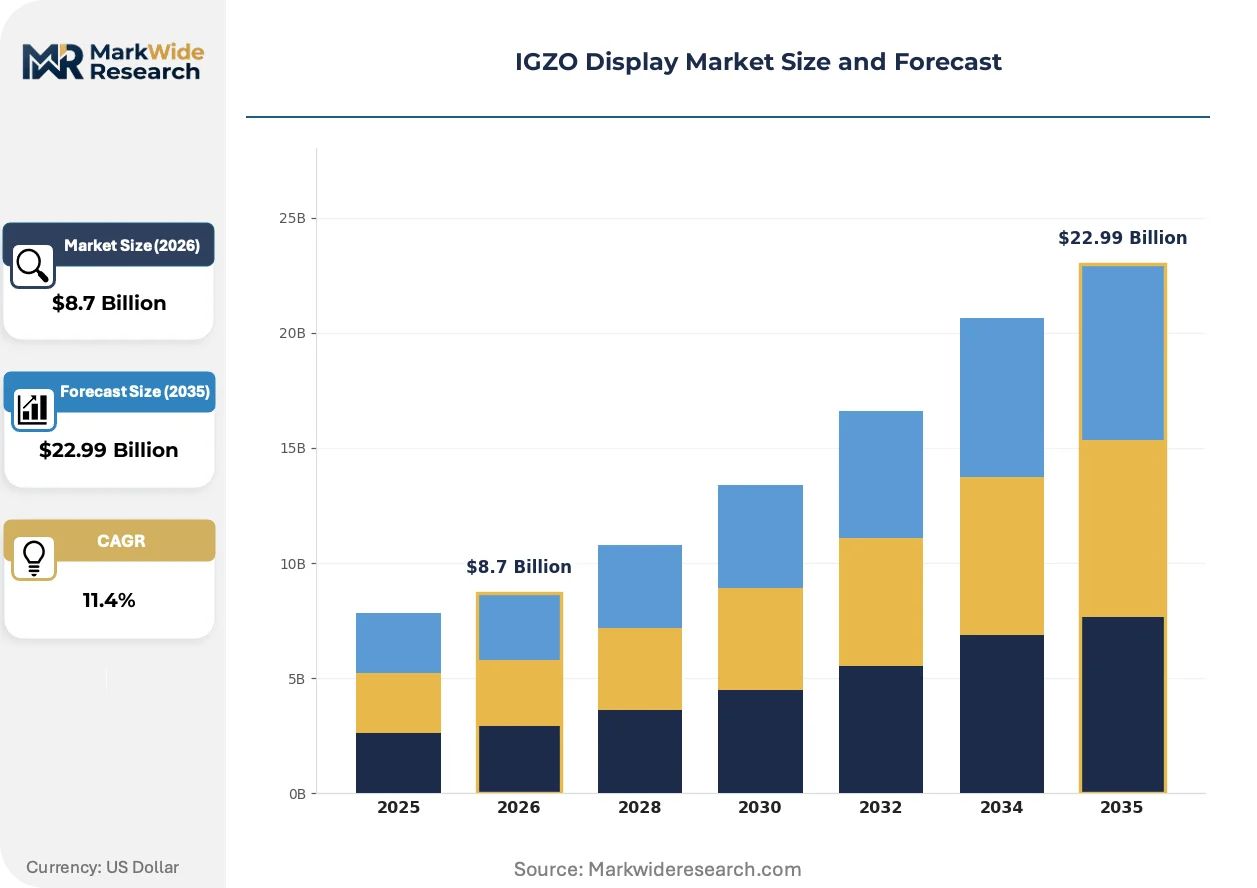
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, MicroLED, AMOLED Technology: In-Cell Touch, Edge-Lit, Direct-Lit, Backlit Application: Smartphones, Tablets, TVs, Laptops End User: Consumer Electronics, Industrial Applications, Automotive Display, Gaming |
| Companies Covered | ASUSTeK Computer Inc, Samsung Electronics, Apple Inc, Sharp Corporation, LG Electronics, Sony Corporation, AU Optronics Corp, Asus, FUJITSU, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IGZO Display Market Strategic Shifts
IGZO technology trajectories center on backplane architecture convergence, regulatory-driven material substitution, and buyer procurement model compression that favors specification-driven sourcing over brand loyalty.
Micro-oxide transistor integration is rendering obsolete conventional amorphous silicon backplanes in professional content-creation laptops. Post-production houses and animation studios in California and London now specify IGZO panels for 4K/8K color-grading workstations. The technology is rendering obsolete legacy silicon-based supply contracts that locked buyers into annual refresh cycles.
Japan's METI energy-efficiency benchmarks for display equipment sold domestically now mandate standby power thresholds that effectively exclude non-oxide backplanes from premium product tiers. Domestic manufacturers Sharp and Japan Display accelerate low-power IGZO variant roadmaps to maintain shelf placement in electronics retail. Professional monitor and high-end tablet segments absorb compliance costs fastest, passing efficiency premiums to enterprise buyers with sustainability procurement mandates.
Direct specification sourcing from panel makers is displacing traditional distribution through branded OEM intermediaries in the gaming monitor segment. Esports organizations and competitive gaming venues in South Korea and the US now contract AU Optronics and Samsung Display directly for high-refresh-rate IGZO variants. This channel compression concentrates volume with fabs capable of custom refresh-rate tuning and reduces margin capture by monitor assemblers lacking deposition expertise.
IGZO Display Market Segmentation
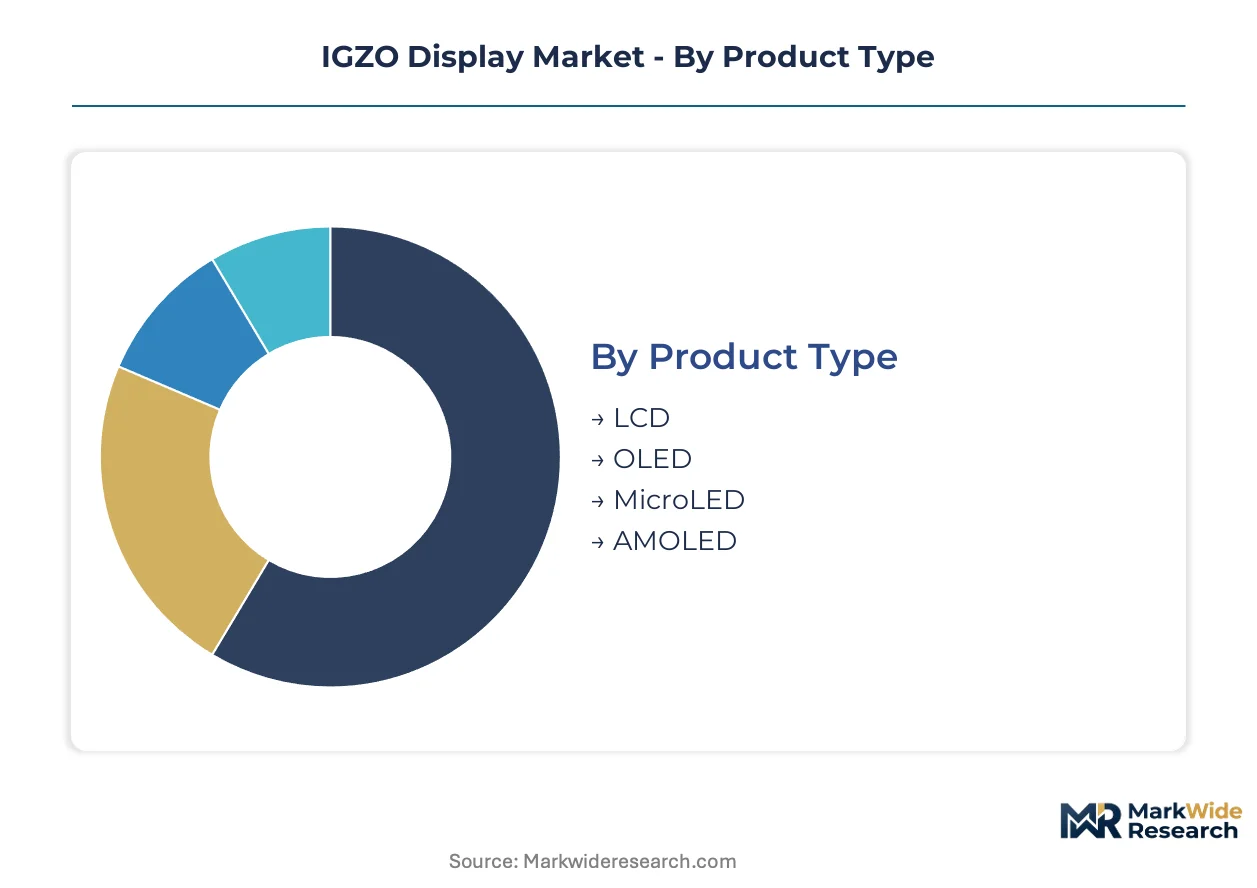
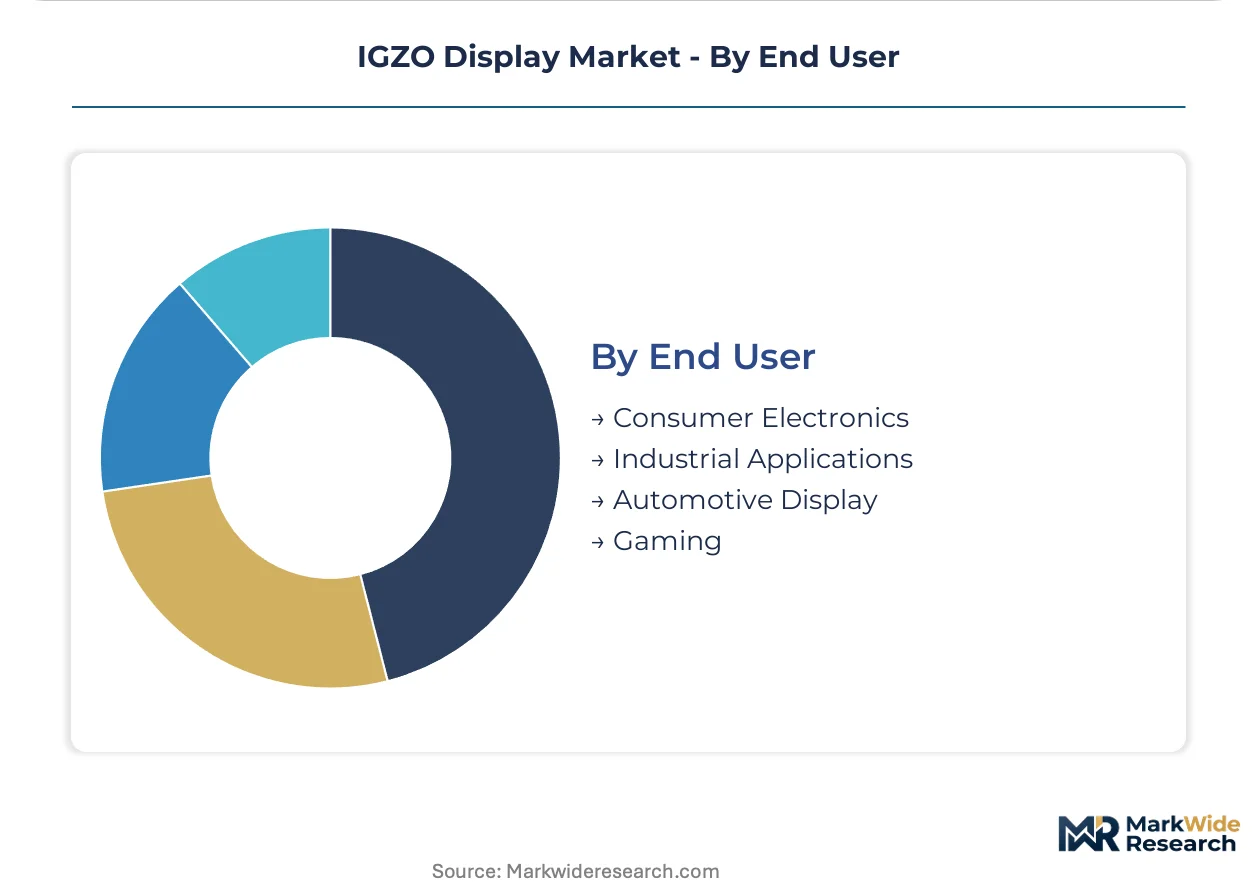
IGZO display procurement cycles vary dramatically across end-use segments, with automotive qualification timelines stretching years while consumer electronics refresh annually. Understanding these velocity differentials helps manufacturers calibrate capacity commitments against margin profiles and technical requirements.
Product Type:
LCD panels turn inventory fastest in high-volume consumer segments, whereas MicroLED and AMOLOED variants face extended validation cycles in medical and military applications.
- LCD:Mature IGZO backplane integration dominates current manufacturing infrastructure. Automotive instrument clusters in Germany and Japan pull steady volume for this segment, constrained by amorphous silicon cost competition in undifferentiated TV panels.
- OLED:Hybrid IGZO-oxide architectures enable foldable form factors previously blocked by silicon backplane rigidity. Samsung Display and LG Display concentrate capacity in South Korea for premium tablet and laptop supply, with China's BOE accelerating line conversions to capture domestic brand demand.
- MicroLED:Extended development timelines concentrate investment in Apple and Samsung pilot lines for watch and near-eye display applications.
- AMOLED:Active-matrix variants command premium positioning in flagship smartphones with refresh rates exceeding 120Hz.
LCD anchors the volume base while OLED gains share at the steepest rate.
Technology:
Cost tier stratification separates in-cell touch premium positioning from edge-lit economy configurations in commercial monitor procurement.
- In-Cell Touch:Integrated touch-layer deposition reduces stack thickness and assembly steps. Notebook manufacturers in Taiwan specify this variant for ultrabook lines where z-height constraints exclude discrete touch modules.
- Edge-Lit:Thin light-guide plate designs dominate large-format TV cost engineering. Chinese panel makers leverage this technology for domestic retail price positioning against Korean premium alternatives.
- Direct-Lit:Full-array local dimming variants concentrate in professional content-creation monitors where contrast ratio specifications determine purchase decisions.
- Backlit:Conventional LED array configurations persist in industrial displays with decade-long replacement cycles and minimal power optimization requirements.
Edge-lit configurations dominate shipment volume while in-cell touch commands the widest margin expansion trajectory.
Application:
Customer type concentration separates enterprise procurement discipline from volatile consumer demand patterns across device categories.
- Smartphones:Annual flagship refresh cycles drive IGZO adoption in high-refresh-rate panels. Chinese OEMs Xiaomi and OPPO specify oxide backplanes for gaming-optimized sub-brands targeting domestic esports audiences.
- Tablets:Professional creative workflows in California post-production houses prioritize color accuracy over absolute cost, sustaining premium IGZO positioning against LCD alternatives.
- TVs:Commoditized large-format panels face persistent amorphous silicon price pressure, limiting IGZO penetration to 8K resolution tiers where electron mobility requirements exclude silicon backplanes.
- Laptops:Enterprise fleet procurement under China's dual carbon goals favors low-leakage oxide variants for data center operator monitor deployments.
Smartphone panels generate the highest absolute revenue while laptop applications climb fastest on enterprise sustainability mandates.
End User:
Supply concentration patterns concentrate IGZO deposition capacity in East Asian clusters serving distinct buyer archetypes with divergent technical specifications.
- Consumer Electronics:Volume concentration in Chinese manufacturing clusters serves seasonal demand peaks with compressed lead times. Domestic brands Huawei and Honor accelerate IGZO adoption in premium tablet lines to differentiate against Samsung.
- Automotive Display:Extended qualification timelines with German and Japanese OEMs favor established suppliers Sharp and Japan Display. Head-up display pixel density requirements mandate oxide semiconductor performance silicon cannot match.
- Industrial Applications:Decade-long replacement cycles and minimal power optimization requirements sustain legacy amorphous silicon preference, limiting IGZO penetration to medical imaging where grayscale stability determines procurement.
- Gaming:Esports venues in South Korea and the US contract panel makers directly for high-refresh-rate variants, bypassing traditional OEM distribution and compressing margin capture by monitor assemblers.
Consumer electronics absorbs the largest production volume while automotive display expands most quickly on cockpit digitization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IGZO deposition capacity clusters in East Asian manufacturing hubs where oxide semiconductor expertise concentrates. Japan, South Korea, Taiwan, and China each host distinct competitive ecosystems shaped by regulatory frameworks and end-use demand patterns.
Japan
Automotive cockpit digitization by Toyota and Honda drives IGZO demand for high-resolution instrument clusters. METI enforces standby power thresholds that effectively exclude non-oxide backplanes from premium domestic product tiers. Sharp Corporation leverages decades of R&D at its Kameyama facility to sustain technology leadership in large-format panels.
South Korea
Samsung Electronics anchors premium tablet and laptop display supply through captive IGZO oxide semiconductor lines. MFDS regulations govern indium sourcing transparency, adding compliance layers to raw material procurement. Seoul-based deposition fabs prioritize high-refresh-rate variants for gaming monitor exports to North American esports venues.
Taiwan
AU Optronics competes aggressively in automotive segments with high-refresh-rate IGZO variants for next-generation cockpit systems. The island's semiconductor equipment ecosystem supports rapid oxide line conversions. Hsinchu Science Park hosts concentrated TFT substrate engineering talent critical for deposition uniformity control.
China
GB 21520-2023 energy efficiency standards tighten display power consumption thresholds, favoring low-leakage oxide semiconductors over amorphous silicon alternatives. BOE accelerates line conversions to capture domestic brand demand for premium tablets. Yangtze River Delta panel makers face indium supply concentration risks from domestic refining clusters.
United States
Professional content-creation workflows in California post-production houses prioritize IGZO panels for 4K/8K color-grading workstations. FCC equipment authorization requirements shape product roadmaps for medical imaging monitors. Austin and Seattle tech corridors drive enterprise fleet procurement under sustainability mandates favoring low-power display technologies.
IGZO Display Market Competitive Environment
Integrated electronics conglomerates and specialized display fabricators split the market between captive supply chains and merchant panel sales. The vendor base concentrates around three strategic archetypes: diversified technology groups with in-house semiconductor deposition, pure-play display specialists with oxide TFT expertise, and vertically integrated device OEMs securing dedicated backplane supply. Competitive moves center on capacity expansion in East Asian clusters and strategic technology licensing to circumvent patent thickets held by Japanese research consortia.
Within the diversified technology group tier, Samsung Electronics and LG Electronics exemplify scale-driven positioning through captive IGZO lines serving premium consumer electronics portfolios. Sharp Corporation and AU Optronics Corp occupy specialist archetype positions, with the former leveraging historical R&D depth and the latter concentrating on high-refresh-rate automotive variants. Apple Inc represents the vertically integrated device OEM archetype, securing dedicated backplane supply through long-term fabrication partnerships rather than in-house deposition capacity.
| Leading Market Players |
|---|
| ASUSTeK Computer Inc |
| Samsung Electronics |
| Apple Inc |
| Sharp Corporation |
| LG Electronics |
| Sony Corporation |
| AU Optronics Corp |
| Asus |
| FUJITSU |
| Others |
Value Chain & Pricing Dynamics
Indium refining concentration in China and South Korea concentrates pricing power upstream, forcing display fabs outside these geographies to absorb raw material premiums or surrender margin in downstream automotive and medical segments.
Pricing Analysis
China's GB 21520-2023 energy efficiency standards dictate the pricing tier structure by mandating standby power thresholds that exclude non-oxide backplanes from premium domestic product tiers. Pricing stratifies across premium IGZO variants for automotive head-up displays, standard oxide backplanes for commercial monitors, and economy amorphous silicon alternatives for undifferentiated TV panels. Cost compression in large-format LCD tiers is intensifying because mature a-Si manufacturing infrastructure in Taiwan and China maintains price pressure. Gaming monitor buyers demonstrate the lowest price sensitivity, prioritizing refresh-rate performance over panel cost, while TV procurement teams remain the most margin-conscious.
Supply Chain Analysis
Indium feedstock draws from primary refining clusters in China and South Korea, with gallium sourcing concentrated in Chinese bauxite processing facilities. IGZO backplane manufacturing sources from deposition equipment fabricators in Japan, sputtering target suppliers in South Korea, and TFT substrate specialists in Taiwan. Single-source vulnerability in indium procurement creates structural risk for oxide semiconductor fabs outside East Asian refining geographies. Distribution runs through direct specification contracts between panel makers and automotive OEMs, bypassing traditional monitor assembler intermediaries in high-margin segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IGZO display adoption is accelerating on automotive cockpit digitization and China's tightening energy efficiency mandates, creating a high-growth disruption window for stakeholders positioned across oxide semiconductor value chains.
For Market Incumbents: Entrench technology leadership through captive indium sourcing partnerships in South Korean refining clusters and accelerated low-power variant R&D to meet Japan's METI standby power thresholds. Defend against emerging Chinese panel makers by securing multi-year automotive qualification contracts with German and Japanese OEMs before BOE completes line conversions. Capacity addition in Taiwan's Hsinchu Science Park reinforces deposition uniformity control capabilities that new entrants cannot replicate quickly. For New Entrants and Emerging Players: Establish a beachhead in India's display manufacturing ecosystem by licensing IGZO technology to domestic fabs seeking differentiation under the PLI scheme. Target medical imaging monitor refresh cycles in the US and EU where diagnostic procurement prioritizes grayscale stability over absolute cost. Pursue direct contracting with esports venues in South Korea and North America as a go-to-market angle that bypasses established OEM distribution channels. For Investors and Strategic Acquirers: Capital is best deployed toward oxide semiconductor deposition specialists with established automotive qualification relationships and patent licensing clarity. Long-term viability hinges on regulatory tailwinds from dual carbon goals in China and energy efficiency mandates in Japan sustaining premium positioning for low-leakage alternatives. Watch patent expiration schedules for Japanese research consortium holdings as an inflection indicator for licensing cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Oxide Semiconductor Line Conversion | BOE and domestic Chinese panel makers accelerate IGZO capacity to meet GB 21520-2023 compliance deadlines. |
| Automotive Qualification Partnership | Sharp and Japan Display secure multi-year supply contracts with Toyota and Honda for head-up display panels. |
| Indium Sourcing Agreement | Samsung Electronics anchors raw material transparency through MFDS-compliant South Korean refining partnerships. |
| Direct Channel Establishment | AU Optronics contracts directly with Seoul and Los Angeles esports venues for high-refresh-rate variants. |
| Low-Power Variant Development | Japan Display accelerates roadmaps to maintain shelf placement under METI standby power thresholds. |
Study Parameters
Cross-validation between primary interviews with TFT substrate engineers, automotive display procurement managers, deposition equipment specialists, and oxide semiconductor R&D directors and secondary validation through SEC filings, customs trade data, and METI regulatory disclosures anchors the qualitative findings. Bottom-up capacity assessments at Kameyama, Hsinchu Science Park, and Yangtze River Delta fabrication facilities triangulate against top-down demand modeling across automotive, gaming, and medical end-use segments.
Calibration against historical IGZO adoption curves in tablet and laptop categories informs the analytical framework across the projection horizon. Segmentation dimensions modeled include backplane architecture, pixel density tier, refresh rate specification, and regional regulatory cluster. CAGRs derive from supply-demand balance analysis incorporating deposition equipment lead times and automotive qualification cycle durations. Forecast inputs capture China's dual carbon goal implementation pace and EU F-Gas Regulation compliance cost trajectories.
Sensitivities concentrate around indium supply disruptions from Chinese refining capacity constraints and patent litigation outcomes affecting Japanese research consortium licensing terms. Forecasts reflect assumptions regarding oxide semiconductor yield improvement rates and automotive OEM platform standardization timelines. Cross-checking against SEMI equipment spending disclosures and display panel shipment data from regional trade associations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Privacy Screens Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
Flexible Screens Market
Display Technologies
Dot Matrix Display Market
Display Technologies
Electronic Paper Display (EPD) Market
Display Technologies
4K VR Displays Market
Display Technologies
Gaming Monitors Market
Display Technologies
Asia-Pacific E-Paper Display Market
Display Technologies
OLED Laptops Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Foldable Screens Market