
 Flexible Display Market | 2026-2036
Flexible Display Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Display Market Intelligence
The immense capital investment needed for advanced fabrication plants is narrowing the competitive field to established firms with deep financial reserves. This capital barrier solidifies the market position of incumbents. Samsung Display leverages its dominant position and scale in mobile AMOLED production. LG Display differentiates with its large-format flexible OLEDs for premium televisions and digital signage. BOE Technology Group aggressively expands its manufacturing capacity to serve China's vast domestic electronics market.
A flexible display is an electronic visual output constructed on a non-rigid substrate, such as polyimide plastic or thin metal foil. This unique construction allows the screen to be bent, folded, or rolled without damage. Its primary commercial purpose is to enable new device form factors where traditional rigid screens are impractical or limiting. AMOLED technology currently leads the high-performance segment, while foldable smartphones represent the principal application driving material science advancements.
Compliance is governed by a patchwork of global electronics standards. The EU’s RoHS directive restricts specific hazardous substances, impacting material selection for all display components. In the United States, FCC regulations set emissions standards for devices integrating these screens, while IEC standards define durability testing protocols. Future profitability will depend on developing materials and manufacturing processes that align with tightening e-waste and circular economy mandates.
Market Dynamics
The market's structure is defined by the immense capital required for advanced flexible substrate fabrication. This financial barrier concentrates production among a few incumbent suppliers in Asia, creating high dependency for global original equipment manufacturers and limiting new market entrants.
Growth Catalysts
- Material Science Advancement:Innovations in polyimide (PI) films and thin-film encapsulation (TFE) are improving durability and flexibility. This enables novel product designs like rollable and stretchable displays, expanding the addressable market beyond foldable smartphones into areas like smart appliances and architectural lighting.
- Foldable Smartphone Adoption:The primary demand driver is the consumer electronics sector, specifically the expanding category of foldable smartphones. Strong consumer interest in these new form factors is directly fueling investment in next-generation flexible panel production capacity.
- Automotive Integration:The automotive industry's push towards digital cockpits and connected cars creates significant demand for non-planar, curved, and free-form displays. These screens are used for instrument clusters, infotainment systems, and passenger-side displays, representing a high-value application segment.
Market Restraints
- High Capital Expenditure:Building and equipping a fabrication plant for flexible displays requires billions in investment. This high barrier to entry restricts competition and concentrates supply chain risk among a small number of manufacturers, primarily in South Korea and China.
- Manufacturing Yield Complexity:Achieving consistently high production yields for large-format flexible OLED panels remains a significant technical hurdle. Defects in the complex multi-layer structure lead to high scrap rates and increased manufacturing costs, impacting overall profitability.
- Durability and Longevity Concerns:Despite improvements, flexible screens remain more susceptible to scratches, creases, and damage from repeated bending compared to their rigid glass counterparts. These reliability concerns can slow adoption in demanding applications and affect consumer confidence.
Strategic Opportunities
- Wearable and Medical Devices:The development of ultra-thin, conformable displays opens opportunities in next-generation wearables and medical sensors. Applications include smart textiles with integrated displays, electronic skin patches for health monitoring, and flexible diagnostic tools.
- Augmented and Virtual Reality:High-resolution, high-refresh-rate flexible micro-displays are critical components for creating lightweight and ergonomic AR and VR headsets. This emerging category presents a significant long-term growth opportunity as metaverse applications develop.
- Aerospace and Defense:The demand for lightweight, rugged, and conformable displays in military hardware and aircraft cockpits provides a niche, high-margin opportunity. These applications require displays that can withstand extreme environmental conditions and fit into unconventional spaces.
Industry Challenges
- Standardization Gaps:A lack of universal standards for flexible display testing and reliability, governed by bodies like the IEC, creates challenges for device integration. OEMs face inconsistencies in performance metrics like bend radius and cycle endurance across different suppliers.
- E-Waste and Recyclability:The complex, multi-material composition of flexible displays makes them difficult to recycle. Upcoming circular economy mandates, particularly from the EU, are forcing manufacturers to invest in sustainable design and end-of-life processing, adding cost and complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Display Market |
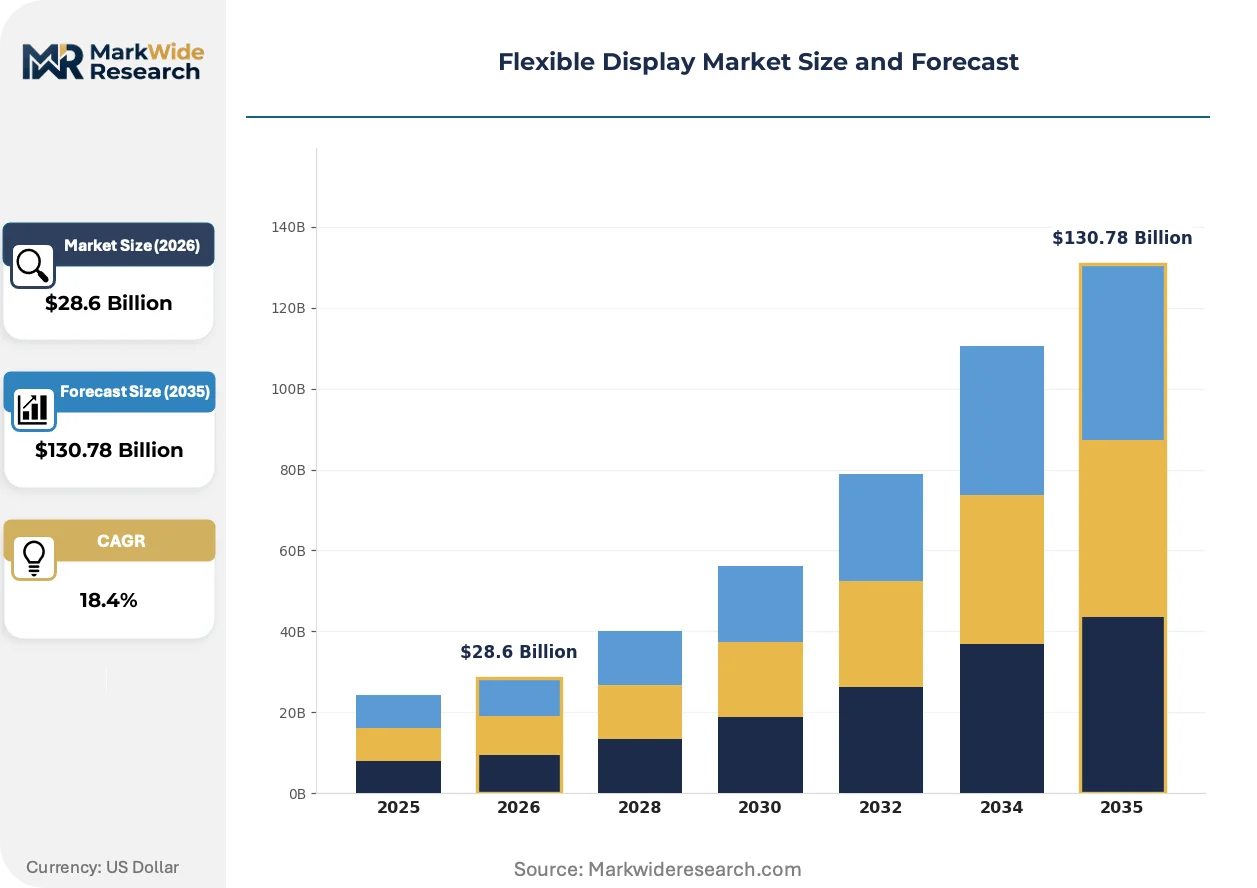
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $130.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OLED, AMOLED, E-Paper, LCD, Quantum Dot Technology: Plastic Substrate, Metal Foil, Thin Glass, Electronic Paper, Organic Semiconductor Application: Smart Wearables, Foldable Smartphones, Digital Signage, Automotive Instrumentation, Consumer Electronics End User: Electronics Manufacturers, Telecommunications Providers, Automotive Systems Integrators, Retail Display Firms |
| Companies Covered | Samsung Display Co., Ltd., LG Display Co., Ltd., BOE Technology Group Co., Ltd., Royole Corporation, AU Optronics Corp., Sharp Corporation, Innolux Corporation, Visionox Technology Inc., FlexEnable Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Display Market Strategic Shifts & Innovations
Material science breakthroughs are fundamentally changing device design, moving beyond rigid rectangular formats toward dynamic, integrated surfaces. This evolution is enabling displays to conform to new shapes, unlocking applications previously limited by the constraints of glass-based screens.
Advanced Substrate Materials
Colorless polyimide (CPI) and ultra-thin glass (UTG) are the two leading materials for the protective cover window in foldable devices. CPI offers superior flexibility and impact resistance, while UTG provides a premium feel and better scratch resistance. The choice between these materials involves a direct trade-off between durability and the user's tactile experience, influencing the final product design and cost in the premium smartphone segment.
Regulatory Focus on Repairability
The EU’s Right to Repair framework and similar initiatives in North America are pressuring electronics manufacturers to design more modular and repairable products. For flexible displays, this is a significant challenge due to the use of strong adhesives and integrated components. The trend is compelling display makers and OEMs to explore new assembly techniques and debondable adhesives that facilitate screen replacement without damaging other components.
Integration with Haptics and Sensors
A key innovation involves embedding sensors and haptic feedback actuators directly into the flexible display stack. This creates more interactive and intuitive user interfaces by providing localized tactile feedback or enabling under-display fingerprint and facial recognition. This trend is most prominent in high-end consumer electronics and automotive dashboards, where it helps reduce physical button clutter and creates a seamless, interactive surface.
Flexible Display Market Segmentation
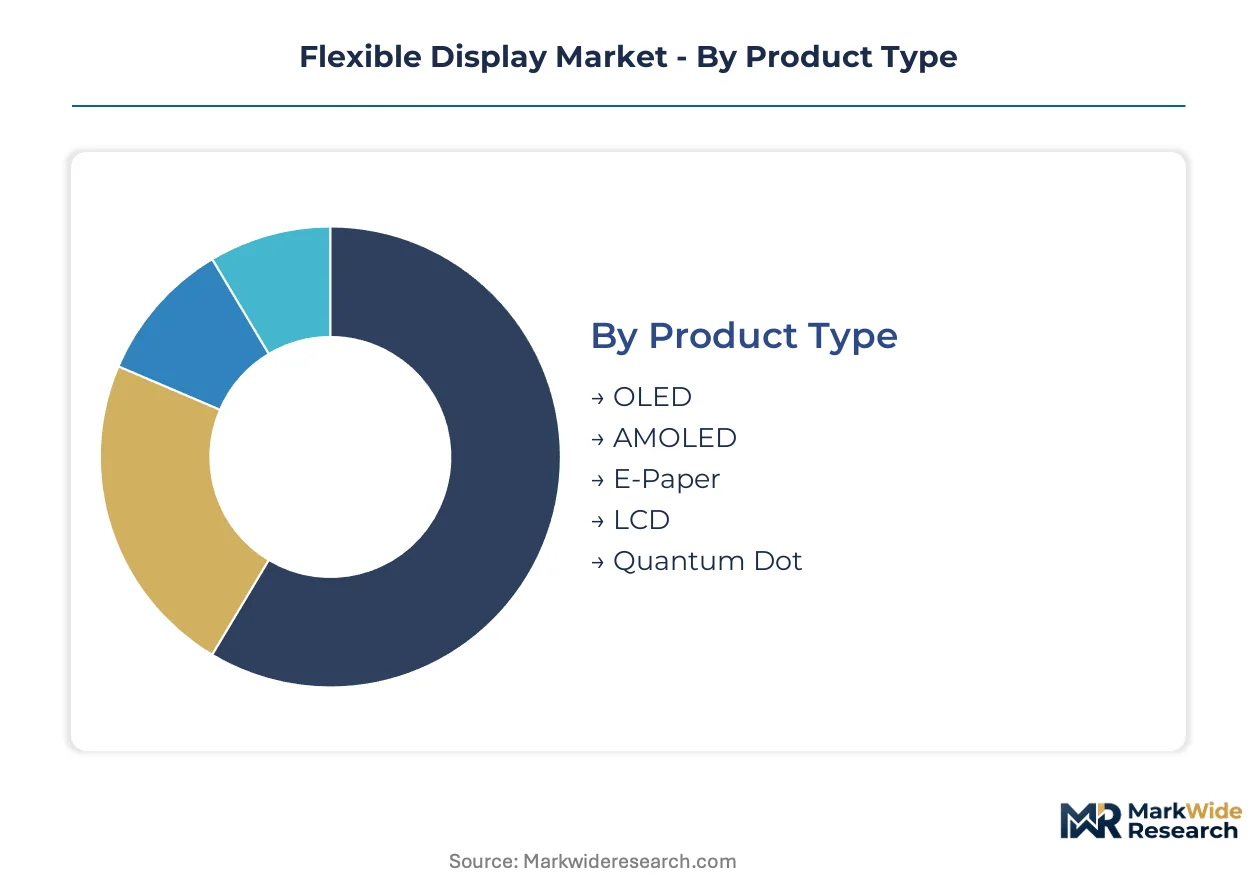
Segmenting the flexible display market reveals distinct technological and application-driven categories. Each segment presents unique characteristics influencing development, production, and end-user adoption. Understanding these divisions is crucial for strategic market positioning and identifying high-growth opportunities within the evolving display landscape.
Product Type:
The product type dimension delineates flexible display technologies based on their core emission and material characteristics.
- OLED:Organic Light-Emitting Diode displays utilize organic compounds that emit light when an electric current passes through them. This technology offers superior contrast ratios and faster response times, with significant demand from premium consumer electronics manufacturers.
- AMOLED:Active Matrix Organic Light-Emitting Diode technology incorporates a thin-film transistor (TFT) array behind each pixel, allowing for independent pixel control. AMOLED panels are widely adopted in high-end smartphones and wearables, driving material science advancements for improved flexibility.
- E-Paper:Electronic paper displays offer low power consumption and high readability in various lighting conditions. These displays are primarily used in e-readers and smart labels.
- LCD:Liquid Crystal Display technology, while traditionally rigid, is being adapted for some flexible applications. It finds use in specific industrial and automotive display contexts.
- Quantum Dot:Quantum dot displays enhance color accuracy and brightness, often used in conjunction with LCD or OLED panels. This technology improves visual performance in advanced display products.
OLED commands the established display base. The steepest expansion runs through AMOLED.
Technology:
Technological advancements define the substrate materials enabling flexible display functionality and durability.
- Plastic Substrate:These displays are constructed on flexible polymer films like polyimide (PI), offering high resilience to bending and impact. Plastic substrate technology is foundational for foldable smartphones, with significant adoption in South Korea and China.
- Thin Glass:Ultra-thin glass (UTG) substrates provide a premium feel and superior scratch resistance compared to plastic, while still allowing for significant bending. UTG is increasingly used as a cover window in high-end foldable devices.
- Metal Foil:Displays built on thin metal foils offer extreme durability and lightweight properties. This technology is employed in specialized industrial and defense applications.
- Electronic Paper:This technology relies on microcapsules containing charged pigments, creating a bistable image. Electronic paper is prevalent in e-readers and low-power signage solutions.
- Organic Semiconductor:Organic semiconductor materials are crucial for the active layers within flexible OLED and AMOLED displays. These materials enable efficient light emission and transistor operation.
Innovation in Plastic Substrate drives new form factors, while Thin Glass secures premium device segments.
Application:
The application landscape demonstrates diverse end-use cases leveraging flexible display attributes for novel product designs.
- Foldable Smartphones:This segment represents the primary demand driver, utilizing flexible panels to create devices with larger screens in compact form factors. Consumer interest in innovative designs fuels significant production capacity investments.
- Automotive Instrumentation:Flexible displays are integrated into vehicle cockpits for curved dashboards, infotainment systems, and digital instrument clusters. This application offers high value due to stringent durability and performance requirements.
- Smart Wearables:Flexible screens enable ergonomic and stylish designs for smartwatches, fitness trackers, and other body-worn devices. These products benefit from conformable display surfaces.
- Digital Signage:Flexible displays are used in advertising and information displays, allowing for curved or unconventional shapes in public spaces. Retail firms deploy these for engaging visual content.
- Consumer Electronics:This broad category includes flexible displays in laptops, tablets, and other portable devices beyond smartphones. Manufacturers seek differentiation through innovative form factors.
Demand for Foldable Smartphones is expanding most quickly, leveraging flexible display capabilities.
End User:
Customer types reflect the primary industries and businesses integrating flexible display solutions into their offerings.
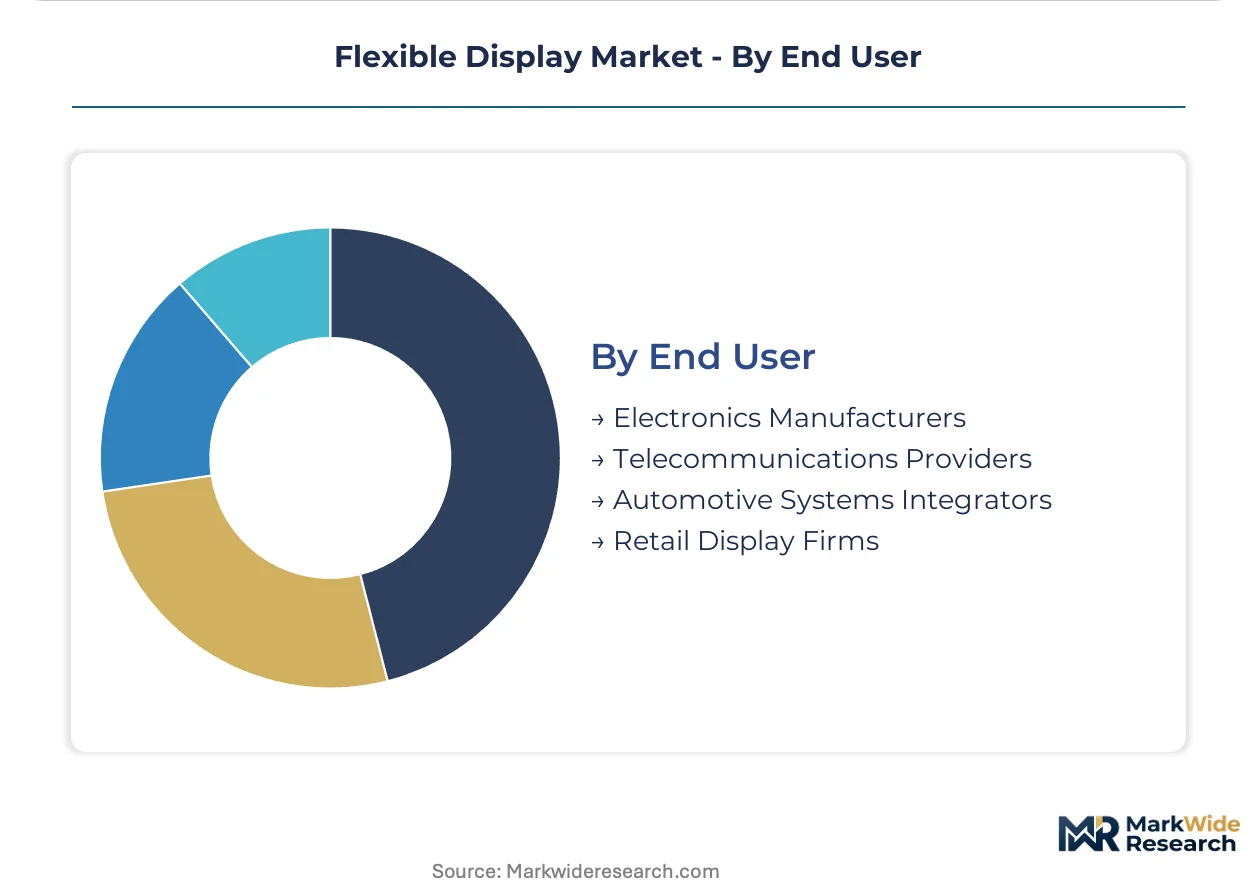
- Electronics Manufacturers:These firms, including major original equipment manufacturers (OEMs), integrate flexible displays into a wide array of consumer electronics. This segment represents the largest volume consumer of flexible panels.
- Automotive Systems Integrators:Companies specializing in vehicle electronics and interior systems procure flexible displays for automotive applications. They develop comprehensive digital cockpit solutions.
- Telecommunications Providers:While not direct display users, these companies influence demand through their device partnerships and network services. They drive adoption of new smartphone form factors.
- Retail Display Firms:Businesses focused on commercial advertising and public information displays utilize flexible screens. They implement innovative signage solutions for various environments.
The primary demand for flexible displays originates from Electronics Manufacturers, with Automotive Systems Integrators representing a high-value niche.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government policies promoting domestic electronics manufacturing are significantly influencing the flexible display market's geographic distribution. These incentives encourage local production and foster innovation within established and emerging display ecosystems. Capital investments are concentrated in regions with robust industrial infrastructure and a skilled workforce.
South Korea
South Korea's robust government support, such as the 'K-Display' initiative, drives advanced display technology development. This nation remains a leader in AMOLED production, benefiting from extensive R&D investments. Major original equipment manufacturers in Seoul and Gyeonggi Province continue to innovate in foldable smartphone designs.
China
China's aggressive industrial policies, including its 'Made in China 2025' strategy, heavily subsidize flexible display manufacturing capacity expansion. The vast domestic electronics market fuels demand for these panels across numerous applications. Production hubs in Shenzhen and Hefei are rapidly increasing output for both local and international brands.
United States
The United States market sees demand from high-end consumer electronics and specialized defense applications, regulated by FCC emissions standards. Federal grants for advanced materials research also support innovation in display substrates. Silicon Valley and other tech clusters drive application development for augmented and virtual reality devices.
Germany
Germany's automotive industry drives demand for flexible displays in digital cockpits, with compliance to EU RoHS directives for material selection. The nation's strong engineering base supports precise integration of these components into vehicle interiors. Automotive manufacturing centers in Bavaria and Baden-Württemberg are key adopters of curved display technologies.
Japan
Japan's Ministry of Economy, Trade and Industry (METI) promotes advanced materials science for flexible display components. The country's display manufacturers focus on high-performance panels for niche applications like medical devices and premium consumer electronics. Research institutions and industrial clusters in Tokyo and Osaka contribute to next-generation display innovations.
Flexible Display Market Key Industry Players
Channel-controlling players compete with product-specialist players, shaping a market structure defined by high capital barriers and technological complexity. The flexible display market exhibits a tiered consolidation, with a few dominant incumbents controlling the majority of advanced panel production. Strategic archetypes include large-scale integrated display manufacturers, niche technology innovators focusing on specific material advancements, and specialized component suppliers. Dominant competitive moves involve significant capacity expansion, particularly in Asia, and strategic partnerships for technology co-development with OEMs.
On the scale-driven vector, Samsung Display Co., Ltd., LG Display Co., Ltd., and BOE Technology Group Co., Ltd. represent the primary manufacturing powerhouses. These established entities exemplify the capital-intensive nature of flexible display production, anchoring significant global supply. Their corporate structures, often including "Co., Ltd." suffixes, indicate large-scale, diversified operations. These firms occupy a position of market leadership due to their extensive fabrication capabilities and long-standing relationships with major electronics OEMs. They consistently push the boundaries of display technology, from AMOLED to advanced substrate materials.
| Leading Market Players |
|---|
| Samsung Display Co., Ltd. |
| LG Display Co., Ltd. |
| BOE Technology Group Co., Ltd. |
| Royole Corporation |
| AU Optronics Corp. |
| Sharp Corporation |
| Innolux Corporation |
| Visionox Technology Inc. |
| FlexEnable Ltd. |
| Others |
Cost & Logistics Intelligence
Polyimide (PI) film production, concentrated in a few Asian suppliers, directly impacts where profit margins accumulate across the flexible display value chain. This upstream concentration solidifies pricing power for key material providers.
Pricing Analysis
Product performance tier, driven by factors like bend radius and scratch resistance, creates the primary spread in flexible display pricing. Transactional pricing dominates for standard panels, while custom designs often use project-based contracts. Pricing pressure stems from aggressive manufacturing capacity expansion in China, particularly for mid-range panels. Automotive system integrators exhibit lower price sensitivity due to stringent quality and longevity requirements, unlike some consumer electronics manufacturers.
Supply Chain Analysis
Upstream raw material sourcing for polyimide films and ultra-thin glass (UTG) primarily draws from Japan, South Korea, and Germany. Key material dependencies include specialized polymers and high-purity glass substrates. Geographically, manufacturing of flexible displays is concentrating heavily in South Korea and China, creating a single-source vulnerability for global OEMs. Distribution runs through established electronics component distributors and direct supply agreements with major original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing a cyclical recovery, propelled by renewed consumer enthusiasm for innovative foldable smartphone designs.
For Market Incumbents: Harden core fabrication capabilities through strategic investments in next-generation panel production lines, particularly for large-format flexible OLEDs. Mitigate the threat of new entrants by securing long-term supply agreements for critical raw materials like colorless polyimide (CPI). Focus R&D efforts on improving manufacturing yield complexity and enhancing display durability against repeated bending cycles.
For New Entrants and Emerging Players: Build out niche expertise in specialized flexible display applications, such as medical sensors or smart textiles. Target the wearables and medical devices segment, which remains underpenetrated by established players. A go-to-market angle focusing on custom form factors and extreme durability for industrial applications offers differentiation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with smaller, product-specialist display manufacturers focused on niche technologies like flexible micro-LEDs. Long-term viability hinges on companies demonstrating consistent improvements in manufacturing yields and material science breakthroughs. The signal to watch is the successful commercialization of stretchable display technology beyond proof-of-concept prototypes.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for UTG | Securing supply of ultra-thin glass addresses premium foldable smartphone demand. |
| R&D in Stretchable Materials | Unlocks novel applications in wearables and medical devices, expanding market reach. |
| Partnerships for Automotive Integration | Co-development with automotive OEMs ensures compliance with stringent industry standards. |
| Investment in Advanced Encapsulation | Enhances durability and longevity of flexible panels, addressing key market restraints. |
| Development of Debondable Adhesives | Supports repairability mandates, improving product lifecycle management and compliance. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with industry stakeholders and secondary validation. Stakeholders included product development executives, procurement leads at OEMs, material science researchers, and regulatory compliance officers. Secondary data sources encompassed corporate financial filings, patent databases, and technical journals. This approach utilized both bottom-up market sizing and top-down validation.
The calibration approach involved modeling market dynamics over the projection horizon, considering technological adoption rates and end-user preferences. Segmentation dimensions modeled included product type, technology, application, end-user, and regional manufacturing capacity. Compound annual growth rates were derived from historical data trends and projected technology roadmaps. Key forecast inputs included material cost trajectories and consumer electronics sales forecasts.
Stress conditions across raw material price volatility and manufacturing yield improvements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements and regulatory stability in key markets. Cross-checking against major industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Thin Display Technology Market
Display Technologies
Global Display Panel Market
Display Technologies
North America TFT LCD Panel Market
Display Technologies
Flat Panel Display (FPD) Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
Global Haptic Touchscreen Market
Display Technologies
Vietnam Displays Market
Display Technologies
Alphanumeric LCD Modules Market
Display Technologies
Plasma Display Module Market
Display Technologies
Global Center Stack Display Market
Display Technologies
Masks for Display Panel Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Rugged Display Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Visual Computing Market
Display Technologies
TFT LCD Panel Market