
 Transparent Solar Cells Market | 2026-2036
Transparent Solar Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Transparent Solar Cells Market Analytics
The EU Green Deal is recalibrating the cost-of-entry calculus for transparent solar cell manufacturers serving European construction markets. Onyx Solar leverages its building-integrated photovoltaic specialization to anchor premium positioning across commercial facade projects. Ubiquitous Energy sustains technology leadership in visibly transparent organic photovoltaics for consumer electronics and smart window applications. Hanwha Q CELLS Co., Ltd. competes through crystalline silicon scale advantages adapted to semi-transparent module formats.
Transparent solar cells are photovoltaic devices engineered to transmit visible light while harvesting ultraviolet and infrared wavelengths, typically achieving light transmission rates between 20% and 70% depending on electrode architecture and active layer composition. Their primary commercial purpose is to convert architectural glass, vehicle windows, and electronic displays into dual-function surfaces that generate electricity without obstructing visibility. Organic photovoltaics currently leads application flexibility due to tunable absorption spectra and solution-processable manufacturing, while perovskite solar cells represent the fastest-growing technology segment as researchers push power conversion efficiency past 15% in visibly transparent architectures. Building integrated PV commands the deepest margin pools because developers accept premium pricing for certified facade systems that satisfy both energy and aesthetic specifications.
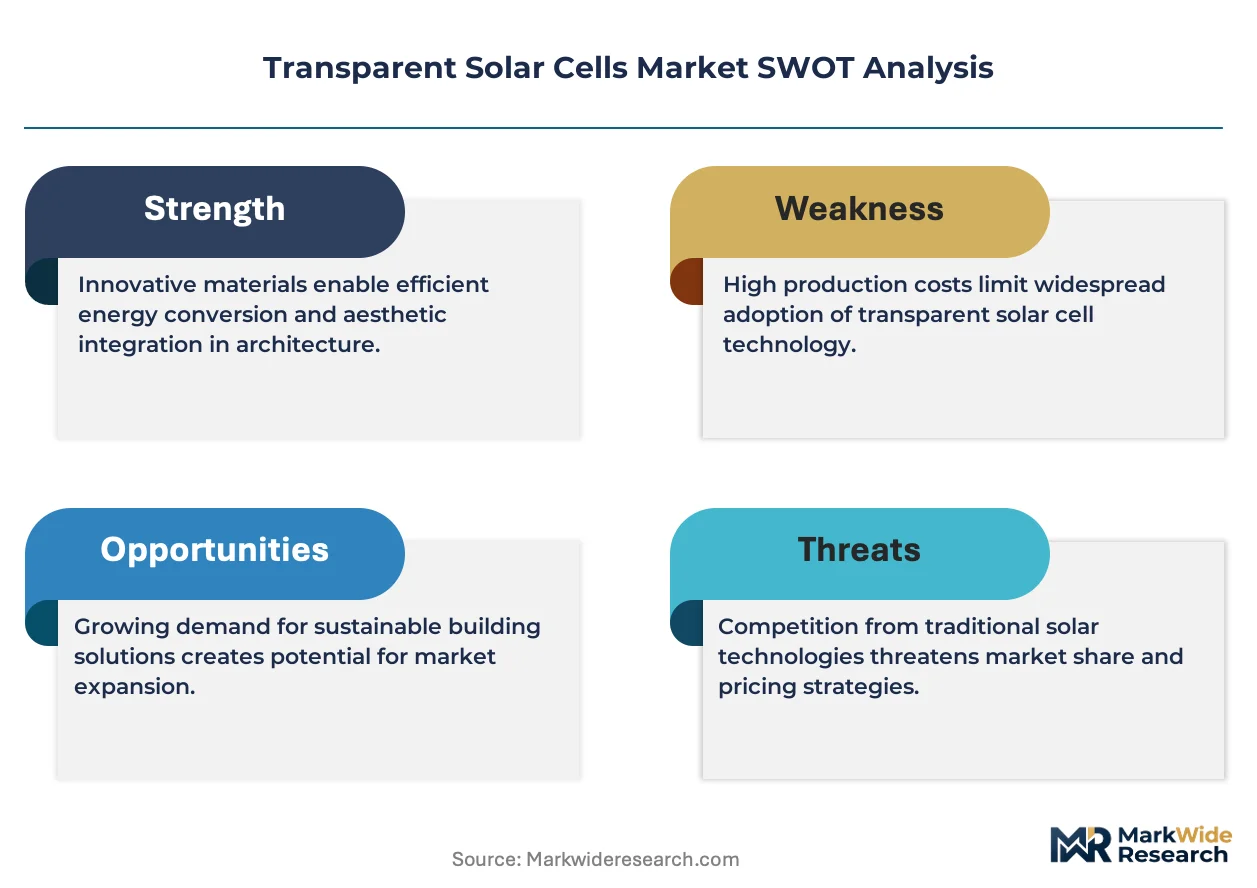
REACH compliance requirements in Europe, EPA photovoltaic waste guidelines in the United States, and China's GB standards for building-integrated solar products collectively shape material selection, recycling obligations, and market access protocols across major supply regions. EMA and ECHA frameworks increasingly scrutinize heavy metal content in perovskite formulations, pressuring manufacturers toward lead-free absorber development. Stakeholders must monitor regulatory divergence between jurisdictions on transparency certification metrics and end-of-life producer responsibility to avoid stranded product development investments.
Market Dynamics
Building integrated photovoltaics is restructuring competitive priorities as architects and developers demand facade systems that satisfy dual certification for energy generation and aesthetic transparency. This end-use pull is compressing development cycles for visibly transparent architectures.
Growth Catalysts
- EU Green Deal renovation mandates:Building renovation targets across Germany, France, and Italy are creating certified demand channels for BIPV-compatible transparent solar solutions in commercial retrofits.
- Perovskite efficiency breakthroughs:Laboratory demonstrations pushing power conversion past 15% in visibly transparent architectures are attracting venture capital into pilot manufacturing lines.
- Automotive glazing integration:Electric vehicle manufacturers are sourcing semi-transparent roof panels to offset auxiliary power loads without compromising cabin illumination.
Market Restraints
- Silver electrode cost volatility:Transparent conductive oxide alternatives face input price pressure from precious metal supply concentration in Latin American mining jurisdictions.
- Encapsulation durability gaps:Organic photovoltaics suffer performance degradation under UV exposure exceeding 5,000 hours, limiting warranty terms and developer financing access.
- REACH compliance complexity:ECHA scrutiny of heavy metal content in lead-based perovskite absorbers is forcing reformulation investments before commercial scale-up.
Strategic Opportunities
- Smart window convergence:Integration of transparent solar cells with electrochromic glazing creates unified building envelope systems commanding premium specification in net-zero commercial developments.
- Consumer electronics white space:Wearable device manufacturers are prototyping visibly transparent photovoltaic displays for extended battery life in ambient light harvesting.
- India PLI scheme extension:Domestic manufacturing incentives for advanced solar technologies are attracting module assembly investment for export-oriented transparent cell production.
Industry Challenges
- Cross-disciplinary talent scarcity:Transparent solar development requires simultaneous expertise in thin-film photovoltaics, architectural glazing engineering, and building code certification.
- Dual certification timelines:Products must sequentially pass IEC photovoltaic standards and regional building material fire-safety ratings, extending commercialization cycles.
- Legacy glazing supply chain reconfiguration:Traditional glass distributors lack technical capacity for electrical integration, forcing manufacturers to build direct specification relationships with facade contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transparent Solar Cells Market |
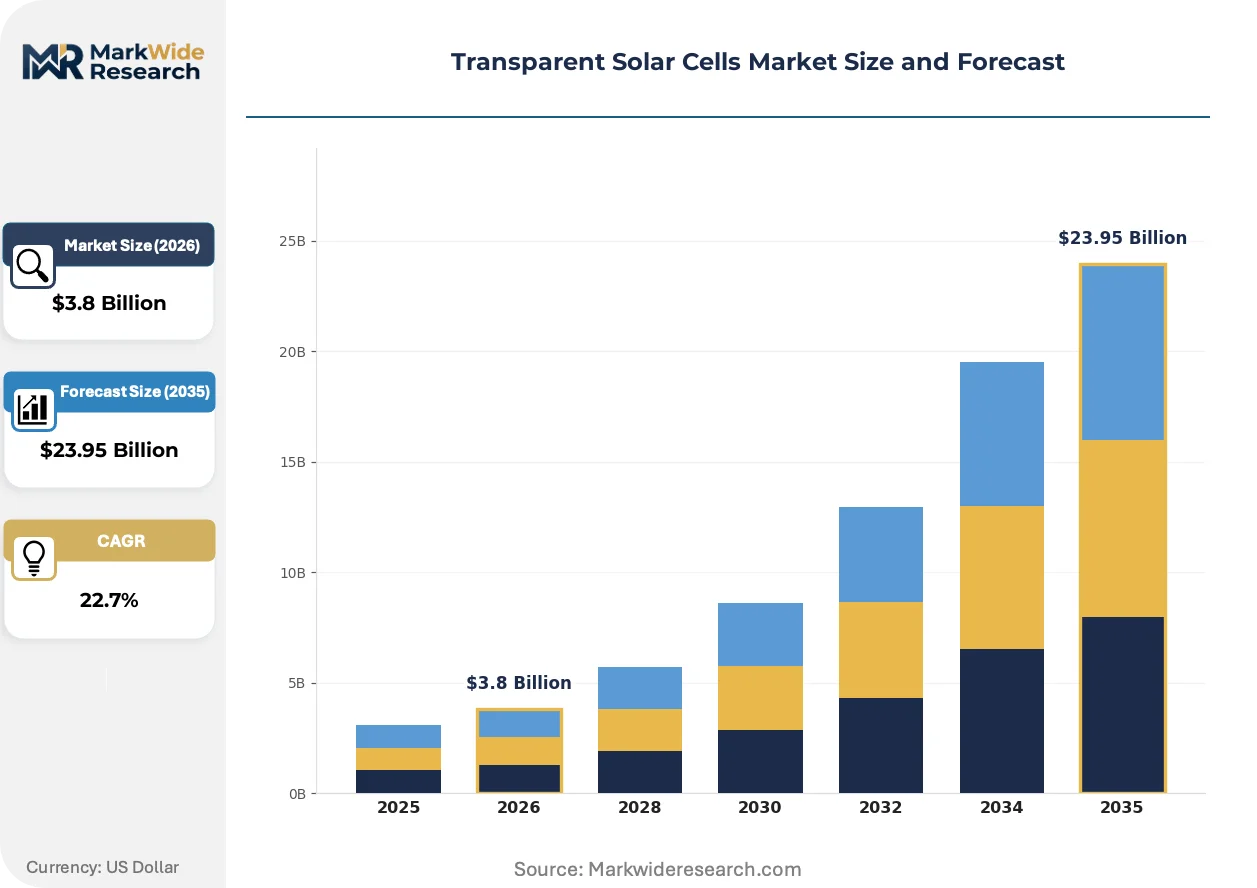
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Organic Photovoltaics, Perovskite Solar Cells, Crystalline Silicon, Amorphous Silicon Application: Building Integrated PV, Automotive Glazing, Consumer Electronics, Smart Windows End User: Residential, Commercial, Industrial, Government Material: Conductive Polymers, Nanocrystals, Silicon Films, Transparent Conducting Oxides |
| Companies Covered | JA Solar, Hanwha Q CELLS Co., Ltd., Onyx Solar, Ubiquitous Energy, Trina Solar Limited, 8MSolar, First Solar, SolarWindow Technologies, LONGi Green Energy Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transparent Solar Cells Market Evolving Landscape
Transparent solar cell architectures are diverging along two paths: high-transmission designs for visibility-critical applications and high-efficiency variants for energy-maximizing building envelopes. This bifurcation is reshaping R&D allocation and partnership strategies across the value chain.
Perovskite tandem configurations are overtaking single-junction organic photovoltaics in building-integrated applications. Commercial facade developers in Germany and the Netherlands are specifying perovskite-silicon tandems for retrofit projects requiring 30-year performance guarantees. The technology is overtaking incumbent thin-film alternatives by delivering superior infrared harvesting without the visible tinting that compromises architectural intent.
REACH authorization procedures are tightening material selection protocols for European market entry. ECHA's 2024 candidate list expansion for lead compounds is forcing absorber layer reformulation toward tin-based alternatives with inferior stability profiles. German manufacturers are responding by accelerating indoor photovoltaic applications where encapsulation requirements are less stringent than facade exposure.
Architects are consolidating specification authority previously held by mechanical engineers in commercial building procurement. Facade consultants in Copenhagen and Singapore are embedding energy generation targets into design briefs before contractor engagement, displacing traditional retrofit-after-construction models. This concentration of early-stage decision-making is most visible in Nordic markets where municipal building codes mandate operational carbon disclosure at planning submission.
Transparent Solar Cells Market Segmentation
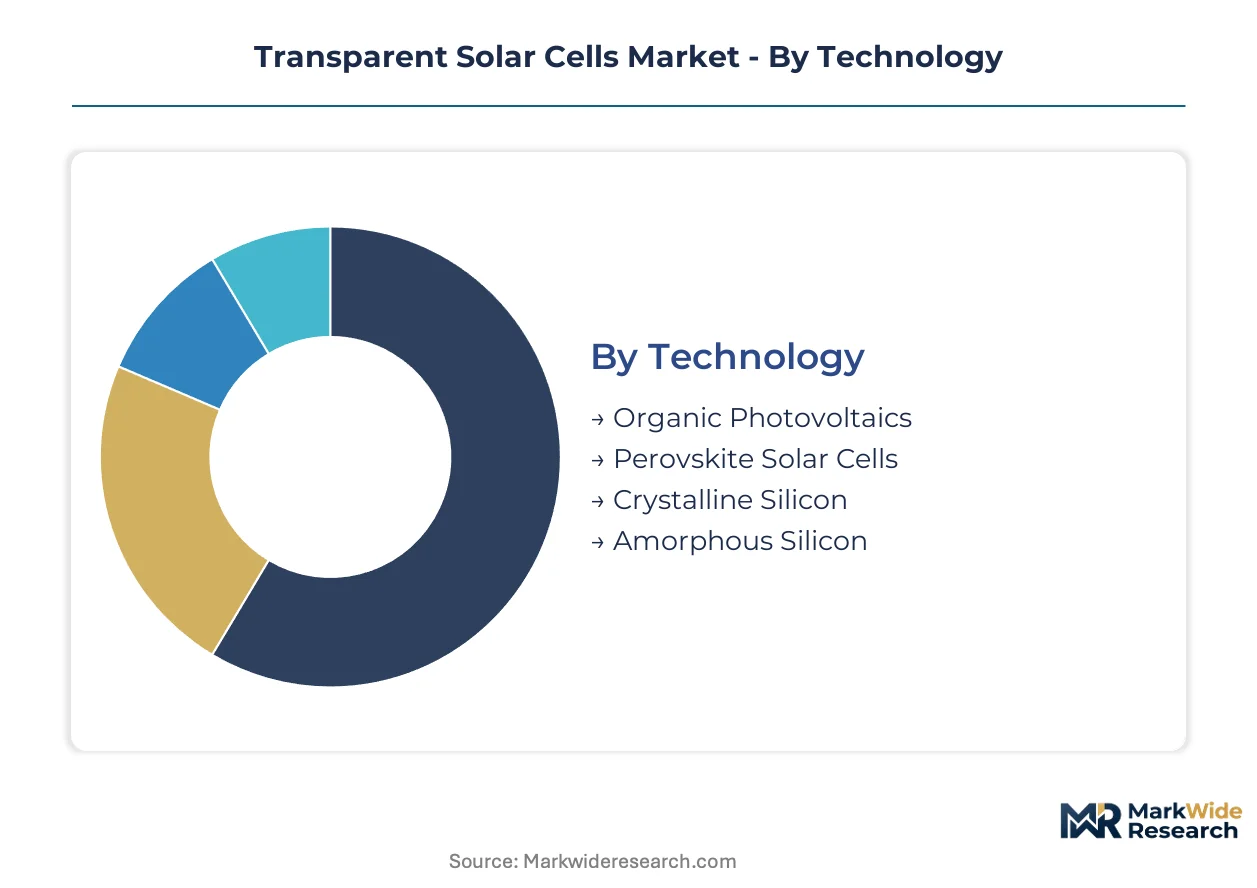
Transparent solar cell architectures require radically different capital commitments across manufacturing approaches. Segmentation reveals which technology bets absorb the heaviest upfront investment before generating certified product revenue.
Technology:
Capital intensity varies by an order of magnitude across fabrication methods, from solution-processed organic films to vacuum-deposited crystalline architectures.
- Organic Photovoltaics:Roll-to-roll coating of donor-acceptor polymer blends enables low-temperature manufacturing on flexible substrates. Demand concentrates in consumer electronics prototyping where solution processability outweighs efficiency limitations.
- Perovskite Solar Cells:Solution or vapor-phase deposition of metal halide absorbers demands glovebox environments and humidity-controlled coating lines. German facade developers are specifying perovskite-silicon tandems for commercial retrofits requiring 30-year performance guarantees.
- Crystalline Silicon:Wafer thinning and laser patterning adapt established supply chains to semi-transparent formats.
- Amorphous Silicon:Plasma-enhanced chemical vapor deposition onto glass substrates leverages display industry equipment.
Most installed capacity flows through Crystalline Silicon. Expansion is steepest in Perovskite Solar Cells.
Application:
Application selection determines which certification regimes govern product release, with building codes imposing the lengthiest validation timelines.
- Building Integrated PV:Curtain wall and skylight integration requires dual IEC photovoltaic and regional fire-safety certification. Copenhagen and Singapore architects are embedding energy generation targets into design briefs before contractor engagement.
- Smart Windows:Electrochromic layer integration with photovoltaic harvesting creates unified envelope systems. EU Green Deal renovation mandates across Germany, France, and Italy are creating certified demand channels for net-zero commercial developments.
- Automotive Glazing:Semi-transparent roof panels offset auxiliary power loads in electric vehicles.
- Consumer Electronics:Wearable device displays harvest ambient light for extended battery life.
Building Integrated PV commands the deepest margin pools. Smart Windows are gaining share fastest.
End User:
End user type shapes procurement scale and specification authority, from individual residential decisions to municipal tender processes.
- Commercial:Corporate real estate developers specify facade-integrated systems with operational carbon disclosure requirements. Nordic municipal building codes mandate energy generation targets at planning submission.
- Government:Public building renovation programs allocate capital through competitive tender with domestic content preferences.
- Residential:Retrofit decisions follow utility rate structures and subsidy availability.
- Industrial:Warehouse and manufacturing facilities prioritize roof-mounted density over transparency.
Commercial accounts for the largest project pipeline. Government procurement is climbing the fastest.
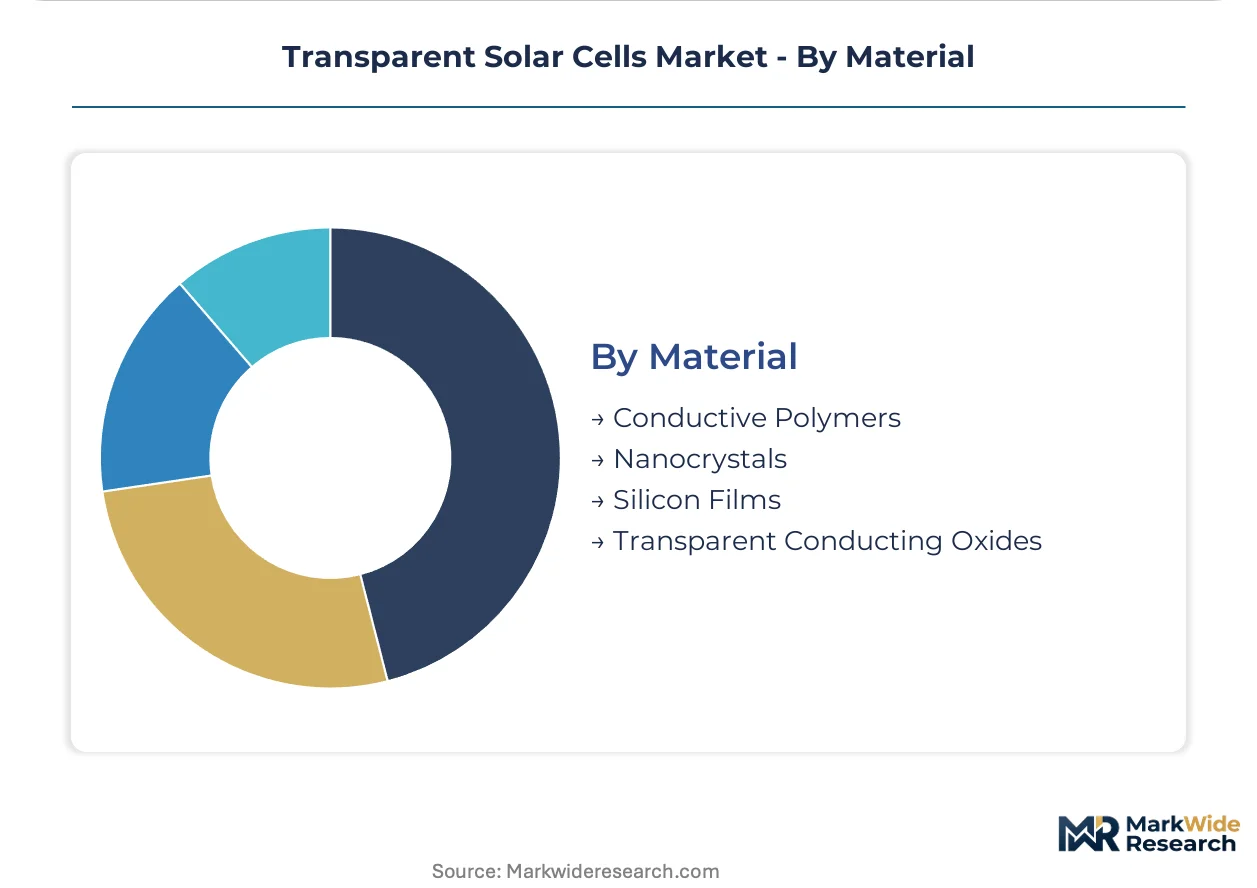
Material:
Material selection faces tightening regulatory scrutiny on heavy metal content, particularly for European market entry.
- Transparent Conducting Oxides:Indium tin oxide and aluminum-doped zinc oxide layers transmit visible light while conducting photocurrent. ECHA's 2024 candidate list expansion for lead compounds is forcing absorber layer reformulation toward tin-based alternatives.
- Conductive Polymers:PEDOT:PSS and related organic conductors enable fully flexible device architectures. REACH compliance complexity is pressuring manufacturers toward lead-free development before commercial scale-up.
- Nanocrystals:Quantum dot and plasmonic nanocrystal integration tailors absorption spectra.
- Silicon Films:Thin-film amorphous and microcrystalline silicon leverages existing photovoltaic supply chains.
Transparent Conducting Oxides dominate current production volumes. Conductive Polymers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transparent solar cell technology first achieved commercial scale in Germany and the Netherlands, where building-integrated photovoltaic mandates created early certification pathways. The industry's geographic footprint now extends across construction markets with stringent operational carbon disclosure requirements.
Germany
Commercial facade developers in Berlin and Hamburg specify perovskite-silicon tandems for retrofit projects requiring 30-year performance guarantees. The EU Green Deal's building renovation mandates create certified demand channels for BIPV-compatible solutions. The Rhine-Ruhr industrial corridor hosts pilot manufacturing lines attracting venture capital from energy transition funds.
United States
Electric vehicle manufacturers in Detroit and California source semi-transparent roof panels to offset auxiliary power loads without compromising cabin illumination. EPA photovoltaic waste guidelines shape material selection and recycling obligations for domestic producers. The Pacific Northwest cluster around Seattle advances organic photovoltaic prototyping for consumer electronics applications.
China
GB standards for building-integrated solar products govern market access protocols for facade system exporters. The Yangtze River Delta manufacturing belt concentrates crystalline silicon wafer thinning and laser patterning capacity adapted to semi-transparent formats. Shanghai-based developers test smart window convergence with electrochromic glazing for net-zero commercial towers.
Netherlands
Architects in Amsterdam and Rotterdam embed energy generation targets into design briefs before contractor engagement, displacing traditional retrofit models. ECHA scrutiny of heavy metal content in lead-based perovskite absorbers forces reformulation investments before commercial scale-up. The Eindhoven region anchors indoor photovoltaic applications where encapsulation requirements are less stringent than facade exposure.
India
The PLI scheme extension for advanced solar technologies attracts module assembly investment for export-oriented transparent cell production. Domestic manufacturing incentives target building-integrated systems for tropical climate durability. The Gujarat industrial corridor scales conductive polymer deposition lines serving wearable device display manufacturers.
Transparent Solar Cells Market Competitive Landscape
The competitive structure tilts toward building-integrated photovoltaic specialists competing against crystalline silicon scale players adapting established supply chains. Three archetypes dominate: facade system integrators with dual certification expertise, thin-film technology developers pushing perovskite efficiency thresholds, and commodity module producers leveraging wafer-thinning capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with manufacturers seeking direct specification relationships with architects to bypass legacy glazing distributors.
Among building-integrated photovoltaic specialists, Onyx Solar and SolarWindow Technologies exemplify the premium-tier archetype focused on certified facade systems. Hanwha Q CELLS Co., Ltd. anchors the scale-driven segment, adapting crystalline silicon manufacturing to semi-transparent formats. Ubiquitous Energy occupies a position in visibly transparent organic photovoltaics for consumer electronics and smart window convergence applications.
| Leading Market Players |
|---|
| JA Solar |
| Hanwha Q CELLS Co., Ltd. |
| Onyx Solar |
| Ubiquitous Energy |
| Trina Solar Limited |
| 8MSolar |
| First Solar |
| SolarWindow Technologies |
| LONGi Green Energy Technology Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Silver spot price volatility on the London Bullion Market Association benchmark cascades through transparent solar cell manufacturing, compressing margins for electrode-intensive architectures while pushing buyers toward indium tin oxide alternatives that trade at premium tiers.
Pricing Analysis
Project-based contract pricing with long-term offtake agreements dominates BIPV procurement, separating certified facade systems with dual IEC and fire-safety ratings from uncertified pilot installations. Price differentiation rests on transparency grade and encapsulation warranty length, with 30-year performance guarantees commanding substantial premiums over 10-year terms. Cost compression in standard-tier organic photovoltaics is intensifying as roll-to-roll manufacturers achieve economies of scale. Government procurement offices exhibit highest price sensitivity, while corporate real estate developers prioritize aesthetic certification over unit economics.
Supply Chain Analysis
India's PLI scheme extension and domestic content mandates for government building projects are reshaping sourcing patterns, forcing module assemblers to localize conductive polymer deposition or forfeit tender eligibility. Manufacturing gravity centers on China for crystalline silicon wafer thinning, Germany for perovskite-silicon tandem pilot lines, and India for export-oriented conductive polymer capacity. Raw material dependencies span indium from Chinese refining operations, silver from Latin American mining jurisdictions, and high-purity glass substrates from float-glass specialists in Germany and China. Single-source vulnerability concentrates in transparent conducting oxide precursors. Distribution runs through direct specification relationships with facade contractors, bypassing legacy glazing distributors lacking electrical integration capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transparent solar cells offer margin expansion potential as perovskite tandem architectures displace lower-efficiency organic alternatives, with cost-down drivers concentrated in solution-processed manufacturing scale-up and encapsulation standardization.
For Market Incumbents: Deploy backward integration into transparent conducting oxide precursor refining to insulate margins from indium price volatility. Accelerate certification investment for dual IEC and regional fire-safety ratings to defend positioning against emerging perovskite specialists. Channel control through direct architect specification relationships offers defensive moats against crystalline silicon scale players adapting semi-transparent formats.
For New Entrants and Emerging Players: Begin with indoor photovoltaic applications for consumer electronics, where encapsulation requirements are less stringent than facade exposure and certification timelines compress substantially. Target wearable device display manufacturers in the Pacific Northwest and Gujarat industrial corridor. A licensing-based go-to-market angle with established glass fabricators reduces capital intensity versus captive manufacturing.
For Investors and Strategic Acquirers: Asymmetric upside sits with perovskite tandem technology developers holding proprietary absorber formulations and glovebox manufacturing expertise. Long-term viability hinges on lead-free reformulation success under ECHA scrutiny. The signal to watch is REACH authorization timeline acceleration for tin-based alternatives, which would de-risk commercial scale-up financing.
| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Tandem Manufacturing Scale-Up | Captures BIPV premium tiers as German developers specify 30-year guaranteed performance. |
| Lead-Free Absorber Reformulation | Secures EU market access ahead of ECHA candidate list expansion enforcement. |
| Direct Architect Specification Programs | Bypasses legacy glazing distributors lacking electrical integration technical capacity. |
| Smart Window Convergence Partnerships | Creates unified envelope systems commanding premium positioning in net-zero developments. |
| Domestic Content Compliance Investment | Unlocks India PLI scheme incentives and government tender eligibility for export-oriented production. |
Research Methodology
Direct dialogue with facade system integrators, thin-film photovoltaic R&D directors, architect specification consultants, and EPC contractors anchors the qualitative foundation. Secondary validation draws from IEC standard documentation, ECHA regulatory filings, EU Green Deal implementation progress reports, and customs trade data for transparent conducting oxide precursor flows. Bottom-up project pipeline analysis triangulates against top-down construction spend forecasts across commercial retrofit markets.
Segment-level value outputs across the projection horizon reflect technology-specific manufacturing cost curves, certification timeline distributions, and end-use procurement scale differentials. The analytical framework models organic photovoltaics, perovskite solar cells, crystalline silicon, and amorphous silicon architectures against building-integrated PV, smart windows, automotive glazing, and consumer electronics applications. CAGRs derive from technology penetration curves calibrated to regulatory mandate implementation schedules and venture capital deployment into pilot manufacturing capacity.
Caveats apply where perovskite stability breakthrough timelines or REACH authorization delays for lead-free formulations could materially shift the outlook. Forecasts reflect assumptions on encapsulation durability validation and dual certification standard harmonization across jurisdictions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global WI SUN Technology Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
Edge Computing Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Global Plasma Pulse Technology Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
AI Edge Computing Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market