
 Flexible PV Cell Market | 2026-2036
Flexible PV Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible PV Cell Market Analysis
IEC 61215 certification for flexible module qualification is unwinding the competitive field, filtering out suppliers lacking accelerated lifetime testing capabilities. First Solar leverages its CdTe thin-film expertise to anchor utility-scale flexible deployments in North American deserts. MiaSolé specializes in copper-indium-gallium-selenide sputtering processes that sustain high-throughput manufacturing. Heliatek competes through organic tandem architectures that extend power conversion efficiency in low-light indoor environments.
Flexible PV cells are photovoltaic devices manufactured on polymer or metal foil substrates, typically achieving thicknesses below 2 millimeters and bend radii under 30 millimeters, designed to convert solar irradiance into electrical power on curved or mobile surfaces. Organic photovoltaics dominate portable electronics applications due to tunable absorption spectra and ambient light harvesting, while perovskite tandem configurations represent the fastest-growing technology segment as manufacturers push toward 30% theoretical efficiency limits. Building integrated PV applications command premium margin pools where aesthetic flexibility and structural load reduction justify higher unit economics.
REACH restrictions on cadmium content and the EU Green Deal carbon-border adjustments are reshaping material selection across European supply chains, compelling reformulation of CdTe and CIGS chemistries. The EPA oversees end-of-life recycling mandates for thin-film modules in the United States, creating compliance overhead that favors vertically integrated producers with captive recovery infrastructure. Stakeholders must monitor convergence between F-Gas Regulation phase-downs and novel encapsulant chemistries that determine long-term field reliability in humid climates.
Market Dynamics
Automotive OEMs in Germany are accelerating roof-integrated photovoltaic programs, forcing substrate suppliers to retool for curved surface compatibility and accelerated thermal cycling protocols.
Growth Catalysts
- EU Green Deal carbon-border adjustments:German automotive manufacturers are sourcing cadmium-free CIGS formulations to preempt compliance costs on imported thin-film modules.
- Portable electronics procurement:Wearable device manufacturers in South Korea are specifying organic photovoltaics with sub-0.5mm bend radii for integration into curved display housings.
- Perovskite tandem efficiency gains:Laboratory demonstrations exceeding 28% power conversion are attracting venture capital into pilot line construction for building-integrated applications.
Market Restraints
- Indium supply concentration:CIGS manufacturers depend on Chinese indium refining capacity, exposing cost structures to export quota volatility.
- Encapsulant degradation in humid climates:Ethylene-vinyl acetate alternatives underperform in tropical field conditions, limiting addressable markets for standard product configurations.
- Silver electrode costs:Screen-printed metallization on flexible substrates consumes precious metal volumes that fluctuate with commodity exchange pricing.
Strategic Opportunities
- India PLI scheme for solar manufacturing:Domestic content incentives are attracting module assembly investment that could anchor flexible PV export capacity to Southeast Asian markets.
- Agricultural photovoltaic integration:German farming cooperatives are piloting semi-transparent organic films for greenhouse energy self-sufficiency without crop yield reduction.
- F-Gas Regulation phase-down convergence:Novel fluoropolymer encapsulant chemistries compliant with EU restrictions are opening premium positioning for humidity-resistant product lines.
Industry Challenges
- IEC 61215 certification timelines:Accelerated lifetime testing protocols require 12-18 month qualification cycles that delay commercialization of iterative cell architectures.
- Cross-functional talent scarcity:Integration of semiconductor processing with polymer substrate handling demands skill sets concentrated in display panel manufacturing regions.
- Reverse logistics infrastructure:EPA end-of-life mandates for thin-film modules require collection networks that most distributors have not constructed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible PV Cell Market |
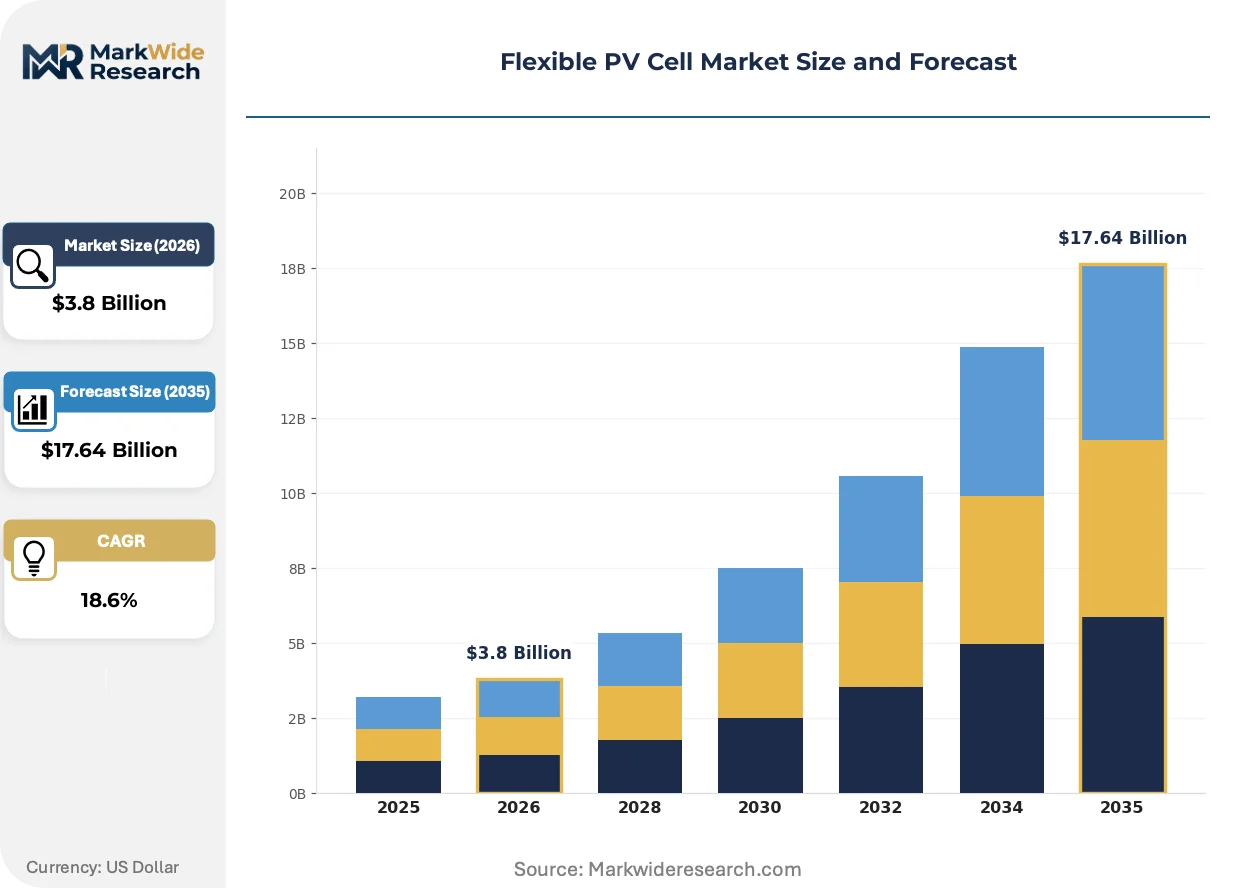
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Photovoltaics, Amorphous Silicon, CdTe, Perovskite Application: Building Integrated PV, Portable Electronics, Automotive, Aerospace End User: Residential, Commercial, Industrial, Off-Grid Solutions Technology: Thin-Film, Bulk-Heterojunction, Tandem Cells, Flexible Substrates |
| Companies Covered | First Solar, MiaSolé, Global Solar, SunPower, Hanergy, Flisom, PowerFilm Solar, Heliatek, SoloPower Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible PV Cell Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are compressing development cycles while fragmenting competitive advantage across distinct technology architectures.
Organic tandem cell stacks are miniaturizing active layer thicknesses below 300 nanometers while maintaining absorption across visible spectra. Smartwatch manufacturers in Japan are qualifying these architectures for ambient light harvesting in always-on display modes. The structural consequence is compressing module weights below 50 grams per square meter, enabling adhesion to thermally sensitive plastic housings previously incompatible with silicon alternatives.
REACH Annex XVII restrictions on cadmium content are compelling reformulation of CdTe buffer layers in European supply chains. ECHA substance evaluation protocols are extending safety data sheet requirements to precursor chemicals used in vapor deposition processes. German module assemblers are responding by qualifying copper-zinc-tin-sulfur alternatives that sacrifice efficiency points for compliance certainty.
Automotive procurement departments are consolidating supplier rosters around vertically integrated producers with captive materials recycling. Tier 1 integrators in Stuttgart are requiring 15-year performance warranties backed by balance sheet strength rather than third-party insurance. This concentration is most visible in Bavaria, where roof-photovoltaic program volumes are concentrating award decisions among three qualified substrate suppliers.
Flexible PV Cell Market Segmentation
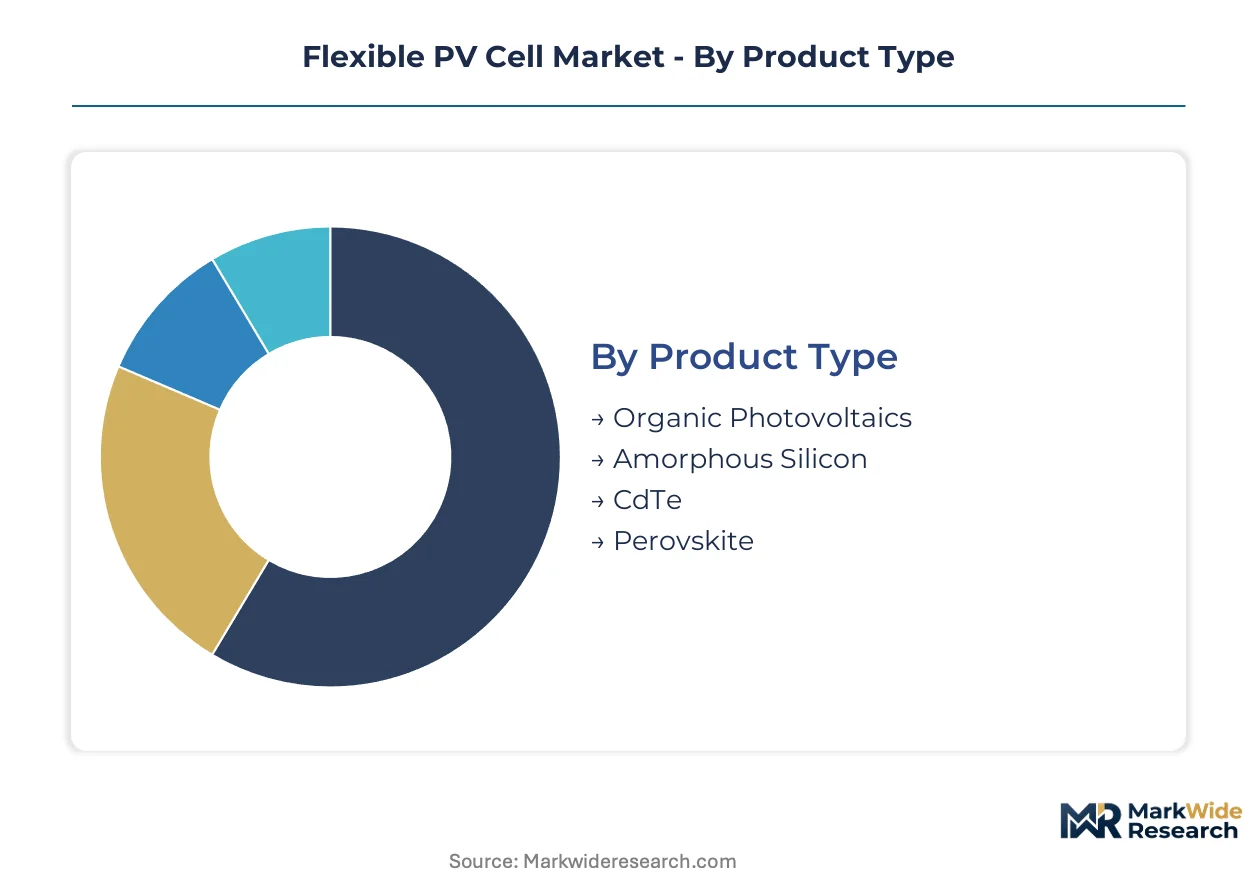
Technology architecture and substrate chemistry dictate manufacturing capital requirements and geographic production concentration. Segment boundaries are blurring as perovskite tandems penetrate automotive qualification programs while organic films displace amorphous silicon in portable electronics.
Product Type:
Organic photovoltaics and perovskite cells anchor export-oriented production in Germany and South Korea, while CdTe and amorphous silicon concentrate in domestic North American utility deployments.
- Organic Photovoltaics:Polymeric active layers enable sub-0.5mm bend radii and sub-50g/m² areal density. Japanese smartwatch manufacturers are qualifying these films for always-on display ambient harvesting, driving specification convergence around 300nm active layer thicknesses.
- Perovskite:Solution-processed metal halide absorbers in tandem configurations are approaching 28% laboratory efficiency. German automotive OEMs are pre-qualifying these architectures for roof-integrated electric vehicle programs, prioritizing suppliers with IEC 61215 certification capabilities.
- CdTe:Cadmium telluride thin-film dominates North American desert utility installations with proven bankability.
- Amorphous Silicon:Hydrogenated silicon on flexible steel substrates serves cost-sensitive building integration in established European markets.
Organic photovoltaics holds the largest share; momentum sits with perovskite.
Application:
Building integrated PV commands premium pricing where structural load reduction justifies higher unit economics, while portable electronics and automotive applications compete for lightweight substrate capacity.
- Building Integrated PV:Aesthetic flexibility and weight reduction enable adhesion to facades and skylights incompatible with glass-glass modules. German architects are specifying semi-transparent organic films for greenhouse energy self-sufficiency without crop yield reduction.
- Automotive:Curved surface compatibility and accelerated thermal cycling protocols are filtering supplier rosters. Stuttgart-based Tier 1 integrators require 15-year performance warranties backed by balance sheet strength rather than third-party insurance.
- Portable Electronics:Wearable device manufacturers in South Korea are driving sub-millimeter thickness specifications for curved display housing integration.
- Aerospace:Power-to-weight ratios above 1kW/kg are qualifying thin-film arrays for satellite and high-altitude platform deployment.
Building integrated PV generates the highest margins; automotive applications are expanding most quickly.
End User:
Industrial off-grid installations prioritize durability and recycling infrastructure, while residential and commercial segments trade efficiency against installation simplicity.
- Commercial:Rooftop lease structures and power purchase agreements favor proven CdTe and CIGS technologies with 25-year performance data. Indian manufacturing investment under the PLI scheme is targeting this segment for Southeast Asian export capacity.
- Off-Grid Solutions:Agricultural photovoltaic integration in German farming cooperatives is piloting semi-transparent organic films for greenhouse energy independence.
- Residential:Aesthetic integration and simplified permitting are driving demand for building-integrated products in premium housing markets.
- Industrial:Large-scale rooftop and ground-mount installations prioritize lowest levelized cost of energy with established recycling pathways.
Commercial deployment holds the largest share; off-grid solutions are gaining share fastest.
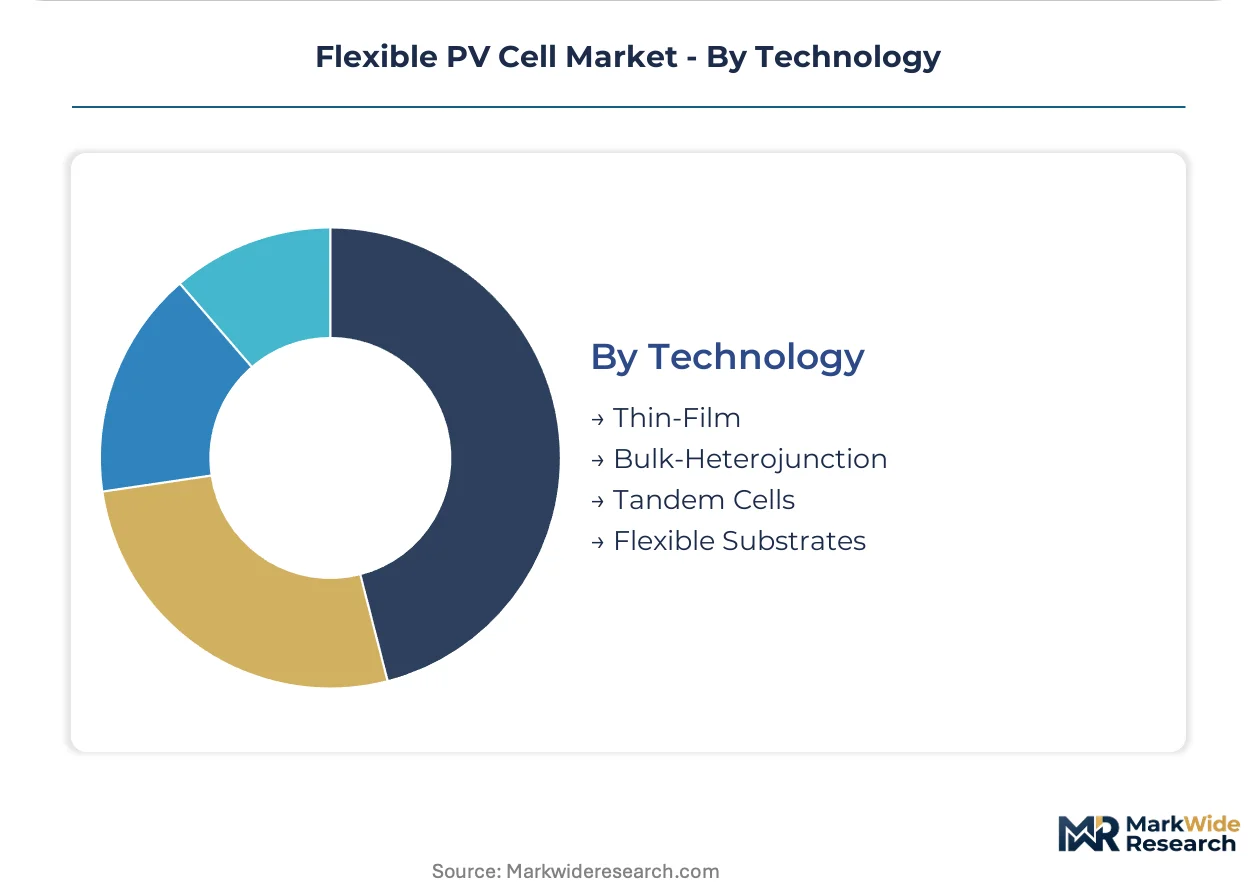
Technology:
Substrate handling capabilities and encapsulant chemistry determine field reliability in humid climates, with tandem architectures capturing venture capital for efficiency breakthroughs.
- Tandem Cells:Perovskite-silicon and all-perovskite stacks are attracting pilot line construction funding for building-integrated applications. Laboratory demonstrations exceeding 28% power conversion are compressing development cycles while fragmenting competitive advantage.
- Thin-Film:Vapor deposition and sputtering processes sustain high-throughput manufacturing for CIGS and CdTe chemistries. REACH restrictions on cadmium content are compelling reformulation of buffer layers in European supply chains.
- Bulk-Heterojunction:Donor-acceptor blends in organic photovoltaics enable tunable absorption spectra for indoor light harvesting.
- Flexible Substrates:Polymer and metal foil handling capabilities are concentrating in display panel manufacturing regions with cross-functional semiconductor processing talent.
Thin-film technology holds the largest share; tandem cells show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon-border adjustments and India's PLI scheme for solar manufacturing are redirecting flexible PV investment toward jurisdictions with domestic content incentives and cadmium-free compliance frameworks.
Germany
Automotive OEMs in Stuttgart and Munich are accelerating roof-integrated photovoltaic programs for electric vehicle platforms. REACH Annex XVII restrictions on cadmium content are compelling CIGS manufacturers to qualify copper-zinc-tin-sulfur buffer layer alternatives. Bavarian farming cooperatives are piloting semi-transparent organic films for greenhouse energy self-sufficiency.
United States
Desert utility installations in Arizona and California anchor demand for CdTe thin-film with proven bankability. EPA end-of-life recycling mandates for thin-film modules create compliance overhead favoring producers with captive recovery infrastructure. First Solar leverages its CdTe expertise to anchor utility-scale flexible deployments across the Southwest.
South Korea
Wearable device manufacturers are specifying organic photovoltaics with sub-0.5mm bend radii for curved display housing integration. MFDS-equivalent industrial standards govern encapsulant reliability testing for humid climate deployment. Seoul-based electronics conglomerates are consolidating supplier rosters around vertically integrated substrate specialists.
India
Domestic content incentives under the PLI scheme are attracting module assembly investment targeting Southeast Asian export markets. CEA grid interconnection standards are adapting to accommodate distributed flexible PV on agricultural and commercial rooftops. Gujarat and Tamil Nadu manufacturing clusters are scaling polymer substrate handling capabilities.
Japan
Smartwatch manufacturers are qualifying organic tandem architectures for ambient light harvesting in always-on display modes. METI technology roadmaps prioritize perovskite stability improvements for building-integrated applications. Kanto region electronics assemblers are compressing module weights below 50 grams per square meter for plastic housing adhesion.
Flexible PV Cell Market Vendor Landscape
Listed leaders compete with private specialists across certification capabilities and captive materials recycling infrastructure. The field filters sharply around IEC 61215 qualification timelines and balance sheet strength to underwrite 15-year performance warranties. Three archetypes dominate: vertically integrated thin-film producers with desert utility track records; CIGS sputtering specialists serving automotive qualification programs; and organic tandem developers targeting indoor ambient harvesting. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEMs consolidate supplier rosters.
Within the thin-film utility tier, First Solar represents the scale-driven archetype with CdTe expertise, while MiaSolé exemplifies CIGS sputtering process specialists. Heliatek occupies a position among organic tandem developers targeting low-light efficiency gains. These three anchors illustrate how competitive advantage fragments across distinct technology architectures and end-use qualification requirements.
| Leading Market Players |
|---|
| First Solar |
| MiaSolé |
| Global Solar |
| SunPower |
| Hanergy |
| Flisom |
| PowerFilm Solar |
| Heliatek |
| SoloPower Systems |
| Others |
Supply Flow & Price Mechanics
IEC 61215 certification gates both supplier qualification and price differentiation simultaneously, compressing margins for uncertified producers while enabling premium positioning for accelerated lifetime testing capabilities. Buyers in Stuttgart automotive programs pay performance warranty premiums backed by balance sheet strength rather than third-party insurance.
Pricing Analysis
Certification level (IEC 61215-grade) creates the primary spread between qualified substrate suppliers and commodity assemblers. Three-tier pricing structure across premium, standard, and economy levels reflects warranty duration, indium content purity, and encapsulant chemistry resilience. Cost compression in standard-grade CIGS modules is intensifying because Chinese indium export quota volatility feeds raw material uncertainty. Commercial rooftop lease structures exhibit highest price sensitivity; German automotive OEMs demonstrate lowest sensitivity due to 15-year performance guarantee requirements.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for polymer substrate imports from South Korean display panel manufacturing clusters. Manufacturing gravity centers on Germany for automotive-qualified CIGS, China for indium refining and perovskite precursor chemicals, and the United States for CdTe desert utility deployments. Feedstock supply draws from concentrated Chinese indium capacity, South Korean copper foil rolling, and Japanese fluoropolymer encapsulant production. Single-source vulnerability in indium refining exposes cost structures to export quota volatility. Distribution runs through vertically integrated producers with captive materials recycling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perovskite tandem efficiency breakthroughs above 28% laboratory demonstration are compressing development cycles and fragmenting competitive advantage across distinct technology architectures.
For Market Incumbents: Shield cadmium-free formulation portfolios against REACH Annex XVII enforcement by qualifying copper-zinc-tin-sulfur buffer layer alternatives. Deepen backward integration into indium recovery infrastructure to preempt supply quota volatility. Consolidate supplier rosters around three qualified substrate specialists with IEC 61215 certification capabilities. For New Entrants and Emerging Players: Anchor in Indian PLI scheme manufacturing clusters targeting Southeast Asian export capacity for commercial rooftop segments. Agricultural photovoltaic integration in German farming cooperatives presents penetrable white-space for semi-transparent organic film pilots. Qualify fluoropolymer encapsulant chemistries compliant with F-Gas Regulation phase-downs as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from electronics conglomerates with stranded organic tandem development assets lacking automotive qualification pathways. Long-term viability hinges on perovskite stability improvements achieving IEC 61215 certification timelines within standard venture capital holding periods. Monitor laboratory-to-pilot-line efficiency retention rates as inflection indicator for manufacturing scalability.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61215 Certification Investment | Accelerated lifetime testing capabilities filter supplier rosters for Stuttgart automotive programs. |
| Backward Integration into Indium Recovery | Captive refining infrastructure mitigates Chinese export quota exposure for CIGS manufacturers. |
| Perovskite Pilot Line Construction | Laboratory efficiency demonstrations attract venture capital for building-integrated applications. |
| Fluoropolymer Encapsulant Reformulation | F-Gas Regulation compliance opens premium positioning for humidity-resistant product lines. |
| Automotive Supplier Roster Consolidation | Tier 1 integrators concentrate awards among three qualified substrate specialists in Bavaria. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings, ECHA substance evaluation protocols, and CEA grid interconnection standards. Semiconductor processing specialists, polymer substrate handling engineers, automotive Tier 1 procurement leads, and agricultural cooperative energy managers provided operational perspective. Bottom-up module shipment tallies triangulate against top-down investment flow tracking across venture capital and corporate R&D disclosures.
Segmentation dimensions modeled span technology architecture, substrate chemistry, application vertical, and end-user procurement structure across the analysis window. CAGRs derive from installation volume trajectories, efficiency improvement curves, and regulatory compliance cost absorption rates. Perovskite stability degradation rates and organic photovoltaics active layer thickness miniaturization curves inform technology penetration assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal carbon-border adjustment enforcement and indium supply concentration persistence; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
AI PC Market
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
Global High-Performance Computing (HPC) Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
Ultra-Fine Ath Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
North America Next Generation Computing Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market