
 Mexico Cleanroom Technology Market | 2026-2036
Mexico Cleanroom Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Cleanroom Technology Market Insights
Capital-intensity divergence between turnkey providers and component suppliers is unwinding competitive stability in Mexico's cleanroom sector. Exyte leverages its integrated project delivery model to anchor large pharmaceutical installations across central Mexico. DuPont de Nemours Inc. sustains polymer science leadership for contamination-control fabrics through captive R&D programs. Camfil AB dominates air filtration supply chains by controlling distribution networks from its regional hub near Mexico City.
Cleanroom technology encompasses engineered enclosures that maintain particulate concentrations below specified thresholds through HEPA or ULPA filtration, typically achieving ISO Class 5 to Class 8 environments for sterile manufacturing or sensitive assembly. These systems regulate airborne particles, temperature, humidity, and pressure differentials to prevent product contamination in precision industries. Air filtration systems command the largest product category share due to recurring replacement cycles and stringent pharmaceutical validation requirements. Modular cleanroom deployments expand fastest among deployment options as electronics manufacturers in Jalisco and Nuevo León prioritize reconfigurable floor space. HEPA filtration technology leads the technology segment, though germicidal UV light gains traction in biotechnology facilities seeking redundant biocontrol layers.
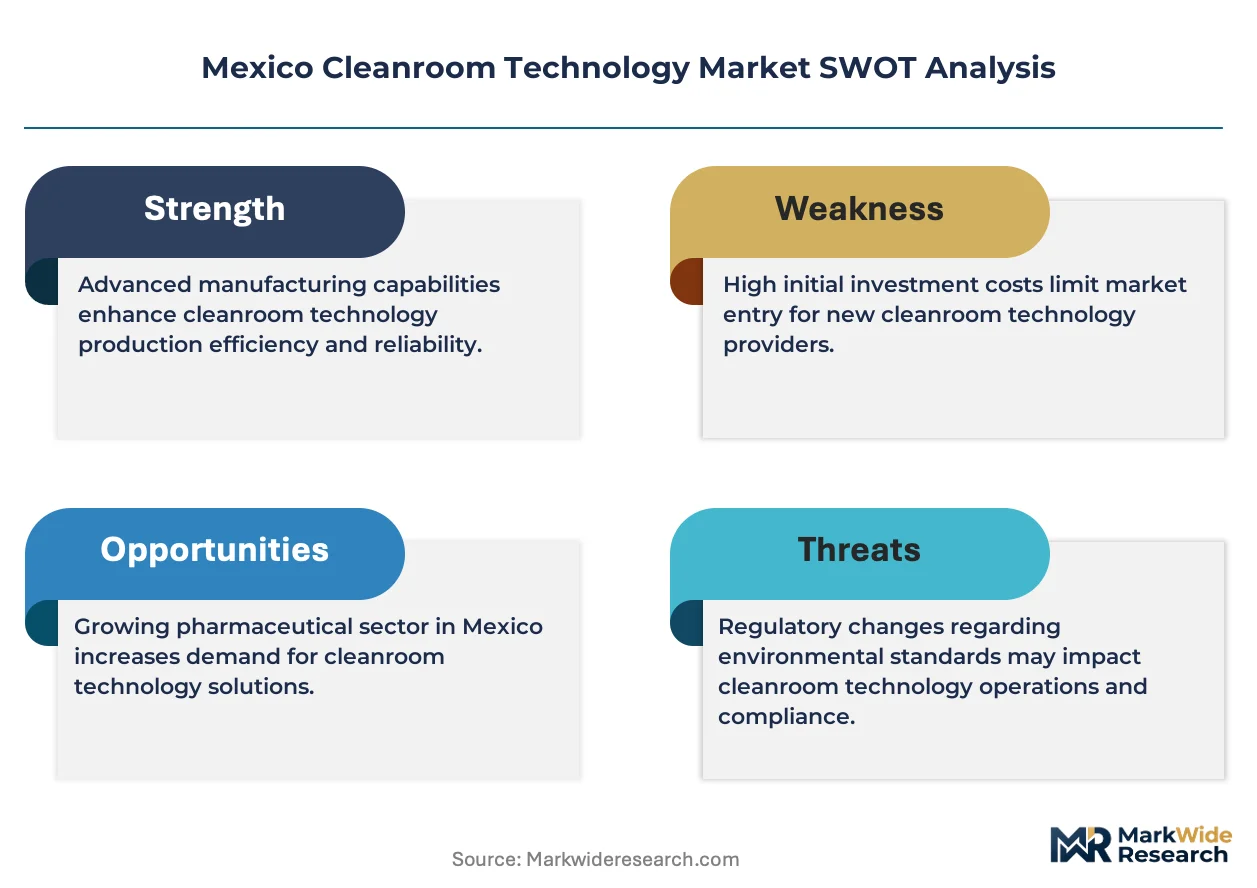
COFEPRIS enforces GMP standards aligned with WHO guidelines, compelling pharmaceutical cleanroom upgrades across Mexican production sites. NOM-059-SSA1 standards for environmental health establish particulate limits that filter manufacturers must certify against for market access. The Secretariat of Economy's pharmaceutical cluster initiatives channel investment toward compliant infrastructure in Querétaro and Puebla. Stakeholders must weigh regulatory trajectory against modular system flexibility when committing to decade-long facility investments.
Market Dynamics
COFEPRIS enforcement of WHO-aligned GMP standards is compressing upgrade timelines for pharmaceutical cleanrooms across central Mexico, forcing facility investments ahead of planned capital cycles.
Growth Catalysts
- NOM-059-SSA1 particulate standards:Mexico's environmental health regulations mandate certified filtration thresholds that compel medical device manufacturers to install validated HEPA systems.
- Tijuana pharmaceutical corridor:Sterile drug production clusters in Baja California generate concentrated demand for ISO Class 5-7 cleanroom infrastructure.
- Semiconductor packaging:Guadalajara electronics assemblers expand controlled environment capacity for advanced chip handling operations.
Market Restraints
- Imported filter media concentration:HEPA and ULPA membrane supply concentrates among Asian polymer suppliers, exposing Mexican integrators to freight cost volatility and extended lead times.
- Specialized installation labor scarcity:Certified cleanroom commissioning engineers remain concentrated in Mexico City and Monterrey, constraining deployment velocity in secondary states.
- Validation protocol rigidity:COFEPRIS requires documented particle count verification for every filter installation, extending project handover timelines by four to eight weeks.
Strategic Opportunities
- Querétaro pharmaceutical cluster:Secretariat of Economy incentives channel foreign investment toward compliant infrastructure in underpenetrated central highlands.
- Germicidal UV-HEPA convergence:Biotechnology facilities seek redundant biocontrol layers, creating hybrid system demand beyond standard filtration.
- Modular cleanroom rentals:Electronics manufacturers in Jalisco adopt reconfigurable floor space to accommodate volatile product mix changes.
Industry Challenges
- Commissioning engineer shortage:ISO 14644 certification programs produce fewer qualified technicians than installation demand requires.
- Legacy HVAC integration:Retrofitting controlled environments into existing pharmaceutical plants demands custom ductwork and pressure cascade redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Cleanroom Technology Market |
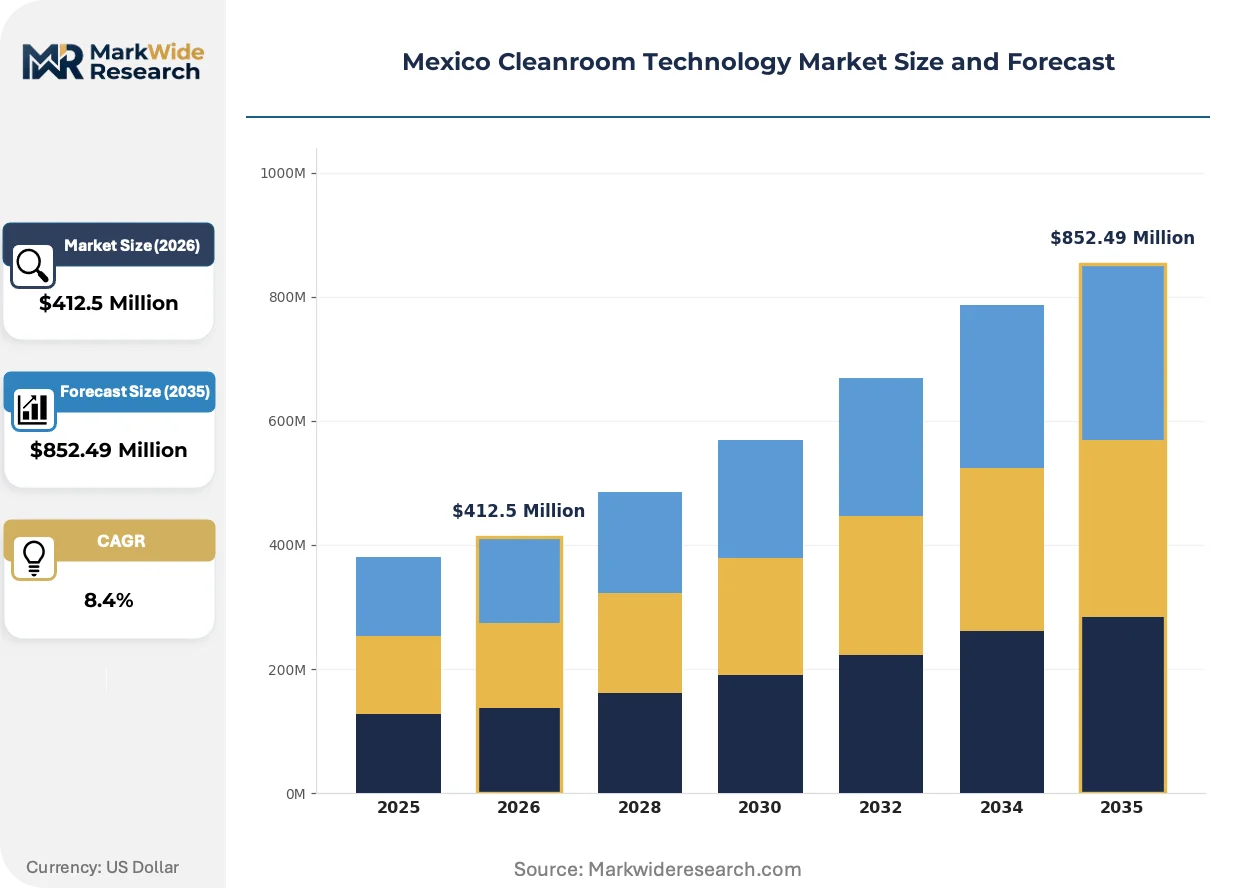
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Filtration Systems, Cleanroom Furniture, Gowning Equipment, Monitoring Systems End User: Pharmaceuticals, Biotechnology, Electronics, Aerospace Deployment: Modular Cleanrooms, Hardwall Cleanrooms, Softwall Cleanrooms, Pass-Through Chambers Technology: HEPA Filters, ULPA Filters, Controlled Environment Systems, Germicidal UV Light |
| Companies Covered | Kimberly-Clark Corporation, DuPont de Nemours Inc., Labconco Corporation, Integrated Clean Room Technologies, Exyte, Clean Air Products, Terra Universal Inc., Camfil AB, Illinois Tool Works Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Cleanroom Technology Market Trends and Innovations
Cleanroom technology in Mexico is fragmenting along modular versus fixed-installation lines as electronics manufacturers prioritize reconfigurable capacity over permanent infrastructure commitments.
Modular cleanroom systems are decomposing traditional fixed-wall construction across Guadalajara and Nuevo León electronics corridors. Automotive semiconductor packers deploy demountable wall panels and ceiling grids that relocate within forty-eight hours. This flexibility is decomposing long-term facility lease economics and compressing capital recovery periods from ten years to three.
COFEPRIS alignment with WHO GMP guidelines is tightening validation documentation for sterile pharmaceutical production. Manufacturers must demonstrate continuous particle monitoring and pressure differential logging across all classified zones. Tijuana and Mexico City facilities face the steepest compliance ramps as inspectors prioritize high-volume injectable drug sites.
Equipment-as-service contracting is displacing outright purchase for HEPA filtration systems in mid-cap pharmaceutical operations. Filter suppliers retain ownership and execute scheduled replacement cycles, unbundling capital expenditure into operational line items. This model spreads fastest among CDMOs in Puebla that lack dedicated maintenance engineering staff.
Mexico Cleanroom Technology Market Segmentation
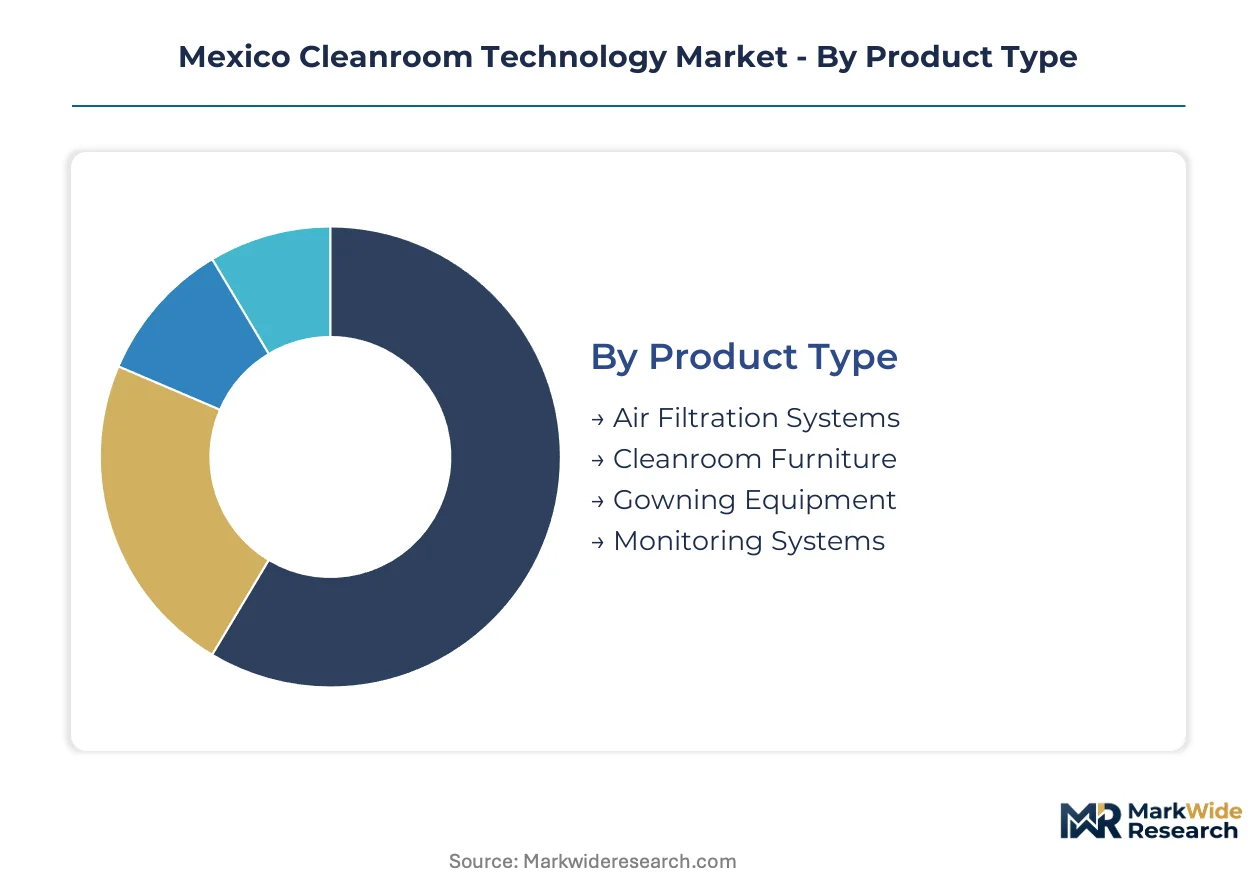
Cleanroom technology segmentation in Mexico reflects divergent capital deployment strategies across pharmaceutical, electronics, and biotechnology end-users. Product mix and deployment architecture choices directly determine compliance cost structures and facility flexibility.
Product Type:
Margin pools concentrate in consumable filtration media and validated monitoring instrumentation rather than durable furniture assets.
- Air Filtration Systems:HEPA and ULPA membrane assemblies with aluminum or stainless steel housings designed for ISO 14644 pressure differential maintenance. Pharmaceutical manufacturers in Tijuana and Mexico City drive replacement demand as COFEPRIS tightens particulate validation protocols for sterile drug production.
- Monitoring Systems:Continuous particle counters, differential pressure transmitters, and environmental data loggers with 21 CFR Part 11 compliant software architectures. Biotechnology facilities in Querétaro prioritize redundant monitoring layers to satisfy WHO-aligned GMP documentation requirements.
- Cleanroom Furniture:Stainless steel workbenches, shelving, and storage systems with electropolished surfaces for particulate shedding reduction.
- Gowning Equipment:Air showers, pass-through garment cabinets, and bench seating with HEPA-filtered air curtains for personnel decontamination.
Air filtration systems hold installed capacity. Monitoring systems are rotating up the share rankings.
End User:
Application intensity varies sharply, with pharmaceutical and biotechnology operations demanding ISO Class 5-7 environments while electronics tolerates Class 8.
- Pharmaceuticals:Sterile injectable drug manufacturers, oral solid dose facilities, and aseptic filling operations requiring validated contamination control. COFEPRIS enforcement of WHO GMP standards compels facility upgrades across central Mexico production clusters.
- Electronics:Semiconductor packaging, printed circuit board assembly, and precision component handling in Guadalajara and Nuevo León corridors. Assembly volatility drives preference for modular deployment architectures over fixed infrastructure.
- Biotechnology:Cell culture processing, biologic drug manufacturing, and research-scale production with redundant biocontrol requirements.
- Aerospace:Satellite component assembly and precision instrument calibration with cleanliness specifications below pharmaceutical thresholds.
Pharmaceuticals anchor capital deployment. Electronics is expanding most quickly as semiconductor reshoring accelerates.
Deployment:
Cost tier stratification separates permanent hardwall construction from reconfigurable alternatives with compressed depreciation schedules.
- Modular Cleanrooms:Demountable wall panels, ceiling grids, and utility distribution systems permitting 48-hour relocation cycles. Electronics manufacturers in Jalisco adopt reconfigurable floor space to accommodate volatile product mix changes without long-term lease commitments.
- Hardwall Cleanrooms:Gypsum board or modular panel construction with integrated HVAC and permanent utility infrastructure. Pharmaceutical facilities in Baja California favor hardwall systems for validated sterile production with decade-long operational horizons.
- Softwall Cleanrooms:Vinyl curtain enclosures with aluminum framing for temporary or lower-classification requirements.
- Pass-Through Chambers:Material transfer airlocks with interlocked doors and HEPA filtration for maintaining pressure differentials.
Hardwall cleanrooms retain the majority of installed base value. Modular cleanrooms are climbing the fastest in new order intake.
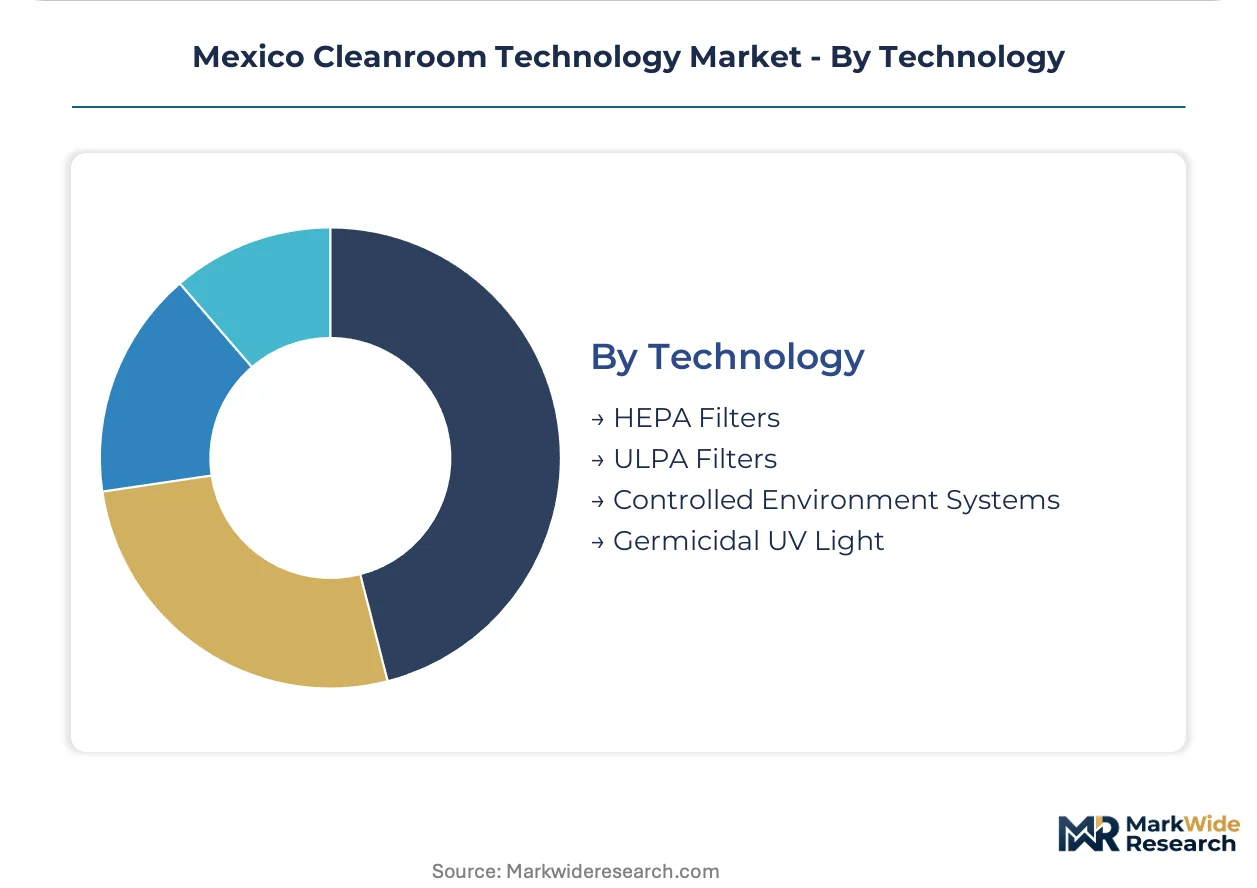
Technology:
Supply concentration in membrane manufacturing creates margin capture asymmetry between filter producers and system integrators.
- HEPA Filters:Glass fiber media with 99.97% efficiency at 0.3 micron particles, aluminum or wood framing, and gasket sealing systems. Medical device manufacturers throughout Baja California's corridor deploy validated HEPA banks to satisfy NOM-059-SSA1 particulate thresholds.
- Germicidal UV Light:Low-pressure mercury or UV-C LED systems for supplemental biocontrol in biotechnology and pharmaceutical applications. Facilities in Puebla integrate UV-HEPA hybrid configurations to address COFEPRIS inspector expectations for redundant contamination barriers.
- ULPA Filters:Extended media depth designs achieving 99.999% efficiency at 0.12 micron for semiconductor and nanotechnology applications.
- Controlled Environment Systems:Integrated temperature, humidity, and pressure control modules with building automation integration.
HEPA filtration dominates replacement revenue. Germicidal UV light is gaining share fastest as hybrid system adoption spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's cleanroom technology market exhibits pronounced regional specialization, with import dependency for critical filtration media contrasting against growing domestic integration capabilities in select manufacturing corridors.
Mexico City Metro
Pharmaceutical manufacturers and biotechnology facilities drive concentrated demand for ISO Class 5-7 cleanroom infrastructure across the capital region. COFEPRIS enforcement of WHO-aligned GMP standards compels continuous facility upgrades among sterile drug producers. Tlalnepantla and Cuautitlán Izcalli host the densest clustering of validated cleanroom installations serving national distribution networks.
Nuevo León
Electronics assemblers and medical device manufacturers anchor cleanroom deployment in Monterrey's industrial corridor. NOM-059-SSA1 particulate standards mandate certified HEPA filtration for device sterilization operations. Apodaca and Santa Catarina concentrate modular cleanroom installations serving volatile semiconductor packaging contracts.
Jalisco
Guadalajara's electronics manufacturing hub generates accelerating demand for reconfigurable controlled environments among contract assemblers. The Secretariat of Economy's innovation incentives support cleanroom infrastructure investment for advanced chip handling. El Salto and Tlajomulco de Zúñiga emerge as focal points for modular system deployment.
Bajío Region
Querétaro's pharmaceutical cluster attracts foreign investment toward compliant sterile production infrastructure. Federal pharmaceutical cluster initiatives channel capital toward GMP-certified facilities in underpenetrated central highlands. San José el Alto and El Marqués concentrate new hardwall cleanroom construction for decade-long operational horizons.
Northern Border States
Baja California's medical device corridor sustains dense HEPA filtration deployment for export-oriented manufacturing. Tijuana's sterile drug production facilities face steep compliance ramps as inspectors prioritize high-volume injectable sites. Mexicali and Ensenada support secondary cleanroom service capabilities for cross-border supply chains.
Mexico Cleanroom Technology Market Competitive Landscape
Concentration sits with integrated project delivery specialists and multinational filtration component suppliers, creating a tiered competitive structure where turnkey providers capture large pharmaceutical installations while regional distributors control replacement media cycles. Three archetypes dominate: European engineering firms with captive construction capabilities, North American polymer science specialists leveraging R&D scale, and Nordic air filtration suppliers with regional distribution control. Competitive dynamics revolve around strategic partnerships for local installation capacity and portfolio diversification into monitoring instrumentation.
Among multinational component specialists, DuPont de Nemours Inc. and Kimberly-Clark Corporation exemplify polymer science leadership through captive material development programs, while Camfil AB occupies a position within air filtration supply chains through regional hub control near Mexico City. Exyte represents the integrated project delivery archetype, anchoring large-scale pharmaceutical installations across central Mexico through combined engineering and construction capabilities. Illinois Tool Works Inc. and Labconco Corporation sit within diversified industrial and laboratory equipment portfolios respectively, serving fragmented demand across multiple end-use segments without cleanroom-specific strategic focus.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| DuPont de Nemours Inc. |
| Labconco Corporation |
| Integrated Clean Room Technologies |
| Exyte |
| Clean Air Products |
| Terra Universal Inc. |
| Camfil AB |
| Illinois Tool Works Inc. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization asymmetries between HEPA membrane producers and Mexican system integrators concentrate pricing power upstream while compressing margin capture for domestic installation contractors serving Tijuana pharmaceutical corridors. Scale advantages in glass fiber media manufacturing anchor price floors for validated filtration assemblies, leaving local distributors to compete on logistics velocity and COFEPRIS documentation support rather than material cost.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across pharmaceutical cleanroom deployments, with price differentiation resting on ISO 14644 certification grade and volume scale commitments. Three-tier pricing structure across premium, standard, and economy levels separates validated HEPA banks with continuous monitoring integration from basic replacement media. Cost compression in mid-cap electronics installations is intensifying because semiconductor packers prioritize capital recovery speed over performance headroom. CDMOs in Puebla exhibit highest price sensitivity due to maintenance staff shortages, while multinational drug manufacturers absorb premium tiers for compliance certainty.
Supply Chain Analysis
Extended lead times for glass fiber media and aluminum extrusion housings expose Mexican integrators to inventory carrying cost escalation when Asian polymer suppliers throttle output. HEPA membrane supply concentrates in China, South Korea, and Germany, with raw material dependencies spanning borosilicate glass microfiber, polyurethane sealants, and anodized aluminum framing. Single-source vulnerability in specialized pleating equipment creates bottleneck risk for domestic filter assembly operations. Distribution runs through regional hub-and-spoke networks anchored by Mexico City warehousing, with secondary nodes in Monterrey and Guadalajara serving corridor-specific demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in Mexico's cleanroom sector gains momentum from COFEPRIS alignment with WHO GMP standards, which forces facility investments ahead of planned capital cycles across central Mexico pharmaceutical clusters.
For Market Incumbents: Secure captive installation capacity in Querétaro and Puebla before certified commissioning engineer scarcity hardens into structural constraint. Deepen backward integration into monitoring instrumentation software to capture recurring revenue streams threatened by equipment-as-service entrants. Anchor long-term service contracts with Tijuana sterile drug producers facing steepest compliance ramps. For New Entrants and Emerging Players: COFEPRIS validation fast-track programs for modular cleanroom systems offer lowest barrier to credible market entry among electronics manufacturers in Jalisco. Target reconfigurable floor space demand from Guadalajara semiconductor packers seeking 48-hour relocation cycles without lease commitments. Pursue white-label partnerships with established HVAC contractors to bypass direct certification investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among filter media suppliers with scheduled replacement cycles, positioning consumable-focused archetypes for superior cash flow quality across 5-10 year holding periods. Acquisition targets should demonstrate established COFEPRIS documentation protocols and regional distribution control near Mexico City. Watch germicidal UV-HEPA hybrid adoption rates in Puebla biotechnology facilities as inflection indicator for technology shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Certification Fast-Track Investment | Accelerates market access for modular system providers serving pharmaceutical clusters in Querétaro. |
| Backward Integration into Filter Media Manufacturing | Reduces freight cost volatility exposure for Mexican integrators dependent on Asian polymer supply. |
| Equipment-as-Service Contracting Model | Converts capital expenditure to operational line items for CDMOs lacking dedicated maintenance engineering. |
| Regional Hub Expansion in Monterrey | Captures electronics corridor demand in Nuevo León with compressed logistics response times. |
| Germicidal UV-HEPA Hybrid System Development | Addresses biotechnology facility demand for redundant biocontrol layers beyond standard filtration. |
Research Methodology
Cross-validation between regulatory filing analysis and supply chain stakeholder interviews anchors the qualitative findings in documented compliance trajectories. Primary engagement with cleanroom commissioning engineers, pharmaceutical facility managers, COFEPRIS regulatory consultants, and HVAC contractor procurement leads combines with secondary validation through NOM-059-SSA1 certification databases, Secretariat of Economy pharmaceutical cluster investment disclosures, and customs records for HEPA media imports. Bottom-up installation project tracking and top-down sectoral investment flow analysis triangulate market sizing.
Sensitivity analysis across regulatory enforcement intensity scenarios and semiconductor reshoring velocity assumptions shapes the analytical framework. Segmentation dimensions span product type, deployment architecture, end-use industry, and technology tier across the projection horizon. CAGRs derive from installed base replacement cycles and new facility commissioning rates, with COFEPRIS inspection prioritization schedules and electronics manufacturer capital commitment patterns serving as key forecast inputs.
Underlying assumptions cover sustained WHO GMP alignment enforcement and stable Asian polymer supply availability, with deviation risk concentrated in tariff regime shifts affecting filter media imports and commissioning engineer training program throughput. Forecasts reflect these documented conditions. Revision becomes warranted when COFEPRIS inspector staffing levels or NOM-059-SSA1 particulate threshold amendments cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Next-Generation Transistors Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
Medical Terahertz Technology Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
North America Wigig Market
Emerging and Next Generation Technologies
Global Broad Ion Beam Technology Market
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Chipless RFID Market