
 Molecular Electronics Market | 2026-2036
Molecular Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Electronics Market Foresight
Specialized nanofabrication workforce availability is collapsing across advanced economies, creating acute bottlenecks for molecular electronics foundries. Merck KGaA leverages its integrated materials science platform to sustain captive precursor supply for organic semiconductor deposition. Samsung Display Co., Ltd. dominates flexible OLED manufacturing, where molecular-scale thin-film transistors anchor next-generation foldable panels.
Molecular electronics employs individual molecules or molecular assemblies as active circuit elements, with device dimensions typically below ten nanometers and conductance quantized through single-molecule junctions. Organic semiconductors currently lead material consumption due to established vapor-deposition infrastructure, while nanomaterials represent the fastest-expanding category as carbon nanotube and graphene interconnects displace conventional metal traces in high-density architectures. Display technologies command the largest application revenue pool, though biomedical devices concentrate the highest margin opportunities through diagnostic sensor miniaturization.
REACH in Europe and FDA nanotechnology guidance in the United States impose stringent characterization requirements on molecule-based materials entering commercial channels. EMA's evolving framework for nanomedicine devices further shapes biocompatibility testing protocols for implantable molecular sensors. Stakeholders must monitor regulatory convergence between jurisdictions, as divergent toxicity assessment standards threaten to fragment market access for cross-border molecular electronics suppliers.
Market Dynamics
Specialized nanofabrication workforce scarcity across advanced economies is compressing foundry expansion timelines, while REACH compliance and FDA nanotechnology guidance impose simultaneous purity and biocompatibility burdens on molecular component suppliers.
Growth Catalysts
- Implantable biomedical sensors:Healthcare systems demand molecular-scale precision for continuous diagnostic monitoring, creating captive demand for biocompatible molecular junctions.
- REACH substance registration:European chemical characterization mandates force standardization of precursor purity grades, accelerating qualified supplier consolidation.
- Foldable display architectures:Samsung Display and LG Display anchor South Korean R&D clusters where molecular thin-film transistors enable next-generation panel mechanics.
Market Restraints
- Precursor supply concentration:Merck KGaA's integrated materials platform controls captive organic semiconductor deposition feedstocks, creating single-source dependency risks.
- Single-molecule junction reliability:Quantized conductance variability below ten nanometers limits reproducible manufacturing yields at commercial scale.
- EMA nanomedicine framework uncertainty:Evolving biocompatibility testing protocols for implantable molecular sensors extend regulatory approval timelines.
Strategic Opportunities
- Carbon nanotube interconnects:Graphene and nanotube traces displace conventional metal wiring in high-density architectures, opening materials substitution revenue pools.
- Diagnostic sensor miniaturization:Biomedical devices concentrate the highest margin opportunities through molecular-scale detection element integration.
- Organic semiconductor infrastructure leverage:Established vapor-deposition equipment bases enable rapid process transfer for emerging molecular assembly techniques.
Industry Challenges
- Nanofabrication talent scarcity:Collapsing specialized workforce availability across Germany, Japan, and the United States creates acute foundry staffing bottlenecks.
- Cross-border regulatory divergence:Divergent toxicity assessment standards between EMA and FDA frameworks threaten to fragment market access for molecular electronics suppliers.
- Legacy metrology incompatibility:Conventional semiconductor characterization tools lack resolution for single-molecule junction verification, forcing capital-intensive equipment transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Electronics Market |
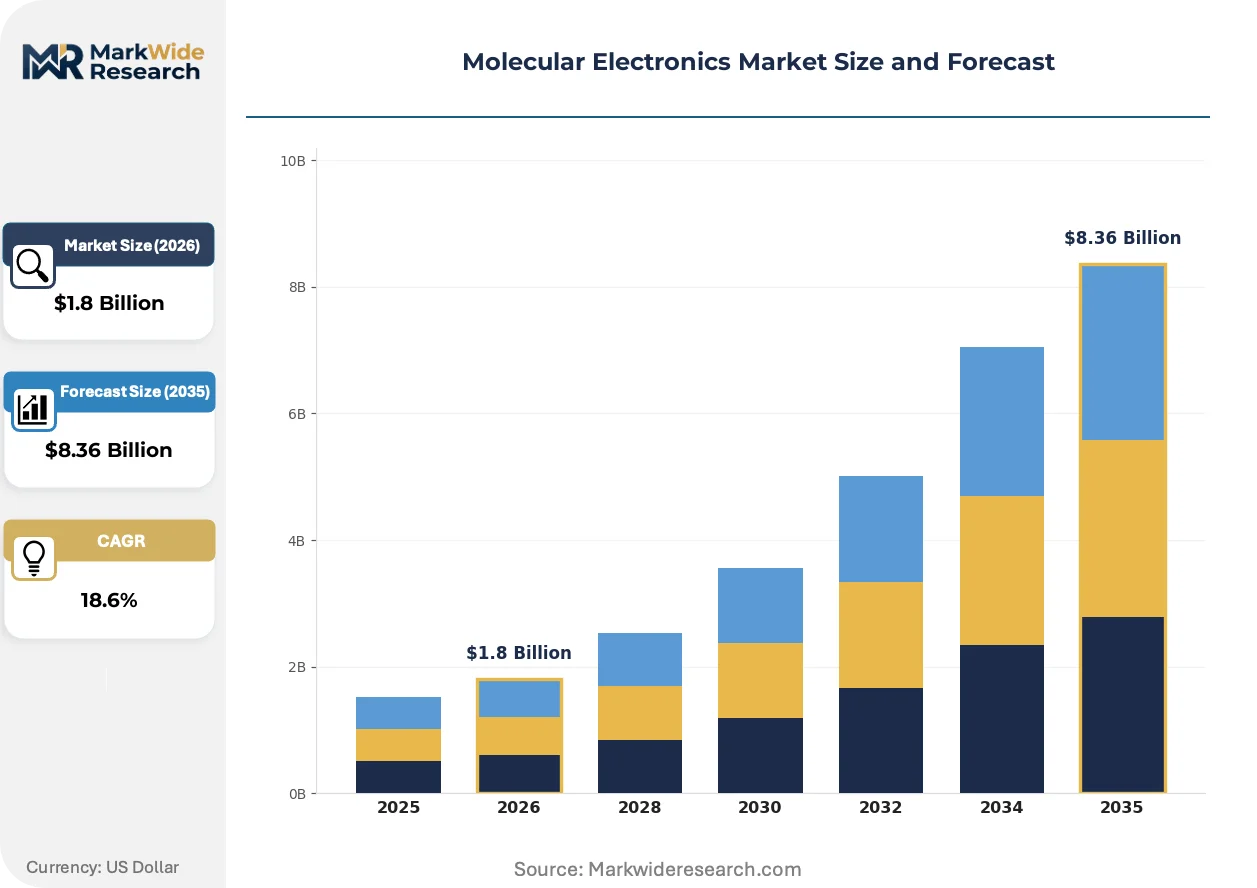
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Transistors, Diodes, Memory Devices, Sensors Material: Organic Semiconductors, Nanomaterials, Molecule-based Materials, Conductive Polymers Application: Flexible Electronics, Energy Harvesting, Display Technologies, Biomedical Devices End User: Consumer Electronics, Healthcare, Automotive, Aerospace |
| Companies Covered | Merck KGaA, Sumitomo Chemical Co., Ltd., Samsung Display Co., Ltd., Evonik Industries AG, Idemitsu Kosan Co., Ltd., LG Display Co., Ltd., DuPont de Nemours, Inc., AGC Inc., Universal Display Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Electronics Market Shifts & Advancements
Molecular-scale device architectures are forcing simultaneous evolution in fabrication methods, regulatory compliance protocols, and procurement specifications across end-use verticals.
Single-molecule junction technology is fragmenting established electronic design paradigms by enabling conductance quantization at sub-ten-nanometer dimensions. Biomedical implant manufacturers are adopting these architectures fastest, driven by diagnostic sensor miniaturization requirements. The technology is fragmenting competitive positioning between organic semiconductor specialists and nanomaterials suppliers.
EMA's evolving nanomedicine device framework is tightening biocompatibility characterization requirements for implantable molecular sensors entering European commercial channels. Manufacturers must now submit extended toxicity profiles alongside traditional electrical performance data. Biomedical device segments face the steepest compliance cost escalation, with South Korean suppliers accelerating parallel FDA submission strategies.
Specification-driven procurement now dominates molecular electronics sourcing, with end-users mandating REACH-compliant precursor certificates and single-batch traceability. Distributors lacking analytical documentation capabilities are losing share to qualified direct-from-foundry channels. This shift is most visible in German and French biomedical device supply chains, where hospital procurement consortiums enforce molecular purity thresholds.
Molecular Electronics Market Segmentation
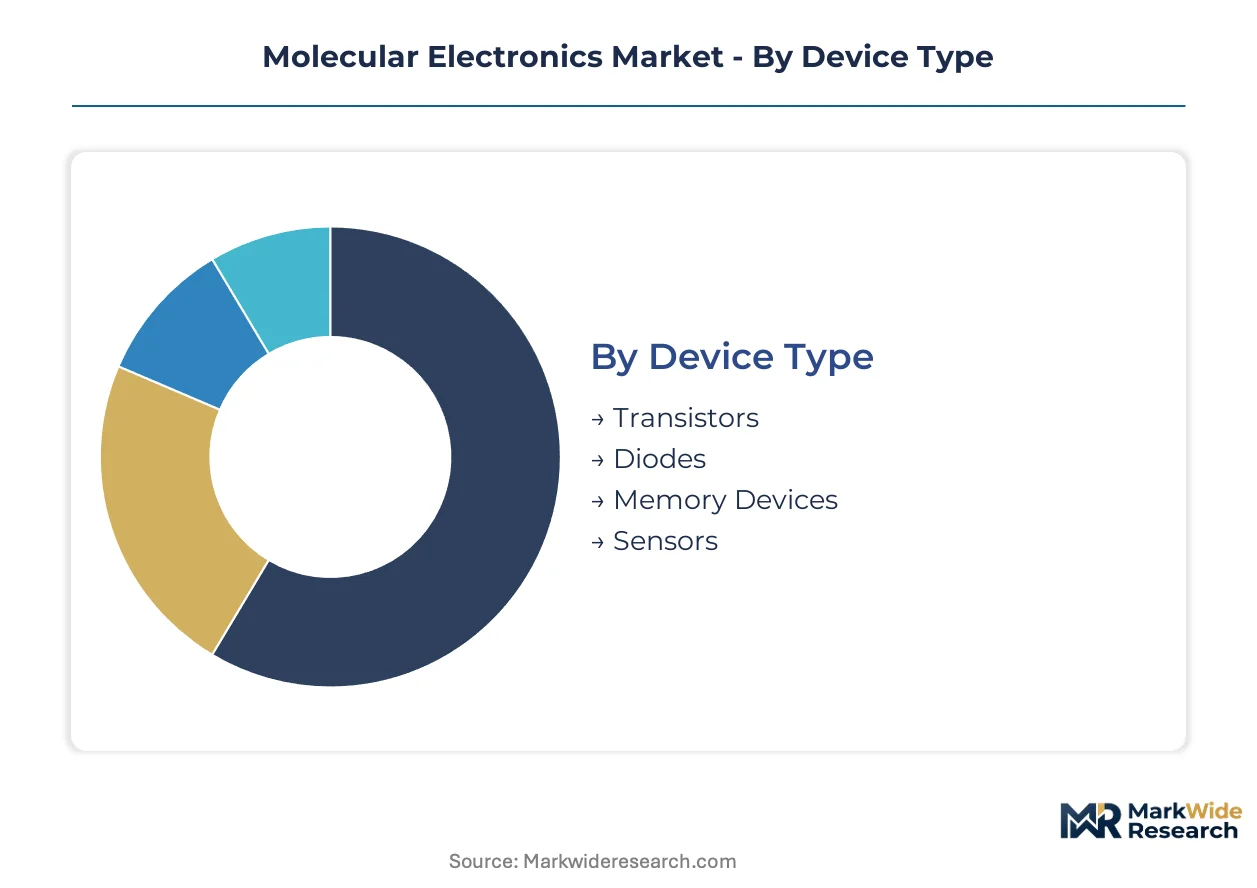
Molecular electronics spans four intersecting segmentation axes where material purity grades, device reliability thresholds, and end-user certification requirements create divergent competitive dynamics. Each dimension carries distinct regulatory burdens and margin structures that reshape supplier positioning across the forecast window.
Device Type:
REACH substance registration in Europe and FDA nanotechnology guidance in the United States impose divergent characterization requirements on molecular-scale active components entering commercial channels.
- Transistors:Molecular thin-film architectures with sub-ten-nanometer channel lengths anchor flexible OLED panel production at Samsung Display and LG Display foundries in South Korea. FDA submission strategies for biomedical variants are accelerating as implantable sensor manufacturers demand quantized conductance precision for diagnostic signal processing.
- Sensors:Single-molecule junction configurations enable continuous biomarker detection with molecular-scale selectivity, though EMA's evolving nanomedicine framework extends European approval timelines for implantable configurations. Biomedical device procurement consortiums in Germany and France now mandate REACH-compliant precursor certificates with single-batch traceability.
- Diodes:Rectifying molecular junctions serve energy harvesting applications where carbon nanotube interconnects displace conventional metal traces.
- Memory Devices:Molecular-scale storage elements exploit conductance hysteresis for non-volatile architectures in aerospace radiation-hardened systems.
Established volume favors transistors; emerging adoption favors sensors.
Material:
Cost tier differentiation separates qualified precursor suppliers from commodity distributors lacking analytical documentation capabilities.
- Organic Semiconductors:Vapor-deposition compatible small-molecule and polymer semiconductors leverage established infrastructure for rapid process transfer, with Merck KGaA's integrated materials platform controlling captive feedstock supply. REACH compliance mandates in Europe are forcing standardization of purity grades and accelerating qualified supplier consolidation.
- Nanomaterials:Carbon nanotube and graphene formulations enable high-density interconnect architectures with superior conductivity-to-weight ratios, expanding most quickly as display manufacturers displace copper traces in foldable panel mechanics. South Korean R&D clusters anchor advanced nanotube purification and dispersion process development.
- Molecule-based Materials:Single-molecule active layers require specialized metrology infrastructure absent from conventional semiconductor characterization facilities.
- Conductive Polymers:Solution-processable formulations target cost-sensitive flexible electronics where deposition equipment capital requirements are lowest.
Organic semiconductors dominate current procurement volumes; nanomaterials are gaining share fastest.
Application:
Customer type concentration splits between specification-driven hospital procurement and volume-optimized consumer electronics supply chains.
- Display Technologies:Molecular-scale thin-film transistors enable mechanical flexibility in foldable OLED panels where Samsung Display commands manufacturing leadership. South Korean foundry clusters integrate precursor synthesis, device fabrication, and panel assembly within concentrated geographic footprints.
- Biomedical Devices:Implantable diagnostic sensors concentrate the highest margin opportunities through molecular-scale detection element integration, though cross-border regulatory divergence between EMA and FDA frameworks threatens supplier market access. Extended toxicity profile submissions now accompany traditional electrical performance data for European commercial entry.
- Flexible Electronics:Wearable and conformable systems prioritize solution-processable materials compatible with roll-to-roll manufacturing.
- Energy Harvesting:Molecular rectifiers and thermoelectric junctions target autonomous sensor networks in automotive and aerospace deployments.
Display technologies anchor revenue scale; biomedical devices command premium pricing tiers.
End User:
Supply concentration patterns mirror the geographic clustering of specialized nanofabrication workforce pools and regulatory expertise.
- Healthcare:Implantable sensor manufacturers in Germany, France, and the United States drive demand for biocompatible molecular junctions with REACH and FDA dual certification. Hospital procurement consortiums enforce molecular purity thresholds that disqualify distributors lacking batch-level analytical documentation.
- Consumer Electronics:Flexible display and wearable device manufacturers in South Korea and Japan concentrate volume demand for organic semiconductor deposition capacity. Samsung Display's captive R&D pipelines integrate molecular electronics development with next-generation panel mechanics.
- Automotive:In-cabin sensing and lightweight wiring applications are emerging as secondary demand centers.
- Aerospace:Radiation-hardened molecular memory and sensing systems serve satellite and deep-space mission requirements.
Healthcare procurement is climbing the fastest; consumer electronics retains volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nanotechnology guidance anchors United States regulatory frameworks, while EMA's evolving nanomedicine protocols and REACH substance registration shape European commercial entry. South Korean foundry clusters concentrate display manufacturing leadership.
United States
Implantable diagnostic sensor manufacturers in Massachusetts and California drive demand for biocompatible molecular junctions with dual FDA certification pathways. EPA characterization requirements for nanomaterial-based devices extend pre-market approval timelines. Greater Boston anchors biomedical device R&D pipelines where hospital procurement consortiums enforce molecular purity thresholds.
South Korea
Samsung Display and LG Display anchor captive demand for molecular thin-film transistors in foldable OLED panel production. MFDS biocompatibility protocols for implantable electronics shape regulatory submission strategies for domestic suppliers. Seoul Capital Area concentrates precursor synthesis, device fabrication, and panel assembly within integrated geographic footprints.
Germany
Merck KGaA's integrated materials platform controls captive organic semiconductor feedstock supply for European deposition capacity. REACH substance registration mandates force standardization of precursor purity grades and accelerate qualified supplier consolidation. Bavaria and North Rhine-Westphalia host specialized nanofabrication workforce pools facing acute scarcity.
Japan
Sumitomo Chemical and Idemitsu Kosan anchor domestic organic semiconductor production for display and flexible electronics applications. METI standards for nanomaterial characterization influence regional testing protocol harmonization. Kansai and Chubu regions concentrate vapor-deposition equipment manufacturing and molecular assembly process development.
China
Domestic display manufacturers accelerate molecular electronics R&D investment to reduce import dependency for advanced panel components. NMPA nanotechnology guidance and GB standards for nanomaterial safety shape biocompatibility testing requirements. Yangtze River Delta clusters integrate carbon nanotube purification with high-density interconnect manufacturing for consumer electronics supply chains.
Molecular Electronics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with materials-science conglomerates controlling captive precursor supply while display manufacturers internalize molecular electronics R&D. Market structure reflects concentration in organic semiconductor deposition and nanomaterial purification. Three archetypes dominate: integrated materials platforms, captive display foundries, and specialized organic electronics suppliers. Competitive moves center on backward integration into precursor synthesis and strategic partnerships for metrology infrastructure access.
Among Germany-based materials conglomerates, Merck KGaA and Evonik Industries AG occupy positions exemplifying integrated platform strategies. Samsung Display Co., Ltd. represents the captive foundry archetype, anchoring molecular thin-film transistor development within concentrated South Korean manufacturing clusters. These three entities illustrate how geographic clustering of specialized workforce pools and regulatory expertise reinforces competitive positioning across precursor supply and device fabrication boundaries.
| Leading Market Players |
|---|
| Merck KGaA |
| Sumitomo Chemical Co., Ltd. |
| Samsung Display Co., Ltd. |
| Evonik Industries AG |
| Idemitsu Kosan Co., Ltd. |
| LG Display Co., Ltd. |
| DuPont de Nemours, Inc. |
| AGC Inc. |
| Universal Display Corporation |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety day precursor lead times for REACH-certified organic semiconductors concentrate pricing power with Merck KGaA's integrated materials platform, while specification-driven hospital procurement in Germany and France compresses margins for distributors lacking batch-level analytical documentation.
Pricing Analysis
Price spreads between South Korean display-grade precursors and European biomedical-certified materials exceed threefold, reflecting divergent purity thresholds and regulatory documentation burdens. Three-tier pricing structure across biomedical-certified, display-grade, and industrial-standard levels segments buyers by certification complexity. Cost compression in display-grade organic semiconductors is intensifying because Samsung Display's captive R&D pipelines internalize molecular thin-film transistor development. Consumer electronics manufacturers exhibit highest price sensitivity; implantable sensor developers accept premium tiers for dual FDA-EMA certification.
Supply Chain Analysis
Germany and South Korea anchor precursor synthesis and device fabrication respectively, with Bavaria controlling captive organic semiconductor feedstocks and Seoul Capital Area integrating panel assembly within concentrated geographic footprints. The supply chain draws from specialized nanofabrication workforce pools, vapor-deposition equipment bases, and carbon nanotube purification infrastructure. Single-source vulnerability in Merck KGaA's organic semiconductor deposition feedstocks threatens foundry expansion timelines. Distribution runs through qualified direct-from-foundry channels for biomedical applications, while display materials move through consolidated chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in regulatory compliance consulting and batch-level certification documentation are expanding faster than hardware revenues as hospital procurement consortiums enforce molecular purity thresholds.
For Market Incumbents: Shield foundry margins by securing captive precursor supply through backward integration into organic semiconductor synthesis, and defend against nanomaterials substitution by accelerating carbon nanotube interconnect R&D partnerships. Regulatory divergence between EMA and FDA frameworks threatens cross-border market access; dual-certification infrastructure investment is the critical defensive lever. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks offer the most penetrable entry path for implantable molecular sensor developers lacking established regulatory track records. Target diagnostic sensor miniaturization in Greater Boston's biomedical device cluster where specialized nanofabrication workforce scarcity constrains incumbent expansion. Lead with regulatory submission strategy as core value proposition rather than hardware differentiation. For Investors and Strategic Acquirers: Long-term, this sits as a materials-science platform play because molecular electronics converges precursor chemistry, device physics, and regulatory expertise into defensible integrated capabilities. Acquisition targets should display captive supply control over REACH-certified precursors or FDA-submitted device pipelines. Watch for EMA-FDA regulatory convergence signaling as the inflection indicator for cross-border market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Merck KGaA's captive organic semiconductor supply demonstrates how materials control anchors pricing power. |
| Dual FDA-EMA Certification Infrastructure | Biomedical device procurement consortiums in Germany and France now mandate REACH-compliant precursor certificates. |
| Carbon Nanotube Interconnect Development | South Korean R&D clusters anchor advanced purification processes displacing copper traces in foldable panels. |
| Regulatory Compliance Consulting Services | Extended toxicity profile submissions for EMA nanomedicine framework compliance create recurring revenue layers. |
| Specialized Nanofabrication Workforce Pipeline | Bavaria and North Rhine-Westphalia face acute talent scarcity compressing foundry expansion timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with molecular electronics foundry engineers, biomedical device regulatory affairs leads, organic semiconductor procurement managers at display manufacturers, and hospital purchasing committee representatives. Secondary validation drew from EMA nanomedicine framework documentation, FDA nanotechnology guidance filings, REACH substance registration databases, and South Korean MFDS biocompatibility protocol submissions. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Across the projection horizon, the analytical framework modeled device type, material grade tier, application vertical, and end-user regulatory cluster dimensions. CAGRs were derived from segment-level growth trajectory analysis calibrated to precursor supply expansion timelines and regulatory approval velocity. Forecast inputs incorporated nanofabrication workforce availability indices and qualified supplier consolidation patterns.
Decision-makers should treat outputs as directional under stable regulatory divergence assumptions; material convergence between EMA and FDA frameworks would warrant model refresh. Forecasts reflect characterization requirement evolution and workforce scarcity persistence as base conditions. Recalibration cycles align with material shifts in nanomedicine device framework finalization and specialized talent pipeline development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
North America Wigig Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
AI PC Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Global Ultrafast Lasers Market
Emerging and Next Generation Technologies
AI Edge Computing Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
Terahertz Radiation Devices Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
Metal Additive Manufacturing Systems Market
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
Nanopatterning Market