
 Triboelectric Nano-Generator Market | 2026-2036
Triboelectric Nano-Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Triboelectric Nano-Generator Market Analytics
China's capacity build-out for nano-energy harvesting is reshaping regional supply dynamics. Samsung Electronics Co., Ltd. leverages its semiconductor fabrication infrastructure to anchor triboelectric module production. TENGTech Co., Ltd. specializes in flexible polymer substrate architectures for wearable integration. Texas Instruments Incorporated competes through precision analog front-end circuits that condition triboelectric output signals.
Triboelectric nano-generators harvest ambient mechanical energy through contact electrification and electrostatic induction between dissimilar material layers, typically operating at 1-1000 Hz with output voltages reaching 10-500V depending on surface functionalization and gap distance. The primary commercial purpose is eliminating battery dependency in distributed sensor networks and portable electronics. Flexible nano-generators dominate current revenue pools due to their compatibility with wearable electronics and biomedical patches, while rigid nano-generators sustain higher power density for industrial automation applications. Hybrid nano-generators represent the fastest structural expansion as manufacturers combine triboelectric and piezoelectric mechanisms to broaden operational frequency ranges.
China's MIIT enforces GB standards for nano-device electromagnetic compatibility that filter non-compliant imports from European and North American suppliers. The EU's RoHS and REACH frameworks restrict hazardous substances in triboelectric polymer layers, forcing reformulation of fluorinated dielectric materials. South Korea's MFDS and KATS coordinate on biomedical device energy-harvesting certifications that shape clinical trial timelines for implantable triboelectric sensors. Stakeholders must monitor which regulatory jurisdiction certifies first for networked energy-harvesting modules, as that geography typically sets the de facto global compliance baseline.
Market Dynamics
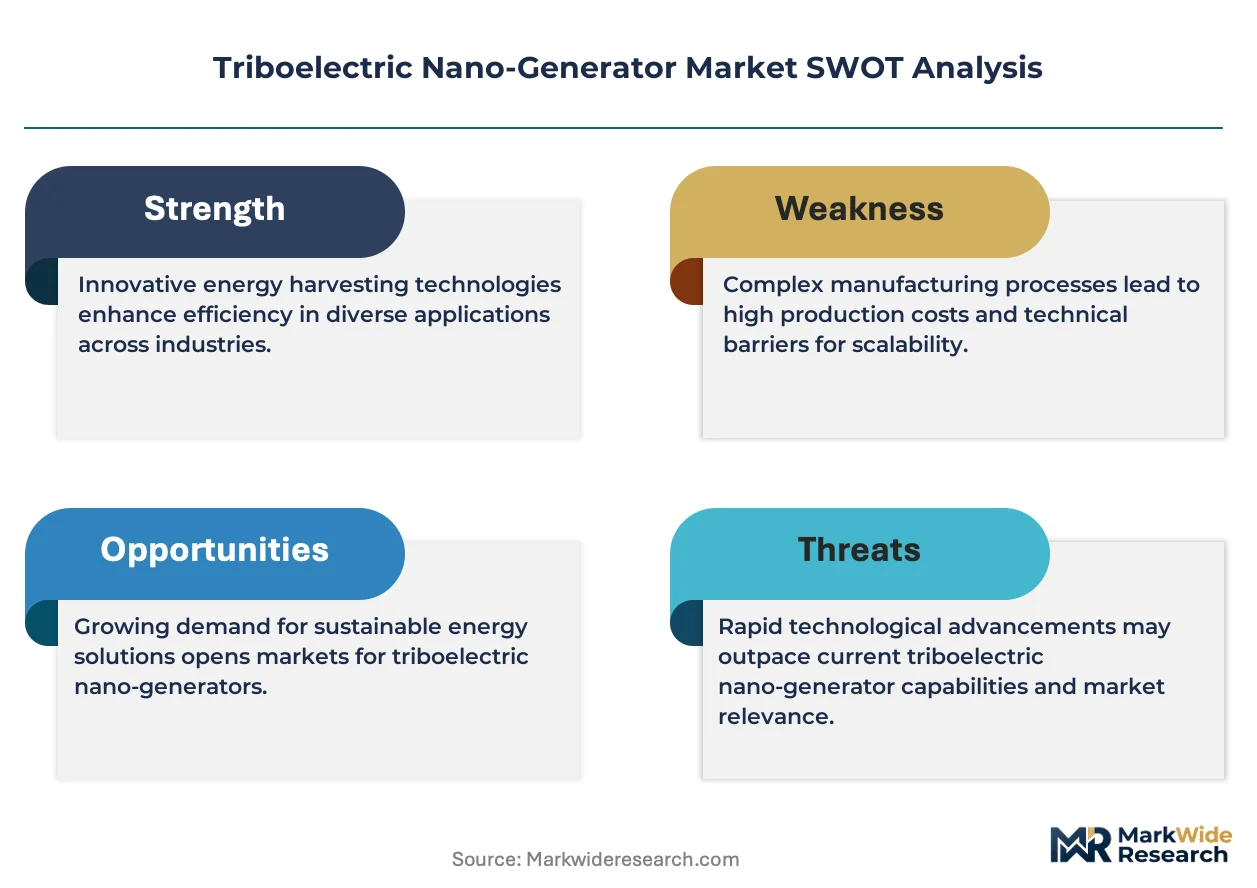
China's MIIT certification acceleration is compressing domestic qualification timelines for triboelectric modules, forcing foreign suppliers to relocate testing facilities or cede procurement slots to local competitors.
Growth Catalysts
- GB Standards Acceleration:China's MIIT has streamlined electromagnetic compatibility testing for nano-energy harvesting devices, reducing certification cycles and unlocking faster domestic deployment.
- Biomedical Implant Demand:South Korea's MFDS and KATS coordination on energy-harvesting certifications is enabling clinical trials for self-powered cardiovascular monitors and neural sensors.
- Wearable Electronics Procurement:Consumer electronics manufacturers in Seoul and Suwon are expanding sensor module orders that eliminate battery dependency through triboelectric power.
Market Restraints
- Fluorinated Dielectric Reformulation:The EU's REACH framework restricts perfluorinated compounds in polymer layers, forcing suppliers to redesign dielectric materials at elevated R&D cost.
- Output Signal Conditioning Complexity:Triboelectric generators produce high-voltage, low-current pulses that require precision analog front-end circuits, adding BOM cost and design risk.
- Frequency Bandwidth Limitation:Single-mechanism devices operate effectively only within narrow 1-1000 Hz ranges, limiting harvestable energy sources in variable mechanical environments.
Strategic Opportunities
- Hybrid Mechanism Convergence:Manufacturers combining triboelectric and piezoelectric layers can capture broader frequency spectra, opening industrial vibration monitoring applications.
- India's Medical Device PLI:India's Production Linked Incentive scheme for electronics manufacturing offers cost offsets for domestic triboelectric sensor assembly targeting diagnostic equipment.
- Industrial Automation Retrofit:Rigid nano-generator architectures with higher power density can replace wired sensors in legacy factory floors across Germany and Japan.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Contact electrification modeling requires expertise in electrostatics, surface chemistry, and mechanical deformation that crosses traditional engineering boundaries.
- Cross-Jurisdictional Certification Stacking:Networked energy-harvesting modules must satisfy sequential GB, CE, and FCC approvals, with the first-certifying geography setting de facto global baselines that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triboelectric Nano-Generator Market |
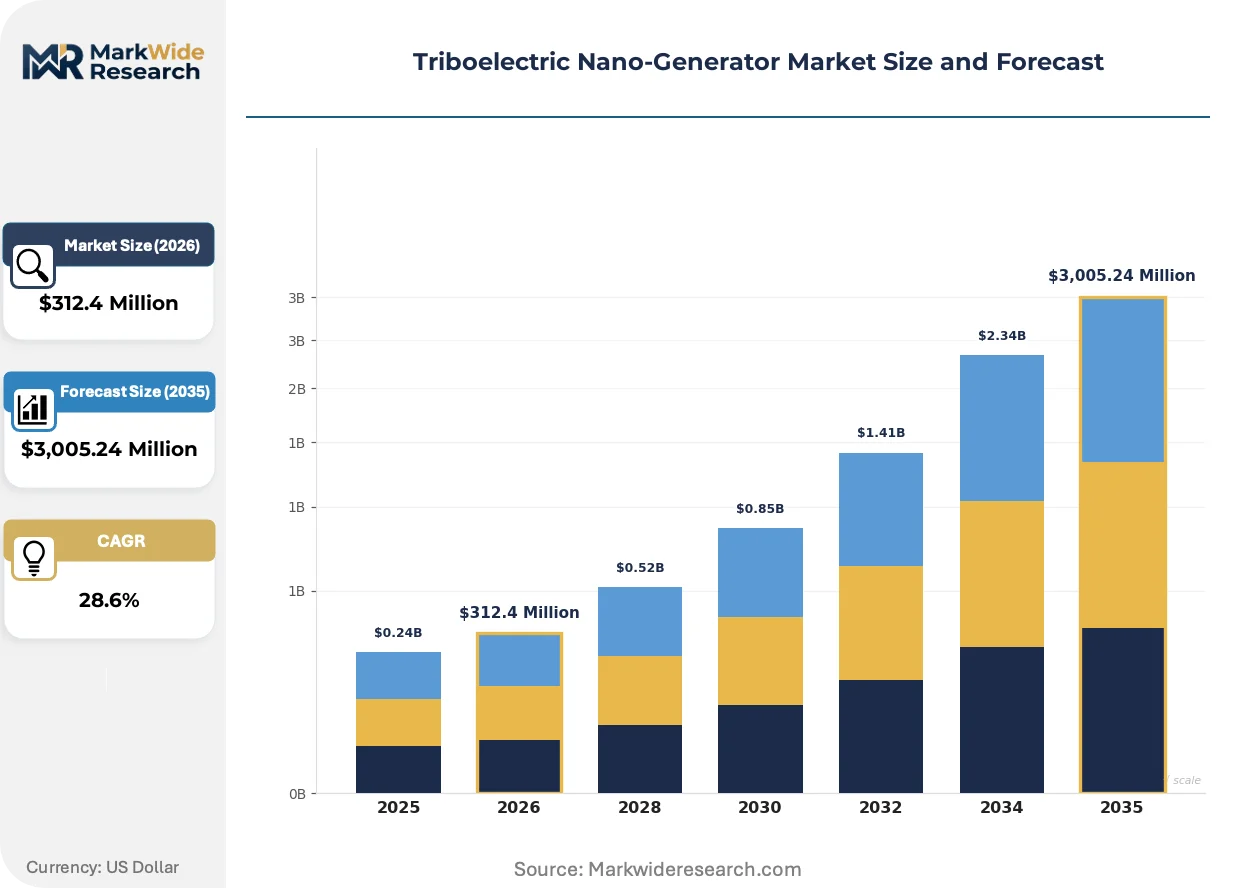
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $3,005.24 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Nano-Generators, Rigid Nano-Generators, Hybrid Nano-Generators, Micro-Dimensional Nano-Generators Application: Wearable Electronics, Wireless Sensors, Biomedical Devices, Automotive Systems End User: Consumer Electronics, Healthcare, Industrial Automation, Aerospace Integration Level: Standalone Systems, Integrated Modules, Networked Solutions, Prototype Editions |
| Companies Covered | Samsung Electronics Co., Ltd., TENGTech Co., Ltd., Texas Instruments Incorporated, Analog Devices, Inc., STMicroelectronics N.V., Xiaomi Corporation, Powercast Corporation, EnOcean GmbH, e-peas S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triboelectric Nano-Generator Market Evolving Landscape
Material surface engineering and hybrid energy-harvesting architectures are collapsing traditional performance trade-offs between flexibility and power density, reshaping competitive differentiation across end-use verticals.
Fluoropolymer-graphene composite dielectrics are collapsing the voltage-gap relationship that previously constrained triboelectric output. Biomedical patch manufacturers in South Korea and Japan are integrating these materials into ultra-thin form factors. The structural consequence is collapsing the minimum viable surface area for clinically relevant power generation, enabling sub-square-centimeter implantable sensors.
The EU's F-Gas Regulation is restricting hydrofluorocarbon use in polymer processing equipment, forcing triboelectric material suppliers to adopt aqueous-based surface functionalization methods. Industrial automation sensor producers face reformulation timelines that compress product refresh cycles. German and French suppliers are responding by vertically integrating polymer synthesis to control substitution pathways.
Sensor OEMs are consolidating vendor relationships around module suppliers offering certified analog front-end integration, displacing discrete component procurement. South Korean consumer electronics clusters now specify complete self-powered sensing subsystems rather than raw harvesters. This consolidation is most visible in wearable manufacturing around Suwon, where buyers demand pre-conditioned signal outputs that eliminate in-house power management design.
Triboelectric Nano-Generator Market Segmentation
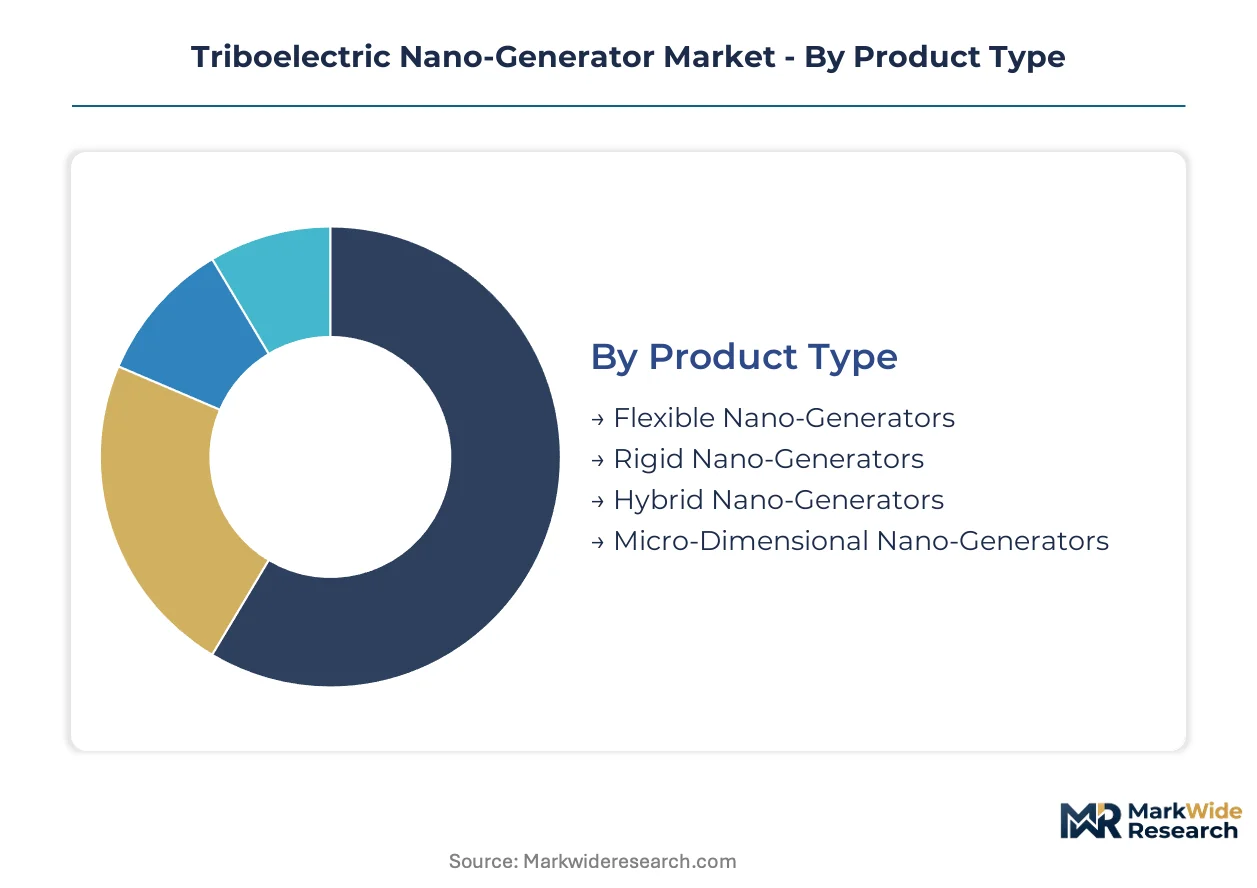
Triboelectric nano-generator architectures diverge sharply across flexibility, power density, and integration depth. Product form factor determines compatible end-use applications, while integration sophistication dictates procurement patterns among OEM buyers.
Product Type:
Structural rigidity versus mechanical compliance defines the primary commercial axis in triboelectric module design.
- Flexible Nano-Generators:Polymer substrate architectures with thin-film electrode layers conform to curved surfaces and dynamic deformation. Wearable electronics manufacturers in Seoul and Suwon specify these for skin-contact devices and textile-integrated sensors. The EU's REACH restrictions on fluorinated dielectrics are forcing material reformulation that elevates unit costs.
- Rigid Nano-Generators:Ceramic or glass-reinforced polymer stacks deliver higher power density through stable gap distances and precise surface alignment. Industrial automation retrofit applications in Germany and Japan favor these for vibration monitoring on legacy factory equipment. The fixed form factor limits deployment to non-conforming surfaces.
- Hybrid Nano-Generators:Combined triboelectric-piezoelectric layers capture broader frequency spectra than single-mechanism alternatives.
- Micro-Dimensional Nano-Generators:Sub-millimeter feature sizes target implantable biomedical sensors and microsystem power supplies.
Flexible nano-generators hold installed capacity. Hybrid nano-generators are rotating up the share rankings.
Application:
End-use verticals impose distinct power output, form factor, and certification requirements on triboelectric module suppliers.
- Wearable Electronics:Wrist-worn, ear-worn, and textile-integrated devices demand sub-millimeter thickness with continuous flex cycling durability. Samsung Electronics Co., Ltd. and domestic competitors in South Korea's consumer electronics cluster are expanding procurement of self-powered sensor modules that eliminate battery dependency.
- Wireless Sensors:Distributed environmental and structural monitors require intermittent high-voltage pulses for data transmission bursts. China's MIIT GB standards for electromagnetic compatibility are accelerating domestic certification timelines for networked deployment.
- Biomedical Devices:Implantable cardiovascular monitors and neural sensors must satisfy biocompatibility and sterilization protocols.
- Automotive Systems:Tire pressure monitors and cabin occupancy sensors harvest vibration and contact energy from vehicle motion.
Wearable electronics commands current revenue concentration. Biomedical devices is climbing the fastest.
End User:
Customer sophistication and procurement scale separate volume buyers from specialized niche adopters.
- Consumer Electronics:Smartphone, tablet, and accessory OEMs specify complete self-powered sensing subsystems with pre-conditioned signal outputs. South Korean manufacturers around Suwon now require module suppliers to deliver certified analog front-end integration, displacing discrete component procurement.
- Healthcare:Hospital systems and diagnostic equipment manufacturers prioritize regulatory compliance over unit economics. South Korea's MFDS and KATS coordination on energy-harvesting certifications shapes clinical trial timelines for implantable triboelectric sensors.
- Industrial Automation:Factory floor operators seek battery elimination in hazardous or inaccessible sensor locations.
- Aerospace:Satellite and unmanned aerial vehicle applications demand extreme temperature tolerance and radiation hardness.
Consumer electronics holds procurement volume leadership. Healthcare is ascending the growth curve.
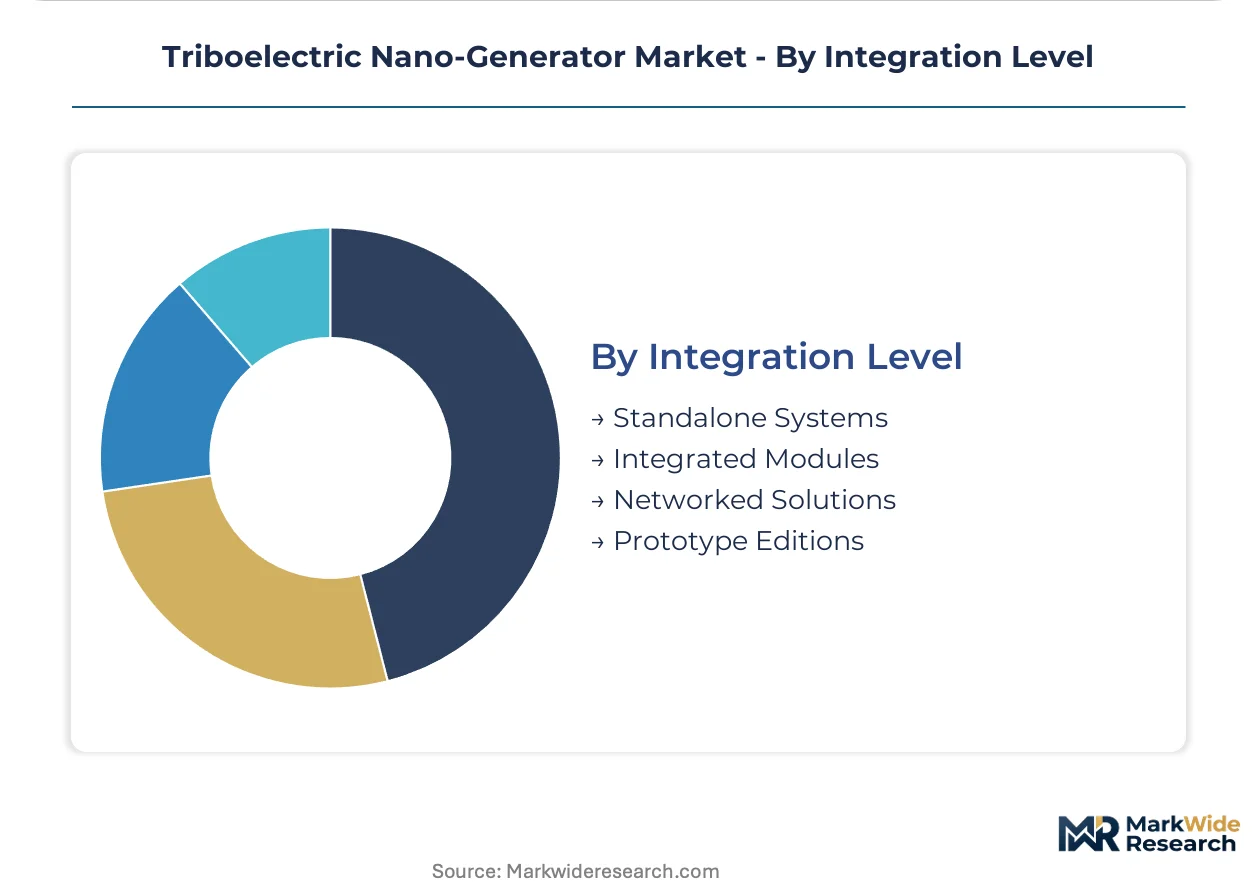
Integration Level:
Supply chain positioning and buyer technical capability determine where value capture concentrates across the integration spectrum.
- Standalone Systems:Complete harvester-storage-load assemblies with enclosure and mounting hardware suit buyers lacking power electronics expertise. Texas Instruments Incorporated competes through precision analog front-end circuits that condition triboelectric output signals for these configurations.
- Integrated Modules:Harvester elements combined with conditioning electronics but without enclosure or energy storage appeal to OEMs with in-house mechanical design.
- Networked Solutions:Multi-node harvester arrays with wireless connectivity and cloud data pipelines target smart building and industrial IoT deployments.
- Prototype Editions:Unqualified engineering samples and development kits support R&D evaluation and custom design iterations.
Integrated modules holds manufacturing scale. Networked solutions is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through accelerated GB standards certification that compresses domestic qualification timelines for triboelectric modules. Foreign suppliers face pressure to relocate testing facilities or cede procurement slots to local competitors.
China
Wearable electronics manufacturers and industrial automation deployers drive module procurement across the Yangtze River Delta. MIIT enforces electromagnetic compatibility GB standards that filter non-compliant imports from European and North American suppliers. The Beijing-Tianjin-Hebei corridor concentrates nano-energy harvesting R&D facilities targeting networked sensor deployment.
South Korea
Consumer electronics OEMs in Seoul and Suwon expand orders for self-powered sensor modules that eliminate battery dependency. MFDS and KATS coordinate on biomedical device energy-harvesting certifications that shape clinical trial timelines for implantable cardiovascular monitors. The Seoul Capital Area anchors triboelectric module production leveraging existing semiconductor fabrication infrastructure.
Germany
Industrial automation retrofit applications favor rigid nano-generator architectures for vibration monitoring on legacy factory equipment. The EU's REACH framework restricts perfluorinated compounds in polymer layers, forcing suppliers to redesign dielectric materials. Bavaria and Baden-Württemberg concentrate precision analog front-end circuit suppliers that condition triboelectric output signals.
United States
Distributed environmental and structural monitors for wireless sensor networks require intermittent high-voltage pulses for data transmission bursts. FCC electromagnetic compatibility approvals set baseline requirements for networked energy-harvesting modules entering North American deployment. The Pacific Northwest and Greater Boston corridors host development activity targeting aerospace and satellite applications demanding radiation hardness.
Japan
Biomedical patch manufacturers integrate fluoropolymer-graphene composite dielectrics into ultra-thin form factors for clinically relevant power generation. METI oversees national standards coordination that aligns with international IEC frameworks for nano-energy devices. The Kanto region around Tokyo concentrates materials engineering expertise for surface functionalization and multilayer deposition processes.
Triboelectric Nano-Generator Market Competitive Landscape
Semiconductor fabricators and precision analog specialists split the market through divergent integration strategies. The vendor base concentrates around three strategic archetypes: integrated device manufacturers leveraging captive wafer capacity, fabless analog designers conditioning raw harvester outputs, and polymer substrate specialists enabling wearable form factors. Dominant competitive moves include backward integration into polymer synthesis to control substitution pathways and consolidation of vendor relationships around certified subsystem suppliers.
Among Asia-Pacific-based electronics conglomerates, Samsung Electronics Co., Ltd. occupies a position exemplifying integrated device manufacturing scale, while TENGTech Co., Ltd. sits within the polymer substrate specialization tier. Texas Instruments Incorporated represents the precision analog conditioning archetype that translates high-voltage triboelectric pulses into usable power rails. These three anchors illustrate how competitive positioning diverges across fabrication depth, materials expertise, and signal processing capability rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| TENGTech Co., Ltd. |
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| STMicroelectronics N.V. |
| Xiaomi Corporation |
| Powercast Corporation |
| EnOcean GmbH |
| e-peas S.A. |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing cluster concentrates triboelectric module fabrication capacity, translating supply scarcity in fluoropolymer substrates into asymmetric pricing power for integrated device manufacturers serving South Korean consumer electronics buyers.
Pricing Analysis
Price spreads between qualified and unqualified module suppliers widen near Seoul and Suwon procurement hubs. Pricing stratifies across premium certified, standard compliant, and economy unqualified tiers, with China's MIIT electromagnetic compatibility certification commanding substantial premiums. Cost compression in standard tiers intensifies because REACH-mandated fluorinated dielectric reformulation elevates R&D amortization. Industrial automation buyers exhibit lowest price sensitivity due to battery elimination value, while wearable OEMs negotiate aggressively on volume.
Supply Chain Analysis
Export control regimes restricting advanced polymer deposition equipment limit technology transfer to non-aligned manufacturing jurisdictions. Supply concentrates in China, South Korea, and Japan for fluoropolymer-graphene composite dielectrics, precision analog front-end circuits, and thin-film electrode deposition systems. The chain draws from fluorochemical feedstocks, semiconductor-grade silicon substrates, and noble metal sputtering targets. Single-source vulnerability concentrates in aqueous-based surface functionalization equipment following EU F-Gas Regulation restrictions. Distribution runs through certified subsystem suppliers rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Triboelectric nano-generators constitute a high-growth disruption anchored by China's MIIT certification acceleration compressing domestic timelines and hybrid mechanism convergence collapsing flexibility-power density trade-offs.
For Market Incumbents: Harden certification portfolios against China's GB standards acceleration by relocating electromagnetic compatibility testing facilities to the Yangtze River Delta or ceding procurement slots to local competitors. Deepen backward integration into fluoropolymer synthesis to control REACH-mandated substitution pathways and defend margin position against aqueous-based surface functionalization cost elevation. For New Entrants and Emerging Players: India's medical device PLI scheme for electronics manufacturing represents the most penetrable entry point, offering cost offsets for domestic triboelectric sensor assembly targeting diagnostic equipment. Biomedical implant applications in South Korea's MFDS-coordinated certification pathway offer second-mover advantage through clinical trial partnership structures. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified materials conglomerates with captive polymer synthesis divisions underutilized for triboelectric dielectric production. The five-to-ten-year viability window favors precision analog front-end circuit specialists over raw harvester manufacturers. Watch hybrid mechanism patent filing velocity as inflection indicator for technology convergence maturity.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT GB Standards Pre-Certification | Accelerated domestic qualification timelines in China filter non-compliant European and North American imports from procurement slots. |
| Fluoropolymer Synthesis Backward Integration | German and French suppliers control REACH-mandated substitution pathways through captive polymer production rather than external sourcing. |
| Hybrid Mechanism R&D Partnership | Combined triboelectric-piezoelectric layer development broadens operational frequency ranges for industrial vibration monitoring applications. |
| Analog Front-End Subsystem Consolidation | South Korean wearable OEMs around Suwon now specify complete self-powered sensing subsystems displacing discrete component procurement. |
| Biomedical Certification Coordination | South Korea's MFDS and KATS alignment on energy-harvesting certifications shapes clinical trial timelines for implantable cardiovascular monitors. |
Research Methodology
A standing panel of triboelectric materials scientists, wearable electronics procurement directors, biomedical device regulatory affairs leads, and precision analog circuit design engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from MIIT GB standards documentation, EU REACH substance restriction filings, MFDS certification pathway disclosures, and semiconductor fabrication capacity announcements. Bottom-up module shipment estimates triangulated against top-down energy-harvesting device market allocations.
Scenario-bracketing framed analytical approach across the projection horizon, with sensitivity testing on fluoropolymer feedstock cost trajectories and certification timeline compression rates. Segmentation dimensions modeled included structural rigidity class, end-use vertical, integration depth, and regional regulatory cluster. CAGRs derived from installed capacity build-out curves and OEM procurement pipeline visibility. Industry-specific inputs incorporated hybrid mechanism patent filing velocity and aqueous-based surface functionalization equipment deployment rates.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or fluorochemical feedstock pricing would shift the trajectory. Forecasts reflect documented assumptions on GB standards enforcement intensity and REACH reformulation timeline adherence. Material shifts in hybrid mechanism convergence rates or biomedical certification reciprocity agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
Terahertz Radiation Devices Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
North America Wigig Market
Emerging and Next Generation Technologies
Global Terahertz Technology Market
Emerging and Next Generation Technologies
Third-Generation Solar Cells Market
Emerging and Next Generation Technologies
Swarm Intelligence Market
Emerging and Next Generation Technologies
MLDW Technology Market
Emerging and Next Generation Technologies
Switchable Smart Film Market
Emerging and Next Generation Technologies
Flexible Electronics Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market