
 Fish Collagen Peptides Market | 2026-2036
Fish Collagen Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Collagen Peptides Market Analysis
Pharmaceutical-grade peptide purity is reorganizing competitive positioning in fish collagen peptides. Gelita AG leverages backward integration into sustainable marine raw material sourcing to sustain cost advantages across European nutraceutical channels. Amicogen Co., Ltd. anchors its position through biotechnology-driven enzymatic hydrolysis platforms that dominate South Korean nutricosmetic supply chains. PB Leiner differentiates via specialized cold-water species extraction protocols that control premium segment access in Nordic markets.
Fish collagen peptides comprise low-molecular-weight protein fragments derived from marine skins and scales through controlled enzymatic hydrolysis, typically achieving molecular weights below 3,000 Daltons for optimal bioavailability in dermal matrix support and joint tissue applications. Hydrolyzed collagen commands the largest value pool due to its formulation flexibility across powders and ready-to-drink formats, while collagen drinks represent the fastest-expanding application format as beverage brands seek functional differentiation. Sports nutrition applications are maturing with established dosage protocols, whereas nutricosmetics concentrates margin capture as beauty-from-within positioning commands premium shelf pricing.
FDA GRAS self-affirmation pathways and EFSA novel food opinions shape ingredient market access timelines for North American and European suppliers respectively, while Japan's FOSHU regulatory framework creates structured health claim validation for marine collagen entrants. China's NMPA and SAMR oversight of dietary supplement registration adds compliance layers for imported peptide ingredients targeting functional food formulations. Stakeholders must monitor evolving marine sustainability certification requirements as procurement standards tighten across major demand centers.
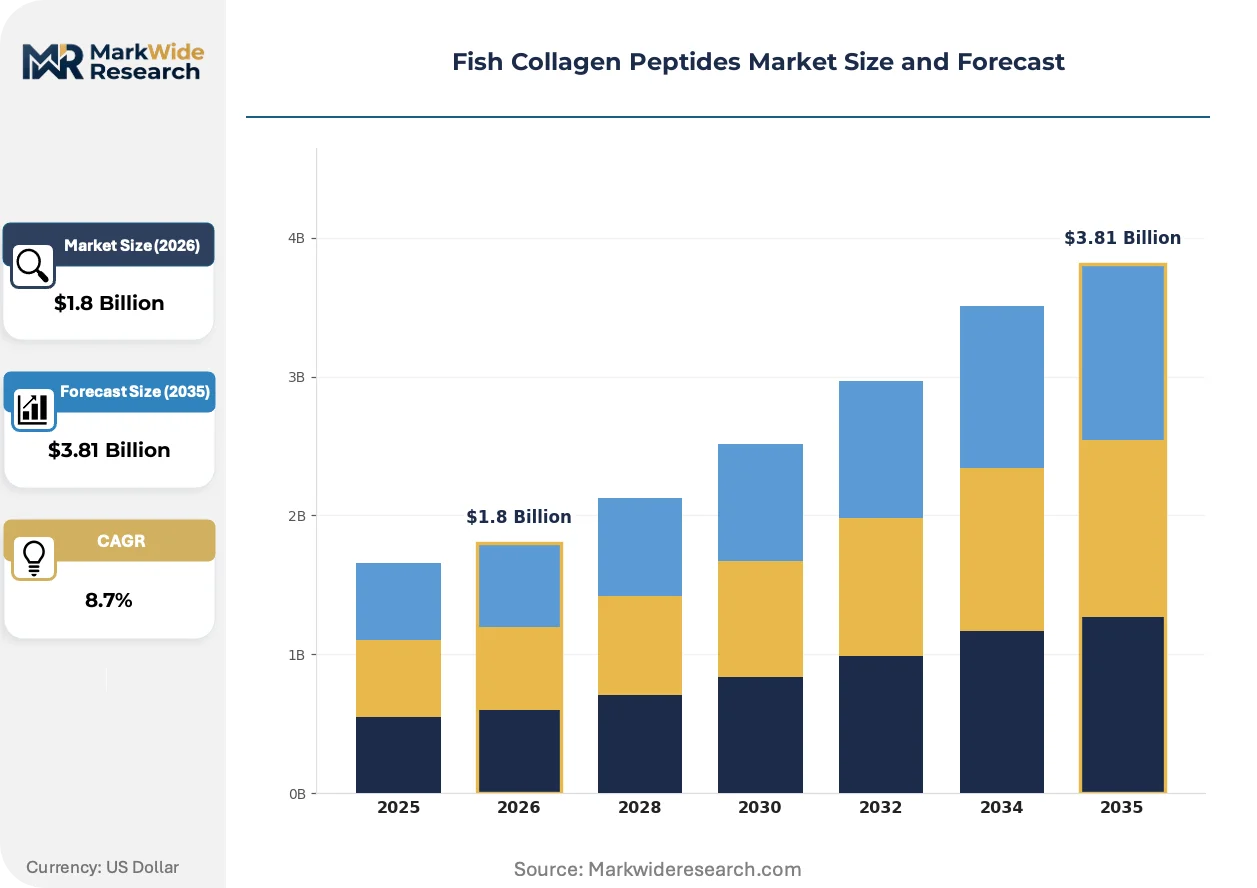
Market Dynamics
Enzymatic hydrolysis efficiency gains are compressing unit production costs for Type I collagen extraction while simultaneously enabling pharmaceutical-grade purity thresholds that reconfigure supplier competitiveness across nutraceutical and nutricosmetic channels.
Growth Catalysts
- Japan's FOSHU framework:Structured health claim validation pathways accelerate marine collagen market access for functional food entrants targeting beauty-from-within positioning.
- Pangasius byproduct utilization:Vietnam's Mekong Delta skin and scale collection infrastructure feeds regional hydrolyzed collagen output with captive raw material flows.
- Nutricosmetic formulation demand:South Korean beauty brands integrate marine peptides into ready-to-drink formats at dosage protocols optimized for dermal matrix support claims.
Market Restraints
- Marine raw material cost volatility:Cold-water species procurement faces seasonal catch fluctuations and fuel-linked vessel operating expenses that transmit into peptide input pricing.
- EFSA novel food opinion timelines:European market access requires structured safety dossiers that extend ingredient commercialization schedules by multiple review cycles.
- Bovine and porcine collagen substitution:Land-based alternatives compete on cost in sports nutrition applications where marine sourcing premiums face price-sensitive formulation budgets.
Strategic Opportunities
- China's functional food registration pathway:NMPA and SAMR oversight creates compliance moats for early entrants mastering dual carbon goal alignment and import peptide documentation.
- Sports nutrition beverage convergence:Ready-to-drink collagen fortification combines with established protein dosage protocols to capture gym-channel shelf space.
- Marine sustainability certification integration:Procurement standards tightening across Nordic and Japanese demand centers reward suppliers with MSC or ASC chain-of-custody credentials.
Industry Challenges
- Enzyme optimization expertise scarcity:Formulation teams with cross-training in protease selection and hydrolysis degree control command compensation premiums that strain mid-scale facility economics.
- Multi-jurisdiction GRAS self-affirmation complexity:FDA notification requirements for novel peptide molecular weight distributions demand toxicology investment without guaranteed timeline certainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Collagen Peptides Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Collagen Capsules, Collagen Powder, Collagen Drinks Application: Nutricosmetics, Dietary Supplements, Functional Foods, Sports Nutrition End User: Healthcare, Beauty, Fitness, Nutritional Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Nitta Gelatin NA Inc, ConnOils LLC, Gelita AG, Amicogen Co., Ltd., Vinh Hoan Corporation, Weishardt International, PB Leiner, Holista Colltech Ltd., Lapi Gelatine S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Collagen Peptides Market Emerging Trajectories
Controlled molecular weight engineering is compressing the gap between commodity hydrolyzed powders and pharmaceutical-grade peptides, enabling new application entry points across medical nutrition and premium nutricosmetics.
Membrane filtration technology is miniaturizing the separation infrastructure required for sub-3,000 Dalton peptide fractionation. Contract manufacturers in South Korea deploy compact ceramic membrane skids that previously demanded industrial-scale footprints. This equipment compression enables regional production nodes to serve nutricosmetic brands with freshness-advantaged, small-batch output.
EFSA's evolving novel food opinion requirements for marine-sourced hydrolysates are extending safety dossier preparation timelines. European ingredient suppliers now front-load toxicokinetic studies before submission to compress regulatory review cycles. This procedural adaptation most affects hydrolyzed collagen entrants targeting powder supplement formulations in Germany and France.
Beauty-from-within buyers are consolidating purchase decisions through dermatology clinic channels rather than mass retail. Korean and Japanese consumers receive peptide regimen guidance from licensed practitioners who specify molecular weight thresholds and co-formulation with hyaluronic acid or ceramides. This channel migration concentrates margin capture with brands maintaining medical affairs capabilities and practitioner education infrastructure.
Fish Collagen Peptides Market Segmentation
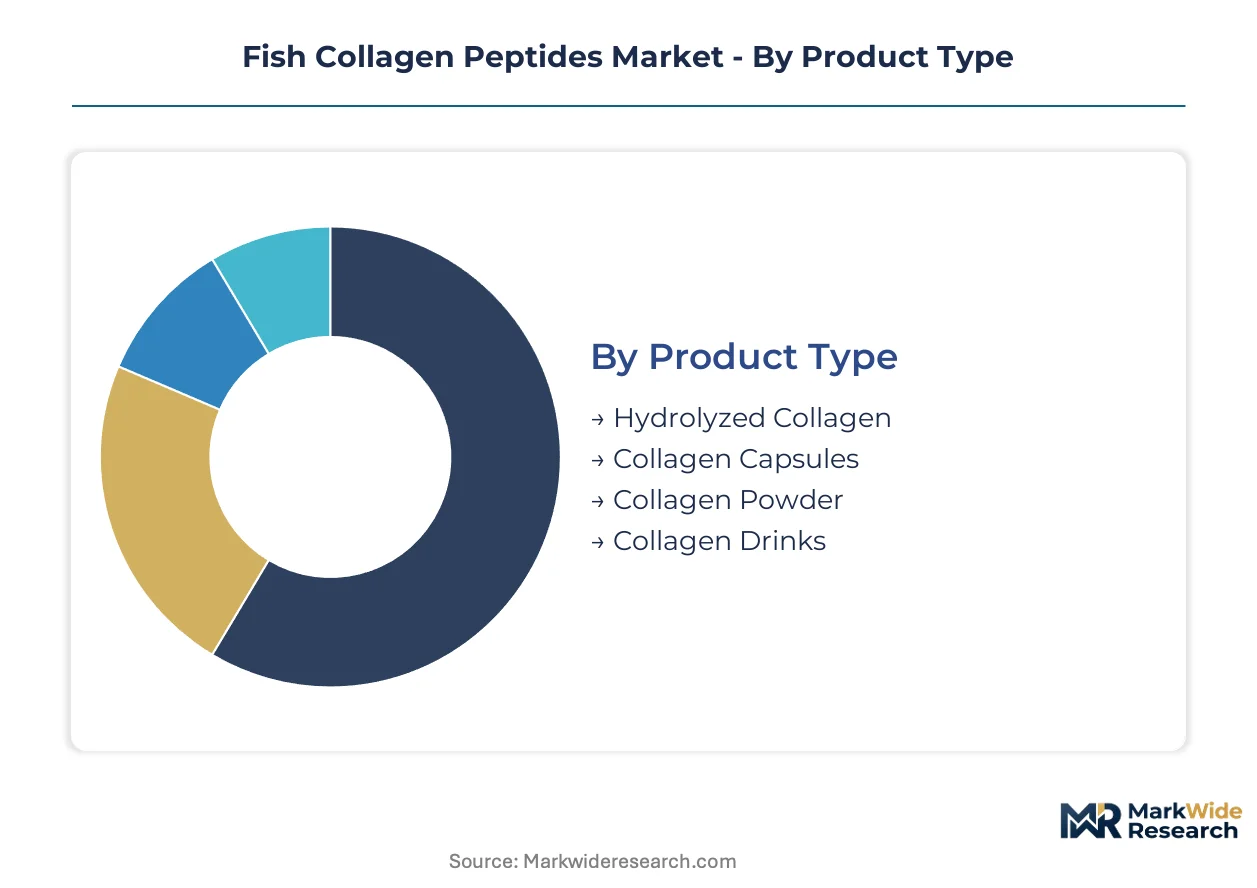
Segmentation in fish collagen peptides reveals how formulation format, regulatory pathway, and channel economics allocate margin capture across nutraceutical value chains. Manufacturers optimize enzyme selection and molecular weight targeting differently for each segment tier.
Product Type:
Margin pools concentrate in ready-to-drink formats where beverage brands absorb peptide premiums for functional differentiation, while powder formulations compete on scale economics.
- Hydrolyzed Collagen:Low-molecular-weight peptides below 3,000 Daltons achieved through controlled enzymatic hydrolysis of marine skins and scales. Demand concentrates in South Korean nutricosmetic supply chains where beauty-from-within positioning commands premium shelf pricing alongside hyaluronic acid co-formulation.
- Collagen Drinks:Ready-to-drink fortification formats leveraging established protein dosage protocols for gym-channel distribution. Japanese and Vietnamese markets show fastest uptake as beverage brands seek functional differentiation with FOSHU-aligned health claims.
- Collagen Powder:Flexible formulation base for supplement compounding across sports nutrition and medical nutrition applications.
- Collagen Capsules:Unit-dose convenience format targeting travel retail and practitioner-directed regimens in dermatology clinic channels.
Hydrolyzed collagen holds installed capacity. Collagen drinks is rotating up the share rankings.
Application:
Application tiering follows regulatory complexity, with nutricosmetics capturing margin through medical affairs infrastructure while sports nutrition competes on dosage standardization.
- Nutricosmetics:Beauty-from-within positioning with peptide regimens specified by licensed practitioners in Korean and Japanese dermatology clinics. EFSA novel food opinion requirements extend European commercialization timelines for entrants targeting Germany and France.
- Sports Nutrition:Established dosage protocols for joint tissue and recovery applications facing substitution pressure from land-based collagen alternatives in price-sensitive formulation budgets.
- Dietary Supplements:Powder and capsule formats distributed through pharmacies and online retail with FDA GRAS self-affirmation pathway access.
- Functional Foods:NMPA and SAMR registration requirements in China create compliance moats for early entrants mastering dual carbon goal alignment.
Nutricosmetics captures premium tier pricing. Sports Nutrition is expanding most quickly through beverage convergence.
End User:
End user segmentation maps to channel control, with beauty and healthcare commanding practitioner gatekeeping while fitness flows through mass retail.
- Beauty:Marine peptide procurement scaled by Japanese and South Korean formulators for skin-health SKUs with molecular weight thresholds specified through dermatology clinic channels.
- Healthcare:Medical nutrition applications requiring pharmaceutical-grade purity thresholds that reconfigure supplier competitiveness through enzymatic processing efficiency.
- Fitness:Gym-channel shelf space competition with ready-to-drink fortification combining collagen with established protein dosage protocols.
- Nutritional:General wellness positioning through supermarkets and online retail with formulation flexibility across powder formats.
Beauty maintains practitioner channel control. Healthcare is climbing the fastest on medical nutrition entry.
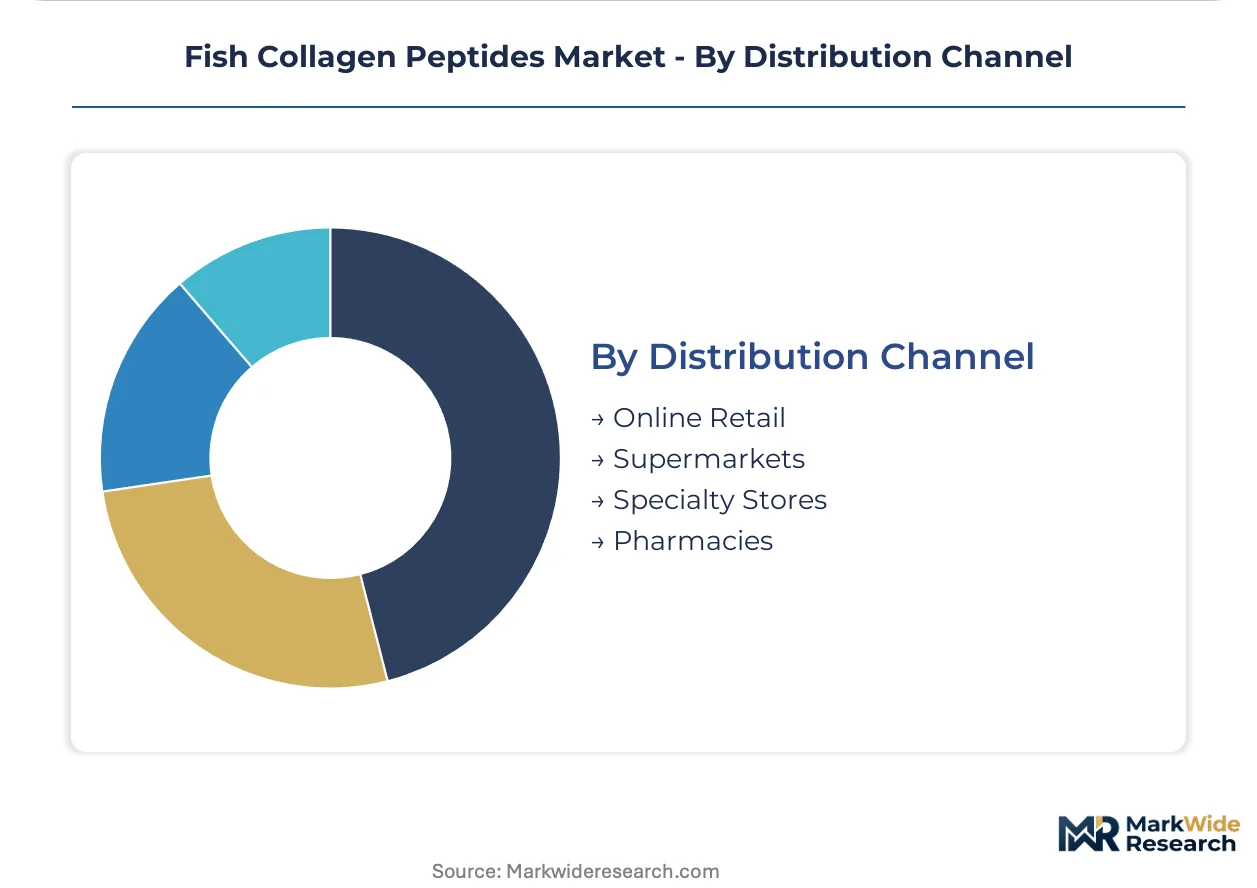
Distribution Channel:
Channel economics separate freshness-advantaged regional production from centralized manufacturing, with specialty stores and pharmacies capturing margin through guidance-intensive purchase decisions.
- Specialty Stores:Korean and Japanese beauty retailers with trained staff delivering peptide regimen guidance on molecular weight thresholds and co-formulation protocols.
- Pharmacies:Healthcare-directed purchasing with regulatory validation requirements varying by jurisdiction—FDA GRAS in the US, EFSA opinions in Europe, FOSHU in Japan.
- Online Retail:Direct-to-consumer scaling with subscription models penetrating mass wellness segments outside practitioner-controlled channels.
- Supermarkets:Mass retail penetration for collagen drinks and powders with price competition from land-based alternatives.
Specialty stores hold premium positioning. Online retail is gaining share fastest through subscription infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese nutricosmetic buyers absorb peptide premiums with minimal price elasticity, while Vietnamese procurement teams negotiate aggressively on pangasius-derived feedstock costs. South Korean formulators balance quality thresholds against landed cost targets. European buyers face extended compliance timelines that compress margin flexibility.
Japan
Beauty-from-within positioning drives marine peptide procurement through dermatology clinic channels where licensed practitioners specify molecular weight thresholds. The Ministry of Health, Labour and Welfare's FOSHU framework creates structured health claim validation for functional food entrants. Tokyo-Osaka corridor formulators dominate nutricosmetic supply chains with co-formulation expertise alongside hyaluronic acid.
South Korea
Ready-to-drink collagen fortification captures gym-channel shelf space with established protein dosage protocols. The Ministry of Food and Drug Safety oversees novel ingredient notifications for marine-sourced peptides entering cosmetic-food hybrid categories. Busan-Ulsan manufacturing clusters deploy compact ceramic membrane skids for sub-3,000 Dalton fractionation serving regional brands.
Vietnam
Pangasius skin and scale collection infrastructure feeds hydrolyzed collagen output with captive raw material flows from Mekong Delta aquaculture operations. The Ministry of Agriculture and Rural Development monitors fishery sustainability certification alignment for export-bound peptide ingredients. Can Tho and An Giang provinces concentrate enzymatic processing facilities leveraging byproduct utilization economics.
United States
Sports nutrition applications face substitution pressure from land-based collagen alternatives in price-sensitive formulation budgets. FDA GRAS self-affirmation pathways demand toxicology investment without guaranteed timeline certainty for novel peptide molecular weight distributions. California and New Jersey house contract manufacturers serving beverage brands with powder and ready-to-drink fortification.
Germany
Pharmaceutical-grade purity thresholds reconfigure supplier competitiveness through enzymatic processing efficiency gains. EFSA novel food opinion requirements extend safety dossier preparation timelines for hydrolyzed collagen entrants targeting powder supplement formulations. Bavaria and North Rhine-Westphalia host ingredient distributors managing multi-jurisdiction compliance for marine-sourced imports.
Fish Collagen Peptides Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where enzymatic hydrolysis specialists compete against scale-driven commodity processors. The vendor base separates into biotechnology-driven platform operators, backward-integrated marine raw material controllers, and regional membrane filtration deployers. Dominant competitive moves include captive supply chain development and regulatory dossier front-loading to compress market access timelines.
Among European-headquartered specialists, Gelita AG and PB Leiner exemplify divergent strategic positioning within marine peptide value chains. Gelita AG represents the backward-integrated archetype with sustainable marine raw material sourcing control. PB Leiner occupies a position emphasizing specialized extraction protocols. Amicogen Co., Ltd. anchors the biotechnology-driven tier with enzymatic hydrolysis platform dominance in South Korean supply chains.
| Leading Market Players |
|---|
| Nitta Gelatin NA Inc |
| ConnOils LLC |
| Gelita AG |
| Amicogen Co., Ltd. |
| Vinh Hoan Corporation |
| Weishardt International |
| PB Leiner |
| Holista Colltech Ltd. |
| Lapi Gelatine S.p.A |
| Others |
Supply Flow & Price Mechanics
Enzymatic hydrolysis capacity utilization above 80 percent in Vietnam's Mekong Delta facilities compresses unit cost floors for pangasius-derived peptides while simultaneously elevating price premiums for pharmaceutical-grade purity thresholds. Scale concentration among backward-integrated processors in Can Tho and An Giang provinces transmits directly into tiered margin capture across nutraceutical and nutricosmetic channels.
Pricing Analysis
FDA GRAS self-affirmation pathways dictate the pricing tier structure across North American peptide procurement, separating validated-ingredient premiums from commodity hydrolyzed powder baselines. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-standard, and feed-economy levels reflects enzymatic efficiency differentials and molecular weight certification depth. Cost compression in standard-grade powders intensifies as Vietnamese pangasius byproduct utilization expands regional supply. Sports nutrition formulators exhibit highest price sensitivity, while Japanese dermatology clinic channels absorb marine peptide premiums with minimal elasticity.
Supply Chain Analysis
Vietnam, South Korea, and Germany anchor fish collagen peptide production through distinct competitive specializations. Vietnam feeds regional hydrolyzed output with captive pangasius skin and scale flows from Mekong Delta aquaculture operations. South Korean Busan-Ulsan clusters deploy compact ceramic membrane skids for sub-3,000 Dalton fractionation. Germany's Bavaria and North Rhine-Westphalia host distributors managing multi-jurisdiction EFSA compliance. Raw material sourcing rests on seasonal cold-water species catch cycles, pangasius aquaculture byproduct economics, and marine sustainability certification alignment. Single-source vulnerability concentrates in Vietnamese pangasius feedstock for economy-tier supply. Distribution runs through specialty beauty retailers, dermatology clinic channels, and direct-to-consumer subscription infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as enzymatic hydrolysis efficiency and membrane filtration miniaturization enable regional production nodes to challenge centralized manufacturing. Interoperability between peptide molecular weight specifications and practitioner-directed regimen protocols creates ecosystem lock-in for medical affairs-capable brands.
For Market Incumbents: Fortify captive supply chain control through backward integration into sustainable marine raw material sourcing and MSC or ASC chain-of-custody credential maintenance. Gelita AG's European nutrichannel positioning demonstrates how procurement standard tightening rewards early sustainability alignment. Capacity addition in Vietnam's Mekong Delta preserves cost competitiveness against land-based collagen substitution threats.
For New Entrants and Emerging Players: Anchor in China's functional food registration pathway where NMPA and SAMR compliance moats protect early entrants mastering dual carbon goal documentation. White-space availability concentrates in medical nutrition applications requiring pharmaceutical-grade purity thresholds that mid-scale facilities struggle to achieve. Go-to-market execution should leverage dermatology clinic channel partnerships with practitioner education infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among biotechnology-driven enzymatic platform operators with South Korean nutricosmetic supply chain dominance. Long-term viability across the projection horizon favors processors with membrane filtration technology deployment capabilities and multi-jurisdiction regulatory dossier expertise. Acquisition target archetype: regional membrane filtration deployers with freshness-advantaged small-batch output capacity. Signal to monitor: EFSA novel food opinion timeline compression efforts among European ingredient suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Platform Expansion | Amicogen Co., Ltd.'s biotechnology-driven dominance in South Korean supply chains demonstrates efficiency capture. |
| Marine Sustainability Certification Integration | MSC and ASC chain-of-custody credentials unlock premium positioning in Nordic and Japanese procurement standards. |
| Membrane Filtration Miniaturization Deployment | Compact ceramic membrane skids enable regional production nodes to serve nutricosmetic brands with freshness advantages. |
| Multi-Jurisdiction Regulatory Dossier Front-Loading | European suppliers compress EFSA novel food opinion timelines through front-loaded toxicokinetic study investment. |
| Dermatology Clinic Channel Partnership Development | Practitioner-directed regimen specification in Korea and Japan concentrates margin capture with medical affairs-capable brands. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with nutricosmetic formulators, enzymatic processing facility managers, marine procurement leads, regulatory affairs specialists at peptide ingredient suppliers, and dermatology clinic practitioners prescribing peptide regimens. Secondary validation drew from FDA GRAS notification databases, EFSA novel food opinion registers, Japan's FOSHU approved product listings, China's NMPA dietary supplement registration records, and customs trade data on marine collagen peptide flows. Bottom-up capacity utilization estimates and top-down demand segmentation were triangulated against disclosed production metrics.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation by product type (hydrolyzed collagen, collagen drinks, powder, capsules), application tier (nutricosmetics, sports nutrition, dietary supplements, functional foods), end-user category (beauty, healthcare, fitness, nutritional), and distribution channel (specialty stores, pharmacies, online retail, supermarkets). CAGRs were derived from installed capacity expansion schedules, regulatory approval timeline assumptions, and channel penetration rate modeling. Industry-specific inputs included pangasius aquaculture byproduct availability projections and enzymatic hydrolysis efficiency improvement curves.
Material uncertainties — marine raw material cost volatility from fuel-linked vessel operating expenses, EFSA novel food opinion timeline extensions, and bovine-porcine collagen substitution pressure in price-sensitive segments — sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory pathway progression and sustainability certification adoption rates. Recalibration cycles align with material shifts in pangasius feedstock economics and enzymatic platform technology maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Medicinal Mushroom Supplement Market
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
Fish Protein Isolate Market
Nutritional Supplements
Coral Calcium Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Fucoidan Market
Nutritional Supplements
Melatonin Supplements Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Digestive Enzyme Complex Market
Nutritional Supplements
Skin-Booster Beverages Market