
 Middle East and Africa Nutricosmetics Market | 2026-2036
Middle East and Africa Nutricosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Nutricosmetics Market Foresight
Pharmacy-led distribution in the Middle East and Africa nutricosmetics sector is narrowing as e-commerce platforms and specialty beauty retailers capture younger demographics seeking personalized regimens. Herbalife International of America Inc leverages its direct-selling infrastructure to sustain recurring purchases across Gulf markets. Beiersdorf AG anchors its position through dermatological credibility transferred from topical skincare into ingestible formats. Amway Corp competes via multi-level networks that penetrate secondary cities beyond Johannesburg and Dubai.
Middle East and Africa nutricosmetics encompass orally administered formulations containing bioactive compounds—collagen peptides, hyaluronic acid, carotenoids, and polyphenols—designed to modulate skin barrier function, hair follicle cycling, and nail keratinization from within. Manufacturing employs microencapsulation and cold-press extraction to preserve thermolabile phytonutrients through gastric transit. Skin Health dominates current value generation due to established consumer literacy around UV-induced photodamage across equatorial and high-altitude African zones. Online Retail captures the fastest trajectory as logistics networks and mobile payment penetration deepen across Kenya, Morocco, and the UAE. Herbal Extracts within the Ingredient Category occupy concentrated margin pools where supply scarcity of saffron-derived crocin and argan oil polyphenols supports premium positioning.
SFDA in Saudi Arabia and MOHAP in the UAE enforce distinct notification pathways for beauty supplements, creating compliance complexity for brands operating across Gulf markets. South Africa's national health regulator applies complementary medicine standards that delay market entry but elevate post-market surveillance rigor. The African Union's nascent harmonization framework for food supplements will reshape registration strategies for entrants targeting pan-African scale. Stakeholders must monitor regulatory divergence between Gulf harmonization initiatives and sub-Saharan national autonomy to optimize portfolio sequencing and local partnership structures.
Market Dynamics
Pharmacy-led distribution in the Middle East and Africa nutricosmetics sector is narrowing as e-commerce platforms and specialty beauty retailers capture younger demographics seeking personalized regimens. Gulf Cooperation Council harmonization of supplement labeling standards is reducing cross-border friction for fortified collagen and antioxidant formulations.
Growth Catalysts
- SFDA notification pathways:Saudi Arabia's streamlined beauty supplement registration is accelerating product launches for collagen peptide formulations targeting urban women.
- Mobile payment penetration:Kenya, Morocco, and the UAE are witnessing logistics network expansion that enables direct-to-consumer delivery of thermolabile phytonutrient products.
- Equatorial UV exposure patterns:Established consumer literacy around photodamage across high-altitude African zones is driving demand for carotenoid-based skin health solutions.
Market Restraints
- Saffron supply scarcity:Crocin extraction from Moroccan and Iranian saffron sources faces concentrated margin pressure due to agricultural yield volatility.
- Regulatory divergence:SFDA and MOHAP maintain distinct notification pathways, creating compliance complexity for brands operating across Saudi Arabia and UAE markets.
- Cold-chain infrastructure gaps:Microencapsulated formulations requiring temperature-controlled transit encounter last-mile limitations in sub-Saharan corridors.
Strategic Opportunities
- Nigeria's Lagos corridor:Pharmacy chain and digital wellness platform co-location creates hybrid distribution white space for ingestible beauty entrants.
- African Union harmonization:The nascent food supplements framework will reshape registration strategies for pan-African scale operations.
- Argan oil polyphenol convergence:Moroccan cosmetic-grade extraction expertise is merging with nutraceutical encapsulation technology for premium positioning.
Industry Challenges
- Complementary medicine standards:South Africa's national health regulator applies rigorous post-market surveillance that delays market entry for novel bioactive compounds.
- Multi-jurisdiction formulation alignment:Brands must reconcile Gulf harmonization initiatives with sub-Saharan national autonomy, complicating portfolio sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Nutricosmetics Market |
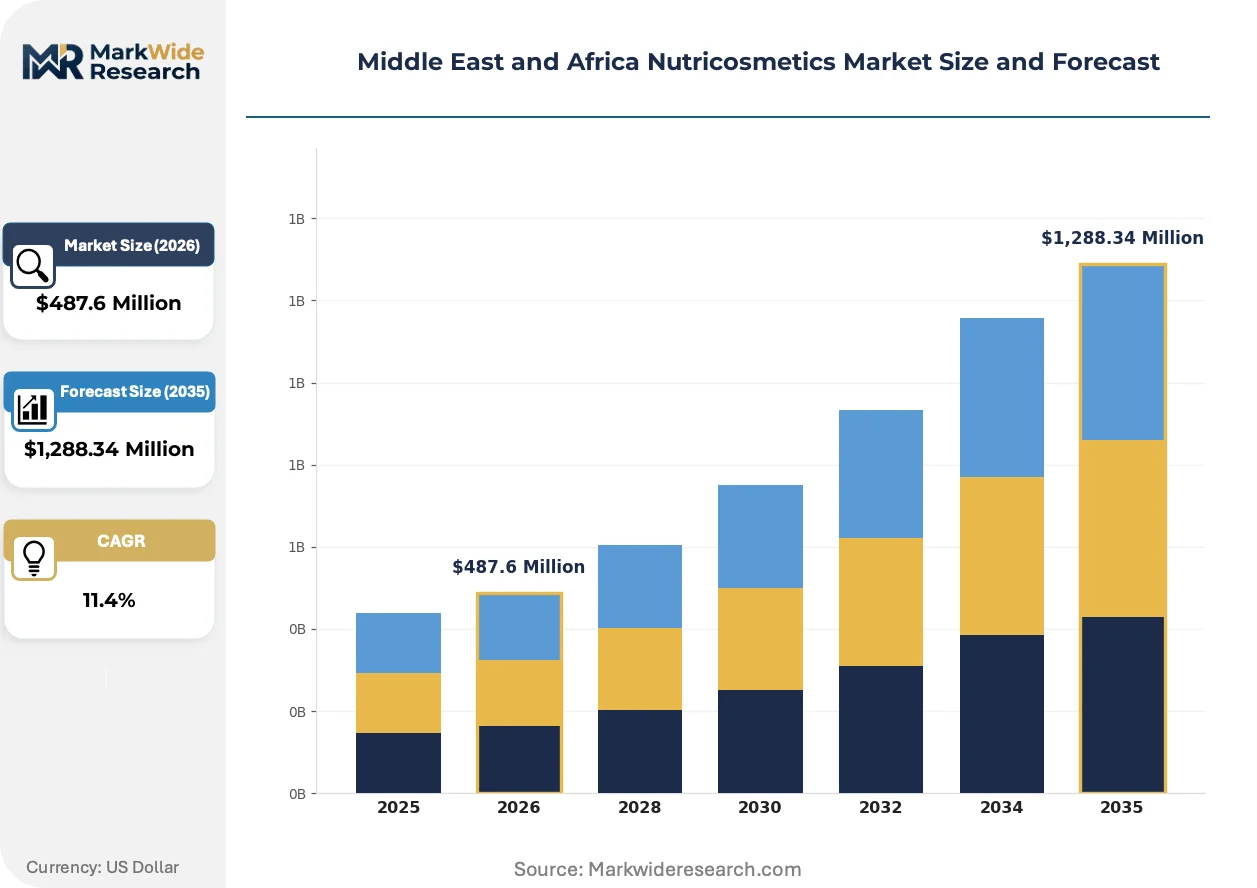
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Health, Hair Care, Nail Care, Anti-Aging Ingredient Category: Vitamins, Minerals, Amino Acids, Herbal Extracts Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies End User: Women, Men, Athletes, Seniors |
| Companies Covered | NATURA &CO, OZNaturals, Herbalife International of America Inc, Corium Skincare, Dose & Co, Beiersdorf AG, H&H Group, Wipro Limited (Canway), Amway Corp, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Nutricosmetics Market Shifts & Advancements
Formulation science and distribution architecture are actively reshaping competitive positioning across Middle East and Africa nutricosmetics. Three developments are compressing traditional go-to-market timelines while elevating technical sophistication requirements.
Microencapsulation technology is migrating from pharmaceutical applications into nutricosmetic manufacturing to preserve thermolabile phytonutrients through gastric transit. Premium skincare brands in Saudi Arabia and South Africa are adopting these delivery systems at accelerated pace. This migration is compressing the performance gap between topical and ingestible beauty claims.
MOHAP in the UAE is enforcing stricter notification pathways for beauty supplements containing hyaluronic acid and collagen peptides. The industrial consequence is elevated documentation requirements for stability testing and bioavailability claims. South African entrants targeting Gulf markets are responding by establishing separate regulatory affairs functions for each jurisdiction.
Urban women in Gauteng province and Lagos are consolidating purchases through subscription-enabled digital wellness platforms rather than intermittent pharmacy visits. Specialty beauty retailers are capturing this behavioral shift via personalized regimen algorithms. Kenya's mobile money infrastructure is making this channel transformation most visible in East African corridors.
Middle East and Africa Nutricosmetics Market Segmentation
Nutricosmetics in the Middle East and Africa demand granular segmentation to capture divergent consumer literacy levels across Gulf and sub-Saharan markets. Product positioning must reconcile premium urban demand in Dubai and Johannesburg with price-sensitive volume opportunities in Lagos and Nairobi corridors.
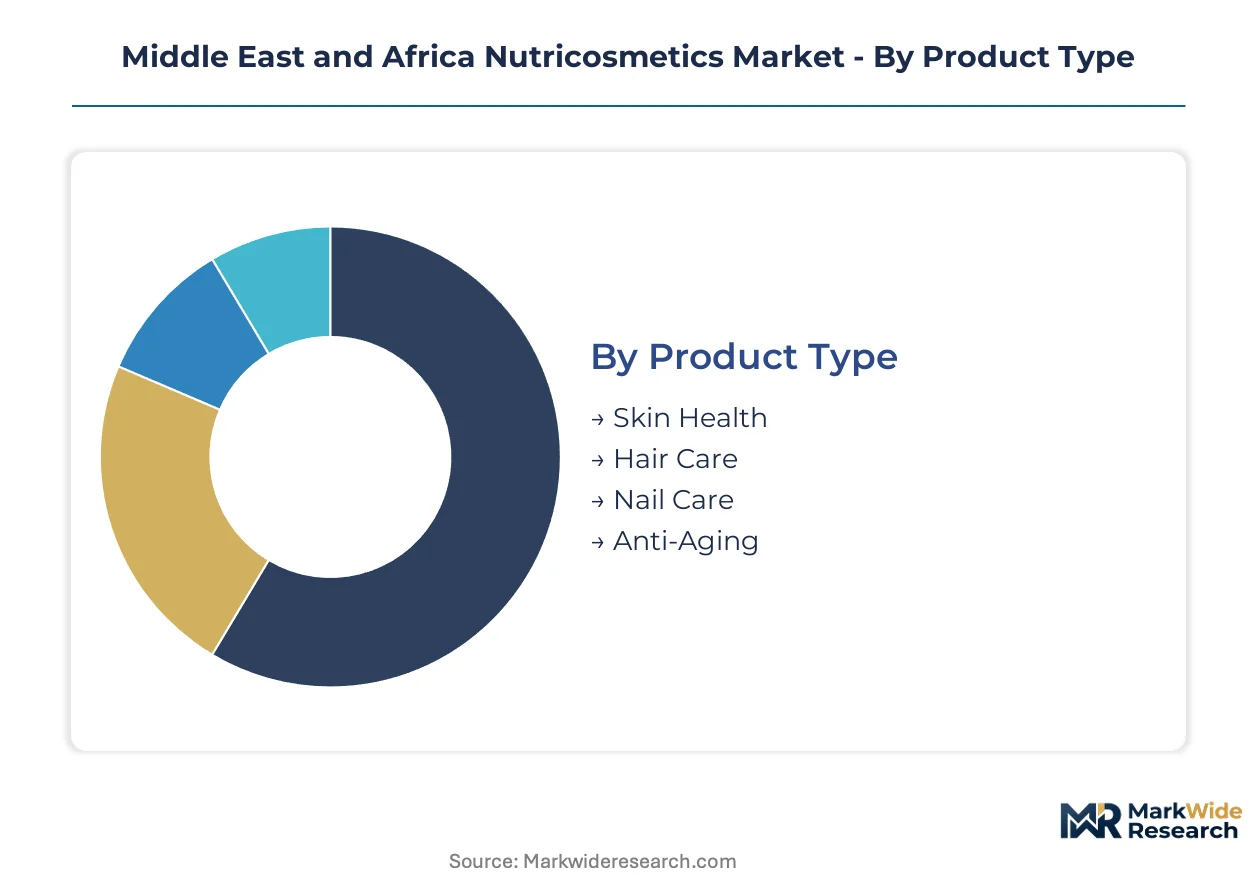
Product Type:
Mature categories dominate current revenue while emerging formats reshape competitive investment priorities.
- Skin Health:Formulations containing collagen peptides, hyaluronic acid, and carotenoids target UV-induced photodamage across equatorial and high-altitude African zones. Saudi Arabia's urban women and South Africa's Gauteng province concentrate demand through pharmacy and digital wellness platform co-location.
- Anti-Aging:Polyphenol-rich ingestibles leverage microencapsulation technology to preserve thermolabile compounds through gastric transit. Morocco's argan oil extraction expertise is merging with nutraceutical encapsulation for premium positioning in Gulf markets.
- Hair Care:Biotin and keratin-support formulations address follicle cycling modulation from within.
- Nail Care:Silicon and mineral complexes target keratinization processes with lower consumer awareness than skin or hair applications.
Skin Health handles the majority of throughput; Anti-Aging is the fastest mover on share.
Ingredient Category:
Cost tier stratification separates commodity inputs from supply-constrained botanicals commanding premium positioning.
- Herbal Extracts:Saffron-derived crocin and argan oil polyphenols face concentrated margin pressure due to agricultural yield volatility in Moroccan and Iranian sourcing regions. Cold-press extraction preserves bioactivity for Gulf market premium positioning.
- Vitamins:Carotenoid-based solutions for photodamage protection dominate volume consumption across high-altitude African zones with established consumer literacy.
- Collagen Peptides:Fortified formulations benefit from GCC harmonization of supplement labeling standards reducing cross-border friction.
- Minerals:Zinc and selenium complexes support skin barrier function with standardized manufacturing protocols.
- Amino Acids:Building-block formulations for keratin and collagen synthesis occupy mid-tier pricing.
Herbal Extracts command the highest margin tier; Vitamins move the largest absolute volume.
Distribution Channel:
Customer type evolution is compressing traditional pharmacy dominance while specialty and digital channels accelerate.
- Online Retail:Subscription-enabled digital wellness platforms capture younger demographics seeking personalized regimens. Kenya's mobile money infrastructure and UAE logistics network expansion enable direct-to-consumer delivery of temperature-sensitive formulations.
- Pharmacies:Traditional pharmacy-led distribution narrows as e-commerce penetrates urban clusters, though South Africa's rigorous complementary medicine standards sustain channel credibility.
- Specialty Stores:Beauty retailers deploy regimen algorithms for personalized nutricosmetic curation in Saudi Arabia and South Africa.
- Supermarkets:Mass-market penetration remains limited by consumer education gaps outside premium urban corridors.
Pharmacies retain the largest installed base; Online Retail is expanding most quickly on share.
End User:
Application focus varies sharply by demographic segment, with gender and lifestyle markers driving formulation specificity.
- Women:Premium skincare routines among urban demographics in Saudi Arabia and South Africa anchor current value generation across skin health and anti-aging categories.
- Athletes:Performance-oriented formulations targeting recovery and oxidative stress modulation represent an emerging specification segment.
- Men:Hair care and skin health formulations gain traction through digital wellness platform marketing.
- Seniors:Joint-skin convergence products with collagen and mineral complexes address aging-related concerns with nascent market development.
Women constitute the core revenue base; Athletes are climbing the fastest on segment share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA in Saudi Arabia anchors regulatory harmonization across Gulf Cooperation Council markets, streamlining beauty supplement registration pathways while sub-Saharan jurisdictions maintain autonomous oversight frameworks. Demand clusters concentrate in Riyadh, Dubai, Johannesburg, and Lagos corridors where pharmacy chains and digital wellness platforms co-locate. National regulators enforce divergent notification standards that reshape market entry sequencing for collagen peptide and antioxidant formulations.
Saudi Arabia
Urban women in Riyadh and Jeddah drive premium skincare routines through pharmacy-led and digital wellness platform channels. SFDA notification pathways for beauty supplements have accelerated product launches for collagen peptide formulations targeting photodamage concerns. The Eastern Province industrial corridor hosts manufacturing facilities serving Gulf markets with microencapsulated thermolabile phytonutrient products.
United Arab Emirates
Dubai's logistics networks and mobile payment infrastructure enable direct-to-consumer delivery of temperature-sensitive nutricosmetic formulations. MOHAP enforces distinct notification pathways for hyaluronic acid and collagen peptide supplements, elevating documentation requirements for stability testing. Specialty beauty retailers in Abu Dhabi and Dubai deploy personalized regimen algorithms for urban consumer segments.
South Africa
Gauteng province concentrates demand through pharmacy chain and digital wellness platform co-location serving premium urban demographics. The national health regulator applies complementary medicine standards that delay market entry but elevate post-market surveillance rigor for novel bioactive compounds. Cape Town and Johannesburg anchor distribution infrastructure for pan-African supply reach.
Nigeria
Lagos corridor pharmacy chains and emerging digital wellness platforms create hybrid distribution white space for ingestible beauty entrants. The national food and drug regulator maintains autonomous standards outside harmonization frameworks, complicating cross-border portfolio sequencing. Kano and Port Harcourt secondary cities represent nascent demand expansion zones.
Morocco
Argan oil polyphenol extraction expertise in Agadir and Marrakech regions merges with nutraceutical encapsulation technology for premium Gulf market positioning. Agricultural yield volatility for saffron-derived crocin concentrates margin pressure among herbal extract suppliers. Casablanca logistics hubs facilitate cold-chain transit for microencapsulated formulations.
Middle East and Africa Nutricosmetics Market Competitive Landscape
Dermatological credibility players and direct-selling network operators split the Middle East and Africa nutricosmetics market across distinct distribution architectures. Market structure exhibits moderate consolidation with multinational skincare houses anchoring premium positioning while multi-level marketing networks penetrate secondary cities beyond primary metros. Three archetypes dominate: science-backed topical-to-ingestible extenders, relationship-driven direct sellers, and mobile-first digital wellness platforms. Competitive intensity concentrates on regulatory compliance capabilities across SFDA and MOHAP jurisdictions and cold-chain infrastructure investments for thermolabile formulations.
Within the dermatological credibility tier, Beiersdorf AG exemplifies topical skincare heritage transferred into ingestible formats through stability-tested collagen and hyaluronic acid delivery systems. Herbalife International of America Inc and Amway Corp occupy the direct-selling network archetype, leveraging recurring purchase infrastructure and multi-level penetration into secondary cities beyond Johannesburg and Dubai. These three entities represent divergent go-to-market philosophies—clinical authority versus relationship commerce—each commanding distinct consumer trust mechanisms across Gulf and sub-Saharan corridors.
| Leading Market Players |
|---|
| NATURA &CO |
| OZNaturals |
| Herbalife International of America Inc |
| Corium Skincare |
| Dose & Co |
| Beiersdorf AG |
| H&H Group |
| Wipro Limited (Canway) |
| Amway Corp |
| Others |
Supply & Pricing Matrix
Overcapacity in Moroccan saffron extraction facilities is compressing crocin supplier margins while simultaneously enabling Gulf-facing brands to negotiate favorable long-term offtake terms for premium nutricosmetic positioning.
Pricing Analysis
Dubai-Riyadh-Johannesburg price spreads of 40-60% separate premium collagen peptide formulations from economy-tier vitamin complexes. Three-tier pricing structure across premium, standard, and economy levels reflects brand heritage, cold-chain certification, and subscription bundling intensity. Pricing pressure stems from Kenyan mobile-money platforms democratizing access and eroding pharmacy markups. Price-sensitive volume buyers in Lagos corridors contrast with least-sensitive premium seekers in Riyadh's Eastern Province.
Supply Chain Analysis
Agricultural yield volatility between Moroccan saffron fields and Iranian crocin sources dominates supply-side risk exposure for herbal extract-dependent formulations. Manufacturing concentrates in Saudi Arabia's Eastern Province, South Africa's Gauteng corridor, and UAE free zones serving as Gulf distribution hubs. Raw material dependencies include Moroccan argan oil polyphenols, hydrolyzed collagen from Brazilian bovine sources, and microencapsulation polymers from German specialty chemical suppliers. Single-source vulnerability concentrates in saffron-derived actives. Distribution runs through pharmacy chain networks in Saudi Arabia and South Africa, with direct-to-consumer platforms accelerating in Kenya and Nigeria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation technology maturation and GCC regulatory harmonization are compressing traditional go-to-market timelines, creating first-mover advantages for brands that synchronize formulation science with mobile-first distribution infrastructure.
For Market Incumbents: Insulate recurring revenue streams by deepening direct-selling infrastructure in secondary Saudi and South African cities beyond Riyadh and Johannesburg. Secure backward integration into Moroccan argan oil extraction to defend margin position against saffron supply volatility. Prioritize SFDA and MOHAP dual-registration capabilities to preempt regulatory fragmentation costs. For New Entrants and Emerging Players: Establish a beachhead in Nigeria's Lagos corridor hybrid pharmacy-digital wellness platform whitespace before incumbent direct-sellers consolidate position. Target Kenya's mobile-money-enabled subscription segment for lowest customer acquisition friction. Lead with thermolabile phytonutrient formulations differentiated through cold-chain delivery guarantees. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-selling network operators with established Gulf penetration and herbal extract supply agreements. Five-to-ten year viability favors entities combining dermatological credibility with mobile-platform subscription infrastructure. Watch for African Union food supplements harmonization framework ratification as acquisition timing signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Enables thermolabile phytonutrient delivery across sub-Saharan logistics gaps. |
| Dual-Jurisdiction Regulatory Registration | SFDA and MOHAP parallel approvals reduce Gulf market entry friction. |
| Herbal Extract Supply Agreement | Moroccan saffron and argan oil offtake contracts secure premium positioning. |
| Mobile-Platform Subscription Launch | Kenya's M-Pesa integration captures recurring purchases from digital-native demographics. |
| Microencapsulation Technology Licensing | Pharmaceutical-grade delivery systems transfer into ingestible beauty formulations. |
Research Methodology
Desk research of customs trade records, SFDA and MOHAP regulatory filings, and GCC supplement labeling standards preceded structured interviews with nutricosmetic brand managers, pharmacy chain procurement directors, cold-chain logistics operators, and mobile payment platform executives. Bottom-up volume estimates triangulated against top-down consumer expenditure data across Saudi Arabia, UAE, South Africa, Nigeria, Kenya, and Morocco.
Assumptions held fixed include current GCC regulatory harmonization trajectory and mobile payment penetration rates in East Africa, while saffron agricultural yields and African Union framework ratification timelines were modeled as scenario variables. Segmentation dimensions spanned product type, ingredient category, distribution channel, and end-user demographic across the projection horizon. CAGRs derived from historical growth rate analysis adjusted for channel shift acceleration and regulatory entry barrier changes. Forecast inputs incorporated pharmacy channel share erosion rates and subscription platform adoption curves.
Sensitivities concentrate around saffron supply shocks, African Union harmonization delays, and cold-chain infrastructure investment gaps in sub-Saharan corridors. Forecasts reflect documented assumptions subject to revision from regulatory divergence or technological substitution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Oncology Nutrition Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Aquatic Feed Supplement Market
Nutritional Supplements
Conjugated Linoleic Acid Market
Nutritional Supplements
Vitamin B12 Market
Nutritional Supplements
Europe Moringa Supplement Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Spirulina Purple Blend Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
Nicotine Gum Market
Nutritional Supplements
Vitamin K2 Market
Nutritional Supplements
Bone Broth Protein Market
Nutritional Supplements
South America Omega-3 Products Market
Nutritional Supplements
Ketogenic Diet Food Market
Nutritional Supplements
Marine Collagen Market