
 Fucoidan Market | 2026-2036
Fucoidan Market Size, Share, and Industry Trends Forecast 2026-2036
Fucoidan Market Analysis
Pharmaceutical formulators is redrawing procurement priorities for high-purity fucoidan extracts. Marinova Pty Ltd leverages its Tasmanian cold-water extraction infrastructure to supply clinical-grade material to European drug developers. Kanehide Bio Co., Ltd. anchors its competitive position through decades of kombu-specific sourcing relationships in Hokkaido. Merck KGaA competes by integrating fucoidan into its broader carbohydrate chemistry portfolio for life science research channels.
Fucoidan constitutes a sulfated polysaccharide extracted primarily from brown seaweed cell walls, with molecular weights typically ranging from 10 to 1,000 kDa depending on extraction method and species source. Its commercial purpose centers on bioactive applications leveraging anticoagulant, antiviral, and immunomodulatory properties. Powder formulations dominate pharmaceutical procurement due to stability and dosing precision, while liquid extracts sustain growth in functional food and beverage integration. Cosmetics applications represent a maturing segment where margin pools concentrate in premium dermal care lines.
Japan's PMDA enforces biopolymer purity benchmarks that elevate manufacturing compliance costs for export-oriented suppliers. The FDA maintains Investigational New Drug documentation requirements for fucoidan entering US clinical trials, creating a two-tier access structure. REACH registration obligations in Europe further shape which Asian extractors can serve formulated product manufacturers. Stakeholders must monitor regulatory divergence between pharmaceutical-grade and nutraceutical-grade certification pathways.
Market Dynamics
Pharmaceutical-grade fucoidan procurement is concentrating around cold-water extraction infrastructure capable of meeting Japan's PMDA biopolymer purity benchmarks, filtering out temperate-zone suppliers lacking sub-5°C processing capability.
Growth Catalysts
- Oncology Adjuvant Trials:Formulators are expanding clinical-grade procurement for combination therapy protocols targeting solid tumors. The FDA's Investigational New Drug pathway is channeling capital toward extractors with documented batch consistency.
- Japan's PMDA Standards:Stringent sulfated polysaccharide purity requirements are creating competitive moats for Hokkaido-based kombu processors with multi-decade sourcing relationships.
- Brown Seaweed Cell Wall Processing:Advances in enzymatic extraction are yielding higher molecular weight fractions preferred for immunomodulatory applications.
Market Restraints
- Wild Harvest Volatility:Laminaria japonica biomass fluctuates with Oyashio Current temperature anomalies, compressing raw material availability in Hokkaido coastal zones.
- REACH Registration Burden:European chemical registration obligations block smaller Asian extractors from serving formulated product manufacturers in Germany and France.
- Synthetic Heparin Substitution:Recombinant anticoagulant production is displacing fucoidan in standard prophylactic applications where molecular precision outweighs natural sourcing appeal.
Strategic Opportunities
- Functional Beverage Integration:Liquid extract formats are penetrating Japanese and South Korean ready-to-drink wellness categories previously dominated by collagen and hyaluronic acid.
- EU Green Deal Biopolymer Incentives:Sustainable sourcing certifications are unlocking preferential procurement terms for Tasmanian cold-water extractors serving Nordic nutraceutical brands.
- Dermal Care Premiumization:Cosmetic formulators in France and Switzerland are specifying high-fucoidan-content serums for anti-inflammatory positioning in prestige skincare lines.
Industry Challenges
- Pharmaceutical-Grade Certification Timelines:FDA and EMA documentation requirements extend qualification cycles to 18-24 months, straining extractor cash conversion.
- Specialized Extraction Talent Scarcity:Marine biochemistry expertise for sulfated polysaccharide fractionation concentrates in Japanese and Australian research clusters, limiting facility replication elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fucoidan Market |
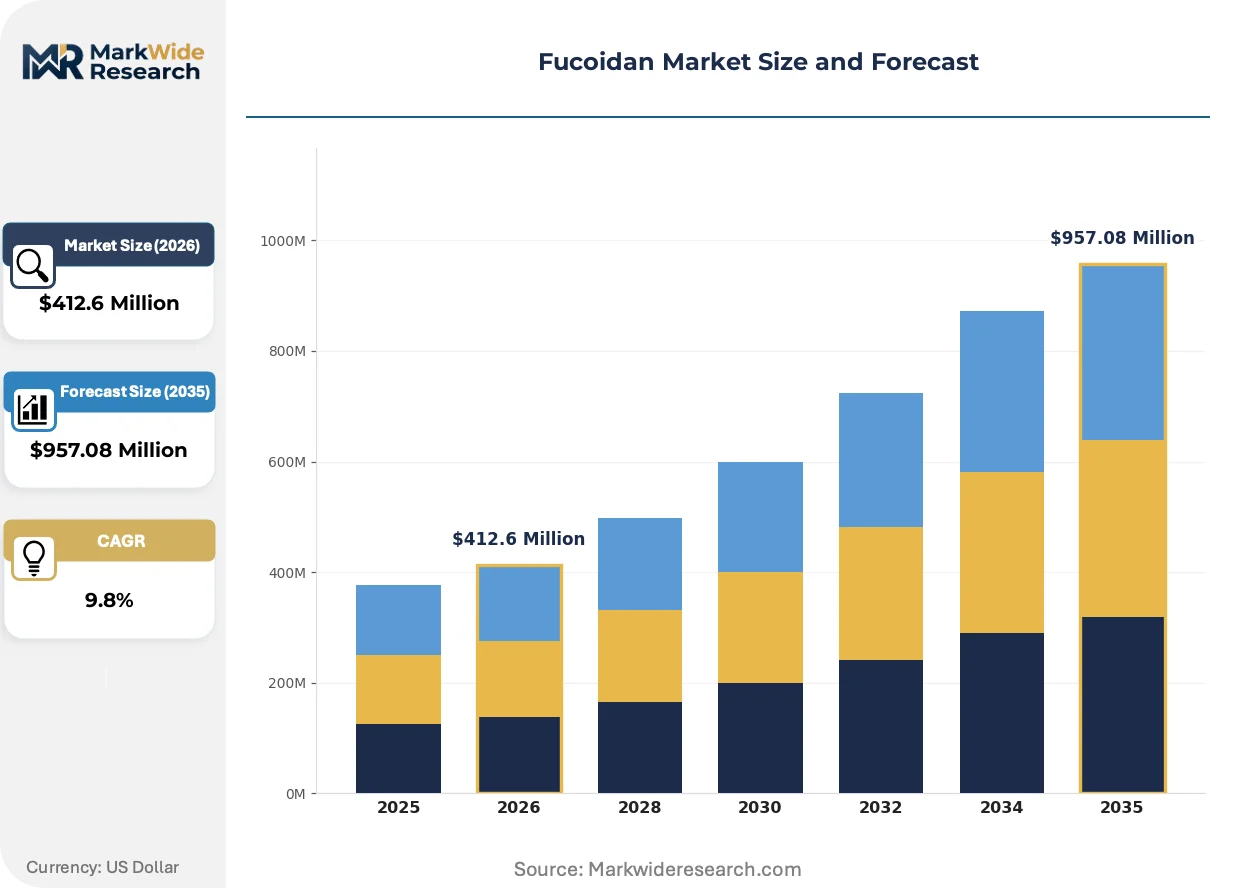
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $957.08 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Tablet Source: Brown Seaweed, Kelp, Kombu, Fucus Vesiculosus Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Cosmetics End User: Healthcare, Food Industry, Personal Care, Research |
| Companies Covered | Marinova Pty Ltd, Kanehide Bio Co., Ltd., Maruha Nichiro, Merck KGaA, Hi-Q Marine Biotech International Ltd., Biosynth, Qingdao Seawin Biotech, Yaizu Suisankagaku, Kamerycah, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fucoidan Market Emerging Trajectories
Enzymatic and subcritical water extraction methods are displacing traditional acid hydrolysis, altering yield profiles and molecular weight distributions across supplier tiers.
Subcritical water extraction is decomposing long-chain fucoidan polymers into targeted 50-300 kDa fractions optimized for bioavailability. European drug developers are adopting these narrow-distribution materials for pharmacokinetic studies. The technology is decomposing price premiums previously commanded by Japanese suppliers with legacy cold-water infrastructure.
REACH registration deadlines for imported biopolymers are compressing supplier lists to extractors with dedicated European regulatory affairs capacity. German and French formulators are consolidating procurement around pre-registered Tasmanian and Norwegian sources. Nutraceutical-grade certification pathways are diverging from pharmaceutical-grade documentation requirements, creating dual-track compliance architectures.
Direct procurement from extraction facilities is displacing layered distributor networks for clinical-grade material. Large pharmaceutical formulators in the United States and Germany are establishing qualification relationships with primary processors. This channel consolidation is most visible in oncology adjuvant supply chains where batch traceability requirements exceed distributor capabilities.
Fucoidan Market Segmentation
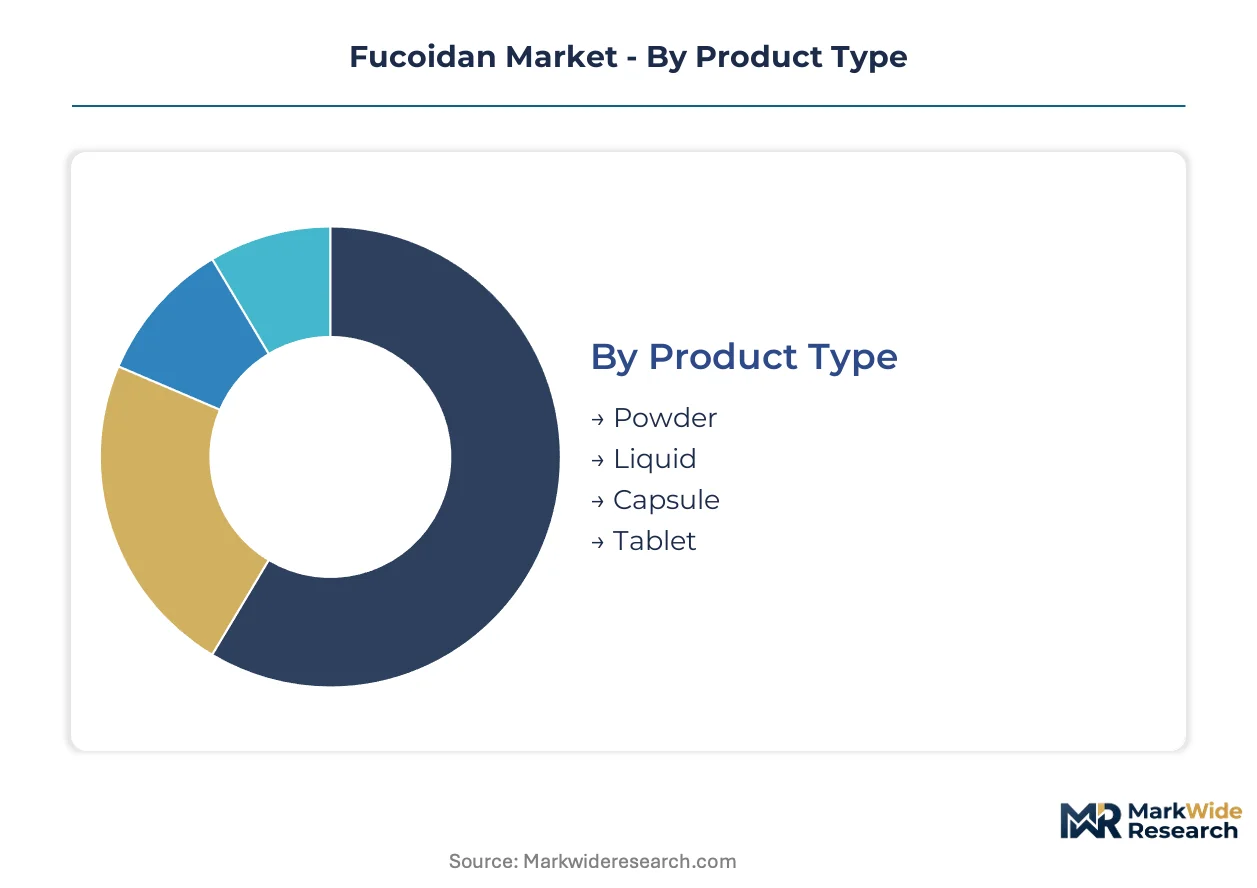
Fucoidan procurement patterns diverge sharply across product formats and purity grades. Pharmaceutical formulators demand batch-traceable powder with documented molecular weight distributions, while functional food developers prioritize liquid extracts for beverage integration.
Product Type:
Premium margin pools concentrate in pharmaceutical-grade powder where cold-water extraction infrastructure creates supply scarcity.
- Powder:Dominates oncology adjuvant procurement due to stability under GMP storage conditions and precise dosing capability. FDA Investigational New Drug documentation requirements favor powder suppliers with validated batch consistency protocols in Hokkaido and Tasmania.
- Liquid:Penetrating South Korean and Japanese ready-to-drink wellness categories. Enzymatic extraction advances are narrowing molecular weight distributions for improved bioavailability in functional beverage applications.
- Capsule:Serves nutraceutical channels requiring convenience positioning with lower purity thresholds than pharmaceutical specifications.
- Tablet:Compressed formats suit mass-market dietary supplement retail in North American and European pharmacy chains.
Powder holds installed capacity. Liquid is rotating up the share rankings.
Source:
Raw material provenance determines sulfated polysaccharide yield and regulatory compliance trajectory.
- Brown Seaweed:Laminaria species from Hokkaido coastal zones supply the highest fucoidan content per biomass unit. Oyashio Current temperature anomalies compress harvest volumes, elevating spot pricing volatility for extractors.
- Kelp:Tasmanian Macrocystis pyrifera supports Marinova's cold-water extraction infrastructure serving European REACH-registered supply chains.
- Kombu:Decades-specific sourcing relationships in northern Japan anchor Kanehide Bio's competitive position for PMDA-compliant material.
- Fucus Vesiculosus:Atlantic-sourced material competes in cosmetics applications where molecular weight requirements are less stringent than pharmaceutical grades.
Kombu commands heritage pricing. Brown seaweed is climbing fastest on volume.
Application:
End-use certification requirements split the market into pharmaceutical-grade and nutraceutical-grade procurement channels.
- Dietary Supplements:Capsule and tablet formats dominate mass-market channels with self-affirmed GRAS status in the United States.
- Functional Foods:Liquid extracts integrate into South Korean beauty-from-within beverages and Japanese fermented dairy products.
- Pharmaceuticals:Clinical-grade material for oncology adjuvant trials requires FDA IND pathway documentation and EMA-compatible stability data.
- Cosmetics:Premium dermal care lines in France and Switzerland specify high-content serums for anti-inflammatory positioning.
Pharmaceuticals holds validation infrastructure. Functional foods is expanding most quickly.
End User:
Customer sophistication determines specification stringency and contract duration.
- Healthcare:Hospital procurement committees and specialty pharmacy networks demand pharmaceutical-grade documentation with batch-level traceability.
- Food Industry:Beverage formulators in Japan and South Korea prioritize liquid extract solubility and clean-label positioning.
- Personal Care:Cosmetic manufacturers specify molecular weight ranges for dermal penetration claims in prestige skincare.
- Research:Academic and contract research organizations drive demand for characterized reference materials with published structural data.
Healthcare anchors long-term contracts. Personal care is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese extractors ship clinical-grade fucoidan to German pharmaceutical formulators under REACH-registered supply chains. Cold-water infrastructure in Tasmania and Hokkaido anchors export capacity to European and North American buyers.
Japan
Oncology adjuvant trials and kombu-specific sourcing relationships drive pharmaceutical-grade procurement. The PMDA enforces sulfated polysaccharide purity benchmarks that elevate compliance costs for export-oriented suppliers. Hokkaido coastal zones concentrate brown seaweed harvesting infrastructure where Kanehide Bio maintains multi-decade processor relationships.
Germany
Drug developers source characterized reference materials for pharmacokinetic studies and carbohydrate chemistry research. REACH registration obligations filter supplier lists to pre-registered Tasmanian and Norwegian extractors. Frankfurt and Munich host formulated product manufacturers consolidating procurement around batch-traceable clinical-grade material.
United States
Specialty pharmacy networks and hospital procurement committees demand FDA Investigational New Drug documentation for oncology applications. The FDA maintains strict batch consistency protocols that channel capital toward extractors with validated stability data. Boston and San Diego biotech clusters anchor clinical trial demand for immunomodulatory fractions.
Australia
Tasmanian cold-water extraction infrastructure supplies European REACH-registered nutraceutical brands under EU Green Deal biopolymer incentives. Macrocystis pyrifera kelp harvesting supports Marinova's export capacity to Nordic functional food developers. Hobart processing facilities concentrate enzymatic extraction expertise for narrow molecular weight distribution materials.
South Korea
Ready-to-drink wellness beverage formulators integrate liquid fucoidan extracts for beauty-from-within positioning. The MFDS regulates functional food ingredient safety standards that shape clean-label procurement priorities. Seoul and Busan anchor demand for solubility-optimized extracts in fermented dairy and beverage applications.
Fucoidan Market Vendor Landscape
Listed leaders compete with private specialists across extraction infrastructure and regulatory certification dimensions. The vendor base stratifies between cold-water extraction specialists with PMDA compliance capabilities and temperate-zone suppliers serving nutraceutical-grade channels. Three archetypes dominate: Hokkaido-based kombu processors with heritage sourcing relationships, Tasmanian kelp extractors with REACH-registered European supply chains, and diversified carbohydrate chemistry portfolios serving research channels. Capacity expansion and strategic partnerships represent the dominant competitive moves as formulators consolidate direct procurement relationships.
Among Asia-Pacific extractors, Marinova Pty Ltd and Kanehide Bio Co., Ltd. exemplify the geographic specialization archetype, while Merck KGaA occupies a position representing diversified life science research supply. These three companies illustrate how competitive positioning depends on matching extraction infrastructure to the regulatory requirements of target buyer geographies.
| Leading Market Players |
|---|
| Marinova Pty Ltd |
| Kanehide Bio Co., Ltd. |
| Maruha Nichiro |
| Merck KGaA |
| Hi-Q Marine Biotech International Ltd. |
| Biosynth |
| Qingdao Seawin Biotech |
| Yaizu Suisankagaku |
| Kamerycah |
| Others |
Supply Flow & Price Mechanics
Enzymatic extraction technology is displacing acid hydrolysis as the dominant processing method, simultaneously shifting supply geography toward Australian and Norwegian facilities with subcritical water infrastructure and compressing price premiums previously commanded by Japanese cold-water specialists. This substitution dynamic redraws procurement economics as European formulators consolidate around REACH-registered Tasmanian sources while tempering historical reliance on Hokkaido-based kombu processors.
Pricing Analysis
Subcritical water extraction equipment commands a generation-gap premium over legacy acid hydrolysis installations, while next-generation enzymatic fractionation systems carry additional capital recovery markups. Pricing stratifies across pharmaceutical-grade, nutraceutical-grade, and research-grade certification tiers, with FDA IND pathway documentation and PMDA compliance benchmarks driving substantial differentiation. Cost compression in standard-grade material is intensifying as temperate-zone suppliers expand enzymatic capacity. Hospital procurement committees exhibit lowest price sensitivity due to batch traceability requirements, while functional beverage formulators demonstrate highest elasticity as clean-label positioning competes with collagen and hyaluronic acid alternatives.
Supply Chain Analysis
The Tsugaru Strait transit corridor between Hokkaido and Honshu underpins raw material flows for Japan's kombu processing cluster, creating seasonal chokepoint exposure during winter storm patterns. Concentrated supply rests on Australia, Japan, and Norway as the primary extraction geographies, with brown seaweed biomass, enzymatic processing reagents, and cold-water infrastructure constituting critical input dependencies. Single-source vulnerability concentrates in Hokkaido's Laminaria japonica harvest zones where Oyashio Current temperature anomalies compress availability. Distribution runs through direct procurement relationships with primary processors, displacing layered distributor networks for clinical-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fucoidan applications sit at an early-cycle expansion phase where oncology adjuvant trial advancement and functional beverage integration represent underpenetrated vectors with substantial runway ahead.
For Market Incumbents: Secure multi-year sourcing contracts with Hokkaido kombu harvesters before enzymatic extraction technology erodes geographic moats. Invest in PMDA and FDA dual-certification infrastructure to defend pharmaceutical-grade positioning against Tasmanian cold-water competitors. Capacity addition in enzymatic fractionation represents the critical lever for maintaining margin structure as acid hydrolysis becomes commoditized. For New Entrants and Emerging Players: Anchor in South Korean ready-to-drink wellness beverage channels where solubility-optimized liquid extracts face limited incumbent competition. Target functional food applications as the most penetrable segment given lower purity thresholds than pharmaceutical pathways. A go-to-market angle emphasizing EU Green Deal biopolymer certification unlocks preferential procurement terms with Nordic nutraceutical brands. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors extractors with enzymatic processing capabilities and established REACH registration. Long-term viability over the next decade hinges on backward integration into brown seaweed cultivation to tame wild harvest volatility. Watch enzymatic extraction yield improvements as the signal indicating when price premiums for cold-water material will collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Scale-Up | Subcritical water infrastructure in Tasmania and Norway is displacing Japanese cold-water capacity for European pharmaceutical procurement. |
| REACH Registration Completion | Pre-registered biopolymer status filters supplier lists for German and French formulators consolidating clinical-grade procurement. |
| Backward Integration into Cultivation | Captive brown seaweed supply in Hokkaido and Tasmanian waters reduces Oyashio Current volatility exposure for extractors. |
| FDA IND Pathway Documentation | Validated batch consistency protocols channel oncology adjuvant procurement toward qualified powder suppliers. |
| Functional Beverage Partnership | Liquid extract solubility specifications align with South Korean MFDS clean-label priorities for beauty-from-within positioning. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with extraction facility technical directors, pharmaceutical formulator procurement leads, and regulatory affairs specialists; and secondary validation through PMDA biopolymer purity filings, FDA IND documentation databases, ECHA REACH registration records, and customs trade flow data. Bottom-up triangulation across extraction capacity estimates and top-down demand modeling from end-use application forecasts ensured convergence.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation by product format, source species, application grade, and end-user sophistication. CAGRs were derived from elasticity-adjusted adoption curves for pharmaceutical versus nutraceutical channels. Forecast inputs incorporated enzymatic extraction yield improvements, PMDA compliance cost trajectories, and functional beverage penetration rates in South Korean and Japanese markets.
Decision-makers should treat outputs as directional under assumptions of stable regulatory divergence between pharmaceutical and nutraceutical certification pathways; material deviation in FDA or EMA documentation requirements would warrant model refresh. Practitioners should keep alternative scenarios live as synthetic heparin substitution rates and EU Green Deal biopolymer incentive structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Human Milk Oligosaccharides (HMO) Market
Nutritional Supplements
Diet Shakes Market
Nutritional Supplements
North America Memory Supplements Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Human Nutrition Market
Nutritional Supplements
Global Nutraceutical Ingredients Market
Nutritional Supplements
Fatty Acid Supplements Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Europe Dietary Supplements Market