
 Microalgae DHA Market | 2026-2036
Microalgae DHA Market Size, Share, and Industry Trends Forecast 2026-2036
Microalgae DHA Market Outlook
Direct procurement partnerships between microalgae DHA suppliers and finished goods manufacturers is reconfiguring traditional ingredient distribution. DSM Nutritional Products leverages backward integration into Schizochytrium strain development to secure proprietary supply. Corbion N.V. sustains commercial fermentation scale through multi-site manufacturing across Europe and North America. Xiamen Huison Biotech Co. Ltd. anchors regional volume by controlling domestic distribution channels in China.
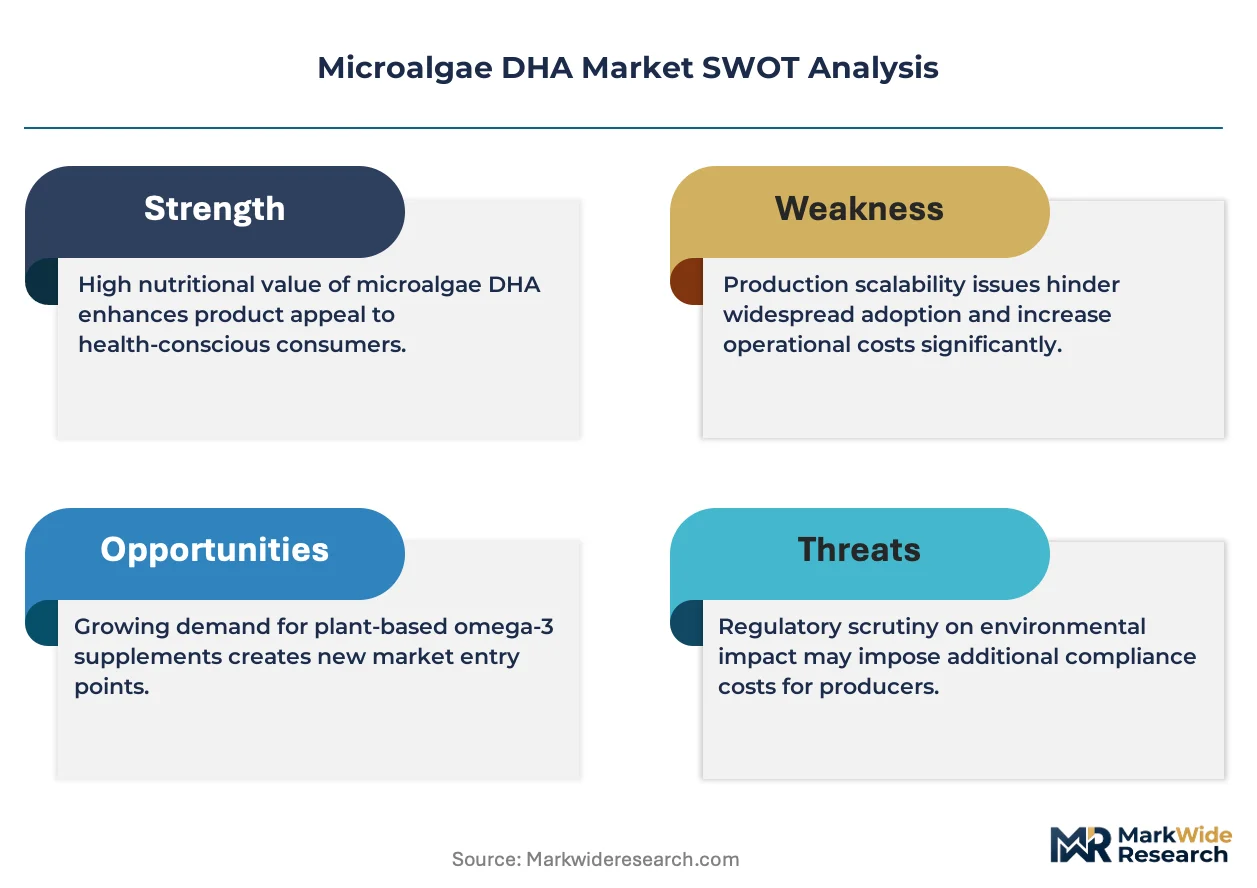
Microalgae DHA denotes omega-3 docosahexaenoic acid extracted from photosynthetic or heterotrophic microalgae, typically achieving concentrations of 35-55% DHA by weight in refined oil form through cold-pressing or supercritical CO2 extraction. The compound serves primarily as a bioactive lipid for cognitive and visual development in infant nutrition, cardiovascular health formulations, and aquaculture feed enrichment. DHA oil dominates current revenue contribution due to its flexibility across softgel encapsulation and liquid fortification, while DHA powders are expanding fastest as dry-blend applications in infant formula and sports nutrition multiply. The dietary supplements application commands mature margin pools in North American and European retail channels, whereas aquaculture feed represents an emerging volume frontier with distinct pricing dynamics.
FDA GRAS notifications and EFSA novel food opinions govern ingredient approval pathways in the United States and European Union respectively, with China's NMPA and national food safety standards administered by SAMR controlling market access for imported and domestically produced microalgae DHA. Regulatory divergence across these jurisdictions forces suppliers to maintain parallel dossier strategies and region-specific purity specifications. Stakeholders must monitor evolving EPA and EFSA limits on marine pollutant carryover, as algae-derived alternatives face intensifying scrutiny despite their theoretically cleaner origin profile.
Market Dynamics
Direct procurement partnerships between microalgae DHA suppliers and finished goods manufacturers is reconfiguring traditional ingredient distribution. DSM Nutritional Products leverages backward integration into Schizochytrium strain development to secure proprietary supply. Corbion N.V. sustains commercial fermentation scale through multi-site manufacturing across Europe and North America. Xiamen Huison Biotech Co. Ltd. anchors regional volume by controlling domestic distribution channels in China.
Growth Catalysts
- EU Novel Food Pathways:The European Commission's streamlined approval processes for algae-derived ingredients accelerates market entry for new suppliers seeking regulatory clearance.
- Aquaculture Feed Enrichment:Salmon and shrimp farming operations in Norway and Chile are substituting microalgae DHA for fish oil to meet sustainability certification requirements.
- Heterotrophic Fermentation:Closed-tank cultivation systems achieve higher cell densities than open-pond methods, compressing production cycles and improving batch consistency.
Market Restraints
- Carbohydrate Feedstock Volatility:Glucose and corn syrup prices fluctuate with agricultural commodity markets, directly impacting fermentation input costs.
- Strain IP Concentration:Proprietary Schizochytrium and Crypthecodinium strains remain controlled by a limited number of research institutions and commercial licensors.
- Fish Oil Price Competition:Anchovy and sardine oil from Peruvian and Chilean fisheries maintains cost advantages in bulk feed applications.
Strategic Opportunities
- Indian Nutraceutical Penetration:FSSAI regulatory harmonization and rising middle-class supplement consumption create entry points for imported algae DHA.
- Sports Nutrition Powders:Dry-blend protein and pre-workout formulations represent an underexploited application channel beyond infant formula.
- EU Green Deal Incentives:Circular bioeconomy funding and carbon accounting rules favor marine-algae alternatives over wild-caught fish derivatives.
Industry Challenges
- Phycologist Talent Scarcity:Industrial microbiology programs produce insufficient specialists in microalgae strain optimization and metabolic engineering.
- Parallel Dossier Burden:Suppliers must maintain separate FDA GRAS notifications, EFSA novel food opinions, and NMPA registration files simultaneously.
- Downstream Processing Bottlenecks:Supercritical CO2 extraction capacity constraints limit the conversion of raw algal biomass into refined oil at commercial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microalgae DHA Market |
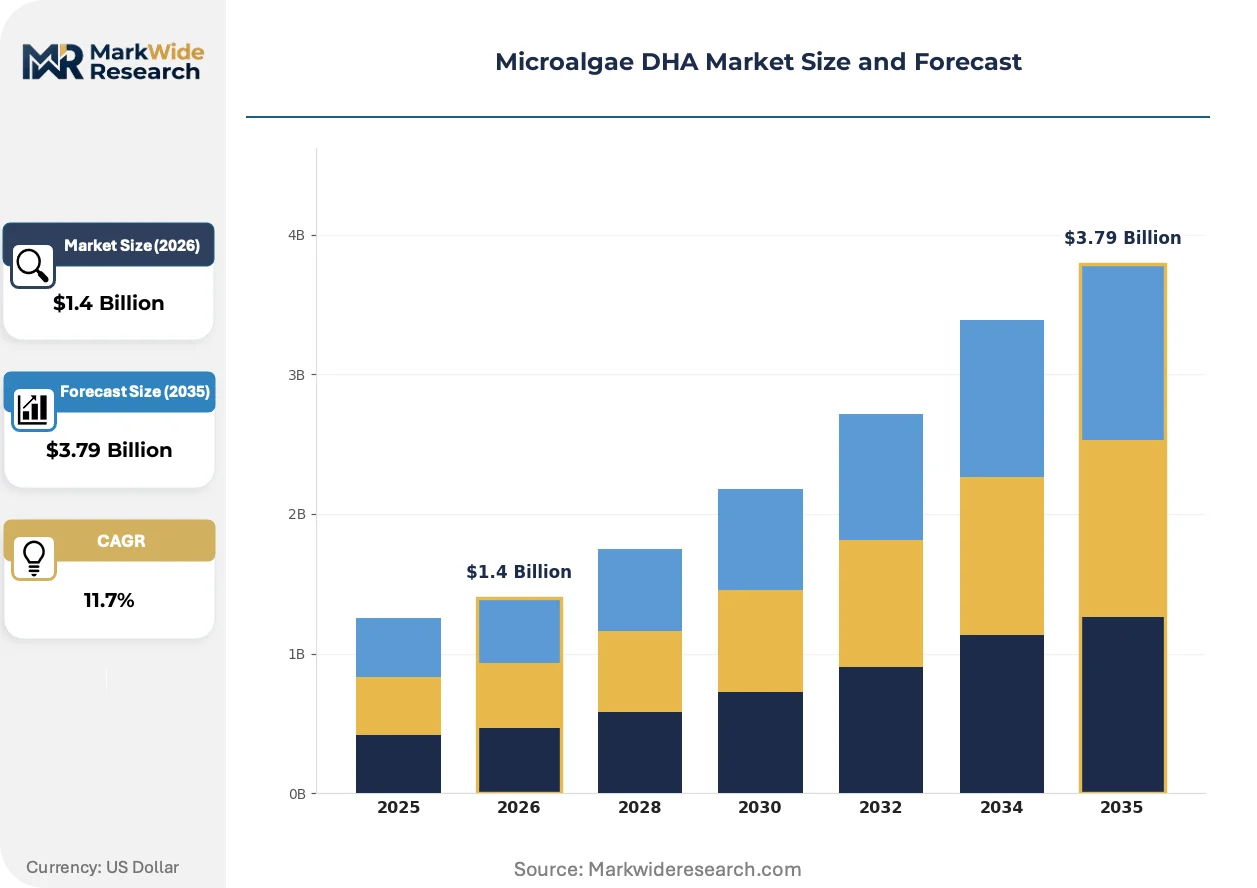
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DHA Oil, DHA Powders, DHA Capsules, DHA Functional Foods Application: Nutraceuticals, Food & Beverages, Dietary Supplements, Animal Feed End User: Healthcare Sector, Food Industry, Pharmaceutical Companies, Aquaculture Form: Liquid, Powder, Emulsion, Freeze-dried |
| Companies Covered | Corbion N.V., DSM Nutritional Products, Lonza Group AG, Archer Daniels Midland (ADM), BASF, Xiamen Huison Biotech Co. Ltd., Roquette Freres, Cellana Inc., Polaris Nutritional Lipids, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microalgae DHA Market Strategic Shifts
Continuous fermentation monitoring and automated harvesting systems are compressing the gap between laboratory strain performance and industrial yield realization. These advances are reshaping how producers balance capital intensity against operational flexibility.
Single-use bioreactor technology is collapsing the capital barrier for mid-scale DHA production. Contract manufacturers in Germany and the Netherlands are adopting disposable cultivation vessels for campaign-based manufacturing. This shift enables smaller players to enter the market without committing to stainless-steel infrastructure.
China's NMPA has tightened contaminant specifications for imported algae-derived lipids, aligning with SAMR's domestic food safety enforcement. This regulatory convergence forces exporters to upgrade purification protocols. European suppliers are responding by investing in ceramic membrane filtration and molecular distillation upgrades.
Formula brands in China are consolidating supplier relationships around vertically integrated producers with captive fermentation capacity. Long-term offtake agreements are displacing spot-market purchasing for infant nutrition applications. This concentration is most pronounced in Shanghai and Guangdong province, where domestic brands compete for secure DHA supply chains.
Microalgae DHA Market Segmentation
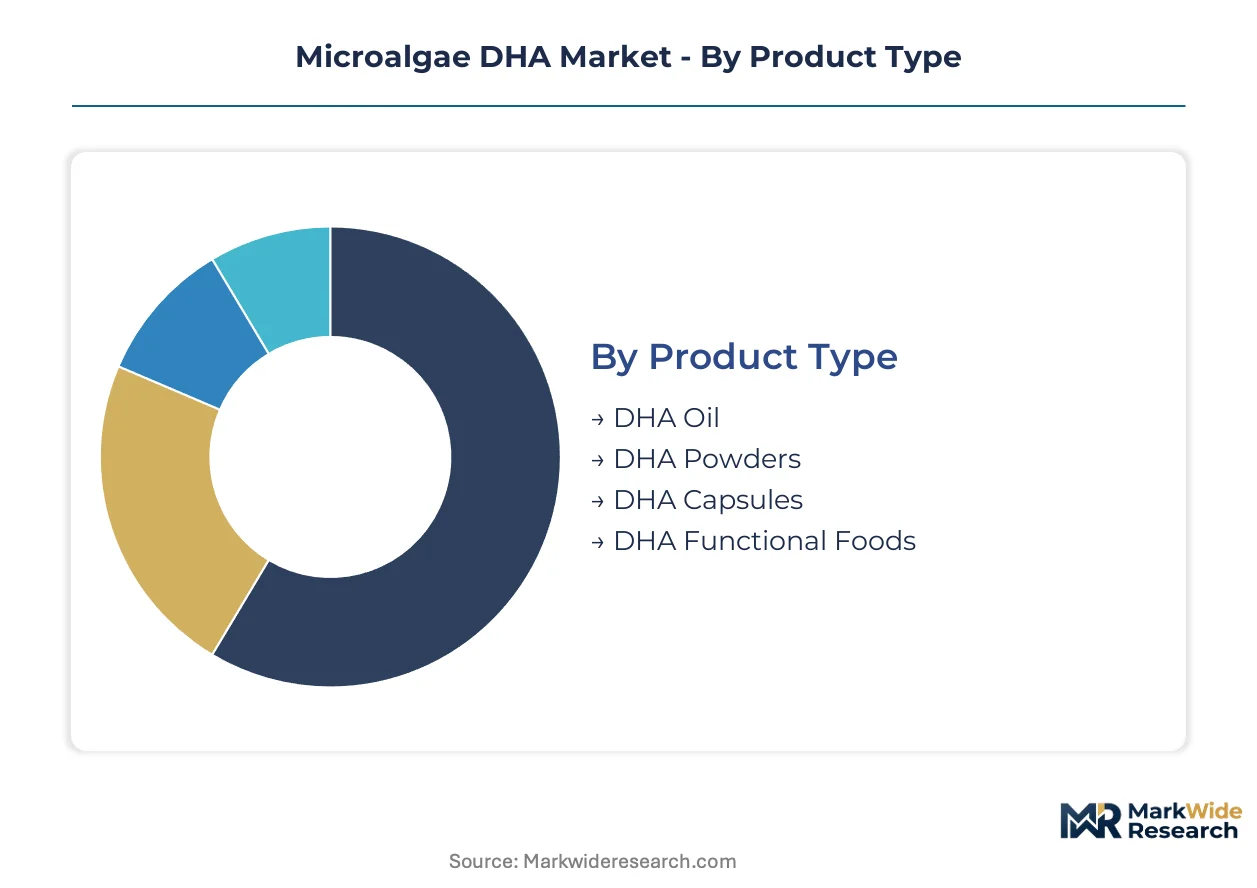
Microalgae DHA suppliers configure production assets around distinct technical specifications and end-use requirements. Segmentation reveals where formulation complexity commands premium positioning versus commodity volume plays.
Product Type:
DHA Oil turns inventory fastest through softgel encapsulation lines, while DHA Functional Foods lock capital into extended development cycles and retail shelf negotiations.
- DHA Oil:Refined lipid concentrate standardized to 35-55% DHA by weight through supercritical CO2 extraction. Infant formula manufacturers in China and Germany anchor demand for bulk oil in liquid fortification systems. Cold-pressing alternatives serve organic-certified product lines at lower throughput rates.
- DHA Powders:Microencapsulated or spray-dried formats enabling dry-blend incorporation into protein matrices and powdered beverages. Sports nutrition brands in the United States are expanding powder offtake for pre-workout formulations, displacing oil-based delivery in convenience-focused segments.
- DHA Capsules:Pre-dosed softgel units for retail supplement channels. Standardized potency reduces quality control burden for contract packagers.
- DHA Functional Foods:Fortified dairy alternatives, baked goods, and ready-to-drink beverages requiring emulsion stability and flavor masking. Extended regulatory clearance timelines in the European Union constrain rollout velocity.
DHA Oil dominates installed base. DHA Powders is where expansion concentrates.
Application:
Margin structure varies sharply across these channels, with pharmaceutical-grade specifications commanding three-to-four-fold premiums over feed-grade volumes.
- Nutraceuticals:Cognitive health and cardiovascular positioning in premium supplement portfolios. EFSA health claim substantiation requirements in Europe drive clinical trial investment for positioning against generic fish oil alternatives.
- Dietary Supplements:Mass-market softgel and gummy formats distributed through pharmacy and e-commerce channels. Amazon's supplement marketplace in the United States has compressed brand loyalty, accelerating private-label substitution.
- Food & Beverages:Beverage fortification and dairy alternative enrichment requiring oxidative stability and neutral flavor profiles. Clean-label positioning in German and Dutch retail chains favors algae-derived over fish-based sourcing declarations.
- Animal Feed:Salmon and shrimp aquaculture operations in Norway and Chile substituting microalgae DHA for fish oil to meet ASC and BAP sustainability certifications. Pricing indexed to anchovy oil futures with quality premiums for contaminant-free profiles.
Dietary Supplements anchors revenue contribution. Animal Feed is gaining share fastest.
End User:
Procurement sophistication separates these segments, with pharmaceutical buyers imposing batch-level traceability that aquaculture operators rarely require.
- Healthcare Sector:Hospital formulary inclusion and clinical nutrition protocols. DSM Nutritional Products maintains dedicated account teams for neonatal intensive care unit supply chains.
- Pharmaceutical Companies:Active pharmaceutical ingredient qualification for prescription omega-3 therapies. FDA drug master file requirements extend qualification timelines beyond food-grade pathways.
- Food Industry:CPG manufacturers integrating DHA into mainstream packaged goods. Cost engineering favors powder formats for high-speed filling lines.
- Aquaculture:Integrated salmon farming operations specifying DHA inclusion rates for fillet fatty acid profiles. Long-term offtake agreements with fermentation suppliers displace spot purchasing.
Healthcare Sector commands specification leadership. Aquaculture is where volume scales.
Form:
Processing intensity and shelf stability requirements differentiate these formats, with emulsion systems demanding continuous manufacturing investment.
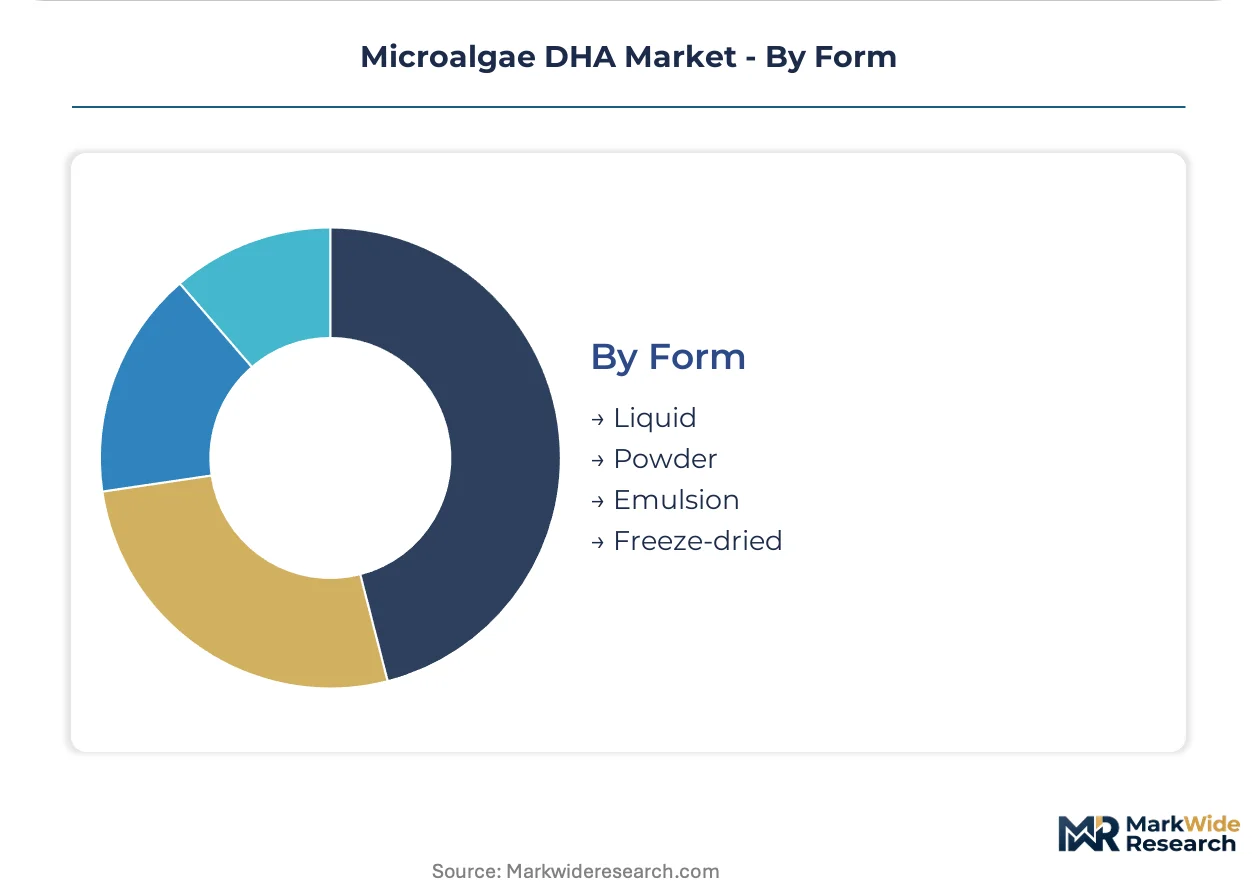
- Liquid:Bulk oil and concentrated suspensions for industrial fortification. Corbion N.V. operates dedicated liquid filling capacity for North American beverage customers.
- Powder:Spray-dried and microencapsulated variants for dry-blend applications. Infant formula producers in Shanghai specify powder purity grades exceeding general food standards.
- Emulsion:Oil-in-water dispersions for beverage and dairy alternative integration. Homogenization equipment requirements limit supplier pool.
- Freeze-dried:Biomass preservation for specialized nutraceutical and research applications. Premium pricing reflects low throughput and high energy input.
Liquid holds production capacity majority. Powder is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal incentives and China's dual carbon goals are redirecting fermentation capacity toward algae-derived lipids. National regulators in major economies are tightening contaminant limits on marine-sourced omega-3 alternatives.
China
Infant formula manufacturers in Shanghai and Guangdong province are consolidating supplier relationships around vertically integrated producers with captive fermentation capacity. NMPA contaminant specifications for imported algae-derived lipids now align with SAMR's domestic food safety enforcement. Xiamen Huison Biotech anchors regional volume by controlling domestic distribution channels.
Germany
Contract manufacturers in Germany are adopting single-use bioreactor technology for campaign-based DHA production. EFSA novel food opinions govern ingredient approval pathways for algae-derived entrants. DSM Nutritional Products operates dedicated account teams for neonatal intensive care unit supply chains across German hospital networks.
United States
Sports nutrition brands are expanding powder offtake for pre-workout formulations, displacing oil-based delivery in convenience-focused segments. FDA GRAS notifications govern market access for new algae-derived ingredients. Corbion N.V. sustains commercial fermentation scale through multi-site manufacturing including North American capacity.
Norway
Salmon farming operations are substituting microalgae DHA for fish oil to meet ASC and BAP sustainability certifications. The country's aquaculture feed pricing indexes to anchovy oil futures with quality premiums for contaminant-free profiles. Integrated farming operations in coastal regions specify DHA inclusion rates for fillet fatty acid profiles.
India
Rising middle-class supplement consumption is creating entry points for imported algae DHA. FSSAI regulatory harmonization is streamlining novel food approvals for fermentation-derived lipids. Nutraceutical distributors in Mumbai and Delhi are establishing direct procurement partnerships with East Asian suppliers.
Microalgae DHA Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated fermentation specialists and multi-site contract manufacturers. Three archetypes dominate: strain developers with proprietary Schizochytrium libraries, toll manufacturers operating single-use bioreactor capacity, and regional distributors controlling domestic channel access. Competitive moves center on backward integration into captive biomass production and long-term offtake agreements that displace spot-market purchasing.
Among Dutch and Swiss nutrition specialists, DSM Nutritional Products and Lonza Group AG exemplify the premium-tier archetype built on pharmaceutical-grade qualification pathways. Xiamen Huison Biotech Co. Ltd. represents the regional-integrator model, while Corbion N.V. occupies a position spanning both European and North American manufacturing footprints. These three anchors illustrate how geographic coverage and regulatory dossier depth separate scalable suppliers from campaign-based competitors.
| Leading Market Players |
|---|
| Corbion N.V. |
| DSM Nutritional Products |
| Lonza Group AG |
| Archer Daniels Midland (ADM) |
| BASF |
| Xiamen Huison Biotech Co. Ltd. |
| Roquette Freres |
| Cellana Inc. |
| Polaris Nutritional Lipids |
| Others |
Value Chain & Pricing Dynamics
Fermentation capacity concentration in China and the Netherlands concentrates upstream supply leverage, directing margin pools toward finished goods manufacturers with long-term offtake agreements in infant formula and aquaculture feed. Carbohydrate feedstock costs transmit directly into DHA oil pricing, while extraction technology tiers separate pharmaceutical-grade premiums from commodity feed-grade volumes.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels governs transactional dynamics. Quality grade and certification tier—FDA GRAS versus EFSA novel food versus NMPA registration—drive price differentiation. Pricing pressure stems from fish oil cost competition in bulk aquaculture applications. Aquaculture operators exhibit highest price sensitivity; neonatal nutrition buyers accept substantial premiums for contaminant-free certification.
Supply Chain Analysis
Tariff exposure between China and major import markets dominates supply chain risk assessment. Manufacturing concentrates in China, the Netherlands, and Germany. Glucose feedstock, Schizochytrium inoculum, and supercritical CO2 extraction equipment constitute critical input dependencies. Single-source vulnerability persists in proprietary strain licensing. Distribution runs through direct procurement partnerships that displace traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical services and regulatory dossier maintenance represent the fastest-expanding recurring-revenue layer, outpacing raw DHA oil sales as infant formula manufacturers outsource compliance burden. Strain optimization consulting and custom formulation development attach to base ingredient contracts with expanding margins.
For Market Incumbents: Insulate proprietary Schizochytrium libraries through patent portfolio enforcement and exclusive research institution partnerships. Add captive fermentation capacity in North America to reduce tariff exposure. EFSA novel food opinion maintenance and NMPA registration renewal constitute critical defensive investments against emerging toll manufacturers with single-use bioreactor capacity. For New Entrants and Emerging Players: Sports nutrition powder applications in the United States represent the most penetrable entry point, with dry-blend protein formulations lacking established algae-DHA suppliers. India's FSSAI-harmonized nutraceutical channel offers secondary white-space with lower competitive density. Go-to-market execution should emphasize direct procurement partnerships with contract manufacturers rather than distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated fermentation specialists with captive strain development and multi-regional regulatory dossiers. Five-to-ten year viability hinges on aquaculture feed volume scaling and pharmaceutical-grade qualification pathways. The signal to watch is consolidation in Chinese infant formula supply chains toward single-source relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Expansion | Parallel FDA GRAS and EFSA novel food filings unlock premium pharmaceutical-grade pricing tiers. |
| Backward Integration into Strain Development | Proprietary Schizochytrium libraries secure supply continuity and differentiate against toll manufacturers. |
| Single-Use Bioreactor Adoption | Disposable cultivation vessels reduce capital barriers for campaign-based manufacturing in European contract facilities. |
| Long-Term Offtake Agreements | Infant formula manufacturers in Shanghai consolidate supplier relationships around secure volume commitments. |
| Aquaculture Feed Certification | ASC and BAP sustainability credentials command quality premiums over fish oil in Norwegian salmon farming. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across fermentation specialists, infant formula procurement managers, aquaculture feed formulators, and regulatory affairs directors. Secondary validation drew from FDA GRAS notifications, EFSA novel food opinions, NMPA registration filings, and customs trade data. Bottom-up volume modeling triangulated against top-down market sizing from industry association disclosures.
Calibration against historical capacity announcements and actual production ramp timelines anchored the analytical framework. Segmentation dimensions spanned product form, application tier, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from slope analysis across the projection horizon, incorporating heterotrophic fermentation yield improvements and extraction capacity expansion schedules as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices and marine oil futures would shift the trajectory. Forecasts reflect assumptions around regulatory approval timelines and strain performance at commercial scale. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Older Adults Health Supplements Market
Nutritional Supplements
Diet Pills Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Vitamin D Supplements Market
Nutritional Supplements
Liuweidihuang Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
Europe Dietary Supplements Market
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
Astragalus Propinquus Market
Nutritional Supplements
Fucoidan Market
Nutritional Supplements
Middle East Protein Market
Nutritional Supplements
Nutrition Powder Market
Nutritional Supplements
Algae Omega Market
Nutritional Supplements
Global Collagen Peptides Market