
 Nutritional Supplements Market | 2026-2036
Nutritional Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Nutritional Supplements Market Intelligence
E-commerce distribution is fragmenting as direct-to-consumer platforms and specialized wellness marketplaces multiply. Amway Corp. leverages its established direct-selling infrastructure to maintain customer relationships outside conventional retail. Glanbia PLC anchors its position through dairy-derived protein specialization and ingredient supply contracts. NOW Foods competes on manufacturing scale, operating vertically integrated production facilities that control quality from raw material to finished good.
Nutritional supplements encompass biologically active compounds including vitamins, minerals, botanical extracts, and protein isolates formulated in dosages intended to augment dietary intake, with specifications typically measured in Recommended Dietary Allowance percentages or gram-per-serving protein content. These products serve industrial purposes spanning preventive health maintenance, athletic performance optimization, and clinical nutritional support. Vitamin formulations command established margin pools due to decades of consumer familiarity and regulatory precedent, while protein powder segments attract formulation investment as sports nutrition applications broaden. Gummy formats represent the fastest-growing delivery system as palatability concerns reshape senior and general consumer adherence patterns.
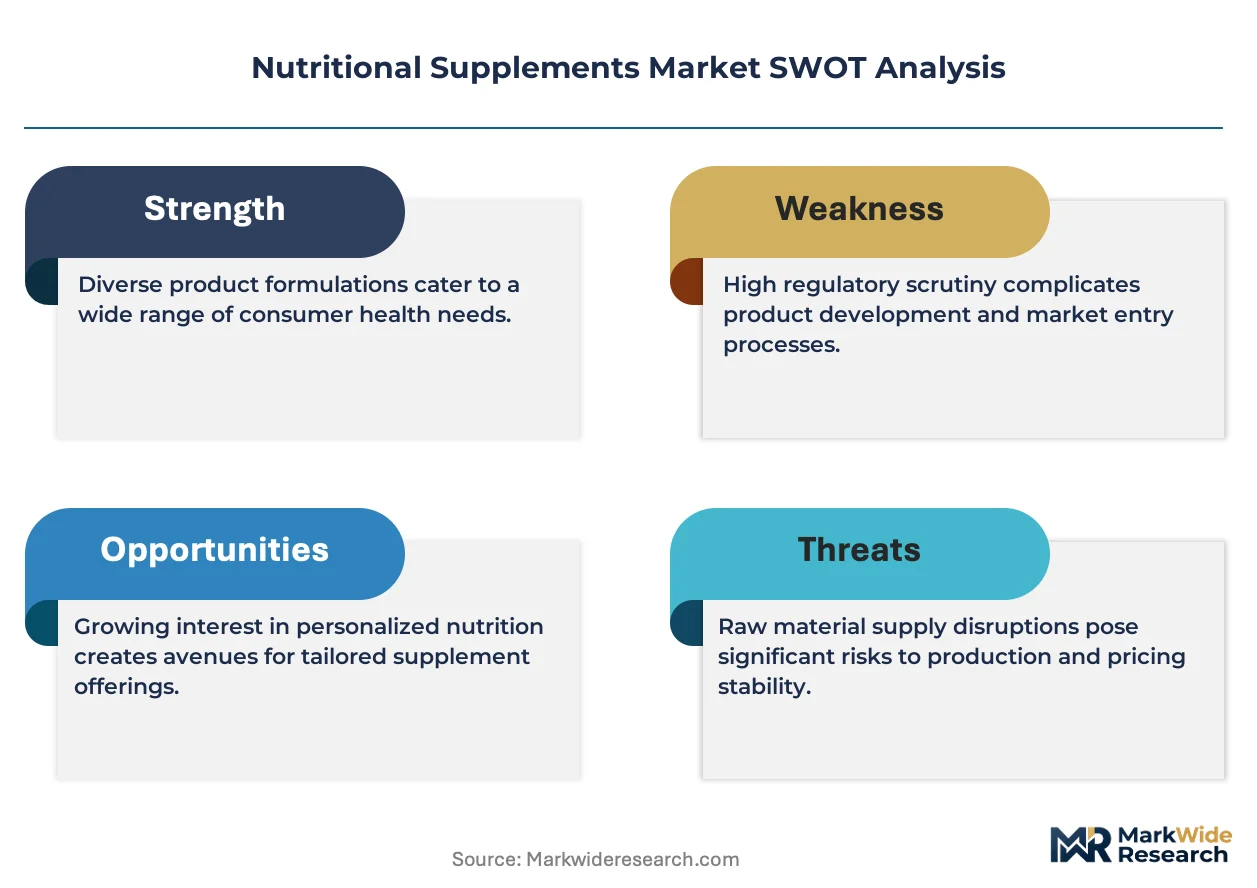
FDA oversight through Current Good Manufacturing Practice regulations and NDI notifications constrains ingredient innovation timelines in the United States, while EFSA health claim assessments shape permissible marketing language across European jurisdictions. ISO 17025 laboratory accreditation requirements increasingly determine which contract manufacturers qualify for brand partnerships. Stakeholders must monitor evolving substantiation standards for structure-function claims as litigation risk and regulatory scrutiny intensify across major markets.
Market Dynamics
E-commerce fragmentation is collapsing traditional retail gatekeeper power in nutritional supplements, as direct-to-consumer platforms and specialized wellness marketplaces multiply access points and compress margin capture by intermediaries.
Growth Catalysts
- FDA New Dietary Ingredient notifications:The NDI pathway, while constraining, creates first-mover advantages for firms that successfully navigate pre-market safety substantiation. Early filers secure ingredient exclusivity windows.
- Protein powder specialization:Dairy-derived and plant-based protein isolates attract formulation investment as sports nutrition applications broaden beyond bodybuilding into endurance and lifestyle fitness segments.
- Gummy format adoption:Palatability-driven delivery system innovation is reshaping senior and general consumer adherence patterns, expanding addressable populations beyond capsule-tolerant users.
Market Restraints
- Whey protein input volatility:Dairy commodity price swings transmit directly to sports nutrition margin structures, compressing EBITDA for brands without backward integration into milk processing.
- Contract manufacturer concentration:ISO 17025-accredited production capacity clusters in the United States and Germany, creating bottleneck risk for brands seeking quality-certified partners.
- Structure-function claim litigation exposure:Intensifying FTC and state attorney general scrutiny constrains marketing language flexibility, raising compliance costs and recall risk.
Strategic Opportunities
- Preventive health program integration:European public health systems are incorporating vitamin D and omega-3 protocols into standard care pathways, creating institutional procurement channels.
- Personalized nutrition convergence:At-home microbiome testing and AI-driven recommendation engines are converging with supplement subscription models to lock in recurring revenue.
- Clean label certification premiums:NSF Certified for Sport and Informed Sport third-party verification commands shelf price premiums in collegiate and professional athletic procurement.
Industry Challenges
- Phytochemical standardization expertise scarcity:Botanical extract potency verification requires analytical chemistry capabilities that outstrip current talent pipeline output, delaying product launches.
- Legacy ERP integration friction:Direct-to-consumer brands acquiring manufacturing assets face system harmonization costs that erode anticipated synergy capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutritional Supplements Market |
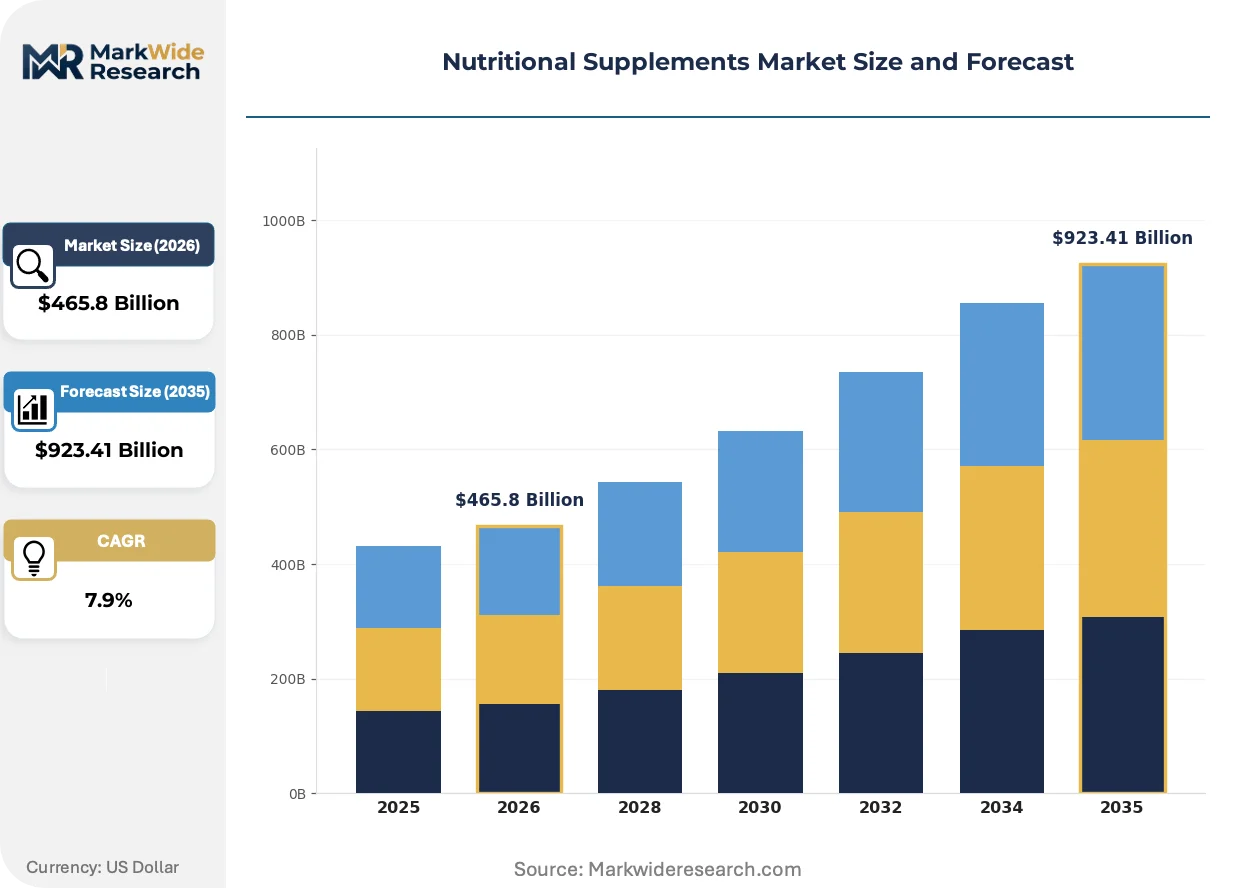
| Market Size in 2026 | $465.8 Billion |
| Market Size in 2035 | $923.41 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbs, Protein Powder Customer Type: Health Enthusiasts, Athletes, Seniors, General Consumers Form: Pills, Capsules, Powders, Gummies Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Amway Corp., The Coca-Cola Company, Glanbia PLC, Thorne, GNC Holdings, Nestle Health Science, PepsiCo, NOW Foods, Herbalife International of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutritional Supplements Market Strategic Shifts & Innovations
Biotechnology and digital distribution infrastructure are compressing development timelines and disintermediating traditional retail relationships across the nutritional supplements value chain.
Precision fermentation is collapsing the cost structure of bioactive compound production. Startups and incumbent ingredient suppliers are adopting microbial platforms to synthesize rare botanical actives at scale. This technology is collapsing the premium pricing power traditionally held by wild-harvested or low-yield extract suppliers.
EFSA health claim assessments are tightening permissible marketing language across European jurisdictions. The regulator's 2023 guidance on botanical substantiation has forced reformulation of several legacy products. Sports nutrition brands are responding by pivoting claims toward structure-function territory and investing in human clinical trials.
Subscription-based replenishment models are displacing retail replenishment cycles among core supplement users. Direct-to-consumer platforms capture purchase data that enables predictive shipping and dosage personalization. This pattern is most visible in North American urban markets where convenience premiums outweigh price sensitivity.
Nutritional Supplements Market Segmentation
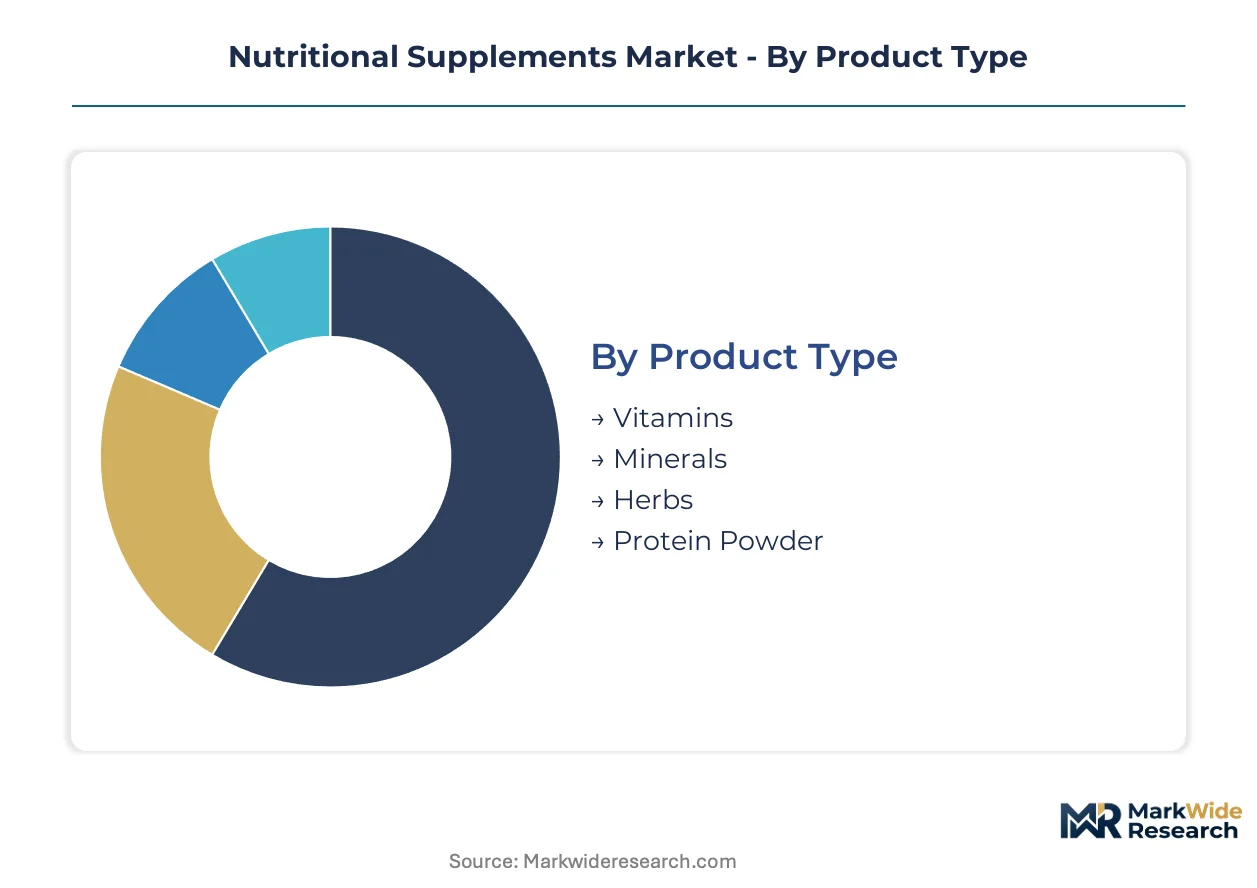
Supplement manufacturers engineer product portfolios around distinct consumption occasions and physiological needs. Segmentation discipline separates commodity-adjacent vitamin sales from premium athletic nutrition, with form factor and channel strategy determining margin capture and customer lifetime value.
Product Type:
After-sales service intensity varies sharply across product categories, with protein powder users demanding formulation guidance and athletes requiring batch certification documentation that vitamin purchasers rarely request.
- Vitamins:Synthetic or natural isolates of essential micronutrients formulated to RDA percentages, with stability and bioavailability specifications driving manufacturing process selection. Demand concentrates in European preventive health programs where public health systems institutionalize vitamin D and omega-3 protocols, though margin compression from decades of consumer familiarity limits pricing power.
- Protein Powder:Dairy-derived whey isolates and plant-based alternatives specified by gram-per-serving content and amino acid profiles, with sports nutrition applications broadening beyond bodybuilding into endurance and lifestyle fitness. Athletes in North American fitness culture drive volume, with clean label certification premiums commanding shelf price advantages in collegiate and professional procurement.
- Minerals:Chelated and elemental forms of calcium, magnesium, zinc, and iron with absorption rate differentials determining formulation choices.
- Herbs:Botanical extracts with phytochemical standardization requirements that outstrip current analytical chemistry talent pipeline output, delaying product launches.
By volume, vitamins lead. By growth pace, protein powder is ahead.
Customer Type:
Cost tier stratification separates premium athletic nutrition from mass-market general wellness, with subscription models capturing recurring revenue from health enthusiasts while seniors drive gummy format innovation.
- Athletes:Performance-focused consumers requiring NSF Certified for Sport or Informed Sport verification for collegiate and professional eligibility, with procurement decisions driven by training protocol integration. North American urban markets show strongest concentration, where convenience premiums outweigh price sensitivity.
- Seniors:Adherence-challenged demographic reshaping delivery system preferences toward palatable gummy formats that expand addressable populations beyond capsule-tolerant users. European public health system integration creates institutional procurement channels for this segment.
- Health Enthusiasts:Core supplement users adopting subscription-based replenishment models and predictive shipping enabled by purchase data capture.
- General Consumers:Price-sensitive occasional purchasers replenishing through retail cycles rather than direct-to-consumer platforms.
By volume, general consumers lead. By subscription attach rate, health enthusiasts are ahead.
Form:
Application context determines format selection, with portable dosing driving capsule adoption for travelers and taste masking enabling pediatric and geriatric compliance through gummy alternatives.
- Gummies:Palatability-driven delivery system expanding fastest as senior and general consumer adherence patterns shift away from traditional pill fatigue. Manufacturing complexity and stability requirements create quality differentiation opportunities.
- Powders:High-dose protein and mineral delivery enabling customizable serving sizes, with sports nutrition applications requiring solubility and flavor masking investment.
- Capsules:Taste-neutral delivery for botanical extracts and sensitive actives, with gelatin and vegetarian shell options addressing dietary restrictions.
- Pills:Lowest-cost manufacturing format for established vitamin and mineral combinations with decades of consumer familiarity.
By volume, pills lead. By innovation investment, gummies are ahead.
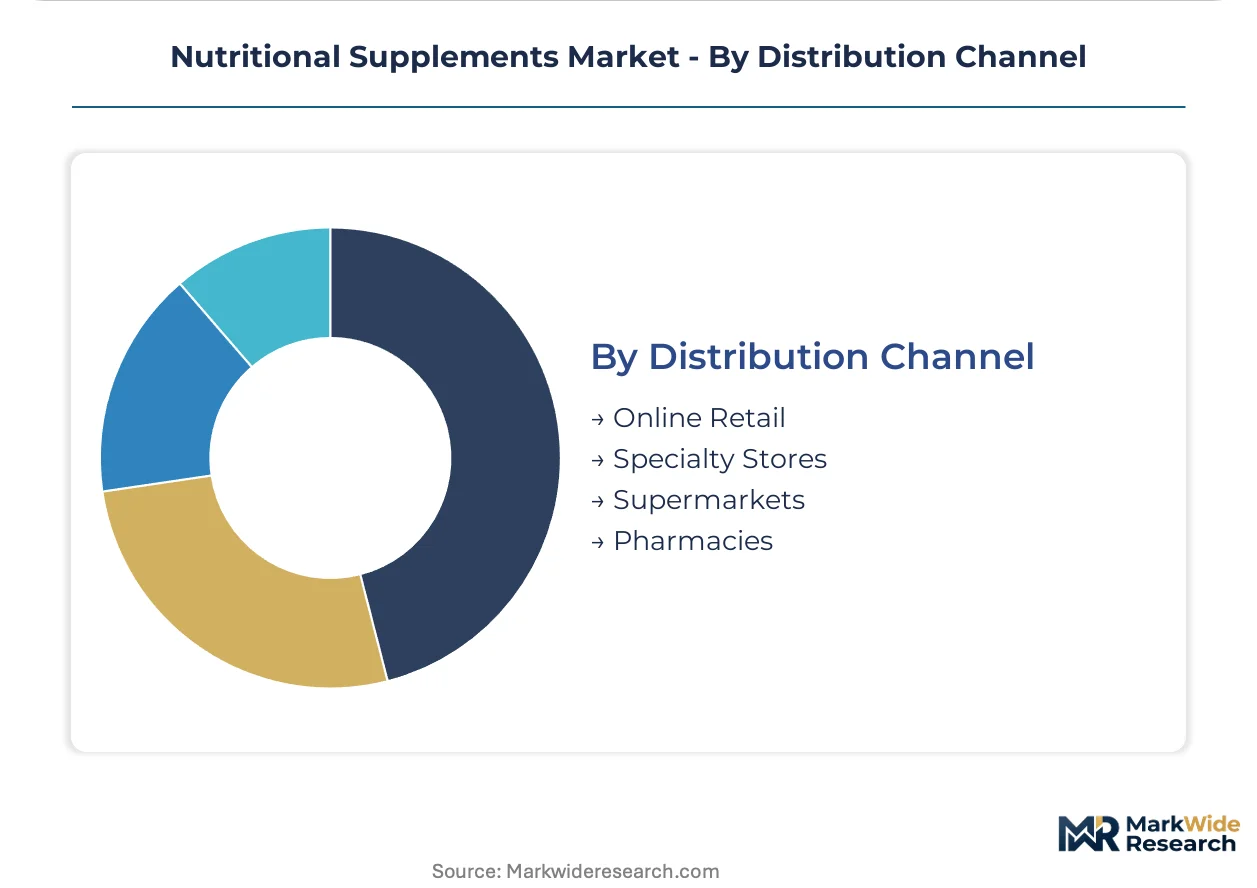
Distribution Channel:
Supply concentration in ISO 17025-accredited contract manufacturing clusters creates bottleneck risk that shapes which channels can reliably source quality-certified inventory.
- Online Retail:Direct-to-consumer platforms and specialized wellness marketplaces fragmenting traditional retail gatekeeper power, compressing intermediary margin capture. Predictive shipping and AI-driven personalization lock in recurring revenue from core users.
- Specialty Stores:Staff expertise and curated assortment commanding premium positioning, with sports nutrition and clean label certifications driving procurement decisions.
- Pharmacies:Clinical credibility and healthcare professional recommendation influence, with European preventive health program integration creating institutional volume.
- Supermarkets:Mass-market accessibility for commodity vitamin and mineral combinations, with private label penetration pressuring branded pricing.
By volume, supermarkets lead. By margin capture, online retail is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites European supplement distribution, while Union Pacific's intermodal network anchors North American ingredient flows.
United States
FDA's New Dietary Ingredient notification pathway constrains ingredient innovation timelines, with pre-market safety substantiation creating first-mover windows for early filers. Current Good Manufacturing Practice regulations enforce quality standards from raw material sourcing through finished good release. ISO 17025-accredited contract manufacturing clusters concentrate in Utah and California, where precision fermentation startups are collapsing bioactive compound production costs.
Germany
EFSA health claim assessments tighten permissible marketing language for botanical substantiation, forcing reformulation of legacy products toward structure-function territory. The country's preventive health programs institutionalize vitamin D and omega-3 protocols, creating institutional procurement channels. North Rhine-Westphalia hosts concentrated analytical chemistry capabilities for phytochemical standardization that outstrip current talent pipeline output elsewhere.
China
SAMR oversight of health food registration and filing pathways shapes domestic formulation strategies, with dual carbon goals accelerating precision fermentation adoption for sustainable bioactive production. NMPA-equivalent provincial regulators enforce manufacturing quality standards across Yangtze River Delta supplement production bases. Shanghai's biotech corridor anchors microbial platform development for rare botanical actives at scale.
Japan
METI's functional food labeling system creates distinct claim categories that separate Foods with Function Claims from Foods for Specified Health Uses, with PMDA-influenced safety standards governing ingredient thresholds. Aging demographics drive gummy format innovation for adherence-challenged senior populations. Kansai region's Osaka-Kobe manufacturing belt concentrates gelatin and vegetarian shell production for capsule export markets.
India
FSSAI's health supplement regulations and nutraceutical standards enforce quality parameters for domestic and export-bound production, with CDSCO-aligned safety assessments for novel ingredients. BIS certification requirements determine contract manufacturer qualification for brand partnerships. Maharashtra's Mumbai-Pune corridor clusters Ayurvedic extract standardization facilities facing phytochemical verification expertise scarcity.
Nutritional Supplements Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream. The nutritional supplements sector fragments across direct-selling infrastructure, dairy-derived protein specialization, and vertically integrated manufacturing scale. Three archetypes dominate: direct-to-consumer relationship platforms, ingredient supply contract anchors, and quality-certified production controllers. Consolidation pressure concentrates around ISO 17025-accredited capacity, while backward integration into milk processing defends sports nutrition margins against whey input volatility.
Among direct-selling specialists, Amway Corp. exemplifies relationship-platform architecture; Glanbia PLC represents dairy-derived protein specialization; NOW Foods occupies the vertically integrated manufacturing tier. These three anchors illustrate divergent defensive strategies against e-commerce fragmentation and contract manufacturer concentration risk. Each archetype responds differently to FDA NDI notification constraints, EFSA claim tightening, and precision fermentation cost collapse.
| Leading Market Players |
|---|
| Amway Corp. |
| The Coca-Cola Company |
| Glanbia PLC |
| Thorne |
| GNC Holdings |
| Nestle Health Science |
| PepsiCo |
| NOW Foods |
| Herbalife International of America |
| Others |
Cost & Logistics Intelligence
Whey protein commodity volatility transmits directly through sports nutrition margin structures, compressing EBITDA for brands lacking backward integration into milk processing while simultaneously widening the spread between premium NSF-certified tiers and economy private-label alternatives. This input-cost instability forces pricing stratification across premium, standard, and economy tiers as manufacturers pass through dairy commodity swings differentially based on certification investment and channel positioning.
Pricing Analysis
Volume-discount tiering structures dominate procurement relationships, with institutional athletic programs capturing 15-25% unit cost advantages over direct-to-consumer single-unit purchasers. Price differentiation hinges on third-party certification grade—NSF Certified for Sport and Informed Sport verification commands shelf premiums—while geographic delivery cost and subscription commitment length shape final landed pricing. Cost compression in the protein powder segment is intensifying due to precision fermentation entrants collapsing bioactive production costs. General consumers replenishing through supermarket retail cycles exhibit highest price sensitivity; collegiate procurement officers with eligibility compliance requirements show lowest sensitivity.
Supply Chain Analysis
Upstream feedstock flows concentrate in dairy processing regions of the United States, New Zealand, and Germany, with whey isolate and casein hydrolysate specifications tethered to seasonal milk production cycles. Raw material dependencies span dairy-derived protein isolates, plant-based pea and rice protein concentrates, and gelatin or pectin substrates for gummy matrices. Single-source vulnerability clusters in ISO 17025-accredited contract manufacturing capacity concentrated in Utah, California, and North Rhine-Westphalia. Distribution runs through direct-to-consumer platforms, specialized wellness marketplaces, and pharmacy chains with cold-chain requirements for probiotic and omega-3 formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms threaten to collapse premium pricing power traditionally held by wild-harvested botanical extract suppliers, forcing incumbents to defend substitution vulnerability through certification moats and captive supply relationships.
For Market Incumbents: Build certification moats through NSF Certified for Sport and Informed Sport third-party verification investments that lock in collegiate and professional athletic procurement channels. Deepen backward integration into dairy processing or precision fermentation partnerships to defend sports nutrition margins against whey input volatility. Channel control through direct-to-consumer platform ownership reduces intermediary margin capture as e-commerce fragmentation accelerates. For New Entrants and Emerging Players: Establish a beachhead in gummy format innovation for adherence-challenged senior populations, where palatability-driven delivery system expertise remains scarce relative to capsule and powder manufacturing. Target European preventive health program institutional procurement channels for vitamin D and omega-3 protocols, leveraging public health system integration that creates volume commitments absent in discretionary retail. A microbiome testing and AI-driven personalization convergence angle unlocks subscription recurring revenue models with predictive shipping capabilities. For Investors and Strategic Acquirers: FDA New Dietary Ingredient notification pathway milestones reshape the acquisition landscape, with early filer ingredient exclusivity windows creating defendable revenue streams. Long-term viability over the 5-10 year horizon favors vertically integrated manufacturers with captive ISO 17025-accredited production capacity and backward integration into protein isolate processing. The signal to watch is precision fermentation cost parity achievement against traditional extraction methods, which will compress premium botanical pricing power and trigger consolidation among wild-harvested extract suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial platform adoption collapses rare botanical active production costs and erodes wild-harvested supplier margins. |
| Third-Party Certification Investment | NSF Certified for Sport and Informed Sport verification commands shelf price premiums in athletic procurement channels. |
| Direct-to-Consumer Platform Launch | Predictive shipping and AI-driven personalization lock in recurring revenue from core supplement users in North American urban markets. |
| Backward Integration into Dairy Processing | Captive whey isolate supply defends sports nutrition margins against commodity price volatility transmission. |
| European Preventive Health Program Integration | Institutional procurement channels for vitamin D and omega-3 protocols create volume commitments through public health system adoption. |
Research Approach
Cross-validation between primary interviews with sports nutrition formulators, contract manufacturing quality directors, and athletic procurement officers anchors the qualitative findings, while secondary validation draws from FDA NDI notification filings, EFSA health claim assessment databases, and ISO 17025 laboratory accreditation registries. Bottom-up triangulation against customs and trade data for whey protein isolate and plant-based protein concentrate flows, combined with top-down reconciliation against Nielsen retail audit data for supplement category dollar velocity, ensures dimensional consistency.
Calibration against historical CAGRs across the projection horizon employed segmented modeling by product type, customer archetype, delivery form, and distribution channel, with regional regulatory cluster overlays for FDA, EFSA, and SAMR jurisdiction-specific claim substantiation requirements. Growth trajectories derived from elasticity modeling of protein powder demand against fitness club membership trends and preventive health program adoption curves in European public health systems.
Sensitivities concentrate around precision fermentation cost parity timelines, dairy commodity price volatility regimes, and EFSA botanical substantiation guidance evolution that could force reformulation of legacy products. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution elasticity between synthetic and bioactive compound sources. Cross-checking against IEA agricultural commodity price benchmarks and WHO micronutrient deficiency prevalence data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Fish Protein Isolate Market
Nutritional Supplements
Lactoferrin Products Market
Nutritional Supplements
Hair Growth Supplements Market
Nutritional Supplements
United States Botanical Supplements Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Energy Gums Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Global Proanthocyanidins Market
Nutritional Supplements
Nutraceutical Gummies Market
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Global Coq10 Supplement Market
Nutritional Supplements
Garcinia Cambogia Extract Market