
 Coral Calcium Market | 2026-2036
Coral Calcium Market Size, Share, and Industry Trends Forecast 2026-2036
Coral Calcium Market Analysis
Supplement ingredient sourcing revenue is fragmenting between reef-harvested and above-sea fossilized coral suppliers. Nature's Way Products LLC leverages long-standing relationships with Okinawan harvesters to sustain premium positioning in North American health food channels. GNC Holdings LLC competes through private-label fortification programs that anchor volume contracts with domestic distributors. Now Foods differentiates via vertically controlled testing protocols for heavy-metal compliance.
Coral calcium consists primarily of calcium carbonate derived from fossilized coral reefs, with trace mineral profiles including magnesium and strontium that distinguish it from standard limestone-derived supplements; manufacturers micronize raw material to sub-50-micron particle size for enhanced bioavailability in tablet and powder formulations. Natural product type occupies the dominant margin pool due to consumer preference for unadulterated reef-derived material, while fortified variants represent the fastest-growing category as manufacturers add vitamin D3 and K2 to improve absorption claims. Powder form leads unit volume in direct-to-consumer channels, though pill formulations retain pharmacy shelf presence through compliance-driven repeat purchases.
FDA Current Good Manufacturing Practice regulations enforce identity testing and contaminant screening for all dietary supplements containing coral calcium sold in the United States. Japan's Ministry of Health, Labour and Welfare administers additional import inspection protocols that restrict supply to pre-approved extraction zones. FSSAI in India mandates heavy-metal limits for mineral supplements that affect market access for uncertified suppliers. Stakeholders must monitor evolving reef-protection designations that could restrict harvest zones and trigger reformulation requirements.
Market Dynamics
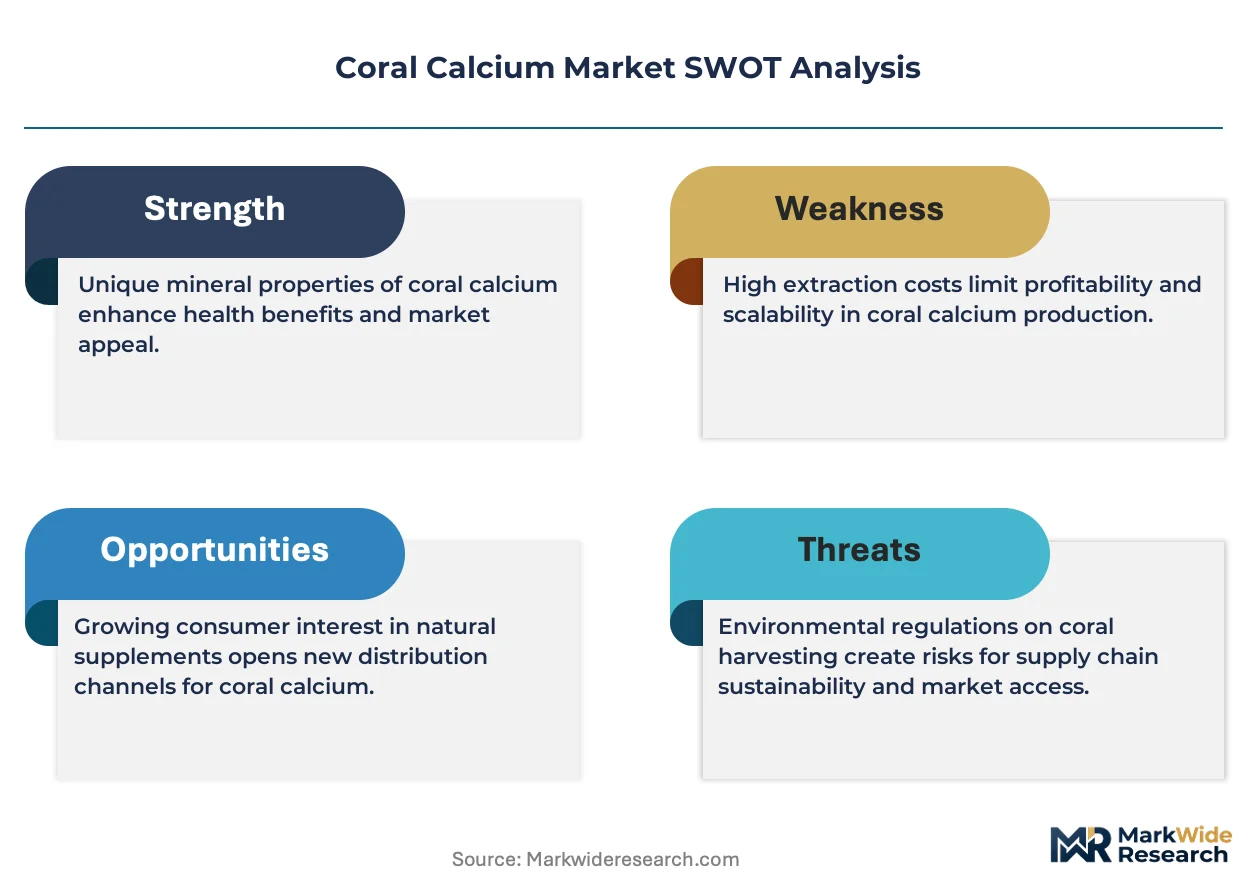
Reef-protection designations are tightening harvest zones across Pacific island jurisdictions, forcing manufacturers to qualify fossilized above-sea deposits or pivot to alternative marine mineral sources entirely.
Growth Catalysts
- FSSAI heavy-metal compliance mandates:India's mineral supplement safety framework creates certified-supplier preference among exporters targeting South Asian wellness channels.
- Okinawa traditional consumption clusters:Prefecture-level demand density sustains premium sourcing relationships and validates bioavailability claims in Japanese functional food applications.
- Micronization below 50 microns:Particle size reduction technology unlocks tablet compression efficiency and powder dissolution rates for direct-to-consumer formulations.
Market Restraints
- Harvest zone concentration risk:Pre-approved Okinawan extraction permits limit qualified raw material pools to a narrow geographic band vulnerable to marine protected area expansion.
- Limestone-derived calcium carbonate substitution:Standard mineral supplements at lower price points capture price-sensitive pharmacy and mass-market shelf space.
- Japan MHLW import inspection protocols:Extended batch-release timelines for foreign suppliers compress working capital cycles and deter new market entrants.
Strategic Opportunities
- Vitamin D3 and K2 fortification convergence:Enhanced absorption positioning opens functional food partnerships beyond traditional supplement aisles.
- Direct-to-consumer powder channels:Subscription wellness platforms bypass pharmacy distribution markups and capture lifetime value through repeat formulation purchases.
- India PLI scheme for nutraceuticals:Domestic production incentives attract contract manufacturers seeking to serve South Asian and Middle East export markets from certified local facilities.
Industry Challenges
- Heavy-metal screening capex:ICP-MS and atomic absorption spectroscopy equipment requirements strain mid-tier ingredient processors without captive testing infrastructure.
- FDA identity testing documentation:Botanical and mineral origin verification protocols demand specialized analytical chemistry talent scarce in contract manufacturing organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coral Calcium Market |
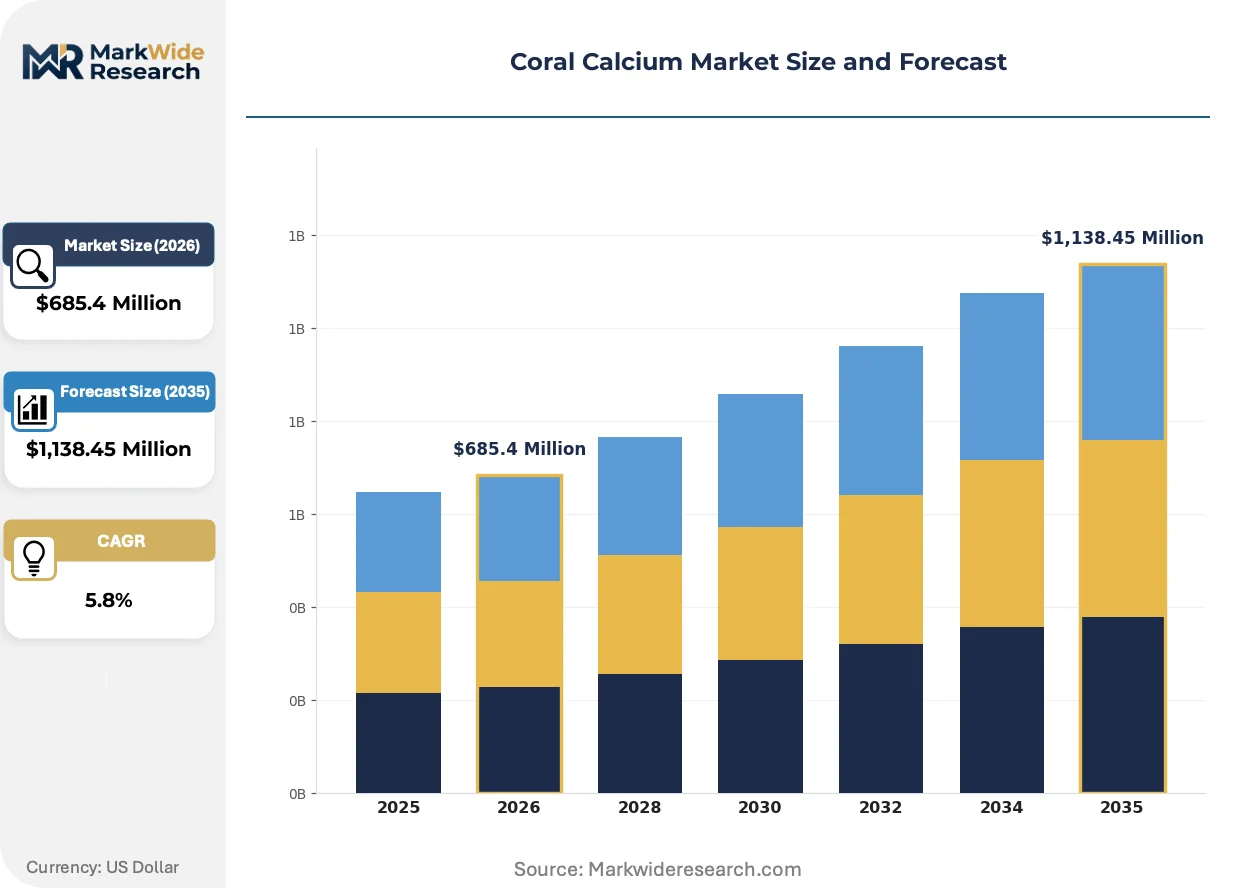
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Fortified, Organic Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets End User: Individuals, Athletes, Healthcare Providers, Nutritional Professionals Form: Pills, Powder, Liquid, Gummies |
| Companies Covered | Marine Bio Co. Ltd., Nature's Way Products LLC, GNC Holdings LLC, Nature Sunshine Products Inc., Nutrabio Labs Inc., Now Foods, Natural Biology Inc., Solgar, Coral LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coral Calcium Market Emerging Trajectories
Sustainability verification and traceability systems are restructuring supplier qualification protocols, while particle engineering and fortification chemistry redefine product differentiation levers across retail and clinical channels.
Sub-micron precipitation technology is collapsing the particle size distribution gap between reef-harvested and fossilized coral sources. Dietary supplement contract manufacturers in Japan and the United States are adopting wet-milling systems that achieve bioequivalent dissolution profiles regardless of raw material provenance. This convergence is eroding the premium price justification for Okinawan reef-derived material and compressing margin pools at the top of the quality ladder.
EMA novel food consultation pathways and EFSA health claim substantiation requirements are tightening evidence standards for bone-health positioning in European markets. Manufacturers must now generate human intervention data rather than relying on compositional equivalence to approved calcium sources. Powder formulations targeting pharmacy channels face reformulation pressure to meet centralized authorization timelines.
Clean-label preference is rotating procurement criteria toward extraction method transparency and carbon footprint disclosure. Wellness-focused retailers in Germany and the Netherlands now require batch-level traceability documentation that extends to fossilized deposit geology and drying energy sources. This behavioral shift favors vertically controlled supply chains over aggregated commodity sourcing.
Coral Calcium Market Segmentation
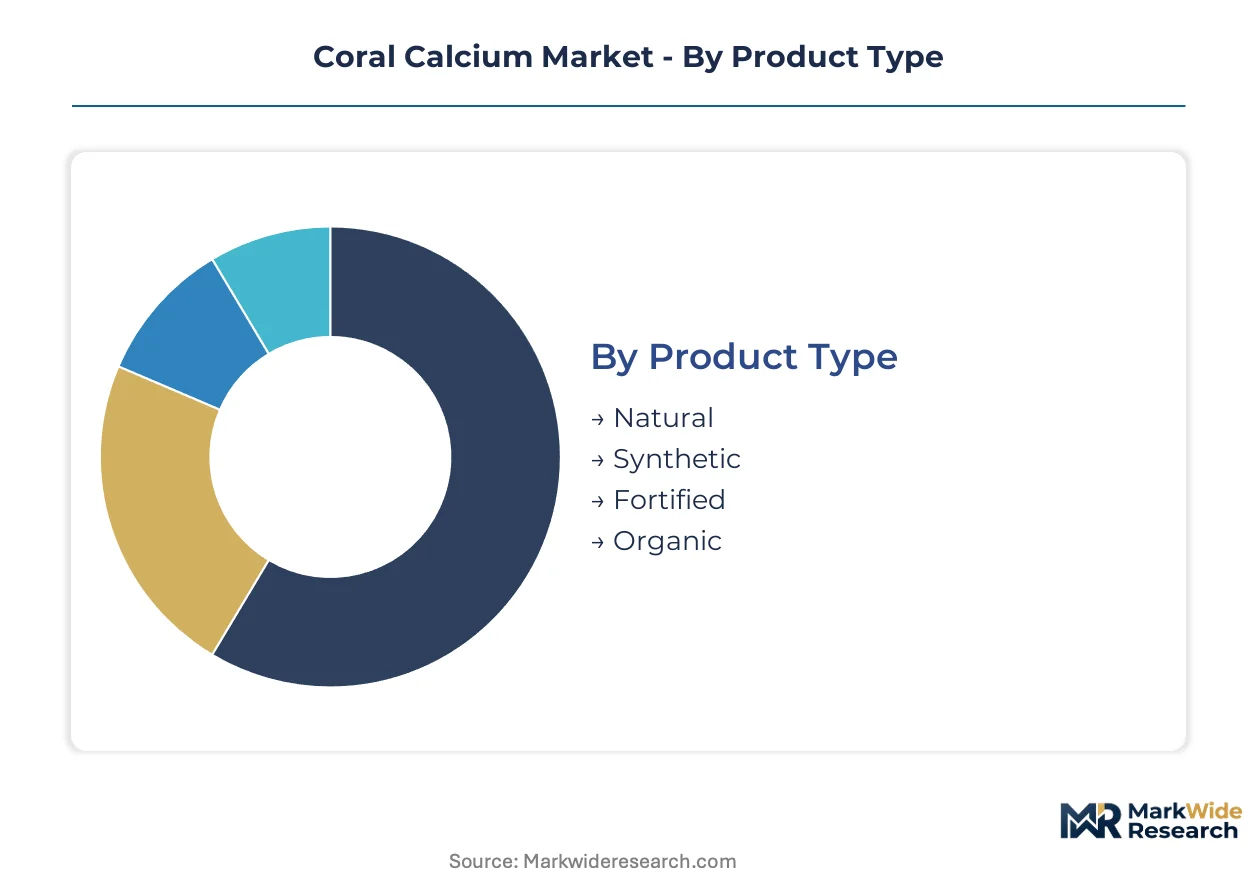
Coral calcium manufacturers configure production lines around formulation chemistry and channel economics rather than uniform scale. Segment-level margin structures diverge sharply between reef-certified premium tiers and mass-market substitutes.
Product Type:
Fortified variants turn inventory fastest through wellness subscription channels, while organic certification cycles stretch longest due to extraction zone verification protocols.
- Natural:Unprocessed coral calcium retains magnesium and strontium trace profiles from Okinawan reef deposits. Japanese functional food manufacturers in Tokyo and Osaka sustain premium offtake for traditional consumption formats.
- Fortified:Vitamin D3 and K2 additions reposition coral calcium for clinical absorption claims. North American direct-to-consumer brands drive formulation innovation through pharmacy bypass models.
- Synthetic:Lab-cultivated mineral matrices replicate trace element ratios without reef extraction. Production scales through Singapore and South Korean biotech contract manufacturers.
- Organic:Certified extraction from fossilized above-sea deposits meets EU organic labeling thresholds. German and Dutch retailers demand batch-level carbon footprint documentation.
Natural product type anchors the volume base while fortified variants gain share at the steepest rate.
Distribution Channel:
Channel cost tiers separate compliance-heavy pharmacy networks from lean digital fulfillment infrastructure.
- Online Retail:Subscription wellness platforms capture lifetime value through powder formulation auto-replenishment. California and New York metro areas concentrate direct-to-consumer demand density.
- Health Stores:Staff-trained consultation environments sustain premium pill and capsule positioning. Regional chains in Texas and Florida anchor shelf-space negotiations.
- Pharmacies:FDA Current Good Manufacturing Practice documentation requirements filter supplier pools. CVS and Walgreens distribution centers enforce lot-level traceability standards.
- Supermarkets:Mass-market placement competes with limestone-derived calcium carbonate at price-sensitive shelf positions. Kroger and Albertsons category managers prioritize household penetration metrics.
Pharmacy channels dominate value capture while online retail expands most quickly.
End User:
Customer procurement authority separates self-directed supplement purchasers from institutional specification writers.
- Individuals:Aging demographic clusters in Japan and Italy drive preventive bone health purchasing. Amazon and iHerb review ecosystems shape brand selection criteria.
- Athletes:Sports nutrition formulators specify micronized powder for protein fortification blends. CrossFit and endurance running communities propagate bioavailability claims through social proof.
- Healthcare Providers:Integrative medicine practitioners in California and Germany recommend coral calcium for mineral repletion protocols. Patient compliance tracking influences repeat prescription patterns.
- Nutritional Professionals:Registered dietitians specify third-party tested brands for client supplementation plans. Continuing education conference exposure determines brand awareness thresholds.
Individual consumers anchor the volume base while healthcare providers gain share at the steepest rate.
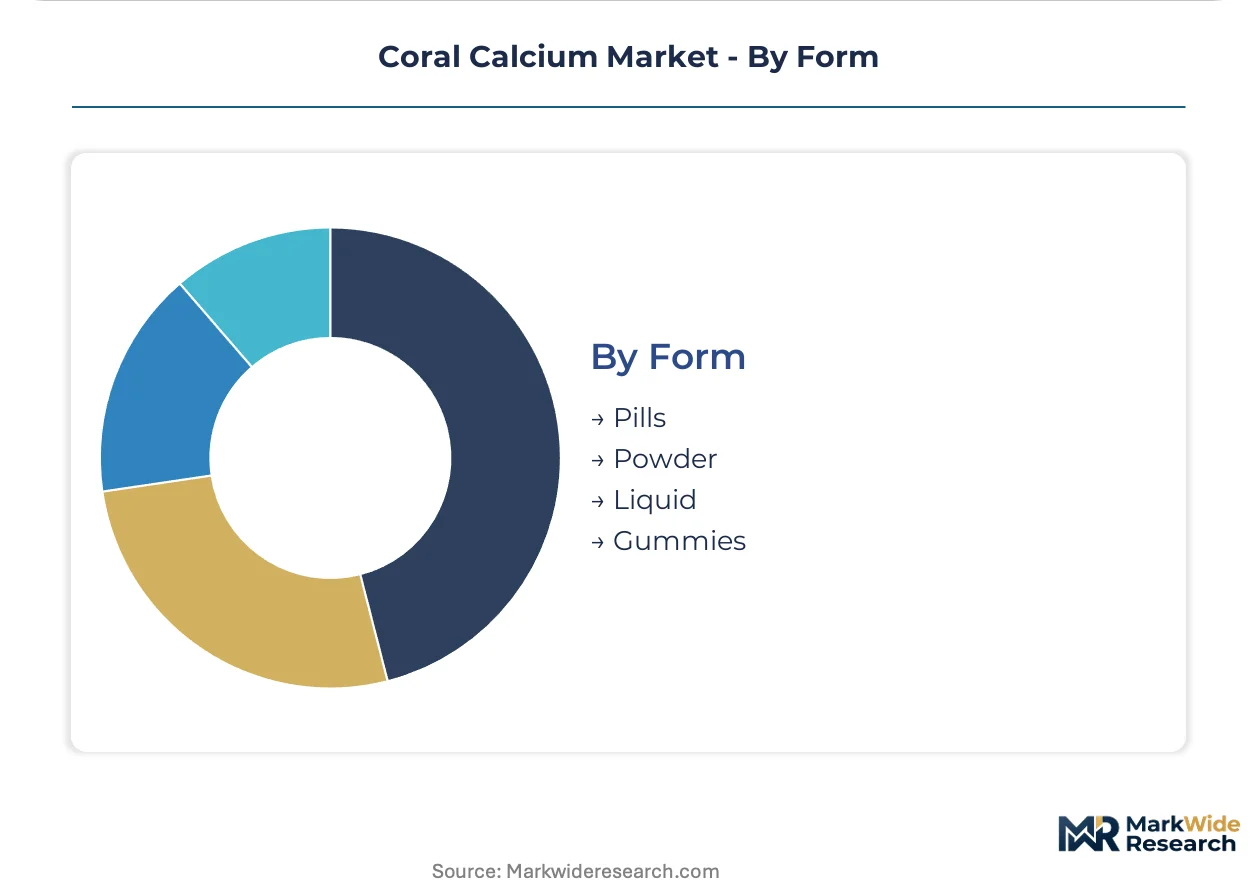
Form:
Manufacturing capital intensity varies dramatically between powder milling infrastructure and gummy confectionery lines.
- Powder:Sub-50-micron particle size enables beverage and smoothie integration. Bulk packaging formats serve contract manufacturers in Utah and Arizona production zones.
- Pills:Tablet compression equipment achieves economies through multi-mineral formulation runs. Japanese pharmaceutical contractors specialize in enteric coating for gastric tolerance.
- Liquid:Suspension stability challenges limit shelf life and distribution radius. Pediatric and geriatric compliance applications justify premium positioning.
- Gummies:Sugar-free pectin bases compete with gelatin alternatives for clean-label positioning. Adult gummy format adoption accelerates through Costco and Target placement.
Pill formulations anchor the volume base while gummies climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across consumption clusters. Japanese buyers absorb substantial premiums for Okinawan-sourced material, while Indian and German markets punish any cost disadvantage against limestone-derived alternatives.
United States
Direct-to-consumer subscription channels concentrate in California and New York metro areas, where wellness platforms capture repeat powder purchases. FDA Current Good Manufacturing Practice regulations enforce identity testing and heavy-metal screening for all dietary supplements. Utah and Arizona host contract manufacturing clusters serving domestic health food and pharmacy distribution networks.
Japan
Traditional consumption patterns in Okinawa prefecture sustain premium sourcing relationships with reef harvesters, validating bioavailability claims for functional food applications. The Ministry of Health, Labour and Welfare administers strict import inspection protocols that restrict supply to pre-approved extraction zones. Tokyo and Osaka manufacturers anchor the national formulation base for domestic and export markets.
Germany
Clean-label preference rotates procurement toward extraction method transparency and carbon footprint disclosure. EFSA health claim substantiation requirements tighten evidence standards for bone-health positioning beyond compositional equivalence. Wellness retailers in Berlin and Hamburg now require batch-level traceability documentation extending to fossilized deposit geology.
India
Aging demographic clusters drive preventive bone health purchasing through pharmacy and emerging direct-to-consumer channels. FSSAI heavy-metal compliance mandates create certified-supplier preference among exporters targeting South Asian wellness markets. The Production Linked Incentive scheme for nutraceuticals attracts contract manufacturers seeking to serve regional export markets from certified local facilities.
Netherlands
EU organic labeling thresholds for fossilized above-sea deposits shape supplier qualification for clean-label positioning. REACH and ECHA frameworks govern mineral supplement safety documentation for cross-border distribution. Rotterdam and Amsterdam distribution hubs consolidate re-export flows to German and Nordic retail channels demanding traceability verification.
Coral Calcium Market Vendor Landscape
Capability concentration sits with vertically integrated harvesters possessing Okinawan extraction permits; scale advantage sits with North American contract manufacturers running multi-mineral formulation lines. The market structures around three archetypes: reef-certified premium suppliers, mass-market private-label processors, and synthetic replication specialists. Dominant competitive moves include backward integration into controlled extraction zones and technology licensing for sub-micron precipitation systems.
Within the premium-tier vector, Nature's Way Products LLC and Marine Bio Co. Ltd. exemplify archetypes built on geographic sourcing control. GNC Holdings LLC occupies a position representing scale-driven private-label fortification programs. These three anchors illustrate how qualification requirements split competitive positioning between provenance verification and volume contract execution.
| Leading Market Players |
|---|
| Marine Bio Co. Ltd. |
| Nature's Way Products LLC |
| GNC Holdings LLC |
| Nature Sunshine Products Inc. |
| Nutrabio Labs Inc. |
| Now Foods |
| Natural Biology Inc. |
| Solgar |
| Coral LLC |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Okinawan reef-certified extraction zones compresses supplier margins while amplifying price premiums for authenticated provenance. Japanese functional food manufacturers absorb elevated input costs to sustain traditional consumption claims, whereas North American contract manufacturers pivot toward fossilized above-sea deposits to defend mass-market price positions.
Pricing Analysis
Subscription auto-replenishment programs anchor lifetime value in direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and extraction method transparency. Price erosion runs through mass-market pharmacy tiers as limestone-derived substitutes capture shelf space. Individual consumers in Germany and the Netherlands exhibit highest price sensitivity to carbon footprint disclosure premiums.
Supply Chain Analysis
Contract manufacturing clusters in Utah and Arizona hold capacity for multi-mineral formulation runs serving North American health food networks. Raw material sourcing draws from Okinawa prefecture, fossilized deposits in the Caribbean, and synthetic replication facilities in Singapore. Single-source vulnerability concentrates in Japanese Ministry of Health, Labour and Welfare pre-approved extraction permits. Distribution runs through pharmacy networks, subscription wellness platforms, and health store regional chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as clean-label preference splinters procurement criteria across traceability, carbon disclosure, and fortification chemistry niches. Supplement ingredient sourcing revenue disperses between reef-certified, fossilized, and synthetic supply tiers.
For Market Incumbents: Build extraction zone control moats through backward integration into fossilized above-sea deposits with batch-level traceability documentation. Secure Okinawan permit renewals ahead of marine protected area expansion. Invest in wet-milling capacity to achieve bioequivalent dissolution profiles that erode competitor premium positioning.
For New Entrants and Emerging Players: Build out synthetic replication capabilities through Singapore and South Korean biotech contract manufacturers to bypass reef-protection designation constraints. Target India Production Linked Incentive scheme-certified facilities for South Asian and Middle East export markets. Penetrate through vitamin D3 and K2 fortification partnerships with functional food brands seeking clinical absorption claims.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription platforms with powder formulation auto-replenishment. Long-term viability favors vertically integrated harvesters possessing Okinawan extraction permits combined with micronization technology licensing. Watch for sub-micron precipitation patent filings as inflection indicators of bioequivalence convergence eroding provenance premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Extraction Zones | Okinawan permit holders secure supply continuity against marine protected area expansion risks. |
| Technology Licensing for Sub-Micron Precipitation Systems | Wet-milling adoption collapses dissolution profile gaps between reef and fossilized sources. |
| Vitamin D3 and K2 Fortification Convergence | Enhanced absorption positioning opens functional food partnerships beyond supplement aisles. |
| Direct-to-Consumer Subscription Platform Launch | California and New York metro wellness platforms capture lifetime value through auto-replenishment. |
| India PLI Scheme Facility Certification | Domestic production incentives attract contract manufacturers serving South Asian export markets. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across dietary supplement contract manufacturers, Okinawan reef harvesters, Japanese functional food formulators, German wellness retailers, and Indian nutraceutical production planners. Primary interview insights were validated against FDA Current Good Manufacturing Practice guidance documents, Japan MHLW import inspection protocols, FSSAI heavy-metal compliance mandates, EFSA health claim substantiation requirements, and customs trade data for coral-derived mineral products. Bottom-up segment sizing and top-down market triangulation were cross-referenced for convergence.
Calibration against historical volume trajectories and regulatory timeline shifts anchored projection reliability across the analysis window. Segmentation dimensions modeled include product type tier, distribution channel cost structure, end-user procurement authority, and geographic regulatory cluster. CAGRs were derived from slope analysis of validated data points adjusted for reef-protection designation impacts and substitution elasticity. Forecast inputs incorporated micronization technology diffusion rates and fortification chemistry adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by synthetic replication specialists or rapid marine protected area expansion would shift outcomes. Quarterly review of Okinawan extraction permit renewals, sub-micron precipitation patent filings, and India PLI scheme facility certifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Effervescent Product Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
North America Vegan Supplements Market
Nutritional Supplements
Older Adults Health Supplements Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Bovine Lactoferrin Market
Nutritional Supplements
Indonesia Beauty Supplements Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
Krill Oil Supplements Market
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
High-Selenium Yeast Market
Nutritional Supplements
Water Soluble Vitamin and Mineral Feed Supplements Market
Nutritional Supplements
Brazil Whey Protein Market