
 Marine Supplements Market | 2026-2036
Marine Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Supplements Market Analytics
Buyer concentration among fitness enthusiasts and sports nutrition distributors is broadening as boutique CrossFit boxes, functional medicine clinics, and direct-to-consumer wellness platforms enter procurement channels. Nordic Naturals anchors North American retail shelf presence through pharmacy and practitioner networks. NOW Foods competes on manufacturing scale and private-label flexibility across multiple form factors. Blackmores dominates Australasian pharmacy channels with practitioner-grade positioning.
Marine supplements comprise bioactive lipid extracts, primarily long-chain omega-3 fatty acids EPA and DHA, harvested from pelagic fish, Antarctic krill, or cultured microalgae and refined to specific oxidative stability indices for human consumption. Standardized peroxide values and TOTOX thresholds ensure shelf integrity across liquid, softgel, powder, and capsule delivery systems. Fish oil occupies the mature volume base, while algal oil captures the fastest expansion as plant-based formulation eliminates marine allergen concerns and satisfies vegan label claims. Softgel formats retain margin concentration due to enteric-coating premiums and dose-precision advantages in clinical applications.
FDA dietary supplement GMPs, EFSA health claim authorization pathways, and Marine Stewardship Council chain-of-custody standards collectively dictate ingredient traceability, label substantiation, and retail access across major markets. Compliance costs favor suppliers with captive raw material sourcing and in-house analytical laboratories. Stakeholders must monitor emerging state-level restrictions on wild-caught fishmeal sustainability narratives and algae cultivation water-use regulations that could reshape feedstock economics.
Market Dynamics
Sports nutrition distributors and functional medicine clinics now drive procurement volume, compressing traditional pharmacy channel margins while algal oil processing investments reshape upstream supply economics.
Growth Catalysts
- EFSA health claim authorization:Validated cardiovascular and cognitive function substantiations unlock premium pricing in European pharmacy networks, accelerating practitioner-grade formulation demand.
- CrossFit box proliferation:Boutique fitness facilities in North America and Western Europe now stock omega-3 concentrates as recovery protocol staples, bypassing traditional retail markup structures.
- Microalgae cultivation scale-up:Photobioreactor technology advances in China and Israel are collapsing unit production costs for DHA-rich algal biomass, enabling vegan label parity with fish oil pricing.
Market Restraints
- Pelagic fish stock volatility:Anchovy and sardine harvest fluctuations off Peru and Chile concentrate raw material risk with three dominant fishing cooperatives controlling South Pacific supply.
- Novel Food compliance costs:EU Regulation 2015/2283 dossier preparation and toxicology studies impose six-figure barriers for novel algal strains and krill extract innovations.
- Plant-based lipid competition:Ahiflower and echium seed oils offering ALA-to-EPA conversion pathways capture budget-conscious vegan consumers without marine allergen concerns.
Strategic Opportunities
- Direct-to-consumer wellness platforms:Subscription models integrating microbiome testing with personalized omega-3 dosing protocols bypass pharmacy intermediaries entirely.
- India practitioner channel:Ayurvedic integrative medicine clinics represent unserved demand for high-concentrate EPA formulations in metabolic syndrome management.
- CSRD supply chain disclosure:EU corporate sustainability reporting mandates create competitive advantage for MSC-certified suppliers with blockchain traceability infrastructure.
Industry Challenges
- Analytical chemistry talent scarcity:GC-MS and NMR spectroscopy expertise for oxidative stability testing concentrates with contract laboratories, creating bottlenecks for in-house quality teams.
- Enteric coating equipment lead times:Specialized softgel manufacturing lines require 18-24 month procurement cycles, constraining capacity expansion for clinical-grade dose precision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Supplements Market |
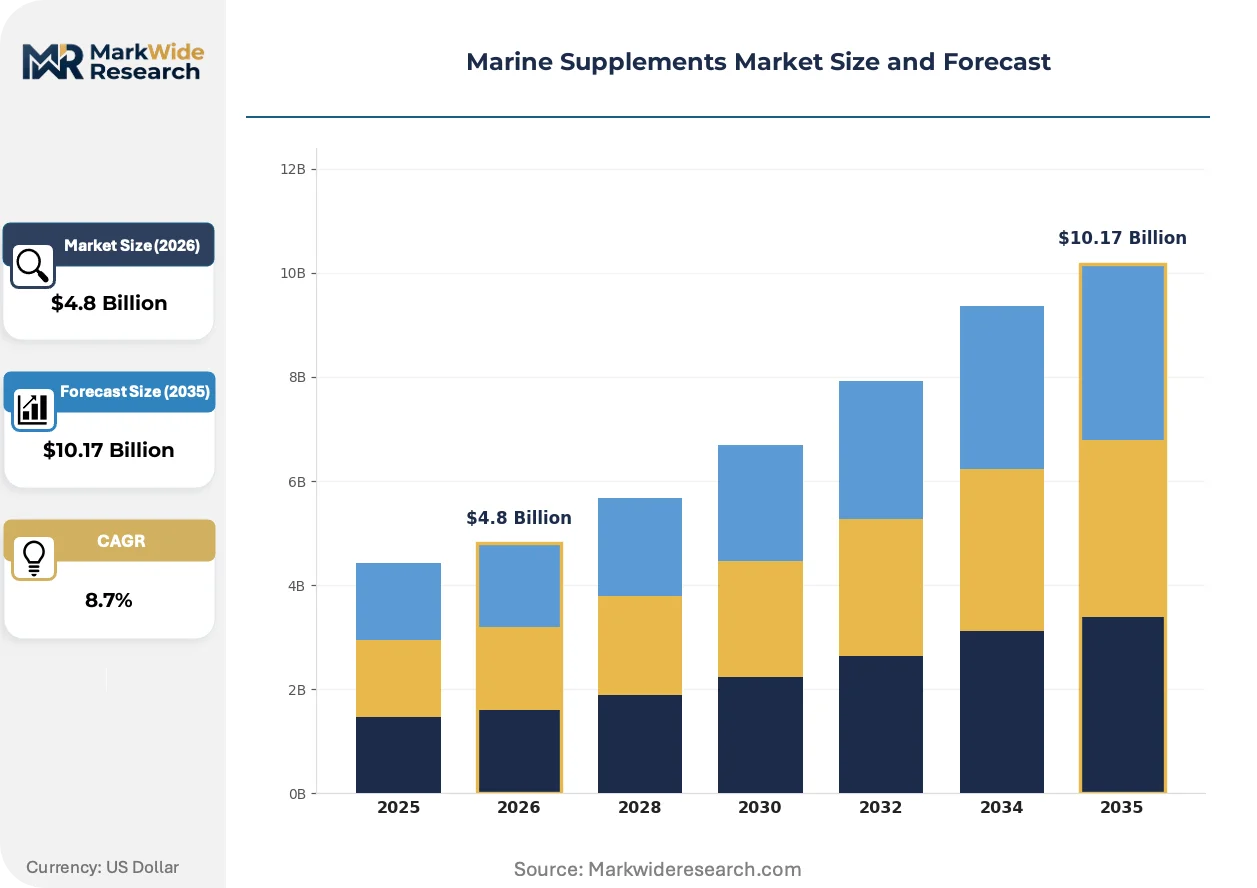
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Krill Oil, Algal Oil, Omega-3 Fatty Acids End User: Fitness Enthusiasts, Elderly, Pregnant Women, General Population Form: Liquid, Softgel, Powder, Capsule Application: Nutritional Supplements, Functional Foods, Sports Nutrition, Dietary Aids |
| Companies Covered | Blackmores, Nature’s Bounty, Nordic Naturals, California Gold Nutrition, NOW Foods, Amway, Nature Made, GNC Holdings, Herbalife Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Supplements Market Evolving Landscape
Formulation science and verification technology are converging to reshape how marine bioactives reach end consumers, with sustainability authentication now as critical as potency standardization.
Algal oil processing is integrating closed-loop photobioreactor systems with continuous harvesting automation. Nordic contract manufacturers are adopting these platforms to secure non-GMO, allergen-free DHA supply chains. This technology is integrating pharmaceutical-grade GMP infrastructure into what was commodity feedstock production, compressing the traditional multi-handler supply chain into single-site vertical operations.
REACH substance registration requirements for novel lipid extracts are tightening purity disclosure thresholds across European manufacturing. Industrial consequence includes mandatory full-spectrum contaminant screening that smaller toll processors cannot absorb. Algal oil innovators with captive cultivation and in-house analytical laboratories are capturing contract manufacturing share from legacy fish oil refiners dependent on third-party testing.
Practitioner-grade buyers now demand batch-level certificate of analysis access through QR-linked digital platforms, replacing paper documentation chains. Functional medicine clinics and compounding pharmacies are the segments most disrupted, with patient compliance tracking apps displacing traditional rep-driven education. Germany and Australia exhibit the most pronounced channel migration, where TGA and BfArM oversight of telehealth prescribing accelerates direct-patient supplement dispensing.
Marine Supplements Market Segmentation
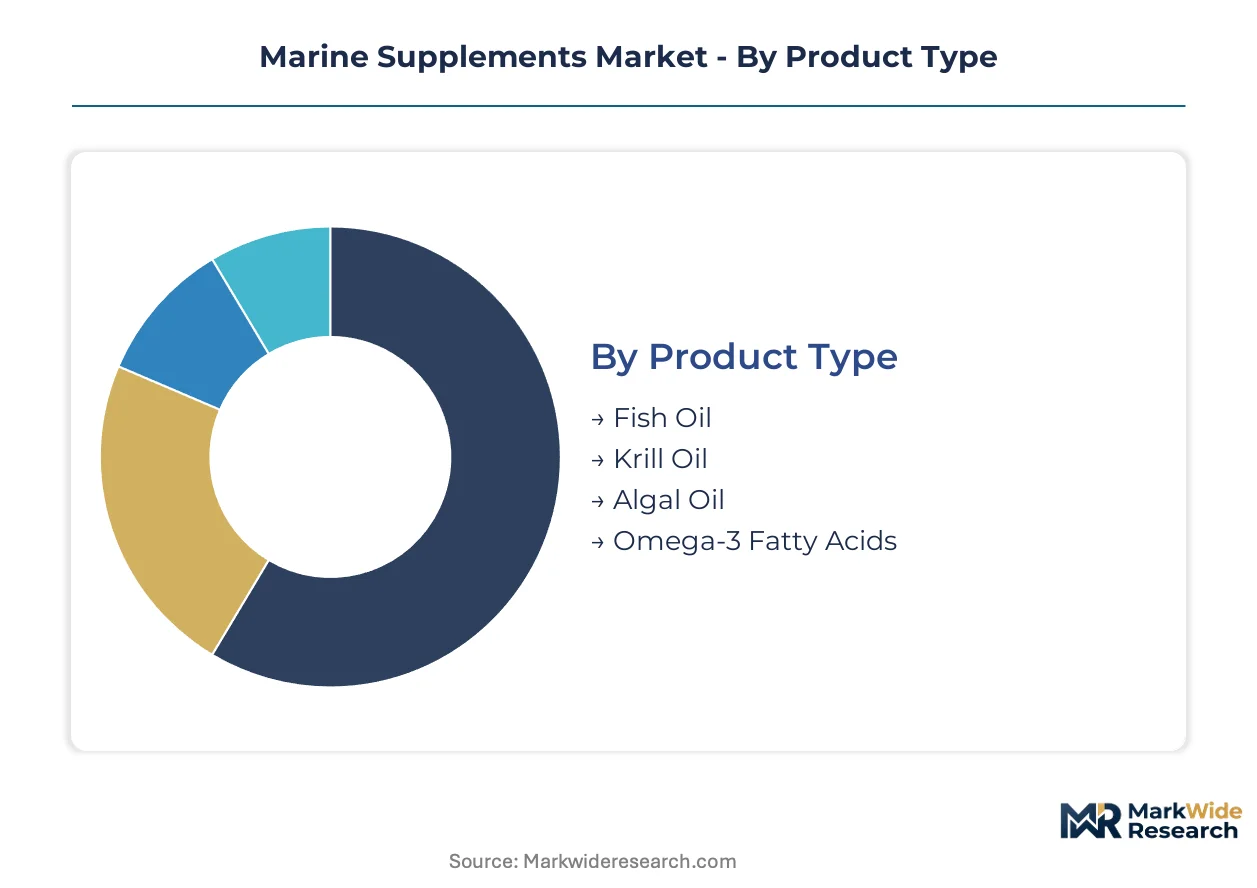
Marine supplement segmentation reveals how formulation chemistry, delivery mechanics, and end-use physiology intersect to create distinct procurement channels. Each dimension carries regulatory and margin implications that reshape competitive positioning across pharmacy, practitioner, and direct-to-consumer routes.
Product Type:
Integration depth varies sharply: fish oil functions as a standalone commodity input for bulk contract manufacturers, while krill and algal oils embed proprietary phospholipid or plant-based positioning into finished brand formulations.
- Fish Oil:Standardized EPA/DHA concentrates from anchovy, sardine, and mackerel biomass dominate volume procurement through Peru and Chile fishing cooperatives. Sports nutrition distributors in the United States and Germany compress margins through bulk concentrate tenders, while oxidative stability indices dictate shelf-life negotiations with retail pharmacy chains.
- Algal Oil:Photobioreactor-cultivated DHA from Schizochytrium and Crypthecodinium strains eliminates marine allergen exposure and satisfies vegan label claims. Israeli and Chinese cultivation facilities are collapsing unit costs, enabling parity pricing with mid-tier fish oil concentrates in European pharmacy networks.
- Krill Oil:Antarctic Euphausia superba extracts deliver phospholipid-bound omega-3s with superior bioavailability markers for practitioner-grade positioning.
- Omega-3 Fatty Acids:Refined EPA and DHA isolates serve pharmaceutical and medical food applications requiring precise dosing protocols.
Fish oil leads volumes today; algal oil is gaining share fastest.
End User:
Cost tier stratification separates premium practitioner-grade formulations from mass-market retail SKUs, with compliance tracking and personalized dosing creating subscription pricing power at the top.
- Fitness Enthusiasts:CrossFit boxes and boutique strength facilities stock omega-3 concentrates as inflammation management staples, bypassing traditional pharmacy markups through direct distributor relationships. Recovery protocol standardization drives bulk procurement of high-concentrate EPA formulations.
- Elderly:Cognitive function claims validated through EFSA authorization unlock premium pharmacy pricing in Germany and Australia, where BfArM and TGA oversight of telehealth prescribing accelerates direct-patient supplement dispensing.
- Pregnant Women:DHA-specific prenatal formulations require contaminant screening protocols that favor suppliers with captive analytical laboratories.
- General Population:Mass-market softgels compete on shelf price and enteric-coating premiums through retail pharmacy and grocery channels.
Fitness enthusiasts drive the steepest volume expansion; elderly consumers command the highest per-unit pricing.
Form:
Margin concentration tracks manufacturing complexity, with specialized coating equipment and dose-precision infrastructure creating defendable positions in clinical applications.
- Softgel:Enteric-coated gelatin and plant-based shells retain margin premiums through oxidative protection and dose accuracy for practitioner protocols. Specialized manufacturing lines require 18-24 month procurement cycles, constraining capacity expansion and protecting incumbent suppliers.
- Liquid:Flavored emulsions capture pediatric and geriatric compliance segments where swallowing difficulty limits solid dosage forms.
- Powder:Microencapsulated formats integrate into functional food matrices and sports nutrition ready-to-mix products.
- Capsule:Hard-shell gelatin and HPMC variants serve cost-sensitive retail segments with standard oxidative stability thresholds.
Softgel formats capture the highest margins; liquid formulations are climbing fastest in pediatric and geriatric channels.
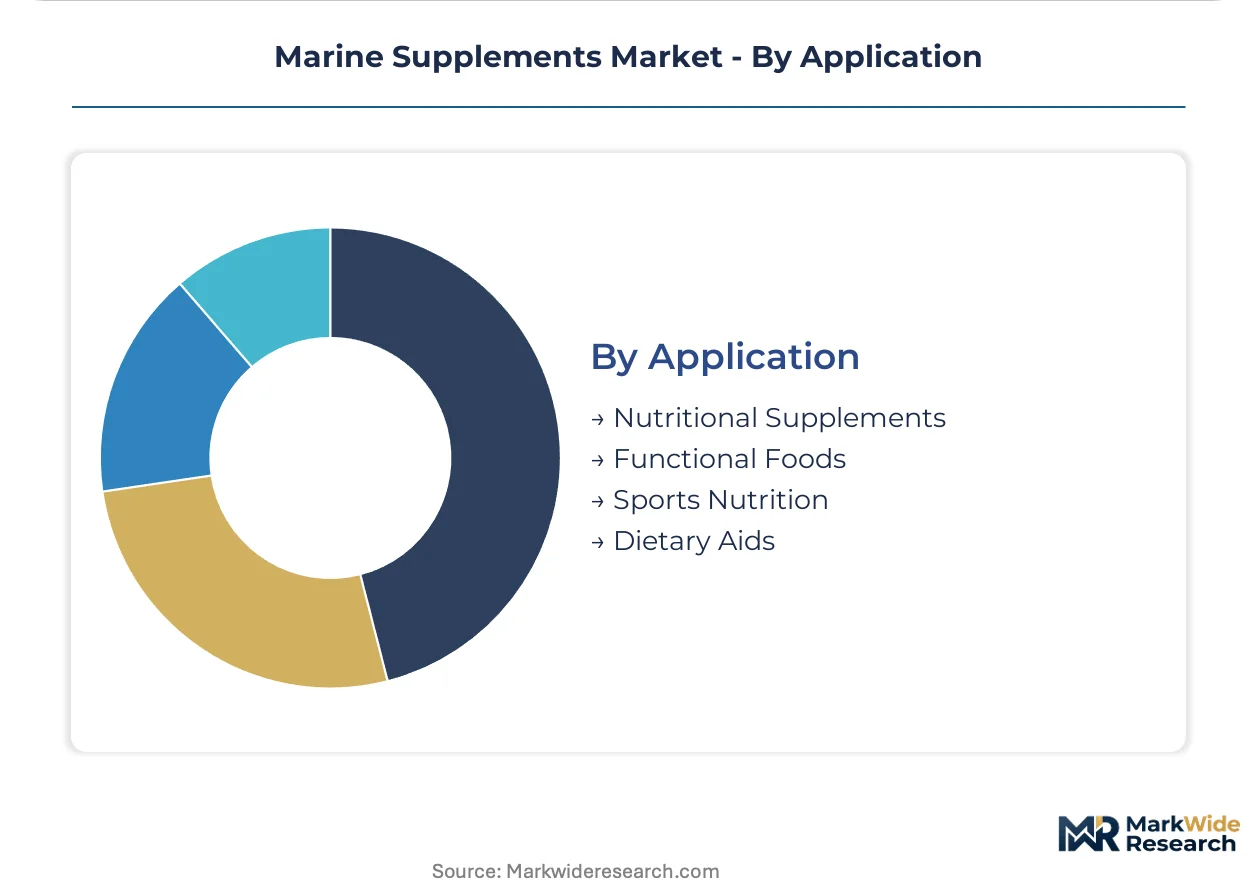
Application:
Supply concentration in China and India shapes where formulation value-add occurs, with raw concentrate exports dominating commodity flows and finished brand manufacturing clustering near consumer markets.
- Nutritional Supplements:Standalone omega-3 capsules and liquids constitute the mature volume base, with MSC certification and blockchain traceability creating differentiation in EU corporate wellness procurement.
- Sports Nutrition:Concentrated EPA/DHA powders and softgels integrate into recovery stacks sold through CrossFit boxes and direct-to-consumer subscription platforms, compressing traditional retail channel margins.
- Functional Foods:Microencapsulated algal and fish oils embed into dairy alternatives, infant formulas, and fortified beverages.
- Dietary Aids:Medical food positioning requires FDA or EFSA substantiation pathways that favor suppliers with in-house regulatory affairs capabilities.
Nutritional supplements anchor current volumes; sports nutrition is expanding most quickly as channel structures bypass pharmacy intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's aquaculture infrastructure processes more marine biomass than any other nation, yet Germany commands premium pricing through EFSA-authorized health claims that Chinese brands cannot yet replicate.
United States
CrossFit box proliferation and direct-to-consumer subscription platforms drive concentrated EPA procurement from sports nutrition distributors. FDA dietary supplement GMPs enforce oxidative stability testing protocols that favor suppliers with captive analytical laboratories. San Diego and Salt Lake City host contract manufacturing clusters where softgel enteric-coating capacity constrains expansion timelines.
Germany
BfArM oversight of telehealth prescribing accelerates direct-patient supplement dispensing through practitioner networks. EFSA cardiovascular and cognitive function authorizations unlock pharmacy premium pricing unavailable to non-validated competitors. Hamburg and Frankfurt concentrate pharmaceutical-grade GMP infrastructure for medical food positioning.
China
Domestic photobioreactor cultivation of Schizochytrium strains collapses algal oil unit costs below imported fish oil concentrates. SAMR food safety regulations and dual carbon goals reshape aquaculture energy inputs. Qingdao and Dalian anchor processing clusters where vertical integration from biomass to finished softgel compresses supply chain handlers.
Australia
TGA oversight of therapeutic goods creates practitioner-grade entry barriers that Blackmores exploits through pharmacy channel dominance. Cognitive function claims for elderly consumers command per-unit pricing premiums above mass-market softgels. Sydney and Melbourne concentrate compounding pharmacy networks where batch-level certificate of analysis access displaces paper documentation.
India
Ayurvedic integrative medicine clinics represent unserved demand for high-concentrate EPA formulations in metabolic syndrome management. FSSAI nutraceutical regulations tighten contaminant screening thresholds that favor suppliers with in-house testing infrastructure. Mumbai and Ahmedabad host formulation facilities serving domestic brands and export markets.
Marine Supplements Market Competitive Landscape
Nordic and North American producers anchor one tier; Chinese cultivation specialists hold cost-advantaged supply positions. The vendor base stratifies across three tiers: multinational brand houses with pharmacy networks, contract manufacturers with GMP-certified softgel capacity, and algal oil innovators with photobioreactor assets. Strategic archetypes include practitioner-grade positioning specialists, private-label scale operators, and vegan-claim pure-plays. Competitive moves concentrate on MSC certification acquisition for EU market access and photobioreactor capacity expansion for algal oil cost parity.
Within the multinational brand tier, Nordic Naturals and Blackmores occupy positions defined by geographic channel dominance and regulatory authorization depth. NOW Foods exemplifies the private-label scale archetype through manufacturing flexibility across multiple delivery formats. California Gold Nutrition represents direct-to-consumer platform positioning that bypasses traditional pharmacy intermediaries entirely.
| Leading Market Players |
|---|
| Blackmores |
| Nature's Bounty |
| Nordic Naturals |
| California Gold Nutrition |
| NOW Foods |
| Amway |
| Nature Made |
| GNC Holdings |
| Herbalife Nutrition |
| Others |
Value Network & Pricing Analysis
Family-owned Peruvian and Chilean fishing cooperatives anchor raw material supply for fish oil concentrates, their collective bargaining power translating directly into concentrate pricing floors that contract manufacturers struggle to compress. Sovereign-backed Chinese algal oil producers are disrupting this equilibrium through photobioreactor scale-up, collapsing DHA production costs and forcing legacy fish oil refiners into defensive margin restructuring.
Pricing Analysis
Capacity additions in China and Israel are reshaping price floors for algal DHA, collapsing the traditional premium over mid-tier fish oil concentrates. Three-tier pricing structure across practitioner-grade, pharmacy-standard, and mass-market economy levels separates MSC-certified concentrates with blockchain traceability from commodity bulk tenders. Pricing pressure stems from sports nutrition distributors consolidating procurement through direct-to-consumer platforms that bypass retail markup layers. Fitness enthusiasts and CrossFit box operators exhibit highest price sensitivity, while functional medicine clinics and compounding pharmacies absorb practitioner-grade premiums for batch-level certificate of analysis access.
Supply Chain Analysis
Dual-sourcing qualification requirements now mandate that finished brand manufacturers qualify both South Pacific fish oil cooperatives and Chinese algal oil cultivators to mitigate harvest volatility. Raw material supply concentrates in Peru, Chile, and China, with Antarctic krill extraction adding Norwegian and South Korean processing nodes. The supply chain draws from anchovy and sardine biomass, Schizochytrium algal strains, and Euphausia superba krill as primary inputs. Single-source vulnerability concentrates around the three dominant Peruvian fishing cooperatives controlling South Pacific anchovy harvests. Distribution runs through sports nutrition distributors, practitioner networks, and direct-to-consumer subscription platforms in parallel channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
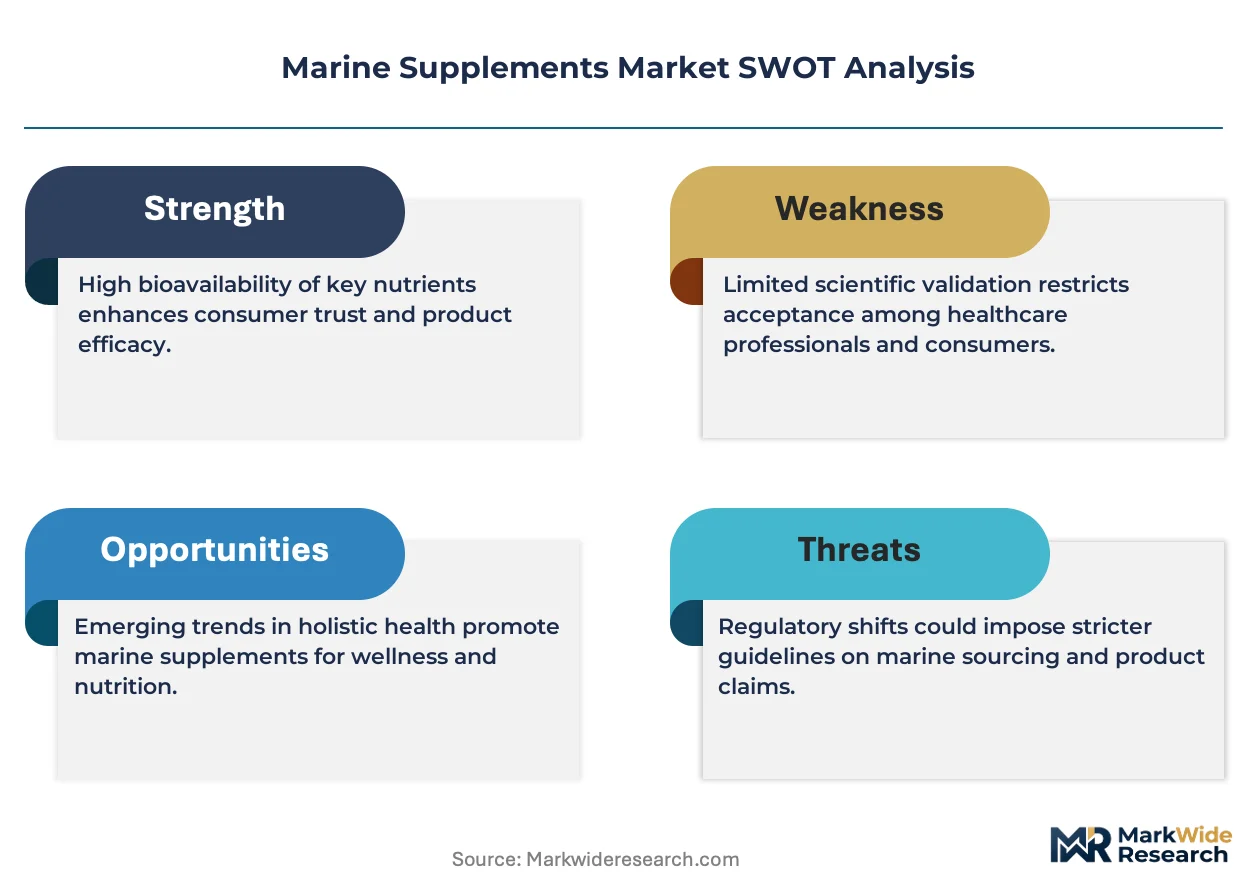
Marine supplements represent a margin-expansion story as photobioreactor technology collapses algal oil production costs and practitioner-grade certification creates defendable premium tiers. The shift from commodity fish oil concentrates to validated health claim formulations concentrates pricing power with suppliers possessing captive analytical infrastructure.
For Market Incumbents: Acquire photobioreactor cultivation assets in China or Israel to secure non-GMO DHA supply chains and neutralize cost advantages held by sovereign-backed algal oil specialists. Defend practitioner-grade positioning through EFSA and FDA medical food substantiation investments that emerging competitors cannot replicate without six-figure toxicology dossier expenditures. Deepen backward integration into Antarctic krill harvesting concessions to lock phospholipid-bound omega-3 supply against Norwegian and South Korean processor consolidation.
For New Entrants and Emerging Players: The price-point gap between premium practitioner-grade formulations and economy mass-market softgels creates white-space opportunity for mid-tier algal oil brands with vegan certification parity. Target India's Ayurvedic integrative medicine clinics with high-concentrate EPA formulations for metabolic syndrome protocols, an unserved demand pocket where FSSAI regulations favor domestic formulation facilities. Deploy direct-to-consumer subscription models integrating microbiome testing with personalized dosing to bypass entrenched pharmacy channel intermediaries entirely.
For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with GMP-certified softgel capacity but lacking captive raw material sourcing, creating roll-up opportunity for private equity platforms. Long-term viability across the analysis window hinges on MSC certification and blockchain traceability infrastructure as EU CSRD disclosure mandates harden. Watch for inflection in state-level wild-caught fishmeal sustainability restrictions that would accelerate feedstock substitution toward algal cultivation.
| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Capacity Expansion | Chinese and Israeli cultivation scale-up collapses algal DHA unit costs below imported fish oil parity. |
| MSC Certification Acquisition | Chain-of-custody standards unlock EU pharmacy network access and corporate wellness procurement channels. |
| Practitioner Channel Partnership | BfArM and TGA telehealth prescribing acceleration enables direct-patient supplement dispensing in Germany and Australia. |
| Blockchain Traceability Infrastructure | EU CSRD supply chain disclosure mandates create competitive differentiation for verified sustainable sourcing. |
| Enteric Coating Capacity Addition | Specialized softgel manufacturing lines with 18-24 month procurement cycles constrain competitor expansion timelines. |
Research Methodology
Multiple input streams — primary interviews with sports nutrition procurement directors, functional medicine clinic operators, and algal oil cultivation specialists; secondary validation through EFSA health claim registers, FDA dietary supplement GMP inspection records, and Marine Stewardship Council chain-of-custody databases; trade flow analysis from customs declarations — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured formulation preferences across delivery formats and oxidative stability thresholds. Secondary sources included regulatory filing databases, practitioner dispensing platform disclosures, and photobioreactor technology patent landscapes.
Historical volume trajectories were cross-referenced against panel input from contract manufacturing executives and ingredient sourcing managers to construct analytical framework projections. Segmentation dimensions modeled include product type chemistry, end-user physiology, delivery form manufacturing complexity, and application channel structure across the projection horizon. CAGRs were derived from fitted growth curves incorporating EFSA authorization timelines, CrossFit facility expansion rates, and algal oil cost parity milestones. Forecast inputs captured SAMR food safety regulatory evolution and EU corporate sustainability reporting mandate implementation phasing.
The model assumes a particular technology adoption path; alternative pathways for closed-loop photobioreactor automation would alter the outlook for algal oil cost compression timelines. Forecasts reflect assumptions regarding EFSA health claim authorization velocity and Antarctic krill harvest quota stability. Deviation in Peruvian anchovy biomass assessments or Chinese dual carbon policy enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Psyllium-Based Supplement Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
North America Digestive Health Supplements Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Prenatal Vitamin Supplements Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
India Whey Protein Market
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
Asia-Pacific Beta-Glucan Market
Nutritional Supplements
Water Soluble Vitamin and Mineral Feed Supplements Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
Grass-Fed Collagen Market