
 Prickly Pear Seed Oil Nutricosmetic Bases Market | 2026-2036
Prickly Pear Seed Oil Nutricosmetic Bases Market Size, Share, and Industry Trends Forecast 2026-2036
Prickly Pear Seed Oil Nutricosmetic Bases Market Insights
EU REACH compliance on botanical cold-press extraction is broadening the cost-of-entry calculus for new entrants into nutricosmetic bases. ZineGlob leverages its Moroccan sourcing infrastructure to sustain supply continuity for European formulators. BIOVALLEY anchors its position through certified organic extraction protocols that navigate evolving EU cosmetic ingredient standards. NOPAL TUNISIE competes via integrated cultivation-to-oil operations that control raw material quality across North African supply corridors.
Prickly Pear Seed Oil Nutricosmetic Bases comprise cold-pressed oil extracts and formulated emulsions derived from Opuntia ficus-indica seeds, typically containing linoleic acid concentrations exceeding 60% alongside antioxidant vitamin E complexes for dermal barrier restoration. These bases serve as active carriers in topical nutricosmetic applications targeting cellular repair and lipid-layer reinforcement. Oil extracts dominate current revenue contribution due to premium positioning in professional channels, while serums represent the fastest-expanding category as dermatology clinics adopt concentrated delivery formats. Emulsions occupy the mass-access tier through pharmacy and specialty store distribution, where margin pools concentrate in preservative-free and cold-process variants.
EMA guidelines on cosmetic-drug boundary classifications intersect with EU REACH substance registration requirements to reshape product claims and labeling obligations for nutricosmetic marketers. France's ANSM enforces additional post-market surveillance protocols that elevate compliance costs for imported seed oil bases. Stakeholders must monitor pending EU Green Deal derivatives affecting botanical sourcing traceability and carbon footprint disclosure thresholds.
Market Dynamics
EU REACH substance registration requirements on botanical cold-press extraction are restructuring entry barriers for nutricosmetic base formulators, forcing capital reallocation toward certified organic protocols and traceable North African sourcing infrastructure.
Growth Catalysts
- Clean-label dermatology protocols:European dermatology clinics now mandate preservative-free, cold-process oil bases for post-procedure barrier repair, creating pull-through demand for high-linoleic prickly pear formulations.
- EU Green Deal traceability mandates:Carbon footprint disclosure requirements for botanical ingredients are accelerating investment in integrated cultivation-to-extraction operations with verified supply chain documentation.
- Sonomechanical extraction advancement:Ultrasound-assisted cold-press technologies are reducing seed oil yield losses below 8% while preserving vitamin E complex integrity, improving unit economics for premium positioning.
Market Restraints
- Opuntia ficus-indica supply concentration:Raw material availability clusters in Moroccan and Tunisian cultivation belts, exposing formulators to climate volatility and geopolitical friction across North African trade corridors.
- Seed-to-oil yield constraints:Mechanical extraction from prickly pear seeds achieves maximum 5% oil recovery versus 40-50% for conventional nut oils, structurally elevating feedstock costs per liter of finished base.
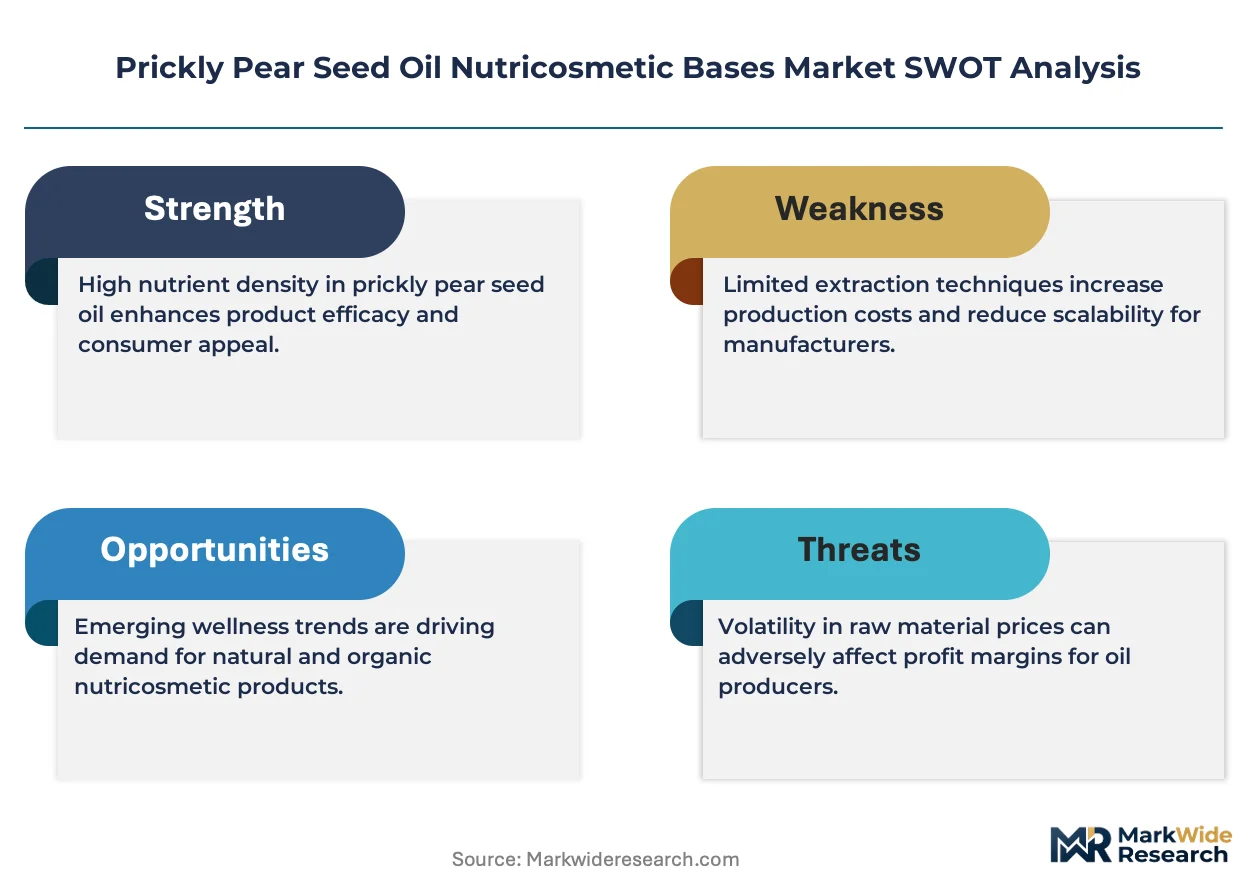
- EMA cosmetic-drug boundary ambiguity:Regulatory uncertainty around cellular repair claims forces conservative labeling that constrains premium positioning and professional channel penetration.
Strategic Opportunities
- Underpenetrated South Korean nutricosmetic channel:K-beauty retailers are expanding clean-ingredient topical lines, creating first-mover advantage for EU-certified organic oil bases with documented antioxidant profiles.
- Pharmacy-direct distribution innovation:Bypassing traditional cosmetic wholesalers through pharmacist-education programs captures margin pools in European markets where dermal barrier restoration claims carry clinical credibility.
- CSRD sustainability reporting convergence:Mandatory EU corporate sustainability disclosures are creating procurement preference for suppliers with verified biodiversity-positive cultivation practices and water-efficient extraction.
Industry Challenges
- Organic certification timeline compression:EU 2018/848 regulation transition periods are forcing rapid recertification of existing North African cultivation sites, creating 12-18 month supply gaps for non-compliant operators.
- Skilled extraction technician scarcity:Cold-press operation expertise specific to heat-sensitive botanical matrices remains concentrated in traditional Mediterranean processing centers, limiting geographic expansion of production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prickly Pear Seed Oil Nutricosmetic Bases Market |
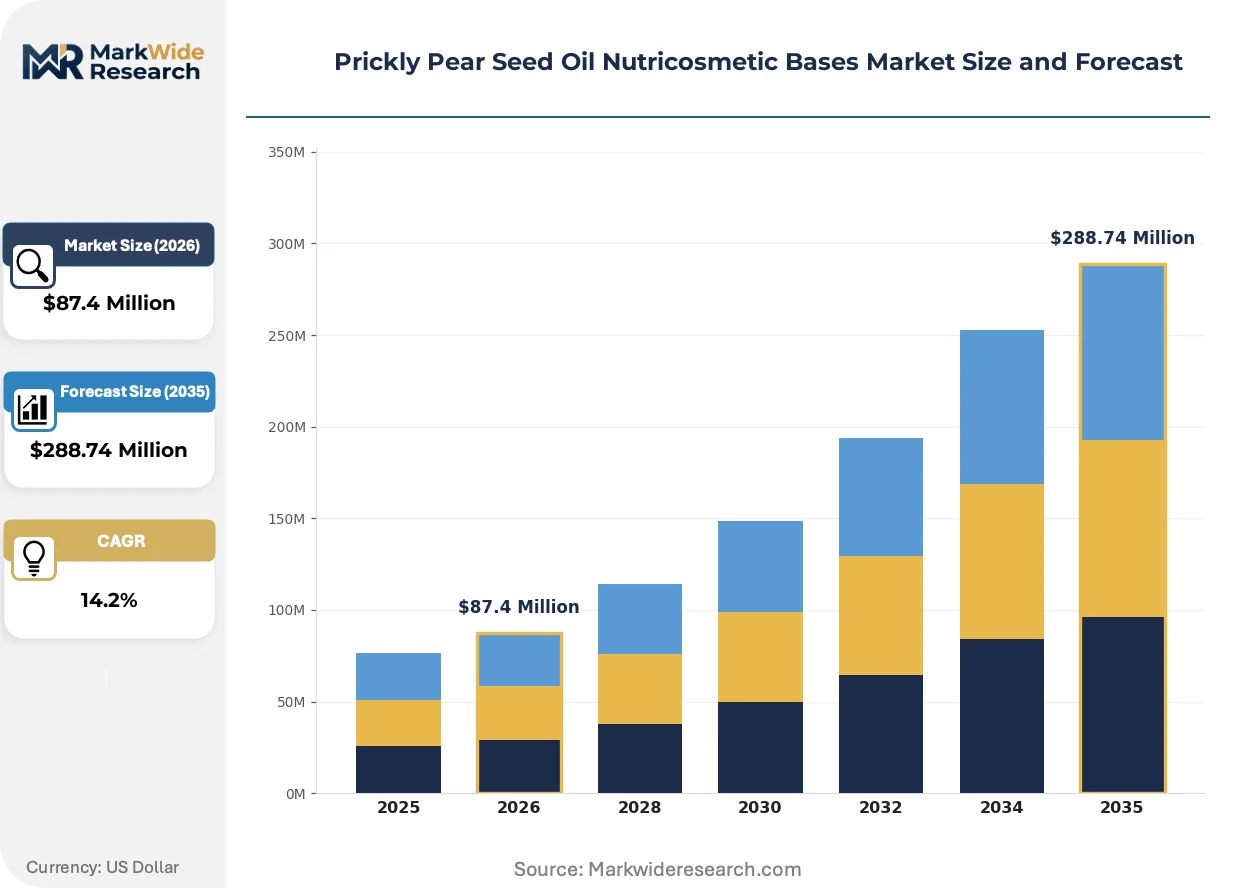
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $288.74 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil Extracts, Emulsions, Powders, Concentrates, Serums Application: Skin Brightening, Anti-Aging, Hydration Enhancement, UV Protection, Anti-Inflammatory End User: Beauty Salons, Wellness Centers, Dermatology Clinics, Spa Chains, Home Care Users Distribution Channel: Online Retailers, Specialty Stores, Pharmacies, Direct Sales, Health Food Shops |
| Companies Covered | ZineGlob, BIOVALLEY, NOPAL TUNISIE, Biopur, Biolissime, BioNatal, Bionoble, Arad Cosmetics, Aromatics International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prickly Pear Seed Oil Nutricosmetic Bases Market Trends and Innovations
Formulation science is converging with regulatory transparency demands to reshape how prickly pear seed oil bases are positioned, processed, and procured across professional and retail channels.
Supercritical CO2 extraction with ethanol co-solvent modification is absorbing market share from conventional mechanical pressing among premium serum manufacturers seeking tocopherol retention above 95%. French pharmacy chains are adopting this technology for in-house private label development. The shift is compressing margins for legacy cold-press equipment suppliers while creating specification divergence between professional-grade and mass-market product tiers.
France's ANSM post-market surveillance protocols are tightening adverse event reporting requirements for nutricosmetic products with barrier restoration claims. Formulators must now maintain batch-level traceability documentation extending to seed provenance. The regulatory friction is elevating compliance costs most acutely for small-scale importers lacking integrated cultivation relationships.
Buyer concentration among European dermatology clinic networks is consolidating procurement decisions into centralized formulary committees with mandatory ISO 16128 natural origin certification. Independent aesthetic practitioners are losing direct supplier relationships as purchasing shifts to group purchasing organizations with audited supply chain requirements. This pattern is most visible in German-speaking markets where clinic chain consolidation has accelerated since 2023.
Prickly Pear Seed Oil Nutricosmetic Bases Market Segmentation
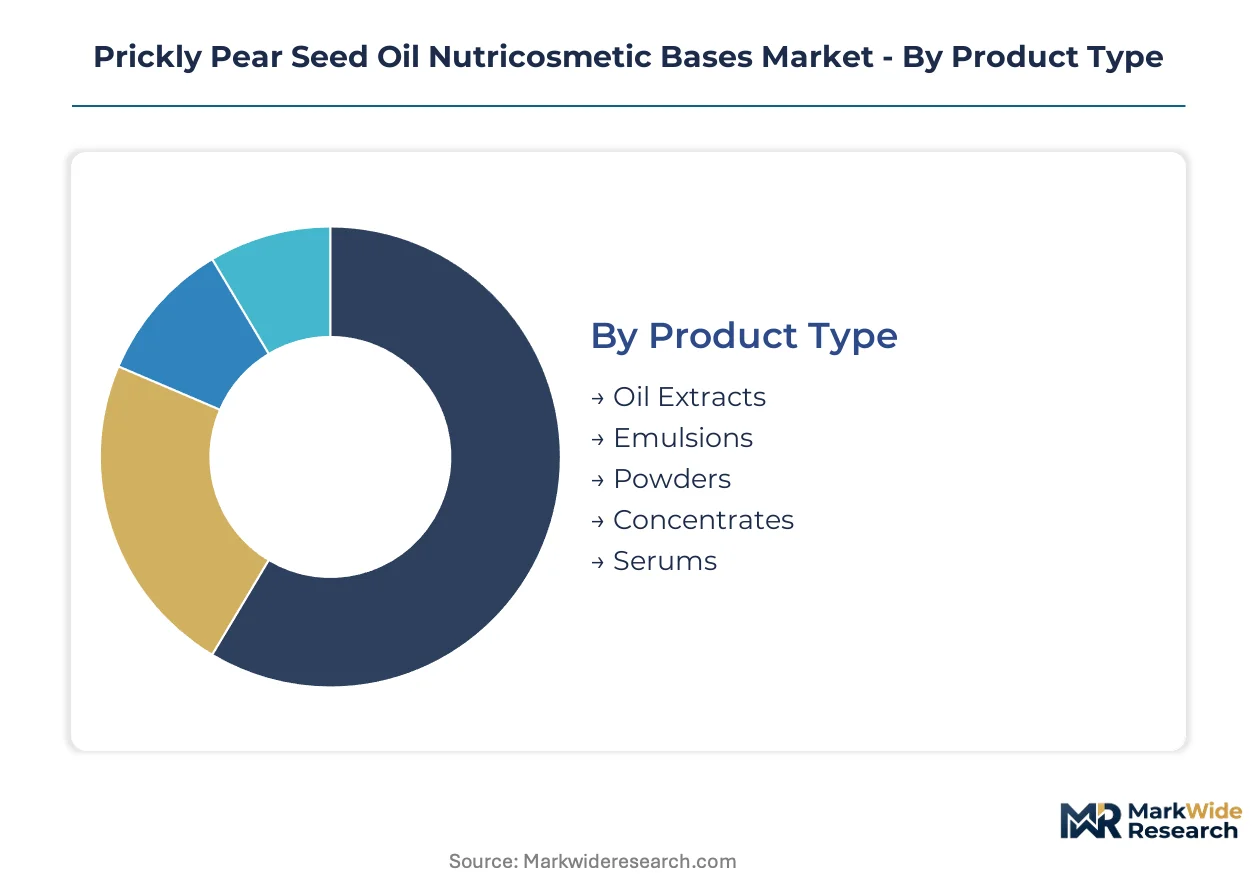
Segmentation in prickly pear seed oil nutricosmetic bases reflects divergent buyer priorities across professional versus retail channels. Formulators must align product specifications with channel-specific compliance requirements and margin structures.
Product Type:
Professional buyers prioritize bioactive integrity over unit cost, driving specification divergence across extraction and delivery formats.
- Oil Extracts:Cold-pressed unrefined bases containing linoleic acid above 60% serve dermatology clinics requiring post-procedure barrier restoration. Demand clusters in French pharmacy chains where ANSM traceability protocols mandate batch-level seed provenance documentation.
- Serums:Concentrated delivery systems with enhanced tocopherol stability target professional aesthetic channels. German clinic networks adopting centralized formulary committees are expanding procurement of ISO 16128-certified serum formats.
- Emulsions:Mass-access carriers for retail pharmacy distribution.
- Powders:Lyophilized formats for cosmetic manufacturer compounding.
- Concentrates:Bulk inputs for private label formulation houses.
Volume sits with Oil Extracts; growth tilts toward Serums.
Application:
Claim substantiation requirements vary sharply across functional positioning, reshaping formulation investment and regulatory exposure.
- Anti-Aging:Cellular repair positioning faces EMA cosmetic-drug boundary scrutiny, forcing conservative label claims. French formulators navigate ANSM post-market surveillance through restricted active concentration thresholds.
- Hydration Enhancement:Lipid barrier reinforcement claims carry lower regulatory risk. Moroccan-sourced bases penetrate German pharmacy channels where clinical credibility supports premium positioning.
- Skin Brightening:Tone-evening applications with antioxidant mechanisms.
- UV Protection:Photoprotective adjunct positioning in nutricosmetic protocols.
- Anti-Inflammatory:Post-procedure soothing for aesthetic clinic protocols.
Revenue concentrates in Anti-Aging; regulatory safety favors Hydration Enhancement.
End User:
Procurement centralization is consolidating supplier relationships across institutional channels while fragmenting retail access.
- Dermatology Clinics:Preservative-free, cold-process specifications dominate purchasing criteria. German-speaking clinic chains have shifted to group purchasing organizations with audited supply chain requirements since 2023.
- Beauty Salons:Mid-tier professional users seek efficacy documentation without clinical-grade compliance costs.
- Wellness Centers:Holistic positioning channels with organic certification requirements.
- Spa Chains:Experience-driven procurement prioritizing sensory attributes.
- Home Care Users:Retail-accessible segments through pharmacy and specialty store channels.
Margin pools concentrate in Dermatology Clinics; volume expansion targets Home Care Users.
Distribution Channel:
Channel selection determines compliance burden, margin retention, and buyer education requirements.
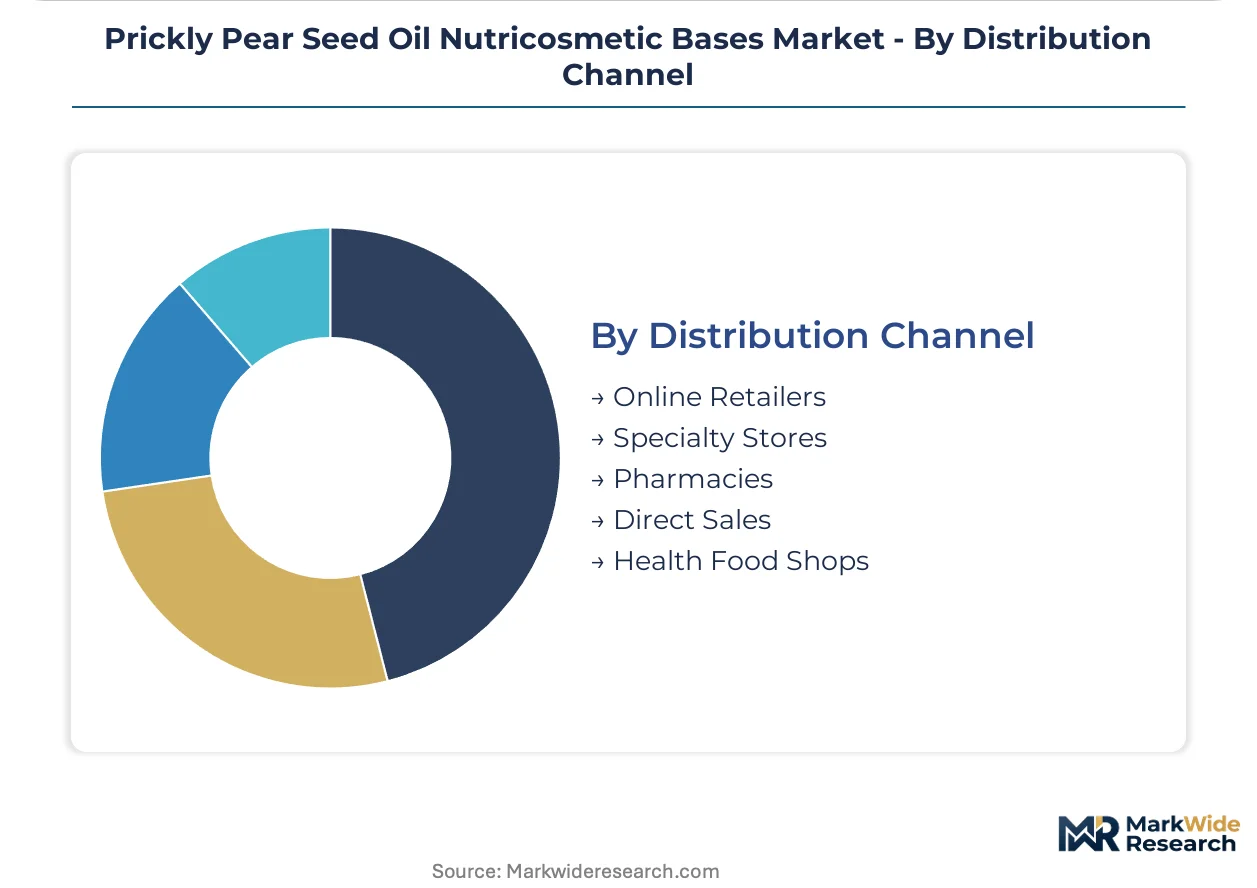
- Pharmacies:Pharmacist-mediated distribution captures clinical credibility premiums in French and German markets. EU REACH documentation requirements elevate barriers for non-integrated suppliers.
- Specialty Stores:Curated retail environments with staff training on botanical ingredient provenance.
- Online Retailers:Direct-to-consumer growth constrained by Green Deal traceability disclosure requirements.
- Direct Sales:Practitioner-exclusive channels for professional-grade formulations.
- Health Food Shops:Organic-certified positioning for wellness-oriented consumers.
Compliance costs peak in Pharmacies; digital expansion runs through Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and Morocco concentrate procurement decisions for prickly pear seed oil nutricosmetic bases, with European dermatology clinics and North African cultivation clusters forming an integrated demand-supply corridor.
France
ANSM post-market surveillance protocols drive preservative-free formulation demand among Paris-based dermatology clinic chains. EMA cosmetic-drug boundary classifications constrain cellular repair claims, forcing conservative label strategies. Grasse extraction specialists and Lyon pharmacy distribution hubs anchor the professional channel infrastructure.
Morocco
Agadir and Marrakech cultivation belts supply cold-pressed oil extracts to European formulators under EU REACH substance registration requirements. Organic certification transitions under EU 2018/848 regulation compress recertification timelines for traditional cooperatives. Casablanca logistics corridors handle bulk exports to German pharmacy chains.
Germany
Munich and Hamburg dermatology clinic networks consolidate procurement through group purchasing organizations with ISO 16128 natural origin certification mandates. CSRD sustainability reporting requirements elevate preference for suppliers with verified biodiversity-positive cultivation documentation. Berlin-based formulators specialize in serum concentration technologies.
Tunisia
Sfax and Sousse processing centers compete via integrated cultivation-to-oil operations controlling raw material quality across North African supply corridors. EU Green Deal traceability mandates accelerate investment in carbon footprint disclosure systems. Tunis laboratories develop sonomechanical extraction protocols for vitamin E complex preservation.
South Korea
Seoul K-beauty retailers expand clean-ingredient topical lines, creating first-mover opportunity for EU-certified organic oil bases with documented antioxidant profiles. MFDS cosmetic safety standards align with European regulatory frameworks. Busan import channels handle bulk procurement for domestic formulation houses.
Prickly Pear Seed Oil Nutricosmetic Bases Market Competitive Landscape
Moroccan producers anchor the integrated cultivation tier; European specialists hold the certified organic extraction segment. Market structure tilts toward geographic specialization rather than scale consolidation, with mid-cap operators controlling critical North African supply infrastructure. Three archetypes dominate: integrated cultivator-extractors, certified organic protocol specialists, and pharmacy-channel formulators. Capacity expansion in ultrasound-assisted cold-press technology and backward integration into seed cultivation represent the primary competitive vectors.
Within the integrated cultivator-extractor tier, ZineGlob exemplifies Moroccan sourcing infrastructure leveraged for European supply continuity. BIOVALLEY occupies a position among certified organic protocol specialists navigating EU cosmetic ingredient standards. NOPAL TUNISIE anchors the North African integrated operations archetype, with Biopur and Biolissime representing European formulators competing through pharmacy-direct distribution models. These five entities collectively illustrate the geographic and regulatory specialization patterns defining competitive positioning.
| Leading Market Players |
|---|
| ZineGlob |
| BIOVALLEY |
| NOPAL TUNISIE |
| Biopur |
| Biolissime |
| BioNatal |
| Bionoble |
| Arad Cosmetics |
| Aromatics International |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon footprint disclosure thresholds gate qualified supply access for European formulators while stratifying pricing tiers between traceable North African sources and uncertified alternatives. ANSM batch-level traceability mandates in France compress procurement options for dermatology clinic networks, elevating premium-tier pricing power for integrated cultivator-extractors with documented seed provenance.
Pricing Analysis
Short lead-time premiums of 15-25% apply to cold-pressed oil extracts with sub-30-day delivery windows to German pharmacy chains, while spot inventory of uncertified Moroccan-origin bases trades at discounted levels. Three-tier pricing structure separates ISO 16128-certified organic extracts for professional dermatology channels from standard-grade emulsions for retail pharmacy distribution and economy-tier bulk concentrates for cosmetic manufacturer compounding. Cost compression in the standard tier is intensifying because Tunisian processors are expanding sonomechanical extraction capacity, eroding legacy cold-press equipment margins. Home care users through online retail channels exhibit highest price sensitivity, whereas French clinic networks purchasing through group buying organizations demonstrate lowest elasticity due to formulary compliance requirements.
Supply Chain Analysis
EU 2018/848 organic certification timelines gate supplier qualification, forcing 12-18 month recertification cycles that eliminate non-compliant Moroccan cooperatives from European procurement pools. Raw material availability clusters in Morocco, Tunisia, and Algeria, with Agadir and Marrakech cultivation belts feeding Casablanca extraction facilities and Sfax processing centers serving European bulk buyers. Feedstock supply draws from Opuntia ficus-indica fruit pulp byproduct streams, mechanical pressing equipment, and lyophilization capacity for powder formats. Single-source vulnerability concentrates in Moroccan cultivation belts exposed to Sahel drought patterns. Distribution runs through Lyon pharmacy distribution hubs and Berlin-based serum formulators for professional channels, with direct bulk export contracts bypassing traditional cosmetic wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated cultivation-extraction capabilities, with EU REACH compliance costs forcing sub-scale importers toward exit or acquisition. Organic certification timeline compression and centralized formulary procurement are accelerating this structural pressure.
For Market Incumbents: To counter centralized formulary procurement by German clinic networks, anchor market position through backward integration into Moroccan seed cultivation with EU 2018/848-compliant documentation and expand ultrasound-assisted cold-press capacity in Agadir processing corridors. Channel control through pharmacist-education programs in France captures margin pools where dermal barrier restoration claims carry clinical credibility.
For New Entrants and Emerging Players: MFDS cosmetic safety standards in South Korea open a window for EU-certified organic oil bases with documented antioxidant profiles, targeting Seoul K-beauty retailers expanding clean-ingredient topical lines. Pharmacy-direct distribution innovation in underpenetrated German-speaking markets bypasses consolidated wholesale channels, while sonomechanical extraction technology licensing from Tunis laboratories enables rapid capability acquisition without proprietary R&D investment.
For Investors and Strategic Acquirers: Completion of EU 2018/848 recertification by Moroccan cooperatives is the leading indicator that supply-constraint pricing power will shift toward certified operators. The 5-10 year viability window favors acquisition of integrated cultivator-extractors with ANSM-traceable supply chains over standalone extraction technology plays. Watch for ANSM adverse event reporting spikes in barrier restoration claims as a signal that regulatory enforcement is tightening claim substantiation requirements, elevating compliance costs for undifferentiated competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Cultivation | EU 2018/848 certification secures supply continuity for ANSM-traceable pharmacy channels. |
| Ultrasound-Assisted Cold-Press Capacity Expansion | Sonomechanical extraction preserves vitamin E complexes above 95% for premium serum positioning. |
| Pharmacist-Education Program Deployment | Clinical credibility capture in French pharmacy chains bypasses consolidated cosmetic wholesalers. |
| Organic Certification Recertification Acceleration | EU REACH substance registration compliance eliminates non-compliant North African competitors. |
| Seoul K-Beauty Retail Partnership | MFDS-aligned EU-certified bases penetrate underpenetrated South Korean nutricosmetic channels. |
Research Methodology
Independent corroboration across extraction technology specialists, dermatology clinic procurement directors, and Moroccan cooperative managers underwrites the qualitative findings on supply chain concentration and pricing stratification. Primary interviews with French pharmacy chain formulary committees, Tunisian processing facility engineers, and German group purchasing organization contract managers combined with secondary validation from EMA cosmetic-drug boundary guidance documents, ANSM post-market surveillance protocols, and EU REACH substance registration databases. Bottom-up triangulation across cultivation belt yield estimates and top-down reconciliation against pharmacy channel procurement volumes anchors volume and value outputs.
Rate-of-change decomposition across product type (oil extracts, serums, emulsions, powders, concentrates), application positioning (anti-aging, hydration enhancement, skin brightening, UV protection, anti-inflammatory), and end-user channel (dermatology clinics, beauty salons, wellness centers, spa chains, home care users) structures the analytical framework over the projection horizon. CAGRs derive from segment-level growth pattern analysis calibrated to EU Green Deal traceability mandate implementation timelines and sonomechanical extraction technology diffusion curves. Industry-specific inputs include Opuntia ficus-indica seed-to-oil yield constraints and ANSM batch-level documentation compliance cost trajectories.
The model assumes a particular technology adoption path for ultrasound-assisted cold-press extraction; alternative pathways for supercritical CO2 with ethanol co-solvent modification would alter the outlook toward premium serum concentration tiers. Forecasts reflect assumptions on EU 2018/848 recertification completion rates and Moroccan cultivation belt climate stability. A model refresh is warranted upon material change in EMA cosmetic-drug boundary enforcement intensity or ANSM adverse event reporting threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Asia Pacific Nutritional Supplements Market
Nutritional Supplements
Sports Food Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Ketogenic Diet Food Market
Nutritional Supplements
Digestive Enzyme Complex Market
Nutritional Supplements
Global Protein Market
Nutritional Supplements
South Africa Collagen Peptides Market
Nutritional Supplements
Algae Omega Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
Royal Jelly Market
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Europe Meal Replacement Products Market