
 Marine Peptides Market | 2026-2036
Marine Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Peptides Market Analytics
Software-defined formulation services is shifting how marine peptide suppliers monetize their offerings, moving beyond bulk ingredient sales toward subscription-based bioactivity profiling and custom peptide sequencing. Gelita AG leverages its gelatin expertise to anchor premium marine collagen supply chains across European cosmetic and pharmaceutical channels. Aker BioMarine dominates Antarctic krill-derived peptide production, sustaining vertical control from sustainable harvesting to omega-3 peptide concentrates. Rousselot differentiates through specialized fish collagen hydrolysates for medical nutrition and wound care segments.
Marine peptides are short-chain amino acid sequences, typically 2-20 residues, extracted through enzymatic hydrolysis of marine proteins and characterized by molecular weights below 10 kDa, bioactive properties including antioxidant, antihypertensive, and antimicrobial functions, and primary use in functional foods, cosmeceuticals, and therapeutic formulations. Collagen peptides from fish sources command the largest revenue pool due to established demand in anti-aging skincare and joint health applications, while antioxidant peptides derived from seaweed hydrolysates represent the fastest-expanding category as clean-label preservation replaces synthetic alternatives in food systems. The nutraceuticals application segment absorbs disproportionate R&D investment as clinical validation of marine bioactives intensifies, though food and beverage remains the volume anchor through fortified dairy and sports nutrition products.
FDA GRAS notifications and EFSA novel food approvals govern marine peptide entry into US and European food systems, with REACH compliance adding sourcing traceability burdens for European manufacturers. Japan's PMDA and FOSHU framework accelerates functional food peptide commercialization through streamlined health claim pathways, while China's NMPA and GB standards impose stringent purity thresholds on marine-derived pharmaceutical ingredients. Stakeholders must monitor evolving regulatory divergence between jurisdictions where marine biotech innovation outpaces harmonized safety standards, particularly as CRISPR-assisted peptide engineering and precision fermentation alternatives challenge traditional extraction economics.
Market Dynamics
Enzymatic hydrolysis automation is compressing production economics for marine peptide suppliers, forcing capital reallocation toward continuous-flow bioreactors and real-time bioactivity monitoring systems that reshape competitive moats around extraction efficiency rather than raw material access.
Growth Catalysts
- Japan's FOSHU framework:Streamlined health claim pathways accelerate functional food commercialization, reducing time-to-market for bioactive peptide formulations by establishing pre-approved ingredient categories.
- Sports nutrition fortification:Recovery-focused formulations drive peptide incorporation into protein bars and ready-to-drink beverages, with marine collagen hydrolysates replacing bovine sources for clean-label positioning.
- Precision fermentation:Microbial production of peptide sequences eliminates seasonal biomass dependency, enabling year-round supply consistency for pharmaceutical-grade applications.
Market Restraints
- Wild-catch supply volatility:Antarctic krill harvesting quotas fluctuate with CCAMLR conservation assessments, constraining raw material predictability for omega-3 peptide producers.
- REACH traceability burdens:ECHA documentation requirements for marine sourcing add compliance overhead that disproportionately impacts small-scale European processors lacking dedicated regulatory teams.
- Plant protein substitution:Fermented legume and algae-derived peptides capture clean-label market share in cosmetic applications where marine origin carries consumer perception risks.
Strategic Opportunities
- Brazil's ANVISA pathway:Underdeveloped regulatory precedent for marine bioactives creates first-mover advantage for firms establishing local clinical validation partnerships.
- Wound care medical devices:Collagen peptide integration into advanced dressings addresses chronic wound management, a segment with limited marine-derived competition.
- CRISPR-assisted engineering:Directed evolution of peptide sequences amplifies bioactivity beyond natural extraction limits, opening therapeutic applications previously inaccessible to marine sources.
Industry Challenges
- Peptide characterization expertise:Shortage of analytical chemists proficient in mass spectrometry-based sequence identification bottlenecks quality control scaling.
- GRAS notification timelines:FDA review periods for novel marine peptide food additives extend 18-24 months, freezing formulation development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Peptides Market |
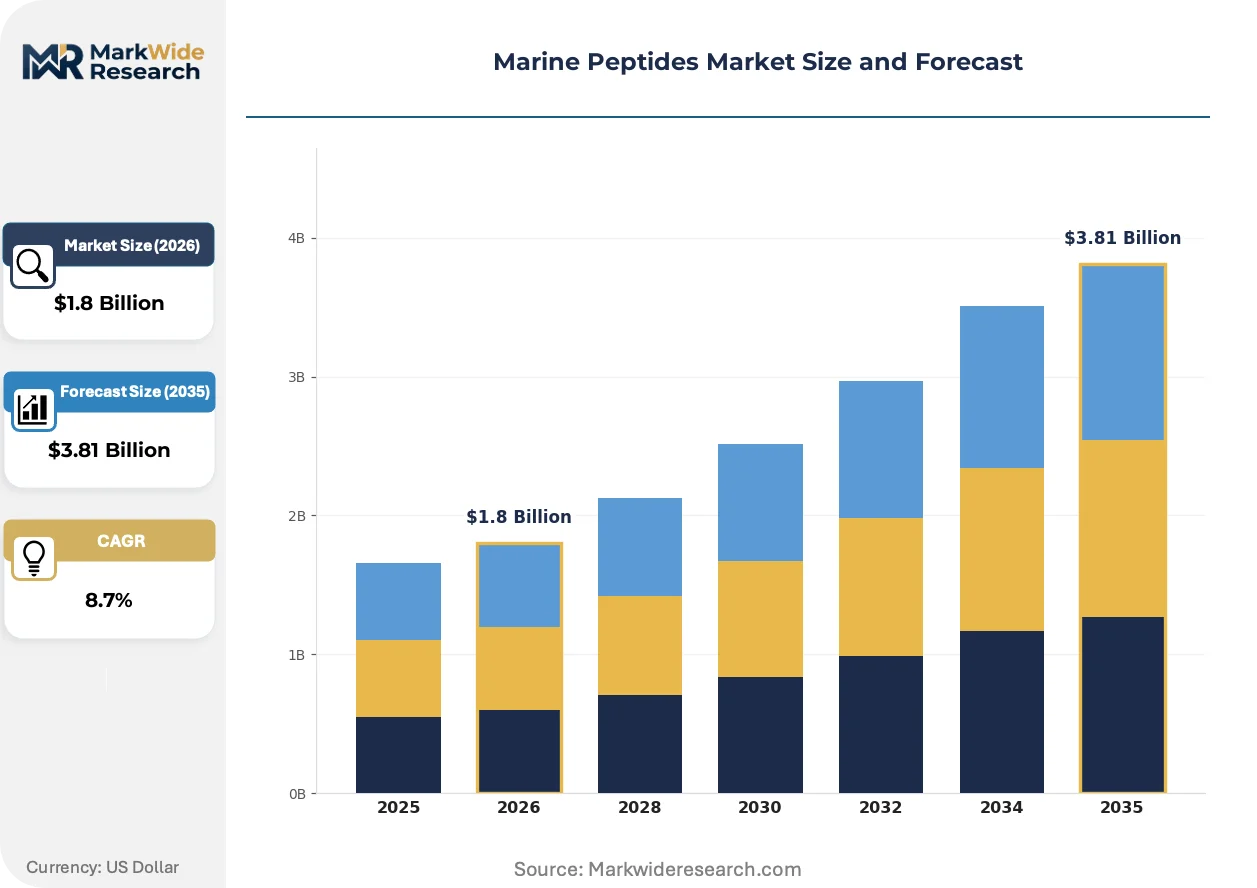
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen, Gelatin, Antioxidants, Amino Acids Application: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals Source: Fish, Mollusks, Seaweed, Crustaceans End User: Food Manufacturers, Cosmetic Companies, Healthcare Providers, Researchers |
| Companies Covered | Gelita AG, Nitta Gelatin, Rousselot, Weishardt Group, Holista CollTech, Algaia, Gelymar, Seagarden, Aker BioMarine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Peptides Market Evolving Landscape
Computational protein design and closed-loop extraction systems are converging to transform marine peptide production from batch-dependent commodity operations into precision-manufactured bioactive platforms with predictable performance profiles.
Continuous enzymatic membrane reactors is electrifying downstream processing economics by replacing traditional batch hydrolysis with steady-state peptide liberation that cuts solvent use and labor intensity. Nutraceutical contract manufacturers in Denmark and Norway are retrofitting facilities at pace, attracted by 40% throughput gains and reduced wastewater treatment loads. This technology is electrifying competitive positioning around extraction yield rather than fleet size or territorial fishing rights.
EU Green Deal sustainable sourcing mandates now require documented carbon footprint accounting for marine biomass inputs, with EFSA novel food approvals increasingly contingent on lifecycle assessment data. European cosmetic peptide suppliers face retrofitting pressure to trace supply chains through Marine Stewardship Council certification or equivalent third-party validation. The nutraceutical segment absorbs the heaviest compliance burden, as finished goods brands demand ingredient-level sustainability credentials to satisfy retailer ESG scorecards.
Direct-to-brand ingredient service contracts are displacing traditional distributor-mediated sales for high-value peptide categories, with cosmetic formulators and functional food developers seeking collaborative R&D partnerships rather than catalog purchasing. Marine peptide houses in France and Japan now embed application scientists within customer innovation teams, co-developing proprietary peptide blends with exclusivity provisions. This pattern concentrates most visibly in South Korean beauty markets, where K-beauty brands prioritize speed-to-shelf over multi-supplier sourcing strategies.
Marine Peptides Market Segmentation
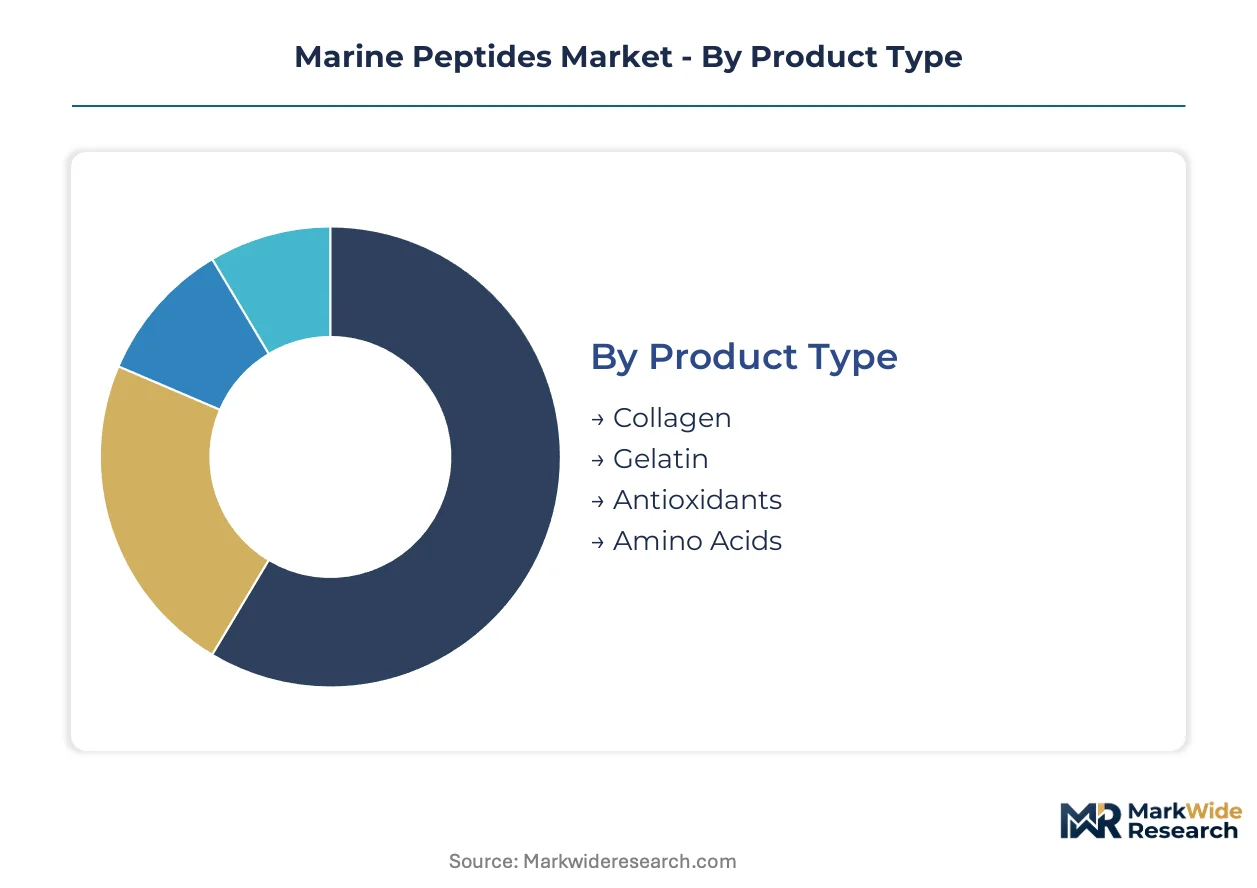
Marine peptide suppliers structure portfolios around bioactivity specificity rather than commodity protein grades. Segmentation discipline separates volume-driven food fortification from premium therapeutic applications where molecular characterization commands pricing power.
Product Type:
Collagen peptides dominate volume flows while antioxidant fractions capture expanding clean-label premiums.
- Collagen:Hydrolyzed fish collagen peptides with molecular weights below 3 kDa penetrate dermal barriers for cosmeceutical absorption. Japanese functional food manufacturers under FOSHU framework absorb the largest procurement volumes for joint health positioning.
- Antioxidants:Seaweed-derived oligopeptides scavenge free radicals through sulfur-containing amino acid residues. European food preservation applications are climbing the fastest as synthetic additive bans tighten under EFSA pressure.
- Gelatin:Partially hydrolyzed collagen retains gelling functionality for encapsulation and texture modification.
- Amino Acids:Free-form taurine and glycine isolates serve pharmaceutical buffer systems and parenteral nutrition.
Today's leader: Collagen. Tomorrow's challenger: Antioxidants.
Application:
Formulation complexity separates pharmaceutical-grade validation from commodity food additive positioning.
- Nutraceuticals:Clinical-grade peptide concentrates require mass spectrometry batch certification and bioactivity retention through enteric coating. Sports nutrition brands in Denmark and Norway are concentrating procurement for recovery positioning.
- Pharmaceuticals:cGMP-manufactured peptides for wound healing matrices and drug delivery systems face the steepest purity thresholds. PMDA accelerated approval pathways in Japan are expanding fastest for marine-derived therapeutics.
- Food & Beverage:Dairy fortification and ready-to-drink protein applications absorb baseline volumes through cost-optimized hydrolysates.
- Cosmetics:Topical collagen penetration claims drive premium peptide sourcing for anti-aging serum formulations.
Nutraceuticals command current margin premiums. Pharmaceuticals are gaining share fastest on regulatory pathway maturation.
Source:
Biomass accessibility and seasonal variability shape sourcing economics across marine taxa.
- Fish:Cod and salmon processing byproducts yield collagen-dominant hydrolysates through enzymatic recovery. Norwegian and Icelandic suppliers anchor supply security through trawler fleet integration.
- Seaweed:Laminaria and Porphyra species deliver sulfated polypeptides with metal-chelating functionality. Korean coastal cultivation operations are expanding most quickly for cosmetic antioxidant extraction.
- Crustaceans:Antarctic krill biomass supplies omega-3 conjugated peptides under CCAMLR quota management.
- Mollusks:Abalone and oyster tissues contribute glycoprotein-rich extracts for traditional medicine applications.
Fish sources dominate current tonnage. Seaweed cultivation is accelerating fastest on land-based aquaculture technology maturation.
End User:
Technical sophistication gaps separate research-grade procurement from industrial-scale formulation.
- Cosmetic Companies:South Korean beauty conglomerates demand peptide sequence customization with exclusivity provisions and rapid iteration cycles. Direct R&D embedding now characterizes premium supplier relationships.
- Food Manufacturers:Dairy and sports nutrition processors prioritize cost-stable supply contracts with GRAS documentation for US market access.
- Healthcare Providers:Hospital nutrition services and wound care clinics source medical-grade collagen for chronic patient management.
- Researchers:Academic and biotech laboratories procure characterized peptide libraries for mechanism-of-study investigations.
Cosmetic companies anchor premium pricing power. Food manufacturers represent the volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan channels marine peptide demand through functional food channels faster than Germany builds pharmaceutical-grade capacity, revealing a split between consumer-facing and clinical applications.
Japan
Functional food manufacturers under METI guidance absorb collagen peptides for joint health positioning. The FOSHU framework accelerates commercialization through pre-approved health claim categories. Osaka-based nutraceutical clusters concentrate formulation expertise for rapid peptide-to-product translation.
Germany
Cosmetic peptide suppliers retrofit operations to meet EU Green Deal carbon accounting mandates. ECHA REACH documentation requirements tighten traceability standards for marine biomass inputs. Hamburg and Bremen harbor zones anchor sustainable sourcing verification centers serving Northern European markets.
United States
Sports nutrition brands drive marine collagen procurement for clean-label protein fortification. FDA GRAS notification timelines extend formulation development cycles for novel peptide additives. San Diego biotech corridors incubate precision fermentation alternatives to wild-catch dependency.
Norway
Trawler fleet integration secures cod and salmon processing byproduct streams for enzymatic peptide recovery. Continuous-flow bioreactor adoption accelerates through Danish and Norwegian contract manufacturing partnerships. Bergen processing hubs concentrate hydrolysis automation expertise.
South Korea
K-beauty conglomerates demand peptide sequence customization with exclusivity provisions and compressed iteration cycles. Coastal cultivation operations near Busan expand Laminaria and Porphyra sourcing for cosmetic antioxidant extraction. Seoul-based innovation teams embed application scientists directly within supplier R&D functions.
Marine Peptides Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with nutraceutical channels favoring ingredient houses and pharmaceutical applications consolidating around validated suppliers. The vendor base organizes into three tiers: vertically integrated biomass processors, enzymatic hydrolysis technology licensors, and formulation-focused service providers. Strategic moves concentrate on backward integration into sustainable harvesting assets and precision fermentation capacity builds that eliminate seasonal raw material constraints.
Within the integrated processor tier, Gelita AG anchors European supply security through gelatin expertise extension into marine collagen channels. Aker BioMarine exemplifies Antarctic biomass-to-peptide vertical control, while Rousselot occupies a position bridging medical nutrition purity standards with cosmetic formulation flexibility. These three represent distinct archetypes: the diversified protein house, the single-source biomass dominator, and the application-specific purity specialist.
| Leading Market Players |
|---|
| Gelita AG |
| Nitta Gelatin |
| Rousselot |
| Weishardt Group |
| Holista CollTech |
| Algaia |
| Gelymar |
| Seagarden |
| Aker BioMarine |
| Others |
Value Network & Pricing Analysis
Antarctic krill quota allocations cascade through peptide pricing tiers, with CCAMLR conservation assessments compressing raw material predictability and forcing pharmaceutical-grade suppliers toward precision fermentation alternatives that reset cost baselines across premium and standard segments.
Pricing Analysis
Capacity additions in Norway and Denmark are reshaping price floors for enzymatic hydrolysis services, eroding legacy extraction premiums. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-certified, and food-additive levels separates mass spectrometry-validated batches from commodity hydrolysates. Cost compression in standard-grade collagen peptides is intensifying because continuous-flow bioreactor adoption cuts unit processing costs. Food manufacturers exhibit highest price sensitivity, while cosmetic formulators absorb premiums for sequence customization with exclusivity provisions.
Supply Chain Analysis
Single-source vulnerability sits with Antarctic krill biomass under CCAMLR quota management, constraining omega-3 peptide concentrate flows. Norwegian, Icelandic, and Japanese suppliers anchor fish-derived collagen security through trawler fleet integration and coastal processing infrastructure. Raw material dependencies center on cod and salmon processing byproducts, Laminaria and Porphyra seaweed cultivation, and krill harvesting permits. Tariff exposure runs through EU Green Deal carbon accounting mandates that add documentation overhead for Asian biomass imports. Distribution runs through direct-to-brand ingredient service contracts displacing traditional distributor mediation for high-value peptide categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine peptides function as a stable compounder, with functional food fortification in aging populations driving consistent demand absorption across economic cycles.
For Market Incumbents: Hedge against wild-catch supply volatility by accelerating precision fermentation capacity builds that eliminate seasonal biomass dependency. Secure backward integration into Marine Stewardship Council-certified harvesting assets before EU Green Deal traceability mandates tighten. Counter plant protein substitution threats in cosmetic channels through clinical validation investments that substantiate bioactivity superiority claims. For New Entrants and Emerging Players: Brazil's ANVISA pathway opens a window for establishing local clinical validation partnerships in a regulatory environment with underdeveloped marine bioactives precedent. Target wound care medical devices as the most penetrable segment, where collagen peptide integration into advanced dressings faces limited marine-derived competition. Pursue co-development contracts with K-beauty brands seeking rapid iteration cycles as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for enzymatic hydrolysis technology licensors because fragmented European processing capacity lacks scale efficiency. Five-to-ten-year viability hinges on consolidation of mid-tier contract manufacturers into platforms with integrated bioactivity profiling capabilities. Watch CRISPR-assisted peptide engineering commercialization timelines as the inflection indicator for therapeutic application expansion beyond natural extraction limits.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Build | Eliminates Antarctic krill quota dependency for pharmaceutical-grade peptide supply consistency. |
| Marine Stewardship Council Certification | Satisfies EU Green Deal carbon accounting mandates for sustainable sourcing verification. |
| Continuous-Flow Bioreactor Retrofit | Captures 40% throughput gains that compress processing economics for contract manufacturers. |
| Direct R&D Embedding Partnership | Locks in exclusivity provisions with South Korean beauty conglomerates demanding rapid iteration. |
| Clinical Validation Investment | Secures FOSHU framework approvals that accelerate functional food commercialization in Japan. |
Research Methodology
Multiple input streams — executive interviews with nutraceutical formulation directors, regulatory affairs specialists at peptide houses, and cosmetic application scientists — were reconciled against customs trade data, EFSA novel food approval databases, and SEC filings from publicly traded suppliers. Primary fieldwork captured procurement patterns from sports nutrition brands and K-beauty innovation teams. Secondary validation drew from CCAMLR conservation assessments, METI biotechnology commercialization reports, and continuous-flow bioreactor technology disclosures. Bottom-up segment sizing and top-down market reconciliation anchored value estimates.
Historical volume trajectories were cross-referenced against expert panel inputs on enzymatic hydrolysis automation adoption curves. Segmentation modeling spanned product type, application, source taxonomy, and end-user sophistication across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity buildout schedules. Forecast inputs incorporated FOSHU framework approval velocities, REACH compliance cost pass-through assumptions, and precision fermentation yield improvement curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under CCAMLR quota restriction scenarios and plant protein substitution acceleration in cosmetic applications. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
United States Corn Glucose Market
Ingredients
Chlorella Ingredients Market
Ingredients
Cheese Ingredients Market
Ingredients
Coconut Oil Market
Ingredients
Diastatic Malt Market
Ingredients
Europe Potato Protein Market
Ingredients
Hydrolyzed Oat Protein Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Casein Hydrolysate Market
Ingredients
Cocoa Powder Market
Ingredients
Ximenia Oil Market
Ingredients
North America Gums Market
Ingredients
Citrus Fiber Market
Ingredients
Mustard Flour Market
Ingredients
Chickpea Protein Ingredients Market
Ingredients
North America Dairy Protein Ingredients Market