
 Collagen Drinks Market | 2026-2036
Collagen Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Collagen Drinks Market Analysis
Marine collagen peptides is rebalancing cost structures against bovine-sourced alternatives across Asia-Pacific formulations. Shiseido Company, Limited leverages its century-long dermatology heritage to anchor premium positioning in Japanese drugstore channels. Vital Proteins competes through aggressive North American retail expansion and direct-to-consumer scale. Suntory Holdings Limited dominates functional beverage R&D pipelines with proprietary low-molecular-weight hydrolysis patents.
Collagen drinks are hydrolyzed peptide suspensions, typically delivering 2,500–10,000 dalton molecular weight fractions in ready-to-consume liquid or reconstitutable formats, engineered for dermal matrix support and connective tissue maintenance. Liquid formats command the dominant share due to convenience positioning and immediate bioavailability claims, while marine collagen ingredient lines attract the fastest growth from pescatarian and halal-observant demographics. Beauty consumers represent the deepest margin pool, though fitness enthusiasts show accelerating trial rates through cross-category sports-nutrition merchandising.
EFSA novel food assessments and Japan's FOSHU (Foods for Specified Health Uses) framework jointly determine permissible structure-function claims across European and Japanese markets. The US FDA exercises enforcement discretion over cosmetic-ingredient crossovers, creating compliance variance that shapes import strategies. Stakeholders must monitor evolving peptide-concentration thresholds in emerging regulatory consultations to preempt reformulation costs.
Market Dynamics
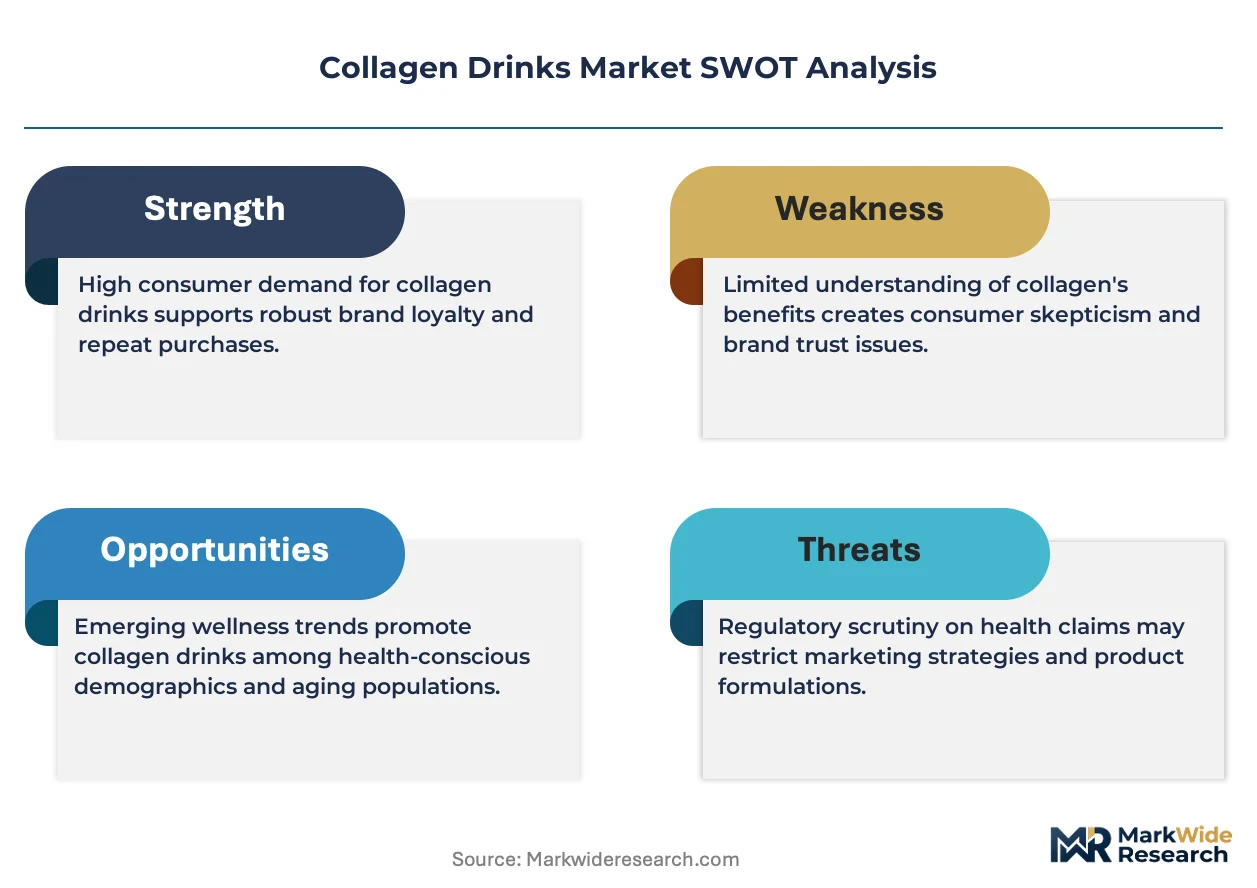
Low-molecular-weight hydrolysis patents held by Japanese beverage conglomerates are redrawing competitive moats around bioavailability claims, compressing formulation differentiation windows for new entrants.
Growth Catalysts
- South Korean beauty-consumer trial rates:K-beauty export momentum normalizes collagen drinks as daily skincare rituals, amplifying category education through social commerce channels.
- EFSA novel food assessments:Clarified peptide-concentration thresholds reduce regulatory uncertainty for European importers, accelerating shelf-space negotiations with continental pharmacy chains.
- Halal-certification pipelines:Marine collagen sourcing satisfies pescatarian and Muslim-observant demographics previously excluded from bovine-derived offerings, unlocking Southeast Asian distribution.
Market Restraints
- Fish-scale raw material volatility:Tilapia and cod skin supply concentrates in Southeast Asian aquaculture zones, exposing formulations to El Niño-driven catch fluctuations.
- Bovine collagen cost undercutting:Cattle-hide peptide production in Brazil and Argentina maintains 15-20% unit cost advantages, pressuring premium marine positioning at mass-market price tiers.
- EFSA health-claim substantiation burdens:Randomized controlled trial requirements for dermal matrix support claims extend product development cycles by 18-24 months versus cosmetic crossovers.
Strategic Opportunities
- Indonesia's Muslim-majority urban centers:Halal-certified marine lines face minimal incumbent competition in Jakarta and Surabaya drugstore channels.
- Sports-nutrition cross-merchandising:Fitness enthusiasts demonstrate accelerating trial rates when collagen drinks sit adjacent to protein powders in gym retail environments.
- Japan's FOSHU framework expansion:Specified Health Uses designation for joint mobility claims opens reimbursement-adjacent positioning through pharmacy benefit networks.
Industry Challenges
- Peptide stability shelf-life engineering:Hydrolyzed collagen degradation in ambient liquid formats demands cold-chain infrastructure investments that erode margin in emerging markets.
- Cross-border customs classification ambiguity:Harmonized System code disputes between food supplement and cosmetic categories trigger detention delays at EU and US ports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collagen Drinks Market |
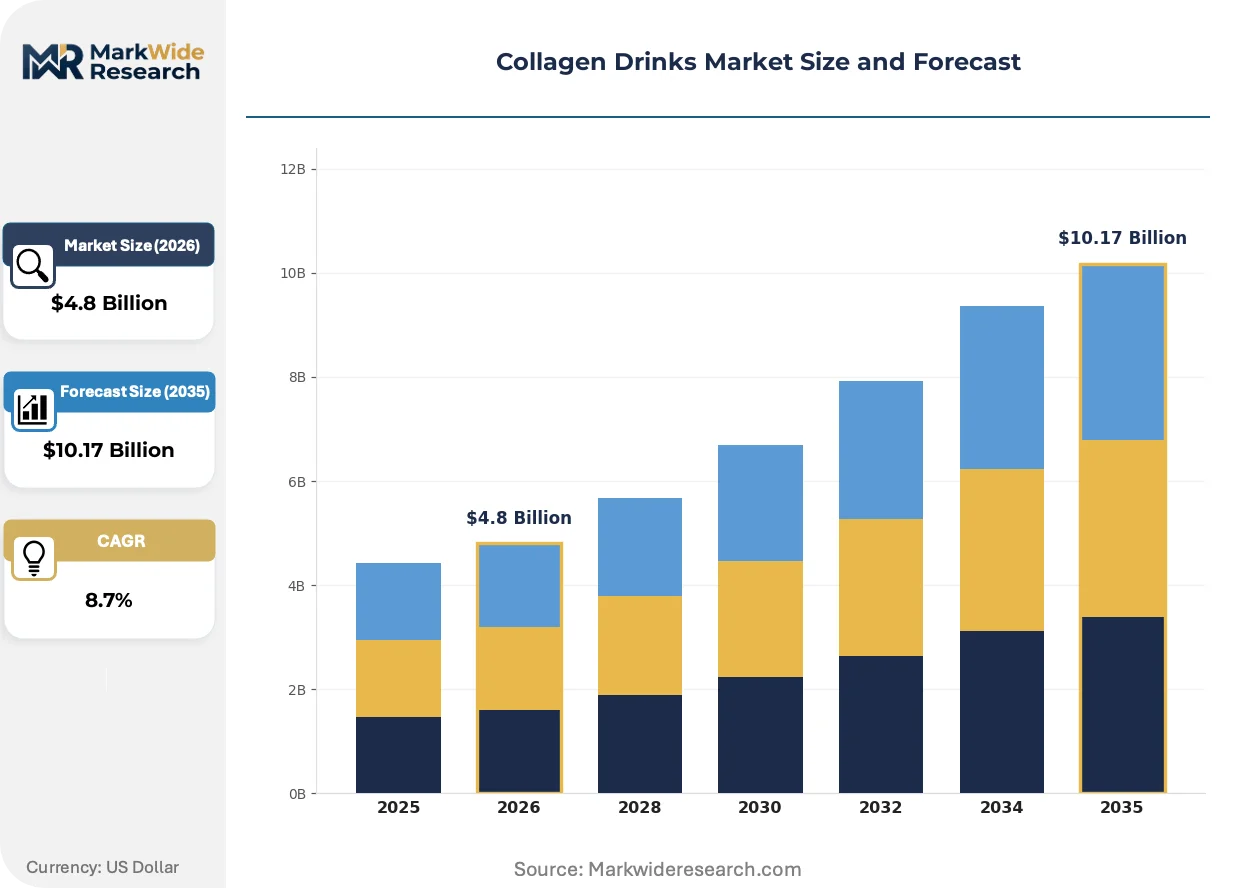
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Capsule, Gel Key Ingredient: Marine Collagen, Bovine Collagen, Plant-Based Collagen, Gelatin Target Audience: Fitness Enthusiasts, Aging Population, Beauty Consumers, Health-Conscious Individuals Packaging Type: Bottles, Sachets, Tubs, Cans |
| Companies Covered | Amorepacific Corporation, Kino Biotech Co., Ltd., Shiseido Company, Limited, Skinade, Suntory Holdings Limited, Vital Proteins, Kirin's Holdings Company, Limited, Bulletproof, Meiji Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collagen Drinks Market Emerging Trajectories
Enzymatic hydrolysis refinements and ambient-stable emulsion technologies are collapsing the functional gap between liquid convenience and powder economics, forcing incumbents to defend channel positioning through format innovation rather than ingredient differentiation alone.
Dual-stage enzymatic hydrolysis is unifying molecular weight precision with production throughput, enabling sub-3,000 dalton peptide fractions at commercial scale. Functional beverage manufacturers in Japan and South Korea deploy these systems to compress lead times for FOSHU-submission batches. The technology is unifying what previously required separate artisanal and industrial production lines, permitting mid-tier brands to access premium bioavailability positioning.
EFSA's 2023 updated guidance on collagen peptide novel food status imposes stricter toxicological data packages for non-hydrolyzed raw material sources. European importers now face reformulation costs when sourcing from suppliers lacking ISO 17025-accredited testing facilities. German and French pharmacy buyers are responding by consolidating supplier bases around vertically integrated marine collagen producers with captive laboratory infrastructure.
Subscription-based replenishment models displace traditional retail replenishment cycles among North American direct-to-consumer brands. Beauty consumers aged 25-34 demonstrate 40% higher lifetime value when enrolled in auto-ship programs versus episodic pharmacy purchases. This shift concentrates most visibly in California and New York metro areas where same-day delivery infrastructure supports perishable liquid format logistics.
Collagen Drinks Market Segmentation
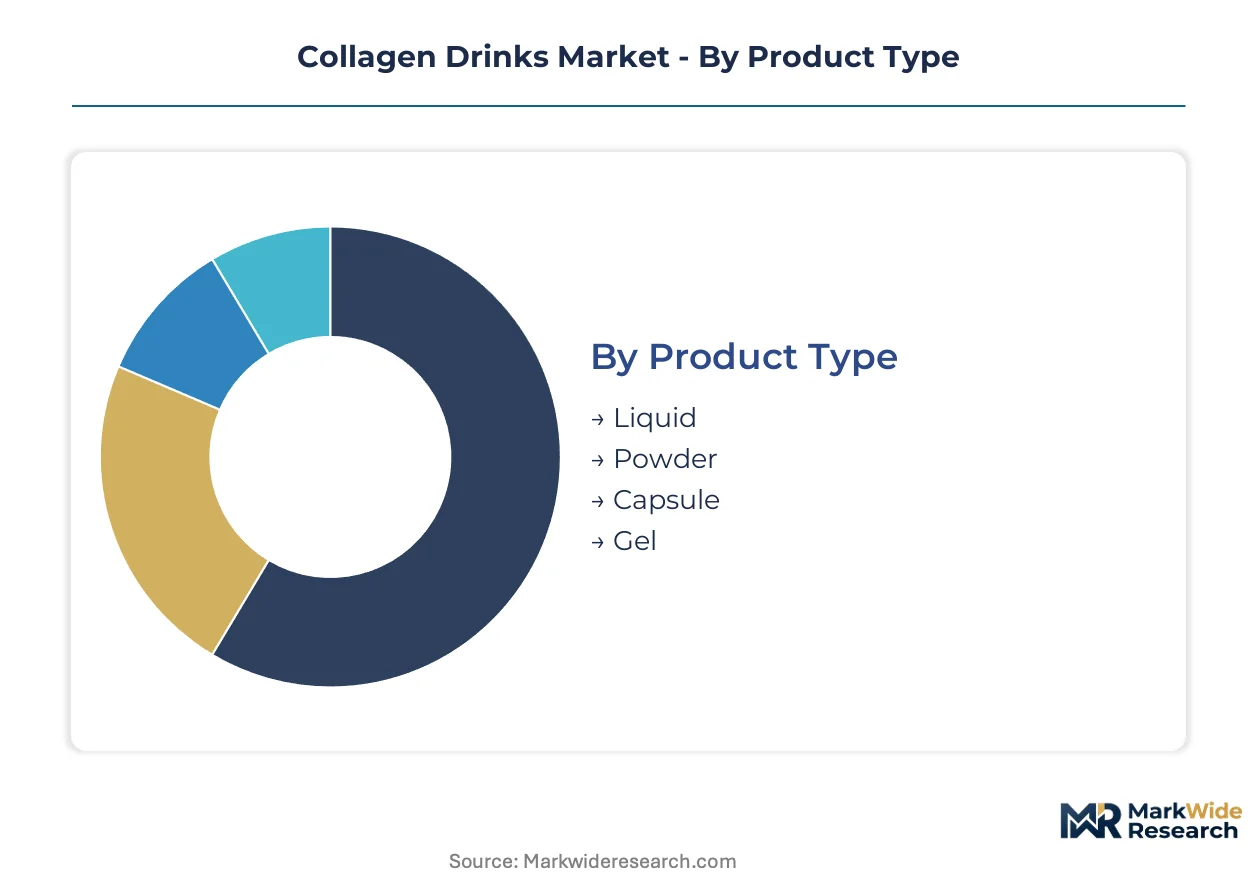
Collagen drinks fragment across four structural dimensions that each reshape capital deployment and margin capture. Product format dictates manufacturing infrastructure requirements, while ingredient sourcing determines regulatory pathway complexity and geographic addressability.
Product Type:
Liquid formats demand the heaviest upfront investment in aseptic filling lines and cold-chain distribution infrastructure.
- Liquid:Hydrolyzed peptide suspensions in ready-to-consume formats require tetra-pak or glass bottling systems with nitrogen-flush capabilities. Demand concentrates in Japanese convenience retail and South Korean social commerce channels where immediate bioavailability claims command shelf-space premiums. Ambient stability engineering remains the primary technical barrier for new entrants.
- Powder:Reconstitutable formats carry lower per-unit logistics costs and extended shelf life without refrigeration. German and French pharmacy buyers favor this format for its dosing flexibility, though consumer education requirements slow trial conversion versus liquid alternatives.
- Capsule:Encapsulated collagen appeals to supplement-purist demographics seeking precise dosing control. Production scales through existing soft-gel contract manufacturing networks with minimal dedicated equipment.
- Gel:Semi-solid delivery systems target pediatric and geriatric swallowing-difficulty segments. Japanese FOSHU submissions for joint mobility claims increasingly incorporate this format for palatability advantages.
Most installed capacity flows through Liquid. Expansion is steepest in Powder.
Key Ingredient:
Ingredient selection restructures procurement risk profiles and certification burdens across supply bases.
- Marine Collagen:Tilapia and cod skin-derived peptides satisfy pescatarian, halal-observant, and kosher demographics previously excluded from animal-sourced alternatives. Japanese beverage conglomerates hold proprietary low-molecular-weight hydrolysis patents that compress formulation differentiation windows for competitors. Indonesian and Malaysian urban centers show accelerating demand for halal-certified marine lines.
- Bovine Collagen:Cattle-hide peptides from Brazilian and Argentine rendering operations maintain unit cost advantages that pressure premium positioning at mass-market tiers. EFSA novel food assessments impose stricter toxicological data requirements for non-hydrolyzed raw material sources.
- Plant-Based Collagen:Amino acid recombinant and plant-extract formulations target vegan-committed beauty consumers in California and New York metro areas. Current bioavailability claims face steeper substantiation burdens versus animal-derived benchmarks.
- Gelatin:Partially hydrolyzed collagen precursors serve cost-sensitive emerging market segments with lower peptide concentration requirements. Southeast Asian functional beverage manufacturers blend gelatin with flavor masking systems for price-tier expansion.
Revenue concentration tilts toward Marine Collagen. Steepest expansion trajectory belongs to Plant-Based Collagen.
Target Audience:
Audience targeting determines channel strategy and customer lifetime value economics.
- Beauty Consumers:The deepest margin pool, with South Korean K-beauty export momentum normalizing daily collagen rituals. Subscription auto-ship programs among 25-34 year-olds in North American coastal metros generate 40% higher lifetime value versus episodic pharmacy purchases.
- Fitness Enthusiasts:Accelerating trial rates when collagen drinks sit adjacent to protein powders in gym retail environments. Cross-category sports-nutrition merchandising is displacing traditional beauty-channel positioning for this segment.
- Aging Population:Joint mobility and connective tissue maintenance claims align with Japan's expanding FOSHU framework for reimbursement-adjacent pharmacy positioning.
- Health-Conscious Individuals:General wellness positioning competes in crowded supplement shelves with diluted brand differentiation. This segment shows highest price elasticity and lowest repeat purchase rates.
Beauty Consumers anchor current revenue. Fitness Enthusiasts are climbing the fastest.
Packaging Type:
Packaging selection balances perishability management, portability, and retail format constraints.
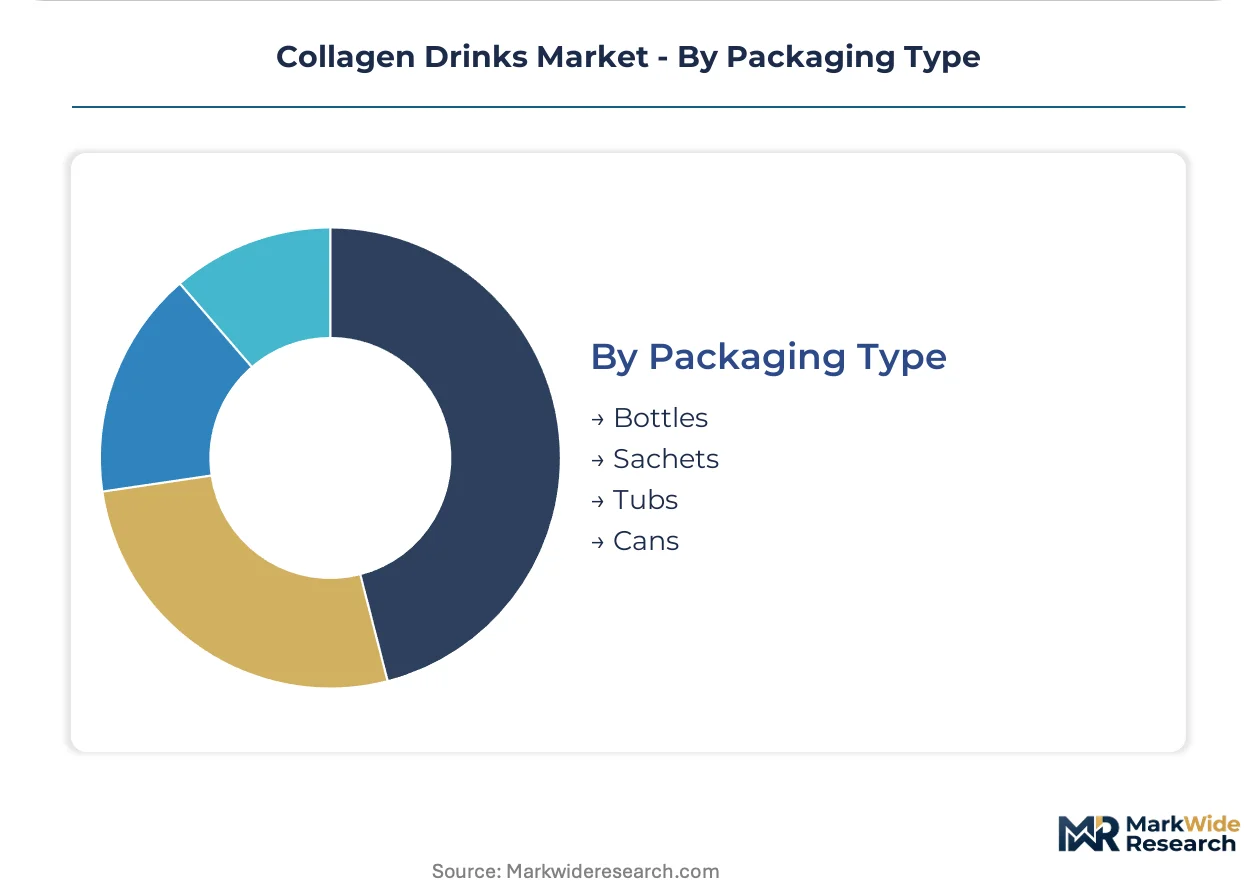
- Bottles:Glass and PET formats dominate Japanese drugstore and South Korean convenience retail. Cold-chain requirements for liquid formats concentrate investment in developed market distribution infrastructure.
- Sachets:Single-serve powder packets enable trial-size sampling and travel portability. Indonesian and Vietnamese urban centers favor this format for humidity-resistant storage in tropical climates.
- Tubs:Bulk powder containers serve committed users with lowest per-gram packaging costs. German and French pharmacy consolidation around vertically integrated suppliers favors this format for professional recommendation settings.
- Cans:Aluminum formats for carbonated or still functional beverages leverage existing beverage industry filling capacity. Limited current adoption but emerging in Japanese vending-machine channels.
Bottles carry the largest installed base. Sachets are gaining share fastest in emerging Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese beverage conglomerates anchor the global collagen drinks market through proprietary low-molecular-weight hydrolysis patents concentrated in Tokyo-Osaka industrial corridors. National regulatory frameworks and raw material sourcing patterns reshape competitive positioning across four major demand centers.
Japan
K-beauty export momentum from South Korea drives cross-border trial adoption among Japanese beauty consumers aged 25-34. METI's FOSHU framework expansion for joint mobility claims opens reimbursement-adjacent pharmacy positioning through national benefit networks. Osaka-based beverage manufacturers deploy dual-stage enzymatic hydrolysis systems to compress lead times for regulatory submission batches.
South Korea
Social commerce channels normalize daily collagen rituals among Seoul's beauty-consumer demographic, amplifying category education through influencer-driven sampling. MFDS novel food assessments impose peptide-concentration disclosure requirements for imported marine formulations. Busan-Ulsan industrial zones concentrate tilapia-skin processing capacity for regional halal-certification pipelines.
United States
Subscription auto-ship programs among California and New York metro consumers generate 40% higher lifetime value versus episodic pharmacy purchases. FDA enforcement discretion over cosmetic-ingredient crossovers creates compliance variance that shapes import strategies from Asian manufacturers. Los Angeles cold-chain infrastructure supports perishable liquid format logistics for direct-to-consumer brands.
Indonesia
Jakarta and Surabaya drugstore channels show accelerating demand for halal-certified marine collagen lines with minimal incumbent competition. The country's national food and drug regulator imposes registration requirements that favor vertically integrated suppliers with captive laboratory infrastructure. Surabaya's Muslim-majority urban centers drive pescatarian formulation adoption previously excluded from bovine-derived offerings.
Germany
Pharmacy buyers in Berlin and Frankfurt consolidate supplier bases around vertically integrated marine collagen producers following EFSA's updated toxicological data requirements. EFSA novel food assessments reduce regulatory uncertainty for peptide-concentration thresholds, accelerating shelf-space negotiations with continental chains. Bavarian contract manufacturers favor powder formats for dosing flexibility in professional recommendation settings.
Collagen Drinks Market Vendor Landscape
Patent licensing dominates the current landscape as Japanese beverage conglomerates redraw competitive moats around bioavailability claims. The vendor base concentrates among three tiers: century-long dermatology heritage brands, aggressive North American retail expanders, and functional beverage R&D specialists. Strategic archetypes include premium-positioned heritage players, direct-to-consumer scale operators, and proprietary hydrolysis technology holders. Capacity expansion and format innovation represent the dominant competitive moves as incumbents defend channel positioning.
Within the heritage-tier, Shiseido Company, Limited and Suntory Holdings Limited exemplify proprietary technology anchoring. Among North American direct-to-consumer operators, Vital Proteins occupies a position representing subscription-model scale. These three companies represent the competitive spectrum from dermatology-channel premium positioning through functional beverage R&D dominance to retail expansion scale.
| Leading Market Players |
|---|
| Amorepacific Corporation |
| Kino Biotech Co., Ltd. |
| Shiseido Company, Limited |
| Skinade |
| Suntory Holdings Limited |
| Vital Proteins |
| Kirin's Holdings Company, Limited |
| Bulletproof |
| Meiji Holdings Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
EFSA's 2023 updated toxicological data requirements for collagen peptide novel food status gate qualified supply and premium-tier pricing access. German and French pharmacy buyers now consolidate supplier bases around vertically integrated marine collagen producers with captive ISO 17025-accredited laboratory infrastructure, compressing procurement options for non-compliant entrants.
Pricing Analysis
Input-cost pass-through from tilapia and cod skin raw materials runs through marine collagen formulations, with Brazilian and Argentine cattle-hide peptides maintaining 15-20% unit cost advantages that pressure premium positioning. Three-tier pricing structure across premium FOSHU-designated lines, standard pharmacy-grade formats, and economy gelatin-blended offerings separates certification tiers. Pricing pressure stems from bovine collagen cost undercutting at mass-market tiers. Beauty consumers aged 25-34 in North American coastal metros show lowest price sensitivity through subscription auto-ship programs, while health-conscious general wellness segments exhibit highest elasticity.
Supply Chain Analysis
Certification and qualification gating through halal-certification pipelines and FOSHU framework compliance redraws supplier viability, with Indonesian and Malaysian urban centers demanding pescatarian formulations previously excluded from bovine-derived offerings. Raw material supply concentrates in Japan, South Korea, and Indonesia, drawing from tilapia-skin processing clusters, dual-stage enzymatic hydrolysis equipment, and cold-chain distribution infrastructure. Single-source vulnerability concentrates in Southeast Asian aquaculture zones exposed to El Niño-driven catch fluctuations. Distribution runs through Japanese drugstore channels, South Korean social commerce platforms, and North American direct-to-consumer subscription networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in collagen drinks rests on enzymatic hydrolysis refinements collapsing production costs for sub-3,000 dalton peptide fractions and subscription auto-ship programs capturing 40% higher lifetime value among beauty consumers.
For Market Incumbents: Lock in proprietary low-molecular-weight hydrolysis patents through defensive licensing to Japanese beverage conglomerates, compressing formulation differentiation windows for emerging competitors. Deepen backward integration into tilapia-skin processing capacity in Busan-Ulsan industrial zones to secure halal-certification pipeline supply against El Niño-driven raw material volatility. Channel control through FOSHU framework expansion for joint mobility claims defends pharmacy benefit network positioning. For New Entrants and Emerging Players: Capture white-space in Indonesia's Muslim-majority urban centers where halal-certified marine lines face minimal incumbent competition in Jakarta and Surabaya drugstore channels. Target sports-nutrition cross-merchandising adjacent to protein powders in gym retail environments, where fitness enthusiasts demonstrate accelerating trial rates. Deploy sachet formats for humidity-resistant storage in tropical climates as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated marine collagen specialists with captive laboratory infrastructure because EFSA's stricter toxicological data requirements consolidate supplier bases around qualified producers. Long-term viability over a multi-year horizon favors targets with FOSHU submission capabilities and dual-stage enzymatic hydrolysis systems. Watch peptide-concentration threshold consultations as the inflection signal for reformulation cost exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Stage Enzymatic Hydrolysis Deployment | Compresses lead times for FOSHU-submission batches in Osaka-based manufacturing. |
| Halal-Certification Pipeline Expansion | Unlocks Southeast Asian distribution for pescatarian and Muslim-observant demographics. |
| Subscription Auto-Ship Model Launch | Captures 40% higher lifetime value among 25-34 year-old beauty consumers in coastal metros. |
| Ambient-Stable Emulsion Technology Investment | Collapses functional gap between liquid convenience and powder economics for emerging markets. |
| Backward Integration into Tilapia-Skin Processing | Secures supply against El Niño-driven catch fluctuations in Southeast Asian aquaculture zones. |
Methodological Framework
Multiple input streams — primary interviews with functional beverage R&D directors, regulatory affairs specialists at EFSA and MFDS, pharmacy category buyers, and marine collagen procurement managers; secondary validation through FOSHU submission databases, EFSA novel food assessment records, customs/trade data, and SEC filings from publicly traded beverage conglomerates — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product format, ingredient sourcing, target audience, and packaging type segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from modeled volume and value outputs reflecting peptide-concentration adoption curves and regulatory pathway timelines. Forecast inputs incorporated FOSHU framework expansion trajectories and El Niño cycle impacts on marine raw material availability.
Regulatory consultation outcomes, raw material catch fluctuations, and cold-chain infrastructure investment delays are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in EFSA peptide-concentration threshold determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Fruit Beverages Market
Beverages
US and Canada Tonic Water Market
Beverages
Birch Water Market
Beverages
Packaged Cactus Water Market
Beverages
Bottled Water Processing Market
Beverages
Semillon Market
Beverages
Collagen-Infused Water Market
Beverages
Global Bottled Water Market
Beverages
Global Soda Maker Market
Beverages
Kvass Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Europe Ready-To-Drink Beverages Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Juice Concentrates Market
Beverages
Plant Based Beverages Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market