
 Skin-Booster Beverages Market | 2026-2036
Skin-Booster Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Skin-Booster Beverages Market Analytics
Japanese collagen peptide producers is recalibrating output schedules to match surging Asian beauty-drink orders. Shiseido Company, Limited leverages its century-old dermatological heritage to anchor premium positioning across East Asian pharmacy channels. Nestlé competes through its nutritional science infrastructure, while Amorepacific Corporation dominates Seoul's duty-free and domestic e-commerce ecosystems with fermented-ingredient formulations.
Skin-booster beverages are ingestible liquid formulations containing bioactive compounds—typically hydrolyzed collagen peptides, low-molecular-weight hyaluronic acid, and lipid-soluble vitamins—designed to enhance dermal hydration and elasticity through systemic delivery rather than topical application. Manufacturing employs aseptic cold-fill processing to preserve heat-sensitive actives at concentrations ranging from 2,000 to 10,000 milligrams per serving. Functional beverages command the widest retail footprint and deepest consumer recognition, yet collagen-specific SKUs within nutraceutical drinks extract the highest per-unit margins due to clinical-positioning premiums. Sachet packaging is accelerating fastest among single-serve trial formats distributed through social-commerce livestreams.
Japan's Consumer Affairs Agency FOSHU approval process and South Korea's Ministry of Food and Drug Safety functional food standards jointly determine which beauty claims survive on product labels. The EU EFSA health claims regulation blocks several collagen-hydration assertions that Asian regulators permit, fragmenting formulation strategies by destination market. Stakeholders must track evolving substantiation thresholds across these jurisdictions to avoid reformulation costs and import holds.
Market Dynamics
Japan's FOSHU approval process and South Korea's MFDS functional food standards are compressing go-to-market timelines while fragmenting formulation requirements across East Asian export corridors.
Growth Catalysts
- Urban beauty corridor expansion:Seoul's Gangnam and Tokyo's Shibuya districts are dedicating premium shelf space to collagen-based ready-to-drink formats, creating visible consumption anchors that drive trial rates among working professionals.
- Fermented ingredient validation:Traditional fermentation processes are gaining scientific substantiation under South Korean MFDS guidelines, enabling brands to command clinical-positioning premiums for bioactive peptide formulations.
- Livestream commerce infrastructure:Social-commerce platforms across East Asia are normalizing single-serve sachet sampling, collapsing customer acquisition costs for new entrants targeting beauty-conscious demographics.
Market Restraints
- Marine collagen supply concentration:Wild-caught fish scale and skin sourcing clusters heavily in specific Japanese coastal prefectures, exposing manufacturers to seasonal catch volatility and climate-driven raw material interruptions.
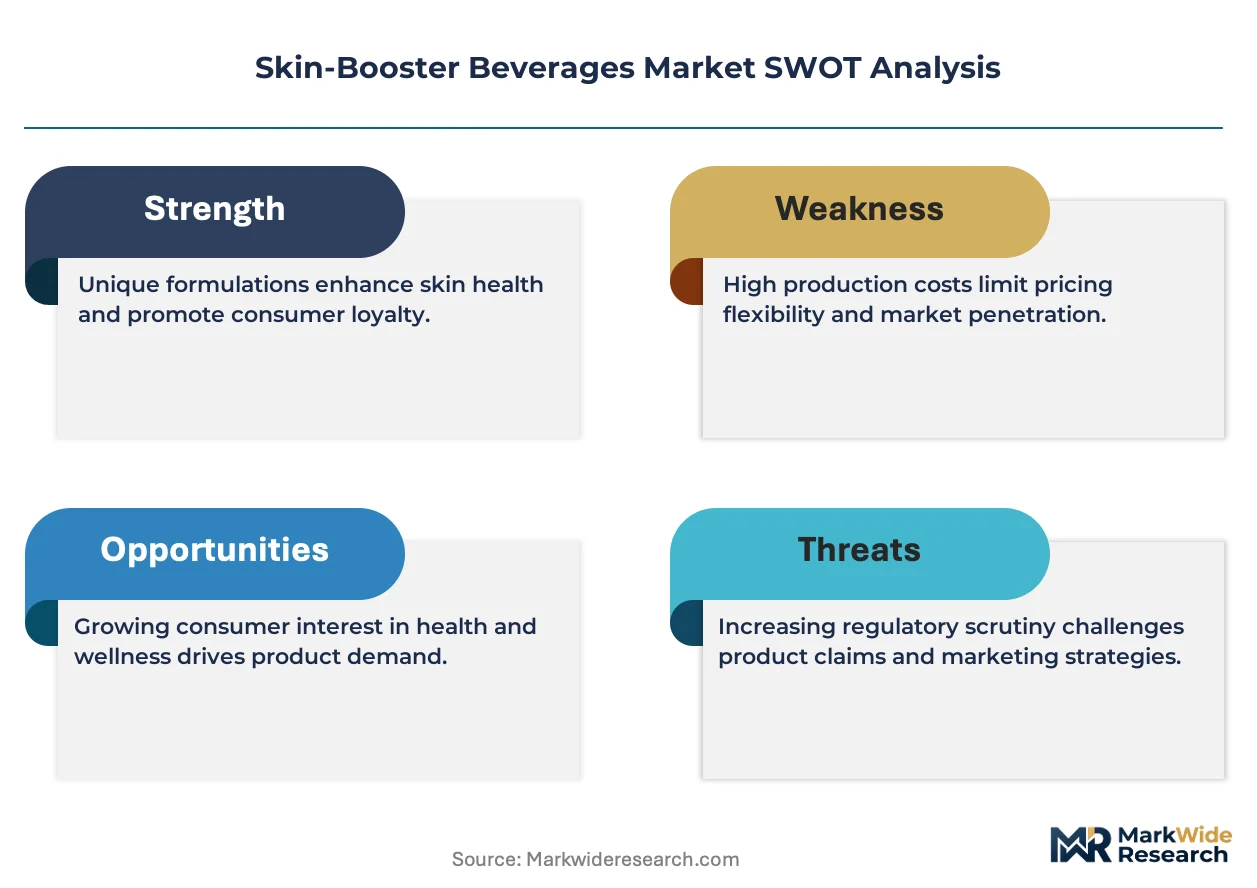
- EFSA claim restrictions:The European regulator's rejection of collagen-hydration substantiation forces dual-formulation strategies, raising R&D overhead for brands seeking pan-regional distribution.
- Heat-sensitive active degradation:Hydrolyzed collagen peptides and low-molecular-weight hyaluronic acid require aseptic cold-fill processing, constraining contract manufacturing capacity and elevating per-unit production costs.
Strategic Opportunities
- Vietnam and Indonesia penetration:Southeast Asian urban centers show rising ingestible beauty awareness with minimal incumbent brand presence, offering first-mover positioning for collagen-specific SKUs.
- Men's functional beverage segmentation:Male-targeted formulations addressing stress-induced skin fatigue remain underdeveloped across East Asian markets, presenting whitespace for gender-specific positioning.
- Pharmacy channel elevation:Japan's deregulation of cosmetic-food hybrid retailing enables pharmacy chains to expand dedicated beauty-drink sections, creating higher-margin distribution alternatives to mass grocery.
Industry Challenges
- Cross-jurisdictional compliance talent scarcity:Formulation scientists capable of navigating simultaneous FOSHU, MFDS, and EU Novel Food requirements command premium compensation, constraining mid-tier brand expansion.
- Cold-chain infrastructure capex:Aseptic processing equipment and refrigerated last-mile logistics demand substantial capital deployment, disadvantaging smaller entrants against integrated beverage conglomerates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin-Booster Beverages Market |
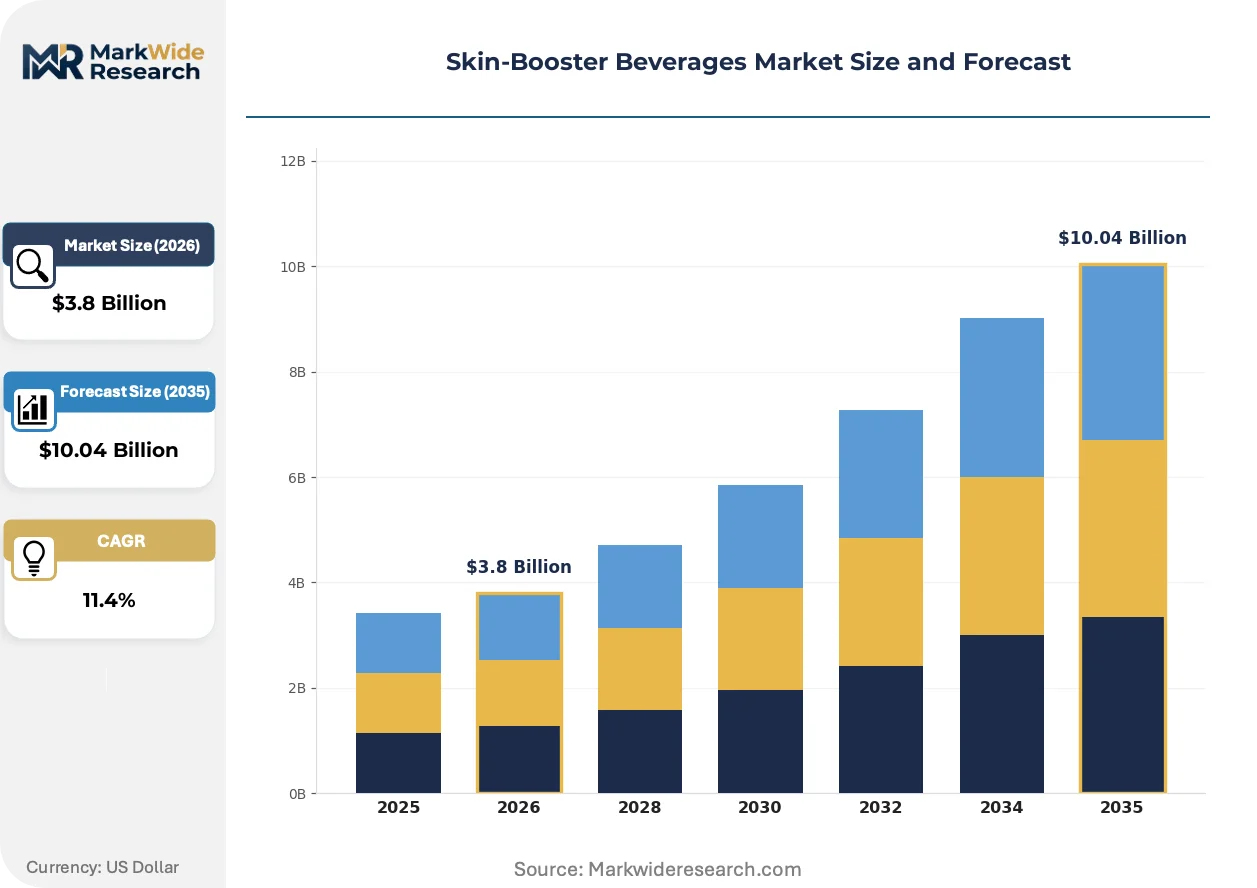
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Alcoholic, Functional Beverages, Herbal Infusions, Nutraceutical Drinks Ingredient: Collagen, Hyaluronic Acid, Vitamins, Antioxidants Packaging Type: Bottles, Tetra Packs, Cans, Sachets Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Shiseido Company, Limited, Nestlé, Amorepacific Corporation, The Bountiful Company, TCI Co., Ltd., Kino Biotech Co., Ltd., Minerva Research Labs, Meiji Holdings Co., Ltd., Nitta Gelatin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin-Booster Beverages Market Evolving Landscape
Biotechnology advances and regulatory recalibration are converging to reshape how bioactive compounds are stabilized, validated, and delivered to beauty-conscious consumers across East Asian markets.
Liposome encapsulation technology is integrating hydrolyzed collagen peptides with lipid-soluble vitamins to enhance systemic absorption rates. Premium beauty drink manufacturers in Seoul are adopting this approach at accelerated pace to differentiate clinical efficacy claims. The technology is compressing the gap between topical and ingestible beauty positioning, forcing reformulation investments across the competitive set.
South Korea's MFDS is tightening substantiation requirements for fermented-ingredient functional claims, requiring human clinical trials for new product registrations. This policy shift is extending development timelines by twelve to eighteen months for novel formulations. Domestic brands with existing trial databases are consolidating advantage while delaying international competitor entry.
Social-commerce livestreams are displacing traditional retail discovery for single-serve trial formats across East Asian markets. Beauty influencers in Tokyo and Seoul are bundling sachet samples with personalized skin assessment content, collapsing the path from awareness to first purchase. This channel shift is most pronounced among consumers aged twenty-two to thirty-five in metropolitan Japan and South Korea.
Skin-Booster Beverages Market Segmentation
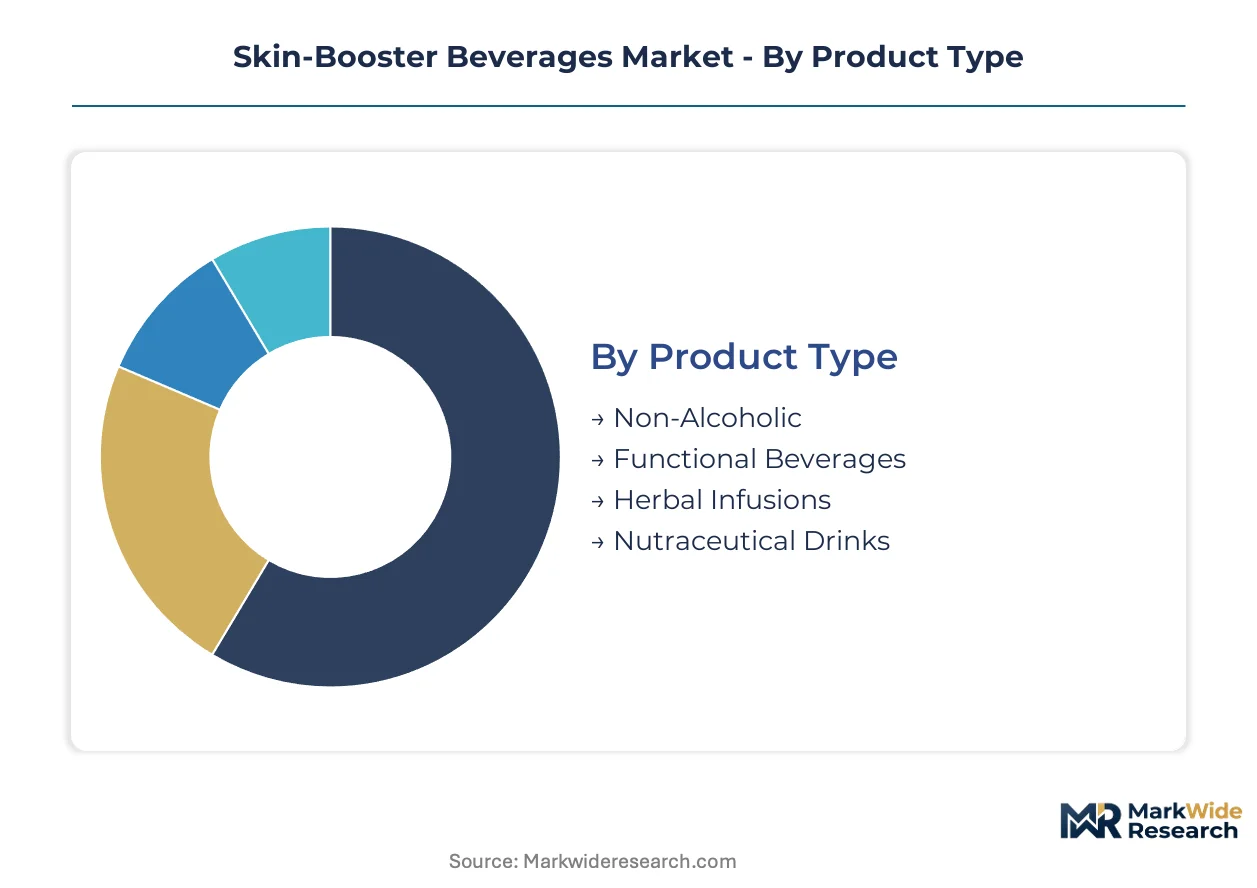
Skin-booster beverages fragment across four structural dimensions that determine formulation investment, margin capture, and channel access. Each category reflects distinct upgrade cycles: consumers trade up from basic hydration to clinically-positioned SKUs, from glass bottles to single-serve sachets, from mass retail to pharmacy-grade distribution.
Product Type:
Upgrade cycles in skin-booster beverages accelerate as consumers shift from general wellness positioning to dermatologically-validated functional claims, compressing replacement timelines from monthly pantry restocking to weekly beauty regimen purchases.
- Non-Alcoholic:Standard hydration-focused formulations without bioactive concentration thresholds. Demand concentrates in mass grocery channels across South Korea's secondary cities where price sensitivity delays clinical-grade adoption.
- Functional Beverages:Ready-to-drink formats with 2,000 to 10,000 milligrams of hydrolyzed collagen peptides per serving, commanding the widest retail footprint. Seoul's Gangnam and Tokyo's Shibuya districts dedicate premium shelf space to these SKUs, driving trial rates among working professionals through visible consumption anchors.
- Herbal Infusions:Traditional botanical extracts positioned for stress-adjacent skin benefits. South Korea's MFDS tightening of fermented-ingredient substantiation requirements is extending development timelines by twelve to eighteen months for novel formulations.
- Nutraceutical Drinks:Clinically-positioned SKUs extracting the highest per-unit margins through bioactive peptide concentrations and liposome encapsulation technology. Japanese FOSHU approval requirements compress go-to-market timelines while fragmenting formulation specifications.
Functional beverages sit at the top of the volume ranking, with nutraceutical drinks climbing the fastest as consumers trade up to clinical-grade positioning.
Ingredient:
Cost tier differentiation in active compounds separates mass-market hydration from premium elasticity claims, with marine-sourced inputs commanding substantial raw material premiums over synthetic or plant-derived alternatives.
- Collagen:Hydrolyzed marine and bovine peptides dominate formulation strategies, with wild-caught fish scale and skin sourcing clustering heavily in Japanese coastal prefectures. Seasonal catch volatility and climate-driven interruptions expose manufacturers to supply concentration risk.
- Hyaluronic Acid:Low-molecular-weight forms requiring aseptic cold-fill processing to preserve heat-sensitive actives. This technical constraint elevates per-unit production costs and limits contract manufacturing capacity.
- Vitamins:Lipid-soluble forms integrated through liposome encapsulation to enhance systemic absorption rates. Seoul manufacturers adopt this approach at accelerated pace to differentiate clinical efficacy claims.
- Antioxidants:Polyphenol and carotenoid compounds positioned for oxidative stress mitigation. EFSA rejection of certain hydration-related substantiation forces dual-formulation strategies for brands seeking pan-regional distribution.
Collagen maintains the steepest expansion trajectory in absolute volume terms, though hyaluronic acid is gaining share fastest as absorption-technology investments mature.
Packaging Type:
Customer type segmentation separates trial-oriented single-serve formats from committed-user bulk purchases, with social-commerce infrastructure collapsing acquisition costs for portable sampling options.
- Bottles:Multi-serve glass and PET formats anchoring pharmacy and premium grocery channels. Shiseido leverages century-old dermatological heritage to anchor premium positioning across East Asian pharmacy channels through this format.
- Tetra Packs:Aseptic carton technology preserving shelf stability for ambient distribution. Japan's deregulation of cosmetic-food hybrid retailing enables pharmacy chains to expand dedicated beauty-drink sections using this packaging.
- Cans:Aluminum formats for carbonated or nitrogen-dosed variants. Limited adoption in skin-booster applications due to incompatibility with heat-sensitive active preservation requirements.
- Sachets:Single-serve flexible packaging accelerating fastest through social-commerce livestreams. Tokyo and Seoul beauty influencers bundle samples with personalized skin assessment content, collapsing the path from awareness to first purchase among consumers aged twenty-two to thirty-five.
Bottles retain volume leadership in established markets, with sachets expanding most quickly as livestream commerce infrastructure matures.
Distribution Channel:
Geography and margin structure intersect in channel selection, with pharmacy elevation in Japan and duty-free dominance in South Korea creating divergent premium pathways.
- Online Retail:Domestic e-commerce ecosystems in South Korea, where Amorepacific Corporation dominates through fermented-ingredient formulations. Platform algorithms prioritize subscription models that compress customer lifetime value realization.
- Supermarkets:Mass grocery footprint for functional beverage SKUs with lower clinical positioning. Nestlé competes through nutritional science infrastructure at this tier.
- Health Stores:Specialized retail capturing wellness-oriented consumers seeking ingredient transparency. Vietnam and Indonesia urban centers show rising ingestible beauty awareness with minimal incumbent brand presence at this channel.
- Direct Sales:Personalized consultation models for premium nutraceutical SKUs. Male-targeted formulations addressing stress-induced skin fatigue remain underdeveloped, presenting whitespace for gender-specific positioning.
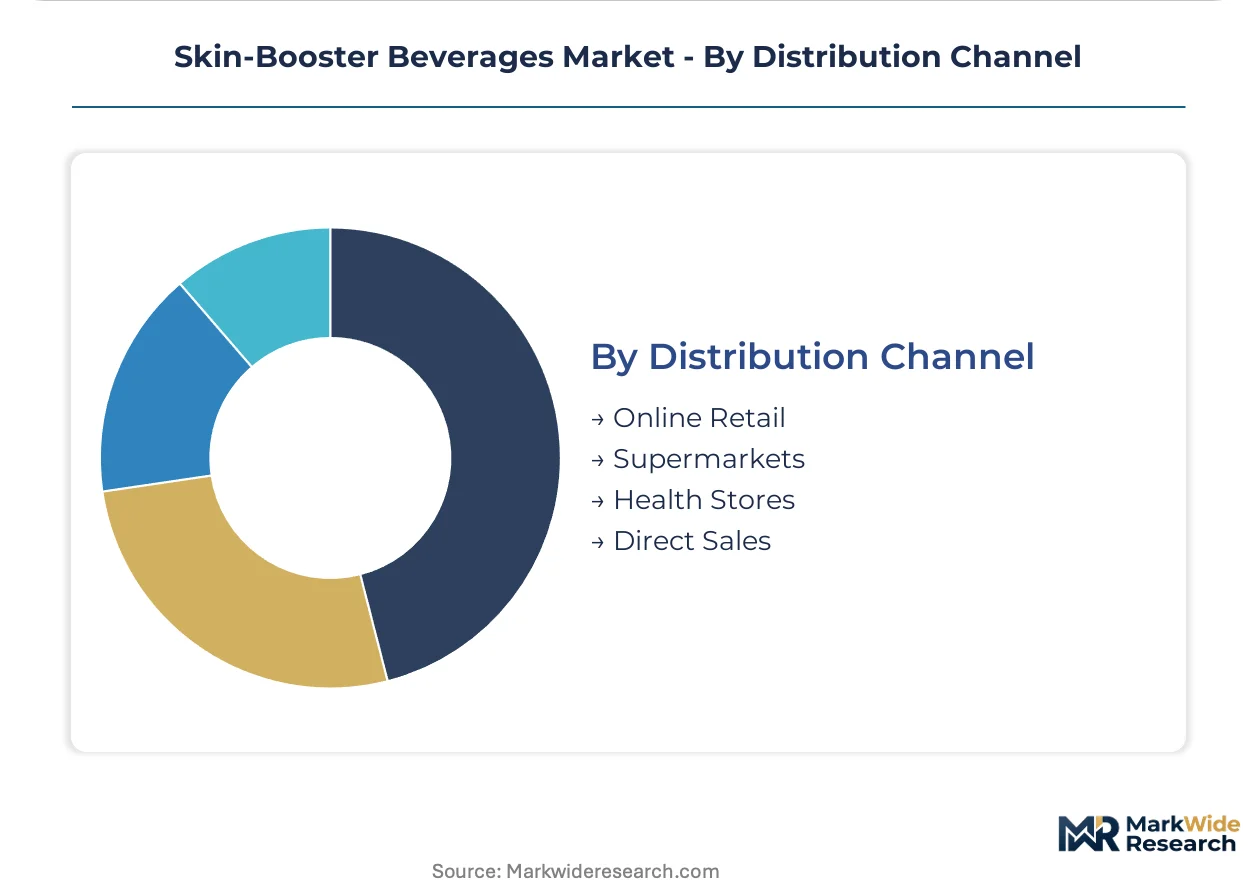
Online retail commands the dominant volume position, while health stores are gaining share fastest as Southeast Asian penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's FOSHU framework generates faster claim approvals than South Korea's MFDS, yet both systems compress go-to-market timelines compared to EU EFSA standards. Seoul's Gangnam corridor and Tokyo's Shibuya district anchor visible consumption that drives trial rates among working professionals. Manufacturers navigate divergent substantiation thresholds across these jurisdictions to avoid reformulation costs.
Japan
Tokyo's metropolitan prefectures concentrate aging demographics seeking ingestible beauty solutions through pharmacy channels. The Consumer Affairs Agency FOSHU approval process shapes which collagen-hydration claims survive on product labels. Coastal prefectures cluster wild-caught fish scale and skin sourcing for marine collagen, exposing supply chains to seasonal catch volatility.
South Korea
Seoul's duty-free and domestic e-commerce ecosystems drive fermented-ingredient formulation demand among twenty-two to thirty-five-year-old consumers. The Ministry of Food and Drug Safety tightened substantiation requirements for fermented-ingredient functional claims, extending development timelines by twelve to eighteen months. Gangnam district retailers dedicate premium shelf space to collagen-based ready-to-drink formats as visible consumption anchors.
Vietnam
Ho Chi Minh City and Hanoi show rising ingestible beauty awareness with minimal incumbent brand presence in health store channels. The country's functional food regulatory framework remains less stringent than East Asian counterparts, enabling faster product entry. Urban centers present first-mover positioning opportunities for collagen-specific SKUs targeting beauty-conscious demographics.
Indonesia
Jakarta's metropolitan area exhibits growing demand for single-serve sachet formats distributed through social-commerce livestreams. The national food and drug regulator maintains evolving standards for beauty-drink claims that lag Japanese and Korean sophistication. Local manufacturing partnerships help brands navigate import logistics and cold-chain infrastructure gaps.
United States
Los Angeles and New York metro areas concentrate early-adopter demographics for clinical-grade nutraceutical positioning. The FDA does not recognize collagen-hydration health claims permitted under Asian regulatory frameworks, forcing distinct formulation strategies. Premium beauty retailers in coastal cities test Asian-imported formats for diaspora and crossover consumer segments.
Skin-Booster Beverages Market Competitive Landscape
Japanese producers anchor one tier through century-old dermatological heritage and FOSHU-navigating expertise; South Korean specialists hold another via fermented-ingredient innovation and social-commerce infrastructure. The competitive set fragments across integrated beverage conglomerates, dedicated beauty houses, and contract manufacturing specialists serving private-label entrants. Three archetypes dominate: heritage beauty brands leveraging pharmacy channel elevation, nutritional science conglomerates competing through R&D scale, and agile domestic players capturing livestream commerce velocity. Capacity expansion in aseptic cold-fill processing and strategic partnerships for marine collagen sourcing represent the dominant competitive moves.
Within the heritage beauty tier, Shiseido Company, Limited and Amorepacific Corporation exemplify divergent geographic anchoring—Tokyo-based dermatological legacy versus Seoul-centric fermented formulation dominance. Nestlé occupies a position representing nutritional science infrastructure applied to functional beverage scale. These three entities illustrate how regulatory navigation capability and channel-specific positioning separate competitive tiers in this market.
| Leading Market Players |
|---|
| Shiseido Company, Limited |
| Nestlé |
| Amorepacific Corporation |
| The Bountiful Company |
| TCI Co., Ltd. |
| Kino Biotech Co., Ltd. |
| Minerva Research Labs |
| Meiji Holdings Co., Ltd. |
| Nitta Gelatin |
| Others |
Value Network & Pricing Analysis
Pharmacy chain procurement in Japan and social-commerce platform buyers in South Korea command divergent pricing models, with the former accepting clinical-grade premiums under FOSHU positioning while the latter compress per-unit costs through high-velocity sachet sampling.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for standard-grade collagen formulations, forcing established manufacturers to defend margin position through liposome encapsulation premiums. Three-tier pricing structure across premium nutraceutical, standard functional beverage, and economy hydration levels separates FOSHU-certified SKUs from mass-market alternatives. Cost compression in ambient-stable formats is intensifying because aseptic cold-fill contract capacity remains constrained. Direct-sales subscribers show lowest price sensitivity, while supermarket trial purchasers exhibit highest elasticity.
Supply Chain Analysis
Marine collagen feedstock rests on Japanese coastal prefectures, South Korean fermentation bioreactors, and emerging Indonesian tilapia aquaculture operations. Wild-caught fish scale and skin, low-molecular-weight hyaluronic acid, and liposome-encapsulated vitamin complexes constitute the critical input trinity. Single-source vulnerability concentrates in specific Japanese fishing cooperatives exposed to climate-driven catch volatility. Distribution runs through refrigerated pharmacy networks in Japan, ambient e-commerce fulfillment in South Korea, and social-commerce livestream intermediaries across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Vietnam and Indonesia's less stringent functional food frameworks enable faster product entry at 40-60% lower substantiation cost than Japanese FOSHU or South Korean MFDS pathways.
For Market Incumbents: Anchor FOSHU and MFDS certification portfolios as defensive moats against private-label entrants leveraging Southeast Asian regulatory shortcuts. Prioritize captive supply agreements with Japanese coastal fishing cooperatives to neutralize marine collagen concentration risk. Cold-chain infrastructure ownership represents the critical lever for margin defense against integrated beverage conglomerates. For New Entrants and Emerging Players: Social-commerce platform operators offer the most accessible channel partnership structure for circumventing incumbent pharmacy shelf dominance. Target Indonesia's metropolitan livestream commerce infrastructure for single-serve sachet launches ahead of fermented-ingredient positioning. Male-targeted stress-fatigue formulations present the least contested white space across East Asian markets. For Investors and Strategic Acquirers: Nutritional science conglomerates with existing functional beverage infrastructure are the most active acquirer in this space, seeking fermented-ingredient capabilities and Southeast Asian distribution access. Long-term viability hinges on regulatory navigation talent scarcity creating consolidation pressure over the next decade. Watch for MFDS tightening enforcement on fermented-ingredient claims as the inflection signal for competitive shakeout timing.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Fill Capacity Expansion | Preservation of heat-sensitive actives at scale separates clinical-grade from commodity positioning. |
| Marine Collagen Supply Agreement | Japanese coastal sourcing concentration demands multi-cooperative partnerships to mitigate climate exposure. |
| FOSHU Claim Substantiation Investment | Japanese Consumer Affairs Agency approval unlocks pharmacy channel premiums unavailable to unverified competitors. |
| Social-Commerce Platform Integration | Tokyo and Seoul influencer bundling collapses customer acquisition costs for trial-format penetration. |
| Men's Functional Beverage Launch | Gender-specific whitespace in stress-fatigue positioning offers first-mover advantage before incumbent response. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers at heritage beauty houses, category buyers at Japanese pharmacy chains, fermentation R&D directors at South Korean biotech firms, and supply planners at marine collagen processors with secondary validation through MFDS functional food registration databases, FOSHU approval filings, Japanese fisheries cooperative catch reports, and social-commerce platform transaction disclosures. Bottom-up SKU-level volume builds and top-down category spend estimates were cross-referenced for triangulation.
Comparable historical periods anchored the projection horizon to established upgrade cycle patterns in ingestible beauty adoption. Segmentation dimensions modeled include product type tier, active ingredient concentration grade, packaging format portability, and distribution channel margin structure. CAGRs were derived from regression analysis against urban beauty corridor expansion rates and livestream commerce penetration curves. Forecast inputs incorporated FOSHU approval timeline distributions and MFDS substantiation requirement evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to marine collagen supply disruption, regulatory claim tightening, and cold-chain infrastructure investment pacing. Assumptions reflect documented stakeholder input and published regulatory frameworks. A small set of triggers—MFDS enforcement intensity, Japanese coastal catch variance, and Southeast Asian social-commerce platform consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Lactates Market
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Functional Carbohydrates Market
Nutritional Supplements
Vegan Protein Market
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Tongkat Ali Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
Plant Based Iron Supplements Market
Nutritional Supplements
South America Collagen Supplements Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Liquid Dietary Supplements Market