
 Marine Hydrolyzed Collagen Market | 2026-2036
Marine Hydrolyzed Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Hydrolyzed Collagen Market Intelligence
Enzymatic hydrolysis at low temperatures is rewriting extraction economics for marine collagen processors. Gelita AG leverages its multi-species sourcing network to sustain supply continuity across Atlantic and Pacific fisheries. Nippi Inc. anchors premium positioning through specialized peptide fractionation capabilities that target dermal matrix applications. Vinh Hoan Corporation competes on pangasius-skin feedstock integration, controlling raw material flows from its aquaculture operations.
Marine hydrolyzed collagen denotes protein fractions extracted from fish skin or scales, typically yielding peptides under 10 kilodaltons through controlled enzymatic cleavage of telopeptide regions; this molecular profile enables cold-water solubility and rapid gastrointestinal absorption for nutraceutical and cosmeceutical delivery systems. Powder formulations dominate bulk ingredient shipments to functional food compounders, while gummies capture accelerated growth in direct-to-consumer beauty supplement channels. Collagen peptides within the form taxonomy command margin premiums over standard gelatin hydrolysates due to validated bioactive signaling properties in clinical dermatology research.
EFSA novel food assessments and FDA GRAS self-affirmation pathways shape ingredient market access timelines for European and North American suppliers. ISO 17025-accredited laboratories and REACH-compliant supply documentation now function as baseline commercial requirements rather than differentiators. Stakeholders must monitor evolving marine sourcing certification schemes and peptide bioavailability substantiation standards as the primary variables determining competitive defensibility.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are compressing ingredient approval timelines and forcing nutraceutical compounders to validate marine sourcing chains through ISO 17025-accredited laboratories.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined safety assessments for fish-derived peptides accelerate European market entry for hydrolyzed collagen suppliers.
- Sports Nutrition Powder Demand:Functional food manufacturers in Germany, Japan, and the United States prioritize cold-water soluble peptide formats for protein fortification applications.
- Enzymatic Hydrolysis Advancement:Low-temperature extraction protocols reduce energy input costs while preserving bioactive peptide fractions for dermal matrix applications.
Market Restraints
- Fishery Supply Concentration:Atlantic and Pacific wild-catch volatility constrains raw material predictability for processors dependent on multi-species sourcing networks.
- REACH Documentation Burden:European suppliers face escalating compliance costs for traceability documentation across complex marine supply chains.
- Gelatin Hydrolysate Substitution:Lower-cost bovine and porcine collagen alternatives capture price-sensitive segments in emerging functional food markets.
Strategic Opportunities
- Direct-to-Consumer Gummy Formats:Beauty supplement channels show accelerated uptake of flavored delivery systems targeting skin health positioning.
- Pangasius Aquaculture Integration:Vietnam-based processors leverage captive skin feedstock from integrated aquaculture operations to secure cost-advantaged supply.
- Peptide Bioavailability Substantiation:Clinical dermatology research validating signaling properties creates premium pricing power over standard hydrolysates.
Industry Challenges
- Peptide Fractionation Expertise Scarcity:Specialized technical talent for molecular weight separation and bioactivity profiling commands wage premiums that constrain mid-tier processor expansion.
- GRAS Self-Affirmation Complexity:FDA notification pathways require toxicological dossiers that extend U.S. market access timelines for novel marine species sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Hydrolyzed Collagen Market |
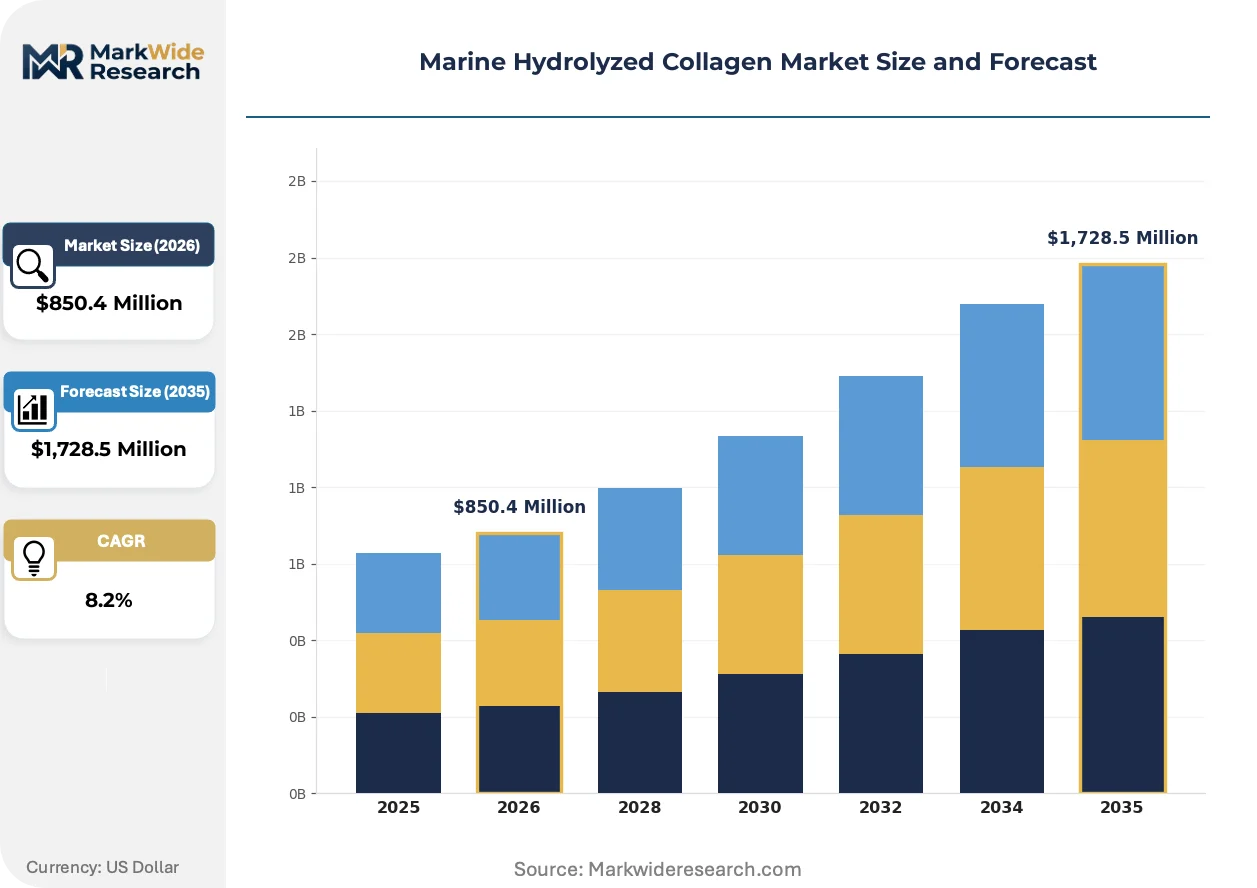
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,728.5 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsules, Gummies Application: Cosmetics, Nutraceuticals, Functional Foods, Dietary Supplements Form: Hydrolyzed, Non-Hydrolyzed, Gelatin, Collagen Peptides End User: Healthcare, Beauty Industry, Sports Nutrition, Food & Beverage |
| Companies Covered | Weishardt, Italgelatine S.p.A., Amicogen Co. Ltd., Lapi Gelatin S.p.A., Norland Products Inc., Gelita AG, Vinh Hoan Corporation, Nippi Inc., Nitta Gelatin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Hydrolyzed Collagen Market Strategic Shifts & Innovations
Extraction technology convergence and regulatory transparency mandates are restructuring how marine collagen processors compete on cost, certification, and clinical substantiation.
Low-temperature enzymatic hydrolysis systems operating below 50°C preserve heat-labile bioactive peptides while reducing thermal energy inputs. Nutraceutical compounders in Japan and Germany adopt these systems to meet clean-label procurement specifications. Acid-based extraction protocols are rendering obsolete as buyers prioritize enzymatic methods for peptide integrity.
EFSA novel food assessment harmonization with REACH substance registration requirements creates dual compliance checkpoints for European market access. Marine collagen suppliers must document fishery sustainability certification alongside peptide safety profiles. Powder ingredient shipments face the strictest documentation scrutiny, while finished gummy brands navigate simplified downstream obligations.
Beauty supplement buyers now demand cold-chain-independent stability and rapid dissolution metrics as primary selection criteria. Direct-to-consumer channels displace traditional ingredient distributor relationships for small-batch cosmetic brands. This preference shift concentrates in the United States and South Korea where influencer-driven skin health positioning dominates marketing spend.
Marine Hydrolyzed Collagen Market Segmentation
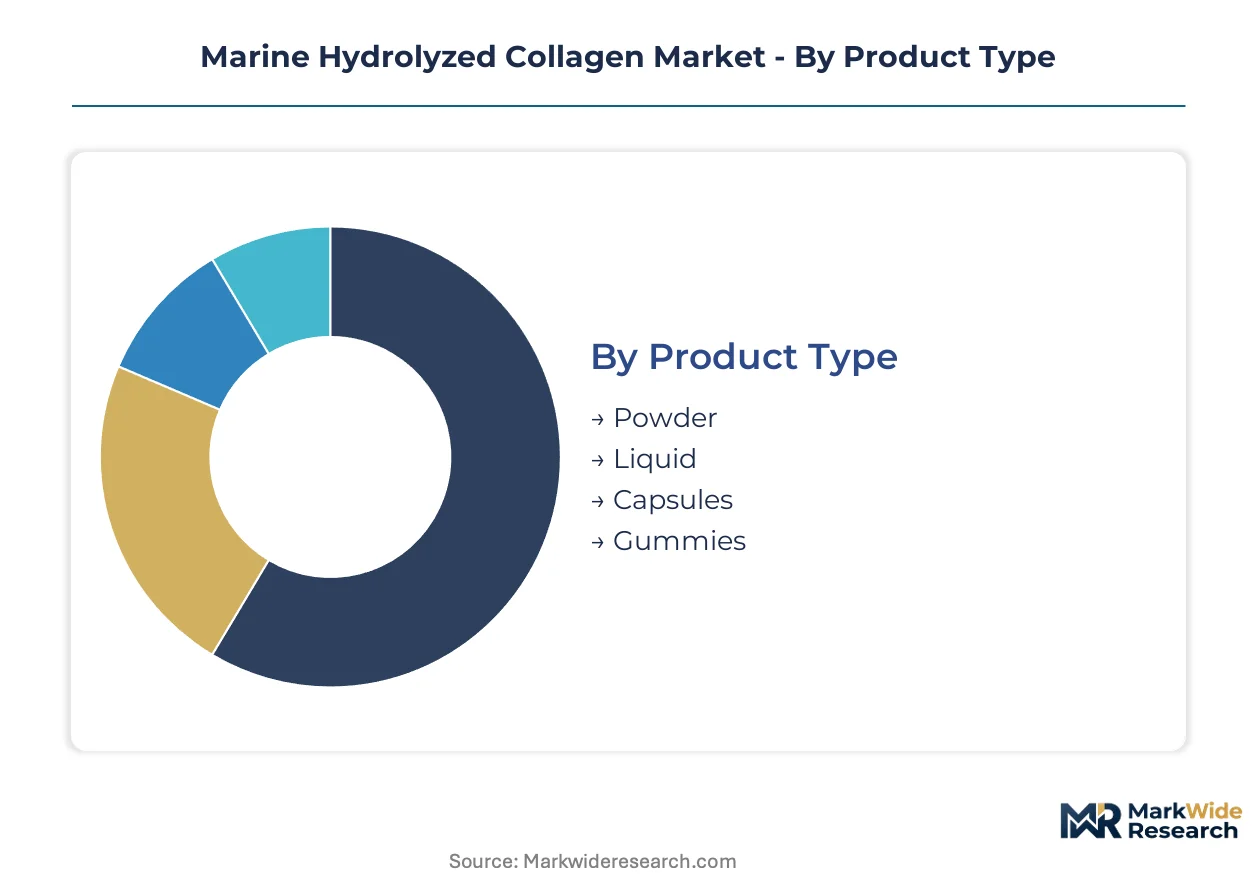
Marine hydrolyzed collagen processors compete across four distinct segmentation axes that determine pricing power, regulatory pathway complexity, and customer acquisition costs. Each dimension carries divergent margin structures and technical requirements that reshape supplier positioning.
Product Type:
Volume concentration and formulation flexibility separate the delivery format tiers, with powder commanding bulk ingredient economics while gummies reshape direct-to-consumer channels.
- Powder:Cold-water soluble peptide fractions under 10 kilodaltons integrate into sports nutrition fortification systems. German and Japanese functional food manufacturers specify this format for protein blending operations where dissolution speed determines processing throughput.
- Gummies:Flavored delivery systems capture accelerated uptake in beauty supplement channels across the United States and South Korea. Influencer-driven skin health positioning commands retail price premiums despite higher per-unit manufacturing complexity.
- Liquid:Ready-to-drink collagen shots target convenience-seeking demographics in urban Japanese and South Korean markets.
- Capsules:Standardized dosing formats serve pharmaceutical-adjacent positioning in European nutraceutical retail.
Powder commands the established base. The steepest expansion runs through gummies.
Application:
End-use requirements diverge sharply between clinical substantiation demands in dermatology and the formulation flexibility priorities of food technologists.
- Nutraceuticals:EFSA novel food assessments and FDA GRAS self-affirmation pathways govern market access for peptide-based supplements. Clean-label procurement specifications from German and U.S. compounders mandate ISO 17025-accredited laboratory documentation.
- Cosmetics:Dermal matrix applications require specialized peptide fractionation capabilities that target specific molecular weight ranges for epidermal penetration claims. South Korean beauty brands lead clinical validation spending for bioactive signaling properties.
- Functional Foods:Protein fortification applications in Japan and Germany prioritize sensory neutrality and heat stability during processing.
- Dietary Supplements:Direct-to-consumer channels in the United States emphasize subscription model compatibility and packaging differentiation.
Nutraceuticals anchor revenue concentration. Cosmetics is gaining share fastest through premium peptide positioning.
Form:
Processing intensity and bioactivity preservation create sharp margin differentiation across the molecular preparation spectrum.
- Collagen Peptides:Controlled enzymatic cleavage of telopeptide regions yields fractions with validated bioactive signaling properties. Clinical dermatology research supports margin premiums over standard hydrolysates in premium beauty and sports recovery applications.
- Hydrolyzed:Partial enzymatic breakdown produces intermediate molecular weight distributions suitable for bulk functional food fortification where cost efficiency outweighs bioactivity specificity.
- Gelatin:Thermal denaturation without targeted enzymatic treatment serves industrial applications with minimal peptide bioactivity requirements.
- Non-Hydrolyzed:Native collagen structures persist in specialized biomedical applications requiring intact triple-helix architecture.
Hydrolyzed formats dominate commodity volume. Collagen peptides is climbing the fastest on substantiation-backed pricing power.
End User:
Customer procurement sophistication spans from institutional healthcare formulators to influencer-dependent beauty brands with divergent technical service expectations.
- Sports Nutrition:Protein fortification specifications from German and U.S. functional food manufacturers emphasize amino acid profile completeness and batch-to-batch consistency for powdered drink mixes.
- Beauty Industry:South Korean and U.S. cosmetic brands demand peptide bioavailability substantiation and cold-chain-independent stability for direct-to-consumer gummy and serum formats.
- Healthcare:Medical nutrition applications in Japan require PMDA consultation for therapeutic positioning claims.
- Food & Beverage:Clean-label compliance and sensory neutrality priorities govern procurement from European compounders facing EFSA transparency mandates.
Sports Nutrition holds the volume base. The Beauty Industry shows the steepest expansion trajectory through influencer-channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam exports pangasius-skin collagen to German functional food compounders and Japanese nutraceutical manufacturers, establishing a trans-Pacific trade corridor that bypasses Atlantic fishery volatility.
Germany
Sports nutrition powder demand from functional food manufacturers drives procurement of cold-water soluble peptide fractions. EFSA novel food assessments mandate ISO 17025-accredited laboratory documentation for all marine-derived ingredient imports. The Baden-Württemberg cluster hosts multiple nutraceutical compounders validating clean-label supply chains.
United States
Direct-to-consumer gummy formats capture accelerated growth through influencer-driven beauty supplement channels. FDA GRAS self-affirmation pathways extend market access timelines for novel marine species sources. Southern California and New York Metro concentrate direct-to-consumer brand headquarters and contract manufacturing capacity.
Japan
Ready-to-drink collagen shots target convenience-seeking demographics in urban centers with PMDA consultation requirements for therapeutic positioning claims. The Kanto region surrounding Tokyo anchors peptide fractionation expertise and clinical dermatology research partnerships. Osaka-based functional food manufacturers prioritize sensory neutrality in protein fortification applications.
South Korea
Beauty industry demand for peptide bioavailability substantiation concentrates in Seoul Capital Area cosmetic brands. MFDS cosmetic ingredient regulations govern dermal matrix application claims and stability testing protocols. Influencer-channel marketing spend dominates customer acquisition for skin health positioning supplements.
Vietnam
Pangasius aquaculture integration secures captive skin feedstock for cost-advantaged supply to export markets. The Mekong Delta region controls raw material flows from integrated farming operations through processing facilities. Vietnamese processors compete on backward integration into upstream aquaculture rather than multi-species sourcing networks.
Marine Hydrolyzed Collagen Market Key Industry Players
On the supply side, the industry is bifurcated between multi-species marine processors and aquaculture-integrated specialists. Tiered competitive positioning separates premium peptide fractionators from commodity hydrolysate suppliers. Three archetypes dominate: integrated aquaculture operators controlling captive feedstock, multi-species Atlantic-Pacific processors sustaining supply continuity, and specialized fractionators targeting dermal matrix applications. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure fishery certification and clinical substantiation capabilities.
Within the aquaculture-integrated tier, Vinh Hoan Corporation exemplifies backward integration into pangasius farming operations. Among multi-species processors, Gelita AG and Nippi Inc. occupy positions spanning Atlantic and Pacific sourcing networks. These three companies represent the structural split between captive supply control and geographic diversification strategies that define competitive positioning in marine collagen extraction.
| Leading Market Players |
|---|
| Weishardt |
| Italgelatine S.p.A. |
| Amicogen Co. Ltd. |
| Lapi Gelatin S.p.A. |
| Norland Products Inc. |
| Gelita AG |
| Vinh Hoan Corporation |
| Nippi Inc. |
| Nitta Gelatin Ltd. |
| Others |
Cost & Logistics Intelligence
The Vietnam-to-Germany pangasius-skin freight corridor carries escalating logistics costs that amplify supply concentration effects while compressing margins for mid-tier processors lacking captive aquaculture integration.
Pricing Analysis
Enzymatic hydrolysis systems command substantial premiums over acid-based extraction platforms, while next-generation low-temperature peptide fractionation technologies widen the gap further. Pricing stratifies across premium, standard, and economy tiers based on molecular weight specificity and ISO 17025 certification status. Cost compression in standard hydrolysates is intensifying because bovine and porcine gelatin alternatives capture price-sensitive functional food segments in emerging markets. Beauty industry buyers exhibit the lowest price sensitivity due to bioavailability substantiation requirements, while bulk sports nutrition compounders negotiate aggressively on volume contracts.
Supply Chain Analysis
Pangasius skin feedstock from Vietnam, Atlantic cod processing bycatch from Norway, and Pacific tuna scale residuals from Japan anchor upstream material flows for marine collagen extraction. Processors draw from enzymatic preparation stocks, cold-chain logistics networks, and REACH-compliant documentation systems to maintain market access. Single-source vulnerability concentrates in Mekong Delta aquaculture operations exposed to climate-induced water quality fluctuations. Distribution runs through ingredient distributors serving functional food compounders, direct-to-consumer contract manufacturers, and cosmetic formulation houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across peptide fractionation expertise, regional regulatory pathways, and end-use application requirements creates multiple niche entry points for specialists targeting underserved buyer archetypes.
For Market Incumbents: Harden supply continuity through multi-species sourcing diversification across Atlantic and Pacific fisheries to mitigate pangasius aquaculture concentration risk. Invest in ISO 17025-accredited laboratory certification to defend margin position against emerging enzymatic hydrolysis specialists from South Korea. Prioritize backward integration into fishery sustainability certification schemes as channel control leverage. For New Entrants and Emerging Players: Mid-market cosmetic brands in South Korea seeking peptide bioavailability substantiation without Gelita AG or Nippi Inc. pricing premiums represent the most penetrable entry point. Vietnam-based processors lacking downstream brand relationships offer partnership opportunities for direct-to-consumer gummy format launches. Target influencer-channel marketing agencies as co-investment partners to bypass traditional distributor gatekeeping. For Investors and Strategic Acquirers: Specialized peptide fractionators with clinical dermatology research partnerships and PMDA consultation experience command scarcity premiums in acquisition markets. Long-term viability hinges on regulatory pathway acceleration capabilities rather than raw material cost advantages alone. Watch for EFSA novel food assessment harmonization completion as an inflection signal for European market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aquaculture | Vietnamese processors secure pangasius skin feedstock cost advantages against Atlantic fishery volatility. |
| ISO 17025 Laboratory Certification | EFSA and FDA documentation requirements elevate accredited facilities to baseline commercial necessity. |
| Peptide Bioavailability Clinical Trials | South Korean beauty brands validate signaling properties to support premium pricing over hydrolysates. |
| Direct-to-Consumer Gummy Launch | Influencer-channel positioning in the United States bypasses traditional ingredient distributor relationships. |
| Multi-Species Sourcing Diversification | Gelita AG sustains supply continuity across Atlantic cod and Pacific tuna residual networks. |
Research Approach
The analysis maps enzymatic hydrolysis technology tiers, peptide fractionation capability levels, and regulatory pathway specializations, each validated through primary interviews with marine collagen extraction plant managers, nutraceutical procurement leads at German functional food compounders, cosmetic R&D directors in Seoul, and fishery sustainability certification officers. Secondary validation draws from EFSA novel food assessment databases, FDA GRAS notification filings, REACH substance registration records, and ISO 17025 accreditation directories. Bottom-up volume modeling and top-down market sizing triangulate across these sources.
Fixed assumptions include EFSA and FDA regulatory pathway timelines, enzymatic hydrolysis technology diffusion rates, and fishery certification scheme adoption curves across the analysis window. Variable inputs span pangasius aquaculture yield fluctuations, bovine collagen substitution elasticity in price-sensitive segments, and influencer-channel marketing spend allocation shifts. Segmentation dimensions modeled include product type, application, molecular preparation form, and end-user procurement sophistication. CAGRs derive from weighted average growth contributions across these segments calibrated to historical volume trajectories in sports nutrition and beauty supplement channels.
Practitioners should monitor EFSA assessment backlog clearance rates, Mekong Delta water quality indices, and South Korean clinical trial publication velocity for early signals of forecast revision triggers. Cross-checking against customs trade data for Vietnam-to-Germany pangasius collagen shipments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Bone Broth Protein Market
Nutritional Supplements
Camu Camu Extract Market
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
Fish Collagen Peptides Market
Nutritional Supplements
Nutritional Food and Drink Market
Nutritional Supplements
Natural Vitamin E Product Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
Global Liver Health Supplements Market
Nutritional Supplements
Mediterranean Citrus Nutricosmetic Complex Market
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Asia-Pacific Dietary Supplement Market
Nutritional Supplements
Australia Nutraceuticals Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
Vegan Collagen Protein Market