
 Fish Collagen Market | 2026-2036
Fish Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Collagen Market Foresight
Marine biochemistry expertise is unwinding capacity bottlenecks as specialized talent shortages ease across Nordic and East Asian processing hubs. GELITA AG leverages captive fishery partnerships to secure Atlantic cod skin supply chains. Nitta Gelatin Inc. anchors its position through advanced enzymatic hydrolysis capabilities in Japanese coastal facilities. Rousselot competes via integrated gelatin-to-peptide verticality across European marine rendering operations.
Fish collagen comprises thermally denatured and enzymatically processed protein fractions extracted from teleost and elasmobranch tissues, with triple-helix preservation critical for bioactive peptide retention in dermal matrix applications. Hydrolyzed collagen dominates value capture due to superior bioavailability indices in oral delivery formats, while native collagen retains premium positioning in wound closure matrices. Cosmetics applications command widening margin pools as marine-origin claims displace mammalian alternatives in K-beauty and European clean-label formulations.
EFSA novel food panels and FDA GRAS self-affirmation pathways shape divergent market access timelines for fish-derived ingredients entering US and European supplement channels. Japan's PMDA and METI coordinate on marine functional food labeling standards that directly influence peptide purity thresholds for domestic and export-bound production. Stakeholders must track regulatory harmonization momentum between ASEAN cosmetic directive frameworks and EU REACH-derived safety protocols to anticipate reformulation requirements.
Market Dynamics
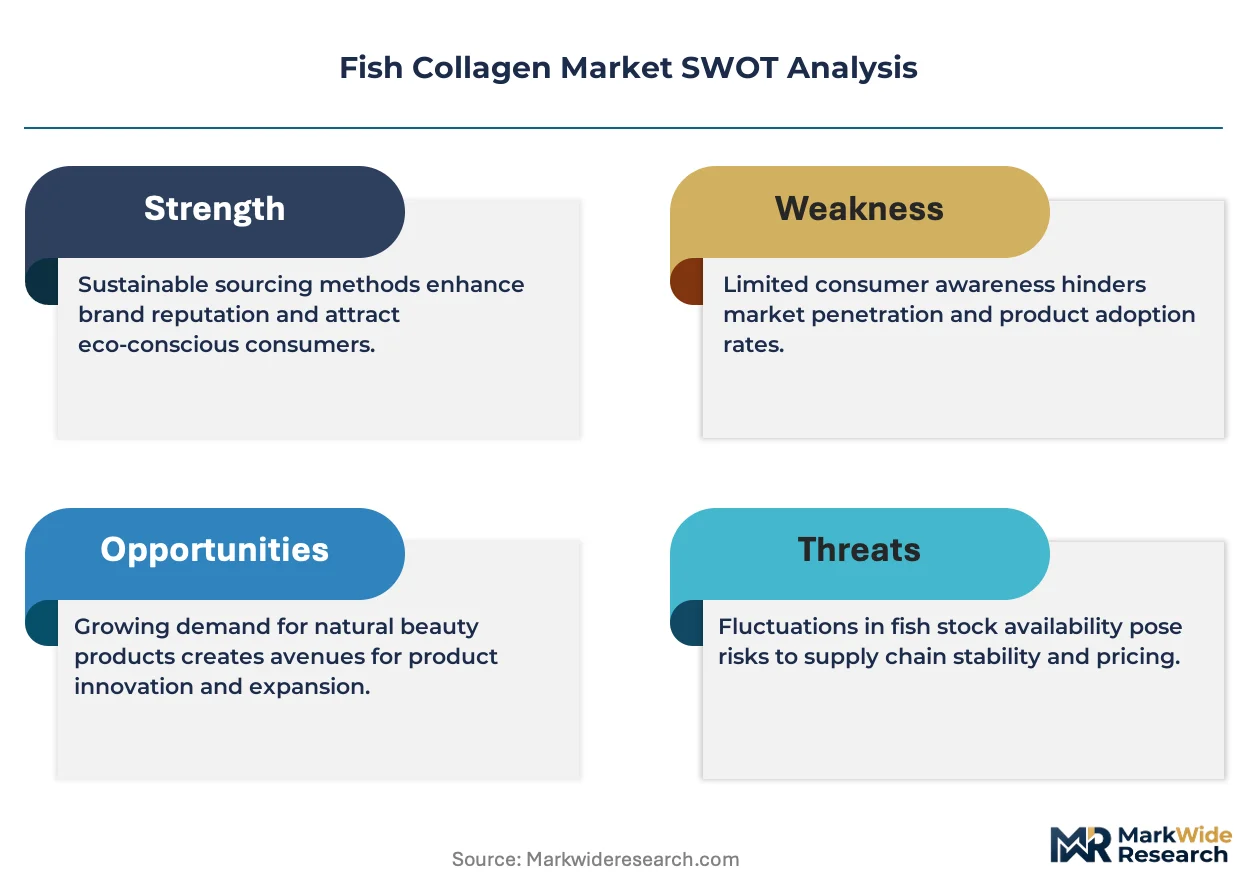
Marine biochemistry specialization is reshaping competitive boundaries as enzymatic hydrolysis capabilities concentrate among Nordic and East Asian processors, compressing margins for commodity-grade suppliers while premium peptide fractions capture widening value pools.
Growth Catalysts
- EFSA Novel Food Pathway:Streamlined ingredient approvals accelerate European market entry for hydrolyzed marine collagen fractions, reducing time-to-shelf for functional food applications.
- K-Beauty Formulation Standards:South Korean cosmetics manufacturers displace mammalian collagen with marine-origin alternatives in anti-aging topicals, driving procurement scale.
- Enzymatic Hydrolysis Advancement:Improved bioavailability indices in oral delivery formats expand nutraceutical adoption beyond traditional gelatin applications.
Market Restraints
- Atlantic Cod Skin Supply Concentration:Nordic fishery partnerships control premium raw material flows, creating bottleneck vulnerability for non-integrated processors.
- Triple-Helix Preservation Costs:Thermal denaturation control requires specialized equipment, elevating capex thresholds for native collagen production.
- Bovine/Porcine Collagen Substitution:Lower-cost mammalian alternatives retain cost-sensitive nutraceutical segments despite clean-label headwinds.
Strategic Opportunities
- Japan PMDA Functional Food Labeling:Peptide purity thresholds for domestic consumption create export-quality standards that premium producers can leverage in adjacent markets.
- ASEAN Cosmetic Directive Harmonization:Alignment with EU REACH-derived safety protocols opens formulation pathways for marine-derived ingredients across Southeast Asian manufacturing hubs.
- Wound Closure Matrix Applications:Native collagen retention of structural integrity addresses unmet needs in advanced dermal regeneration therapies.
Industry Challenges
- Marine Biochemistry Talent Scarcity:Specialized enzymatic processing expertise remains concentrated in Japanese and Nordic coastal facilities, limiting geographic expansion.
- FDA GRAS Self-Affirmation Complexity:Divergent US-EU regulatory timelines create dual-track compliance burdens for supplement channel entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Collagen Market |
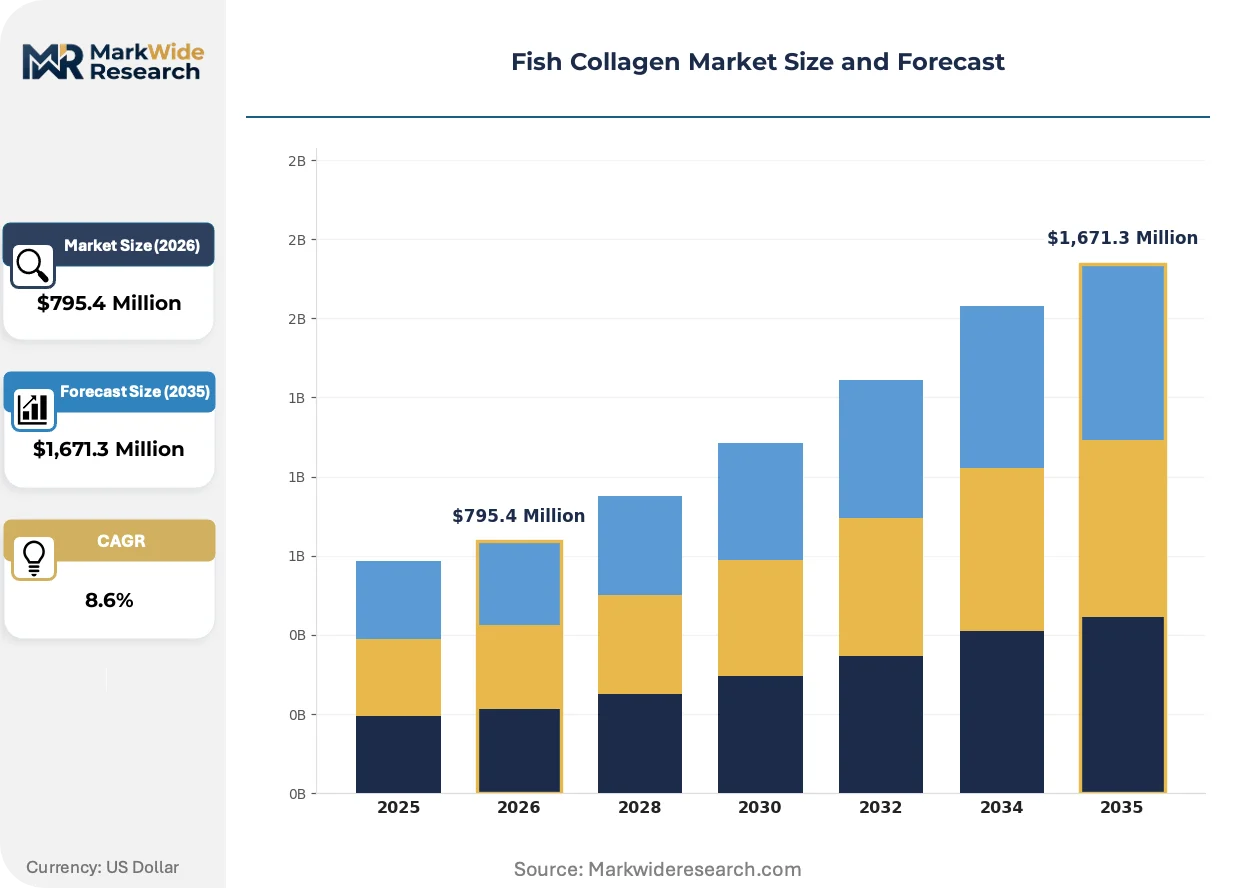
| Market Size in 2026 | $795.4 Million |
| Market Size in 2035 | $1,671.3 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Native Collagen, Peptides, Gelatin, Others Source: Fish Skin, Fish Scales, Fish Bones, Fish Cartilage, Others Application: Dietary Supplements, Cosmetics, Pharmaceuticals, Functional Foods, Animal Nutrition End User: Manufacturers, Research Laboratories, Formulators, Contract Packaging, Distributors |
| Companies Covered | GELITA AG, Nitta Gelatin Inc., Rousselot, Weishardt Group, Vital Proteins, Amicogen Inc., Hangzhou Nutrition Biotechnology Co., Ltd, Norland Products Inc, Seagarden AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Collagen Market Shifts & Advancements
Processing technology convergence and regulatory pathway differentiation are compressing traditional competitive moats while opening premium positioning for biochemistry-specialized operators.
Cold-enzymatic extraction protocols are decomposing thermal degradation losses in peptide recovery, enabling cosmetic formulators in Osaka and Seoul to specify higher molecular weight fractions for dermal matrix applications. This precision is compressing commodity gelatin margins while expanding certified-peptide premium tiers.
EU CSRD disclosure mandates now require marine ingredient provenance tracking, forcing renderers to document fishery partnership chains and enzymatic processing parameters. Supplement and cosmetics brands sourcing from European operations face accelerated compliance investments, with German and French manufacturers leading traceability system deployment.
Direct-to-clinic sampling programs are displacing traditional distributor relationships in Japanese and South Korean aesthetic medicine channels, compressing wholesale margins while capturing end-user preference data. This channel compression is most visible in Tokyo and Seoul metropolitan clusters where dermatology clinics consolidate procurement decisions.
Fish Collagen Market Segmentation
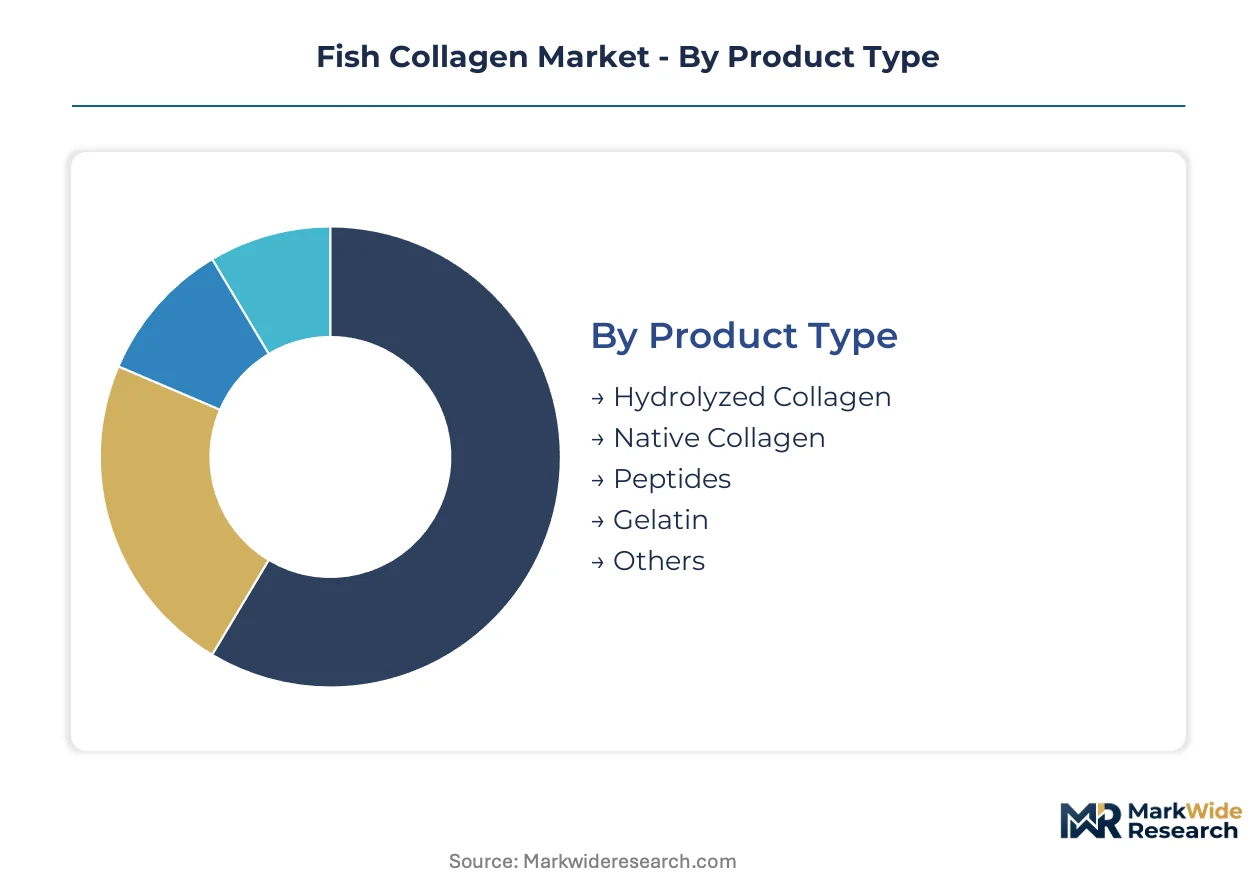
Fish collagen segmentation reflects divergent regulatory pathways across product formats and source tissues. EFSA novel food panels, FDA GRAS frameworks, and Japan's PMDA functional food standards each favor specific molecular weight fractions and extraction methods.
Product Type:
EFSA novel food authorization timelines favor hydrolyzed fractions under 10,000 Daltons, while FDA GRAS self-affirmation accommodates broader molecular weight ranges in supplement applications.
- Hydrolyzed Collagen:Enzymatically cleaved peptides below 5,000 Daltons demonstrate superior bioavailability indices in oral delivery. Japanese nutraceutical manufacturers in Osaka and Tokyo metropolitan clusters specify these fractions for PMDA-compliant functional food labeling.
- Native Collagen:Triple-helix structural integrity preserved through cold-extraction protocols commands wound closure matrix applications. German medical device manufacturers prioritize Atlantic cod skin-derived native fractions for dermal regeneration therapies.
- Peptides:Bioactive di- and tripeptide sequences drive K-beauty formulation procurement in Seoul.
- Gelatin:Thermal denaturation products retain cost-sensitive food and pharmaceutical capsule segments.
- Others:Collagen blends and modified derivatives serve niche industrial applications.
Established volume favors Hydrolyzed Collagen; emerging adoption favors Native Collagen.
Source:
Raw material procurement costs stratify sharply based on fishery partnership proximity and seasonal landing volumes.
- Fish Skin:Atlantic cod and Alaskan pollock skins yield premium triple-helix fractions. Nordic coastal processors in Norway and Iceland leverage captive supply agreements with trawler cooperatives.
- Fish Scales:Tilapia and pangasius scale processing concentrates in Vietnamese and Thai aquaculture hubs. Scale-derived collagen avoids mammalian pathogen concerns in clean-label cosmetics.
- Fish Bones:Post-fillet processing residues from Chilean salmon farms supply calcium-enriched fractions.
- Fish Cartilage:Shark and ray cartilage extraction yields chondroitin-coextracted matrices.
- Others:Fin and swim bladder tissues serve traditional medicine channels in East Asia.
Scale-derived sourcing gains share fastest in cosmetics; skin-derived sourcing retains premium nutraceutical positioning.
Application:
End-use profitability diverges based on certification requirements and formulation complexity barriers.
- Dietary Supplements:Powder and capsule formats dominate volume. US direct-to-consumer brands leverage FDA GRAS self-affirmation to compress launch timelines versus EFSA novel food pathways.
- Cosmetics:Marine-origin claims displace mammalian collagen in K-beauty anti-aging topicals. Seoul formulators specify enzymatically processed fractions for dermal penetration specifications.
- Pharmaceuticals:Wound closure matrices and hemostatic applications require ISO 13485-certified production.
- Functional Foods:Beverage fortification and gummy formats expand in Japanese convenience retail.
- Animal Nutrition:Pet food and aquaculture feed applications compete on commodity gelatin pricing.
Cosmetics applications command widest margin expansion; functional foods represent the steepest volume trajectory.
End User:
Channel structure determines specification control and pricing leverage across the value chain.
- Manufacturers:Integrated nutraceutical and cosmetics producers in Japan and South Korea specify peptide purity thresholds directly.
- Research Laboratories:Academic and clinical trial sponsors drive native collagen demand for regenerative medicine protocols.
- Formulators:Contract cosmetic developers in Seoul and Osaka translate marine-origin claims into finished product positioning.
- Contract Packaging:Third-party encapsulation and sachet filling services compete on throughput scale.
- Distributors:Traditional wholesale relationships face compression from direct-to-clinic sampling programs in Tokyo and Seoul aesthetic medicine clusters.
Manufacturer direct procurement dominates volume; research laboratory channels expand most quickly for native collagen fractions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese consumers ingest fish collagen predominantly through functional food formats, while South Korean and German buyers prioritize topical cosmetic applications and medical-grade matrices respectively.
Japan
PMDA functional food labeling standards drive peptide purity specifications for domestic nutraceutical manufacturers. METI coordinates marine ingredient safety protocols with export certification requirements. Osaka and Tokyo metropolitan clusters concentrate enzymatic hydrolysis capacity for beverage fortification and gummy formats.
South Korea
K-beauty formulators specify marine-origin collagen for anti-aging topical penetration claims. MFDS cosmetic ingredient safety assessments align with ASEAN directive harmonization efforts. Seoul-based contract developers translate marine sourcing into premium finished product positioning.
Germany
EFSA novel food authorization timelines favor hydrolyzed fractions entering European supplement channels. CSRD disclosure mandates force marine provenance tracking through fishery partnership documentation. Hamburg and North Sea coastal processors deploy traceability systems ahead of continental compliance deadlines.
Norway
Atlantic cod skin supply agreements with trawler cooperatives secure premium raw material flows. EFSA streamlined approval pathways accelerate ingredient market entry for Nordic processors. Bergen and Tromsø facilities leverage captive fishery partnerships for triple-helix fraction production.
United States
FDA GRAS self-affirmation compresses supplement launch timelines versus European regulatory pathways. Direct-to-consumer brands exploit regulatory agility in powder and capsule formats. California and Northeast corridor distribution hubs consolidate procurement from multiple sourcing origins.
Fish Collagen Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in fish collagen supply. The upper tier controls captive fishery partnerships and enzymatic processing infrastructure. Specialist operators concentrate on peptide fraction purification or regional cosmetic formulation supply. Competitive moves center on backward integration into raw material sourcing and geographic expansion into ASEAN manufacturing hubs.
Within the integrated tier, GELITA AG anchors European marine rendering operations through Atlantic supply chain control. Nitta Gelatin Inc. occupies a position representing Japanese coastal processing specialization. Rousselot exemplifies gelatin-to-peptide verticality across Nordic and European facilities. These three entities represent distinct geographic anchoring strategies rather than overlapping territorial competition.
| Leading Market Players |
|---|
| GELITA AG |
| Nitta Gelatin Inc. |
| Rousselot |
| Weishardt Group |
| Vital Proteins |
| Amicogen Inc. |
| Hangzhou Nutrition Biotechnology Co., Ltd |
| Norland Products Inc |
| Seagarden AS |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with Nordic trawler cooperatives lock in Atlantic cod skin access while freezing peptide purity premiums for Japanese nutraceutical manufacturers, compressing spot-market arbitrage opportunities for non-integrated processors.
Pricing Analysis
Long-term offtake contracts dominate premium native collagen fractions, with peptide purity thresholds and ISO 13485 certification status driving price differentiation between medical-grade and cosmetic-grade tiers. Cost compression in hydrolyzed collagen stems from Vietnamese and Thai scale processors flooding commodity peptide segments. Contract manufacturers in Seoul exhibit lowest price sensitivity due to K-beauty premium positioning, while animal nutrition buyers compete purely on gelatin spot pricing.
Supply Chain Analysis
Strategic stockpiling of Atlantic cod skins through Q4 fishing seasons buffers Nordic processors against biomass volatility, while just-in-time enzymatic processing in Osaka and Tokyo minimizes peptide degradation losses. Raw material flows concentrate in Norway, Iceland, and Vietnam, with fishery partnership proximity determining triple-helix fraction yields. Single-source vulnerability runs through concentrated Atlantic cod cooperatives. Distribution runs through direct-to-clinic sampling programs in Tokyo and Seoul aesthetic medicine clusters, displacing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized enzymatic hydrolysis expertise remains anchored in Japanese and Nordic coastal facilities, creating acquisition scarcity for processors lacking captive marine biochemistry talent pipelines.
For Market Incumbents: Compound defensive positioning through backward integration into Alaskan pollock and Atlantic cod fishery partnerships, securing raw material flows against Vietnamese scale-processor encroachment. Invest in cold-extraction capacity expansion for native collagen wound matrix applications where ISO 13485 certification creates formulation lock-in. Prioritize EFSA novel food panel pre-submission dossiers to compress European supplement channel entry timelines versus FDA GRAS-track competitors. For New Entrants and Emerging Players: Differentiate on ASEAN cosmetic directive compliance capabilities, targeting Seoul-based contract formulators seeking marine-origin alternatives to mammalian collagen for K-beauty export formulations. Penetrate the functional food beverage fortification segment in Japanese convenience retail, where PMDA labeling standards favor domestic partnership structures over foreign direct entry. Lead with peptide purity certification documentation as the primary go-to-market credential. For Investors and Strategic Acquirers: Japanese coastal processors with integrated enzymatic hydrolysis infrastructure and METI export certification relationships represent the highest-conviction acquisition archetype for exposure to premium peptide margin expansion. Long-term viability hinges on biochemistry talent pipeline depth and fishery partnership renewal terms. Watch for EFSA-ASEAN cosmetic directive harmonization momentum as the signal indicating Southeast Asian manufacturing hub access premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fishery Partnerships | Captive Atlantic cod skin supply secures triple-helix fraction yields against Nordic cooperative concentration. |
| EFSA Novel Food Pre-Submission Investment | Accelerated European supplement channel entry compresses time-to-shelf versus FDA GRAS self-affirmation timelines. |
| Cold-Extraction Capacity Expansion | Native collagen structural integrity preservation unlocks wound closure matrix premiums in German medical device channels. |
| Direct-to-Clinic Sampling Program Deployment | Tokyo and Seoul aesthetic medicine procurement consolidation captures end-user preference data while compressing distributor margins. |
| Peptide Purity Certification Documentation | PMDA-compliant functional food labeling standards create export-quality credentials for adjacent market leverage. |
Research Methodology
Cross-validation between primary interviews with marine biochemistry directors, fishery cooperative procurement leads, and Seoul-based cosmetic formulators anchors the qualitative findings, while secondary validation draws from EFSA novel food panel decisions, PMDA functional food registration databases, and METI marine ingredient safety protocols. Bottom-up triangulation across enzymatic processing capacity installations and top-down reconciliation against fishery landing statistics ensure segment-level coherence.
Sensitivity analysis around peptide purity threshold compliance costs and fishery partnership renewal probability distributions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, source tissue, application end-use, and regional regulatory cluster. CAGRs derive from installed hydrolysis capacity utilization rates and functional food format adoption curves in Japanese metropolitan convenience retail.
The analysis sits within stated boundaries; outcomes outside EFSA-ASEAN harmonization momentum or Atlantic cod biomass stability assumptions would require recalibration. Forecasts reflect documented assumptions regarding enzymatic processing technology diffusion and clean-label cosmetics substitution elasticity. Revision becomes warranted when PMDA peptide purity threshold modifications or CSRD provenance tracking mandate implementations cross compliance investment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Nutraceutical Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Omega-3 Products Market
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
North America Omega-3 Products Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
North America Spirulina Extract Market
Nutritional Supplements
South America Collagen Supplements Market
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Green Food Supplements Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Hydroxymethylbutyrate (HMB) Market
Nutritional Supplements
Europe Nutritional Beverages Market
Nutritional Supplements
Global General Well-Being Dietary Supplements Market