
 Medicinal Mushroom Supplement Market | 2026-2036
Medicinal Mushroom Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Medicinal Mushroom Supplement Market Insights
Organic certification under USDA National Organic Program standards is unwinding competitive access for smaller extract suppliers unable to sustain multi-year accreditation costs. Four Sigmatic leverages Nordic sourcing relationships and lifestyle branding to command premium shelf positioning in North American retail. Fungi Perfecti anchors its market presence through Paul Stamets-associated mycology credibility and extensive substrate research capabilities. Om Mushroom Superfood competes on vertically controlled cultivation in California and Colorado facilities, ensuring batch-to-batch beta-glucan consistency.
Medicinal mushroom supplements comprise concentrated bioactive extracts from fungal fruiting bodies or mycelial biomass, standardized to polysaccharide content typically exceeding 20% beta-glucans by dry weight, and consumed for immunomodulatory, nootropic, or adaptogenic benefit. Powder and capsule forms dominate current volume throughput due to dosing precision and shelf stability, though liquid extracts capture expanding share among bioavailability-focused consumers. Reishi and Lion's Mane SKUs lead revenue contribution given established clinical visibility in stress response and cognitive support applications, while Cordyceps extracts represent the fastest-growing product type as athletic performance positioning gains traction. Online retail channels concentrate margin pools through subscription models and direct consumer education, reducing intermediary cost structures relative to pharmacy and supermarket placements.
FDA cGMP enforcement under DSHEA, EFSA novel food assessments for emerging fungal species, and NMPA traditional medicine registration pathways in China collectively determine which suppliers achieve cross-border market access and product legitimacy. These frameworks elevate testing burdens for heavy metals, adulteration, and identity verification, favoring laboratories with in-house HPLC and PCR capabilities over contract-dependent competitors. Stakeholders must monitor evolving mycelium-versus-fruiting-body labeling disputes and adaptogen classification debates that threaten to resegment regulatory compliance costs across the supplier base.
Market Dynamics
FDA cGMP enforcement under DSHEA is compressing supplier margins through mandatory heavy metal testing and identity verification protocols, favoring laboratories with captive HPLC and PCR capabilities over contract-dependent competitors.
Growth Catalysts
- Adaptogenic positioning:Functional food integration in the United States, Germany, and China drives cross-category demand as wellness consumers seek stress-response and cognitive support applications beyond traditional supplement formats.
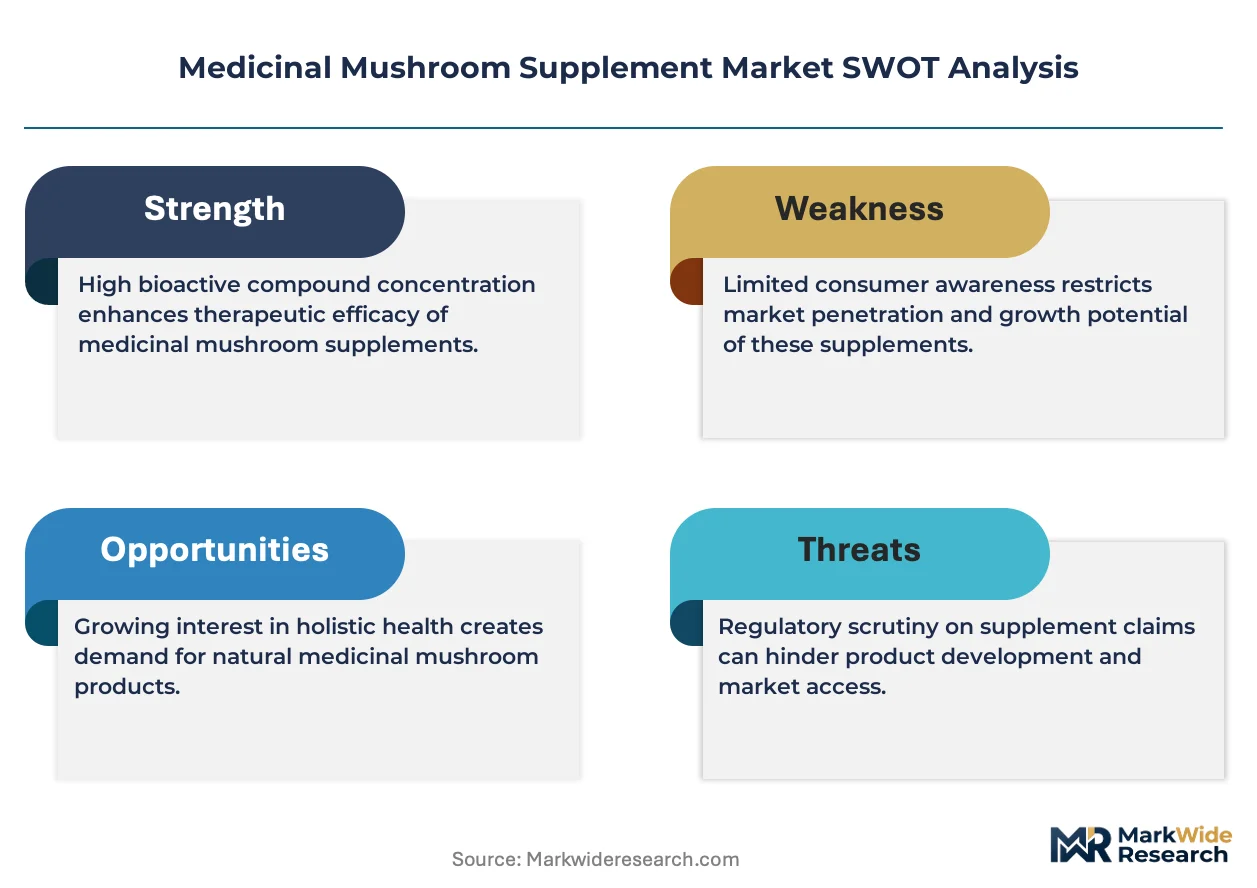
- DSHEA compliance infrastructure:FDA dietary supplement enforcement elevates quality benchmarks for fruiting body extracts, creating legitimacy advantages for suppliers with in-house analytical laboratories and batch-to-batch standardization protocols.
- Athletic performance marketing:Cordyceps extracts gain traction among bioavailability-focused consumers seeking ergogenic benefits, expanding the addressable base beyond immunomodulatory and nootropic use cases.
Market Restraints
- Organic certification cost structure:USDA National Organic Program multi-year accreditation expenses unwind competitive access for smaller extract suppliers unable to sustain compliance investments relative to scaled Nordic and North American competitors.
- Substrate supply concentration:Hardwood and grain substrate sourcing for mycelial biomass production concentrates in specific agricultural regions, exposing cultivation facilities to input volatility and quality inconsistency.
- Mycelium-versus-fruiting-body labeling ambiguity:Ongoing regulatory disputes over polysaccharide standardization and beta-glucan content claims threaten to resegment compliance costs across the supplier base without clear FDA guidance.
Strategic Opportunities
- Subscription commerce penetration:Direct-to-consumer channels concentrate margin pools through recurring revenue models and consumer education platforms, reducing intermediary cost structures relative to pharmacy and supermarket placements.
- Liquid extract format expansion:Bioavailability-focused consumers drive share capture away from powder and capsule forms, creating white space for suppliers with extraction technology capable of preserving heat-sensitive triterpenoid compounds.
- EFSA novel food pathway navigation:European suppliers achieving safety assessments for emerging fungal species unlock first-mover positioning in functional food integration across Germany and adjacent markets.
Industry Challenges
- Analytical chemistry talent scarcity:In-house HPLC and PCR capability requirements outpace qualified laboratory technician supply, forcing suppliers to choose between capital-intensive equipment investment and unreliable contract testing relationships.
- Batch-to-batch consistency protocols:Vertically controlled cultivation demands precise environmental monitoring and substrate standardization, requiring sustained capex in climate-controlled facilities across California and Colorado.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medicinal Mushroom Supplement Market |
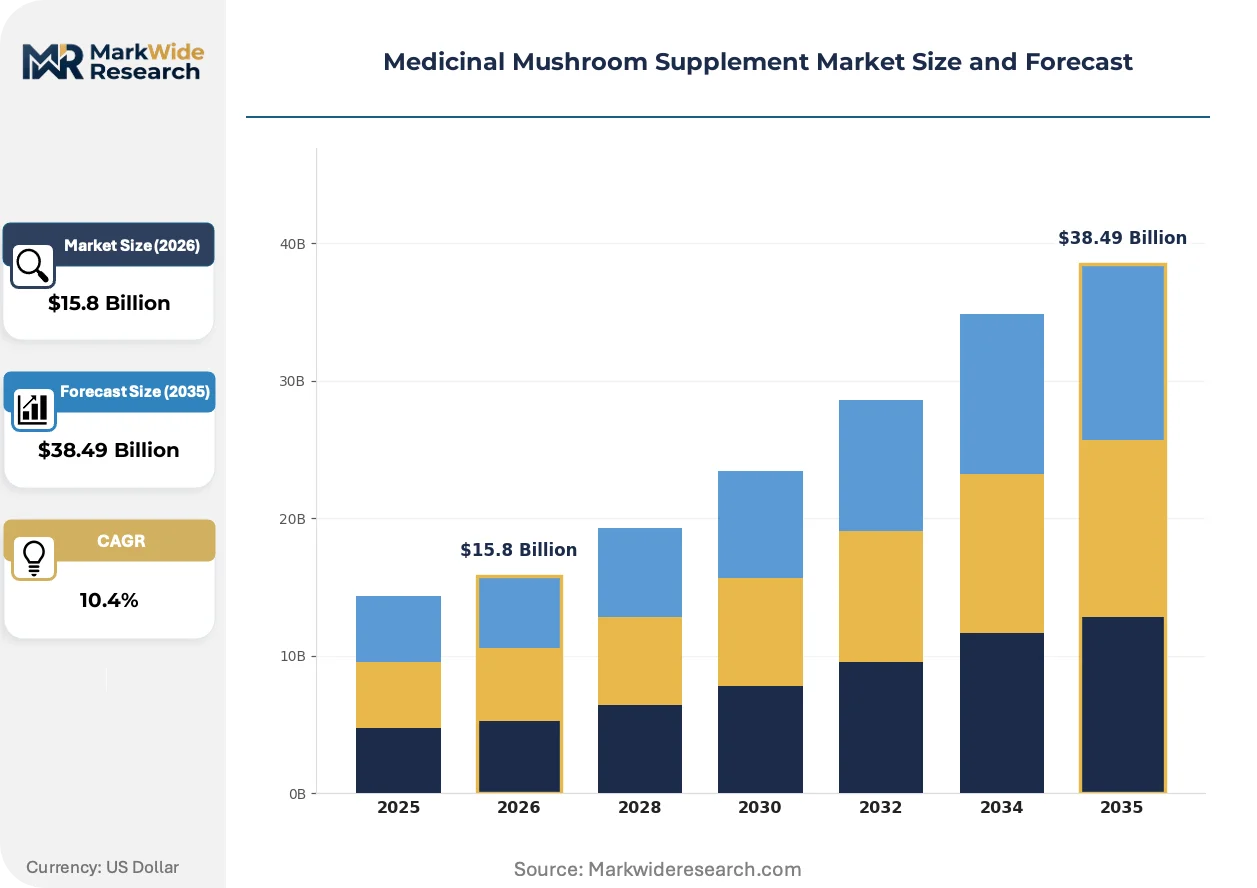
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $38.49 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reishi, Lion's Mane, Cordyceps, Chaga Form: Powder, Capsule, Liquid, Extract End User: Health Enthusiasts, Athletes, Seniors, Wellness Consumers Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets |
| Companies Covered | Four Sigmatic, Fungi Perfecti, Om Mushroom Superfood, Real Mushrooms, Nammex, Mushroom Wisdom, Host Defense, Nature's Way Brands, DXN Holdings Bhd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medicinal Mushroom Supplement Market Trends and Innovations
Dual-extraction processing protocols combining hot water and alcohol phases are reshaping bioactive compound preservation, while regulatory clarity efforts and channel disintermediation accelerate competitive repositioning across the value chain.
Ultrasonic-assisted extraction technology is fragmenting traditional hot-water processing dominance by improving polysaccharide yield rates while reducing thermal degradation of heat-sensitive compounds. Premium supplement manufacturers in the United States and Germany adopt these systems to differentiate finished goods on beta-glucan concentration claims. The capital barrier for ultrasonic equipment is fragmenting competitive tiers, separating laboratories with captive processing capabilities from contract-dependent suppliers.
EFSA novel food assessments for emerging fungal species are compressing market entry timelines for European suppliers while creating compliance moats against unvalidated competitors. The industrial consequence favors established players with toxicology study budgets and regulatory affairs expertise over emerging market entrants. Cordyceps militaris and lesser-known Ganoderma species face the steepest documentation requirements, forcing suppliers to prioritize species with existing safety dossiers.
Consumer education platforms embedded in direct-to-consumer channels are displacing traditional retail dependency for product discovery and dosage guidance. Subscription models in the United States capture recurring revenue while reducing customer acquisition costs relative to pharmacy shelf placement. Germany and China show parallel channel evolution as wellness consumers prioritize traceability and fruiting-body verification over mass-market accessibility.
Medicinal Mushroom Supplement Market Segmentation
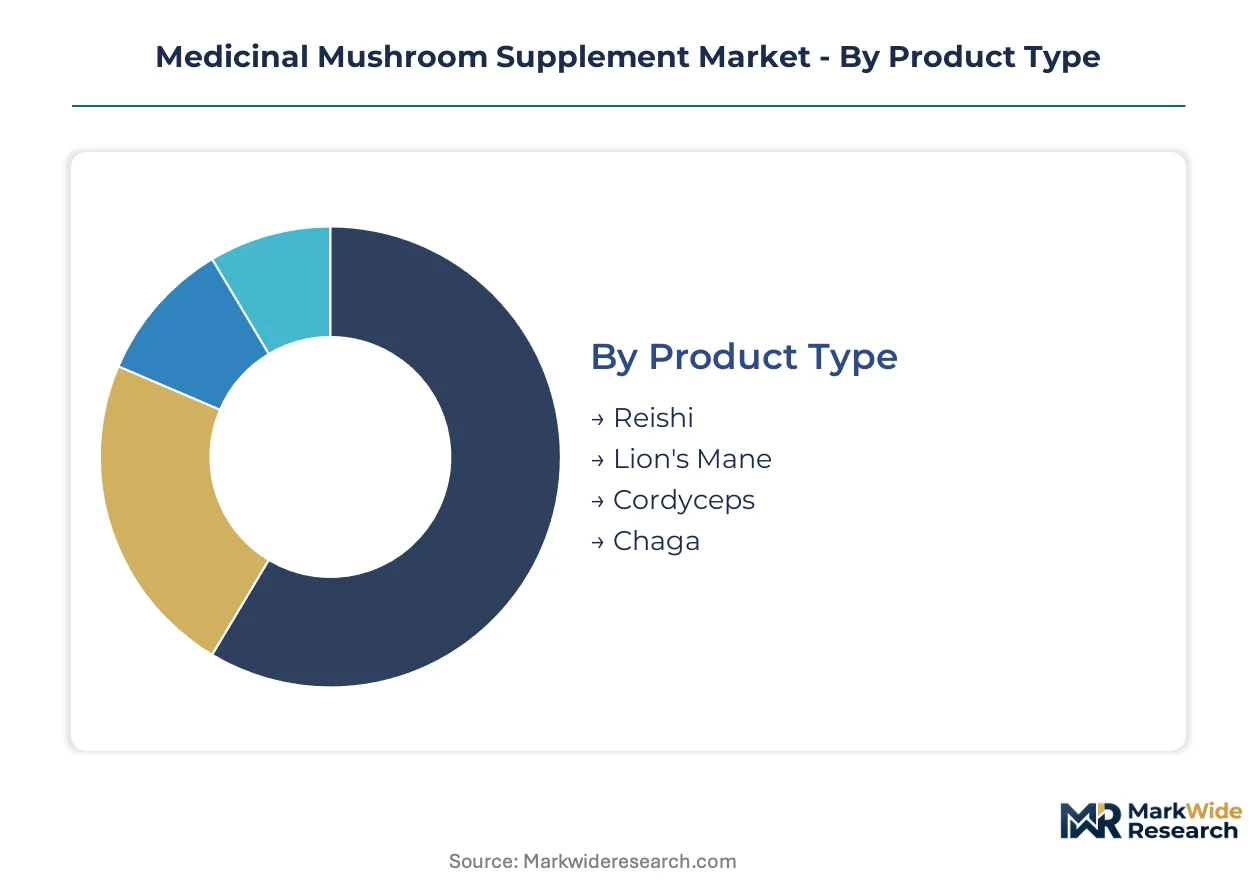
Mushroom supplement segmentation reveals how bioactive compound standardization, format bioavailability, and channel economics split margin pools across distinct buyer profiles. Category boundaries are blurring as functional food integration collapses traditional distinctions between wellness, sports nutrition, and cognitive health applications.
Product Type:
Reishi and Lion's Mane dominate North American and German domestic consumption, while Cordyceps supply chains orient heavily toward export-led athletic performance markets in Asia-Pacific.
- Reishi:Triterpenoid-rich fruiting body extracts standardized to 10-30% polysaccharide content anchor stress-response and sleep-support formulations. Demand concentrates in United States wellness consumers seeking adaptogenic alternatives to pharmaceutical anxiolytics, constrained by extended cultivation cycles that compress supplier margins.
- Lion's Mane:Hericenones and erinacines drive nootropic positioning for cognitive clarity and neuroplasticity support. German and Chinese buyers prioritize fruiting-body verification over mycelial biomass, tightening identity testing requirements for cross-border suppliers.
- Cordyceps:Cordycepin and adenosine content fuel ergogenic marketing toward bioavailability-focused athletes.
- Chaga:Betulinic acid and melanin compounds target antioxidant positioning in premium Nordic-sourced formulations.
Reishi holds the largest share; momentum sits with Cordyceps.
Form:
Cost tier stratification separates commodity powders from precision-dosed capsules and premium liquid extracts with escalating unit economics.
- Powder:Bulk dry weight products with 20%+ beta-glucan standardization serve price-sensitive health enthusiasts and formulation houses. United States direct-to-consumer channels capture recurring subscription volume, though caking and oxidation sensitivity elevate packaging costs for moisture-barrier sachets.
- Capsule:Hard-shell gelatin and vegetable cellulose delivery ensures dosing precision and shelf stability for pharmacy and health store placement. German regulatory scrutiny of excipient declarations favors suppliers with EFSA-compliant manufacturing documentation.
- Liquid:Alcohol and glycerin suspensions preserve heat-sensitive triterpenoids for bioavailability-focused consumers.
- Extract:Concentrated dual-phase processed materials command premium positioning in functional food integration.
Capsule formats dominate volume throughput; liquid extracts are climbing the fastest.
End User:
Application intensity varies sharply: athletes demand batch-tested ergogenic verification while seniors prioritize immunomodulatory simplicity.
- Health Enthusiasts:Early-adopter buyers with substrate literacy drive fruiting-body verification trends and organic certification premiums. United States subscription commerce captures this segment through educational content and traceability tools, reducing price elasticity relative to mass-market channels.
- Athletes:Cordyceps-centric demand for VO2 max and endurance positioning requires third-party banned-substance testing and NSF Certified for Sport accreditation. Chinese and German Olympic training facilities represent concentrated procurement nodes with stringent documentation requirements.
- Seniors:Simplified dosing regimens and immune support claims dominate purchasing criteria.
- Wellness Consumers:Stress-response and sleep applications drive cross-category purchasing across adaptogenic portfolios.
Health enthusiasts anchor current revenue; athletes show the steepest expansion trajectory.
Distribution Channel:
Margin concentration inverts traditional retail economics as direct-to-consumer platforms disintermediate pharmacy and supermarket intermediaries.
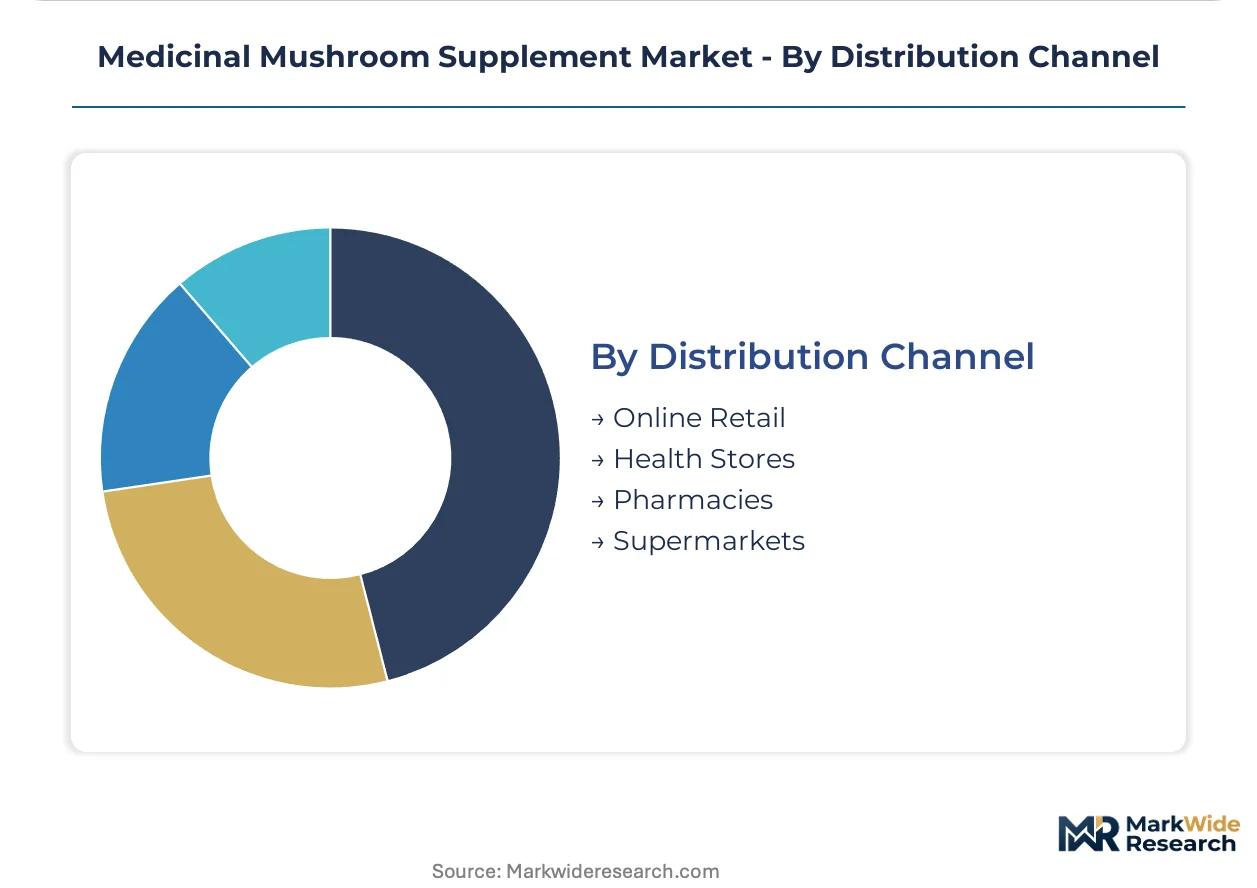
- Online Retail:Brand-owned storefronts and marketplace presence enable subscription models with 40-60% gross margins versus 20-30% in brick-and-mortar. United States consumers prioritize batch-specific COA access and mycologist-curated education over price comparison.
- Health Stores:Staff-trained recommendation environments favor premium positioning and SKU depth for Reishi and Lion's Mane. German Reformhaus chains require organic certification and local language labeling compliance that filters out smaller import suppliers.
- Pharmacies:Professional endorsement channels demand DSHEA-compliant structure-function claims and child-resistant packaging.
- Supermarkets:Mass-market accessibility trades margin for volume in private-label functional food adjacencies.
Online retail commands margin concentration; health stores retain loyalty-driven repeat purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and Los Angeles rail intermodal network underwrites United States distribution capacity for finished supplement exports to Asia-Pacific markets.
United States
DSHEA cGMP enforcement by FDA elevates testing burdens for heavy metals and identity verification. Wellness consumers in California and Colorado drive subscription commerce penetration for fruiting-body verified formulations. The Denver-Boulder corridor anchors vertically controlled cultivation facilities with batch-to-batch beta-glucan standardization protocols.
China
NMPA traditional medicine registration pathways determine cross-border legitimacy for Reishi and Cordyceps militaris extracts. Domestic demand concentrates in Olympic training facilities seeking ergogenic verification with banned-substance documentation. Zhejiang and Fujian provinces host concentrated substrate supply networks for hardwood-dependent mycelial biomass production.
Germany
EFSA novel food assessments compress entry timelines for emerging fungal species while filtering unvalidated competitors. Reformhaus chains require organic certification and German-language labeling compliance. Bavaria anchors analytical laboratory clusters with captive HPLC capabilities serving premium extract manufacturers.
Canada
Health Canada Natural and Non-prescription Health Products Directorate oversees site licensing for mushroom extract manufacturing. British Columbia's climate-controlled cultivation infrastructure supplies North American demand for organic-certified fruiting body materials. Vancouver serves as Pacific Rim export hub for dual-extraction processed formulations.
Australia
TGA complementary medicine regulations mandate evidence for permitted indications on mushroom supplement labels. Melbourne and Sydney health store networks prioritize traceability tools and batch-specific certificate of analysis access. Queensland subtropical zones support year-round cultivation cycles for tropical-adapted Ganoderma species.
Medicinal Mushroom Supplement Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and channel access dimensions. The supplier base stratifies into three tiers: scaled laboratories with captive analytical capabilities, vertically integrated cultivators with climate-controlled facilities, and contract-dependent importers facing margin compression from multi-year accreditation costs. Two dominant competitive moves define current positioning: backward integration into substrate supply networks and subscription commerce platform development.
Within the vertically integrated tier, Om Mushroom Superfood and Real Mushrooms exemplify cultivation-controlled supply chain models. Four Sigmatic occupies a position bridging Nordic sourcing relationships with North American lifestyle branding. Fungi Perfecti anchors credibility-focused positioning through mycology-associated research capabilities. These three represent distinct strategic archetypes: captive production, lifestyle brand premiumization, and scientific legitimacy respectively.
| Leading Market Players |
|---|
| Four Sigmatic |
| Fungi Perfecti |
| Om Mushroom Superfood |
| Real Mushrooms |
| Nammex |
| Mushroom Wisdom |
| Host Defense |
| Nature's Way Brands |
| DXN Holdings Bhd |
| Others |
Pricing and Supply Chain Analysis
Dual-extraction processing protocols replacing single-phase hot-water methods are redrawing supplier geography toward laboratories with captive ultrasonic equipment while compressing margins for contract-dependent processors. This substitution dynamic concentrates pricing power with scaled Nordic and North American operators that have amortized capital investments, forcing smaller competitors toward commodity powder tiers or exit.
Pricing Analysis
Volume-discount tiering structures separate subscription-commerce direct-to-consumer channels from pharmacy and supermarket placements. Three-tier pricing stratifies across organic-certified fruiting-body extracts, conventional mycelial biomass formulations, and bulk unstandardized powders. Pricing pressure stems from USDA National Organic Program multi-year accreditation costs that smaller suppliers cannot sustain. Health enthusiasts in United States subscription channels show lowest price sensitivity due to traceability demands, while supermarket buyers drive hardest volume negotiations.
Supply Chain Analysis
China and the United States anchor global substrate supply networks and finished extract production respectively. Hardwood and grain substrate sourcing for mycelial biomass production draws from Zhejiang and Fujian provinces, while California and Colorado facilities dominate North American fruiting-body cultivation. Single-source vulnerability concentrates in hardwood substrate regions exposed to agricultural input volatility. Distribution runs through Port of Long Beach and Los Angeles rail intermodal networks for Asia-Pacific export fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA cGMP enforcement under DSHEA is disrupting competitive economics by mandating in-house analytical capabilities that fragment the supplier base into capital-rich laboratories and margin-compressed contract-dependent competitors.
For Market Incumbents: Shield market position by accelerating backward integration into hardwood substrate supply networks in Zhejiang province, reducing input volatility exposure. Fortify analytical chemistry capabilities through captive HPLC and PCR laboratory investment, creating compliance moats against emerging entrants lacking multi-year accreditation budgets. For New Entrants and Emerging Players: Liquid extract format gaps where incumbents under-serve bioavailability-focused athletes present immediate white-space opportunity. Target German Reformhaus channels with EFSA novel food dossiers for emerging fungal species, exploiting compressed entry timelines. Deploy direct-to-consumer education platforms with batch-specific COA access as primary go-to-market mechanism. For Investors and Strategic Acquirers: Capital is best deployed toward vertically controlled cultivators with climate-controlled California and Colorado facilities and existing organic certification infrastructure. Long-term viability over the next decade hinges on traceability-verified fruiting-body positioning as labeling disputes resolve. Monitor EFSA novel food approval velocity for Cordyceps militaris and lesser-known Ganoderma species as inflection indicator for European market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Extraction Processing Scale-Up | Captive ultrasonic equipment preserves heat-sensitive triterpenoids for premium positioning. |
| Organic Certification Investment | USDA National Organic Program accreditation filters out smaller competitors in North American retail. |
| Direct-to-Consumer Platform Launch | Subscription models capture 40-60% gross margins versus 20-30% in brick-and-mortar pharmacy placements. |
| EFSA Novel Food Dossier Development | Safety assessments for emerging fungal species unlock first-mover positioning in German functional food integration. |
| Substrate Supply Network Integration | Upstream control over hardwood and grain sourcing in Zhejiang province mitigates agricultural input volatility. |
Research Methodology
Initial hypotheses were tested against primary input from cultivation facility operators, analytical laboratory directors, dietary supplement regulatory consultants, and health store category buyers, then refined through secondary validation against FDA cGMP inspection records, EFSA novel food submission databases, USDA National Organic Program certification listings, and NMPA traditional medicine registration filings. Bottom-up volume estimates from substrate throughput and extraction capacity were triangulated with top-down demand segmentation across end-user archetypes.
Variance-decomposition across product type, form factor, end-user application intensity, and distribution channel economics structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate assumptions applied to baseline volume estimates. Industry-specific forecast inputs included dual-extraction processing adoption curves and EFSA novel food approval pipeline velocity for emerging fungal species.
Forecasts assume regulatory continuity in FDA DSHEA enforcement, EFSA novel food assessment protocols, and NMPA traditional medicine pathways; material policy shifts in heavy metal testing thresholds or adaptogen classification would require re-modeling. Recalibration cycles align with material shifts in organic certification cost structures and mycelium-versus-fruiting-body labeling clarity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Spain Whey Protein Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Conjugated Linoleic Acid Market
Nutritional Supplements
Prickly Pear Seed Oil Nutricosmetic Bases Market
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market
Nutritional Supplements
Australia Whey Protein Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Chia-Based Protein Market
Nutritional Supplements
Middle East and Africa Collagen Supplements Market