
 Melatonin Supplements Market | 2026-2036
Melatonin Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Melatonin Supplements Market Intelligence
Microencapsulation technology is narrowing the bioavailability gap between immediate-release and extended-release melatonin formats, forcing reformulation across the supply base. Natrol leverages its sustained-release platform to anchor shelf presence in North American retail channels. Nature's Bounty competes through vertical integration into softgel manufacturing, while Pharmavite differentiates via USP-verified purity standards that sustain premium positioning.
Melatonin supplements are synthetically or naturally derived formulations of N-acetyl-5-methoxytryptamine, typically dosed from 0.5 mg to 10 mg, designed to modulate circadian rhythm by binding to MT1 and MT2 receptors in the suprachiasmatic nucleus. Gummies lead product type growth due to palatability-driven expansion in pediatric and senior adherence, while tablets retain volume dominance in pharmacy channels where dose precision commands trust. E-commerce captures the fastest-growing distribution channel as direct-to-consumer subscription models reshape repurchase behavior, though health stores still occupy the highest-margin position through personalized consultation attach.
The FDA's cGMP rules for dietary supplements enforce identity, purity, and composition standards that shape manufacturing investment thresholds, while the FTC monitors advertising claims linking melatonin to sleep outcomes. EFSA in Europe maintains stricter novel food assessments that limit market access for non-pharmaceutical melatonin products. Stakeholders must monitor evolving pharmacovigilance frameworks that could reclassify melatonin from supplement to prescription status in key jurisdictions.
Market Dynamics
Microencapsulation technology is compressing the efficacy gap between immediate-release and extended-release formats, forcing incumbent manufacturers to reformulate legacy product lines or surrender retail shelf space to sustained-release platforms.
Growth Catalysts
- Shift work prevalence:Expanding 24-hour logistics and healthcare operations in the United States, Germany, and Japan generate sustained demand for circadian rhythm management among non-traditional workers.
- FDA cGMP enforcement:Stricter identity and purity standards for dietary supplements elevate consumer trust in over-the-counter sleep aids, reducing hesitation among first-time buyers.
- Gummy format innovation:Palatability-driven formulations expand adherence among pediatric populations and seniors who reject tablet consumption, opening new household penetration vectors.
Market Restraints
- API supply concentration:Pharmaceutical-grade melatonin synthesis clusters in Chinese and Indian chemical manufacturing hubs, exposing brands to input volatility and geopolitical friction.
- EFSA novel food classification:European regulators treat non-pharmaceutical melatonin as a novel food requiring extensive safety dossiers, blocking market access for standard supplement formats.
- Prescription reclassification risk:Pharmacovigilance frameworks in France and Australia signal potential schedule shifts that would eliminate over-the-counter availability.
Strategic Opportunities
- Pediatric sleep protocols:Clinical validation of low-dose melatonin for neurodevelopmental conditions creates prescriber-channel entry points in Canada and the United Kingdom.
- Subscription commerce models:Direct-to-consumer platforms with automated replenishment capture recurring revenue streams and disintermediate pharmacy intermediaries.
- Dual-release hybrid formats:Convergence of immediate-onset and sustained-release technologies in single-dose products commands premium positioning against commodity immediate-release tablets.
Industry Challenges
- USP verification backlog:Third-party purity certification queues extend 8-14 months, delaying product launches and freezing marketing claims.
- Cross-border formulation compliance:Divergent maximum permitted doses across jurisdictions force SKU proliferation and inventory fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melatonin Supplements Market |
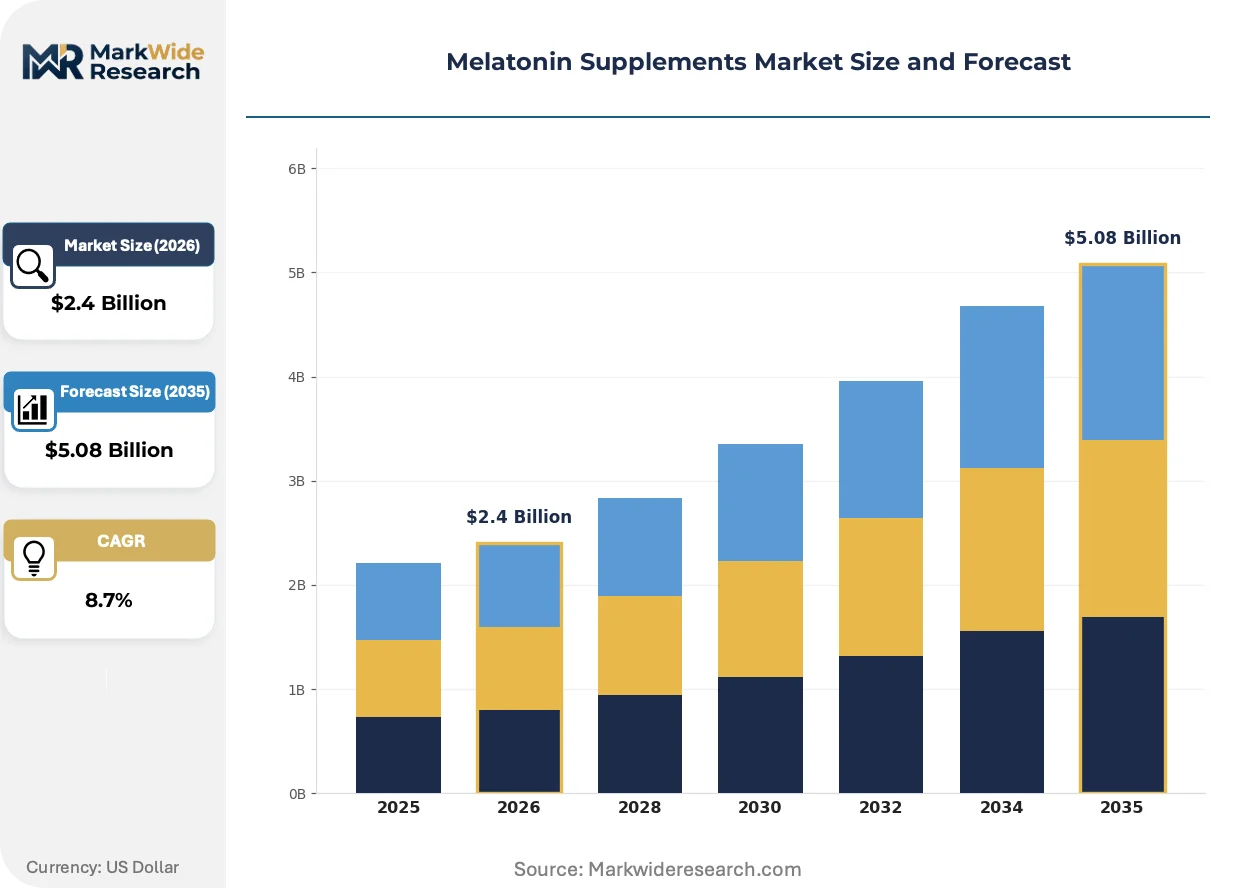
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Gummies, Powders Application: Sleep Disorders, Jet Lag, Shift Work, General Wellness Distribution Channel: E-commerce, Pharmacies, Supermarkets, Health Stores Customer Type: Adults, Seniors, Athletes, Children |
| Companies Covered | Natrol, Nature’s Bounty, Puritan’s Pride, Church & Dwight Co., Inc., Pharmavite, GNC, Jamieson Vitamins, Life Extension, Nature Made, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melatonin Supplements Market Strategic Shifts & Innovations
Formulation science and distribution architecture are converging to reshape how melatonin products reach end users, with technology-enabled delivery systems and regulatory arbitrage strategies creating new competitive axes beyond raw ingredient sourcing.
Microencapsulation with lipid-based coatings is hybridizing release profiles previously locked into binary immediate-versus-extended formats. Pediatric sleep specialists and airline crew health programs are adopting these hybrid platforms at accelerating rates. The technology is compressing differentiation timelines for legacy tablet manufacturers who lack in-house coating capabilities.
EFSA's novel food assessment framework is tightening evidentiary requirements for melatonin-containing products seeking European market entry. Manufacturers must now submit comprehensive toxicological dossiers that previously sufficed with abbreviated safety summaries. Botanical extract suppliers and synthetic API producers are diverging their regulatory strategies, with the former pursuing novel food approvals and the latter seeking pharmaceutical reclassification.
Subscription-based replenishment models are displacing episodic pharmacy purchases among chronic users. Direct-to-consumer platforms with algorithmic dosing adjustments capture higher lifetime value than retail channels. This behavioral shift concentrates in United States metropolitan markets where same-day delivery infrastructure supports just-in-time inventory models.
Melatonin Supplements Market Segmentation
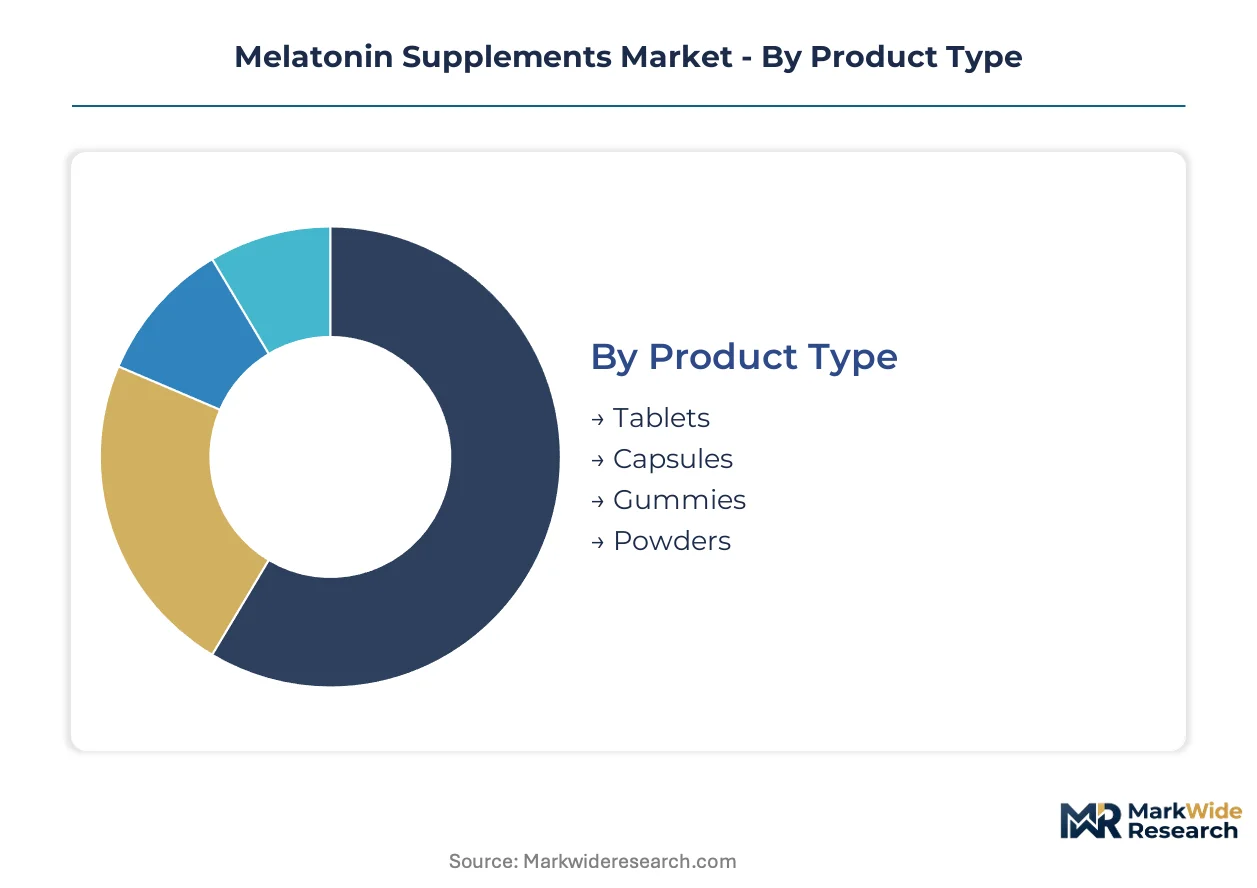
Melatonin supplement formats fragment across four distinct product architectures, each commanding different manufacturing investment thresholds and retail margin profiles. Understanding segment velocity reveals where inventory cycles compress and where shelf-life risk concentrates.
Product Type:
Gummies turn inventory fastest through impulse-driven replenishment, while powders sit longest due to niche positioning and lower household penetration rates.
- Tablets:Compressed formulations of synthetic or natural melatonin with precise dose standardization, typically 0.5 mg to 10 mg. Pharmacy channels in the United States favor tablets for their stability profile and dose reliability, though swallowing difficulty limits expansion among pediatric and geriatric populations.
- Gummies:Gelatin or pectin-based chewable matrices with flavor masking systems that obscure melatonin's bitter aftertaste. Household penetration in Canada and the United Kingdom is climbing fastest among parents managing pediatric sleep-onset insomnia, with palatability driving repeat purchase rates above other formats.
- Capsules:Two-piece hard gelatin or vegetable-derived shells containing melatonin powder or granules. Health store channels prefer capsules for their clean-label positioning and compatibility with combination formulations.
- Powders:Bulk melatonin for measured dosing into beverages or foods. Fitness communities and biohacking segments in Germany and Japan represent the primary demand concentration for this format.
Tablets dominate installed base. Gummies are where expansion concentrates.
Application:
Cost tiering separates condition-specific positioning from commoditized wellness marketing, with prescription-adjacent applications commanding formulation rigor that general wellness SKUs bypass.
- Sleep Disorders:Clinical-grade formulations targeting insomnia, delayed sleep phase syndrome, and non-24-hour sleep-wake disorder. Demand clusters in United States metropolitan markets where sleep medicine referrals intersect with over-the-counter accessibility, though FDA cGMP compliance costs elevate price floors.
- Jet Lag:Time-zone synchronization protocols using timed melatonin administration. Airline crew health programs in Japan and long-haul business travelers in Germany drive concentrated adoption of rapid-onset formulations.
- Shift Work:Circadian realignment for night-shift healthcare workers, logistics operators, and emergency responders. United States 24-hour healthcare operations generate sustained volume for sustained-release platforms that maintain daytime sleep windows.
- General Wellness:Lifestyle-positioned products without specific condition claims. E-commerce subscription models in Canada capture recurring revenue from chronic users seeking stress resilience or antioxidant benefits.
Sleep Disorders anchor revenue concentration. General Wellness is climbing the fastest.
Distribution Channel:
Margin structure inverts between high-velocity digital platforms and consultation-dependent physical retail, with inventory ownership risk shifting dramatically across channel types.
- E-commerce:Direct-to-consumer platforms with algorithmic replenishment and same-day delivery infrastructure. United States metropolitan markets show the steepest expansion trajectory as subscription models disintermediate pharmacy intermediaries and capture lifetime value through automated reordering.
- Pharmacies:Brick-and-mortar and online pharmacy networks with pharmacist consultation attach. Germany's pharmacy-dense retail environment sustains this channel's volume dominance despite slower growth rates.
- Supermarkets:Mass-market retail placement alongside vitamins and digestive health. Impulse purchase dynamics in United Kingdom grocery chains drive seasonal velocity spikes.
- Health Stores:Specialty retailers with trained staff and premium positioning. Personalized consultation attach in Canadian health food cooperatives sustains the highest per-unit margins despite lower throughput.
Pharmacies retain volume leadership. E-commerce is gaining share fastest.
Customer Type:
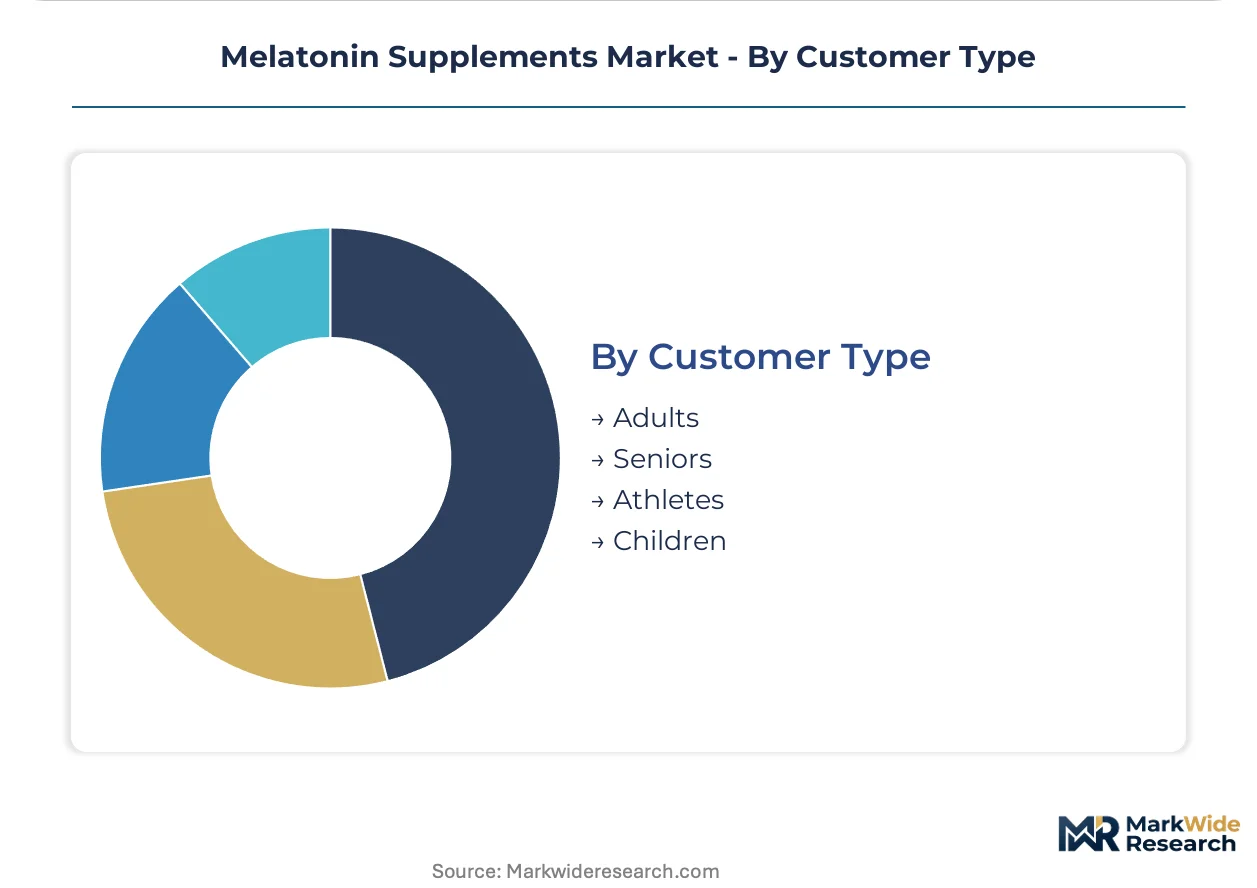
Maturity gradients separate established adult markets from emerging pediatric protocols, with regulatory scrutiny intensity varying sharply across age-defined segments.
- Adults:Working-age consumers managing occupational stress, travel schedules, or lifestyle-induced circadian disruption. United States office workers represent the core volume base, with employer wellness programs increasingly subsidizing melatonin access.
- Seniors:Age-related sleep architecture changes drive demand for low-dose formulations with reduced next-day grogginess. Japan's aging demographic sustains specialized product development for this segment.
- Athletes:Recovery-optimized sleep protocols in professional and amateur sports. CrossFit communities and endurance athletes in Germany adopt melatonin for its antioxidant properties alongside circadian benefits.
- Children:Neurodevelopmental condition management under pediatric supervision. Clinical validation in Canada and the United Kingdom is opening prescriber-channel entry points, though EFSA novel food restrictions limit European expansion.
Adults dominate installed base. Children is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese and Indian API manufacturers supply pharmaceutical-grade melatonin to formulation houses in the United States, Germany, and Japan, creating a trade-flow corridor that exposes finished-goods brands to input volatility and geopolitical friction.
United States
Shift work prevalence in 24-hour logistics and healthcare operations sustains demand for circadian rhythm management. FDA cGMP enforcement for dietary supplements elevates consumer trust in over-the-counter sleep aids. Metropolitan markets in California and New York show the steepest e-commerce subscription growth as direct-to-consumer platforms disintermediate pharmacy intermediaries.
Germany
Pharmacy-dense retail environments sustain volume dominance for tablet formats despite slower growth rates. EFSA novel food assessments block standard supplement formats from European market entry, forcing German distributors toward pharmaceutical reclassification pathways. The Rhine-Ruhr industrial corridor hosts contract manufacturers serving airline crew health programs with rapid-onset jet lag formulations.
Japan
Aging demographics drive specialized product development for seniors managing age-related sleep architecture changes. METI oversight of functional food claims shapes marketing boundaries for melatonin-positioned wellness products. The Kanto region around Tokyo anchors demand concentration among office workers with employer-subsidized sleep aid access.
Canada
Clinical validation of low-dose melatonin for pediatric neurodevelopmental conditions opens prescriber-channel entry points. Health Canada regulations permit broader over-the-counter availability than European counterparts. Health food cooperatives in British Columbia and Ontario sustain the highest per-unit margins through personalized consultation attach.
United Kingdom
Impulse purchase dynamics in grocery chains drive seasonal velocity spikes for gummy formats. The Medicines and Healthcare products Regulatory Agency monitors advertising claims linking melatonin to sleep outcomes. London metropolitan markets concentrate subscription commerce adoption among chronic users seeking stress resilience positioning.
Melatonin Supplements Market Key Industry Players
Channel-controlling players compete with product-specialist players across a fragmented vendor base where no single entity commands decisive share. The market structure tiers across mass-market retail anchors, pharmacy-network distributors, and direct-to-consumer platforms. Three strategic archetypes dominate: sustained-release technology specialists, vertical integration players with in-house softgel production, and USP-verified purity standard bearers. Competitive moves concentrate on microencapsulation licensing and subscription-commerce infrastructure buildout.
Within the sustained-release technology tier, Natrol anchors shelf presence through platform differentiation. Among vertically integrated manufacturers, Nature's Bounty exemplifies backward integration into softgel manufacturing. On the purity-verification vector, Pharmavite occupies a position defined by third-party certification standards. These three entities collectively represent the competitive axes—release-profile innovation, manufacturing control, and quality assurance—that reshape procurement decisions across North American retail channels.
| Leading Market Players |
|---|
| Natrol |
| Nature's Bounty |
| Puritan's Pride |
| Church & Dwight Co., Inc. |
| Pharmavite |
| GNC |
| Jamieson Vitamins |
| Life Extension |
| Nature Made |
| Others |
Cost & Logistics Intelligence
Zhejiang and Jiangsu provinces anchor pharmaceutical-grade melatonin synthesis capacity, with their fermentation and chemical conversion clusters feeding downstream formulation houses in the United States, Germany, and Japan. This geographic concentration grants API manufacturers substantial leverage over finished-goods pricing, while FDA cGMP compliance costs and USP verification queues add fixed-cost layers that compress margins for brands lacking scale.
Pricing Analysis
Immediate-release tablet formats occupy the economy tier, sustained-release platforms command mid-market positioning, and dual-release hybrid technologies capture premium pricing. Price differentiation hinges on USP verification status and microencapsulation licensing costs. Pricing pressure stems from subscription-commerce models disintermediating pharmacy intermediaries and compressing per-unit margins. Pediatric and senior segments show lowest price sensitivity due to adherence-driven purchasing, while general wellness buyers in e-commerce channels exhibit highest elasticity.
Supply Chain Analysis
Pharmaceutical-grade melatonin feedstock draws from chemical manufacturing hubs in China and India, with synthetic tryptamine derivatives and acetic anhydride as critical inputs. Supply chain risk centers on single-source vulnerability for USP-verified API batches and extended certification queues. Distribution runs through direct-to-consumer platforms, pharmacy networks, and health store channels with diverging inventory ownership models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The melatonin supplements market functions as a service-attach opportunity where subscription-based replenishment and algorithmic dosing platforms expand faster than standalone product sales, with recurring revenue layers capturing lifetime value beyond initial transactions.
For Market Incumbents: Harden sustained-release technology moats through exclusive microencapsulation licensing agreements that block competitor access to lipid-based coating platforms. Expand backward integration into softgel manufacturing to neutralize Nature's Bounty's cost advantages. Priority lever rests on USP verification pipeline acceleration to preempt certification backlogs that freeze marketing claims. For New Entrants and Emerging Players: Pursue pediatric sleep protocol validation in Canada and the United Kingdom where clinical entry points remain underdeveloped and prescriber-channel access offers margin protection. Target airline crew health programs in Japan with rapid-onset jet lag formulations. Go-to-market angle should emphasize dual-release hybrid formats that command premium positioning against commodity tablets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation-science specialists with captive microencapsulation capabilities over pure-play distribution assets. Long-term viability over a 5-10 year window rests on regulatory arbitrage strategies that navigate EFSA novel food restrictions and prescription reclassification risks. Acquisition target archetype: vertically integrated manufacturers with in-house coating technology and established subscription-commerce infrastructure. Signal to watch: pharmacovigilance framework shifts in France and Australia that would eliminate over-the-counter availability.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Platform Licensing | Exclusive lipid-coating agreements lock in sustained-release differentiation against immediate-release commoditization. |
| Subscription Commerce Buildout | Algorithmic replenishment models capture recurring revenue and disintermediate pharmacy intermediaries in United States metropolitan markets. |
| USP Verification Pipeline Expansion | Third-party purity certification accelerates product launches and sustains premium positioning against uncertified competitors. |
| Pediatric Protocol Clinical Validation | Low-dose melatonin trials for neurodevelopmental conditions open prescriber-channel entry points in Canada and United Kingdom. |
| Dual-Release Hybrid Format Development | Convergence of immediate-onset and sustained-release technologies commands premium pricing against binary format alternatives. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with supplement brand managers, contract manufacturing executives, pediatric sleep specialists, pharmacy procurement directors, and health store category buyers. Secondary validation drew from FDA cGMP inspection records, EFSA novel food assessment dossiers, Health Canada regulatory guidance, and United States customs import data for melatonin API shipments. Bottom-up volume modeling triangulated against top-down market sizing across product format, application, distribution channel, and customer type dimensions.
Calibration anchored volume and value outputs to historical shipment data, channel inventory turns, and pricing surveys collected across the projection horizon. Segmentation modeling spanned product architecture, condition-specific positioning, distribution format, and age-defined customer segments. CAGRs were derived from regression analysis of adoption curves, regulatory event impacts, and format substitution patterns. Forecast inputs incorporated shift work prevalence indices, e-commerce penetration rates, and pharmacovigilance framework evolution signals.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, healthcare reimbursement policies, or cross-border trade friction would shift the trajectory. Forecasts reflect assumptions around regulatory status quo maintenance and API supply continuity that pharmacovigilance reviews or geopolitical disruptions could revise. Cross-checking against Nielsen retail audit data and IQVIA pharmacy sales benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
South America Omega-3 Products Market
Nutritional Supplements
Lutein Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
Europe Dietary Supplements Market
Nutritional Supplements
Botanical Supplements Market
Nutritional Supplements
Cognition Supplements Market
Nutritional Supplements
Chewable Energy Tablet Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
Policosanol Market
Nutritional Supplements
China Collagen Peptides Market
Nutritional Supplements
Sports Food Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Canada Whey Protein Market