
 Fitness Cookies Market | 2026-2036
Fitness Cookies Market Size, Share, and Industry Trends Forecast 2026-2036
Fitness Cookies Market Analytics
Health-conscious millennials are reorganizing purchasing patterns across the Fitness Cookies Market, displacing traditional impulse buyers at convenience stores. Quest Nutrition leverages direct-to-consumer subscriptions to sustain repeat purchase rates. Lenny & Larry's anchors shelf presence in specialty retail through vegan positioning. RXBAR differentiates via minimalist ingredient lists and transparent protein sourcing.
Fitness cookies are shelf-stable baked goods formulated with elevated protein content, typically derived from whey isolate or plant concentrates, designed to support post-workout recovery or meal substitution. Protein Cookies dominate unit volume due to established gym-channel penetration, while Vegan Cookies capture the fastest expansion as allergen-free formulations attract lactose-intolerant consumers. Online Retail concentrates margin pools through subscription bundling, though Supermarkets retain volume leadership in mass-market access.
The FDA governs nutrition labeling and health claim substantiation, while the USDA oversees organic certification pathways that premium brands pursue. The Federal Trade Commission monitors influencer marketing disclosures as social commerce expands. Stakeholders must monitor evolving protein content thresholds as regulatory scrutiny intensifies.
Market Dynamics
Protein fortification technology is compressing formulation cycles while FDA labeling scrutiny intensifies disclosure requirements across shelf-stable baked goods. Manufacturers now balance clean-label positioning against functional ingredient density.
Growth Catalysts
- Direct-to-Consumer Subscriptions:Digital-native brands bypass traditional retail slotting fees through recurring revenue models that lock in predictable demand.
- FDA Nutrition Facts Modernization:Updated serving-size definitions and added-sugar line-item disclosures push reformulation toward higher-protein, lower-glycemic recipes.
- Whey Isolate Microfiltration:Advanced membrane separation yields neutral-tasting protein concentrates that eliminate chalky aftertastes in baked matrices.
Market Restraints
- Pea Protein Supply Concentration:North American processing capacity for plant concentrates remains bottlenecked at three major extraction facilities.
- Allulose Regulatory Friction:The FDA's pending classification of rare sugars as added versus natural sugars creates formulation uncertainty for low-calorie variants.
- Fresh Bakery Substitution:Refrigerated protein brownies and chilled doughs capture trial purchases through superior texture perception.
Strategic Opportunities
- German Pharmacy Channel:Regulatory acceptance of medical foods creates shelf space for clinically positioned recovery cookies in Apotheke chains.
- Precision Fermentation Collagen:Lab-grown structural proteins enable vegan cookies to match the chew density of whey-based competitors.
- USDA Organic Certification:Premium positioning through the National Organic Program commands 40-60% shelf price premiums in natural retail.
Industry Challenges
- Food Science Talent Scarcity:Formulators who bridge bakery process engineering with sports nutrition biochemistry command compensation premiums that strain mid-tier R&D budgets.
- Co-Manufacturer Capacity Constraints:Qualified facilities with allergen-segregated lines for vegan and dairy-free runs operate at 90%+ utilization, extending new product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fitness Cookies Market |
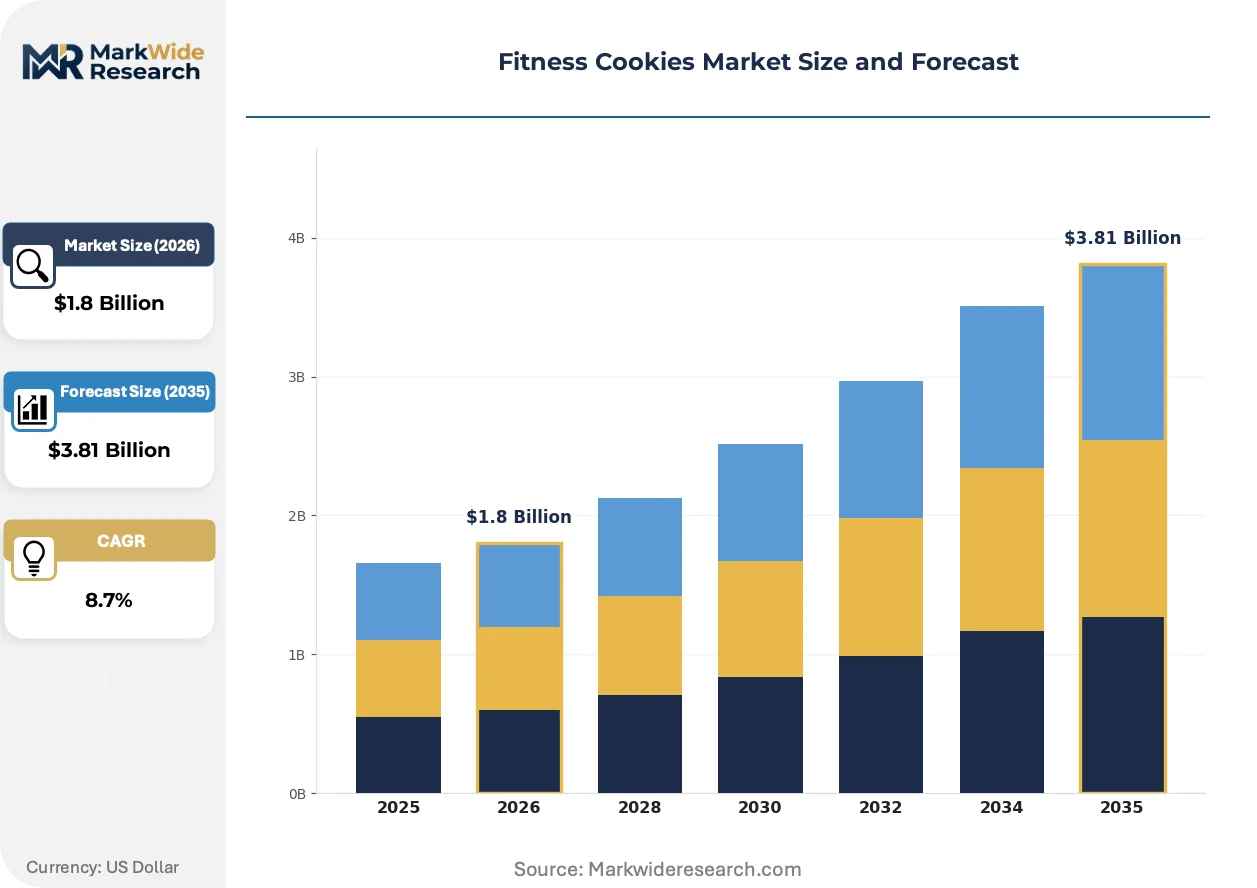
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Cookies, Meal Replacement Cookies, Vegan Cookies, Gluten-Free Cookies Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Fitness Centers Target Consumer: Athletes, Health-Conscious Individuals, Busy Professionals, Parents Flavor Profile: Chocolate Chip, Peanut Butter, Oatmeal Raisin, Cinnamon Spice |
| Companies Covered | Quest Nutrition, Lenny & Larry's, Clif Bar & Company, Mondelēz International, Kellogg, RXBAR, KIND Healthy Snacks, Munk Pack, Buff Bake, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fitness Cookies Market Evolving Landscape
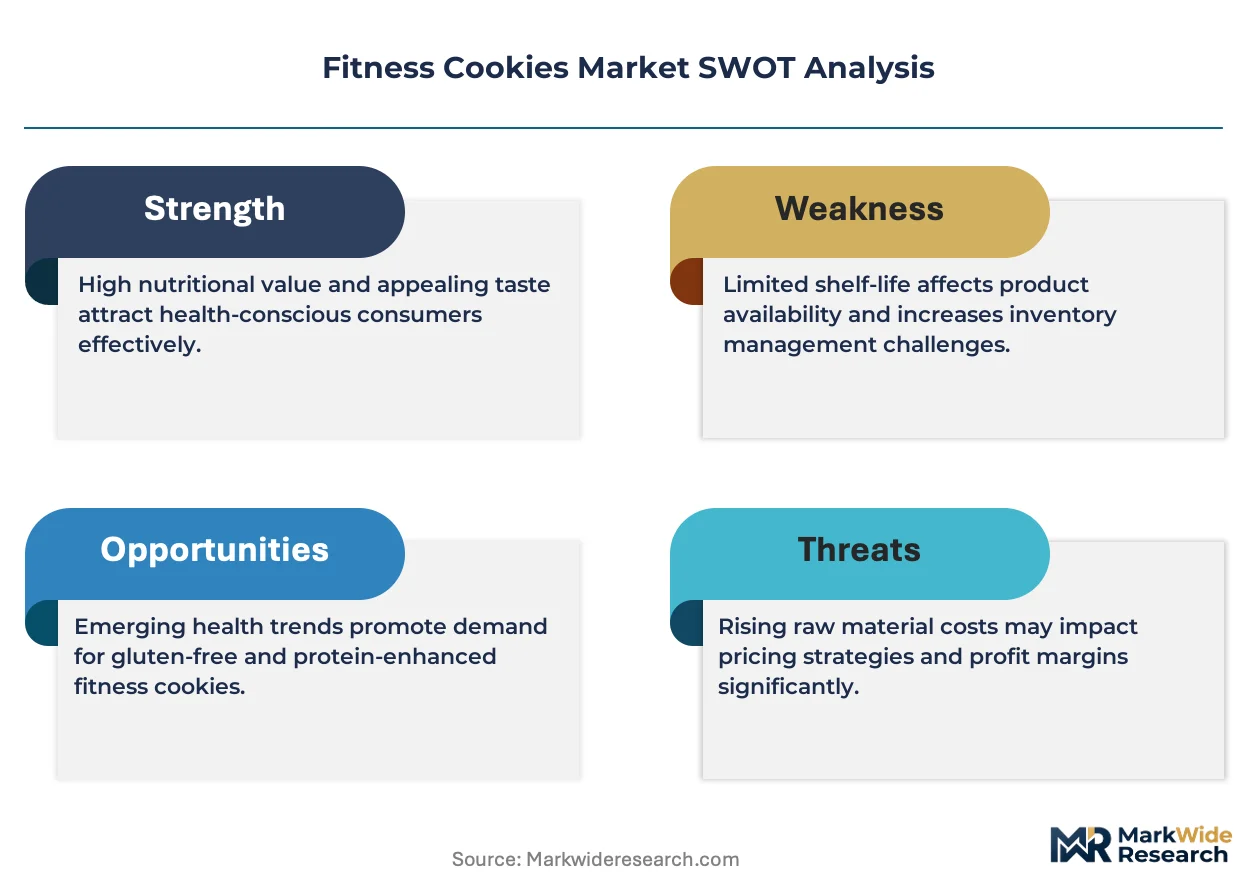
Clean-label protein sourcing and packaging sustainability are compressing traditional supply chain configurations. Manufacturers now compete on ingredient transparency rather than functional claims alone.
Encapsulated lipid technology is miniaturizing omega-3 and MCT oil droplets to prevent oxidative rancidity in extended-shelf-life cookies. Sports nutrition brands are adopting this at pilot scale for 2025 line extensions. The technology is miniaturizing flavor-mask requirements, allowing higher inclusion rates of functional lipids without sensory trade-offs.
EFSA's novel food approval pathway for insect protein is opening formulation possibilities for European manufacturers seeking complete amino acid profiles. The regulatory gatekeeping adds 18-24 months to product development timelines. German and Dutch startups are pre-submitting safety dossiers for house cricket and mealworm flours ahead of anticipated 2026 market entry.
Subscription bundling is displacing single-unit impulse purchases as the dominant trial mechanism. Gym chains and fitness apps now white-label curated cookie boxes, capturing customer data that retail channels forfeit. This pattern concentrates most visibly in United States metropolitan markets where digital fitness penetration exceeds 35%.
Fitness Cookies Market Segmentation
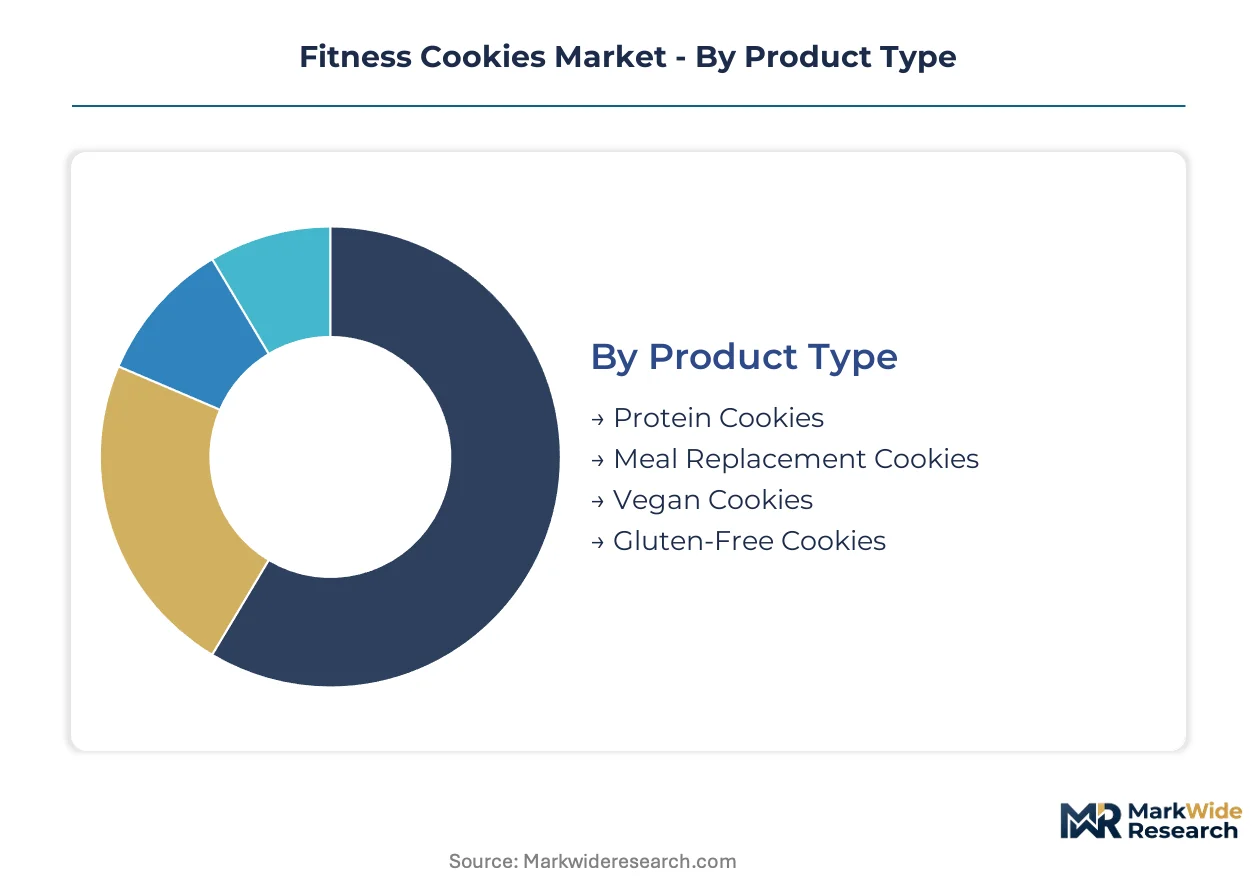
Fitness cookies fragment across four distinct classification axes that determine regulatory pathways, margin architecture, and channel access. Product formulation dictates USDA organic eligibility and FDA health claim boundaries. Distribution channel selection locks in customer acquisition economics and repeat purchase mechanics.
Product Type:
FDA protein content thresholds and USDA National Organic Program certification create divergent compliance burdens across formulation categories.
- Protein Cookies:Whey isolate or plant concentrate formulations delivering 10-20g protein per serving, targeting post-workout recovery windows. Gym channel penetration in the United States concentrates demand here, though whey sourcing costs fluctuate with dairy commodity cycles.
- Meal Replacement Cookies:Calorie-dense formulations (300-400 kcal) with balanced macronutrient profiles designed for on-the-go sustenance. Busy Professionals in metropolitan corridors sustain trial rates, but satiety claims trigger heightened FTC scrutiny on marketing disclosures.
- Vegan Cookies:Pea, rice, or pumpkin seed protein matrices excluding all animal derivatives. Allergen-free positioning captures lactose-intolerant consumers, though supply bottlenecks at North American extraction facilities constrain formulation flexibility.
- Gluten-Free Cookies:Oat, almond, or cassava flour bases targeting celiac and gluten-sensitive populations. Certification through the Gluten-Free Certification Organization commands ingredient segregation protocols that elevate co-manufacturing costs.
Protein Cookies handle the majority of throughput; Vegan Cookies is the fastest mover on share.
Distribution Channel:
Customer lifetime value economics separate digital-native subscription models from brick-and-mortar trial mechanics.
- Online Retail:Direct-to-consumer platforms and third-party marketplaces enabling subscription bundling and curated discovery. United States metropolitan markets with digital fitness penetration above 35% concentrate margin pools here, though customer acquisition costs escalate with platform advertising rates.
- Supermarkets:Mass-market shelf presence requiring slotting fee investments and velocity-based reorder triggers. Health-Conscious Individuals seeking convenience without delivery friction sustain volume leadership, though private-label compression erodes branded pricing power.
- Health Food Stores:Specialty retail environments emphasizing clean-label curation and staff recommendation. Premium positioning through the National Organic Program commands 40-60% shelf price premiums, though narrow foot traffic limits absolute volume.
- Fitness Centers:Proximity merchandising at point-of-exertion capturing impulse replenishment. Athletes seeking immediate post-workout recovery drive per-unit consumption frequency, though inventory turns depend on seasonal membership fluctuations.
Online Retail captures the steepest expansion trajectory; Supermarkets retain absolute volume dominance.
Target Consumer:
Usage occasion specificity determines formulation priorities and packaging formats across demographic clusters.
- Athletes:Performance-oriented consumers prioritizing protein bioavailability and rapid glycogen restoration. Competitive and recreational sports participation rates in the United States anchor demand concentration, with collegiate athletic programs representing institutional procurement channels.
- Health-Conscious Individuals:Wellness-focused buyers evaluating ingredient transparency and macronutrient density. Clean-label protein sourcing and minimal processing claims drive switching behavior, though price sensitivity intensifies with subscription fatigue.
- Busy Professionals:Time-constrained workers substituting structured meals with portable nutrition. Urban commuter corridors and airport retail environments concentrate trial purchases, though texture degradation in briefcase storage limits repeat rates.
- Parents:Household purchasers seeking permissible indulgence for children and adolescents. School lunch compliance and allergen-free positioning influence selection, though sugar content scrutiny from pediatric nutrition guidelines constrains formulation options.
Health-Conscious Individuals generate the highest subscription retention; Athletes is climbing the fastest on per-capita consumption intensity.
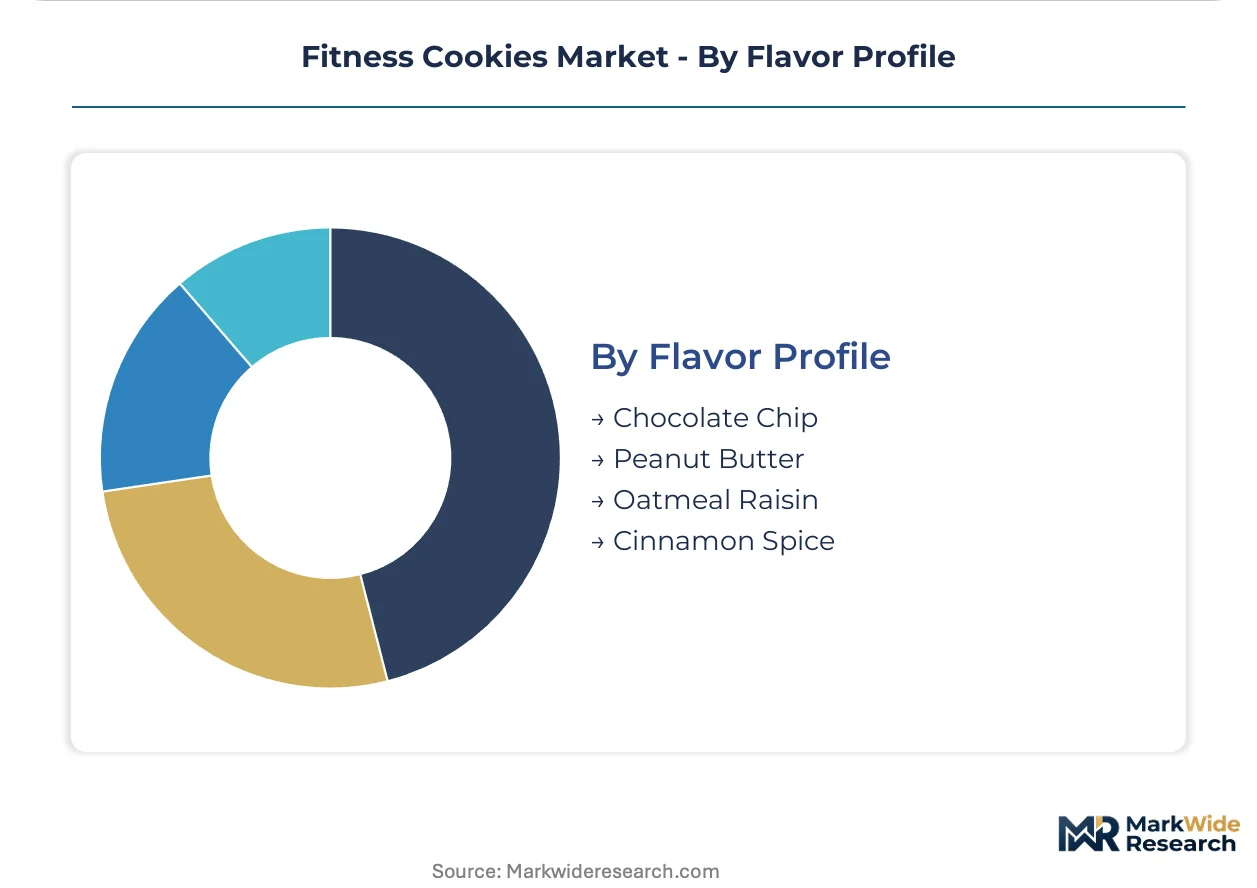
Flavor Profile:
Sensory familiarity versus novelty tension shapes R&D allocation and inventory risk across taste architectures.
- Chocolate Chip:Mass-appeal benchmark flavor leveraging cocoa butter and vanilla symmetry for palatability masking of protein aftertaste. United States consumer preference testing consistently ranks this profile highest for first-time trial, though commoditization pressures margin.
- Peanut Butter:Dense, satiating mouthfeel complementing nut butter's natural protein contribution. Allergen labeling requirements and school district restrictions constrain distribution scope, though loyalist repurchase rates exceed category averages.
- Oatmeal Raisin:Heritage bakery association signaling wholesomeness and sustained energy release. Older demographic skews and morning consumption occasions concentrate demand, though raisin texture integration challenges shelf-stability engineering.
- Cinnamon Spice:Seasonal and limited-edition positioning exploiting warming flavor perception and appetite modulation claims. Holiday promotional calendars and Q4 retail velocity targets drive periodic manufacturing surges, though year-round baseline demand remains thin.
Chocolate Chip commands absolute volume throughput; Peanut Butter is gaining share fastest on functional ingredient synergy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific distribution corridors for protein-fortified baked goods entering North American retail channels. Container throughput at Long Beach-San Pedro Bay complexes enables just-in-time replenishment for direct-to-consumer subscription models. Rail intermodal links from these ports extend shelf-stable inventory to Chicago and Dallas distribution hubs within 72 hours.
United States
Gym culture penetration and digital fitness app integration drive subscription bundling demand across metropolitan corridors. FDA Nutrition Facts modernization mandates added-sugar line-item disclosures that push reformulation toward lower-glycemic recipes. Southern California and Austin tech corridors concentrate venture-backed cookie startups leveraging precision fermentation research partnerships.
Germany
Apotheke pharmacy chains create regulated shelf space for clinically positioned recovery cookies as medical foods. EFSA novel food approval pathways for insect protein extend development timelines but open complete amino acid formulation possibilities. Berlin and Munich startup ecosystems pre-submit safety dossiers for house cricket flours ahead of anticipated 2026 market entry.
United Kingdom
Health-conscious urban professionals sustain trial rates for meal replacement formats in London commuter corridors. Trading Standards and Food Standards Agency oversight of protein content claims intensifies labeling scrutiny. Manchester and Birmingham co-manufacturing clusters develop allergen-segregated production lines for vegan and dairy-free runs.
Canada
Cross-border e-commerce integration with US subscription platforms expands addressable market for specialty formulations. Health Canada and Canadian Food Inspection Agency regulate protein fortification claims and organic certification equivalency. Toronto and Vancouver metropolitan areas concentrate natural retail channels commanding premium shelf price positioning.
Australia
Sports nutrition culture and outdoor recreation participation anchor demand for portable protein recovery formats. FSANZ governs nutrition content claims and novel ingredient approvals with stringent substantiation requirements. Sydney and Melbourne fitness studio partnerships white-label curated cookie boxes capturing customer data streams.
Fitness Cookies Market Competitive Landscape
Listed leaders compete with private specialists across direct-to-consumer channel access and formulation patent portfolios. The vendor base fragments across sports nutrition heritage brands, conventional CPG conglomerates, and venture-backed clean-label entrants. Three archetypes dominate: digital-native subscription specialists, retail-anchored mass-market players, and ingredient-transparent minimalist formulators. M&A activity concentrates on acquiring captive subscription bases, while capacity expansion targets allergen-segregated co-manufacturing lines.
Within the digital-native tier, Quest Nutrition and RXBAR exemplify recurring revenue models that bypass traditional retail slotting fees. Lenny & Larry's occupies a position bridging specialty retail shelf presence with vegan positioning credibility. These three entities anchor distinct competitive vectors—subscription technology, retail velocity, and plant-based formulation—that define strategic positioning across the category.
| Leading Market Players |
|---|
| Quest Nutrition |
| Lenny & Larry's |
| Clif Bar & Company |
| Mondelēz International |
| Kellogg |
| RXBAR |
| KIND Healthy Snacks |
| Munk Pack |
| Buff Bake |
| Others |
Value Network & Pricing Analysis
Pea protein substitution for whey isolate is redrawing ingredient sourcing maps and compressing margin structures across formulation tiers. Manufacturers absorbing North American extraction bottlenecks face elevated input costs that transmit unevenly through subscription versus retail channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment scale. USDA Organic certification through the National Organic Program commands 40-60% shelf price premiums in natural retail, while direct-to-consumer subscriptions lock in lower per-unit economics through recurring revenue commitments. Price erosion runs through mass-market supermarket tiers as private-label compression intensifies. Health-Conscious Individuals in subscription channels exhibit lowest price sensitivity; Busy Professionals in convenience retail show highest elasticity.
Supply Chain Analysis
The United States and Canada anchor North American protein concentrate processing, with Germany and the Netherlands advancing insect protein extraction capabilities. Whey isolate supply draws from dairy commodity cycles, while pea protein rests on concentrated extraction facility capacity. Single-source vulnerability at three major North American plant protein processors creates formulation bottlenecks. Distribution runs through Port of Los Angeles trans-Pacific corridors and rail intermodal links to Chicago and Dallas hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around gym chains and fitness apps white-labeling curated cookie boxes, fragmenting traditional retail channel leverage.
For Market Incumbents: Shield subscription retention through precision fermentation R&D partnerships that neutralize plant-based texture deficits. Deepen backward integration into allergen-segregated co-manufacturing capacity to offset 90%+ utilization constraints at qualified facilities. Lock in exclusive whey isolate supply agreements before dairy commodity volatility intensifies. For New Entrants and Emerging Players: Differentiate on precision fermentation collagen integration for vegan chew-density parity. Target German Apotheke pharmacy channels where medical food positioning escapes conventional retail slotting requirements. Pursue EFSA novel food pre-submission pathways for insect protein formulations ahead of competitive entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed clean-label entrants holding captive subscription bases but strained co-manufacturer access. Five-to-ten year viability hinges on formulation patent portfolios bridging bakery process engineering with sports nutrition biochemistry. Monitor FDA allulose classification rulings as margin structure inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Lab-grown structural proteins enable vegan cookies to match whey-based chew density. |
| Subscription Platform Acquisition | Captive customer data streams from gym chains displace traditional retail channel economics. |
| Allergen-Segregated Capacity Expansion | Dedicated production lines for vegan and dairy-free runs alleviate 90%+ utilization bottlenecks. |
| EFSA Novel Food Pre-Submission | Early safety dossiers for house cricket flour compress 18-24 month regulatory timelines. |
| USDA Organic Certification Investment | National Organic Program eligibility commands 40-60% shelf price premiums in natural retail. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers, category buyers at natural retailers, sports nutrition formulators, and supply chain planners and refined through secondary validation. FDA nutrition labeling guidance documents, USDA National Organic Program standards, EFSA novel food safety assessments, and customs trade data on protein concentrate imports provided foundational benchmarks. Bottom-up demand modeling triangulated against top-down market sizing across formulation and channel dimensions.
Variance decomposition across the projection horizon isolates volume, price, and mix contributions to value expansion. Segmentation modeling incorporated product type, distribution channel, target consumer archetype, and flavor profile dimensions with regulatory pathway overlays. CAGRs were derived from normalized growth trajectory fitting against historical protein fortification adoption curves and digital fitness penetration rates.
Material uncertainties — FDA allulose classification delays, pea protein supply disruptions, and precision fermentation scale-up failures — sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory timelines and ingredient substitution elasticities. Recalibration cycles align with material shifts in FDA labeling enforcement and novel food approval velocities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Energy Gums Market
Nutritional Supplements
Forskolin Market
Nutritional Supplements
Mediterranean Citrus Nutricosmetic Complex Market
Nutritional Supplements
Algae Omega Market
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
South America Meal Replacement Products Market
Nutritional Supplements
Gummy Vitamins Market
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Meal Replacement Products OEM Market
Nutritional Supplements
Europe Botanical Supplements Market
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
Sea Moss Supplements Market
Nutritional Supplements
Africa Beta Glucan Market
Nutritional Supplements
Whey Protein Market
Nutritional Supplements
Krill Oil Market