
 Digestive Enzyme Complex Market | 2026-2036
Digestive Enzyme Complex Market Size, Share, and Industry Trends Forecast 2026-2036
Digestive Enzyme Complex Market Insights
Multi-source enzyme procurement is consolidating as large supplement brands reduce supplier fragmentation to secure batch consistency and traceability. Enzymedica leverages its specialized protease and lipase formulations to dominate the premium direct-to-consumer channel. Klaire Labs anchors its position through healthcare practitioner-exclusive distribution, while National Enzyme Company sustains contract manufacturing scale for private-label clients across North America.
A digestive enzyme complex comprises synergistic blends of pancreatic and plant-derived enzymes—typically amylase, protease, lipase, cellulase, and lactase—standardized to specific activity units per serving to catalyze macronutrient breakdown in the gastrointestinal tract. These formulations serve therapeutic, preventive, and performance-oriented purposes across human and animal nutrition applications. Pancreatin-based prescription-grade products occupy the highest-margin tier within pharmaceutical applications, while alpha-galactosidase formats compete aggressively in over-the-counter anti-bloating segments. Nutritional supplements channel the largest volume flow, though food and beverage fortification with heat-stable proteases represents the fastest-growing application frontier.
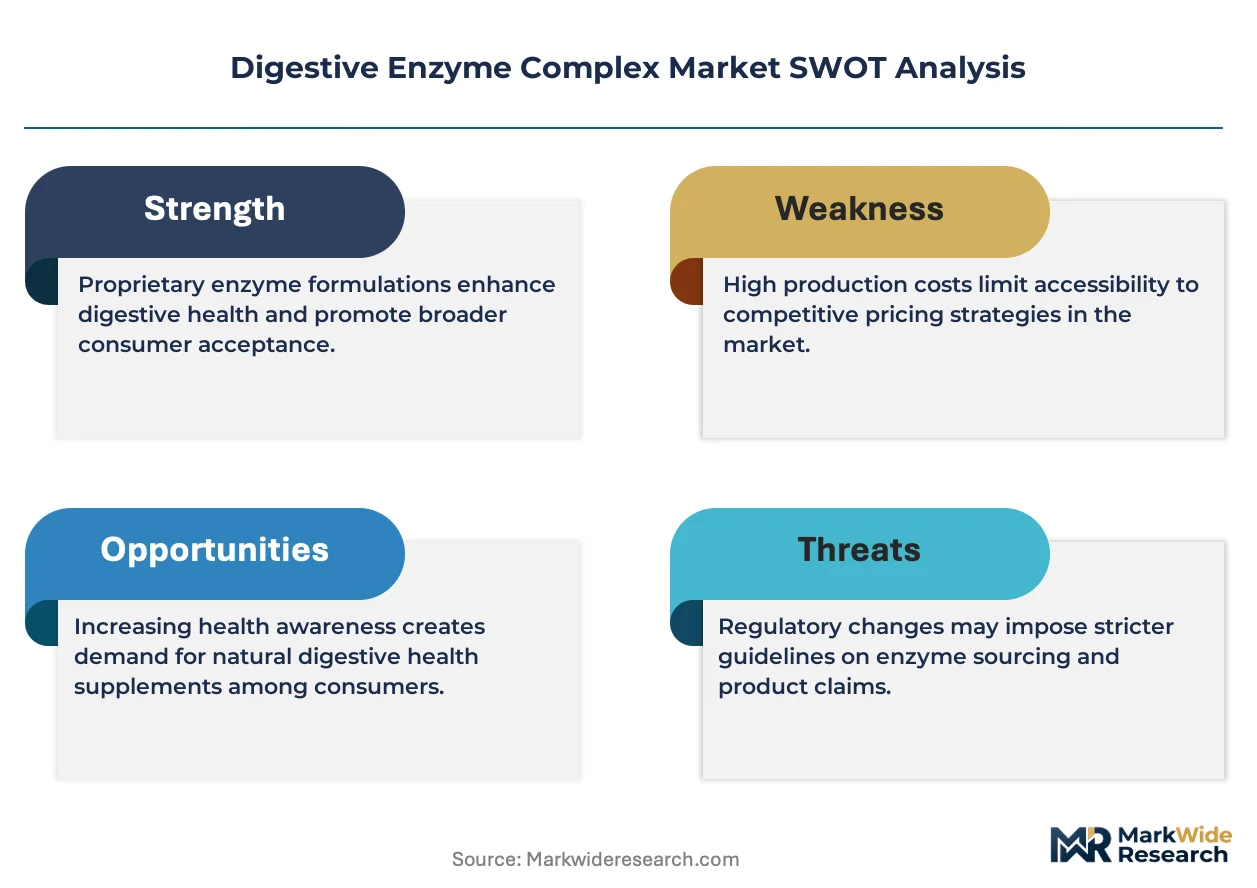
FDA oversight under DSHEA and cGMP manufacturing rules shapes product claims, enzyme activity labeling, and facility auditing requirements for all U.S.-marketed complexes. EFSA novel food evaluations and health claim restrictions in Europe constrain marketing language and substantiation burdens for enzyme suppliers seeking cross-border access. Stakeholders must monitor evolving pharmacovigilance expectations for enzyme-drug interactions as regulators scrutinize high-potency formulations previously treated as benign supplements.
Market Dynamics
Multi-source enzyme procurement is consolidating as large supplement brands reduce supplier fragmentation to secure batch consistency and traceability. This structural compression is reshaping competitive positioning across the value chain.
Growth Catalysts
- DSHEA Amendment Compliance:The FDA's evolving labeling requirements under dietary supplement amendments are forcing formulation upgrades that favor standardized activity-unit disclosure. Premium brands capture margin by leading this transparency transition.
- Healthcare Practitioner Channel:Prescription-grade pancreatin demand through clinician-exclusive distribution is accelerating as functional medicine protocols integrate enzyme therapy into gastrointestinal treatment regimens.
- Plant-Derived Enzyme Biotechnology:Microbial fermentation advances in Aspergillus-derived protease production are displacing animal-sourced alternatives and opening kosher, halal, and vegan-certified product lines.
Market Restraints
- Raw Material Concentration:High-purity pancreatin supply concentrates among porcine-derived processors in Denmark and Spain, creating single-source vulnerability for prescription-grade manufacturers.
- EFSA Novel Food Evaluations:European health claim restrictions and substantiation burdens constrain cross-border marketing language, delaying product launches by 18-24 months for enzyme suppliers seeking EU market access.
- Enzyme-Drug Interaction Scrutiny:Pharmacovigilance expectations for high-potency formulations previously treated as benign supplements are tightening, requiring clinical safety documentation that small brands cannot fund.
Strategic Opportunities
- Food and Beverage Fortification:Heat-stable protease integration into shelf-stable functional foods represents the fastest-growing application frontier, with sports nutrition bars and meal replacement beverages leading adoption.
- Direct-to-Consumer Subscription Models:Personalized enzyme blends based on microbiome testing are displacing one-size-fits-all SKUs, locking in recurring revenue and reducing customer acquisition costs.
- Veterinary Therapeutic Applications:Companion animal digestive health protocols are incorporating enzyme complexes into prescription diets, opening a margin-rich channel with lower regulatory burden than human pharmaceuticals.
Industry Challenges
- Activity Unit Standardization:Inconsistent assay methodologies across USP, FCC, and proprietary activity measurements create formulation mismatches and contract manufacturing disputes.
- cGMP Facility Certification Timelines:FDA facility auditing backlogs and corrective action requirements are extending time-to-market for new manufacturing entrants by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digestive Enzyme Complex Market |
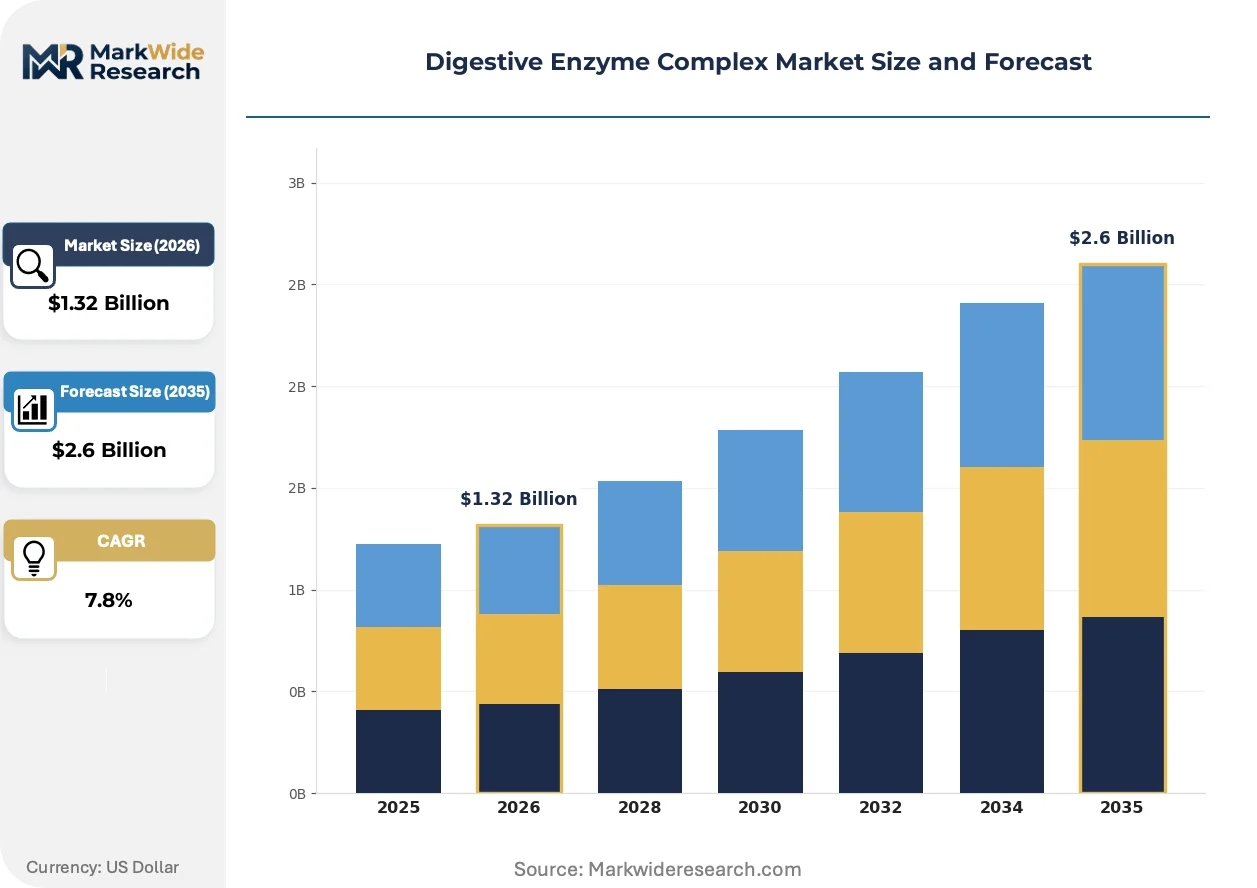
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.6 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pancreatin, Bromelain, Papain, Alpha-Galactosidase Application: Nutritional Supplements, Food & Beverage, Pharmaceutical, Animal Feed Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets Customer Type: Individuals, Healthcare Professionals, Fitness Enthusiasts, Pets |
| Companies Covered | AbbVie Inc., Amway Corporation, AST Enzyme, Biotics Research Corporation, Enzymedica, Klaire Labs, National Enzyme Company, Integrative Therapeutics, Garden of Life Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digestive Enzyme Complex Market Trends and Innovations
Formulation science and distribution architecture are undergoing parallel transformation as enzyme suppliers compete on bioavailability claims and channel control. Three developments are compressing competitive timelines.
Microencapsulation technology using enteric-coated beadlets is converging with sustained-release polymer matrices to protect enzyme activity through gastric transit. Nutritional supplement manufacturers adopting these dual-barrier systems command 15-20% price premiums over standard tablet formats. The structural consequence is tiered product architecture separating clinical-grade from commodity enzyme offerings.
EFSA's tightened novel food evaluation pathways and health claim substantiation requirements are constraining marketing language for enzyme suppliers seeking European market access. Industrial consequence includes delayed product launches and reformulation costs for brands dependent on cross-border revenue. Digestive health positioning now requires clinical trial investment that mid-tier brands cannot fund, advantaging established pharmaceutical enzyme divisions.
Practitioner-exclusive distribution models are fragmenting as telehealth platforms and direct-to-consumer microbiome testing services disintermediate traditional healthcare gatekeepers. Functional medicine clinicians are losing prescription control to algorithm-driven personalized supplement subscriptions. This channel compression is most visible in United States metropolitan markets where wellness-focused consumers bypass traditional healthcare access points.
Digestive Enzyme Complex Market Segmentation
Enzyme suppliers configure production lines around distinct specification tiers, with each segment demanding different activity-unit standardization, stability profiles, and regulatory documentation. Procurement patterns diverge sharply between prescription-grade manufacturers and commodity supplement blenders.
Product Type:
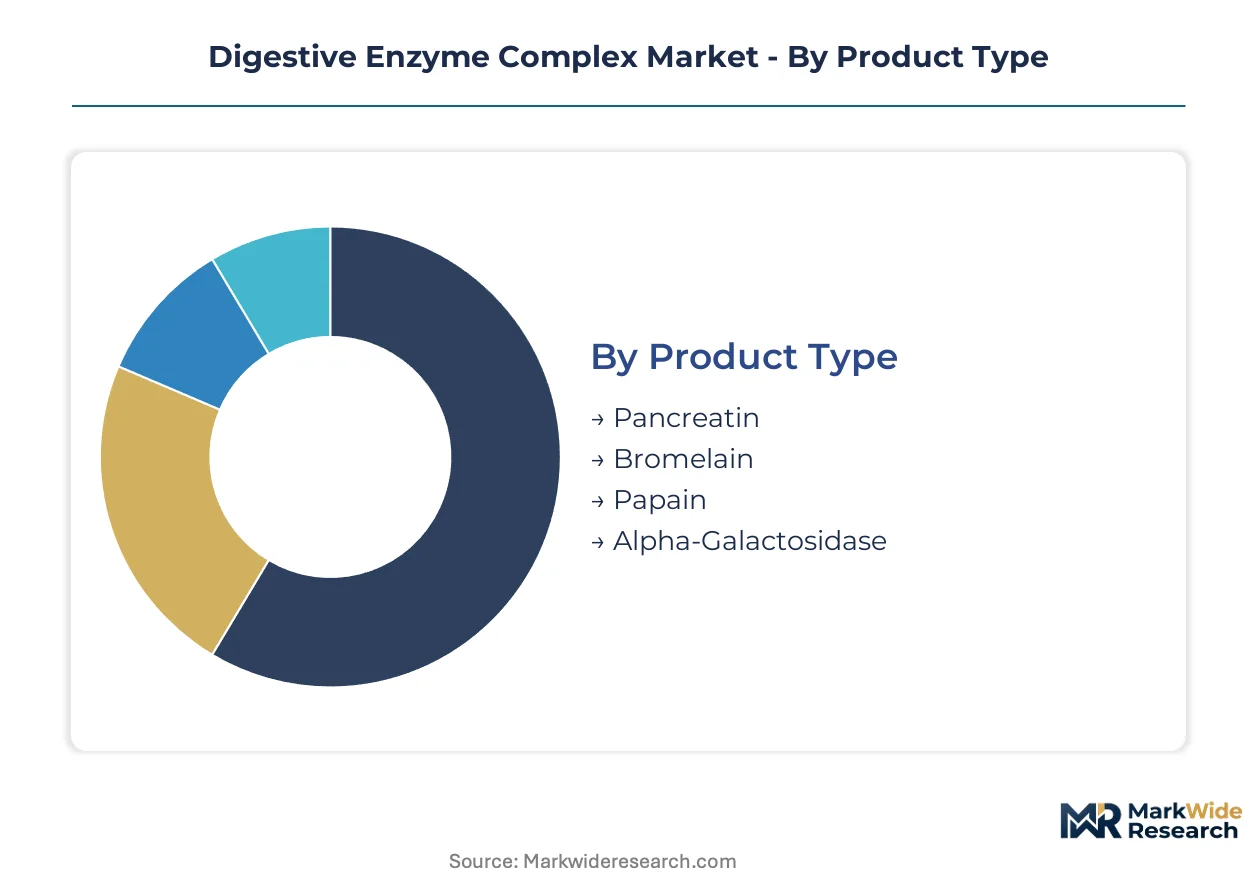
The customization-to-standardization spectrum spans prescription-grade pancreatin requiring batch-specific certificates of analysis to commodity proteases sold on bulk activity-unit pricing.
- Pancreatin:Porcine-derived multi-enzyme concentrate standardized to USP lipase, protease, and amylase activity units. Demand concentrates among prescription pharmaceutical manufacturers in the United States facing FDA cGMP audit requirements for pancreatic enzyme replacement therapy products.
- Alpha-Galactosidase:Single-enzyme formulation targeting oligosaccharide breakdown for flatulence reduction. Applications in over-the-counter anti-bloating supplements are expanding fastest through direct-to-consumer channels as microbiome awareness spreads.
- Bromelain:Pineapple stem-derived cysteine protease with established fibrinolytic applications.
- Papain:Papaya latex-derived protease used in meat tenderization and digestive supplements.
Most installed capacity flows through Pancreatin. Expansion is steepest in Alpha-Galactosidase.
Application:
Cost tier separation distinguishes clinical-grade documentation requirements from commodity food-grade specifications.
- Nutritional Supplements:Bulk powder and capsule formats dominating volume throughput. Direct-to-consumer brands in the United States drive formulation innovation through subscription-based personalized blends.
- Pharmaceutical:Prescription-grade pancreatin for exocrine pancreatic insufficiency requiring FDA-approved NDA or ANDA pathways. Clinician-exclusive distribution in functional medicine protocols supports premium pricing tiers.
- Food & Beverage:Heat-stable protease integration into shelf-stable functional foods and sports nutrition products.
- Animal Feed:Enzyme complexes for monogastric livestock digestion efficiency and companion animal therapeutic diets.
Volume leadership sits with Nutritional Supplements. Margin expansion concentrates in Pharmaceutical.
Distribution Channel:
Customer acquisition economics vary dramatically across channel types, with digital-native brands capturing lifetime value through subscription mechanics.
- Online Retail:Direct-to-consumer platforms and marketplace storefronts enabling personalized enzyme subscriptions. Fitness enthusiasts and gut-health-focused consumers in the United States bypass traditional retail for algorithm-driven product matching.
- Health Stores:Specialty retailers stocking practitioner-branded and premium consumer enzyme lines.
- Pharmacies:Prescription-grade pancreatin and pharmacist-recommended digestive aids.
- Supermarkets:Mass-market enzyme supplements positioned adjacent to probiotics and fiber categories.
Customer lifetime value peaks in Online Retail. Prescription volume anchors Pharmacies.
Customer Type:
Maturity gradients separate established clinical prescribing patterns from emerging wellness-driven self-selection behaviors.
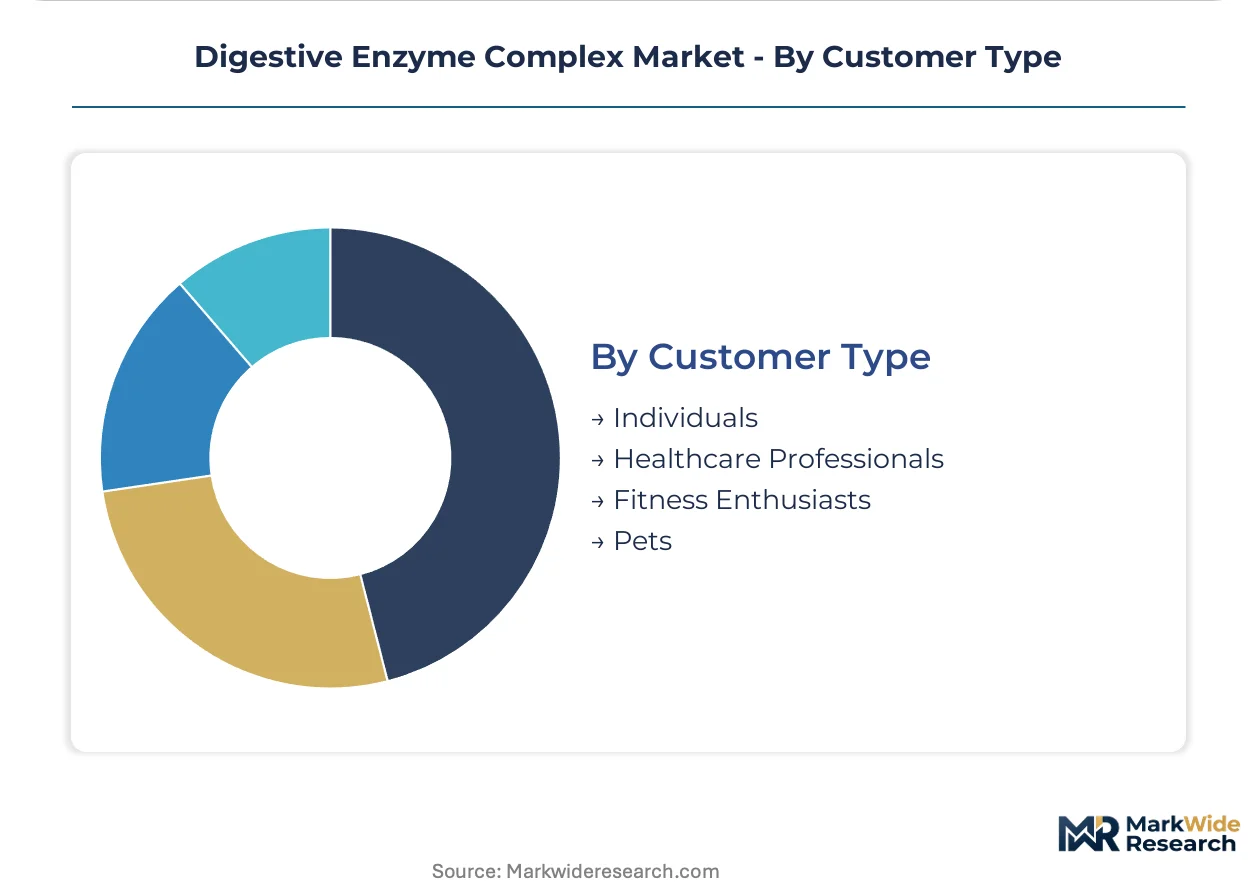
- Individuals:Self-directed consumers purchasing over-the-counter digestive aids. United States metropolitan markets show highest per-capita enzyme supplement penetration as functional wellness spending displaces reactive healthcare utilization.
- Healthcare Professionals:Functional medicine clinicians and gastroenterologists prescribing therapeutic enzyme protocols. Practitioner-exclusive brands maintain distribution control through credential-verified portals.
- Fitness Enthusiasts:Athletes and bodybuilders targeting protein digestion optimization and recovery support.
- Pets:Companion animal owners and veterinary clinics incorporating enzymes into prescription diets and therapeutic regimens.
Volume concentration favors Individuals. Prescription authority concentrates with Healthcare Professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting digestive enzyme production toward jurisdictions with streamlined novel-food pathways and lower cGMP compliance costs, while demand clusters persist in high-income markets with established functional wellness spending.
United States
FDA cGMP enforcement and DSHEA amendment compliance costs are accelerating supplier consolidation among domestic contract manufacturers. Direct-to-consumer enzyme brands in California and New York Metro command premium positioning through subscription mechanics. The FDA's evolving labeling requirements favor standardized activity-unit disclosure, disadvantaging smaller importers.
Germany
EFSA novel food evaluation timelines and health claim substantiation burdens delay product launches by 18-24 months for enzyme suppliers seeking EU market access. Bavaria and Baden-Württemberg host concentrated pharmaceutical enzyme processing capacity for prescription-grade pancreatin. The country's national pharmaceutical regulator maintains stringent pharmacovigilance expectations for high-potency formulations.
China
Microbial fermentation advances in Aspergillus-derived protease production are displacing animal-sourced alternatives and opening kosher, halal, and vegan-certified product lines. The Yangtze River Delta and Shandong Peninsula concentrate bulk enzyme manufacturing for export markets. NMPA oversight shapes domestic labeling standards and facility certification requirements.
India
Contract manufacturing scale for private-label clients is expanding as Western brands seek cost-competitive production alternatives. Maharashtra and Gujarat host emerging enzyme formulation clusters serving nutritional supplement exporters. FSSAI regulations govern food-grade enzyme specifications while CDSCO oversight applies to pharmaceutical applications.
Denmark
Porcine-derived pancreatin supply concentrates among high-purity processors, creating single-source vulnerability for prescription-grade manufacturers. Copenhagen and surrounding regions anchor Nordic pharmaceutical enzyme production. The country's national pharmaceutical regulator enforces batch-specific certificate-of-analysis requirements for pancreatic enzyme replacement therapy products.
Digestive Enzyme Complex Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue personalized microbiome-based subscription models and veterinary therapeutic applications. The market structure reflects moderate consolidation around specialized fermentation capabilities and healthcare practitioner distribution networks. Three archetypes dominate: pharmaceutical-grade pancreatin suppliers, direct-to-consumer wellness brands, and contract manufacturing specialists serving private-label clients. Competitive moves center on backward integration into raw material sourcing and geographic expansion through telehealth platform partnerships.
Within the practitioner-exclusive tier, Klaire Labs and Integrative Therapeutics occupy positions anchored through credential-verified distribution portals. Enzymedica represents the direct-to-consumer archetype with premium positioning in algorithm-driven product matching channels. Among diversified nutrition conglomerates, Amway Corporation and Garden of Life Inc. exemplify scale-driven portfolio breadth spanning enzyme complexes within broader supplement ecosystems. National Enzyme Company sits within the contract manufacturing archetype, sustaining production scale for private-label clients across North America.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Amway Corporation |
| AST Enzyme |
| Biotics Research Corporation |
| Enzymedica |
| Klaire Labs |
| National Enzyme Company |
| Integrative Therapeutics |
| Garden of Life Inc. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into porcine-derived pancreatin sourcing anchors pricing power for prescription-grade manufacturers while locking in batch consistency that commodity blenders cannot match. This upstream control separates clinical-grade suppliers commanding premium activity-unit pricing from private-label competitors exposed to raw material volatility.
Pricing Analysis
Distributor margin compression in the healthcare practitioner channel is forcing brands toward direct-to-consumer subscription models that capture full lifetime value. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and activity-unit standardization, with USP-verified pancreatin products commanding the widest spreads. Pricing pressure stems from bulk enzyme commoditization as Chinese fermentation capacity floods mid-tier supplement markets. Direct-to-consumer fitness enthusiasts show lowest price sensitivity, while supermarket mass-market buyers demand per-capsule cost parity with generic probiotics.
Supply Chain Analysis
Domestic-content mandates in India's nutritional supplement sector are reshaping sourcing patterns for Western private-label brands seeking FSSAI-compliant production alternatives. High-purity pancreatin supply concentrates in Denmark and Spain, while bulk Aspergillus-derived protease flows from China's Yangtze River Delta and Shandong Peninsula. Raw material dependencies center on porcine pancreas tissue, microbial fermentation substrates, and enteric coating polymers. Single-source vulnerability in Nordic pancreatin processing creates supply chain risk for prescription-grade manufacturers. Distribution runs through credential-verified practitioner portals for clinical-grade products and algorithm-driven subscription platforms for direct-to-consumer brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on microbial fermentation cost-down curves displacing animal-sourced inputs, while premium-tier shifts toward personalized microbiome-based subscriptions capture recurring revenue premiums.
For Market Incumbents: Extend formulation patent protection through microencapsulation technology investments that create 15-20% price premiums over standard tablet formats. Consolidate supplier relationships to reduce batch-to-batch variability exposure, as large supplement brands already compress multi-source procurement into single-source partnerships. Channel control through telehealth platform partnerships defends against algorithm-driven subscription services disintermediating traditional healthcare gatekeepers.
For New Entrants and Emerging Players: Launch via veterinary therapeutic applications where prescription diet integration faces lower regulatory burden than human pharmaceuticals. Target companion animal owners in United States metropolitan markets with margin-rich therapeutic regimens underserved by incumbent human-focused suppliers. White-space concentration in personalized enzyme blends based on at-home microbiome testing offers the most penetrable entry vector.
For Investors and Strategic Acquirers: Roll-up economics work for contract manufacturing specialists because private-label demand fragmentation across North American supplement brands sustains acquisition currency for facility-scale players. Five-to-ten year viability hinges on heat-stable protease capabilities serving food and beverage fortification's fastest-growing application frontier. Watch FDA cGMP enforcement intensity as the inflection signal determining whether small-batch craft enzyme brands survive compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Investment | Enteric-coated beadlets with sustained-release matrices protect enzyme activity through gastric transit, commanding clinical-grade price premiums. |
| Microbiome-Based Subscription Launch | Algorithm-driven personalized blends displace one-size-fits-all SKUs, locking recurring revenue and reducing customer acquisition costs. |
| Veterinary Therapeutic Expansion | Companion animal prescription diet integration opens margin-rich channel with lower regulatory burden than human pharmaceuticals. |
| Backward Integration into Fermentation | Captive Aspergillus-derived protease production secures kosher, halal, and vegan-certified supply lines for premium positioning. |
| Telehealth Platform Partnership | Direct-to-consumer algorithm matching bypasses traditional healthcare gatekeepers, capturing wellness-focused consumers in metropolitan markets. |
Research Methodology
Bottom-up nutritional supplement modeling reconciled against top-down pharmaceutical and food-grade enzyme production tracking forms the analytical core of this study. Primary interviews with formulation scientists at contract manufacturers, procurement leads at direct-to-consumer brands, regulatory affairs specialists navigating FDA cGMP audits, and veterinary nutritionists developing companion animal therapeutic diets combined with secondary validation. Data sources include FDA facility inspection databases, EFSA novel food evaluation registers, USP monograph activity-unit standards, and customs records tracking bulk enzyme imports into North American processing hubs.
Historical trendline analysis of prescription-grade pancreatin pricing and microbial fermentation capacity expansion informed projection parameters across the analysis window. Segmentation modeling incorporated product type tiers, application channels from pharmaceutical to food fortification, distribution mechanics spanning practitioner portals to subscription platforms, and customer archetypes from self-directed consumers to credential-verified clinicians. CAGRs derived from elasticity-adjusted demand curves and supply-side capacity buildout timelines, with specific inputs including DSHEA amendment compliance cost trajectories and heat-stable protease adoption rates in sports nutrition applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA pharmacovigilance enforcement shifts or EFSA health claim substantiation requirement escalations. Projections reflect assumptions regarding regulatory pathway stability, raw material supply continuity from Nordic porcine processors, and consumer willingness-to-pay for personalized microbiome-matched formulations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Human Milk Oligosaccharides (HMO) Market
Nutritional Supplements
Coral Calcium Supplements Market
Nutritional Supplements
Sleep Gummies Market
Nutritional Supplements
GLP-1 Hydration Product Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
North America Spirulina Extract Market
Nutritional Supplements
Global Egg Protein Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
CBD Nutraceuticals Market
Nutritional Supplements
Algae Omega Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Europe Feed Prebiotics Market
Nutritional Supplements
Energy Gums Market