
 Global Collagen Peptides Market | 2026-2036
Global Collagen Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Collagen Peptides Market Analysis
Subscription-based replenishment programs for collagen peptide powders is repositioning how consumers engage with the category, shifting one-time purchases into recurring revenue streams. Gelita AG leverages its century-old gelatin heritage to sustain European manufacturing dominance in pharmaceutical-grade hydrolysates. Darling Ingredients anchors North American supply through its integrated rendering-to-peptide value chain. Rousselot competes on marine-sourced collagen specialization, targeting cosmetics industry formulators with traceable fish-derived inputs.
Collagen peptides comprise short-chain amino acid sequences—primarily glycine, proline, and hydroxyproline—produced through controlled enzymatic hydrolysis of native collagen, typically achieving molecular weights below 10 kDa for optimal bioavailability in human tissue repair and protein synthesis applications. The hydrolyzed collagen segment leads volume due to its solubility advantages in functional beverages and sports nutrition, while marine-sourced variants command premium positioning in cosmetics applications where sustainability credentials and halal compliance broaden addressable markets. Nutritional supplements as an end-user category captures the fastest growth trajectory, though food and beverage sector integration into fortified dairy and confectionery maintains the largest absolute revenue pool.
EFSA novel food evaluations, FDA GRAS self-affirmation pathways, and FSSAI functional food ingredient registrations collectively determine which collagen sources and hydrolysis grades achieve commercial distribution in their respective jurisdictions. REACH compliance for residual processing chemicals and EU Green Deal-aligned carbon footprint disclosures are tightening entry barriers for non-integrated suppliers. Stakeholders must monitor evolving allergen labeling requirements for marine and bovine sources while calibrating sourcing strategies against shifting religious dietary certification demands.
Market Dynamics
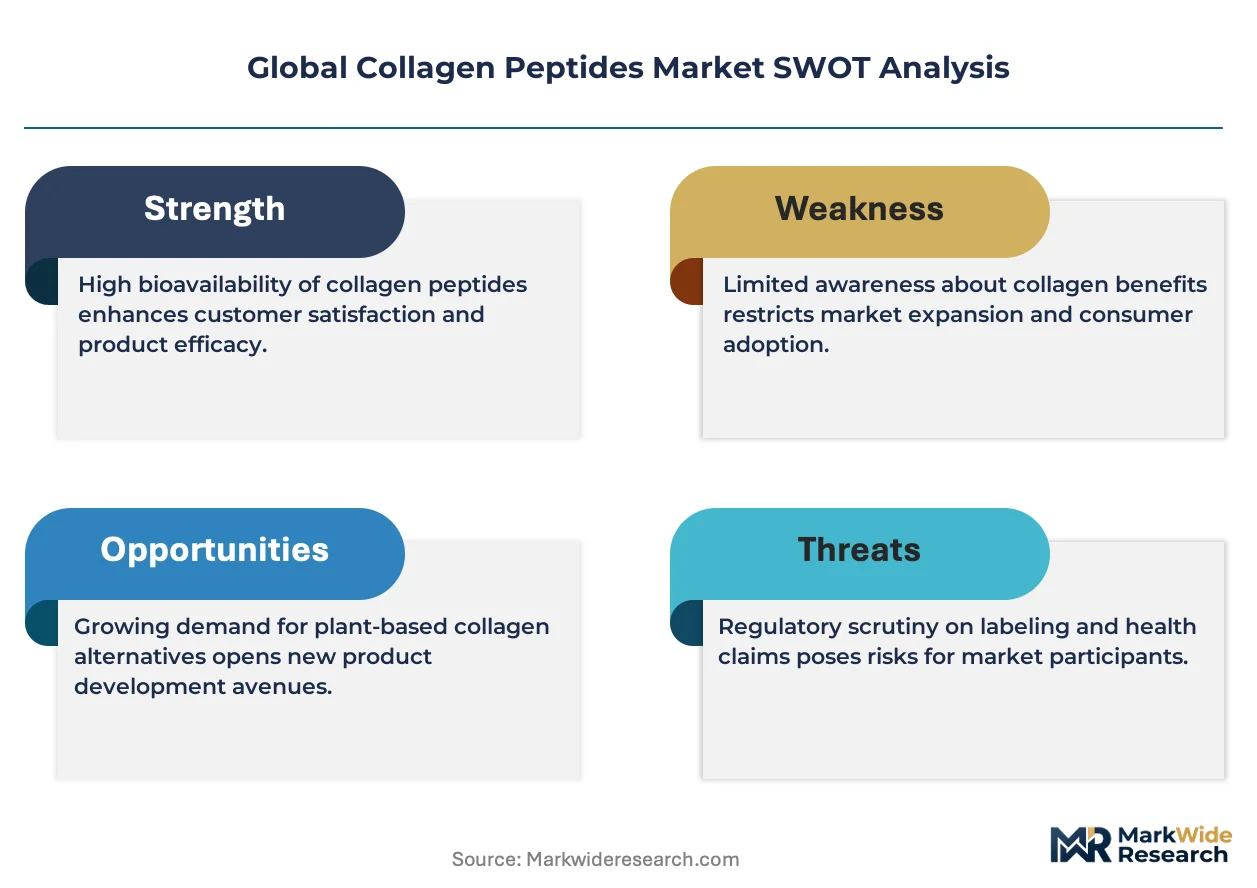
Enzymatic hydrolysis refinements are compressing production cycles and tightening purity benchmarks, forcing suppliers to recalibrate capital deployment toward continuous-flow bioreactor systems or cede share to integrated processors.
Growth Catalysts
- EFSA novel food pathways:Streamlined safety evaluations for marine-sourced collagen hydrolysates accelerate European cosmetics and nutraceutical commercialization timelines.
- Sports nutrition formulators:Functional beverage brands in the United States are embedding collagen peptides into post-workout recovery SKUs, creating pull-through for pharmaceutical-grade inputs.
- Halal certification infrastructure:Traceable fish-derived supply chains from Southeast Asian processing hubs unlock Middle Eastern and Indonesian consumer segments previously inaccessible to bovine sources.
Market Restraints
- Raw material cost volatility:Bovine hide and fish skin prices fluctuate with livestock harvest cycles and fishery quota restrictions, squeezing margin structures for non-integrated peptide producers.
- REACH compliance burdens:Residual solvent documentation and carbon footprint disclosure mandates under EU Green Deal alignment raise fixed compliance costs for smaller European manufacturers.
- Plant protein substitution:Pea and rice protein isolates with comparable amino acid profiles capture share in mass-market sports nutrition, pressuring collagen's premium positioning.
Strategic Opportunities
- Brazilian functional food penetration:ANVISA regulatory modernization for novel protein ingredients creates first-mover advantage for collagen-fortified dairy and confectionery launches.
- Subscription replenishment channels:Direct-to-consumer auto-ship models for powdered collagen peptides convert transactional buyers into predictable recurring revenue streams.
- Bioreactor-cultured collagen convergence:Precision fermentation platforms combining microbial chassis with recombinant collagen expression promise animal-free supply chains with identical amino acid sequences.
Industry Challenges
- Cross-functional talent scarcity:Bioprocess engineers with simultaneous expertise in enzymatic hydrolysis optimization and food-grade GMP compliance command premium compensation, constraining scale-up velocity.
- Multi-jurisdiction certification timelines:Simultaneous FDA GRAS self-affirmation, EFSA novel food dossier preparation, and FSSAI functional food registration create 18-24 month commercialization lags.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Collagen Peptides Market |
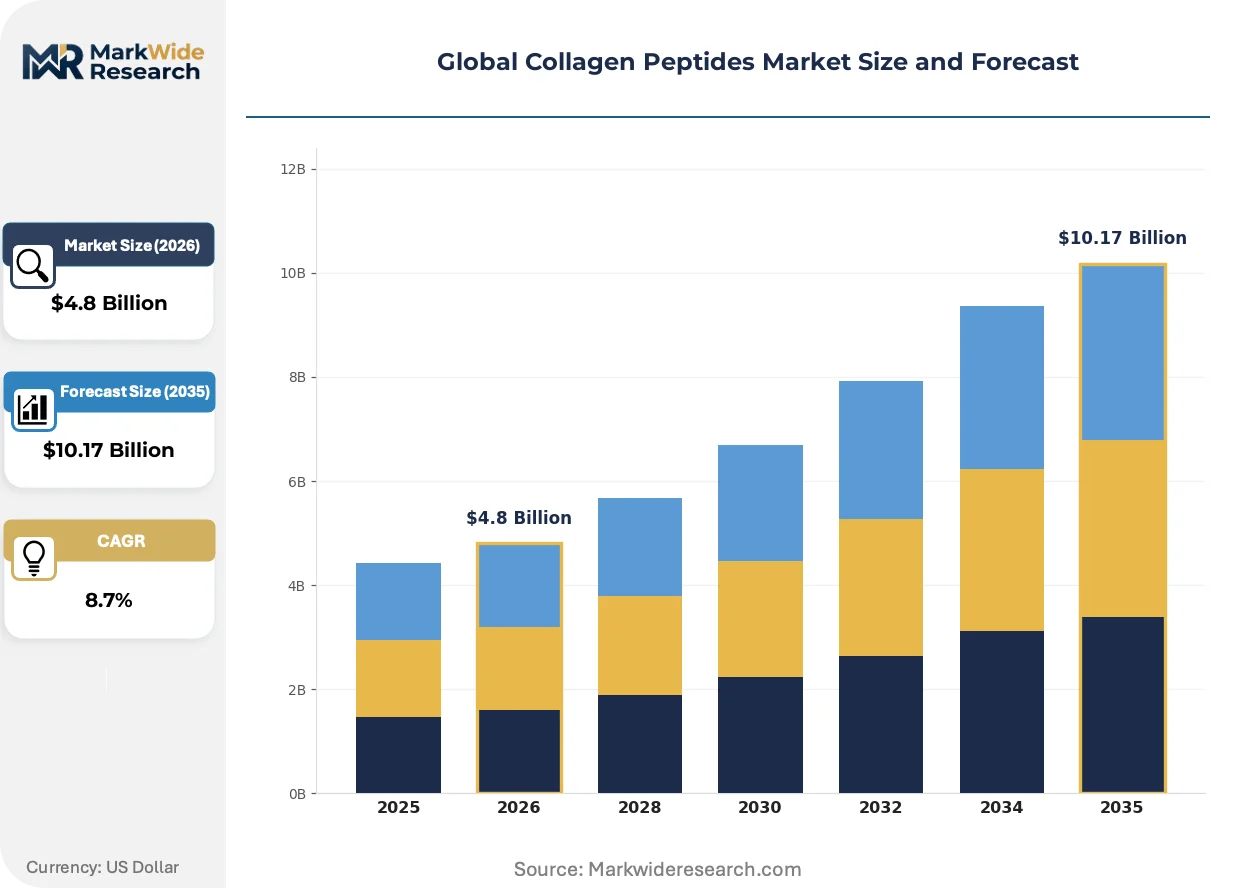
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Undenatured Collagen, Collagen Peptide Powders End User: Food & Beverage Sector, Cosmetics Industry, Nutritional Supplements, Pharmaceuticals Source: Bovine, Porcine, Marine, Chicken Application: Functional Foods, Dietary Supplements, Cosmetics, Medical Applications |
| Companies Covered | Gelita AG, Darling Ingredients, Nitta Gelatin, Tessenderlo Group, Rousselot, Weishardt Group, PB Gelatins, Lapi Gelatine, Vital Proteins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Collagen Peptides Market Emerging Trajectories
Clean-label extraction protocols and molecular weight precision are redefining competitive differentiation, collapsing the historical gap between cosmetic-grade and nutritional-grade specifications while opening new application categories.
Membrane filtration technology with tunable molecular weight cutoffs is modularizing collagen peptide production into standardized unit operations. Nutraceutical contract manufacturers in Germany and the United States are adopting skid-mounted systems that swap between 3 kDa and 10 kDa specifications without line shutdowns. This flexibility collapses minimum order quantities and enables just-in-time customization for functional beverage brands with volatile formulation cycles.
EU Green Deal-aligned carbon footprint disclosure requirements are forcing supply chain reconfiguration across marine collagen processors. EFSA guidance on novel food environmental impact assessments now mandates cradle-to-gate lifecycle documentation for fish-sourced hydrolysates. Italian and French cosmetics formulators are responding by consolidating procurement around North Sea fishery cooperatives with certified traceability systems, displacing fragmented Mediterranean sourcing.
Certification-driven preference shifts are restructuring B2B procurement patterns among multinational food brands. FSSAI functional food ingredient registrations and halal compliance documentation now precede price negotiations in supplier selection workflows. Indian and Indonesian dairy processors prioritize collagen peptide vendors with pre-certified dual-compliance packages, compressing supplier shortlists and elongating qualification timelines for uncertified competitors.
Global Collagen Peptides Market Segmentation
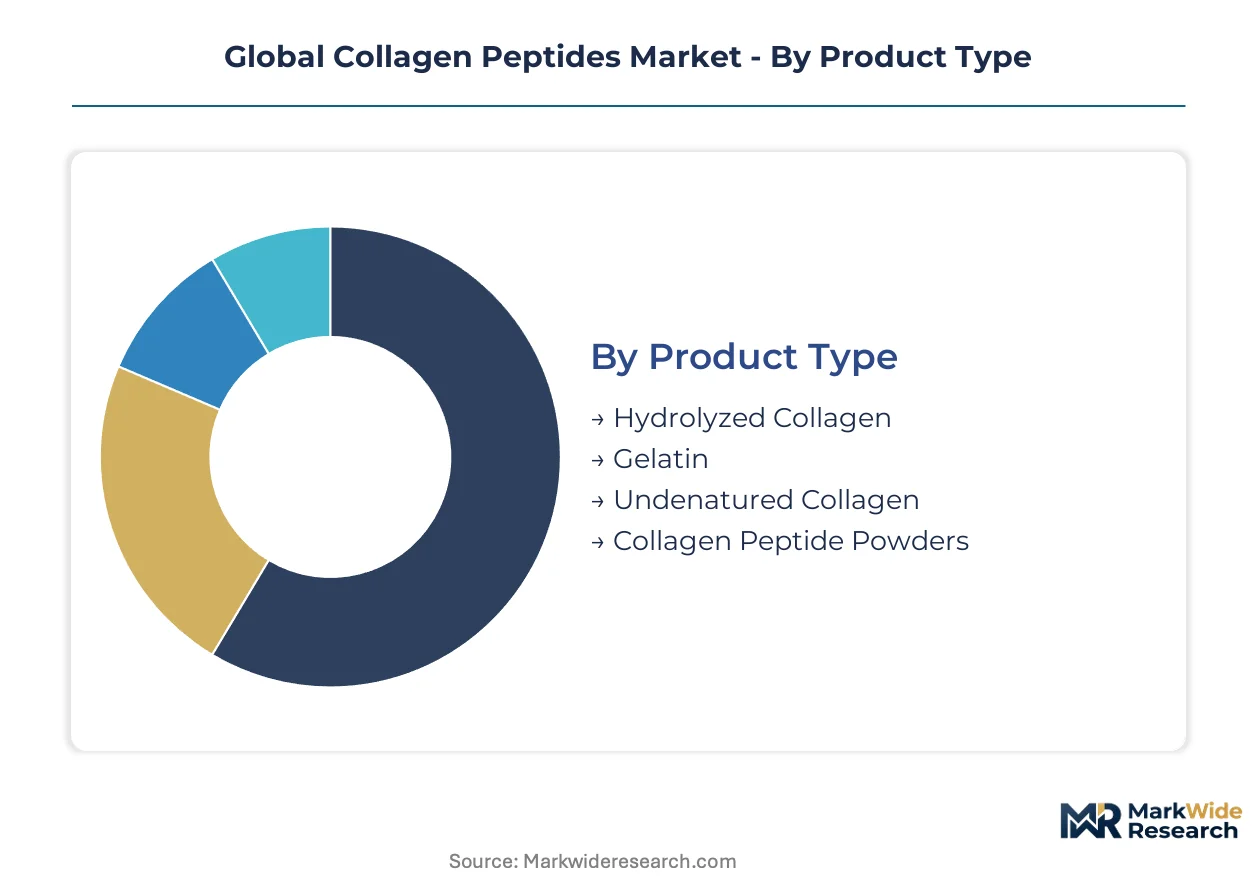
Segmentation in the collagen peptides market determines sourcing strategies, regulatory pathways, and capital allocation priorities. Suppliers configure enzymatic hydrolysis lines and certification packages around specific product grades and end-use specifications rather than pursuing universal coverage.
Product Type:
Production assets cluster around hydrolysis sophistication levels, with continuous-flow bioreactor investments favoring suppliers targeting pharmaceutical-grade specifications over commodity gelatin outputs.
- Hydrolyzed Collagen:Enzymatically cleaved peptide chains below 10 kDa molecular weight achieve rapid dissolution in functional beverages and sports nutrition formulations. United States-based sports nutrition brands embed these inputs into post-workout recovery SKUs, pulling pharmaceutical-grade material through previously cosmetic-dominant supply channels.
- Gelatin:Partial hydrolysis yields gelling proteins with Bloom strength specifications determining confectionery and pharmaceutical capsule applications. European manufacturers with century-old rendering heritage sustain capacity concentration here, though margin compression from energy-intensive processing favors strategic retreat toward higher-value peptide grades.
- Undenatured Collagen:Native triple-helix preservation targets joint health applications with distinct immunomodulatory claims.
- Collagen Peptide Powders:Spray-dried formats with neutral organoleptic profiles enable direct-to-consumer subscription channels and clean-label fortification.
Hydrolyzed collagen absorbs the bulk of installed capacity; collagen peptide powders are expanding most quickly.
End User:
Customer procurement workflows diverge sharply between regulated pharmaceutical channels and discretionary cosmetic segments, dictating divergent sales force structures and certification investments.
- Nutritional Supplements:Powder and capsule formats dominate as consumers prioritize protein fortification and joint health maintenance. Direct-to-consumer auto-ship models convert transactional buyers into recurring revenue streams, compressing customer acquisition costs relative to retail-dependent competitors.
- Food & Beverage Sector:Fortified dairy, confectionery, and functional beverage applications require FSSAI registration in India and FDA GRAS self-affirmation in the United States, elongating supplier qualification timelines.
- Cosmetics Industry:Marine-sourced variants with sustainability credentials and halal compliance broaden addressable markets in Southeast Asia and the Middle East.
- Pharmaceuticals:Injectable-grade hydrolysates command stringent endotoxin and heavy metal specifications, limiting viable supplier pools.
Food & Beverage Sector absorbs the bulk of installed capacity; nutritional supplements are climbing the fastest.
Source:
Raw material geography determines religious dietary compliance, carbon footprint disclosure obligations, and exposure to livestock harvest cycle volatility.
- Bovine:Hide and bone rendering from integrated meatpacking operations supplies the largest volume base. REACH compliance for residual processing chemicals and EU Green Deal-aligned carbon footprint disclosures favor consolidated North American and European processors over fragmented Mediterranean suppliers.
- Marine:Fish skin and scale hydrolysis from North Sea fishery cooperatives delivers traceable, certified-sustainable inputs for Italian and French cosmetics formulators. EFSA novel food environmental impact assessments now mandate cradle-to-gate lifecycle documentation, displacing unverified Southeast Asian sourcing.
- Porcine:Skin and bone-derived material serves markets without halal or kosher constraints, typically at cost advantage.
- Chicken:Sternum cartilage extraction yields type II collagen variants for joint health applications with distinct clinical positioning.
Bovine sources absorb the bulk of installed capacity; marine sourcing is gaining share fastest.
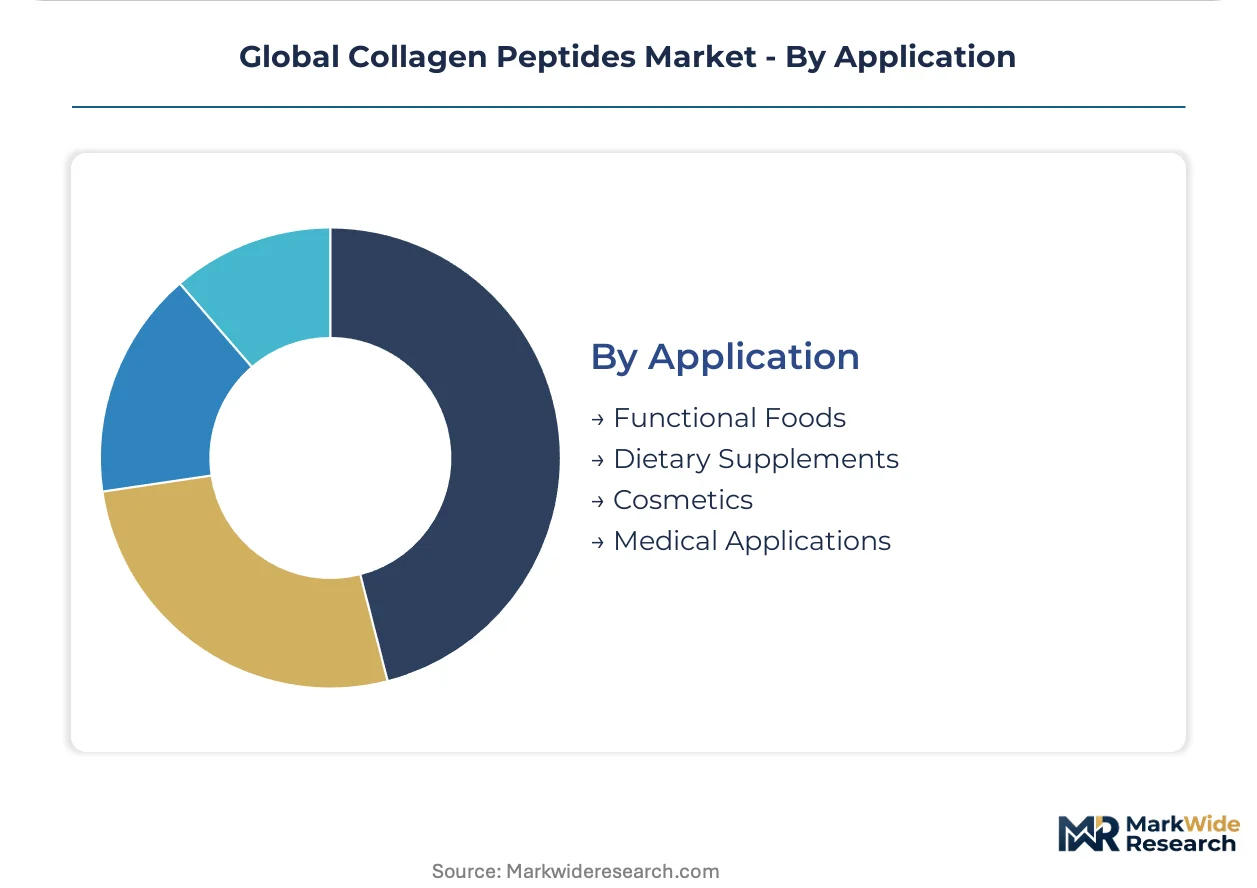
Application:
Formulation requirements span solubility thresholds, pH stability windows, and sensory masking demands that collapse the historical gap between cosmetic-grade and nutritional-grade specifications.
- Dietary Supplements:Tablet, capsule, and ready-to-mix powder formats prioritize bioavailability claims and clean-label positioning. Membrane filtration technology with tunable molecular weight cutoffs enables just-in-time customization for brands with volatile formulation cycles.
- Functional Foods:Beverage, dairy, and confectionery fortification demands heat stability and neutral flavor profiles that strain unoptimized hydrolysis outputs.
- Cosmetics:Topical formulations require low-odor, low-color peptide grades with documented dermal penetration data.
- Medical Applications:Wound healing matrices and tissue engineering scaffolds impose sterility and biocompatibility standards accessible only to GMP-certified manufacturers.
Dietary supplements absorb the bulk of installed capacity; functional foods are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and the United States, while consumption accelerates fastest in India and Brazil. Regulatory divergence across FDA, EFSA, and FSSAI frameworks fragments commercialization timelines. Raw material access and certification infrastructure determine competitive positioning in each geography.
United States
Sports nutrition brands and functional beverage formulators drive pharmaceutical-grade collagen uptake through post-workout recovery SKUs. FDA GRAS self-affirmation pathways streamline ingredient approvals for fortified dairy applications. Chicago and New Jersey host contract manufacturing clusters where membrane filtration systems enable just-in-time customization for volatile brand formulation cycles.
Germany
Century-old gelatin heritage sustains European dominance in pharmaceutical-grade hydrolysates and confectionery applications. EFSA novel food evaluations and REACH compliance for residual processing chemicals tighten purity benchmarks. The Eberbach industrial cluster anchors enzymatic hydrolysis capacity serving cosmetics formulators across France and Italy.
India
FSSAI functional food ingredient registrations and halal compliance documentation now precede price negotiations in supplier selection workflows. Dairy processors in Maharashtra and Gujarat prioritize vendors with pre-certified dual-compliance packages. The Mumbai-Pune corridor concentrates contract manufacturing for Southeast Asian export markets.
Brazil
ANVISA regulatory modernization for novel protein ingredients creates first-mover advantage for collagen-fortified dairy and confectionery launches. São Paulo-based food brands integrate hydrolyzed peptides into functional beverage portfolios. The Campinas research triangle hosts pilot-scale bioreactor facilities testing continuous-flow production systems.
Japan
Aging demographics prioritize joint health maintenance and protein fortification in senior nutrition formats. METI standards for functional food labeling create compliance thresholds for bioavailability claims. The Kansai industrial corridor around Osaka maintains specialized capacity for low-molecular-weight cosmetic-grade hydrolysates.
Global Collagen Peptides Market Vendor Landscape
Top-tier vendors anchor pharmaceutical-grade and marine-sourced specializations, while mid-scale processors compete on regional certification packages and flexible membrane filtration capacity. The vendor base stratifies across integrated rendering-to-peptide operators, enzymatic hydrolysis technology licensors, and nutraceutical contract manufacturers. Three archetypes dominate: heritage gelatin producers with backward integration into raw material rendering, marine-sourced specialists leveraging traceable fishery cooperatives, and direct-to-consumer brands capturing subscription replenishment economics. Competitive moves concentrate on M&A for integrated supply chain control and strategic partnerships for multi-jurisdiction certification acceleration.
Among European heritage producers, Gelita AG exemplifies the integrated rendering-to-peptide archetype through its century-old manufacturing footprint. Rousselot occupies a position within marine-sourced specialization, representing traceable fish-derived supply chain capabilities for cosmetics industry procurement. Darling Ingredients anchors North American supply security through captive raw material access from integrated meatpacking operations. These three companies represent distinct strategic vectors—heritage integration, marine sustainability credentials, and vertical raw material control—that structure competitive positioning across the forecast window.
| Leading Market Players |
|---|
| Gelita AG |
| Darling Ingredients |
| Nitta Gelatin |
| Tessenderlo Group |
| Rousselot |
| Weishardt Group |
| PB Gelatins |
| Lapi Gelatine |
| Vital Proteins |
| Others |
Supply Flow & Price Mechanics
Direct-to-consumer subscription buyers concentrate purchasing power through auto-ship collagen peptide programs, locking in predictable revenue that favors contract-based long-term offtake over spot-market transactions. This buyer archetype consolidation tightens price negotiation leverage for bulk powder formats while fragmenting pricing power across marine-sourced specialty grades.
Pricing Analysis
Margin tightening in pharmaceutical-grade hydrolysates reflects enzymatic hydrolysis equipment depreciation and REACH compliance documentation burdens. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified manufacturers from cosmetic-grade processors and commodity gelatin suppliers. Cost-down pressure on standard-tier bovine peptides accelerates because pea protein isolates capture mass-market sports nutrition share. Nutritional supplement contract manufacturers exhibit highest price sensitivity; pharmaceutical capsule formulators show least.
Supply Chain Analysis
Single-source vulnerability sits with North Sea fishery cooperatives supplying traceable marine collagen to French and Italian cosmetics formulators. Production gravity centers on Germany, the United States, and Brazil, with raw material dependencies spanning bovine hide rendering, fish skin hydrolysis, and enzymatic processing chemicals. Tariff exposure on cross-Atlantic peptide shipments threatens margin structures for non-integrated European suppliers. Distribution runs through nutraceutical contract manufacturers in Chicago and New Jersey clusters before reaching direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous-flow bioreactor systems are displacing batch enzymatic hydrolysis platforms, compressing production cycles and resetting capital intensity benchmarks across supplier tiers.
For Market Incumbents: To counter precision-fermentation entrants promising animal-free collagen sequences, deepen backward integration into captive bovine rendering operations and accelerate FDA GRAS self-affirmation for novel hydrolysis grades. Prioritize membrane filtration capacity additions in Germany and the United States to defend formulation flexibility against agile contract manufacturers. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription channels targeting underpenetrated Brazilian functional food markets where ANVISA regulatory modernization creates first-mover windows. White-space opportunities concentrate in halal-certified marine peptides for Indonesian dairy processors and bioreactor-cultured collagen for cosmetics formulators seeking sustainability credentials. For Investors and Strategic Acquirers: The window for entry favors integrated rendering-to-peptide operators with pre-certified multi-jurisdiction compliance packages. Long-term viability hinges on carbon footprint disclosure capabilities aligning with EU Green Deal mandates. Watch EFSA novel food evaluation timelines as inflection indicators for marine-sourced commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering Operations | Darling Ingredients anchors North American supply security through captive raw material access from meatpacking operations. |
| Continuous-Flow Bioreactor Deployment | Campinas pilot facilities test production systems that compress enzymatic hydrolysis cycles for Brazilian dairy fortification. |
| Halal Certification Infrastructure Investment | Traceable fish-derived supply chains from Southeast Asian hubs unlock Middle Eastern consumer segments inaccessible to bovine sources. |
| Direct-to-Consumer Subscription Launch | Vital Proteins captures recurring revenue economics that convert transactional buyers into predictable replenishment streams. |
| EFSA Novel Food Dossier Acceleration | Rousselot leverages streamlined safety evaluations to compress European cosmetics and nutraceutical commercialization timelines. |
Methodological Framework
Multi-period observation of enzymatic hydrolysis capacity additions, certification timeline completions, and subscription channel revenue mixes anchored the trend analysis, supplemented by interviews with bioprocess engineers, FSSAI registration consultants, sports nutrition formulators, and cosmetics procurement directors. Secondary validation drew from FDA GRAS notification databases, EFSA novel food opinions, customs trade records, and SEC 10-K filings of publicly traded rendering operators. Bottom-up peptide production estimates triangulated against top-down functional food ingredient consumption models.
Input-output matrices mapped hydrolysis sophistication levels against end-use procurement workflows across the projection horizon. Segmentation dimensions spanned product type, source origin, application category, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating raw material price elasticity and certification lag effects. Industry-specific forecast inputs included fishery quota restrictions and enzymatic processing yield improvements.
The model assumes a particular technology adoption path; alternative pathways for precision-fermentation collagen would alter the outlook if microbial chassis expression achieves cost parity with animal-derived hydrolysates. Forecasts reflect documented assumptions about regulatory approval velocities and consumer willingness-to-pay for sustainability credentials. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Europe Nutritional Beverages Market
Nutritional Supplements
North and South America Mineral Supplement Tablets Market
Nutritional Supplements
South America Nutraceuticals Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Zinc Supplement Market
Nutritional Supplements
North America Insoluble Dietary Fibers Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Bone Broth Protein Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Indonesia Beauty Supplements Market
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
Choline Market
Nutritional Supplements
Global Vitamin Supplements Market
Nutritional Supplements
Lipid Nutrition Market