
 Germany Whey Protein Market | 2026-2036
Germany Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Whey Protein Market Foresight
Asset-light contract manufacturing and third-party toll processing is fragmenting competitive boundaries in German whey protein, allowing smaller brands to enter without capital-intensive drying and separation infrastructure. DMK Deutsches Milchkontor GmbH anchors upstream supply through its cooperative dairy network across northern Germany. Glanbia Plc differentiates via isolate and hydrolysate specialization for premium sports nutrition channels. Euroduna Food Ingredients GmbH competes on regional logistics proximity to mid-sized functional food processors.
Germany whey protein denotes the dairy-derived protein fraction extracted during cheese manufacturing, typically containing beta-lactoglobulin, alpha-lactalbumin, and immunoglobulins with protein concentrations ranging from 35% to 90% depending on processing grade; it serves primarily as a functional ingredient in formulated foods and nutritional products targeting muscle protein synthesis and satiety modulation. Isolate commands the highest margin pool due to filtration intensity and lactose-free positioning, while hydrolysate represents the fastest-growing product type as enzymatic pre-digestion appeals to athletes with gastrointestinal sensitivity. Sports nutrition applications dominate volume offtake, though functional beverages are gaining share as ready-to-drink formats penetrate convenience retail channels.
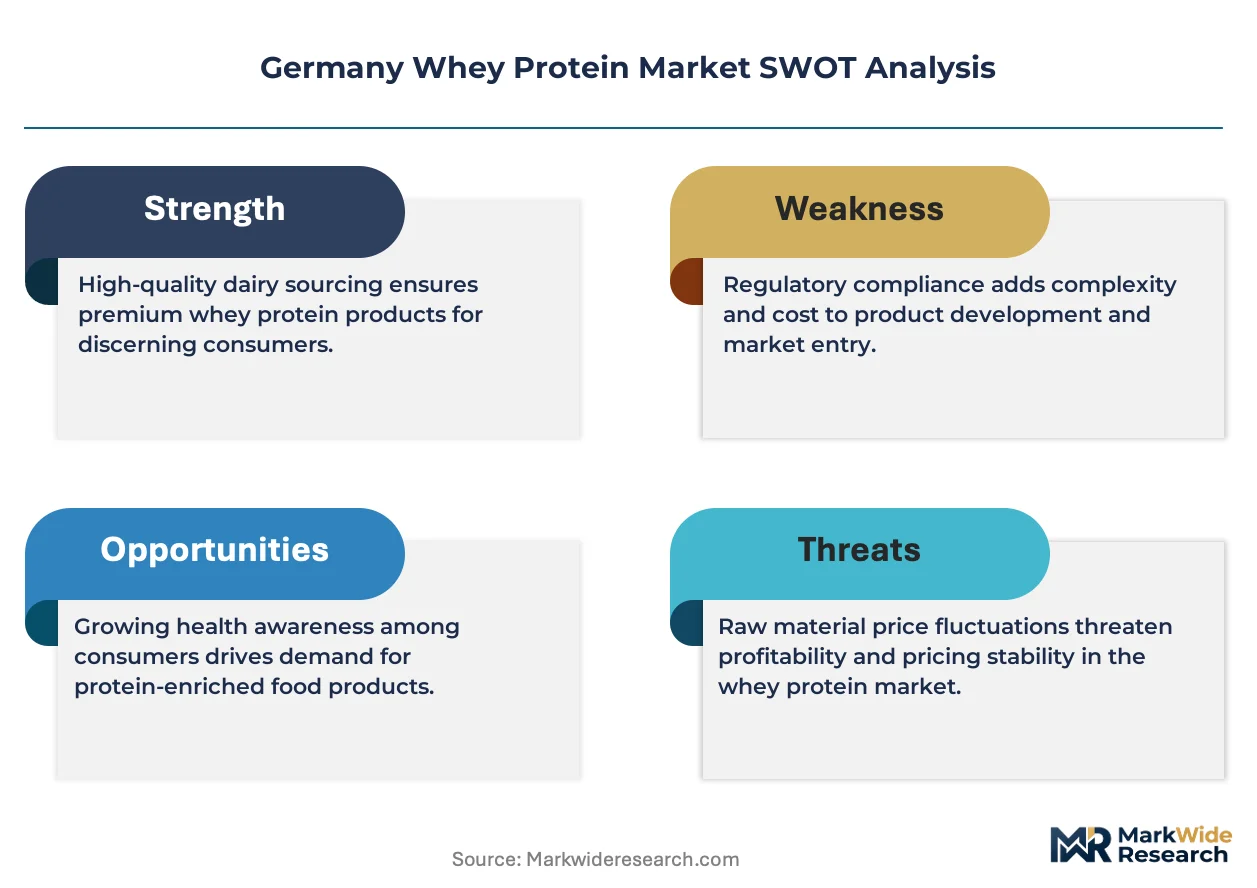
The European Food Safety Authority (EFSA) evaluates health claim substantiation for whey protein products marketed in Germany, while the German Federal Office of Consumer Protection and Food Safety (BVL) enforces national residue limits and hygiene standards across dairy processing facilities. These frameworks elevate compliance costs for imported concentrates but simultaneously protect domestic processors from lower-standard competition. Stakeholders must monitor evolving EFSA opinions on protein-specific health claims, as revised substantiation requirements could reshape permissible marketing language and reformulation priorities across the German market.
Market Dynamics
The EU's Farm to Fork Strategy is compressing margins across German whey protein supply chains by mandating traceable sustainability credentials and carbon footprint disclosure for dairy-derived ingredients entering formulated foods.
Growth Catalysts
- Amateur athlete expansion:Sports nutrition demand is dispersing beyond bodybuilding into running, cycling, and team sports communities throughout Bavaria and North Rhine-Westphalia.
- EFSA health claim pathways:Substantiated protein-specific claims for muscle maintenance and satiety modulation are enabling premium positioning in functional beverages and medical nutrition.
- Contract manufacturing proliferation:Asset-light toll processing infrastructure is lowering barriers for mid-sized brands seeking isolate and hydrolysate grades without captive drying facilities.
Market Restraints
- Feed cost volatility:German dairy cooperative milk pricing fluctuates with global grain and soybean meal markets, compressing processor margins on concentrate output.
- Import compliance friction:Non-EU concentrate suppliers face elevated BVL residue testing and hygiene documentation requirements that extend customs clearance timelines.
- Plant protein substitution:Pea and fava protein isolates are capturing share in mass-market sports nutrition and vegan-positioned functional foods.
Strategic Opportunities
- Ready-to-drink penetration:Convenience retail and petrol station channels in urban centers present underexploited distribution for shelf-stable protein beverages.
- Medical nutrition applications:Sarcopenia-targeted clinical formulations for aging populations align with German healthcare reimbursement trends for protein fortification.
- EU Green Deal alignment:Early adoption of regenerative dairy sourcing and renewable energy in drying operations secures preferential positioning with sustainability-scoring food manufacturers.
Industry Challenges
- Filtration technician scarcity:Crossflow membrane and chromatography operation expertise is concentrated among aging workforces at legacy dairy processors.
- Isolate capex intensity:Cold microfiltration and ion exchange systems require substantial capital deployment with extended payback periods relative to concentrate lines.
- Health claim substantiation timelines:EFSA opinion cycles for novel protein-specific claims routinely extend 18-24 months, delaying product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Whey Protein Market |
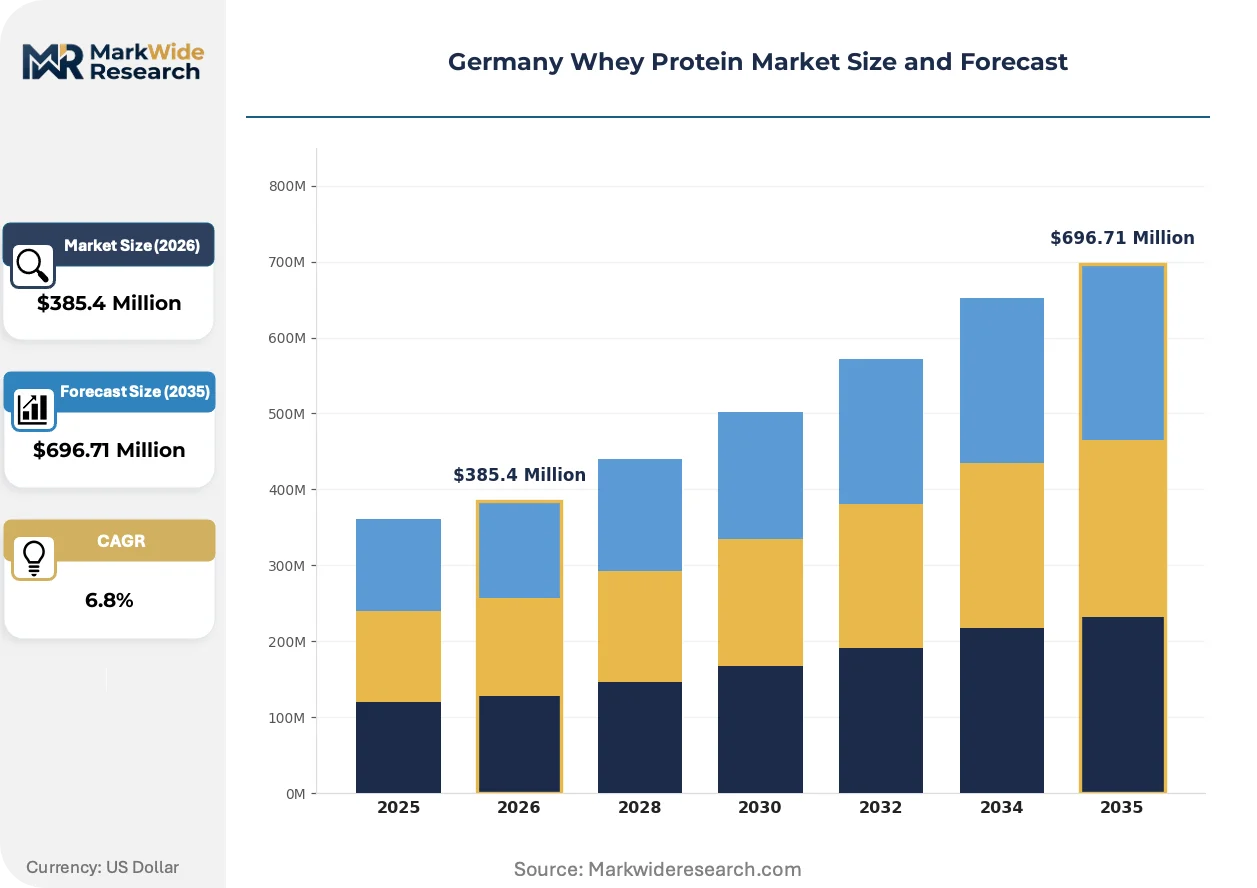
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Native Whey Application: Sports Nutrition, Weight Management, Dietary Supplements, Functional Beverages End User: Athletes, Nutritionists, Fitness Enthusiasts, Wellness Centers Packaging Type: Powder Bags, Sachets, Ready-to-Drink Bottles, Canisters |
| Companies Covered | Lactalis, Hilmar Cheese Company, DMK Deutsches Milchkontor GmbH, Koninklijke DSM N.V., Kerry Group, Arla Foods amba, Fonterra Co-Operative Group Limited, Euroduna Food Ingredients GmbH, Glanbia Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Whey Protein Market Shifts & Advancements
Membrane filtration advances and enzymatic processing are reconfiguring product economics across whey protein grades, while regulatory sustainability mandates and shifting retail formats reshape competitive priorities.
Precision fermentation-derived dairy proteins are digitizing supplier qualification protocols as food manufacturers deploy blockchain-anchored traceability systems. Major functional food processors in southern Germany are piloting real-time carbon accounting integration. This technology is digitizing procurement risk assessment by automating batch-level sustainability verification.
The EU Green Deal's Farm to Fork targets are mandating 25% organic farming conversion and pesticide reduction benchmarks that cascade into dairy feed sourcing requirements. German whey processors must now document regenerative agriculture compliance across cooperative milk pools. Isolate-grade suppliers face the steepest documentation burdens as their premium positioning attracts heightened retailer scrutiny.
Petrol station and convenience retail channels are capturing incremental protein beverage volume as traditional gym and pharmacy distribution saturates. Ready-to-drink formats with extended ambient stability are displacing powder sachets in impulse purchase environments. This shift concentrates in metropolitan corridors where fitness club density overlaps with commuter traffic patterns.
Germany Whey Protein Market Segmentation
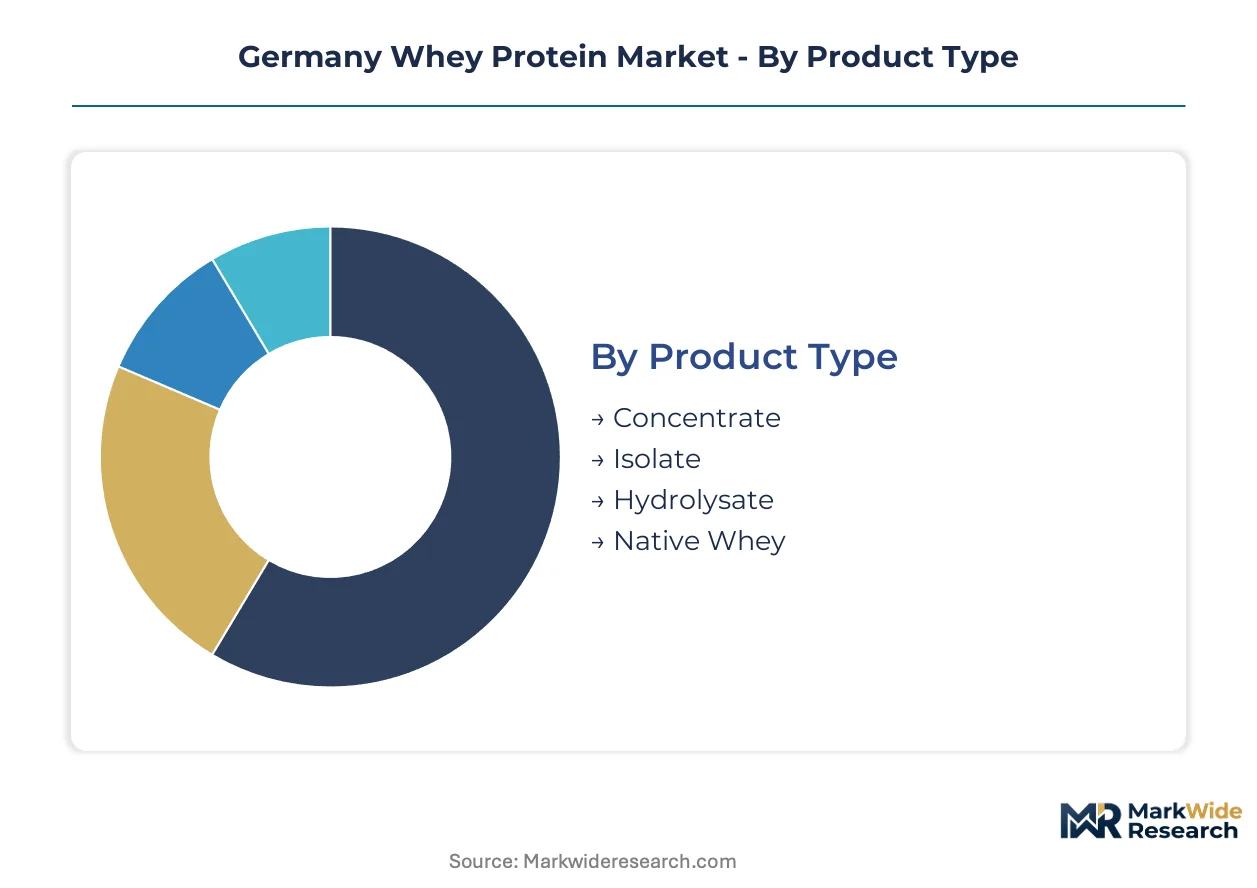
Segmentation in German whey protein reveals how processing intensity, consumption context, and distribution format create distinct margin pools. Each dimension carries specific regulatory and competitive dynamics that shape supplier strategy.
Product Type:
Mature filtration technologies dominate concentrate output, while emerging enzymatic and membrane advances are reconfiguring isolate and hydrolysate economics.
- Concentrate:Protein content ranges from 35% to 80% with retained lactose and milk fat fractions. Bavarian functional food manufacturers absorb the bulk of volume for bakery and dairy fortification applications. DMK Deutsches Milchkontor GmbH anchors supply through its cooperative dairy network across northern Germany.
- Isolate:Cold microfiltration and ion exchange processing achieve 90%+ protein concentration with minimal lactose. North Rhine-Westphalia sports nutrition brands command premium positioning for lactose-free positioning. EFSA health claim substantiation requirements elevate compliance costs but protect domestic processors from lower-standard imports.
- Hydrolysate:Enzymatic pre-digestion yields peptide fractions for rapid absorption. Appeals to amateur athletes with gastrointestinal sensitivity in running and cycling communities.
- Native Whey:Direct extraction from skim milk without cheese manufacturing byproduct status. Commands niche positioning in clean-label medical nutrition formulations.
Concentrate handles the majority of throughput; hydrolysate is expanding most quickly on share as enzymatic processing costs decline.
Application:
Volume concentration tracks fitness club density and retail channel evolution across German metropolitan corridors.
- Sports Nutrition:Powder and bar formats targeting muscle protein synthesis. Amateur athlete expansion beyond bodybuilding into team sports and endurance disciplines drives dispersion throughout Bavaria and North Rhine-Westphalia.
- Weight Management:Satiety-modulating formulations in meal replacement and clinical contexts. German healthcare reimbursement trends for protein fortification support medical nutrition positioning.
- Dietary Supplements:Capsule and tablet formats for convenience-driven consumption. Pharmacy channel saturation is redirecting investment toward petrol station and convenience retail distribution.
- Functional Beverages:Ready-to-drink formats with extended ambient stability. Urban commuter traffic patterns and fitness club proximity create impulse purchase environments in metropolitan centers.
Sports nutrition retains volume leadership; functional beverages are climbing the fastest as ready-to-drink penetration accelerates in convenience channels.
End User:
Customer sophistication spans professional guidance to self-directed consumption, with distinct procurement and formulation requirements.
- Athletes:Competitive and amateur participants seeking performance optimization. Running, cycling, and team sports communities throughout Bavaria and North Rhine-Westphalia represent the core demand concentration.
- Nutritionists:Clinical and sports dietitians specifying protein interventions for sarcopenia and recovery protocols. German healthcare reimbursement structures influence formulation priorities for aging populations.
- Fitness Enthusiasts:Recreational gym attendees prioritizing convenience and taste. Petrol station and convenience retail channels capture incremental volume as traditional gym distribution saturates.
- Wellness Centers:Spa and holistic health facilities integrating protein into broader lifestyle programs. Sustainability-scoring procurement criteria align with EU Green Deal compliance documentation.
Athletes generate the dominant share of volume; wellness centers are gaining share fastest as sustainability credentials reshape B2B procurement.
Packaging Type:
Format economics reflect channel requirements from bulk manufacturing to impulse retail environments.
- Powder Bags:Flexible bulk packaging for manufacturing and institutional use. Functional food processors in southern Germany prioritize logistics efficiency and storage density.
- Sachets:Single-serve portions for trial and travel occasions. Gym and pharmacy channel saturation is compressing growth trajectories.
- Ready-to-Drink Bottles:Shelf-stable formats for convenience retail and petrol station channels. Ambient stability technology enables distribution beyond refrigerated cold chains in metropolitan corridors.
- Canisters:Rigid packaging for home-use powder storage. Sports nutrition brands differentiate through premium tactile and visual design elements.
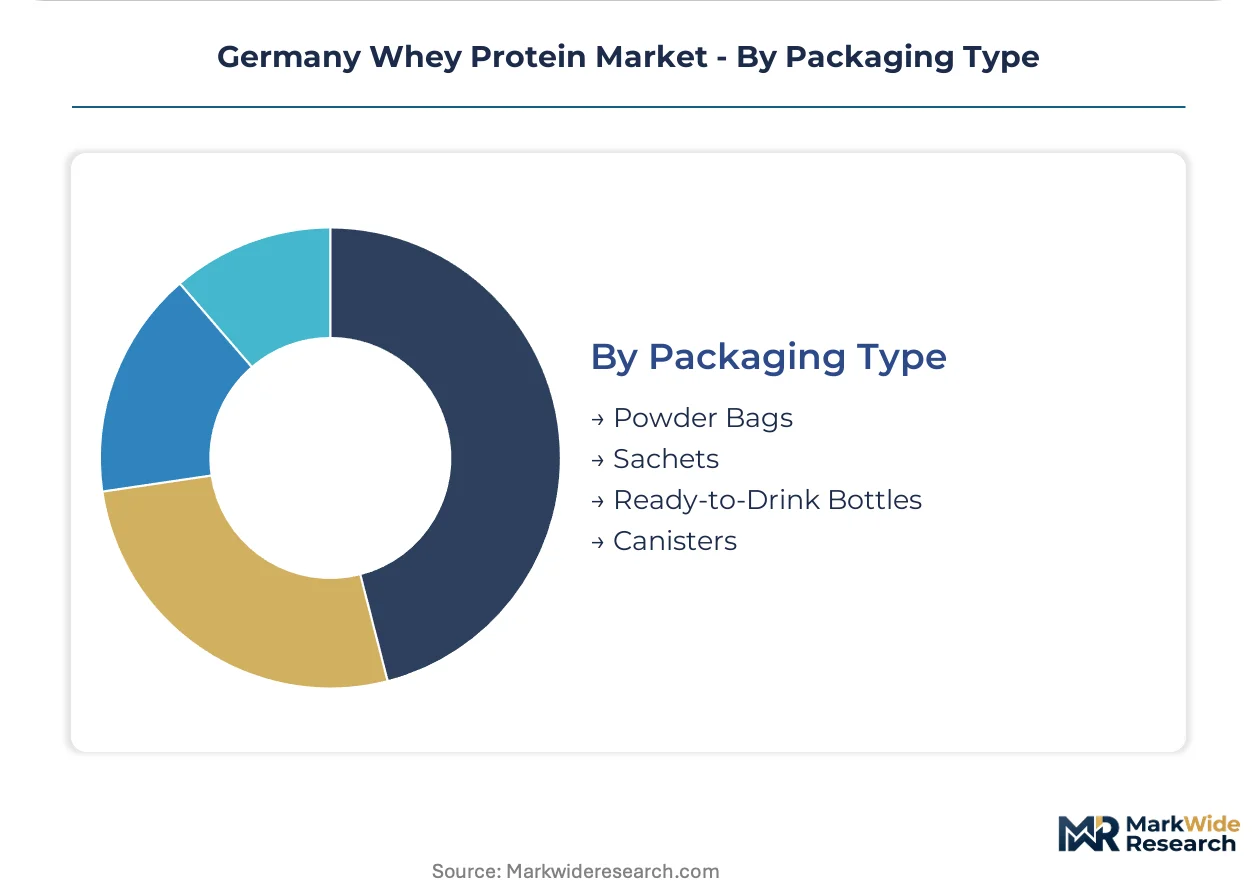
Powder bags move the largest absolute volume; ready-to-drink bottles are expanding most rapidly as channel mix shifts toward impulse retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal nutrition guidelines and regional fitness infrastructure investments are concentrating whey protein demand across German states. The EU Green Deal's carbon accounting requirements are reshaping procurement patterns for dairy-derived ingredients. State-level agricultural cooperatives coordinate milk pool quality standards that cascade into protein fraction specifications.
Bavaria
Amateur athlete communities in Munich and Nuremberg drive sports nutrition consumption beyond traditional bodybuilding circles. The Bavarian State Ministry for Food, Agriculture and Forestry enforces stricter dairy traceability protocols than federal baselines. Ingolstadt's functional food manufacturing cluster hosts multiple toll processing facilities serving mid-sized protein brands.
North Rhine-Westphalia
Fitness club density in Cologne and Düsseldorf creates impulse purchase environments for ready-to-drink protein beverages. The German Federal Office of Consumer Protection and Food Safety maintains regional testing laboratories in Münster for residue screening. Dortmund's logistics hub enables rapid distribution to convenience retail channels across the Rhine-Ruhr metropolitan region.
Baden-Württemberg
Precision fermentation startups in Stuttgart are piloting alternative dairy protein production alongside conventional whey processing. The state's Ministry of Rural Affairs and Consumer Protection coordinates with EFSA on novel food authorization pathways. Freiburg's sustainability-focused food manufacturers prioritize regenerative agriculture credentials in supplier qualification.
Lower Saxony
Dairy cooperative concentration in the north German plain secures upstream milk supply for concentrate production. The German Agricultural Society certifies feed sourcing standards that affect whey protein carbon footprint calculations. Oldenburg's research institutions collaborate with processors on membrane filtration efficiency improvements.
Hesse
Frankfurt's financial infrastructure supports commodity hedging for dairy processors managing milk price volatility. The Hessian Ministry for the Environment, Climate Protection, Agriculture and Consumer Protection implements EU Farm to Fork pesticide reduction targets in regional feed crop production. Darmstadt's technical universities supply filtration engineering talent to adjacent processing facilities.
Germany Whey Protein Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Cooperative-backed dairy processors anchor upstream concentrate supply through captive milk pools. Isolate and hydrolysate specialists command premium positioning via EFSA-aligned health claim substantiation. Asset-light toll processors enable mid-sized brand entry without capital-intensive drying infrastructure. Competitive moves center on sustainability certification acquisition and convenience retail distribution expansion.
Among Germany-based cooperative processors, DMK Deutsches Milchkontor GmbH anchors upstream supply positioning through its northern dairy network. Irish-domiciled Glanbia Plc exemplifies isolate-grade specialization for premium sports nutrition channels. Euroduna Food Ingredients GmbH occupies a regional logistics proximity position serving mid-sized functional food manufacturers in southern Germany. These three represent distinct competitive archetypes: cooperative-integrated supply, premium product specialization, and regional service proximity.
| Leading Market Players |
|---|
| Lactalis |
| Hilmar Cheese Company |
| DMK Deutsches Milchkontor GmbH |
| Koninklijke DSM N.V. |
| Kerry Group |
| Arla Foods amba |
| Fonterra Co-Operative Group Limited |
| Euroduna Food Ingredients GmbH |
| Glanbia Plc |
| Others |
Supply & Pricing Matrix
Overcapacity in concentrate-grade drying facilities across northern Germany compresses spot pricing power while forcing processors toward isolate and hydrolysate specialization to escape margin erosion. This utilization squeeze cascades into cooperative milk pricing negotiations, reshaping how DMK Deutsches Milchkontor GmbH and regional competitors allocate capital between commodity concentrate lines and premium filtration infrastructure.
Pricing Analysis
Certification level creates the primary spread across whey protein tiers, with EFSA-aligned health claim substantiation commanding premium positioning over baseline concentrate grades. Three-tier pricing structure separates isolate hydrolysate blends from standard concentrate from economy-grade feed applications, with feed cost volatility from global grain markets exerting downward pressure on concentrate margins. Amateur athletes in Bavaria demonstrate lowest price sensitivity for gastrointestinal-friendly hydrolysate formats, while functional food manufacturers in North Rhine-Westphalia negotiate aggressively on bulk concentrate offtake.
Supply Chain Analysis
Export-control restrictions on advanced membrane filtration equipment from Germany and the Netherlands constrain capacity expansion timelines for domestic isolate producers. Raw material flows draw from northern German dairy cooperatives, Irish grass-fed milk pools, and French Alpine supply regions, with chromatography resin supply concentrated among Japanese and Swiss specialty chemical suppliers. Single-source vulnerability in ion exchange media creates procurement risk for hydrolysate-grade expansion. Distribution runs through cooperative-owned logistics networks for concentrate bulk, while isolate and hydrolysate ship via temperature-controlled channels to sports nutrition contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German whey protein is emerging from a cyclical trough driven by feed cost normalization and amateur athlete demand dispersion beyond traditional bodybuilding channels.
For Market Incumbents: Entrench isolate-grade positioning through EFSA health claim investment before regulatory substantiation timelines lengthen further. Secure captive milk supply via cooperative equity deepening in Lower Saxony and Schleswig-Holstein to defend against plant protein substitution in mass-market sports nutrition. Cold microfiltration capacity expansion in Bavaria represents the critical defensive lever against toll-processing fragmentation. For New Entrants and Emerging Players: Build out ready-to-drink formulation capabilities targeting petrol station and convenience retail channels in Cologne and Düsseldorf, where impulse purchase infrastructure remains underdeveloped relative to gym distribution saturation. Medical nutrition applications for sarcopenia-targeted clinical formulations offer the most penetrable white space given German healthcare reimbursement tailwinds. Partner with established toll processors to bypass capital-intensive drying infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among isolate-grade specialists with EFSA-substantiated health claim portfolios and long-term sports nutrition brand contracts. Five-to-ten year viability hinges on sustainability credentialing alignment with EU Farm to Fork traceability mandates. Monitor EFSA opinion cycle acceleration on novel protein-specific claims as the primary inflection signal for premium positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Investment | Substantiated muscle maintenance claims protect isolate-grade pricing from commodity concentrate erosion. |
| Regenerative Dairy Sourcing | EU Green Deal compliance documentation secures preferential supplier status with sustainability-scoring food manufacturers. |
| Ready-to-Drink Format Expansion | Ambient-stable beverage development captures impulse volume in underexploited petrol station channels. |
| Toll Processing Partnership | Asset-light manufacturing access enables mid-sized brand entry without captive filtration infrastructure. |
| Membrane Filtration Talent Development | Crossflow and chromatography expertise scarcity threatens expansion timelines for premium-grade output. |
Research Methodology
Initial hypotheses were tested against primary input from dairy cooperative procurement directors, sports nutrition brand formulators, functional food R&D leads, and EFSA regulatory affairs specialists, then refined against secondary validation from BVL residue testing protocols, EU Farm to Fork Strategy documentation, EFSA health claim opinion databases, and German agricultural cooperative financial disclosures. Bottom-up volume modeling triangulated with top-down market sizing across concentrate, isolate, hydrolysate, and native whey grades.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning protein concentration tier, application category, end-user sophistication level, and packaging format. CAGRs derived from growth driver elasticity analysis calibrated against historical milk pool production data and fitness club membership trajectories. Feed cost volatility indices and EFSA opinion cycle timelines served as industry-specific forecast inputs.
Stress conditions across grain and soybean meal price bands, EFSA substantiation timeline extensions, and plant protein substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding amateur athlete demand dispersion and sustainability credentialing adoption curves. Material shifts in EU organic farming conversion mandates or EFSA protein claim substantiation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Plant Sterol Supplements Market
Nutritional Supplements
Older Adults Health Supplements Market
Nutritional Supplements
Nutritional Food and Drink Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Vitamin B12 Market
Nutritional Supplements
Green Food Supplements Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Conjugated Linoleic Acid Market
Nutritional Supplements
North America Vegan Supplements Market
Nutritional Supplements
China Collagen Peptides Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
North America Collagen Supplements Market
Nutritional Supplements
Choline Market
Nutritional Supplements
Throat Lozenges Market