
 Middle-East and Africa Dietary Supplement Market | 2026-2036
Middle-East and Africa Dietary Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Dietary Supplement Market Foresight
Qualified nutritionist and clinical dietitian availability across the Middle-East and Africa is collapsing, forcing manufacturers to build in-house advisory capabilities and digital self-service platforms. Bayer AG leverages its pharmaceutical heritage to anchor premium vitamin lines through pharmacy channels in Saudi Arabia and the UAE. Amway Corporation competes through direct-selling networks that sustain penetration in South African townships and Nigerian cities. Herbalife Nutrition differentiates by occupying the sports nutrition niche with protein powders targeted at gym chains and fitness influencers.
Dietary supplements comprise concentrated sources of vitamins, minerals, botanicals, amino acids, and enzymes delivered in standardized dosages through tablets, capsules, powders, or liquids to supplement nutritional intake and support physiological function. Manufacturing requires precise blending, encapsulation, and stability testing to ensure bioavailability and shelf-life integrity across varied climatic conditions. Vitamins and minerals represent the mature revenue core, with established consumer recognition and pharmacy shelf dominance across the region. Protein powders capture the fastest growth trajectory, driven by fitness culture expansion and athlete end-user demand in Gulf Cooperation Council states. Online retail distribution channels are reshaping margin structures, bypassing traditional pharmacy markups while expanding geographic reach to underserved markets.
Saudi Arabia's Food and Drug Authority and South Africa's Health Products Regulatory Authority enforce divergent registration and labeling standards that fragment market access protocols across the region. The Gulf Standards Organization harmonization efforts and Nigeria's National Agency for Food and Drug Administration and Control import certification requirements further complicate cross-border product flows. Stakeholders must monitor regulatory convergence negotiations and build modular compliance architectures capable of adapting to both Gulf harmonization and sub-Saharan national sovereignty approaches.
Market Dynamics
Pharmacy channel consolidation across Gulf Cooperation Council states is compressing distributor margins while elevating regulatory compliance costs for market entry, forcing manufacturers to bypass wholesale layers through direct-to-consumer digital platforms.
Growth Catalysts
- Sports Nutrition Adoption:Fitness culture expansion across Saudi Arabia, UAE, and Qatar drives protein powder demand through gym chain partnerships and athlete endorsement networks.
- SFDA Registration Harmonization:Saudi Arabia's Food and Drug Authority streamlines import protocols for vitamins and minerals, reducing time-to-market for compliant manufacturers.
- Urban Pharmacy Penetration:Lagos and Abuja corridor expansion by direct-selling networks reaches Nigeria's concentrated middle-class consumer base with personalized nutrition advisory services.
Market Restraints
- Import Certification Fragmentation:NAFDAC requirements in Nigeria diverge from South African Health Products Regulatory Authority standards, forcing redundant testing and label redesign for cross-border shipments.
- Active Ingredient Supply Concentration:Botanical extract sourcing clusters in Indian and Chinese supplier networks expose manufacturers to raw material price volatility and currency fluctuation risk.
- Climate Stability Limitations:Encapsulation technologies face shelf-life degradation challenges across Middle-East and Africa temperature extremes, requiring cold-chain investments that inflate landed costs.
Strategic Opportunities
- Direct-Selling Network Expansion:South African township penetration models transfer to Kenya and Ghana urban corridors, replicating Amway-style distributor training and community-based sales structures.
- Digital Self-Service Platforms:In-house nutritionist chatbots and AI-driven supplement recommendation engines address qualified clinical dietitian scarcity across the region.
- Gulf Standards Organization Convergence:Pending harmonization of technical regulations across Bahrain, Kuwait, Oman, Qatar, Saudi Arabia, and UAE promises unified compliance architecture for vitamins and minerals registration.
Industry Challenges
- Qualified Nutritionist Scarcity:Clinical dietitian training program gaps across Middle-East and Africa force manufacturers to build captive advisory capabilities rather than relying on independent healthcare professional networks.
- Label-Claim Verification Timelines:South African Health Products Regulatory Authority tightening of imported supplement substantiation requirements extends product launch cycles and elevates legal review costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Dietary Supplement Market |
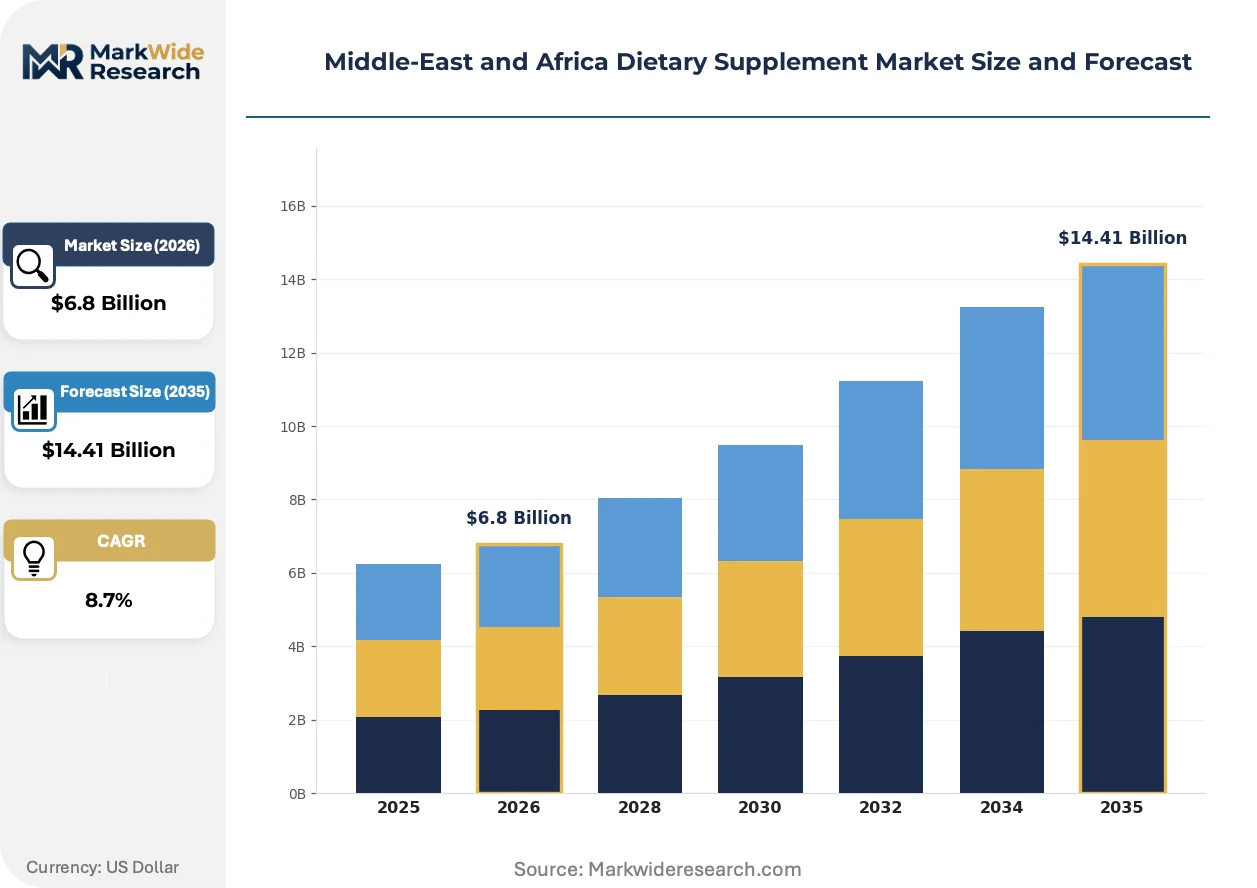
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Protein Powders Form: Tablets, Capsules, Powders, Liquids End User: Health-Conscious Consumers, Athletes, Seniors, Children Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Bayer AG, Amway Corporation, Herbalife Nutrition, Vitabiotics Ltd, GlaxoSmithKline PLC, Nestlé SA, Abbott Laboratories, Pfizer Inc, Aspen Pharmacare Holdings Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Dietary Supplement Market Shifts & Advancements
Digital distribution infrastructure is compressing traditional pharmacy markup structures while enabling geographic reach expansion to previously underserved sub-Saharan markets through mobile-first purchasing platforms.
Microencapsulation technology using lipid-based delivery systems is displacing conventional tablet and capsule formats in the protein powder and sports nutrition segment. Gym chains and fitness influencers across Dubai, Riyadh, and Doha adopt these formats for enhanced bioavailability claims. This displacement is fragmenting manufacturing scale advantages as smaller batch production becomes economically viable.
South African Health Products Regulatory Authority enforcement of amended complementary medicines labeling standards tightens health claim substantiation requirements for imported botanical supplements. Manufacturers must submit clinical evidence packages or reformulate marketing language. Vitamin and mineral importers bear the heaviest compliance burden as they hold the largest pharmacy shelf presence.
Subscription-based replenishment models now capture recurring revenue from chronic condition consumers in Nigeria's Lagos corridor and South Africa's Johannesburg metropolitan area. Traditional pharmacy counter sales face disintermediation as direct-to-consumer platforms offer price transparency and automated delivery scheduling. This behavioral shift concentrates most visibly among diabetes and cardiovascular management supplement users seeking predictable supply continuity.
Middle-East and Africa Dietary Supplement Market Segmentation
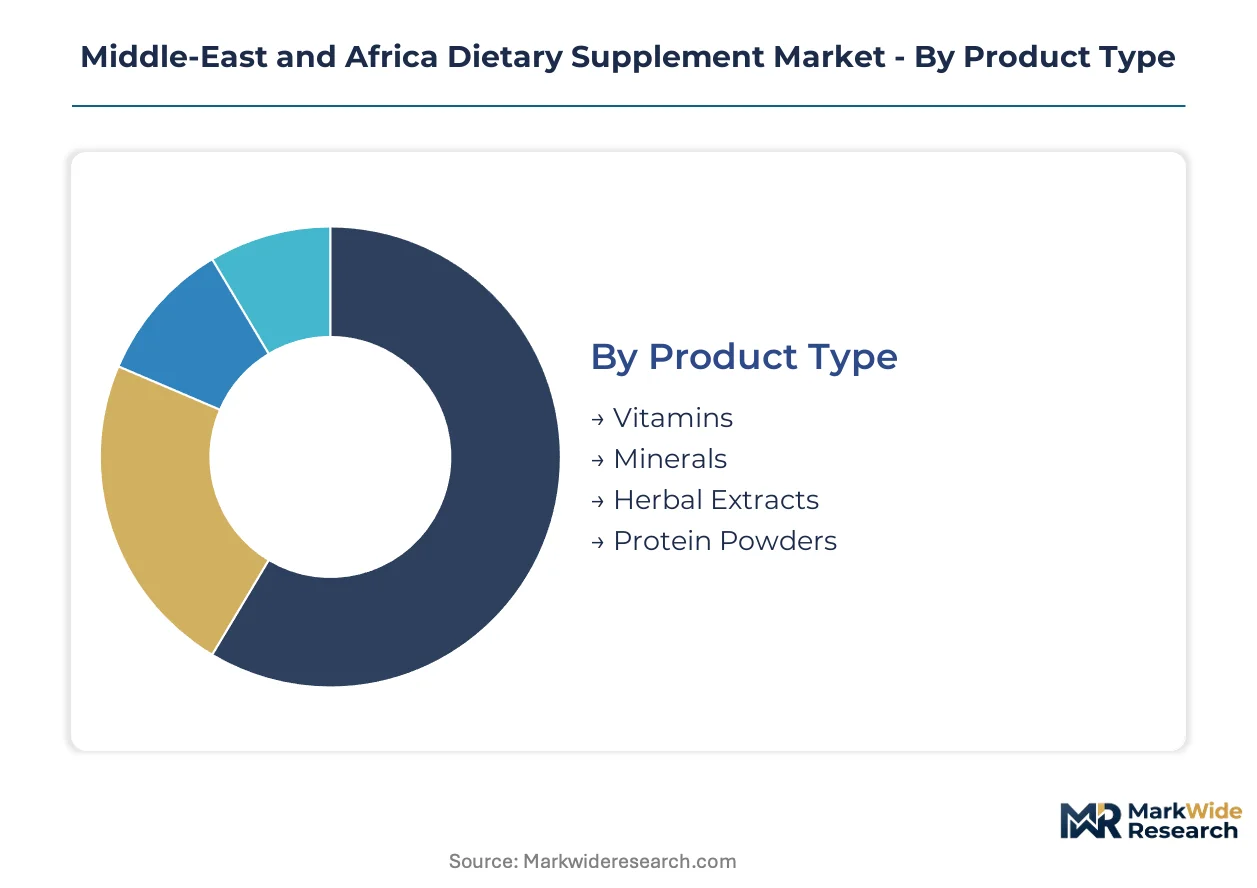
Regulatory divergence across Middle-East and Africa jurisdictions fragments product registration pathways, forcing manufacturers to architect segment-specific compliance strategies. Shelf-life stability requirements vary dramatically between Gulf Cooperation Council humidity-controlled environments and sub-Saharan ambient temperature extremes, driving form factor selection and packaging investment decisions.
Product Type:
SFDA registration protocols in Saudi Arabia and NAFDAC certification requirements in Nigeria impose divergent substantiation standards for active ingredient claims, compelling manufacturers to maintain parallel documentation systems.
- Vitamins:Synthetic and natural vitamin compounds delivered in standardized IU concentrations. Pharmacy chains across Riyadh and Jeddah concentrate demand for prenatal and immune-support formulations, though SFDA label-claim verification timelines extend launch cycles. Vitamins handle the majority of throughput; Protein Powders is the fastest mover on share.
- Minerals:Chelated and inorganic mineral salts including calcium, magnesium, zinc, and iron compounds. Direct-selling networks in Lagos and Abuja penetrate Nigeria's urban middle-class with anemia-prevention and bone-health SKUs, leveraging personalized advisory to overcome qualified nutritionist scarcity.
- Herbal Extracts:Botanical concentrates from ashwagandha, turmeric, and moringa face South African Health Products Regulatory Authority substantiation requirements for traditional medicine claims.
- Protein Powders:Whey, casein, and plant-derived protein isolates targeting fitness culture expansion across Dubai, Doha, and Riyadh gym chains.
Cost tier differentiation separates premium pharmaceutical-grade vitamins from economy-positioned mineral complexes, with herbal extracts occupying a volatile middle tier dependent on raw material sourcing stability.
Form:
Encapsulation technology selection directly responds to climate stability limitations across regional temperature extremes, with liquid formats requiring cold-chain investments that inflate landed costs in sub-Saharan corridors.
- Tablets:Compressed powder matrices with disintegrant and binder systems enabling high-speed production. Saudi Arabia's pharmacy channel consolidation elevates tablet shelf presence for chronic-condition management SKUs, though margin compression forces manufacturers toward direct-to-consumer bypass strategies.
- Capsules:Gelatin and vegetable-based shells protecting moisture-sensitive actives from Gulf humidity exposure. Johannesburg and Cape Town metropolitan areas show concentration for senior-targeted capsule formulations, driven by swallowability preferences and subscription replenishment model adoption.
- Powders:Bulk protein and pre-mix formats dominate sports nutrition with flexible dosing and flavor customization.
- Liquids:Suspension and solution formats for pediatric and geriatric populations with swallowing difficulties.
Tablets maintain volume leadership through manufacturing scale and pharmacy channel alignment; powders are climbing the fastest as gym chain partnerships proliferate.
End User:
Application-specific formulation requirements diverge sharply between performance-optimization and deficiency-correction use cases, with dosage precision and palatability engineering commanding distinct R&D investment profiles.
- Health-Conscious Consumers:Preventive wellness seekers purchasing multivitamin and general wellness formulations. Kenya and Ghana urban corridors replicate South African direct-selling penetration models, with community-based distributor networks overcoming pharmacy access limitations.
- Athletes:Protein powder and ergogenic aid demand concentrates in Dubai, Riyadh, and Doha fitness ecosystems, where gym chain partnerships and influencer endorsement networks drive brand preference formation.
- Seniors:Bone health, cognitive support, and cardiovascular management formulations face swallowability and drug-interaction advisory requirements.
- Children:Gummy and liquid formats with palatability engineering and precise micro-dosing for developmental nutrition support.
Health-Conscious Consumers represent the largest addressable base; Athletes are expanding most quickly through fitness culture diffusion.
Distribution Channel:
Margin structure erosion from digital platform proliferation is fragmenting traditional pharmacy markup architectures, with geographic reach extension to previously underserved markets enabled by mobile-first purchasing infrastructure.
- Online Retail:Direct-to-consumer platforms bypassing wholesale markups with automated replenishment and price transparency. Nigeria's Lagos corridor demonstrates subscription model concentration for chronic-condition supplement users, disintermediating traditional pharmacy counter sales.
- Pharmacies:Regulated channel with pharmacist advisory access and SFDA import protocol alignment. Gulf Cooperation Council consolidation elevates compliance costs while compressing distributor margins, forcing manufacturer investment in digital self-service alternatives.
- Supermarkets:Mass-market vitamin and mineral placement with impulse purchase dynamics and limited advisory support.
- Specialty Stores:Sports nutrition and premium wellness positioning with trained staff and experiential merchandising.
Pharmacies retain regulatory legitimacy and volume throughput; Online Retail is gaining share fastest through margin compression and reach extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Food and Drug Authority anchors regulatory harmonization efforts across Gulf Cooperation Council states, while South Africa's Health Products Regulatory Authority enforces divergent standards that fragment sub-Saharan market access protocols.
Saudi Arabia
Fitness culture expansion and pharmacy channel consolidation drive protein powder demand through Riyadh and Jeddah gym chains. SFDA registration protocols streamline import documentation for vitamins and minerals, reducing time-to-market for compliant manufacturers. The Eastern Province industrial corridor hosts cold-chain logistics investments addressing encapsulation stability challenges.
United Arab Emirates
Dubai's fitness influencer networks and Doha-connected gym chains accelerate sports nutrition adoption among professional athletes. MOHAP standards align with Gulf Standards Organization harmonization efforts for technical regulation convergence. Abu Dhabi pharmacy consolidation elevates compliance costs while compressing traditional distributor margins.
South Africa
Direct-selling network penetration in Johannesburg and Cape Town townships sustains mineral complex demand through personalized advisory services. Health Products Regulatory Authority tightening of label-claim verification extends botanical supplement launch cycles. The Western Cape hosts microencapsulation technology investments targeting senior-targeted capsule formulations.
Nigeria
Urban pharmacy expansion in Lagos and Abuja corridors concentrates multivitamin demand among middle-class consumers. NAFDAC import certification requirements diverge from Gulf standards, forcing redundant testing for cross-border shipments. Direct-selling networks replicate South African community-based distributor models in Ibadan and Port Harcourt.
Qatar
Athlete endorsement networks and luxury gym chain partnerships drive premium protein powder positioning in Doha. National food safety authority regulations track Gulf Standards Organization harmonization timelines for unified compliance architecture. The Lusail development zone attracts sports nutrition distribution infrastructure investments.
Middle-East and Africa Dietary Supplement Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical heritage companies leveraging pharmacy channel dominance against direct-selling networks and sports nutrition pure-plays. The structure compresses distributor margins through Gulf pharmacy consolidation while elevating digital platform competition. Three archetypes prevail: pharmaceutical conglomerates with vitamin lines, direct-selling networks with community penetration models, and fitness-focused protein powder specialists. Competitive moves center on direct-to-consumer platform bypass strategies and Gulf Standards Organization pre-positioning for harmonized compliance.
Within the pharmaceutical heritage tier, Bayer AG and GlaxoSmithKline PLC occupy positions leveraging pharmacy channel legitimacy across Saudi Arabia and the UAE. Among direct-selling specialists, Amway Corporation exemplifies community-based distributor training models transferable across South African and Nigerian urban corridors. Herbalife Nutrition anchors the sports nutrition archetype through gym chain partnerships and fitness influencer networks in Dubai, Riyadh, and Doha.
| Leading Market Players |
|---|
| Bayer AG |
| Amway Corporation |
| Herbalife Nutrition |
| Vitabiotics Ltd |
| GlaxoSmithKline PLC |
| Nestlé SA |
| Abbott Laboratories |
| Pfizer Inc |
| Aspen Pharmacare Holdings Ltd |
| Others |
Supply & Pricing Matrix
High-volume encapsulation capacity utilization in Indian and Chinese contract manufacturing clusters concentrates cost leverage among a handful of suppliers, compressing price floors for finished vitamin and mineral tablets while elevating landed premiums for cold-chain-dependent liquid formats across sub-Saharan corridors.
Pricing Analysis
Gulf Cooperation Council pharmacy markups diverge sharply from Nigerian direct-selling network pricing, with Riyadh and Dubai channels commanding premium positioning for pharmaceutical-grade vitamins while Lagos corridor subscription models undercut per-unit economics through automated replenishment. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-registered pharmacy SKUs from supermarket impulse placements and township direct-sales inventory. Pricing pressure stems from digital platform proliferation bypassing wholesale layers. Chronic-condition subscribers in Johannesburg metropolitan areas show lowest price sensitivity; economy mineral complex buyers in Nigerian secondary cities exhibit highest elasticity.
Supply Chain Analysis
Strait of Hormuz transit underwrites Gulf-bound botanical extract shipments from Indian supplier networks, exposing manufacturers to geopolitical disruption risk while Dubai's Jebel Ali free zone offers tariff-advantaged redistribution staging. Active ingredient sourcing concentrates in India, China, and select European phytochemical specialists. Whey protein isolate and plant-derived amino acid premixes draw from North American and South American dairy processing clusters. Single-source vulnerability pervades specialized encapsulation equipment procurement. Distribution runs through pharmacy channel consolidation in Saudi Arabia and UAE, with direct-to-consumer platforms fragmenting downstream access in Nigeria and South Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fitness culture penetration across Gulf Cooperation Council states signals early-cycle expansion, with gym chain partnerships and athlete endorsement networks driving protein powder adoption faster than traditional vitamin maturation curves.
For Market Incumbents: Compound pharmacy channel legitimacy through SFDA pre-registration investments that extend compliance moats against direct-selling insurgents. Deepen backward integration into botanical extract sourcing to offset Indian and Chinese supplier price volatility. Defend capsule format margins in Johannesburg and Cape Town senior segments through microencapsulation technology differentiation.
For New Entrants and Emerging Players: Anchor in Kenya and Ghana urban corridors where direct-selling network density remains below South African and Nigerian saturation levels. Target protein powder white space in secondary Gulf cities beyond Dubai-Riyadh-Doha fitness epicenters. Deploy mobile-first subscription platforms with automated replenishment to bypass pharmacy markup structures.
For Investors and Strategic Acquirers: Sports nutrition pure-plays with established gym chain partnerships and influencer endorsement networks offer the clearest acquisition target archetype for Gulf market exposure. Long-term viability hinges on Gulf Standards Organization harmonization completion and digital platform scalability across sub-Saharan mobile infrastructure. Watch NAFDAC-SFDA regulatory convergence negotiations as the inflection signal for cross-border product flow rationalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Bypasses pharmacy markup compression in Saudi Arabia and UAE while extending geographic reach to underserved sub-Saharan markets. |
| SFDA Pre-Registration Investment | Accelerates time-to-market for vitamin and mineral imports while building compliance barriers against non-pharmaceutical heritage competitors. |
| Gym Chain Partnership Expansion | Secures protein powder shelf presence in Dubai, Riyadh, and Doha fitness ecosystems with athlete endorsement amplification. |
| Microencapsulation Technology Adoption | Addresses climate stability limitations across Middle-East and Africa temperature extremes with lipid-based delivery system differentiation. |
| Direct-Selling Network Replication | Transfers South African township penetration models to Kenyan and Ghanaian urban corridors with community-based distributor training. |
Research Methodology
A spread of perspectives from regulatory affairs specialists at Gulf national food safety authorities, pharmacy chain procurement directors, direct-selling network regional managers, and sports nutrition brand managers converged on the working assumptions driving this analysis. Primary interview intelligence combined with secondary validation from SFDA registration databases, NAFDAC import certification records, Gulf Standards Organization technical regulation drafts, and regional trade flow customs data. Bottom-up demand modeling across product type, form, end user, and distribution channel segments triangulated against top-down market sizing from pharmaceutical industry association reports.
Segmentation dimensions modeled include product type tier, encapsulation form factor, end-user application, and distribution channel structure across the projection horizon. CAGRs were derived from trend extrapolation anchored in documented adoption trajectories for fitness culture expansion and digital platform penetration. Forecast inputs incorporated SFDA registration timeline improvements, NAFDAC certification backlog projections, and cold-chain infrastructure investment announcements.
Material uncertainties — regulatory divergence persistence, botanical extract supply disruption, and currency fluctuation in raw material sourcing corridors — sit outside the modeled envelope. Forecasts reflect documented assumptions about Gulf Standards Organization harmonization completion and mobile commerce adoption curves. Practitioners should keep alternative scenarios live as SFDA-NAFDAC bilateral negotiations and Indian supplier network consolidation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Asia-Pacific Digestive Health Supplements Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
Digestive Health Supplements Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
North and South America Mineral Supplement Tablets Market
Nutritional Supplements
Global Adaptogens Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Mineral Supplements Market
Nutritional Supplements
Global Digestive Enzymes Market
Nutritional Supplements
Whey Hydrolysates Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Europe Botanical Supplements Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
Vegan Protein Supplements Market