
 Europe Meal Replacement Products Market | 2026-2036
Europe Meal Replacement Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Meal Replacement Products Market Foresight
Germany is reconfiguring its position as the primary production hub for meal replacement manufacturing across the continent. yfood Labs GmbH leverages its Munich-based operations to dominate the ready-to-drink segment with precision-engineered liquid nutrition. Abbott Laboratories anchors its European portfolio through science-backed clinical formulations that sustain trust among healthcare-adjacent consumers. Huel Inc. competes on plant-based powder economics, extending its direct-to-consumer model into continental retail partnerships.
Europe meal replacement products encompass nutritionally complete formulations designed to substitute conventional meals through controlled macronutrient profiles, typically delivering 400-600 kcal per serving with standardized protein, carbohydrate, fat, and micronutrient ratios. These products serve industrial purposes ranging from clinical weight management protocols to convenience-driven consumer nutrition, manufactured through spray-drying, extrusion, or aseptic liquid processing depending on delivery format. The ready-to-drink category leads volume due to on-the-go consumption patterns among busy professionals, while powder formulations retain margin advantages through lower logistics costs and longer shelf stability. Vegan formulation options represent the fastest-expanding structural segment as EFSA-aligned clean-label requirements reshape ingredient sourcing across the supply base.
The European Food Safety Authority and EU Nutrition and Health Claims Regulation govern permissible health statements, directly constraining how brands communicate satiety and metabolic benefits to consumers. EMA-adjacent borderline product classifications create compliance complexity for formulations positioned between food supplements and medical nutrition, particularly affecting Abbott Laboratories' clinical-adjacent positioning. Stakeholders must monitor pending EU packaging waste directives and evolving green taxonomy alignment for protein sourcing claims, as these frameworks will determine which suppliers retain shelf access across major retail banners.
Market Dynamics
EFSA's tightening grip on permissible health claims under the EU Nutrition and Health Claims Regulation is forcing wholesale reformulation across European meal replacement portfolios. Brands must now substantiate satiety and metabolic benefit statements through clinical validation, compressing marketing flexibility while accelerating R&D investment cycles.
Growth Catalysts
- EU Green Deal protein sourcing mandates:The EU Green Deal's sustainable protein requirements are redirecting supply chains toward regenerative agriculture and alternative protein inputs. This regulatory pressure is compressing carbon footprints across ingredient procurement.
- Fitness enthusiast demand concentration:Urban professionals in Berlin, Munich, and Amsterdam are integrating ready-to-drink formulations into pre- and post-workout routines. Gym chains and boutique fitness studios are expanding shelf space for liquid nutrition.
- Clean-label ingredient transparency:EFSA-aligned disclosure requirements are eliminating artificial sweeteners and synthetic additives from premium formulations. Consumer scrutiny of supply chain provenance is accelerating reformulation timelines.
Market Restraints
- Pea protein supply concentration:European pea protein processing capacity concentrates in northern France and the Netherlands, creating input cost volatility when harvest yields fluctuate. Alternative legume proteins require sensory re-engineering that extends development cycles.
- EMA borderline classification friction:Formulations positioned between food supplements and medical nutrition face protracted regulatory review. Abbott Laboratories' clinical-adjacent products encounter compliance complexity that delays market entry.
- Fresh prepared meal substitution:Refrigerated convenience meals from established foodservice operators compete directly on taste and perceived freshness. Meal replacement powders require consumer education on preparation and nutritional equivalence.
Strategic Opportunities
- Poland and Romania underpenetration:Eastern European markets exhibit low per-capita meal replacement consumption relative to Germany and the UK. Localized flavor profiles and price-positioned formats could capture emerging professional demographics in Warsaw and Bucharest.
- Pharmacy channel expansion:Weight management protocols through community pharmacies offer clinical credibility that conventional retail lacks. Pharmacist recommendation networks provide trusted distribution for science-backed formulations.
- AI-driven personalization convergence:Machine learning platforms analyzing microbiome data and metabolic markers enable bespoke macronutrient profiling. Subscription models integrating wearable glucose monitors are creating stickier consumer relationships.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning sensory science, nutritional biochemistry, and clean-label processing commands premium compensation. Startups struggle to recruit against established food and beverage conglomerates.
- Novel Food authorization timelines:EFSA Novel Food applications for emerging protein sources and bioactive compounds extend 18-24 months. Pipeline products face revenue recognition delays that strain venture-backed operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Meal Replacement Products Market |
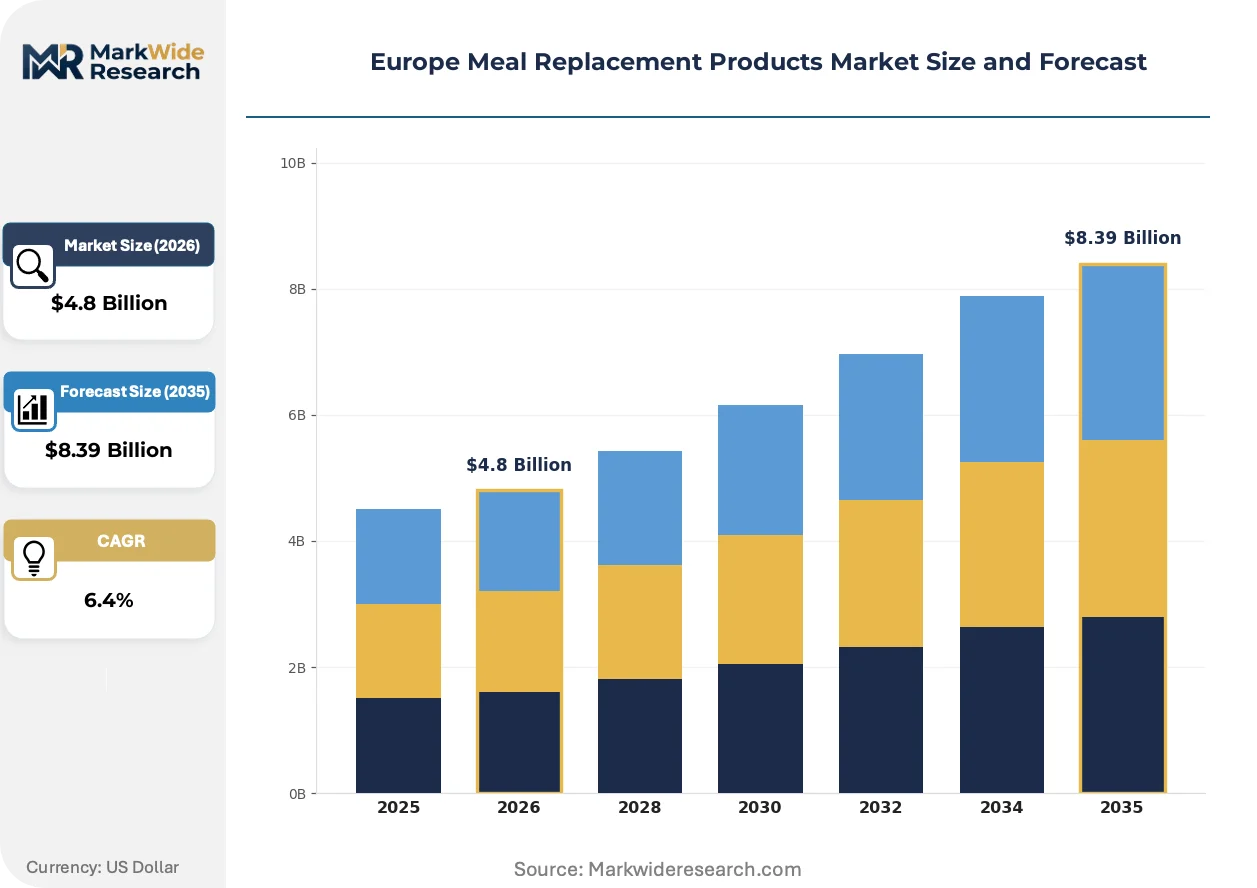
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shakes, Bars, Powder, Ready-to-Drink Target Audience: Fitness Enthusiasts, Weight Watchers, Busy Professionals, Athletes Formulation: Protein-Rich, Low-Carb, Organic, Vegan Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores |
| Companies Covered | yfood Labs GmbH, Herbalife International of America Inc., Abbott Laboratories, Ambronite Oy, Amway Corp., Nestle SA, Glanbia plc, Peeroton GmbH, Huel Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Meal Replacement Products Market Shifts & Advancements
Digital twin technology is virtualizing product development pipelines across European meal replacement manufacturing. Virtual formulation modeling compresses prototype iteration cycles while reducing physical waste from failed batches.
High-pressure processing is virtualizing aseptic liquid manufacturing by eliminating thermal degradation of heat-sensitive vitamins and bioactive peptides. Premium ready-to-drink brands in Germany and the Netherlands are adopting cold-chain HPP to extend clean-label shelf stability without synthetic preservatives. This technology is virtualizing the trade-off between convenience and nutritional integrity that previously favored powders.
EFSA's 2024 guidance on glycemic response claims is tightening evidentiary standards for blood glucose management statements. Manufacturers must now conduct human intervention studies with standardized protocols to support marketing language. The ready-to-drink segment faces the steepest compliance burden as consumers increasingly scrutinize postprandial metabolic impact.
Subscription direct-to-consumer models are displacing conventional retail stocking patterns among urban professional cohorts. Berlin and London-based consumers increasingly expect personalized delivery frequencies and flavor rotations. This channel shift is most pronounced among plant-based powder buyers who prioritize convenience over immediate availability.
Europe Meal Replacement Products Market Segmentation
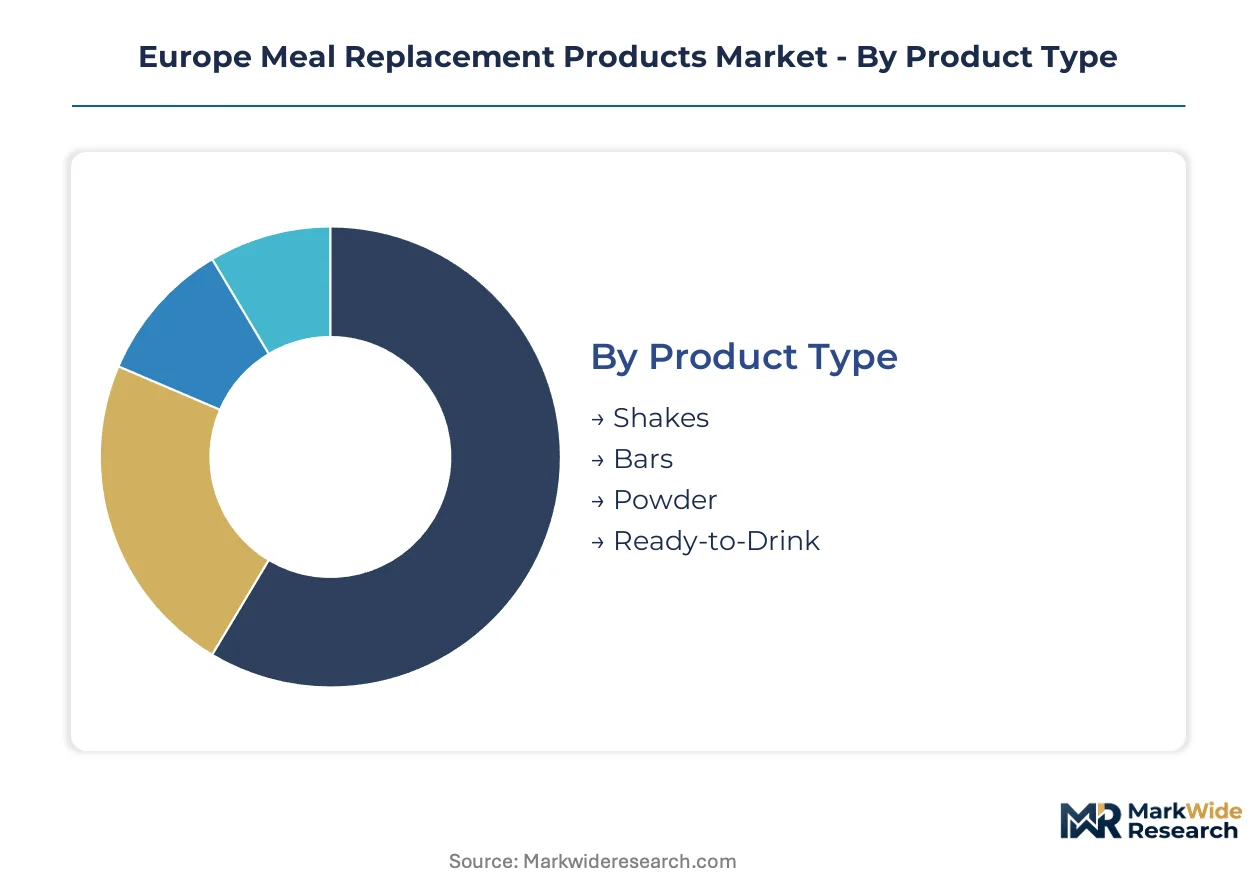
Segmentation in Europe's meal replacement market reveals how regulatory pressure and consumption context reshape product development priorities. Manufacturers must align format, formulation, and channel strategy with distinct user motivations ranging from clinical weight management to post-workout recovery.
Product Type:
Mature liquid formats coexist with emerging solid alternatives as convenience preferences fragment across European urban centers.
- Shakes:Blended or pre-mixed formulations delivering 400-600 kcal with standardized macronutrient ratios. Demand concentrates in German gym chains and Dutch corporate cafeterias where consumers prioritize minimal preparation friction.
- Bars:Extruded solid formats combining protein isolates with binding agents for shelf-stable portability. Weight Watchers in France and Italy favor bars for discrete workplace consumption without refrigeration dependency.
- Powder:Spray-dried concentrates requiring reconstitution with water or milk alternatives.
- Ready-to-Drink:Aseptically processed liquid nutrition in single-serve packaging.
Ready-to-Drink retains volume leadership; Powder holds the steepest expansion curve.
Target Audience:
Professional lifestyle constraints drive the steepest demand concentration among time-compressed urban demographics.
- Fitness Enthusiasts:Consumers integrating structured exercise with precise macronutrient timing. Berlin and Amsterdam boutique studios stock pre-workout and recovery formulations, with EFSA-compliant protein claims accelerating brand switching toward validated products.
- Busy Professionals:Urban knowledge workers substituting conventional meals during compressed schedules. Munich's banking and tech sectors sustain per-capita consumption rates exceeding other European cities through subscription direct-to-consumer models.
- Weight Watchers:Consumers pursuing clinically supervised or self-directed caloric restriction.
- Athletes:Competitive and recreational performers with elevated protein requirements.
Busy Professionals dominate absolute volume; Fitness Enthusiasts display the most rapid adoption velocity.
Formulation:
Clean-label requirements under EU Nutrition and Health Claims Regulation are eliminating artificial inputs from premium positioning tiers.
- Protein-Rich:Formulations exceeding 20g protein per serving through whey, casein, or alternative isolates. German consumers prioritize leucine content for muscle protein synthesis, driving specification requirements that compress margin on commodity formulations.
- Vegan:Plant-derived protein combinations from pea, rice, and fava bean sources. Netherlands-based processing capacity constraints create supply volatility that extends EFSA Novel Food authorization timelines for emerging legume inputs.
- Low-Carb:Ketogenic-aligned macronutrient profiles restricting carbohydrate below 10g per serving.
- Organic:EU Organic Regulation-certified ingredient sourcing with full supply chain traceability.
Protein-Rich maintains revenue concentration; Vegan climbs fastest as EFSA-aligned sourcing requirements reshape procurement.
Distribution Channel:
Channel selection determines compliance burden and consumer trust positioning across the regulatory landscape.
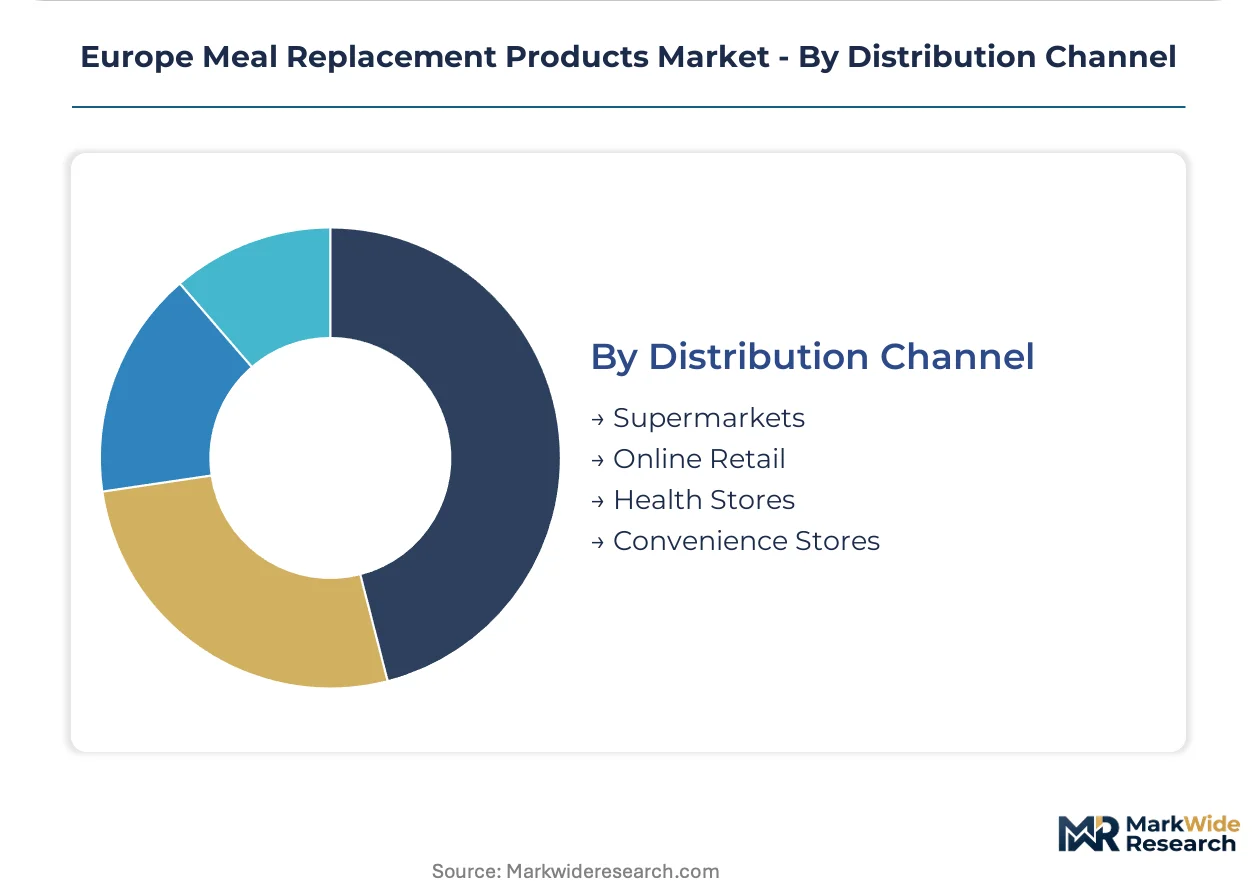
- Online Retail:Direct-to-consumer platforms enabling subscription personalization and flavor rotation. UK and German consumers increasingly expect AI-driven recommendation engines that integrate wearable metabolic data for bespoke macronutrient profiling.
- Supermarkets:Mass-market retail banners requiring standardized packaging and pan-European logistics. EFSA health claim substantiation becomes mandatory for shelf placement as major chains implement clean-label procurement policies.
- Health Stores:Specialized retailers emphasizing clinical credibility and practitioner recommendation.
- Convenience Stores:Impulse-oriented small-format retail with limited SKU depth.
Supermarkets anchor volume throughput; Online Retail gains share fastest through subscription stickiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient processing and formulation R&D concentrate in Germany, the Netherlands, and France, with northern European supply chains dominating pea protein extraction and spray-drying capacity. EFSA regulatory enforcement varies in intensity across member states, creating compliance arbitrage opportunities for brands optimizing market entry sequencing.
Germany
Munich and Berlin sustain Europe's highest per-capita meal replacement consumption through fitness-integrated lifestyles and banking-sector work compression. The German Federal Ministry of Food and Agriculture enforces strict Novel Food documentation requirements that extend authorization timelines for emerging protein sources. Bavaria hosts yfood Labs GmbH's precision-engineered liquid nutrition operations, serving as the continent's primary ready-to-drink manufacturing cluster.
United Kingdom
London's direct-to-consumer subscription density exceeds continental averages, with urban professionals prioritizing personalized delivery frequencies over retail immediacy. The UK Food Standards Agency maintains post-Brexit alignment with EFSA health claim substantiation standards while operating independent enforcement protocols. Plant-based powder buyers in Greater Manchester and Birmingham increasingly integrate wearable glucose monitors into AI-driven macronutrient profiling services.
Netherlands
Amsterdam's boutique fitness studios anchor pre-workout and recovery formulation demand, with gym chains expanding dedicated shelf space for liquid nutrition. The Dutch Food and Consumer Product Safety Authority coordinates closely with EFSA on clean-label ingredient transparency mandates. Northern Dutch processing facilities concentrate European pea protein extraction capacity, creating input cost volatility when regional harvest yields fluctuate.
France
Paris and Lyon exhibit strong bar-format preference for discrete workplace consumption without refrigeration dependency. ANSM maintains borderline product classification scrutiny for formulations positioned between food supplements and medical nutrition. Weight management protocols through community pharmacies in Île-de-France offer clinical credibility that conventional retail channels lack.
Poland
Warsaw's emerging professional demographic shows underpenetrated meal replacement consumption relative to western European benchmarks. The Polish Chief Sanitary Inspectorate implements EU Nutrition and Health Claims Regulation with evolving interpretation consistency. Localized flavor profiles and price-positioned formats targeting Kraków's corporate workforce present first-mover expansion opportunities.
Europe Meal Replacement Products Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The European meal replacement sector exhibits moderate consolidation, with science-backed clinical formulations and plant-based direct-to-consumer models occupying distinct competitive strata. Three archetypes dominate: precision-engineered liquid nutrition platforms, clinical-adjacent medical nutrition specialists, and plant-based powder economics disruptors. Capacity expansion through automated aseptic processing and strategic retail partnerships constitute the primary competitive moves reshaping shelf access.
Among German-origin platform operators, yfood Labs GmbH exemplifies the ready-to-drink manufacturing archetype through its Munich-based precision engineering. Abbott Laboratories occupies a position within the clinical credibility tier, leveraging science-backed formulations that sustain trust among healthcare-adjacent consumers. Huel Inc. represents the plant-based powder economics model, extending direct-to-consumer subscription infrastructure into continental retail partnerships.
| Leading Market Players |
|---|
| yfood Labs GmbH |
| Herbalife International of America Inc. |
| Abbott Laboratories |
| Ambronite Oy |
| Amway Corp. |
| Nestle SA |
| Glanbia plc |
| Peeroton GmbH |
| Huel Inc. |
| Others |
Supply & Pricing Matrix
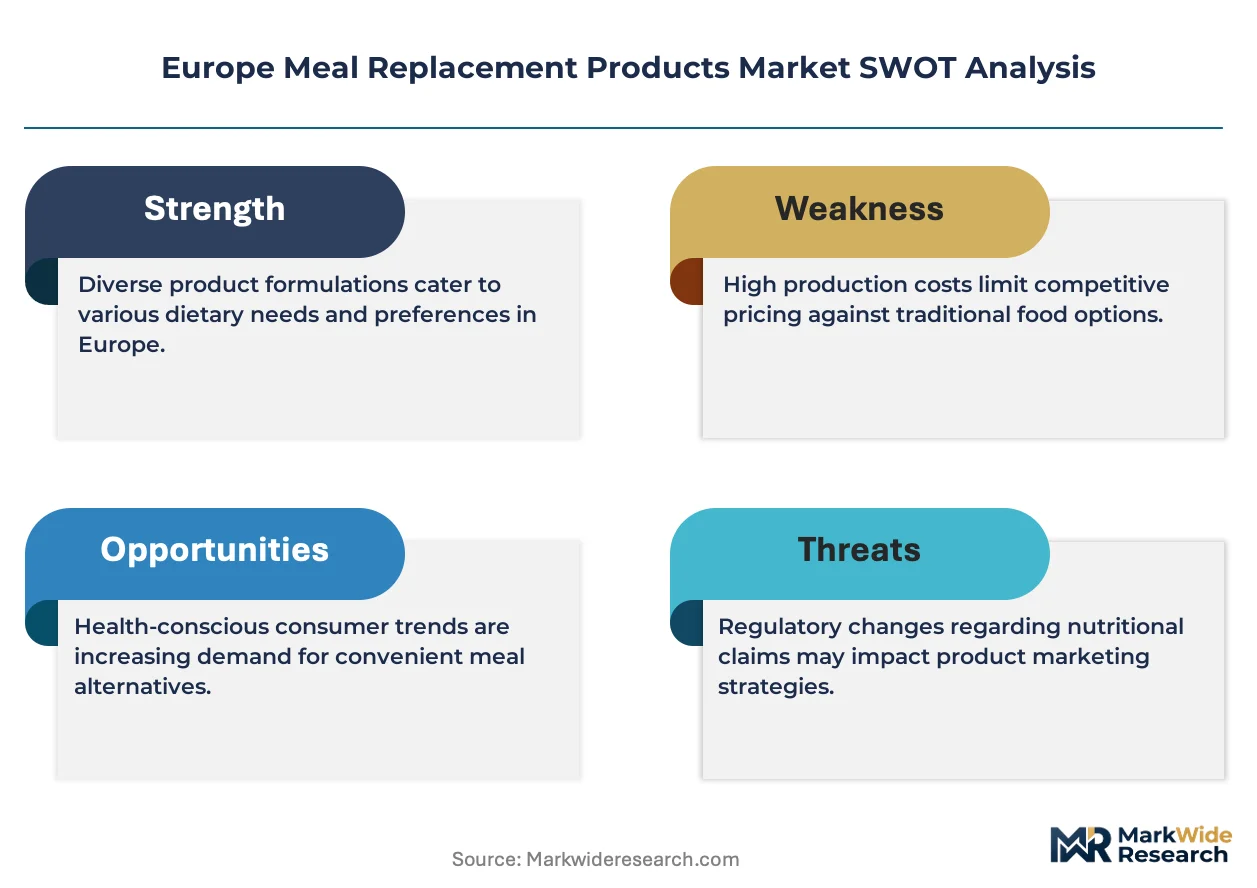
Pea protein extraction capacity in northern France and the Netherlands concentrates upstream margin capture, with spray-drying facilities in Bavaria and Gelderland provinces anchoring the continent's powder formulation economics. This geographic clustering allows processors to command premium input pricing during harvest volatility, while finished goods manufacturers absorb cost compression through private-label partnerships and subscription contract structures.
Pricing Analysis
EFSA's EU Nutrition and Health Claims Regulation dictates the pricing tier structure across European meal replacement portfolios, forcing clinical validation investments that stratify offerings across premium validated, standard compliant, and economy basic levels. Price differentiation hinges on certification grade for clean-label positioning and volume scale in direct-to-consumer subscriptions. Pricing pressure stems from refrigerated fresh meal substitution in urban convenience retail, compressing powder margins. Weight watchers and clinical protocol buyers exhibit lowest price sensitivity; impulse convenience purchasers show highest elasticity.
Supply Chain Analysis
Extended payment terms from Dutch and German retail banners now finance upstream pea protein procurement, compressing working capital cycles for spray-drying operators. Ingredient sourcing draws from France, the Netherlands, and Germany for protein extraction, with binding agents and micronutrient premixes anchored in Swiss and Italian specialty chemical production. Supply chain risk centers on single-source vulnerability in northern Dutch pea processing capacity. Distribution runs through automated aseptic bottling facilities in Bavaria serving pan-European retail and pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as fitness enthusiast demand splinters formulation requirements across pre-workout, recovery, and meal substitution contexts, creating niche positioning space for specialized entrants alongside platform incumbents.
For Market Incumbents: Pre-empt subscription churn by integrating AI-driven personalization engines that lock in urban professional cohorts through metabolic data integration. Acquire pea protein processing capacity in Poland or Romania to reduce Dutch supply concentration exposure. Defensive patent filing around high-pressure processing applications will block emerging ready-to-drink competitors from clean-label shelf positioning. For New Entrants and Emerging Players: Build out pharmacy channel relationships in France and Poland where clinical credibility gaps exist between medical nutrition and conventional food supplements. Target Warsaw and Bucharest corporate cafeterias with localized flavor profiles at price points below German premium tiers. Direct-to-consumer subscription with wearable glucose monitor bundling offers the stickiest go-to-market angle for metabolic personalization. For Investors and Strategic Acquirers: Capital is best deployed toward verticalized ready-to-drink manufacturers with captive aseptic processing and EFSA-validated health claim portfolios. Long-term viability favors assets with regulatory moats rather than pure brand equity in powder commoditization. Watch EFSA Novel Food authorization timelines for emerging legume proteins as the inflection signal for supply chain repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Validation Investment | Clinical substantiation unlocks pharmacy channel access and premium pricing tiers. |
| Pea Protein Supply Agreement | Long-term offtake contracts with Dutch or French processors reduce input cost volatility exposure. |
| High-Pressure Processing Adoption | Cold-chain aseptic technology extends clean-label shelf stability without synthetic preservatives. |
| AI-Driven Personalization Platform | Metabolic data integration creates subscription stickiness among Berlin and London urban professionals. |
| Eastern European Manufacturing Footprint | Polish or Romanian production addresses underpenetrated Warsaw and Bucharest demand clusters. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with formulation R&D directors, retail category buyers, pharmacy procurement managers, and fitness studio operators; and secondary validation through EFSA Novel Food register entries, EU Nutrition and Health Claims Regulation guidance documents, and customs trade data for pea protein and vitamin premix flows. Bottom-up segment sizing triangulated against top-down category expenditure estimates from pan-European retail audit databases.
Forecast inputs incorporated product type, target audience, formulation, and distribution channel segmentation dimensions across the modeling period. CAGRs derived from regression analysis of historical consumption patterns against regulatory enforcement intensity and protein sourcing cost indices. EFSA authorization timeline assumptions and EU Green Deal protein mandate implementation schedules shaped supply-side projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by plant-based powder direct-to-consumer specialists or clinical nutrition platform integrators would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Vietnam Collagen Supplements Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
Direct Fed Microbials Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Asia Pacific Nutritional Supplements Market
Nutritional Supplements
Chia-Based Protein Market
Nutritional Supplements
Global Docosahexaenoic Acid (DHA) Market
Nutritional Supplements
Global Proanthocyanidins Market
Nutritional Supplements
South America Botanical Supplements Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Prickly Pear Seed Oil Nutricosmetic Bases Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
Europe Moringa Supplement Market
Nutritional Supplements
Green Supplement Market