
 Fish Protein Isolate Market | 2026-2036
Fish Protein Isolate Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Protein Isolate Market Analysis
REACH is realigning the cost-of-entry calculus for European suppliers of fish protein isolate by mandating exhaustive substance registration and safety documentation. Bio-marine Ingredients Ireland Ltd. leverages its coastal processing infrastructure to sustain raw material traceability from catch to isolate. Omega Protein Corporation anchors North American supply through vertical control of menhaden reduction operations. Hofseth BioCare ASA differentiates via enzymatic hydrolysis technology that preserves bioactive peptide fractions.
Fish protein isolate denotes a highly refined protein fraction extracted from whole fish or processing by-products, typically achieving protein concentrations exceeding 90 percent on a dry-weight basis through isoelectric precipitation or membrane filtration, and serves primarily as a functional ingredient in high-performance nutrition and specialized feed formulations. The isolate category commands premium positioning in human nutrition applications where allergen labeling and digestibility scores determine procurement decisions, while hydrolyzed protein variants gain traction in clinical and sports segments due to superior absorption kinetics. Powder form dominates current manufacturing output, though liquid concentrates are expanding in ready-to-drink applications where solubility and flavor masking present formulation advantages.
The European Food Safety Authority and the FDA jointly shape product standards through divergent approval pathways for novel food status and Generally Recognized as Safe determinations, creating compliance complexity for multinational suppliers. Codex Alimentarius guidelines on fish allergen thresholds further constrain labeling and cross-contamination protocols in export-oriented facilities. Stakeholders must monitor regulatory harmonization progress between major import jurisdictions while building redundant certification portfolios to preserve market access flexibility.
Market Dynamics
Fish protein isolate production is consolidating around enzymatic hydrolysis infrastructure, with coastal processing clusters in Norway, Iceland, and Chile capturing disproportionate value through proximity to raw material supply and cold-chain logistics density.
Growth Catalysts
- Sports Nutrition Formulation:Performance nutrition brands in the United States are expanding R&D pipelines to incorporate marine-derived isolates with superior digestibility scores compared to whey alternatives.
- REACH Registration Mandates:European suppliers completing exhaustive substance documentation under ECHA requirements are securing preferential access to EU food and feed ingredient procurement channels.
- Menhaden Reduction Verticality:North American processors with captive fleet operations control input costs through backward integration into Atlantic menhaden harvesting and rendering.
Market Restraints
- Raw Material Volatility:Wild-catch quota fluctuations in Peruvian anchoveta fisheries create input cost instability for hydrolyzed protein manufacturers dependent on South American meal supply.
- Allergen Labeling Thresholds:Codex Alimentarius fish protein thresholds constrain export flexibility, forcing dual-label SKUs for markets with divergent consumer sensitivity protocols.
- Plant Protein Substitution:Pea and fava protein isolates achieve price parity in mass-market applications, compressing premium positioning for marine alternatives in non-specialized nutrition.
Strategic Opportunities
- Clinical Nutrition Penetration:Hydrolyzed peptide fractions with documented bioactivity are entering medical food formulations for post-surgical recovery and sarcopenia management in Japan's aging demographic.
- EU Green Deal Incentives:Circular economy funding streams for by-product valorization are subsidizing capital deployment for processors converting filleting waste into food-grade isolate.
- Ready-to-Drink Channels:Liquid concentrate formats with improved solubility profiles are displacing powder sachets in convenience-oriented sports recovery beverages across South Korean gym networks.
Industry Challenges
- Enzymatic Process Engineering Talent:Specialized biochemists capable of optimizing hydrolysis parameters for peptide preservation command scarcity premiums, constraining capacity expansion timelines.
- Dual Jurisdiction Certification:Simultaneous FDA GRAS self-determination and EFSA novel food dossier preparation extends time-to-market by 18-24 months for multinational launch strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Protein Isolate Market |
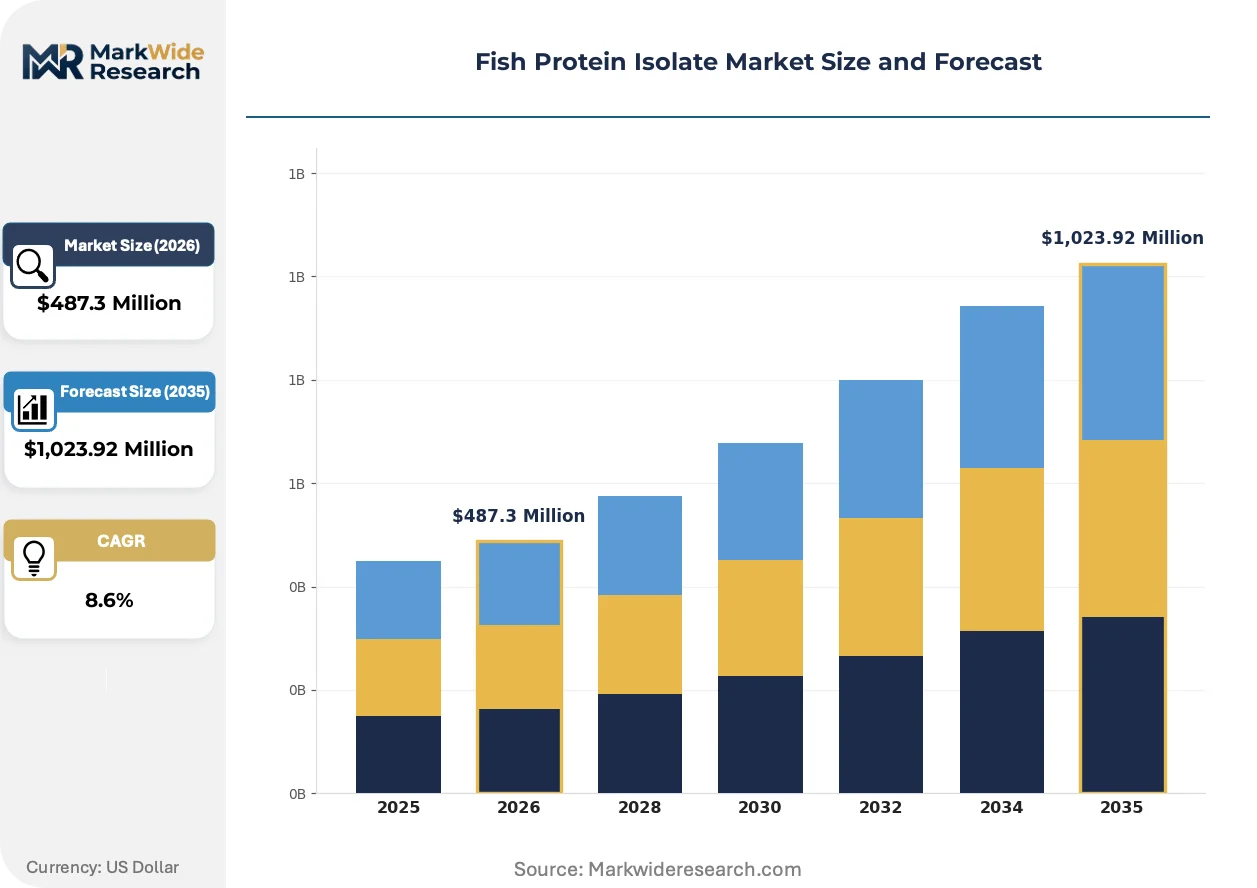
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Protein, Concentrate, Isolate, Peptides Form: Powder, Liquid, Granule, Tablet Application: Nutrition Supplements, Animal Feed, Food Processing, Functional Foods End User: Athletes, Health-Conscious Consumers, Pet Food Manufacturers, Food Industry |
| Companies Covered | Bio-marine Ingredients Ireland Ltd., Copalis Sea Solutions, Omega Protein Corporation, TripleNine Group A/S, Titan Biotech Limited, Scanbio Marine Group, Bio-Oregon Protein Inc., Colpex International, Hofseth BioCare ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Protein Isolate Market Emerging Trajectories
Membrane filtration and precision enzymatic systems are compressing production economics while regulatory divergence between Atlantic and Pacific jurisdictions is fragmenting compliance architecture.
Cross-flow membrane filtration systems with ceramic microfiltration modules are achieving protein recovery rates above 92% from stickwater streams. Ready-to-drink manufacturers in Germany and the Netherlands are adopting these liquid concentrates at accelerating pace. The technology is expanding into flavor-sensitive applications previously dominated by spray-dried powders.
EFSA's evolving novel food assessment pathway for enzymatically processed marine proteins is extending evaluation timelines for hydrolyzed isolate categories. European ingredient suppliers are front-loading toxicology dossiers to preempt regulatory bottlenecks. Clinical nutrition segments with existing peptide approvals are absorbing compliance costs more readily than mass-market entrants.
Buyer consolidation among contract manufacturers is compressing supplier qualification cycles from 18 months to 9 months in North American sports nutrition. Direct procurement relationships with aquaculture processors are displacing traditional ingredient distributor networks. This pattern is most visible in Norway's Bergen-Stavanger processing corridor where filleting operations co-locate with isolate production.
Fish Protein Isolate Market Segmentation
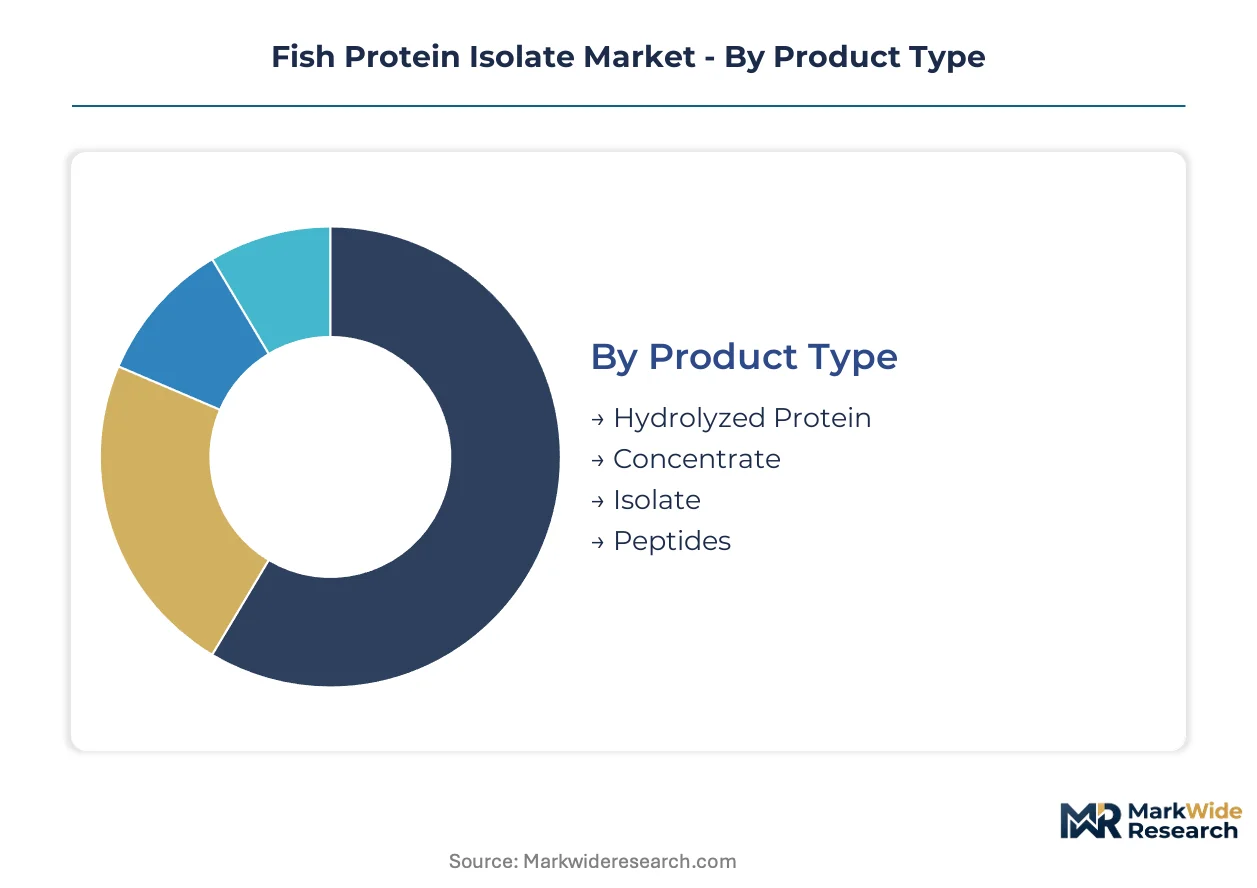
Fish protein isolate formulations diverge sharply across performance tiers and consumption occasions, with enzymatic processing depth and delivery format determining addressable market width. Procurement patterns in sports nutrition and clinical recovery segments are pulling manufacturers toward specialized peptide fractions and ready-to-drink liquid concentrates.
Product Type:
Upgrade cycles in this market track protein refinement depth, with buyers trading up from basic concentrates to bioactive peptide isolates as formulation science advances.
- Isolate:Achieves protein concentrations exceeding 90% dry-weight through isoelectric precipitation or membrane filtration. Demand concentrates in United States sports nutrition brands seeking superior digestibility scores versus whey alternatives, though FDA novel protein labeling requirements extend qualification timelines.
- Hydrolyzed Protein:Enzymatic cleavage yields low-molecular-weight peptides with accelerated absorption kinetics. Norway's aquaculture processing corridor dominates supply, with Hofseth BioCare ASA leveraging coastal infrastructure to preserve bioactive fractions through controlled hydrolysis parameters.
- Concentrate:Intermediate protein fraction typically ranging 70-85% purity, serving cost-sensitive feed and mass-market nutrition applications where premium positioning is unattainable.
- Peptides:Bioactive fractions with documented functional properties; Japan's clinical nutrition segment absorbs output for post-surgical recovery formulations targeting sarcopenia management.
Volume placements concentrate in Isolate; the faster expansion belongs to Hydrolyzed Protein.
Form:
Cost-tier differentiation separates commodity powder formats from premium liquid concentrates commanding formulation convenience premiums in ready-to-drink channels.
- Powder:Spray-dried output dominates manufacturing scale, with solubility and flavor-masking limitations constraining penetration in beverage applications.
- Liquid:Concentrate formats with improved solubility profiles are displacing powder sachets in South Korean gym network recovery beverages, where convenience-oriented consumption is accelerating.
- Granule:Intermediate format offering dosing precision for specialized feed compounding; captive demand from European aquaculture feed mills.
- Tablet:Compressed delivery for clinical and sports supplement SKUs; EFSA novel food assessments extend approval timelines for marine-derived tablet formulations.
Procurement weight sits with Powder; the steepest expansion trajectory is Liquid.
Application:
Application segmentation reflects margin stratification, with human nutrition commanding premium multiples over commodity feed uses.
- Nutrition Supplements:Sports and clinical segments drive specification intensity; United States brands expanding R&D pipelines with marine-derived isolates for performance positioning.
- Functional Foods:Fortified beverages and medical foods in Japan and Germany absorb hydrolyzed peptide output; EFSA toxicology dossier requirements filter mass-market entrants.
- Food Processing:Binder and emulsifier applications in processed seafood and surimi; Codex Alimentarius allergen thresholds constrain export flexibility for dual-label SKUs.
- Animal Feed:Aquaculture and premium pet nutrition; Peruvian anchoveta quota volatility creates input cost instability for hydrolyzed protein manufacturers.
Revenue concentration favors Nutrition Supplements; Functional Foods is climbing the fastest.
End User:
Customer-type segmentation maps to certification burden and procurement sophistication, with institutional buyers demanding redundant qualification portfolios.
- Athletes:Performance-oriented demand prioritizing digestibility scores and rapid absorption; North American contract manufacturers compressing supplier qualification cycles from 18 months to 9 months.
- Health-Conscious Consumers:Aging demographic in Japan drives clinical peptide absorption; EU Green Deal circular economy funding subsidizes by-product valorization for food-grade isolate.
- Pet Food Manufacturers:Premium positioning in companion animal nutrition; allergen labeling requirements less stringent than human food channels.
- Food Industry:Industrial procurement with price sensitivity; pea and fava protein isolates achieving parity in non-specialized applications.
Contract volume aggregates with Athletes; Health-Conscious Consumers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States sports nutrition brands drive formulation demand for marine-derived isolates, while coastal processing clusters in Norway and Chile capture disproportionate value through raw material proximity. Regulatory divergence between FDA novel protein pathways and EFSA novel food assessments fragments compliance architecture across Atlantic and Pacific supply routes.
United States
Performance nutrition brands expand R&D pipelines with fish-derived isolates targeting superior digestibility scores versus whey alternatives. FDA evolving stance on novel protein labeling extends supplier qualification timelines and reshapes import compliance cost structures. Sports nutrition contract manufacturers in California and Texas compress supplier onboarding cycles from eighteen months to nine months.
Norway
Aquaculture processing corridors between Bergen and Stavanger co-locate filleting operations with isolate production, enabling cold-chain density advantages. REACH registration mandates through ECHA filter mass-market entrants while securing preferential EU procurement channels for compliant suppliers. Hofseth BioCare ASA leverages coastal infrastructure to preserve bioactive peptide fractions through controlled enzymatic hydrolysis.
Chile
Pacific menhaden and anchovy reduction operations supply hydrolyzed protein manufacturers serving Asian export markets. Wild-catch quota fluctuations in Peruvian anchoveta fisheries create input cost instability for processors dependent on South American meal supply. Coastal processing clusters near Valparaíso capture logistics efficiencies through port-proximate rendering infrastructure.
Germany
Ready-to-drink manufacturers adopt liquid concentrate formats with improved solubility profiles for flavor-sensitive applications. EFSA toxicology dossier requirements for enzymatically processed marine proteins extend evaluation timelines, front-loading compliance costs onto ingredient suppliers. Membrane filtration technology providers in Bavaria and North Rhine-Westphalia serve cross-flow ceramic microfiltration demand from isolate producers.
Japan
Aging demographic absorption of hydrolyzed peptide fractions targets post-surgical recovery and sarcopenia management in clinical nutrition segments. METI oversight of functional food claims shapes medical food formulation standards for marine-derived bioactives. Osaka and Tokyo metropolitan areas concentrate demand for premium isolate applications in geriatric care protocols.
Fish Protein Isolate Market Vendor Landscape
Norwegian and Icelandic producers anchor the premium-tier supply base; North American specialists hold scale advantages through menhaden reduction verticality. Market structure tilts toward coastal processing clusters with captive fleet operations or aquaculture by-product access. Three archetypes dominate: enzymatic hydrolysis technology owners, membrane filtration equipment integrators, and aquaculture waste valorization specialists. Capacity expansion and regulatory certification redundancy constitute the dominant competitive moves.
Within the coastal infrastructure tier, Bio-marine Ingredients Ireland Ltd. and Hofseth BioCare ASA exemplify European positioning through traceability-from-catch systems and enzymatic peptide preservation. Omega Protein Corporation occupies a scale-driven position reflecting North American menhaden supply control. These three entities represent the geographic and technological split between Atlantic premium positioning and volume-oriented Pacific supply.
| Leading Market Players |
|---|
| Bio-marine Ingredients Ireland Ltd. |
| Copalis Sea Solutions |
| Omega Protein Corporation |
| TripleNine Group A/S |
| Titan Biotech Limited |
| Scanbio Marine Group |
| Bio-Oregon Protein Inc. |
| Colpex International |
| Hofseth BioCare ASA |
| Others |
Supply Flow & Price Mechanics
EU Green Deal circular economy mandates gate qualified supply and premium-tier pricing access for fish protein isolate manufacturers, rewarding processors converting filleting waste into food-grade isolate with preferential procurement channels while filtering out mass-market entrants lacking by-product valorization infrastructure.
Pricing Analysis
Short lead-time premiums dominate contract negotiations for clinical-grade hydrolyzed peptides, while spot inventory of commodity concentrates trades at discounts reflecting Peruvian anchoveta quota volatility. Three-tier pricing structure across premium peptide isolates, standard hydrolyzed proteins, and economy-grade concentrates separates buyers by certification burden and application specificity. Cost compression in economy tiers intensifies as pea and fava proteins achieve functional parity in non-specialized nutrition. Food industry procurement teams exhibit highest price sensitivity, whereas clinical nutrition formulators absorb premium multiples for documented bioactivity.
Supply Chain Analysis
Menhaden and anchovy supply rests on coastal reduction operations concentrated in Norway, Chile, and Peru, with Atlantic and Pacific fleet operations anchoring regional processing clusters. Enzymatic hydrolysis equipment, ceramic membrane filtration modules, and specialized cold-chain logistics constitute critical input dependencies. Single-source vulnerability runs through Peruvian anchoveta quota allocations, where wild-catch fluctuations cascade into input cost instability. Distribution runs through direct procurement relationships with aquaculture processors, displacing traditional ingredient distributor networks in North American sports nutrition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
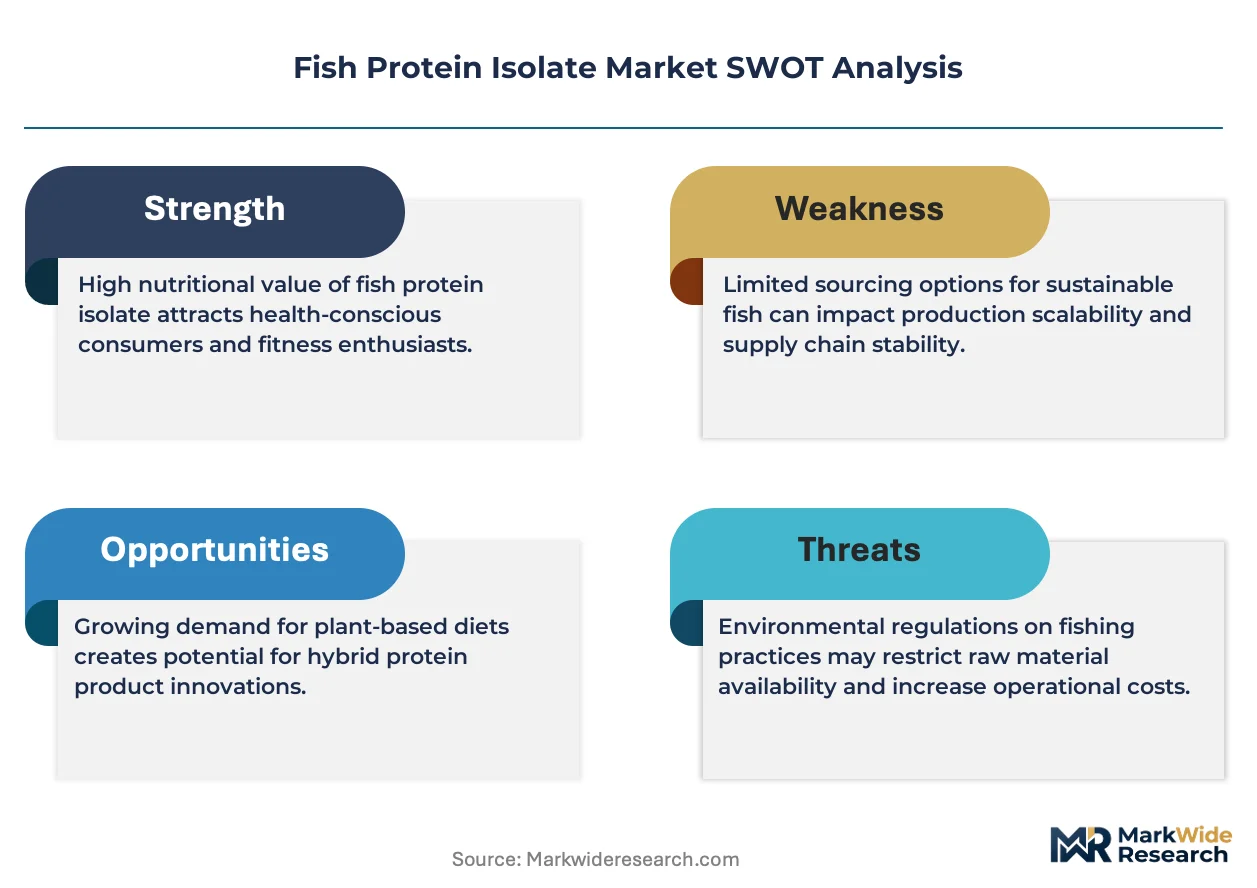
This market functions as a vertical-integration race, with backward integration into captive fleet operations or filleting by-product streams determining cost position and supply security.
For Market Incumbents: Anticipate plant protein substitution threats by deepening peptide specialization for clinical and sports segments where digestibility scores command premium positioning. Secure redundant EFSA novel food and FDA GRAS certification portfolios to preserve cross-Atlantic market access flexibility. Expand enzymatic hydrolysis capacity in Norway's Bergen-Stavanger corridor to exploit cold-chain density advantages. For New Entrants and Emerging Players: Begin with EU Green Deal circular economy funding streams subsidizing by-product valorization capital deployment, targeting filleting waste conversion into food-grade isolate. Penetrate Germany and Netherlands ready-to-drink channels where liquid concentrate adoption accelerates and solubility advantages displace spray-dried powders. Pursue direct supply relationships with aquaculture processors rather than distributor intermediation. For Investors and Strategic Acquirers: REACH registration completion timelines extending 18-24 months for ECHA compliance are the leading indicator that regulatory certification redundancy will separate viable acquisition targets from stranded capacity. Five-to-ten-year viability hinges on coastal infrastructure access with traceability-from-catch systems. Target processors with enzymatic hydrolysis technology ownership and established peptide fraction preservation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fleet Operations | Omega Protein Corporation's menhaden supply control demonstrates cost stability advantages. |
| Enzymatic Hydrolysis Capacity Expansion | Hofseth BioCare ASA's coastal infrastructure preserves bioactive peptide fractions through controlled parameters. |
| Dual Jurisdiction Certification Investment | Simultaneous FDA GRAS and EFSA novel food dossiers extend time-to-market but secure flexible access. |
| By-Product Valorization Infrastructure | Bio-marine Ingredients Ireland Ltd. leverages traceability-from-catch systems for premium positioning. |
| Liquid Concentrate Format Development | South Korean gym network adoption signals displacement of powder sachets in convenience channels. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with plant managers at coastal reduction facilities, procurement leads at sports nutrition contract manufacturers, regulatory affairs specialists navigating EFSA novel food pathways, and technical R&D directors optimizing enzymatic hydrolysis parameters. Bottom-up volume modeling triangulated against top-down value assessments derived from customs records and SEC filings of publicly traded processors.
Segment-level granularity modeled protein refinement depth across isolate, hydrolyzed protein, concentrate, and peptide categories; delivery format differentiation between powder, liquid, granule, and tablet; application stratification across nutrition supplements, functional foods, food processing, and animal feed; and end-user archetypes spanning athletes, health-conscious consumers, pet food manufacturers, and food industry procurement. CAGRs were computed from annualized growth trajectories across the analysis window, incorporating enzymatic process efficiency improvements and regulatory harmonization progress as industry-specific forecast inputs.
Underlying measurement precision varies by segment; clinical nutrition and sports supplement applications carry tighter precision than commodity feed uses due to more transparent procurement data. Forecasts reflect documented assumptions regarding REACH registration completion rates, wild-catch quota stability, and peptide bioactivity validation timelines. Regulatory divergence between FDA and EFSA pathways, Peruvian anchoveta quota volatility, and plant protein substitution acceleration warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Middle East and Africa Omega-3 Products Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Melatonin Supplements Market
Nutritional Supplements
Natural Vitamin E Product Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Indonesia Beauty Supplements Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
Global Beta-Alanine Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
Global Liver Health Supplements Market
Nutritional Supplements
Energy Gums Market
Nutritional Supplements
Global Multivitamin Capsules and Tablets Market
Nutritional Supplements
South Africa Collagen Peptides Market
Nutritional Supplements
Prenatal Vitamin Supplements Market
Nutritional Supplements
South America Nutricosmetics Market