
 Fire Trucks Market | 2026-2036
Fire Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Trucks Market Analysis
Aluminum is broadening its share of fire truck body construction as fleets seek corrosion resistance and weight reduction alongside payload retention. Rosenbauer International AG leverages in-house chassis production to control delivery timelines across European and Middle Eastern contracts. Oshkosh Corporation anchors North American municipal procurement through established defense-sector manufacturing discipline. Morita Holdings Corporation specializes in compact pumper designs for dense Asian urban corridors where maneuverability constrains apparatus selection.
Fire trucks are motorized emergency vehicles engineered with integrated water pumping systems, aerial ladder assemblies, and foam proportioning equipment rated between 1,000 and 3,000 gallons per minute discharge capacity, purpose-built for rapid fire suppression and technical rescue operations. Aerial platform configurations command premium positioning due to extended reach requirements in high-rise districts, while wildland variants face accelerating demand from prolonged fire seasons across Mediterranean and western North American terrains. Municipal fire departments represent the dominant end user channel, though industrial facilities in petrochemical and power generation sectors pursue dedicated apparatus with hazardous materials response certifications.
NFPA 1901 in the United States, ECE R107 across European member states, and China's GB 7956 standards collectively dictate pump performance testing, stability criteria, and electrical system safety thresholds that manufacturers must satisfy for market access. Compliance complexity rises as jurisdictions adopt divergent emissions protocols for auxiliary power units and chassis engines. Stakeholders must track regulatory harmonization efforts between national standards bodies and assess localized content requirements before committing to regional production footprints.
Market Dynamics
NFPA 1901 pump performance mandates and ECE R107 stability requirements are forcing synchronous chassis and body redesign cycles, compressing development timelines as manufacturers must recertify entire platforms rather than incremental upgrades.
Growth Catalysts
- NFPA 1901 Pump Standards:United States municipal departments face mandated replacement of pre-2016 apparatus, triggering fleet turnover concentrated in California, Texas, and Florida metropolitan districts.
- China's GB 7956 Expansion:Provincial governments beyond tier-one cities are professionalizing fire services, generating apparatus procurement from Sichuan, Henan, and Shandong municipal authorities.
- Aluminum Body Adoption:Corrosion-resistant alloy construction extends service intervals in coastal and chemical corridor deployments, reducing lifecycle maintenance burdens for fleet managers.
Market Restraints
- Specialized Steel Input Volatility:High-strength chassis-grade steel and aluminum alloy pricing fluctuations compress fabrication margins for body builders dependent on spot-market purchasing.
- Chassis Supply Concentration:European and North American apparatus manufacturers rely on a narrow supplier base for custom fire-service chassis, creating delivery vulnerability when commercial vehicle demand surges.
- Emissions Divergence:California Air Resources Board auxiliary power unit rules, Euro VI Stage D engine standards, and China's Stage VIb protocols impose incompatible certification requirements, fragmenting platform development.
Strategic Opportunities
- India's Urban Fire Service Modernization:Smart Cities Mission funding is creating dedicated procurement budgets for Mumbai, Delhi, and Bangalore municipal corporations previously reliant on state-level equipment sharing.
- Wildland-Urban Interface Apparatus:Extended Mediterranean and western North American fire seasons are generating specialized pumper-tanker specifications distinct from structural firefighting platforms.
- Electrification Convergence:Battery-electric chassis integration with pump-drive systems opens municipal procurement channels in jurisdictions with zero-emission vehicle mandates and carbon neutrality targets.
Industry Challenges
- Certification Timeline Compression:NFPA 1901 pump testing, aerial stability validation, and electrical system safety verification now require 14-18 month approval cycles, extending order-to-delivery intervals.
- Electro-Mechanical Integration Complexity:CAN bus architecture, automated foam proportioning, and telemetry systems demand software engineering capabilities foreign to traditional metal-fabrication shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Trucks Market |
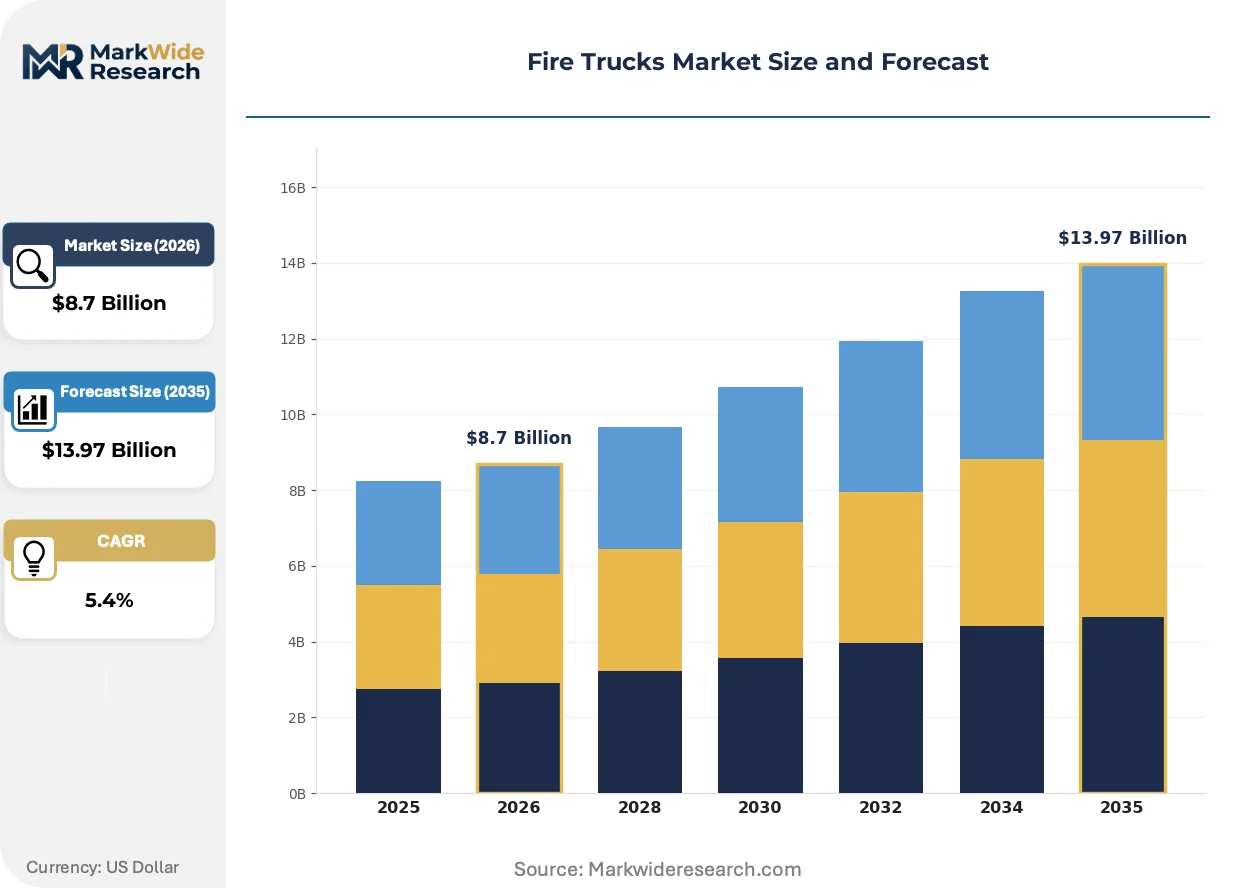
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Fire Pumper, Aerial Platform, Tanker, Wildland Application: Urban response, Rural firefighting, Industrial safety, Forest management End User: Municipal fire departments, Industrial facilities, Military, Volunteer fire services Technology: Hybrid engines, Fire suppression systems, Communication tools, GPS tracking |
| Companies Covered | Rosenbauer International AG, Oshkosh Corporation, REV Group, Morita Holdings Corporation, Magirus GmbH, Danko Emergency Equipment, Weihai Guangtai Airport Equipment Co., Ltd., Zoomlion Heavy Industry Science & Technology Co., Ltd., The Shyft Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Trucks Market Emerging Trajectories
Electrified chassis platforms, integrated telematics architectures, and modular body construction are compressing traditional apparatus lifecycle assumptions and opening new procurement channels for specialized configurations.
Telematics-enabled predictive maintenance systems are consolidating fleet management practices across municipal departments. Chicago, Houston, and Phoenix fire departments now mandate onboard diagnostic platforms that transmit pump performance, aerial stress, and electrical fault data to centralized maintenance hubs. This consolidation is compressing aftermarket service revenue for independent repair facilities while shifting procurement evaluation criteria toward software integration capabilities.
ECE R107 stability testing protocols and their GB 7956 Chinese equivalents are mandating real-time center-of-gravity monitoring for aerial platforms. Manufacturers must now engineer load-cell integration into outrigger and ladder assemblies, adding sensor procurement costs but reducing liability exposure. European aerial platform specialists face the steepest compliance burden as existing designs require structural reinforcement to meet revised tipping-moment thresholds.
Lifecycle cost analysis is displacing upfront capital expenditure as the dominant municipal evaluation framework. Procurement departments in Los Angeles County, Cook County, and Harris County now require 15-year total cost of ownership modeling that incorporates fuel consumption, maintenance intervals, and residual value depreciation. This behavioral shift favors manufacturers with documented reliability data and compresses market access for new entrants lacking operational track records.
Fire Trucks Market Segmentation
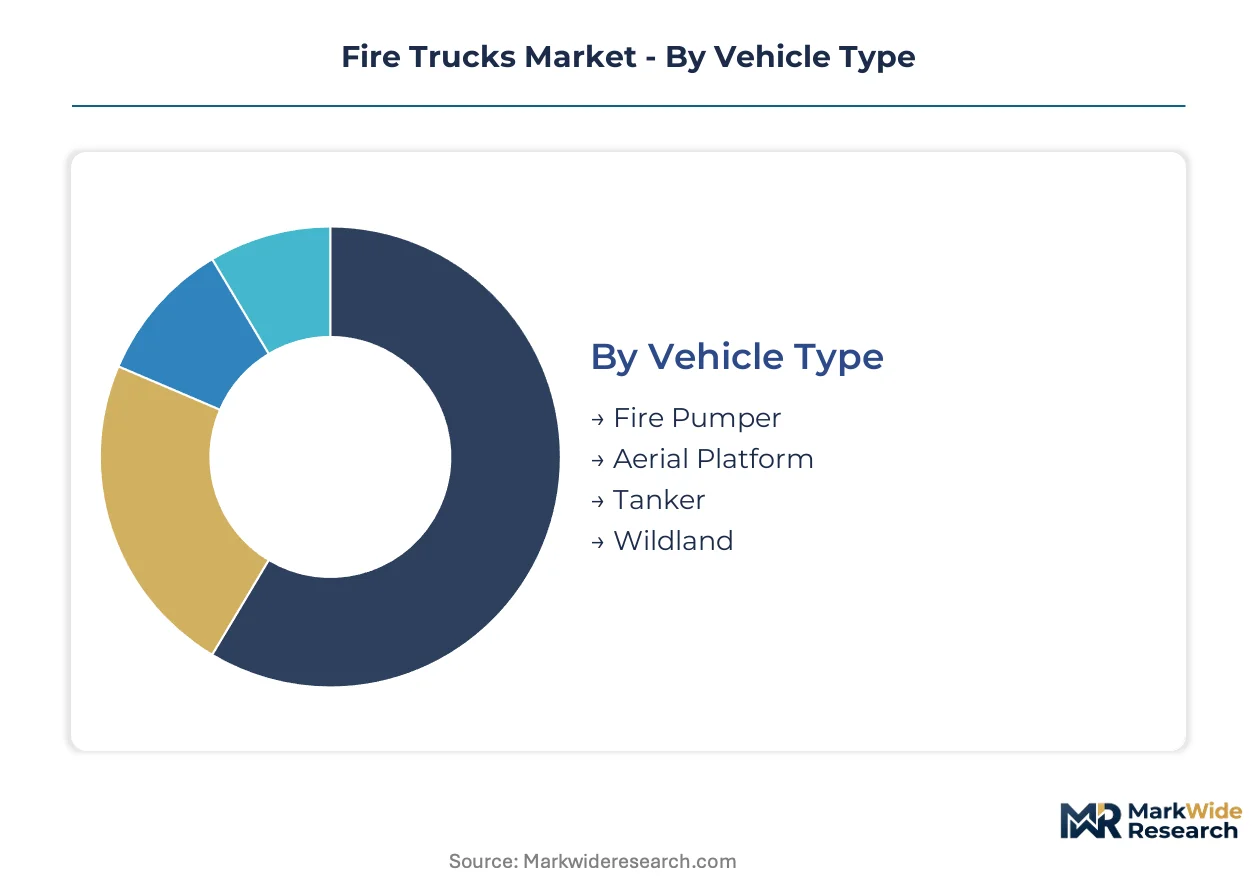
Fire truck procurement decisions hinge on divergent certification pathways, with NFPA 1901 structural requirements, ECE R107 stability mandates, and GB 7956 pumping specifications each favoring distinct apparatus configurations. Fleet managers align vehicle selection with incident response profiles, terrain constraints, and regulatory compliance burdens specific to their operating jurisdictions.
Vehicle Type:
NFPA 1901 pump certification governs pumper apparatus, ECE R107 aerial stability testing dominates platform designs, and wildland variants face distinct forestry service approvals rather than municipal codes.
- Fire Pumper:Integrated pumping systems rated 1,000-3,000 gallons per minute discharge capacity form the municipal fleet backbone. California, Texas, and Florida metropolitan districts drive replacement cycles as pre-2016 apparatus face mandated retirement under revised NFPA 1901 testing protocols.
- Aerial Platform:Articulating and straight-stick ladder assemblies with 75-110 foot vertical reach command premium positioning. High-rise construction corridors in Chicago, Houston, and Phoenix generate concentrated demand where ECE R107 center-of-gravity monitoring now adds sensor procurement costs.
- Tanker:High-capacity water transport units bridge hydrant-deficient rural infrastructure. Volunteer fire services in Australia's bushfire-prone regions and Mediterranean coastal municipalities specify 2,500-4,000 gallon configurations.
- Wildland:Compact, high-mobility units with four-wheel-drive chassis and reduced water weight for off-road terrain access. Prolonged fire seasons across Portugal, Spain, and western North American states accelerate specialized procurement distinct from structural platforms.
Leading the category by volume: Fire Pumper. Expanding most quickly: Wildland.
Application:
Cost tier stratification separates capital-intensive urban fleets from maintenance-constrained rural operations and hazard-certified industrial deployments.
- Urban response:Multi-functional apparatus with integrated pumping, aerial, and rescue capabilities serve dense population centers. Municipal procurement in China's tier-two cities—Sichuan, Henan, Shandong—generates apparatus demand as professional fire service coverage expands beyond Beijing and Shanghai.
- Rural firefighting:Tanker-dependent operations with extended response radius requirements dominate hydrant-sparse territories. India's Smart Cities Mission is creating dedicated procurement budgets for Mumbai, Delhi, and Bangalore municipal corporations previously reliant on equipment sharing.
- Industrial safety:Hazardous materials response certifications and foam proportioning systems address petrochemical and power generation facility requirements. Dedicated apparatus specifications exceed municipal pump performance thresholds.
- Forest management:Rapid deployment and terrain traversal capabilities prioritize maneuverability over water volume. Mediterranean forestry services and North American federal land management agencies specify compact pumper-tanker hybrids.
Urban response commands the largest procurement budgets. Forest management shows the steepest expansion trajectory.
End User:
Customer type determines financing mechanisms, with tax-funded municipal departments, capital-expense industrial facilities, defense procurement channels, and donation-dependent volunteer services each imposing distinct vendor qualification criteria.
- Municipal fire departments:Professional career services dominate apparatus procurement volume. Los Angeles County, Cook County, and Harris County now mandate 15-year total cost of ownership modeling incorporating fuel consumption, maintenance intervals, and residual value depreciation.
- Industrial facilities:Petrochemical complexes and power generation plants pursue dedicated hazardous materials response apparatus. On-site brigades require NFPA 1901 compliance plus facility-specific foam and chemical suppression certifications.
- Military:Defense-sector procurement channels leverage established manufacturing discipline for airfield crash rescue and structural protection vehicles. Delivery timelines align with base modernization schedules rather than emergency replacement cycles.
- Volunteer fire services:Donation-funded and partially subsidized operations prioritize acquisition cost over lifecycle analysis. Equipment standardization suffers from fragmented funding sources across county and township jurisdictions.
Municipal departments anchor procurement volume. Industrial facilities are gaining share fastest as on-site hazardous materials capabilities expand.
Technology:
Margin concentration shifts toward electro-mechanical integration as CAN bus architecture, automated systems, and telemetry displace traditional metal-fabrication value capture.
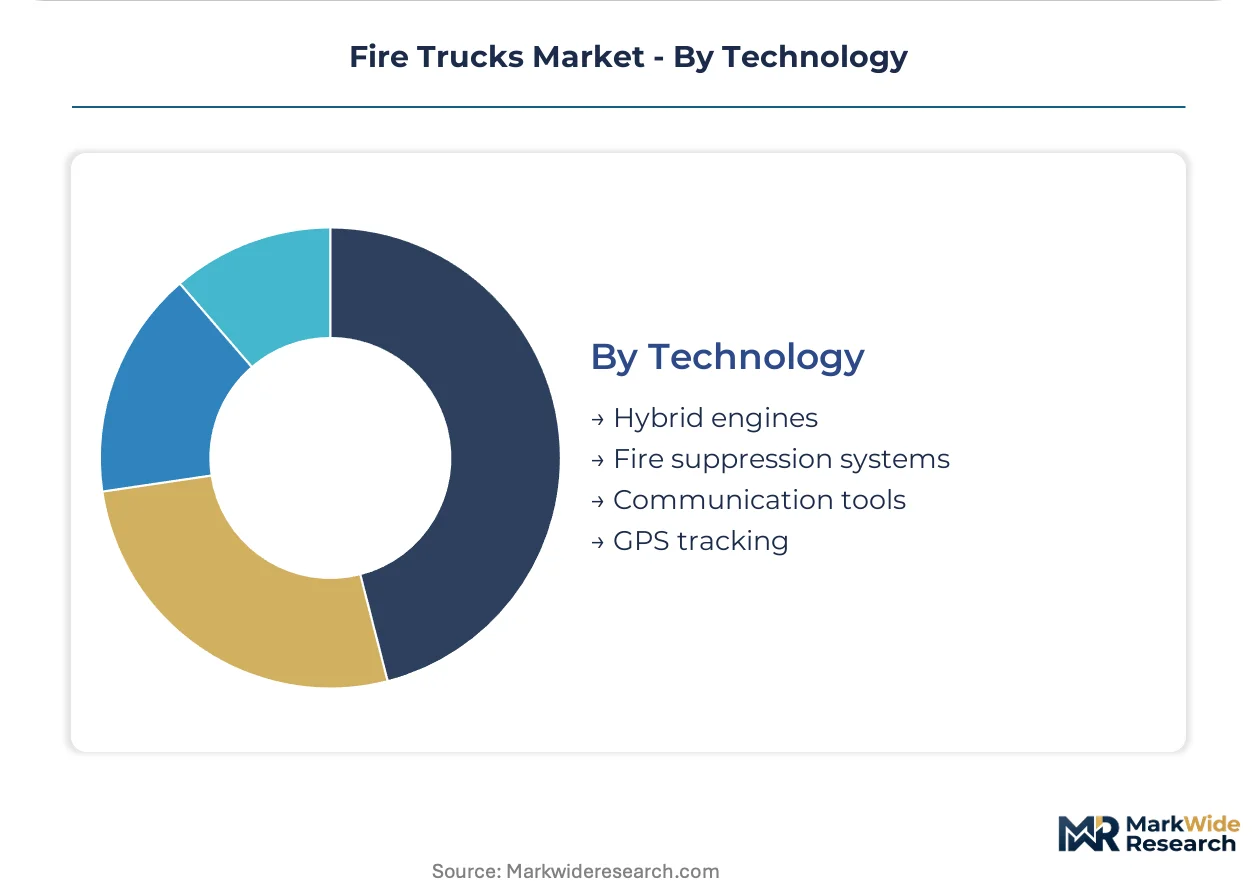
- Hybrid engines:Battery-electric chassis integration with pump-drive systems opens municipal procurement channels in jurisdictions with zero-emission vehicle mandates. California Air Resources Board auxiliary power unit rules impose certification requirements distinct from Euro VI and China's Stage VIb protocols.
- Fire suppression systems:Automated foam proportioning and compressed air foam systems reduce operator error in hazardous materials incidents. Software engineering capabilities now determine competitive positioning.
- Communication tools:Integrated dispatch, incident command, and mutual aid coordination platforms consolidate fleet management practices. Chicago, Houston, and Phoenix departments mandate onboard diagnostic data transmission to centralized maintenance hubs.
- GPS tracking:Real-time location and route optimization supports multi-agency coordination during large-scale incidents. Telemetry-enabled predictive maintenance compresses aftermarket service revenue for independent repair facilities.
Fire suppression systems represent the most mature technology segment. Hybrid engines are climbing the fastest as carbon neutrality targets reshape municipal procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's municipal governments generate the densest procurement activity as professional fire service coverage expands into tier-two and tier-three cities. Fleet replacement cycles in the United States and Western Europe follow regulatory mandates rather than organic growth.
United States
California, Texas, and Florida metropolitan districts concentrate apparatus replacement demand as pre-2016 fleets face mandated retirement under NFPA 1901 pump testing protocols. The Environmental Protection Agency and California Air Resources Board impose divergent auxiliary power unit emissions rules that fragment platform certification. Los Angeles County and Harris County procurement departments now require 15-year total cost of ownership modeling.
Germany
ECE R107 stability requirements force synchronous chassis and body redesign cycles for aerial platform manufacturers serving Central European municipal departments. The Kraftfahrt-Bundesamt enforces commercial vehicle type approval standards that extend to fire-service chassis modifications. Stuttgart and Munich fire authorities drive specification evolution through centralized state-level procurement consortia.
China
Provincial governments in Sichuan, Henan, and Shandong professionalize fire services beyond Beijing and Shanghai coverage zones. GB 7956 pumping specifications and Stage VIb emissions protocols create localized certification requirements distinct from Western standards. Weihai and Changsha host manufacturing clusters supplying domestic municipal authorities with apparatus tailored to dense urban corridors.
India
Smart Cities Mission funding creates dedicated procurement budgets for Mumbai, Delhi, and Bangalore municipal corporations previously dependent on state-level equipment sharing. The Central Electricity Authority and Bureau of Indian Standards influence electrical system safety thresholds for imported apparatus. Maharashtra and Karnataka state fire services drive specification standardization across western and southern urban clusters.
Japan
Metropolitan Tokyo and Osaka fire departments prioritize compact pumper designs constrained by narrow street geometries and high-rise density. The Ministry of Economy, Trade and Industry oversees industrial standards coordination with municipal procurement specifications. Nagoya and Yokohama anchor manufacturing and fleet modernization activity in the Chubu and Kanto industrial belts.
Fire Trucks Market Vendor Landscape
Backward integration into in-house chassis production dominates the current landscape as manufacturers seek delivery timeline control. The vendor base concentrates around three tiers: integrated chassis-body builders, specialized body fabricators dependent on third-party chassis, and regional assemblers serving protected procurement markets. Strategic archetypes include European engineering-led specialists, North American defense-sector disciplined manufacturers, and Asian compact-design innovators. M&A activity and geographic licensing partnerships represent the primary competitive vectors as scale advantages consolidate.
Among European integrated producers, Rosenbauer International AG and Magirus GmbH occupy positions exemplifying engineering-led specialization with captive chassis capabilities. Oshkosh Corporation anchors North American municipal procurement through defense-sector manufacturing discipline. Morita Holdings Corporation represents the Asian compact-design archetype, with specialists in dense urban configurations including Weihai Guangtai Airport Equipment Co., Ltd. and Zoomlion Heavy Industry Science & Technology Co., Ltd. sitting within the Chinese fabricator tier.
| Leading Market Players |
|---|
| Rosenbauer International AG |
| Oshkosh Corporation |
| REV Group |
| Morita Holdings Corporation |
| Magirus GmbH |
| Danko Emergency Equipment |
| Weihai Guangtai Airport Equipment Co., Ltd. |
| Zoomlion Heavy Industry Science & Technology Co., Ltd. |
| The Shyft Group, Inc. |
| Others |
Supply Flow & Price Mechanics
Chassis fabrication specialists in Baden-Württemberg and Upper Austria create labor-cost differentials that widen spreads between premium aerial platforms and standard pumper configurations. European engineering wages compress margins on complex apparatus while Asian metalworking clusters enable aggressive entry-level positioning.
Pricing Analysis
Volume concentrates in municipal pumper procurement while margins accumulate in aerial platform segments. Three-tier pricing structure across premium, standard, and economy levels separates NFPA 1901-certified aerial ladders from basic tanker configurations. Pricing pressure stems from aluminum alloy spot-market volatility squeezing body-builder margins. Volunteer fire services exhibit acute price sensitivity, while industrial facilities prioritize lifecycle cost over acquisition outlay.
Supply Chain Analysis
High-strength chassis-grade steel supply rests on German, Japanese, and South Korean specialty mills with limited fire-service certification. Aluminum extrusion and CAN bus control modules constitute critical component dependencies. Single-source vulnerability concentrates in custom fire-service chassis where commercial vehicle demand surges crowd out apparatus builders. Distribution runs through municipal procurement consortia and defense-sector channels rather than open dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chassis supply bottlenecks prop pricing power for integrated manufacturers with captive production. Limited qualified suppliers for fire-service-grade chassis create procurement queues that favor backward-integrated incumbents.
For Market Incumbents: Anchor market position through in-house chassis production expansion in Central European manufacturing corridors. Certification investment in GB 7956 compliance opens Chinese provincial procurement channels. Capacity addition in Weihai or Changsha manufacturing clusters defends against emerging Asian competitors with cost-advantaged aluminum fabrication. For New Entrants and Emerging Players: Launch via wildland-urban interface apparatus specialization targeting Mediterranean forestry services and western North American state agencies. India's Smart Cities Mission municipal corporations represent the most penetrable geography with dedicated procurement budgets displacing state-level equipment sharing. Telematics integration partnerships with fleet management software providers accelerate credibility building. For Investors and Strategic Acquirers: Re-rating potential sits with European engineering-led specialists given ECE R107 stability mandate compliance burden advantages. Long-term viability favors integrated chassis-body builders over fabricators dependent on third-party supply. Watch aerial platform order backlogs as inflection indicator for pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chassis Production | In-house chassis manufacturing compresses delivery timelines for NFPA 1901 and ECE R107 recertification cycles. |
| Electrification Platform Development | Battery-electric chassis integration with pump-drive systems captures California Air Resources Board zero-emission procurement mandates. |
| Telematics Architecture Partnership | Onboard diagnostic data transmission aligns with Chicago, Houston, and Phoenix centralized maintenance hub requirements. |
| Wildland Apparatus Specialization | Compact pumper-tanker hybrids address prolonged Mediterranean and western North American fire season demand. |
| GB 7956 Certification Investment | Chinese domestic standard compliance unlocks Sichuan, Henan, and Shandong provincial government procurement channels. |
Methodological Framework
Independent corroboration across fire apparatus procurement officers, chassis engineering directors, and municipal fleet managers underwrites the qualitative findings. Secondary validation draws from NFPA technical committee documentation, ECE R107 regulatory filings, and GB 7956 standard revisions. Customs data on high-strength steel and aluminum alloy trade flows, combined with SEC 10-K disclosures from listed manufacturers, support demand-side estimation. Bottom-up apparatus shipment tracking and top-down municipal budget allocation analysis triangulate market sizing.
Rate-of-change decomposition across vehicle type, application, end user, and technology dimensions structures the analytical framework. CAGRs derive from regression against historical replacement cycle data, regulatory mandate implementation schedules, and infrastructure investment trajectories. Chassis supply constraints, emissions protocol divergence, and aluminum alloy price volatility constitute industry-specific forecast inputs across the projection horizon.
Regulatory harmonization failure, raw material price spikes, and chassis supplier capacity allocation shifts are the dominant revision risks. Forecasts reflect documented assumptions on fleet replacement timing and provincial budget execution rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Full Truckload Transportation Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Dashboard Switch Panel Systems Market
Heavy-Duty Trucks
Truck Bedliner Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Heavy Duty Truck Wash Market