
 Full Truckload Transportation Market | 2026-2036
Full Truckload Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Full Truckload Transportation Market Foresight
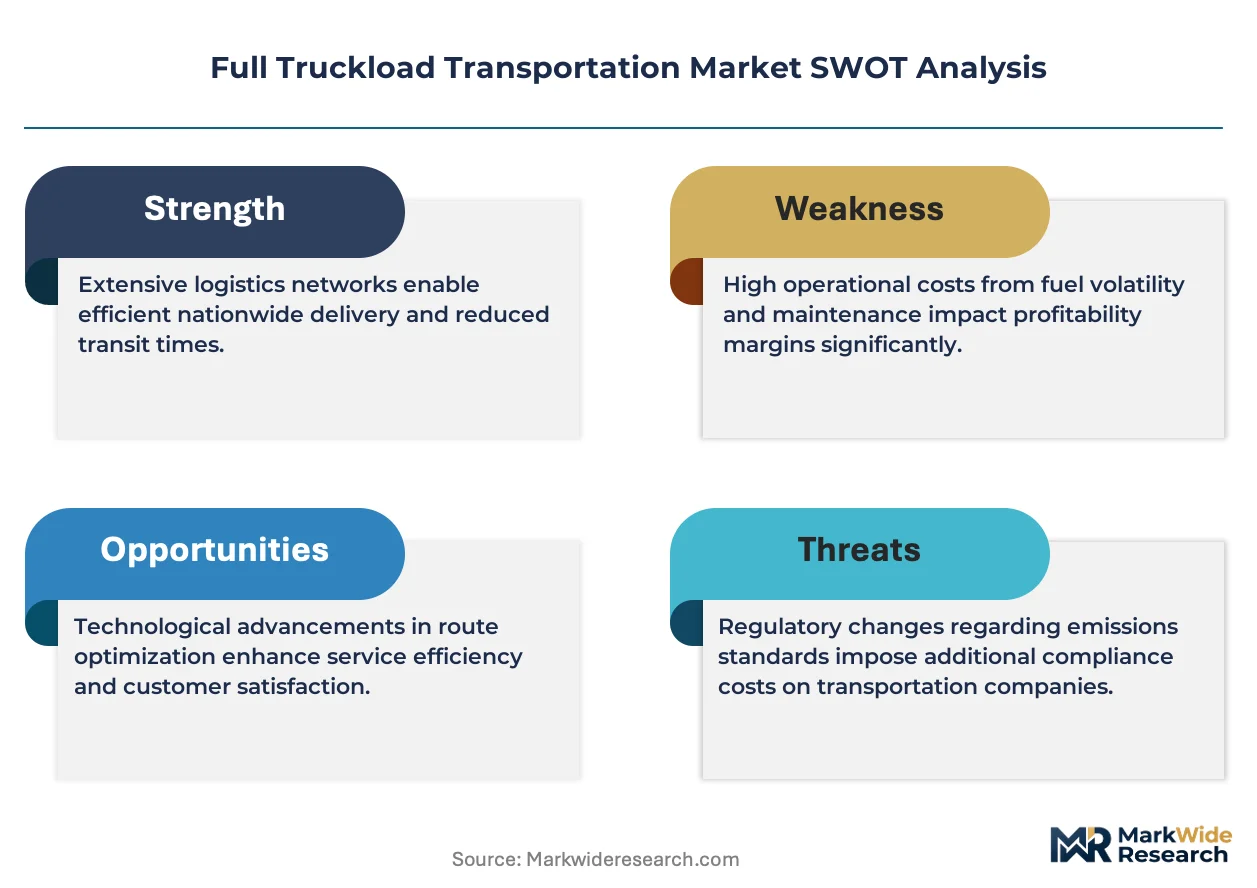
Freight visibility software is pivoting from add-on feature to core service layer in full truckload contracting. J.B. Hunt Transport Services leverages its J.B. Hunt 360 platform to anchor shipper-carrier matching across North American lanes. Knight-Swift Transportation sustains one of the largest owned fleet footprints, while Schneider National differentiates through intermodal integration and dedicated contract structures.
Full truckload transportation moves a single shipper's cargo in a dedicated trailer from origin to destination without intermediate consolidation, typically requiring tractors with gross vehicle weight ratings of 80,000 pounds under US federal limits and operating across distances exceeding 250 miles per haul. Dry van equipment dominates volume across consumer goods lanes, though refrigerated units command premium positioning in fresh produce and temperature-controlled chemicals. Regional service types are maturing as shorser haul networks absorb e-commerce restocking cycles, while expedited offerings capture margin pools in electronics and just-in-time machinery movements.
The US EPA and NHTSA jointly enforce heavy-duty emissions and fuel economy standards that reshape tractor procurement cycles and fleet renewal timelines. The EU Green Deal's Fit for 55 framework and the EU AI Act's logistics monitoring provisions together tighten both carbon intensity and data governance requirements for cross-border hauliers. Stakeholders must monitor how California's Advanced Clean Trucks rule and parallel state-level mandates fragment compliance pathways across domestic operating territories.
Market Dynamics
Freight visibility platforms are consolidating shipper-carrier relationships into data-integrated service layers, compressing spot-market reliance and embedding long-term contracting logic into fleet procurement decisions.
Growth Catalysts
- E-commerce fulfillment networks:Dedicated fleet contracts are absorbing restocking cycles from regional distribution centers, tightening lane density on high-volume corridors.
- US EPA Phase 3 standards:Emissions rules are accelerating tractor fleet renewal timelines, creating replacement demand for compliant powertrain configurations.
- China manufacturing clusters:Port throughput and inland production hubs sustain concentrated origin-destination pairings that favor full truckload economics.
Market Restraints
- Diesel price volatility:Fuel represents 25-30% of operating costs for asset-based carriers, compressing margins during price spikes without contract fuel surcharges.
- Driver labor concentration:The US faces persistent shortages in commercial driver availability, limiting fleet expansion regardless of equipment access.
- California Advanced Clean Trucks rule:State-level zero-emission mandates fragment compliance pathways, forcing multi-state operators into bifurcated fleet strategies.
Strategic Opportunities
- India industrial corridors:Dedicated freight routes connecting Delhi-Mumbai and Chennai-Bengaluru remain underpenetrated by organized fleet operators.
- EU Green Deal mobility targets:Carbon intensity benchmarks create preference premiums for carriers with verified low-emission fleet credentials.
- Autonomous convoying:Platooning technology paired with telematics infrastructure is expanding into long-haul corridors with consistent traffic patterns.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems resist seamless API connectivity with shipper ERP platforms, delaying real-time data exchange.
- Alternative powertrain certification:Battery-electric and hydrogen fuel cell tractors face extended homologation timelines with the US NHTSA and state-level air quality boards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Full Truckload Transportation Market |
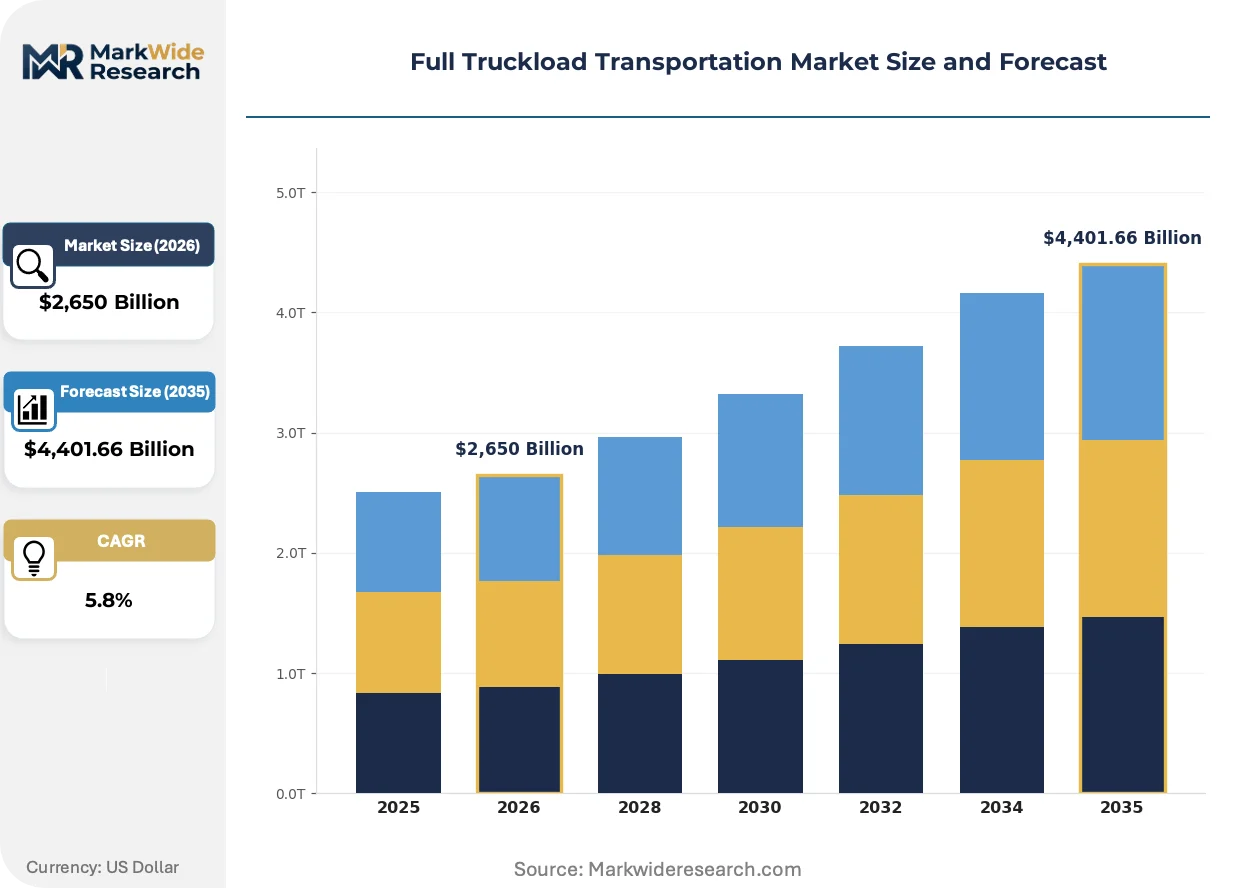
| Market Size in 2026 | $2,650 Billion |
| Market Size in 2035 | $4,401.66 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Long Haul, Regional, Expedited, Dedicated, Intermodal Application: Consumer Goods, Electronics, Machinery, Fresh Produce, Chemicals Customer Type: Manufacturers, Wholesalers, Distributors, Retailers, Third-Party Logistics Providers Vehicle Type: Dry Van, Refrigerated, Flatbed, Tanker, Curtain Side |
| Companies Covered | J.B. Hunt Transport Services, Werner Enterprises, Knight-Swift Transportation, US Xpress Enterprises, CRST International, Schneider National, Prime Inc., Crete Carrier Corporation, Landstar Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Full Truckload Transportation Market Shifts & Advancements
Digital freight matching is compressing transaction friction between shippers and carriers, while emissions monitoring tools and predictive maintenance systems reshape how fleet assets are deployed and valued.
Telematics-enabled predictive maintenance is expanding into tractor lifecycle management. Large shippers with dedicated fleet contracts are mandating real-time engine diagnostics and component wear monitoring as contract conditions. This capability is compressing unplanned downtime and shifting maintenance from calendar-based to condition-based intervals.
The EU AI Act's logistics monitoring provisions are tightening data governance requirements for cross-border hauliers. Carriers operating EU-UK corridors must now maintain auditable algorithmic decision trails for route optimization and driver scheduling. Refrigerated transport operators face the steepest compliance costs given temperature-sensitive cargo liability.
Shippers are consolidating procurement around contracted lane commitments rather than spot-market exposure. Consumer goods manufacturers with volatile demand patterns are shifting volume into dedicated fleet structures with guaranteed capacity provisions. This behavioral pivot is most visible in US Midwest distribution networks serving e-commerce fulfillment nodes.
Full Truckload Transportation Market Segmentation
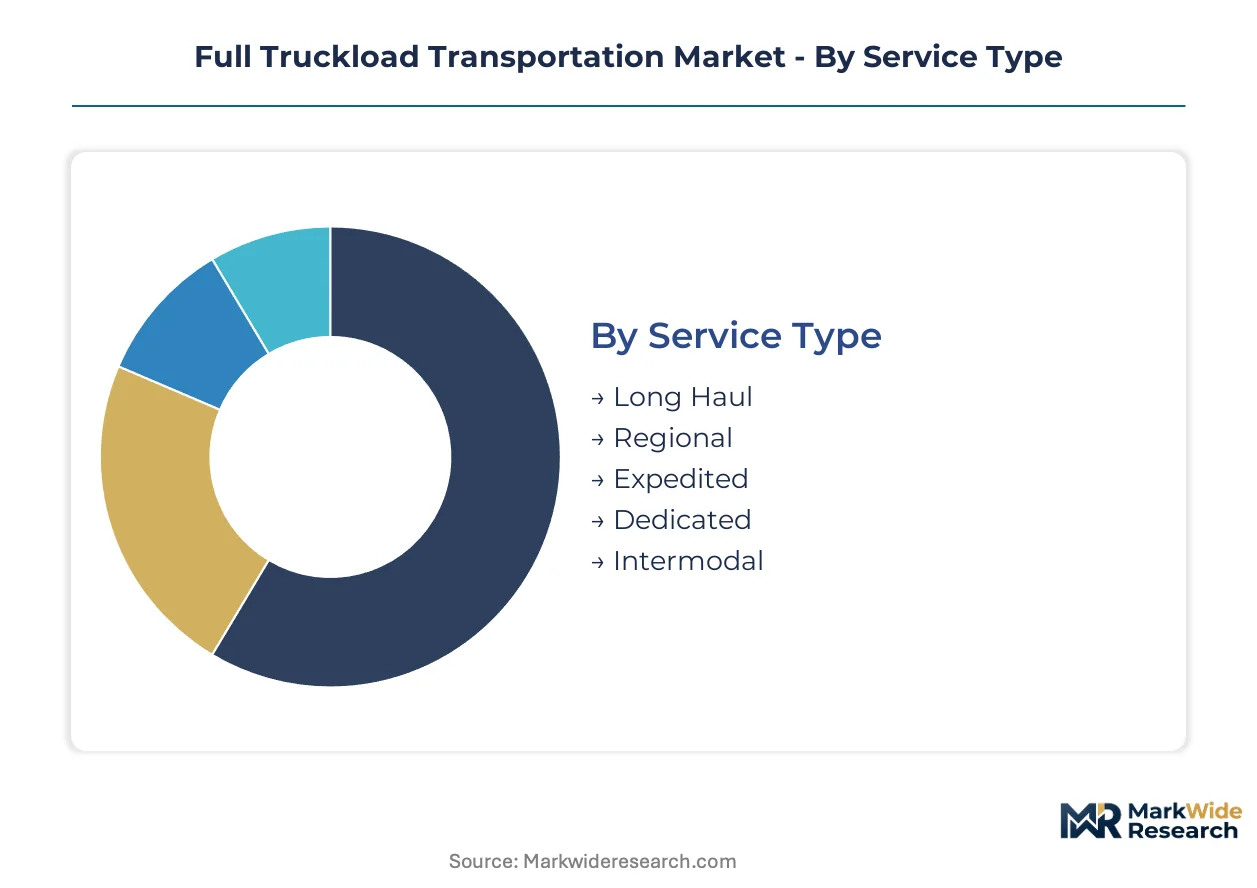
Full truckload transportation segments reflect divergent equipment economics and contract structures. Service type determines lane density and asset utilization rates. Application and customer type dictate scheduling flexibility and margin profiles.
Service Type:
Volume concentration sits with scheduled networks, while premium capture belongs to guaranteed-capacity offerings.
- Long Haul:Routes exceeding 250 miles per haul connect manufacturing clusters to port terminals and inland distribution hubs. Demand concentrates on China-to-coastal corridors and US Midwest-Southeast lanes where manufacturing output sustains consistent origin-destination pairings.
- Regional:Shorter-haul networks absorb e-commerce restocking cycles from distribution centers to last-mile nodes. This segment gains share fastest as retailers compress inventory positioning and demand predictable lane density within 150-mile radii.
- Expedited:Time-definite delivery for electronics and just-in-time machinery movements commands surcharge pricing.
- Dedicated:Exclusive fleet assignments for single shippers eliminate spot-market exposure.
- Intermodal:Rail-truck combinations reduce fuel cost exposure on corridors with parallel track infrastructure.
Today's leader: Regional. Tomorrow's challenger: Dedicated.
Application:
Margin structure separates temperature-sensitive cargo from standard dry freight.
- Consumer Goods:Packaged products moving through retail replenishment networks dominate trailer volume. Demand clusters in US Southeast distribution corridors serving e-commerce fulfillment nodes with predictable weekly cadences.
- Fresh Produce:Temperature-controlled transport from agricultural regions to processing centers and retail distribution commands equipment premiums. California's Central Valley and Florida's winter vegetable belts sustain dedicated refrigerated fleet deployment.
- Electronics:High-value, time-sensitive shipments from assembly plants to regional distribution centers.
- Machinery:Project-based movements of industrial equipment with specialized loading requirements.
- Chemicals:Hazmat-certified tanker and dry van movements with strict chain-of-custody protocols.
Consumer Goods anchors current volume. Fresh Produce offers the steepest expansion trajectory.
Customer Type:
Contract scale distinguishes national account structures from fragmented spot-market participants.
- Manufacturers:Original equipment producers and component suppliers with predictable production schedules generate baseline fleet utilization. Automotive assembly plants in Germany's Baden-Württemberg region and electronics foundries in China's Pearl River Delta sustain high-frequency lane contracts.
- Third-Party Logistics Providers:Asset-light intermediaries aggregate shipper demand and procure capacity from contracted carrier networks. 3PLs expand most quickly as mid-market manufacturers outsource fleet management and driver compliance burdens.
- Wholesalers:Intermediate buyers consolidating product from multiple manufacturers for redistribution.
- Distributors:Inventory-holding intermediaries with warehouse networks requiring scheduled replenishment.
- Retailers:Direct procurement by big-box and grocery chains with private fleet supplementation.
Manufacturers hold contracted capacity. 3PLs are capturing share from fragmented procurement.
Vehicle Type:
Equipment specialization creates tiered pricing aligned with cargo protection requirements.
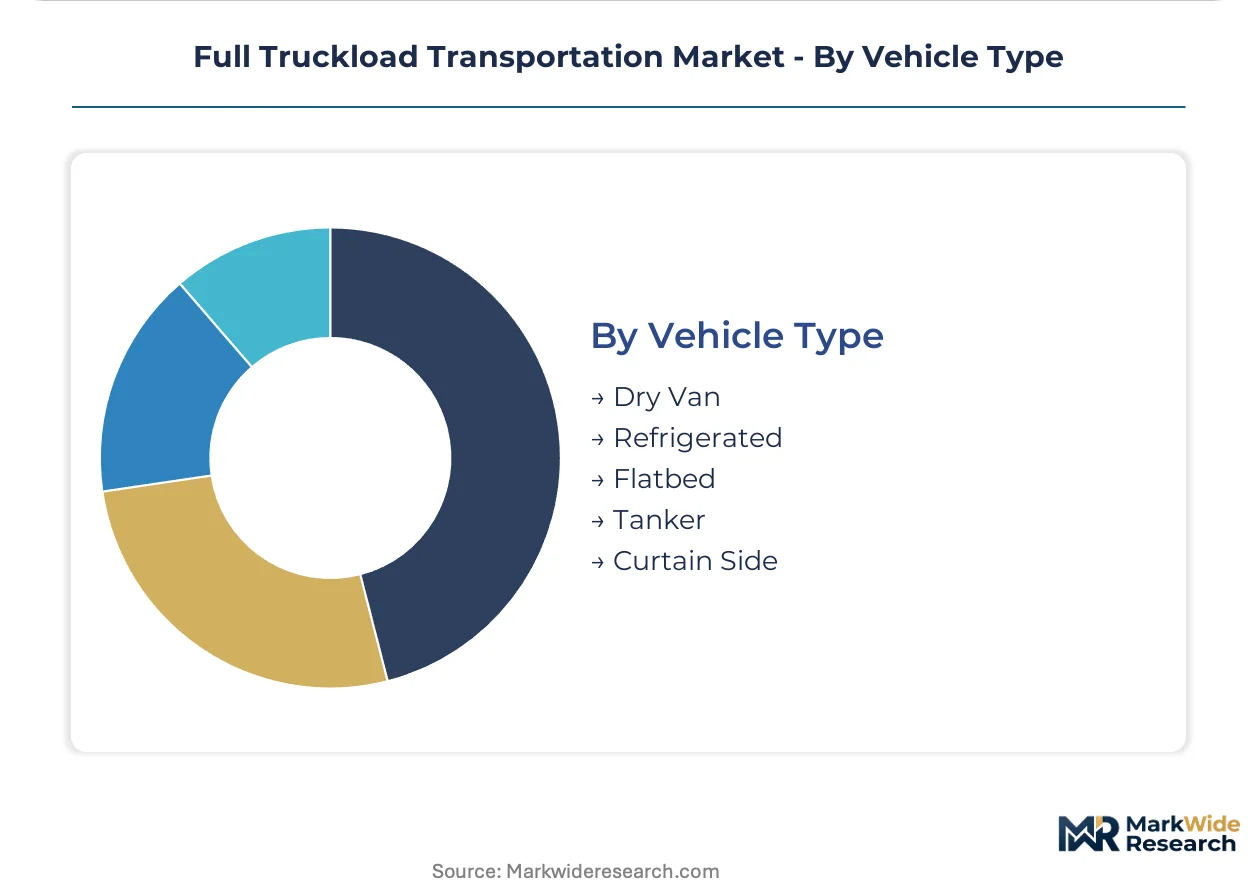
- Dry Van:Enclosed box trailers handle the majority of non-temperature-sensitive freight across consumer goods and packaged materials lanes. Dry van assets achieve highest utilization rates on dense corridors connecting China's manufacturing zones to Shanghai and Shenzhen port facilities.
- Refrigerated:Insulated trailers with integrated cooling systems serve fresh produce, pharmaceuticals, and temperature-controlled chemicals. Refrigerated units command 25-40% rate premiums over dry van equivalents due to equipment scarcity and fuel consumption.
- Flatbed:Open-deck trailers for machinery, building materials, and oversized loads requiring crane loading.
- Tanker:Liquid and gas bulk transport with specialized cleaning and certification protocols.
- Curtain Side:Flexible sidewall configurations enabling forklift access from trailer sides.
Dry Van dominates asset deployment. Refrigerated offers the strongest margin expansion pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers migrate freight corridors to exploit compliance-cost gaps between jurisdictions. Fleet operators now route through regions with deferred emissions mandates to preserve diesel asset utilization. This dynamic concentrates investment in corridors where enforcement timelines lag adoption curves.
United States
E-commerce fulfillment networks in the Midwest and Southeast sustain dense lane contracts between distribution centers and last-mile nodes. The EPA Phase 3 greenhouse gas standards accelerate tractor fleet renewal timelines, pressuring carriers to deploy compliant powertrains ahead of 2027 enforcement. Dallas-Fort Worth and Chicago anchor high-volume corridors where manufacturing output feeds retail replenishment cycles.
Germany
Automotive assembly plants in Baden-Württemberg generate predictable production schedules requiring just-in-time component delivery. The EU Green Deal's Fit for 55 framework imposes carbon intensity benchmarks on cross-border hauliers, creating preference premiums for low-emission fleet credentials. The Rhine-Ruhr and Stuttgart industrial regions sustain dedicated contract structures for tier-one supplier networks.
China
Manufacturing clusters in the Pearl River Delta and Yangtze River Delta sustain concentrated origin-destination pairings favoring full truckload economics. The Ministry of Ecology and Environment enforces dual carbon goals tightening heavy-duty freight emissions standards. Shanghai and Shenzhen port throughput drives high-volume lane density connecting inland production hubs to coastal export terminals.
India
Industrial corridors linking Delhi-Mumbai and Chennai-Bengaluru remain underpenetrated by organized fleet operators, creating expansion opportunities for contract logistics providers. The Bureau of Indian Standards and state transport authorities impose varying axle-load regulations fragmenting interstate compliance. Gujarat's manufacturing zones and Maharashtra's JNPT port complex anchor emerging dedicated fleet deployments.
Mexico
Nearshoring manufacturing investment in Nuevo León and the Bajío Region intensifies cross-border freight demand connecting to US distribution networks. The Secretariat of Environment and Natural Resources coordinates with US EPA standards on heavy-duty emissions compliance for binational operators. Monterrey and Guadalajara industrial parks sustain growing contract carrier presence serving automotive and electronics assembly.
Full Truckload Transportation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with asset-heavy carriers dominating scheduled networks while asset-light intermediaries capture fragmented spot-market demand. The vendor base concentrates around three tiers: national fleet operators with dedicated contract structures, regional specialists with lane-specific density, and digital freight platforms compressing transaction friction. Consolidation pressures favor scale-driven procurement of compliant powertrains and telematics infrastructure. Competitive positioning hinges on guaranteed capacity provisions and emissions-verified fleet credentials.
Within the national fleet operator tier, J.B. Hunt Transport Services and Knight-Swift Transportation occupy positions exemplifying integrated service models combining asset ownership with digital matching platforms. Schneider National represents the intermodal-dedicated hybrid archetype, embedding rail-truck combinations into long-term shipper contracts. These carriers anchor the competitive landscape through contracted lane commitments that displace spot-market exposure.
| Leading Market Players |
|---|
| J.B. Hunt Transport Services |
| Werner Enterprises |
| Knight-Swift Transportation |
| US Xpress Enterprises |
| CRST International |
| Schneider National |
| Prime Inc. |
| Crete Carrier Corporation |
| Landstar Systems |
| Others |
Supply & Pricing Matrix
Equipment-grade bifurcation between refrigerated and dry van assets creates divergent margin structures that reshape both rate-setting power and fleet procurement geography. Premium-credential carriers command rate advantages on temperature-controlled lanes while commodity dry van operators absorb fuel cost volatility through contract surcharge mechanisms.
Pricing Analysis
Distributor margin layers in 3PL-orchestrated freight absorb 8-12% of shipper spend before carrier payment. Contract-based long-term offtake dominates procurement, with volume scale and EPA Phase 3 compliance certification as the primary price differentiation drivers. Pricing pressure stems from diesel cost pass-through limitations in non-fuel-surcharged lanes. Mid-market manufacturers exhibit highest price sensitivity, while pharmaceutical cold chain shippers show least elasticity due to liability exposure.
Supply Chain Analysis
Direct-to-shipper dedicated contracts handle hyperscale retail replenishment demand, bypassing spot-market intermediaries. Tractor and trailer manufacturing concentrates in the United States, Mexico, and China. Diesel refining capacity, tire rubber supply, and semiconductor components for telematics systems constitute critical input dependencies. Single-source vulnerability in electronic logging device chips creates fleet deployment risk. Distribution runs through regional distribution center networks anchored by e-commerce fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Full truckload transportation operates as a geographic-arbitrage play where carriers route through jurisdictions with deferred zero-emission mandates to preserve diesel asset utilization against California's Advanced Clean Trucks rule compliance costs.
For Market Incumbents: Anticipate margin compression from digital freight platforms by embedding guaranteed capacity provisions into long-term shipper contracts. Secure backward integration into trailer manufacturing to control equipment replacement timelines. Prioritize EPA Phase 3 certification investment ahead of enforcement windows to capture compliant-asset scarcity premiums.
For New Entrants and Emerging Players: Capture underpenetrated dedicated fleet opportunities in India's Delhi-Mumbai industrial corridor where organized operators hold minimal share. Target refrigerated produce lanes from California's Central Valley where equipment scarcity sustains rate premiums. Deploy telematics-enabled condition-based maintenance as the go-to-market differentiator against legacy calendar-based competitors.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized regional carriers lack capital for compliant powertrain procurement and telematics infrastructure. The 5-10 year viability window favors asset-heavy operators with contracted lane density over spot-market-dependent fleets. Target acquisition archetypes: refrigerated specialists with temperature-verified credentials. Watch EPA enforcement timeline adherence as the inflection signal for stranded diesel asset risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliant Powertrain Procurement | EPA Phase 3 certification locks in shipper contract eligibility ahead of enforcement deadlines. |
| Telematics Platform Integration | J.B. Hunt 360-style matching layers compress transaction friction into retained margin. |
| Intermodal Rail Partnership | Rail-truck combinations on Chicago-Los Angeles corridors reduce fuel cost exposure. |
| Dedicated Fleet Contract Expansion | Exclusive shipper assignments eliminate spot-market volatility and stabilize utilization rates. |
| Refrigerated Equipment Scale-Up | Insulated trailer scarcity in produce belts commands 25-40% rate premiums over dry van. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged fleet operations directors, shipper procurement leads at consumer goods manufacturers, 3PL contract managers, and commercial driver training administrators. Secondary validation drew from FMCSA carrier safety data, EPA emissions certification filings, ATA freight economic indices, and customs port throughput records. Bottom-up lane density modeling and top-down market sizing triangulated volume estimates.
Historical reference periods anchored the projection horizon to observed fleet renewal cycles and regulatory phase-in timelines. Segmentation dimensions modeled include service type, equipment configuration, customer contract structure, and regional regulatory cluster. CAGRs derived from equipment deployment trajectories and shipper procurement pattern shifts. Forecast inputs incorporated diesel price scenario bands and driver availability demographic projections.
Regulatory enforcement delays, alternative powertrain homologation setbacks, and autonomous platooning technology adoption rates are the dominant revision risks. Forecasts reflect documented assumptions about shipper contract duration preferences and carrier consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Europe Medium and Heavy-Duty Commercial Vehicles Market
Heavy-Duty Trucks
Tipper Truck Market
Heavy-Duty Trucks
Truck Racks Market
Heavy-Duty Trucks
Flatbed Truck Market
Heavy-Duty Trucks
United States Tank Trucking Market
Heavy-Duty Trucks
India Vacuum Truck Market
Heavy-Duty Trucks
Poly Trucks Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market