
 Heavy-Duty Truck Load and Axle Weight Sensor Systems Market | 2026-2036
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market Insights
Market Dynamics
Modular sensor bundling is expanding as fleet procurement teams increasingly specify combined axle-load and tire-pressure monitoring packages from single vendors. Kistler Group leverages its piezoelectric manufacturing depth to anchor premium onboard configurations for Class 8 line-haul tractors. TE Connectivity competes through strain gauge specialization across embedded weighbridge architectures. Intercomp differentiates with portable calibration systems that reduce installation downtime for transportation contractors.
Technology and Segmentation
Heavy-duty truck load and axle weight sensor systems comprise electromechanical transducers, signal conditioning modules, and telemetry interfaces engineered to measure static and dynamic axle forces within ±0.25% accuracy for vehicles exceeding 26,000 pounds gross vehicle weight. These systems enforce bridge formula compliance, prevent cargo overload, and extend infrastructure service life across interstate corridors and port access routes. Strain gauge technology dominates embedded and in-ground installations where durability under cyclic loading determines replacement cycles. Piezoelectric arrays lead portable and remote monitoring deployments favored by enforcement agencies and freight terminals. MEMS-based configurations represent the fastest-growing installation type as semiconductor packaging reduces per-axis cost for vocational and dump truck fleets.
Regulatory Environment
The Federal Motor Carrier Safety Administration and state departments of transportation mandate axle weight compliance through roadside inspection protocols, while the European Union's Weigh-in-Motion directive standardizes enforcement technology across member state border crossings. NHTSA's underride guard and braking performance rules indirectly intensify load distribution verification requirements for domestic carriers. Stakeholders must monitor pending revisions to federal bridge formula tables and emerging state-level per-mile weight taxation pilots that would reshape sensor deployment economics.
Market Dynamics
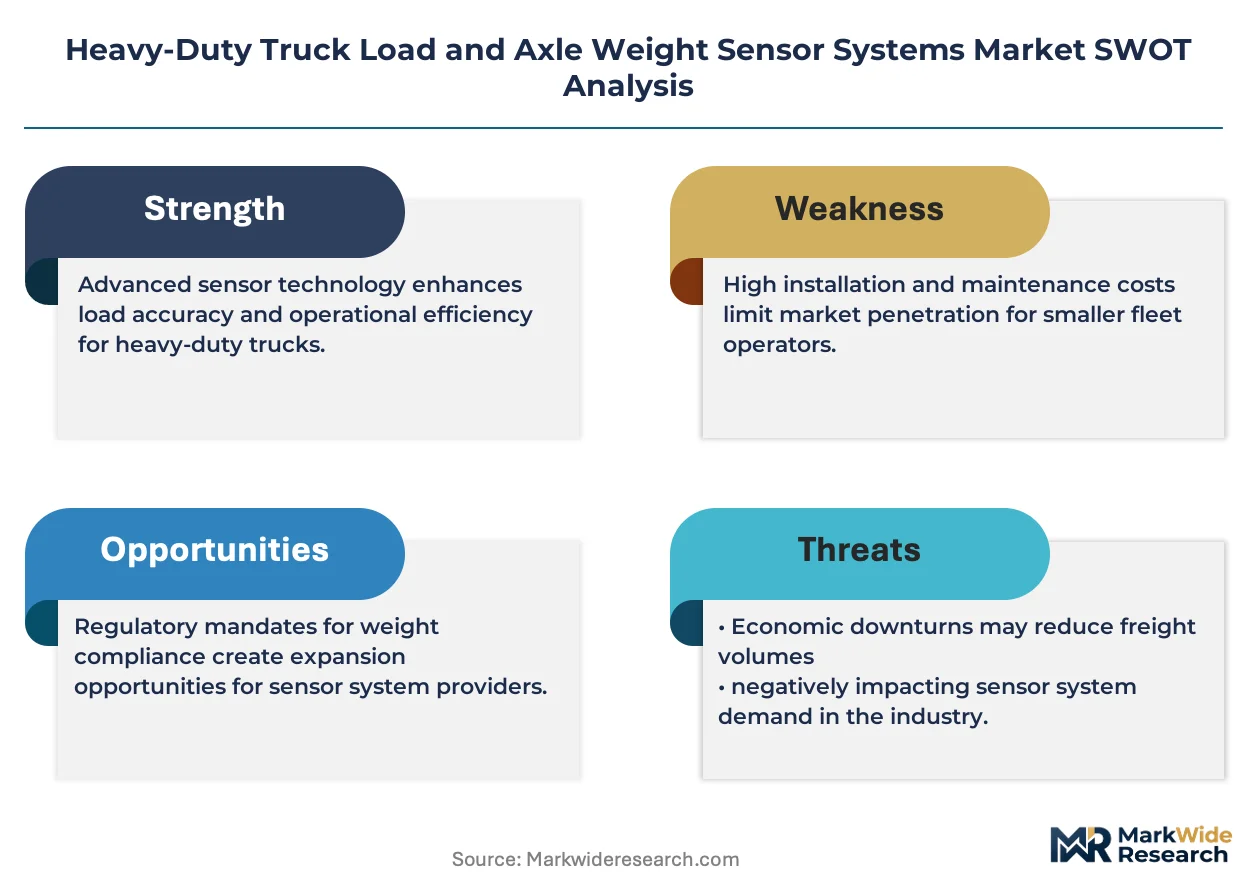
Fleet procurement teams now specify integrated axle-load and tire-pressure packages from single vendors, compressing supplier relationships and forcing sensor manufacturers to bundle electromechanical transducers with telemetry modules under unified warranties.
Growth Catalysts
- Bridge Formula Enforcement:The Federal Motor Carrier Safety Administration's roadside inspection protocols mandate real-time axle weight verification, compelling long-haul carriers to install onboard strain gauge systems before interstate corridor access.
- Piezoelectric Arrays:Enforcement agencies and port terminals favor portable WIM deployments using quartz sensor strips for dynamic weighing at speeds up to 80 mph, displacing static scale infrastructure.
- MEMS Semiconductor Packaging:Silicon foundries now produce microelectromechanical load cells at unit costs viable for vocational dump truck fleets, opening sensor adoption to owner-operators previously priced out of embedded systems.
Market Restraints
- Strain Gauge Calibration Drift:Electromechanical transducers require recertification every 18-24 months under cyclic loading conditions, creating recurring service costs that deter small fleet adoption.
- Raw Material Concentration:High-purity quartz crystal supply for piezoelectric wafers concentrates in limited extraction regions, exposing sensor manufacturers to input volatility and long lead times.
- Mechanical System Persistence:Legacy spring-scale and hydraulic load cell installations in municipal weigh stations resist replacement due to capital budget constraints and maintenance staff familiarity.
Strategic Opportunities
- State Per-Mile Taxation Pilots:Oregon and Utah weight-distance levy experiments create demand for certified onboard weighing as audit evidence, positioning sensor vendors as compliance infrastructure providers.
- Telematics Convergence:Integration of axle load data with fleet management platforms and predictive maintenance algorithms enables subscription-based analytics revenue beyond hardware sales.
- Autonomous Truck Pre-Loading:Self-driving freight terminals require automated weight verification before dispatch, creating specification pull from robotruck developers and their logistics partners.
Industry Challenges
- Signal Conditioning Expertise:Shortage of analog electronics engineers capable of designing noise-resistant Wheatstone bridge amplifiers delays product development cycles for Tier 2 sensor suppliers.
- ISO 9001 Certification Burden:Transportation authorities require quality management system documentation for sensor approval, extending time-to-market for startups by 12-18 months.
- Legacy Fleet Integration:CAN bus protocol fragmentation across truck OEMs forces sensor vendors to maintain multiple firmware branches, inflating engineering overhead and support complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Duty Truck Load and Axle Weight Sensor Systems Market |
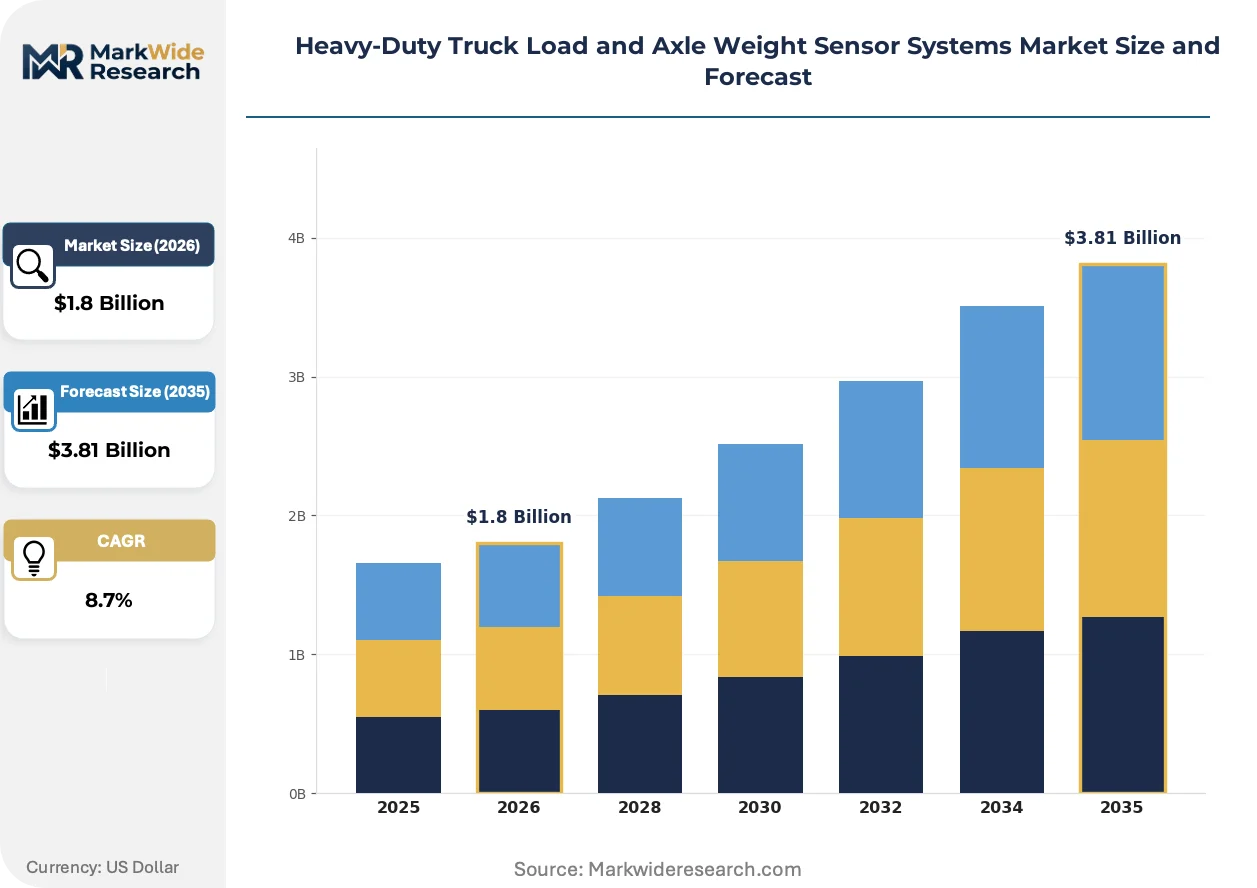
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Technology: Piezoelectric, Capacitive, Strain Gauge, Fiber Optic, MEMS Installation Type: Onboard, In-ground, Portable, Embedded, Remote Truck Classification: Class 6, Class 7, Class 8, Vocational Trucks, Dump Trucks End User Segment: Logistics Providers, Fleet Operators, Freight Carriers, Transportation Contractors |
| Companies Covered | Kistler Group, Siemens Mobility, Kapsch TrafficCom, Q-Free ASA, SWARCO AG, International Road Dynamics, Intercomp, TE Connectivity, Mettler Toledo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market Trends and Innovations
Sensor architecture is fragmenting into interoperable subsystems as fleet buyers demand mix-and-match compatibility between transducer hardware, wireless telemetry, and cloud analytics platforms from competing vendors.
Silicon carbide MEMS load cells are modularizing across vocational truck segments. Dump truck and refuse hauler fleets in Texas and Alberta now specify semiconductor-based axle sensors as factory options. This technology is modularizing the supplier base, allowing fleet managers to source transducers, signal processors, and dashboard interfaces from separate vendors rather than locked proprietary stacks.
The European Union's Weigh-in-Motion directive standardizes enforcement technology specifications across member state border crossings. Truck sensor manufacturers must now certify to unified quartz strip and piezoelectric cable standards to access the continental market. German freight corridors and Dutch port access routes are deploying harmonized WIM infrastructure, forcing non-compliant legacy installations into retrofit cycles.
Fleet maintenance departments now unbundle sensor calibration from original equipment supply contracts. Third-party metrology services in Ohio and Illinois capture recurring revenue from transportation contractors seeking to minimize installation downtime. This service disintermediation concentrates in North American long-haul corridors where uptime metrics dominate procurement evaluation.
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market Segmentation
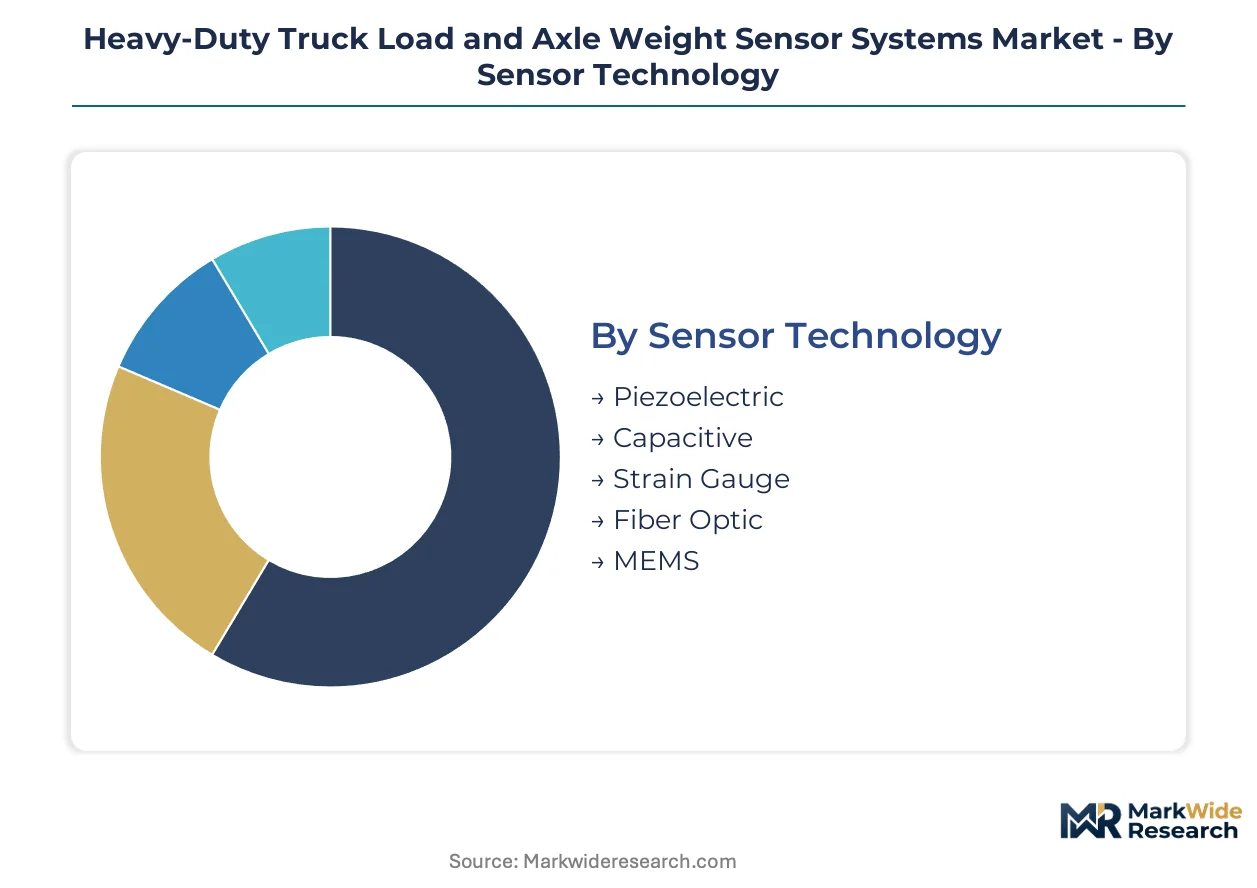
Sensor deployment patterns diverge sharply between long-haul compliance mandates and vocational flexibility requirements. Fleet procurement teams now specify bundled configurations that cross technology, installation, and vehicle class boundaries rather than purchasing standalone components.
Sensor Technology:
Standardization pressures from enforcement agencies favor proven electromechanical platforms, while MEMS packaging opens semiconductor economics to price-sensitive owner-operators.
- Piezoelectric:Quartz crystal arrays generate charge signals proportional to dynamic axle loading with microsecond response times. Enforcement agencies along German autobahns and Dutch port corridors specify these strips for high-speed Weigh-in-Motion verification.
- Strain Gauge:Metallic foil resistors bonded to steel load cells measure static weight through Wheatstone bridge circuits with ±0.25% accuracy. North American Class 8 fleets embed these in chassis frames to satisfy FMCSA roadside inspection protocols.
- Capacitive:Dielectric displacement sensors suit food-grade and chemical transport trailers requiring corrosion resistance.
- Fiber Optic:Bragg grating configurations tolerate electromagnetic interference in electric truck prototypes.
- MEMS:Silicon foundry production reduces per-axis costs below embedded system thresholds.
Most installed capacity flows through Strain Gauge. Expansion is steepest in MEMS.
Installation Type:
Capital intensity and uptime requirements determine whether fleets favor permanent infrastructure or mobile verification assets.
- Onboard:Chassis-integrated transducer arrays with CAN bus telemetry enable real-time payload monitoring during transit. Freight carriers traversing Oregon and Utah weight-distance tax corridors require certified onboard systems as audit documentation.
- In-ground:Concrete-embedded quartz strip networks at weigh stations capture axle weights without stopping traffic. State transportation departments in Texas and California deploy these for bridge formula enforcement.
- Portable:Battery-powered pad scales allow transportation contractors to verify loads at remote construction sites.
- Embedded:Factory-installed configurations reduce field calibration complexity for OEM delivery.
- Remote:Solar-powered telemetry nodes transmit weight data from unmanned port terminals.
Volume concentrates in Onboard installations. Gaining share fastest is Portable.
Truck Classification:
Regulatory thresholds and duty cycles fragment sensor specifications across gross vehicle weight ratings.
- Class 8:Vehicles exceeding 33,000 pounds gross vehicle weight face the strictest axle load enforcement. Interstate line-haul tractors require redundant sensor arrays with FMCSA-compliant calibration certificates.
- Vocational Trucks:Refuse haulers and concrete mixers operate in stop-start cycles that accelerate mechanical fatigue. MEMS-based configurations suit these applications where embedded system costs previously prohibited adoption.
- Class 6:Medium-duty delivery trucks face lighter enforcement scrutiny.
- Class 7:Regional freight carriers balance payload optimization against sensor capital expenditure.
- Dump Trucks:Unloading shock loads demand reinforced transducer housings.
Class 8 dominates unit deployments. Vocational Trucks show the steepest expansion trajectory.
End User Segment:
Procurement sophistication varies from centralized fleet specifications to contractor spot purchases.
- Fleet Operators:Asset managers at large for-hire carriers standardize onboard configurations across thousands of tractors. Unified warranties covering transducers, telemetry, and cloud analytics compress supplier relationships toward single-vendor contracts.
- Logistics Providers:Third-party freight brokers specify weight verification at pickup to prevent downstream penalty exposure.
- Freight Carriers:Owner-operators prioritize portable calibration systems minimizing installation downtime.
- Transportation Contractors:Construction and energy sector haulers favor modular sensor packages compatible with mixed equipment fleets.
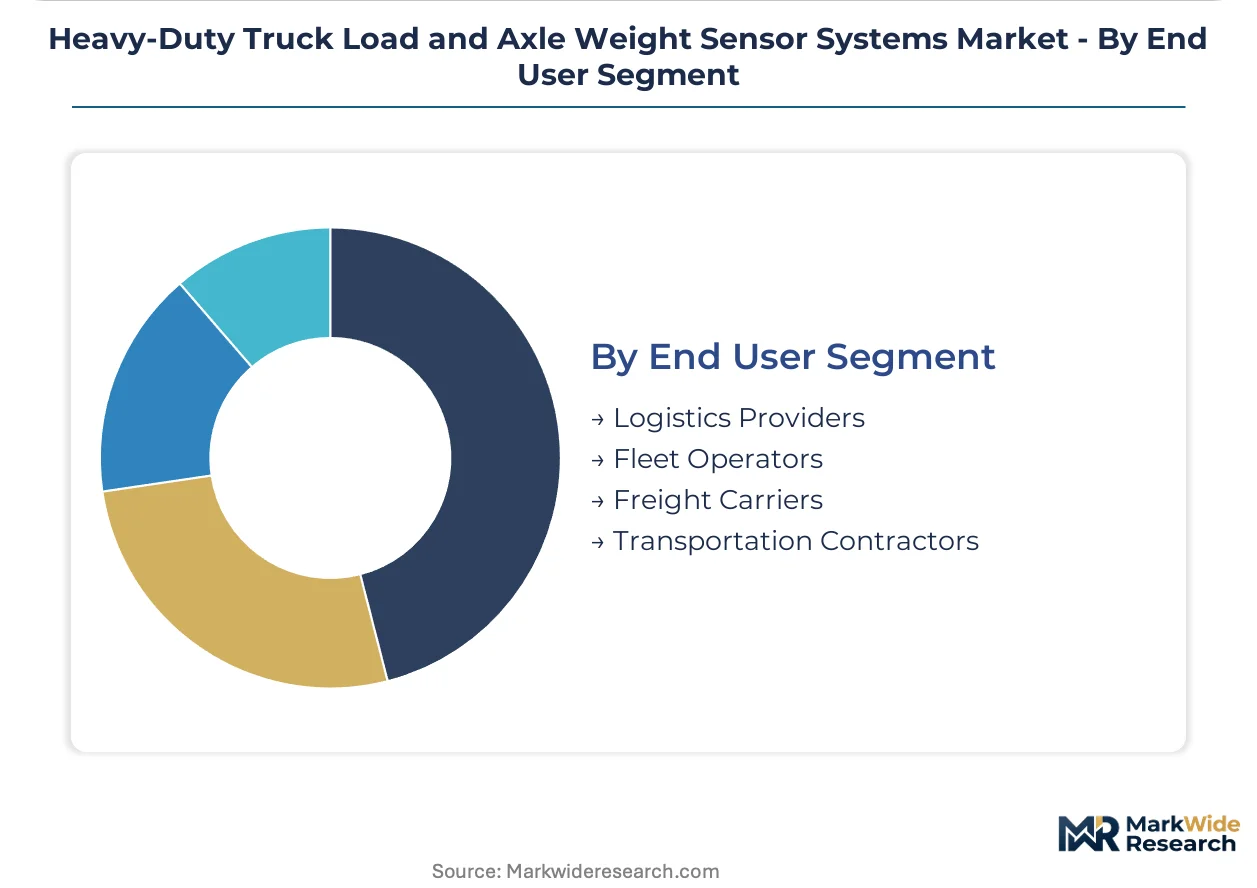
Fleet Operators account for the largest installed base. Logistics Providers are expanding sensor specifications fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Onboard weighing technology first achieved commercial scale along German autobahns and Dutch freight corridors during the 1990s Weigh-in-Motion standardization push. The industry subsequently expanded across North American interstate systems and Asian port networks. Today, sensor deployment patterns reflect distinct regulatory enforcement intensities and infrastructure investment cycles across national markets.
United States
Class 8 line-haul fleets dominate sensor procurement as FMCSA roadside inspection protocols mandate real-time axle weight verification. The Federal Motor Carrier Safety Administration enforces bridge formula compliance through automated inspection stations across Interstate 10 and Interstate 80 corridors. Dallas-Fort Worth freight terminals concentrate OEM sensor installations for regional distribution networks.
Germany
Enforcement agencies specify quartz strip arrays for high-speed dynamic weighing at autobahn access points. The EU Weigh-in-Motion directive harmonizes certification requirements across member state border crossings. Stuttgart industrial clusters host calibration service providers supporting cross-border freight operators.
China
Port automation drives demand for embedded sensor networks at Shanghai and Ningbo container terminals. MIIT standards govern telematics integration for domestic heavy-duty truck manufacturers. Yangtze River Delta manufacturing bases produce MEMS load cells for vocational dump truck fleets.
Japan
Precision agriculture and construction equipment sectors adopt fiber-optic sensors for electromagnetic immunity. METI carbon neutrality targets accelerate electric truck prototype testing with integrated weight verification. Nagoya industrial corridors concentrate sensor foundry capacity for semiconductor-based configurations.
India
National highway expansion projects embed in-ground weighing systems at toll plaza locations. BIS certification requirements for automotive components extend to onboard sensor modules. Gujarat freight corridors connect manufacturing zones to Mundra port with automated weight enforcement.
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology specialization and calibration service depth. The vendor base organizes into three tiers: piezoelectric quartz specialists commanding enforcement agency contracts, strain gauge fabricators serving embedded fleet installations, and MEMS semiconductor foundries penetrating vocational truck price points. Consolidation pressures intensify as fleet procurement teams compress supplier relationships toward single-vendor bundled warranties. Dominant competitive moves include backward integration into quartz crystal supply and geographic expansion through third-party metrology service acquisitions.
Within the piezoelectric tier, Kistler Group exemplifies premium positioning through manufacturing depth in quartz sensor arrays. Among North American calibration specialists, Intercomp occupies a service-differentiation position. TE Connectivity represents the strain gauge fabrication archetype with embedded system specialization. These three anchors illustrate how technology lineage shapes competitive positioning across enforcement, fleet, and semiconductor market vectors.
| Leading Market Players |
|---|
| Kistler Group |
| Siemens Mobility |
| Kapsch TrafficCom |
| Q-Free ASA |
| SWARCO AG |
| International Road Dynamics |
| Intercomp |
| TE Connectivity |
| Mettler Toledo |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon-border adjustment requirements gate qualified supply and premium-tier pricing access for heavy-duty truck sensor manufacturers, as only vendors with certified low-carbon quartz crystal sourcing and ISO 14001 environmental management systems qualify for German autobahn enforcement contracts and Dutch port terminal specifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FMCSA-certified onboard systems from commercial-grade fleet installations and uncertified aftermarket modules. Price differentiation hinges on calibration certificate tier and after-sales service bundling. Cost compression in the economy tier is intensifying because MEMS foundries in Taiwan and China are flooding vocational truck segments with sub-hundred-dollar per-axis units. Fleet operators show least price sensitivity for embedded Class 8 configurations, while owner-operators in dump truck and refuse hauler segments drive volume at entry price points.
Supply Chain Analysis
Freight costs from high-purity quartz extraction regions in Brazil and Madagascar to sensor fabrication facilities in Germany and Switzerland add 12-15% to piezoelectric wafer landed costs. Raw material dependencies center on synthetic quartz crystal boules, semiconductor-grade silicon wafers, and specialty steel alloys for load cell housings. Single-source vulnerability concentrates in Brazilian quartz mines controlled by three extraction consortiums. Distribution runs through OEM direct contracts for embedded installations and specialized metrology service providers for aftermarket calibration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: Oregon and Utah weight-distance tax pilots create certified onboard demand at 40% premium pricing versus uncertified Mexican aftermarket imports facing NHTSA enforcement gaps.
For Market Incumbents: Anchor premium positioning through backward integration into quartz crystal supply and captive calibration service networks in Ohio and Illinois. Defend against MEMS semiconductor entrants by accelerating FMCSA certification cycles and locking fleet operators into unified warranty contracts covering transducers, telemetry, and cloud analytics. Capacity addition in Stuttgart industrial clusters supports cross-border EU enforcement contract capture. For New Entrants and Emerging Players: Begin with vocational dump truck fleets in Texas and Alberta where factory-option MEMS specifications are displacing embedded strain gauge retrofits. Target third-party metrology services in North American long-haul corridors where fleet maintenance departments unbundle calibration from original equipment supply contracts. A direct-to-fleet SaaS telemetry play bypasses incumbent hardware bundling. For Investors and Strategic Acquirers: Roll-up economics work for regional calibration specialists because fragmented third-party metrology services in Ohio, Illinois, and Stuttgart lack scale to negotiate OEM warranty partnerships. Long-term viability rests on telematics convergence subscription revenue exceeding hardware depreciation cycles. Watch for state-level per-mile weight taxation pilots expanding beyond Oregon and Utah as inflection indicator for certified onboard system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Supply | Kistler Group's captive Brazilian mine access locks piezoelectric wafer costs below spot-market volatility. |
| Telematics Platform Convergence | Integration of axle load data with fleet management systems enables recurring SaaS revenue beyond hardware sales. |
| MEMS Foundry Partnership | Taiwan semiconductor packaging partnerships reduce per-axis costs for vocational truck price-point penetration. |
| Third-Party Metrology Acquisition | Ohio and Illinois calibration service buyouts compress fleet installation downtime and capture recurring revenue. |
| EU WIM Directive Certification | Harmonized quartz strip standards unlock German autobahn and Dutch port enforcement agency contracts. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each market combining interviews with fleet procurement directors, sensor manufacturer product managers, state transportation department enforcement officers, and third-party metrology service operators. Secondary validation draws from FMCSA roadside inspection protocols, EU Weigh-in-Motion directive documentation, MIIT telematics integration standards, and SEC filings from publicly traded sensor technology vendors. Bottom-up unit deployment estimates triangulate against top-down fleet penetration assumptions.
Granularity-level modeling segments the market by sensor technology, installation type, truck classification, and end user segment at the country level, with technology-specific adoption curves calibrated to enforcement mandate implementation timelines. CAGRs derive from logistic diffusion models fitted to historical Weigh-in-Motion deployment patterns and projected fleet replacement cycles. Industry-specific forecast inputs include bridge formula enforcement intensity indices and weight-distance tax pilot expansion probabilities.
Caveats apply where pending revisions to federal bridge formula tables or state-level per-mile weight taxation scaling could materially shift the outlook for onboard system deployment economics. Forecasts reflect assumptions about MEMS cost reduction trajectories and quartz crystal supply stability. A model refresh is warranted upon material change in FMCSA roadside inspection automation funding or EU carbon-border adjustment enforcement scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Fire Trucks Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Garbage Collection Trucks Market
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
Malaysia Fire Truck Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Full Truckload Transportation Market
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
Europe Medium and Heavy-Duty Commercial Vehicles Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market