
 Truck Tank Market | 2026-2036
Truck Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Tank Market Analytics
Certified welder availability for aluminum tank fabrication is collapsing across Midwestern US manufacturing zones. Daimler Truck AG leverages captive stamping capacity to secure tank shell supply chains. Volvo Trucks anchors its position through in-house testing protocols for chemical tank pressure ratings. Tata Motors competes on cost-optimized steel tank variants for emerging market logistics operators.
A truck tank is a cylindrical or rectangular vessel mounted on commercial vehicle chassis, typically fabricated from carbon steel, aluminum alloy, or high-density polyethylene, designed to contain liquids or gases under pressure or atmospheric conditions for over-the-road transport. Fuel tanks dominate product type volume due to diesel and alternative-fuel powertrain proliferation, while composite material tanks command premium positioning in corrosive chemical applications. Transportation application demand leads absolute volume, though firefighting segment tanks sustain higher per-unit margins through specialized NFPA certification requirements.
EPA emissions regulations and DOT hazardous materials standards govern US tank construction, testing, and retirement schedules, directly influencing replacement demand cycles. ECE R34 and ADR certification frameworks in Europe mandate specific crash-resistance and leakage thresholds for cross-border tank operations. Stakeholders must monitor evolving low-carbon fuel compatibility standards and assess material transition timelines between conventional steel and emerging composite alternatives.
Market Dynamics
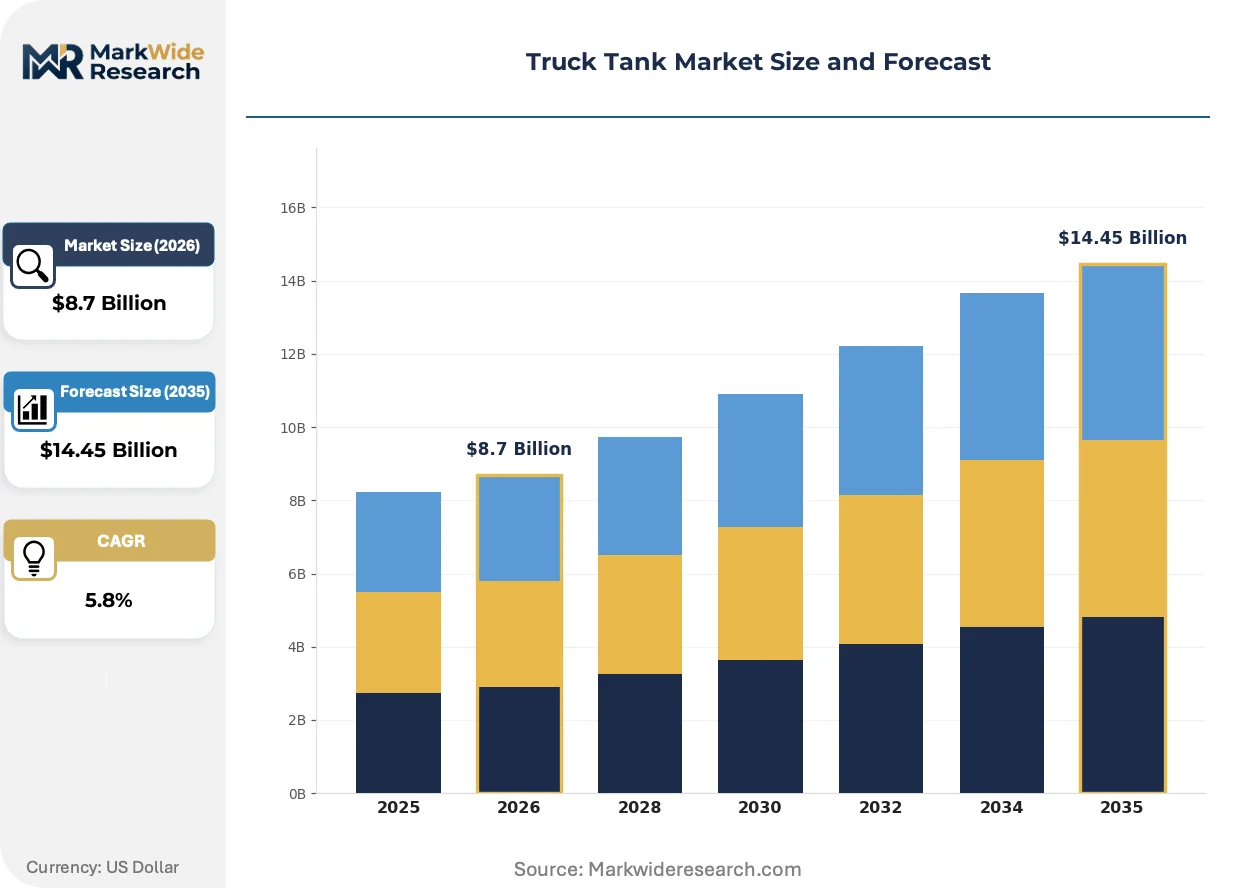
EPA emissions standards and DOT hazardous materials rules are compressing tank replacement cycles while certified aluminum welder shortages concentrate fabrication capacity in captive manufacturing clusters.
Growth Catalysts
- DOT Hazardous Materials Regulations:Tightened testing and retirement schedules force earlier tank replacements across chemical transport fleets.
- Alternative Fuel Powertrain Proliferation:Diesel and hydrogen fuel systems require specialized tank architectures with pressure-rated specifications.
- Midwestern US Manufacturing Zones:Chemical transport fleet expansion drives demand for aluminum tank fabrication capacity.
Market Restraints
- Certified Welder Scarcity:Aluminum tank fabrication requires specialized welding certifications that face collapsing availability.
- Steel Price Volatility:Carbon steel input costs fluctuate with raw material markets, pressuring cost-optimized tank margins.
- High-Density Polyethylene Substitution:Corrosion-resistant polymer tanks threaten metal tank share in non-pressurized chemical applications.
Strategic Opportunities
- Emerging Market Logistics:Steel tank variants serve cost-sensitive operators in India and Brazil with localized fabrication.
- Composite Material Convergence:Fiber-reinforced polymers combined with aluminum liners enable lightweight corrosive chemical transport.
- NFPA Firefighting Certification:Specialized pressure-rated tanks command premium positioning in municipal procurement.
Industry Challenges
- Multi-Regulatory Certification Timelines:ECE R34, ADR, and DOT approvals require parallel testing protocols that extend product launch schedules.
- Legacy Fleet Integration Complexity:New tank specifications must interface with existing chassis mounting systems and pressure monitoring hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Tank Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Tanks, Water Tanks, Chemical Tanks, Pressure Tanks Application: Transportation, Agriculture, Construction, Firefighting Material: Steel, Aluminum, Plastic, Composite Size: Small, Medium, Large, Extra Large |
| Companies Covered | Daimler Truck AG, Volvo Trucks, PACCAR, Tata Motors, Kenan Advantage Group, Trimac Transportation, Isuzu Motors, Mahindra and Mahindra, Shacman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Tank Market Evolving Landscape
Material science advances and regulatory pressure are reconfiguring tank fabrication methods while procurement patterns favor integrated testing and certification capabilities.
Filament-wound composite tanks with aluminum liners are supplanting conventional steel vessels in corrosive chemical transport. Specialty chemical haulers in Germany and the Netherlands adopt these systems for sulfuric acid and caustic soda routes. The shift is compressing demand for traditional carbon steel tank shells in premium chemical applications.
EPA greenhouse gas emissions standards for heavy-duty vehicles now incorporate tank vapor recovery and permeation thresholds. Tank manufacturers must redesign fuel system architectures to meet evaporative emission limits. Chemical transport operators in California face the most stringent implementation timelines.
Integrated procurement contracts bundle tank fabrication with in-house pressure testing and certification documentation. Fleet operators bypass independent testing laboratories to compress delivery schedules. This pattern concentrates in United States chemical transport and German bulk liquid logistics.
Truck Tank Market Segmentation
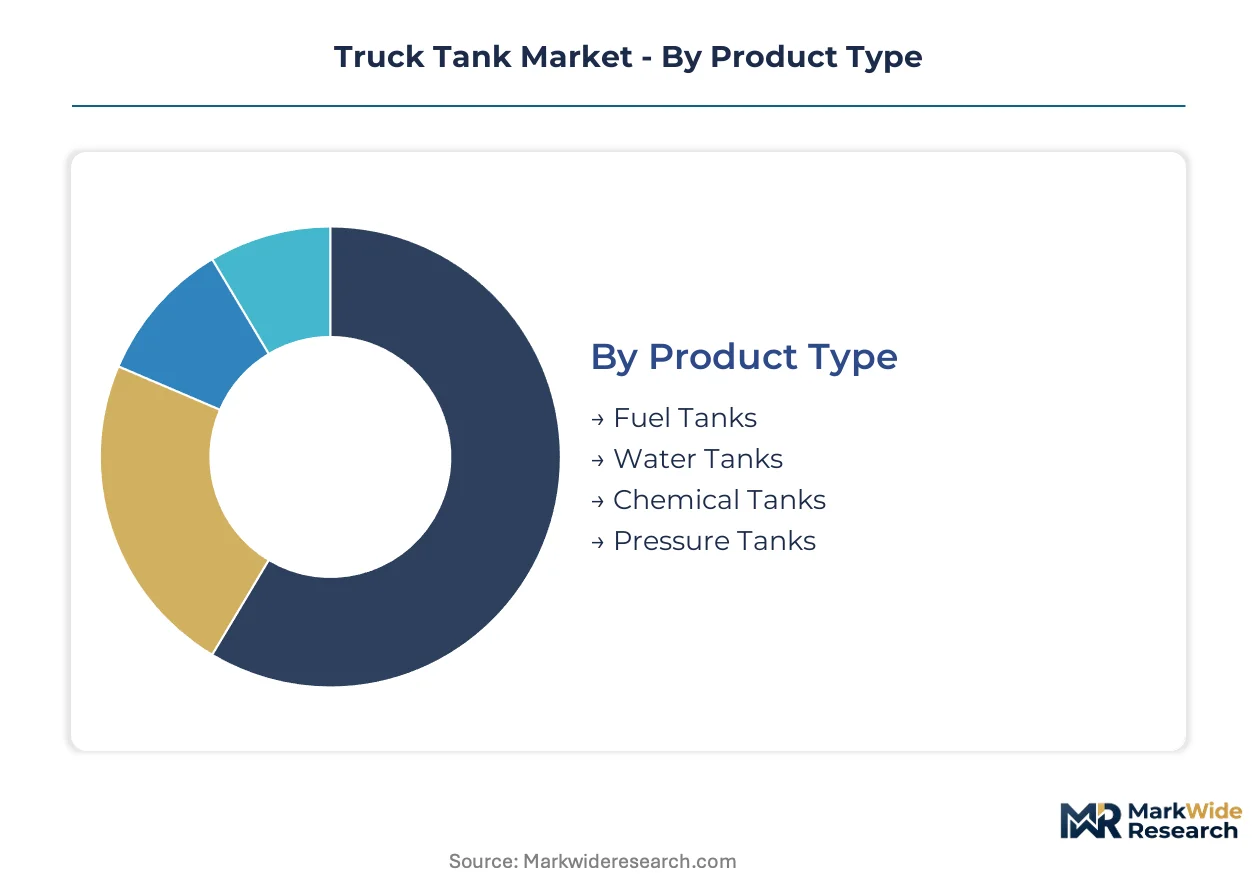
Tank procurement patterns diverge sharply across end-use applications, with chemical transport operators prioritizing certified fabrication while fuel system integrators emphasize vapor recovery compliance. Material selection and size classification determine channel access and margin structure for fabricators.
Product Type:
Fuel tanks and chemical tanks move through distinct distribution channels, with OEM chassis integrators dominating fuel system volumes and specialized tank fabricators serving chemical fleet direct procurement.
- Fuel Tanks:Cylindrical or rectangular vessels engineered for diesel, gasoline, or alternative fuel containment, incorporating vapor recovery systems and permeation barriers. Demand concentrates in United States heavy-duty vehicle manufacturing zones where EPA greenhouse gas standards mandate evaporative emission controls.
- Chemical Tanks:Pressure-rated or atmospheric vessels fabricated with corrosion-resistant linings for hazardous liquid transport. German and Dutch specialty chemical haulers drive specification intensity through ADR certification requirements for sulfuric acid and caustic soda routes.
- Water Tanks:Atmospheric vessels for municipal and agricultural liquid transport, typically polyethylene or coated steel construction.
- Pressure Tanks:ASME-coded vessels for compressed gas and cryogenic applications, requiring specialized welding protocols.
By volume, fuel tanks lead. By growth pace, chemical tanks are expanding most quickly.
Application:
End-use segmentation determines certification burden and replacement cycle length, with firefighting applications commanding premium positioning through specialized testing protocols.
- Transportation:Over-the-road liquid and gas logistics serving chemical, petroleum, and food-grade supply chains. United States chemical transport fleet expansion in Midwestern manufacturing zones sustains aluminum tank demand despite certified welder scarcity.
- Firefighting:NFPA-certified pressure-rated tanks for municipal emergency response vehicles. Higher per-unit margins reflect specialized testing documentation and limited qualified supplier base.
- Agriculture:Non-pressurized tanks for fertilizer, water, and fuel distribution across seasonal operational cycles.
- Construction:Mobile fuel and water service tanks for equipment refueling and dust suppression operations.
Transportation dominates absolute volume. Firefighting claims the steepest margin premium.
Material:
Material selection tracks regulatory pressure and weight optimization priorities, with composite convergence threatening conventional metal dominance in corrosive applications.
- Steel:Carbon steel construction for cost-optimized fuel and water applications. Tata Motors leverages localized fabrication for emerging market logistics operators in India and Brazil.
- Aluminum:Lightweight alloy fabrication for chemical transport and weight-sensitive fuel applications. Daimler Truck AG secures supply through captive stamping capacity as certified welder availability collapses.
- Plastic:High-density polyethylene rotationally molded tanks for non-pressurized agricultural and water applications.
- Composite:Filament-wound fiber-reinforced polymers with aluminum liners enabling lightweight corrosive chemical transport. German specialty haulers pioneer adoption for premium chemical routes.
Steel retains volume leadership. Composite materials gain share fastest in corrosive chemical segments.
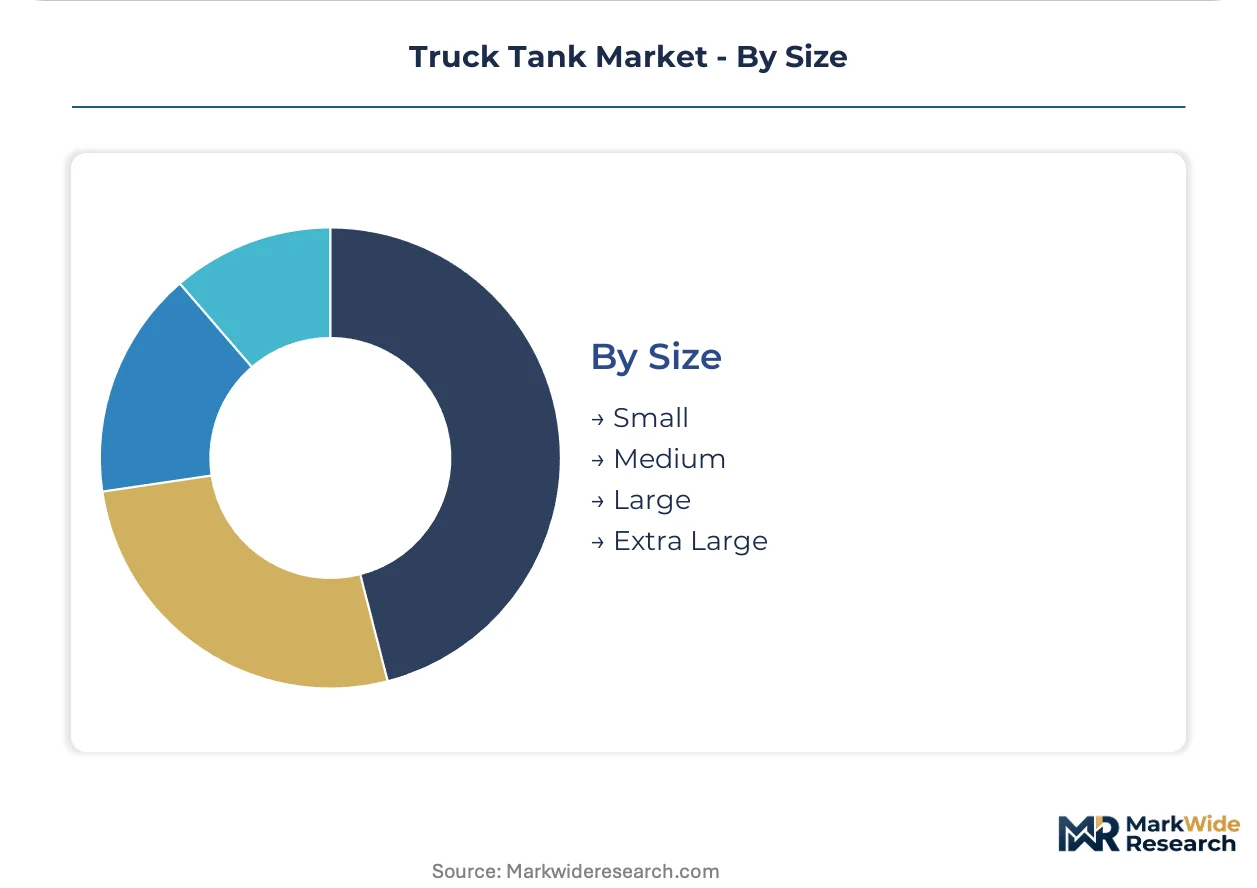
Size:
Size classification interfaces directly with chassis payload regulations and route-specific volume economics, with extra-large tanks concentrated in long-haul chemical and fuel logistics.
- Large:High-capacity vessels for interstate chemical and petroleum transport. Volvo Trucks anchors positioning through in-house pressure rating protocols for large-format chemical tanks.
- Medium:Versatile capacity range serving regional distribution and municipal applications.
- Small:Compact tanks for urban delivery, construction equipment service, and auxiliary fuel systems.
- Extra Large:Maximum-capacity configurations for dedicated long-haul routes with minimal handling requirements.
Medium sizes lead procurement frequency. Extra large tanks command the highest per-unit value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA greenhouse gas standards for heavy-duty vehicles compress tank replacement cycles across United States chemical transport fleets. DOT hazardous materials regulations mandate accelerated retirement schedules for pressurized vessels. Certified aluminum welder scarcity concentrates fabrication capacity in captive manufacturing clusters.
United States
Midwestern chemical transport fleet expansion drives aluminum tank demand despite collapsing certified welder availability. EPA emissions standards and DOT hazardous materials rules govern construction, testing, and retirement schedules. Manufacturing zones in Ohio and Michigan anchor fabrication capacity for pressure-rated chemical transport vessels.
Germany
Specialty chemical haulers adopt filament-wound composite tanks with aluminum liners for sulfuric acid and caustic soda routes. ECE R34 and ADR certification frameworks mandate crash-resistance and leakage thresholds for cross-border operations. Industrial corridors in North Rhine-Westphalia concentrate tank testing and certification documentation services.
China
Domestic logistics operators demand cost-optimized steel tank variants for bulk liquid distribution networks. GB standards and MIIT regulations establish pressure vessel construction protocols for commercial vehicle applications. Manufacturing clusters in Shandong Province scale rotational molding capacity for high-density polyethylene agricultural tanks.
India
Emerging market logistics operators prioritize localized fabrication of steel tanks for fuel and chemical transport. BIS certification requirements and CDSCO hazardous materials protocols influence vessel specification standards. Industrial zones in Maharashtra and Gujarat expand tank assembly capacity for regional distribution networks.
Brazil
Agricultural supply chains sustain demand for atmospheric water and fertilizer tanks across seasonal operational cycles. ANVISA and national transport regulator standards govern hazardous liquid containment specifications. São Paulo state manufacturing bases serve cost-sensitive operators with coated steel and polyethylene vessel production.
Truck Tank Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the truck tank market. Premium chemical transport applications concentrate around integrated chassis manufacturers with captive fabrication and in-house testing protocols. Volume-oriented fuel tank supply fragments across independent fabricators serving aftermarket replacement cycles. Strategic moves center on securing aluminum stamping capacity and acquiring certified welding labor pools.
Among integrated chassis manufacturers, Daimler Truck AG and Volvo Trucks occupy positions defined by captive supply chain control and proprietary pressure rating capabilities. Tata Motors exemplifies the cost-optimization archetype through emerging market-focused steel tank variants. These three anchors represent divergent competitive vectors: technology integration, certification depth, and manufacturing economics.
| Leading Market Players |
|---|
| Daimler Truck AG |
| Volvo Trucks |
| PACCAR |
| Tata Motors |
| Kenan Advantage Group |
| Trimac Transportation |
| Isuzu Motors |
| Mahindra and Mahindra |
| Shacman |
| Others |
Value Network & Pricing Analysis
Captive aluminum stamping capacity at integrated chassis manufacturers creates scale advantages that compress price floors for independent fabricators while elevating margins for vertically integrated producers. EPA emissions compliance costs and certified welder scarcity concentrate fabrication economics in Midwestern US and German industrial corridors, forcing price stratification between integrated OEM supply and aftermarket replacement channels.
Pricing Analysis
United States-Germany price spreads for pressure-rated chemical tanks reach 15-25% premiums in the German market due to ADR certification documentation burdens and composite material adoption. Three-tier pricing structure across premium composite, standard aluminum, and economy steel levels tracks certification grade and vapor recovery system complexity. Pricing pressure stems from high-density polyethylene substitution in non-pressurized agricultural applications, eroding metal tank share. Fleet operators in emerging markets exhibit highest price sensitivity, while California chemical haulers facing EPA greenhouse gas standards show lowest sensitivity due to compliance-driven procurement.
Supply Chain Analysis
Strategic stockpiling of aluminum coil and certified welding labor dominates inventory strategy as fabricators buffer against certified welder availability collapse and raw material delivery volatility. Supply concentrates in the United States, Germany, and China, with carbon steel coil drawn from domestic mills and aluminum alloy sourced from North American smelters. The supply chain rests on welding consumables, pressure relief valves, and corrosion-resistant liner materials as critical component dependencies. Single-source vulnerability concentrates in certified aluminum welder labor pools across Ohio and Michigan manufacturing zones. Distribution runs through OEM chassis integrators for fuel tank volumes and direct fleet procurement for chemical transport vessels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across material technology and certification requirements creates niche entry points as alternative fuel powertrains and composite convergence splinter previously standardized demand.
For Market Incumbents: Consolidate captive aluminum stamping capacity and in-house pressure testing protocols to defend against filament-wound composite substitution in corrosive chemical segments. Acquire certified welding labor pools in Midwestern US zones to offset scarcity-driven cost inflation. Backward integration into aluminum coil supply secures margin position against steel price volatility. For New Entrants and Emerging Players: Lead with localized steel tank fabrication for cost-sensitive emerging market logistics operators in India and Brazil, where BIS and ANVISA certification pathways remain more accessible than EPA or ADR frameworks. Target agricultural water tank segments with rotational molding capacity for polyethylene atmospheric vessels. Pursue municipal firefighting procurement through NFPA certification investment as a premium positioning mechanism. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors composite-aluminum hybrid fabricators with established ADR and EPA certification documentation capabilities. Five-to-ten year viability hinges on low-carbon fuel compatibility standard transitions and material substitution timelines. Acquisition targets should demonstrate integrated testing protocols rather than outsourced certification. The signal to watch is EPA permeation threshold tightening for diesel alternative fuel architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Stamping Expansion | Daimler Truck AG secures shell supply chains against certified welder scarcity in Ohio manufacturing zones. |
| In-House Pressure Testing Investment | Volvo Trucks compresses delivery schedules by bypassing independent laboratories for ADR documentation. |
| Composite Material Convergence Partnership | German specialty haulers adopt filament-wound tanks with aluminum liners for sulfuric acid routes. |
| Localized Steel Fabrication Scale-Up | Tata Motors serves cost-optimized demand across Maharashtra and Gujarat distribution networks. |
| NFPA Certification Acquisition | Municipal firefighting procurement commands premium margins through specialized pressure-rated documentation. |
Research Methodology
The analysis maps fuel tank, chemical tank, water tank, and pressure tank sub-sectors, each validated through fleet procurement managers, OEM chassis integrators, certified welding contractors, and tank fabricator operations directors. Primary interviews with EPA compliance officers and ADR certification specialists cross-reference secondary validation from DOT hazardous materials filings, ECE R34 regulatory databases, SEC 10-K disclosures from integrated chassis manufacturers, and customs trade data for aluminum alloy and carbon steel coil imports. Bottom-up tank unit economics and top-down fleet replacement cycle modeling enable triangulation across demand-side and supply-side intelligence.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models material type, application end-use, product architecture, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from replacement cycle compression rates under EPA greenhouse gas standards and DOT hazardous materials retirement schedules. Industry-specific forecast inputs include certified welder availability indices and alternative fuel powertrain penetration curves.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity or alternative fuel infrastructure buildout would require recalibration. Forecasts reflect assumptions regarding aluminum welder training pipeline recovery and composite material cost parity timelines. Revision becomes warranted when high-density polyethylene substitution rates in agricultural applications cross material-specific threshold levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Truck Bedliner Market
Heavy-Duty Trucks
Heavy-Duty Truck Fleet Control Unit Architectures Market
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
Saudi Arabia Refrigerated Truck Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
India Vacuum Truck Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
Truck Racks Market
Heavy-Duty Trucks
United States Tank Trucking Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
North America Heavy Commercial Vehicle (HCV) TMPS Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Platooning Trucks Market