
 Automotive Proportioning Valves Market | 2026-2036
Automotive Proportioning Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Proportioning Valves Market Outlook
Modular brake system packaging is realigning how fleet buyers and OEMs evaluate proportioning valve suppliers. Continental leverages its integrated chassis electronics portfolio to bundle valve modules with ABS controllers. Bosch anchors its position through in-house semiconductor capacity for sensor-integrated valve units. Aisin Seiki specializes in compact hydraulic architectures for Asian OEM transmission-brake integration programs.
Automotive proportioning valves regulate hydraulic pressure distribution between front and rear brake circuits, typically operating at system pressures of 10-20 MPa with response thresholds below 100 milliseconds to prevent rear-wheel lockup during deceleration. Electronic valves now lead product type demand as automakers phase out pure mechanical modulation for software-defined braking. Hydraulic systems retain the largest installed base among technology categories, though electric actuation represents the fastest-growing margin pool. Passenger vehicles dominate application volume, while heavy-duty trucks command premium pricing due to load-adaptive calibration requirements.
NHTSA Federal Motor Vehicle Safety Standards govern brake system performance thresholds for vehicles sold in the United States. ECE R13 and EU General Safety Regulation mandate automatic emergency braking and stability control, which embed proportioning valves within broader active-safety architectures. China's MIIT enforces GB standards for braking performance on domestic production. Stakeholders must monitor how software-over-the-air update capabilities reshape hardware certification cycles and aftermarket liability frameworks.
Market Dynamics
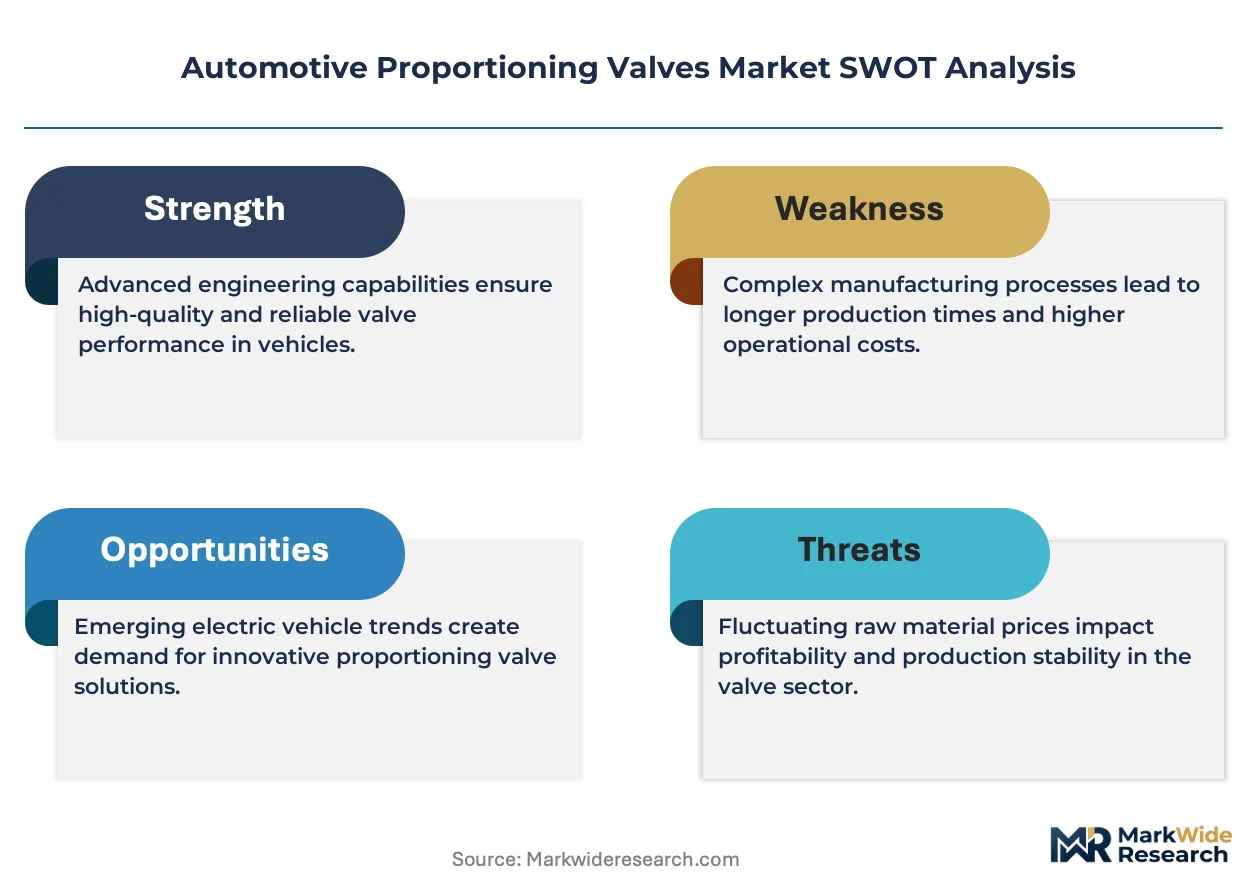
Electronic stability control mandates are compressing mechanical valve procurement cycles as automakers consolidate brake system architectures under software-defined platforms. Tier-one suppliers now engineer proportioning valves as embedded modules within integrated chassis controllers rather than discrete hydraulic components.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 126:Mandates electronic stability control on all light vehicles, embedding proportioning valves within active-safety architectures that require continuous hydraulic modulation.
- Load-adaptive calibration:Heavy-duty truck fleets demand proportioning valves with dynamic pressure mapping for variable axle loads, expanding addressable hardware content per vehicle.
- Germany-Japan-US manufacturing clusters:Proximity between valve suppliers and vehicle assembly hubs reduces logistics latency for just-in-time brake system integration.
Market Restraints
- Semiconductor input volatility:Sensor-integrated electronic valves depend on analog-digital converter chips subject to foundry allocation constraints.
- Supplier concentration in Baden-Württemberg:German chassis component manufacturing clusters create geographic single-point vulnerability for European OEM supply security.
- Hydraulic fluid compatibility thresholds:Emerging low-viscosity brake fluids degrade legacy seal materials, forcing premature component redesign cycles.
Strategic Opportunities
- India domestic production incentives:PLI scheme subsidies for advanced automotive components attract valve suppliers to localize for Maruti Suzuki and Tata Motors programs.
- Over-the-air calibration:Software-defined braking architectures enable remote valve-response tuning, opening recurring revenue streams through firmware subscription models.
- China GB 7258 enforcement:Mandatory ABS and stability control on commercial vehicles expands addressable fleet retrofits beyond factory-installed systems.
Industry Challenges
- Functional safety certification:ISO 26262 ASIL-D validation for brake-by-wire systems extends development timelines and requires specialized systems-engineering talent.
- Legacy hydraulic integration:Electrified platforms must maintain backward compatibility with mechanical backup circuits, doubling validation matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Proportioning Valves Market |
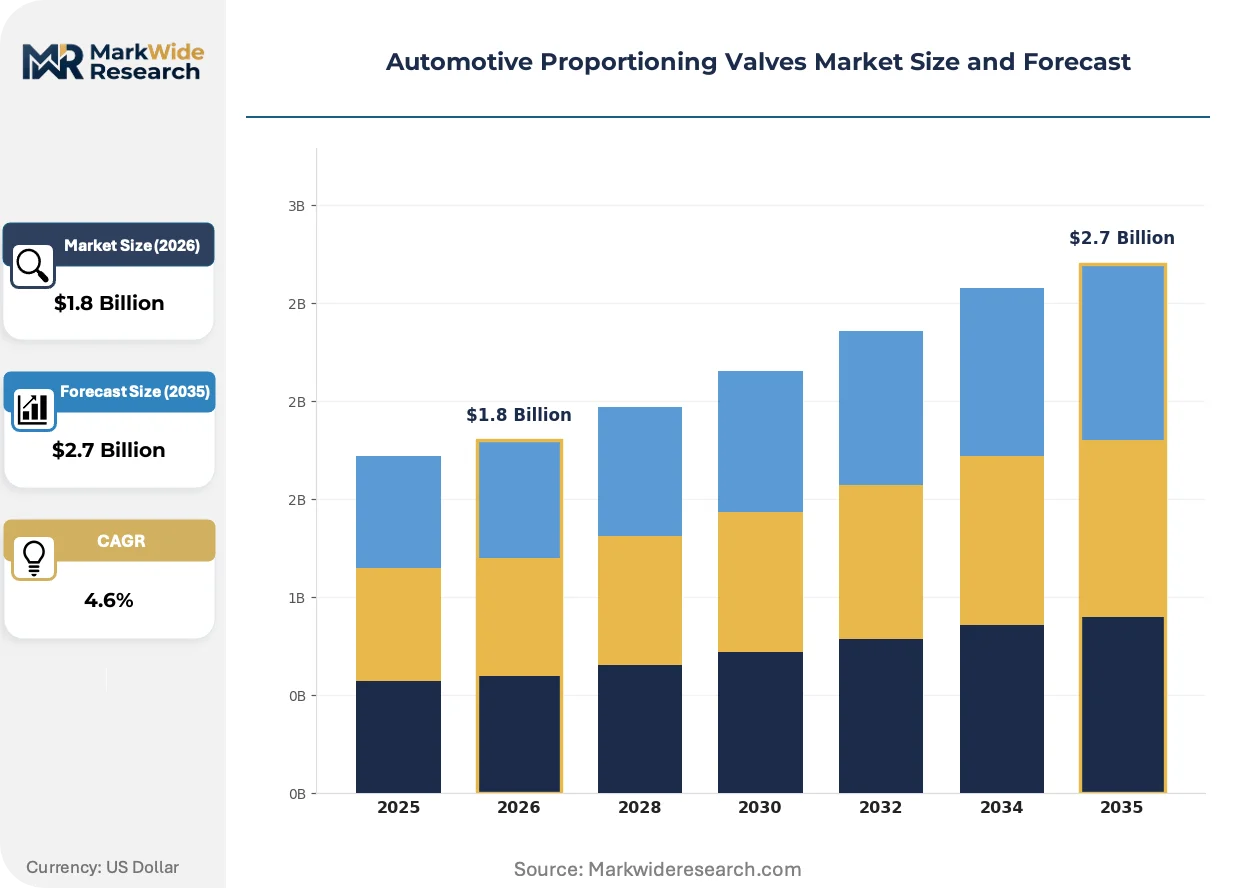
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Valves, Electronic Valves, Hydraulic Valves, Proportional Valves End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Component Manufacturers Technology: Pneumatic Systems, Hydraulic Systems, Electric Systems, Mechanical Systems Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks |
| Companies Covered | Continental, Aisin Seiki, Knorr-Bremse, Eaton Corporation, Delphi Technologies, WABCO, Denso Corporation, Nachi, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Proportioning Valves Market Strategic Shifts
Brake system electrification is collapsing the boundary between hydraulic actuation and electronic control, forcing valve suppliers to reconstitute their hardware as software-configurable platforms. This convergence is redrawing competitive boundaries between traditional hydraulic specialists and semiconductor-integrated chassis suppliers.
Electro-hydraulic brake (EHB) actuation is unifying pressure modulation and wheel-slip control within single valve-body assemblies. European premium OEMs are adopting these consolidated architectures for their next-generation electric platforms. This unification is compressing the supplier base as hydraulic component houses acquire sensor and controller capabilities to remain specification-relevant.
ECE R13 revision mandates automatic emergency braking and stability intervention for all new commercial vehicles above 3.5 tonnes. The regulation forces retrofit of electronic proportioning hardware onto existing hydraulic circuits for fleet compliance. Heavy-duty truck operators in Poland and Spain are accelerating procurement to avoid registration penalties.
Fleet procurement departments now specify brake systems through total cost of ownership models rather than unit pricing. Large logistics operators in the US Midwest are consolidating supplier relationships to capture volume-based calibration services. This behavioral shift favors valve manufacturers with embedded telematics and predictive maintenance software over pure hardware vendors.
Automotive Proportioning Valves Market Segmentation
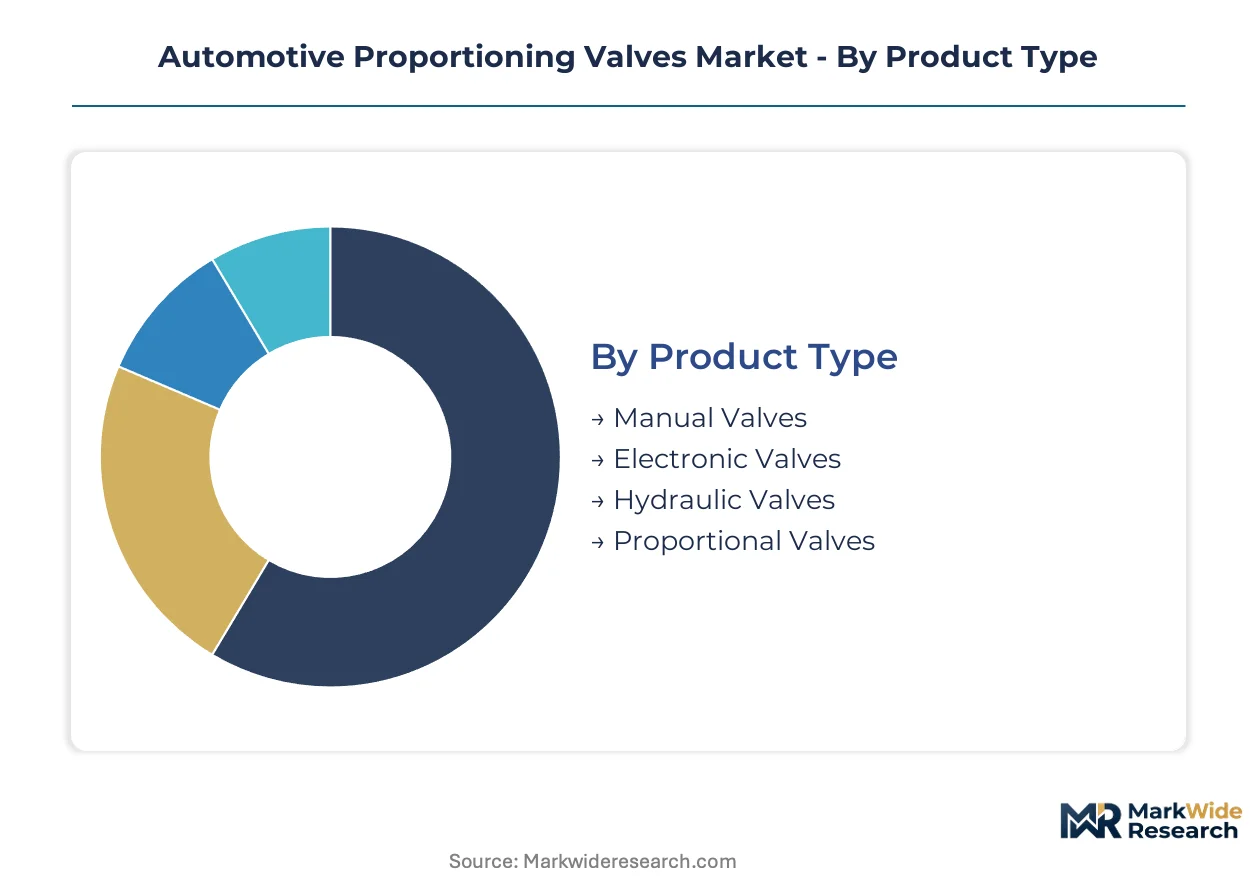
Segmentation in automotive proportioning valves reveals how capital deployment, regulatory exposure, and technology maturity diverge across product architectures. Suppliers must align R&D budgets with the electrification trajectory while maintaining legacy hydraulic revenue streams.
Product Type:
Capital intensity varies sharply across valve architectures, with sensor-integrated electronic variants demanding semiconductor foundry commitments and software validation infrastructure that mechanical designs avoid entirely.
- Electronic Valves:Microprocessor-controlled units with integrated pressure sensors and PWM-driven solenoids enable closed-loop modulation within 50-millisecond response windows. Germany's Continental and Japan's Aisin Seiki dominate specification lists for European and Asian OEM stability control platforms, driven by NHTSA FMVSS 126 mandates that phase out pure hydraulic modulation on light vehicles.
- Hydraulic Valves:Piston-and-spring architectures operating at 10-20 MPa system pressures remain the installed base majority, particularly in emerging-market vehicle production where cost sensitivity delays electronic migration. India's Motherson Group and China's Wanxiang supply these units for domestic OEM brake system integration, constrained by legacy seal compatibility with emerging low-viscosity brake fluids.
- Manual Valves:Cable-actuated pressure reducers for rear brake circuits in entry-level commercial vehicles and motorcycle applications.
- Proportional Valves:Variable-orifice designs providing progressive pressure reduction based on input force, common in heavy-duty truck load-sensing applications.
Hydraulic valves absorb the bulk of installed capacity; electronic valves are expanding most quickly.
End User:
Procurement authority concentrates with entities controlling brake system architecture decisions, creating tiered margin structures based on specification influence and volume commitment scale.
- OEMs:Vehicle manufacturers with in-house chassis engineering teams specify valve modules as part of integrated brake control systems, often sourcing directly from tier-one suppliers for software-defined platforms. Toyota, Volkswagen Group, and Ford Motor Company consolidate procurement under long-term platform agreements that bundle valve hardware with ABS controller electronics, driven by ECE R13 and NHTSA stability control mandates requiring continuous hydraulic modulation capability.
- Vehicle Assemblers:Contract manufacturers and joint-venture production facilities rely on specified supplier lists from technology-licensing partners, limiting direct procurement autonomy.
- Aftermarket Providers:Independent distributors and service chains serving fleet maintenance and collision repair channels.
- Component Manufacturers:Brake system integrators sub-assembling valve units into caliper or master cylinder modules for upstream supply to OEMs.
OEMs command the specification authority; vehicle assemblers are gaining procurement autonomy fastest.
Technology:
Technology selection determines validation burden and supply chain resilience, with electric architectures requiring semiconductor sourcing strategies that hydraulic systems avoid.
- Hydraulic Systems:Fluid-based pressure transmission through sealed circuits dominates current production, with established seal material supply chains and repair infrastructure. Bosch's hydraulic valve production in Germany and Denso's Japanese manufacturing clusters serve premium OEM platforms, constrained by geographic concentration risk in Baden-Württemberg and Aichi Prefecture.
- Electric Systems:Electromechanical actuation eliminating hydraulic fluid enables brake-by-wire architectures with software-configurable response curves. ZF Friedrichshafen and Hyundai Mobis are qualifying these units for next-generation electric vehicle platforms, driven by EU General Safety Regulation requirements for automatic emergency braking integration.
- Pneumatic Systems:Compressed-air modulation for heavy-duty commercial vehicle air brake circuits, prevalent in North American Class 8 trucks.
- Mechanical Systems:Direct linkage actuation retained for backup circuits and cost-optimized emerging-market vehicles.
Hydraulic systems retain the largest installed base; electric systems are climbing the fastest.
Application:
Application segmentation exposes diverging performance requirements and pricing power, with heavy-duty platforms justifying premium hardware for load-adaptive functionality.
- Passenger Vehicles:Light-duty automobiles and SUVs generate volume concentration, with electronic proportioning valves standard equipment under NHTSA and EU mandates. Stellantis, Hyundai-Kia, and Geely Auto specify integrated valve-controller modules for compact and mid-size platforms, driven by pedestrian-safety directives requiring optimized brake force distribution.
- Heavy-Duty Trucks:Class 7-8 commercial vehicles demand load-sensing proportioning with dynamic pressure mapping for variable axle weights. Daimler Truck, Volvo Group, and PACCAR specify these units for North American and European fleet customers, driven by total cost of ownership procurement models that prioritize predictive maintenance integration.
- Commercial Vehicles:Light and medium-duty trucks and vans below 3.5 tonnes gross vehicle weight.
- Motorcycles:Two-wheeler applications with compact valve designs and simplified hydraulic circuits for cost-sensitive markets.
Passenger vehicles absorb the bulk of installed capacity; heavy-duty trucks are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures proportioning valves at scale while the United States and China absorb the dominant share of OEM installation demand. Production clusters concentrate near Stuttgart, Detroit, and Shanghai to minimize logistics latency for just-in-time brake system assembly.
Germany
Baden-Württemberg hosts the densest concentration of chassis component engineering in Europe, with tier-one suppliers co-located at vehicle assembly hubs. ECE R13 mandates automatic emergency braking and stability control for commercial vehicles, forcing hardware upgrades across existing fleets. Continental and Bosch anchor production in Stuttgart and Reutlingen, supplying integrated valve-controller modules to premium OEM platforms.
United States
NHTSA Federal Motor Vehicle Safety Standard 126 requires electronic stability control on all light vehicles, embedding proportioning valves within active-safety architectures. Michigan and Ohio manufacturing corridors serve Detroit Three assembly operations with sub-48-hour component delivery windows. Daimler Truck North America and PACCAR specify load-adaptive valves for Class 8 production at facilities in Portland and Denton.
China
MIIT enforces GB 7258 braking performance standards that mandate ABS on commercial vehicles and expand addressable retrofit volumes beyond factory installations. Yangtze River Delta clusters around Shanghai and Suzhou concentrate domestic valve production for Geely Auto, BYD, and SAIC Motor programs. Local suppliers compete on cost-optimized hydraulic architectures while foreign joint ventures dominate electronic valve specifications.
Japan
Aichi Prefecture and Kanagawa manufacturing belts supply Toyota, Honda, and Nissan with brake system integration at source. METI industrial policy prioritizes semiconductor resilience for sensor-integrated valve units, reducing foundry allocation vulnerability. Aisin Seiki and Denso Corporation dominate specification lists for Asian OEM stability control platforms through in-house controller production.
India
PLI scheme subsidies for advanced automotive components attract valve suppliers to localize for Maruti Suzuki and Tata Motors domestic production programs. Tamil Nadu and Gujarat industrial corridors host expanding brake system component manufacturing. BIS certification requirements for braking performance create compliance barriers that favor established tier-one suppliers over emerging domestic competitors.
Automotive Proportioning Valves Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered supplier tiers. The market structure consolidates around integrated chassis electronics houses that bundle valve hardware with ABS controllers, while hydraulic component specialists defend position through cost-optimized mechanical designs. Three archetypes dominate: semiconductor-integrated system suppliers, hydraulic-focused component houses, and diversified industrial conglomerates with brake system divisions. Competitive moves center on backward integration into sensor production and strategic partnerships for brake-by-wire qualification.
Among German diversified industrial groups, Continental and Bosch occupy positions as integrated system suppliers with in-house semiconductor capacity. Aisin Seiki represents the Japanese precision manufacturing archetype with compact hydraulic architectures for transmission-brake integration. Knorr-Bremse anchors the commercial vehicle specialization tier with heavy-duty load-adaptive calibration expertise. These three exemplify how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Continental |
| Aisin Seiki |
| Knorr-Bremse |
| Eaton Corporation |
| Delphi Technologies |
| WABCO |
| Denso Corporation |
| Nachi |
| Bosch |
| Others |
Value Chain & Pricing Dynamics
Performance-grade divergence between ISO 26262 ASIL-D certified electronic valves and commodity hydraulic units manifests in contract structures and supplier qualification timelines, with NHTSA FMVSS 126 mandates compressing procurement cycles for certified architectures while emerging-market OEMs extend payment terms on mechanical designs sourced from India's Motherson Group and China's Wanxiang.
Pricing Analysis
Margin tightening in electronic valve tiers reflects semiconductor foundry allocation premiums and ISO 26262 validation costs, while hydraulic valve pricing stratifies across premium, standard, and economy tiers based on seal material compatibility and regional logistics. OEM direct procurement commands volume discounts through platform bundling with ABS controllers, whereas aftermarket distributors face acute price sensitivity on legacy mechanical replacements for fleet maintenance channels.
Supply Chain Analysis
Single-source vulnerability sits with German Baden-Württemberg clusters for precision-machined valve bodies and Taiwanese foundries for sensor-integrated analog-digital converter chips. Production draws from Germany, China, and Japan for tier-one supply, with raw material dependencies spanning aluminum die-cast housings, EPDM seal compounds, and copper winding wire. Tariff exposure on cross-border semiconductor shipments threatens just-in-time delivery windows to Detroit and Stuttgart assembly corridors, while distribution runs through tier-one brake system integrators with specified supplier list authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where NHTSA FMVSS 126 and ECE R13 stability control mandates erect certification barriers that favor incumbent tier-one suppliers with amortized validation infrastructure over capital-constrained challengers.
For Market Incumbents: Anticipate brake-by-wire displacement of hydraulic architectures by qualifying electromechanical actuation platforms with ZF Friedrichshafen and Hyundai Mobis, while backward integration into captive semiconductor sourcing mitigates foundry allocation volatility threatening sensor-integrated valve margins. For New Entrants and Emerging Players: Aftermarket telematics providers offer the most penetrable channel partnership for valve-response calibration software, with white-space concentration in India's PLI-subsidized domestic production for Maruti Suzuki and Tata Motors programs where BIS certification barriers remain navigable for tier-two hydraulic specialists. For Investors and Strategic Acquirers: Re-rating potential sits with brake-by-wire qualification leaders given EU General Safety Regulation automatic emergency braking mandates, with long-term viability hinging on software-over-the-air revenue streams; watch for OEM platform standardization announcements as inflection signals for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Brake-by-Wire Platform Qualification | Enables ZF Friedrichshafen and Hyundai Mobis to capture EU General Safety Regulation-mandated automatic emergency braking integration. |
| Semiconductor Backward Integration | Reduces Bosch and Continental exposure to Taiwanese foundry allocation constraints on analog-digital converter chips. |
| India PLI Localization | Positions valve suppliers for Maruti Suzuki and Tata Motors domestic production with subsidized advanced component manufacturing. |
| Over-the-Air Calibration Development | Creates recurring firmware subscription revenue through software-defined braking architectures for fleet telematics integration. |
| Heavy-Duty Load-Adaptive Certification | Captures premium pricing from Daimler Truck and PACCAR through dynamic pressure mapping for variable axle weights. |
Study Parameters
Document review covered vehicle production databases, NHTSA FMVSS 126 regulatory filings, and IHS Markit registration data, complemented by interviews with tier-one supplier procurement officers, OEM platform engineers, aftermarket distributors, and brake system integration specialists. Secondary validation drew from ECE R13 revision texts, MIIT GB 7258 enforcement notices, and SEC 10-K disclosures from diversified chassis suppliers. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Historical trend extrapolation cross-referenced with expert panel input on electrification timelines and regulatory phase-in schedules. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from regression analysis of installed base turnover rates and mandate-driven replacement cycles, with semiconductor availability and brake fluid compatibility thresholds as industry-specific forecast inputs.
Caveats apply where foundry allocation disruptions, ECE R13 retrofit compliance delays, or low-viscosity brake fluid seal degradation could materially shift the outlook. Forecasts reflect documented assumptions on mandate enforcement timing and OEM platform consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Brake Shoe Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Electric Vehicle Aluminum Die Casting Parts Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
Insert Drive for Torque Wrench Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
United States Automotive Glass Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
Motor Bearings Market
Automotive Parts
Europe Automotive Engine Oils Market