
 Truck Bedliner Market | 2026-2036
Truck Bedliner Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Bedliner Market Analysis
North American polyurethane spray capacity is consolidating around specialized applicator networks and captive resin production. LINE-X sustains technology leadership through proprietary polyurea formulations and certified dealer infrastructure. Rhino Linings leverages its global franchise model to control application quality across independent operators. BedRug differentiates through carpet-composite hybrid designs that serve consumers seeking cargo protection without permanent modification.
A truck bedliner is a protective barrier applied to the interior cargo box of pickup trucks, typically formulated from polyurethane, polyethylene, or rubberized compounds and applied via high-pressure spray, roll-on, or thermoformed drop-in methods to prevent abrasion, corrosion, and impact damage. Spray-on polyurethane systems dominate the premium tier due to permanent adhesion and custom fit, while drop-in polyethylene liners anchor the value segment through ease of removal and replacement. Commercial fleet end users represent the fastest-growing demand pool as total-cost-of-ownership calculations elevate durable protection over upfront spend.
EPA VOC regulations constrain solvent-based spray formulations in the United States, pushing applicators toward low-emission polyurea and waterborne chemistries. NHTSA vehicle safety standards indirectly shape bedliner design through load retention and slip-resistance requirements in commercial configurations. Stakeholders must monitor evolving state-level environmental mandates and fleet electrification timelines, as battery-electric truck architectures will demand revised bedliner thermal management and weight-optimized material specifications.
Market Dynamics
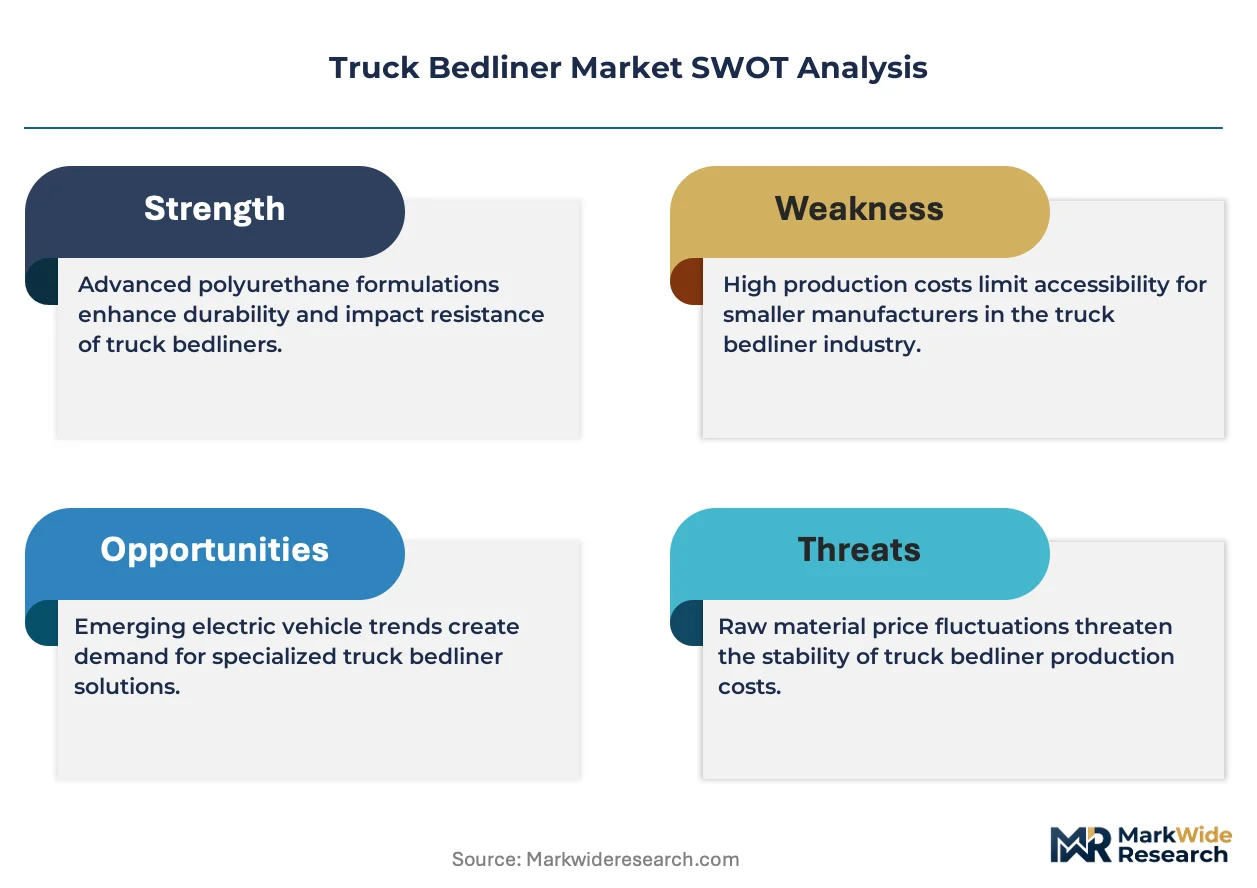
Commercial fleet electrification is compressing bedliner design cycles as thermal management requirements for battery-electric pickup architectures diverge sharply from internal combustion layouts, forcing reformulation of polyurethane density and adhesion chemistry.
Growth Catalysts
- EPA VOC compliance mandates:Federal emissions standards are accelerating applicator migration toward low-emission polyurea and waterborne spray systems, expanding addressable market for compliant coating providers.
- Commercial fleet total-cost-of-ownership modeling:Logistics operators are elevating durable cargo protection over upfront capital expenditure, pulling premium spray-on polyurethane into standardized procurement specifications.
- Pickup truck ownership concentration:Texas, Michigan, and California anchor aftermarket service density, creating localized demand pools that sustain specialized applicator network expansion.
Market Restraints
- Isocyanate input cost volatility:Polyurethane precursor pricing fluctuates with petrochemical feedstock markets, compressing applicator margins and destabilizing project quoting.
- Application skill concentration:High-pressure spray competency clusters around certified dealer networks, constraining geographic expansion and service accessibility.
- Drop-in polyethylene substitution:Thermoformed liner systems retain value-segment share through removability and zero cure-time installation, limiting spray-on penetration in price-sensitive buyer pools.
Strategic Opportunities
- Battery-electric truck thermal interface:Revised bedliner specifications for electric vehicle battery cooling integration represent uncontracted white space in OEM and aftermarket channels.
- State-level environmental incentive programs:California Air Resources Board low-VOC equipment rebates are creating procurement pull for compliant applicator investments.
- Franchise-certified mobile application units:Deployable spray rigs are opening fleet-yard service models that bypass traditional shop-based installation bottlenecks.
Industry Challenges
- Polyurea spray technician certification timelines:Dealer network quality standards require extended training periods, throttling workforce scaling during demand surges.
- Legacy adhesive compatibility testing:New low-emission formulations demand extensive substrate validation across aging truck fleet paint systems, elongating product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Bedliner Market |
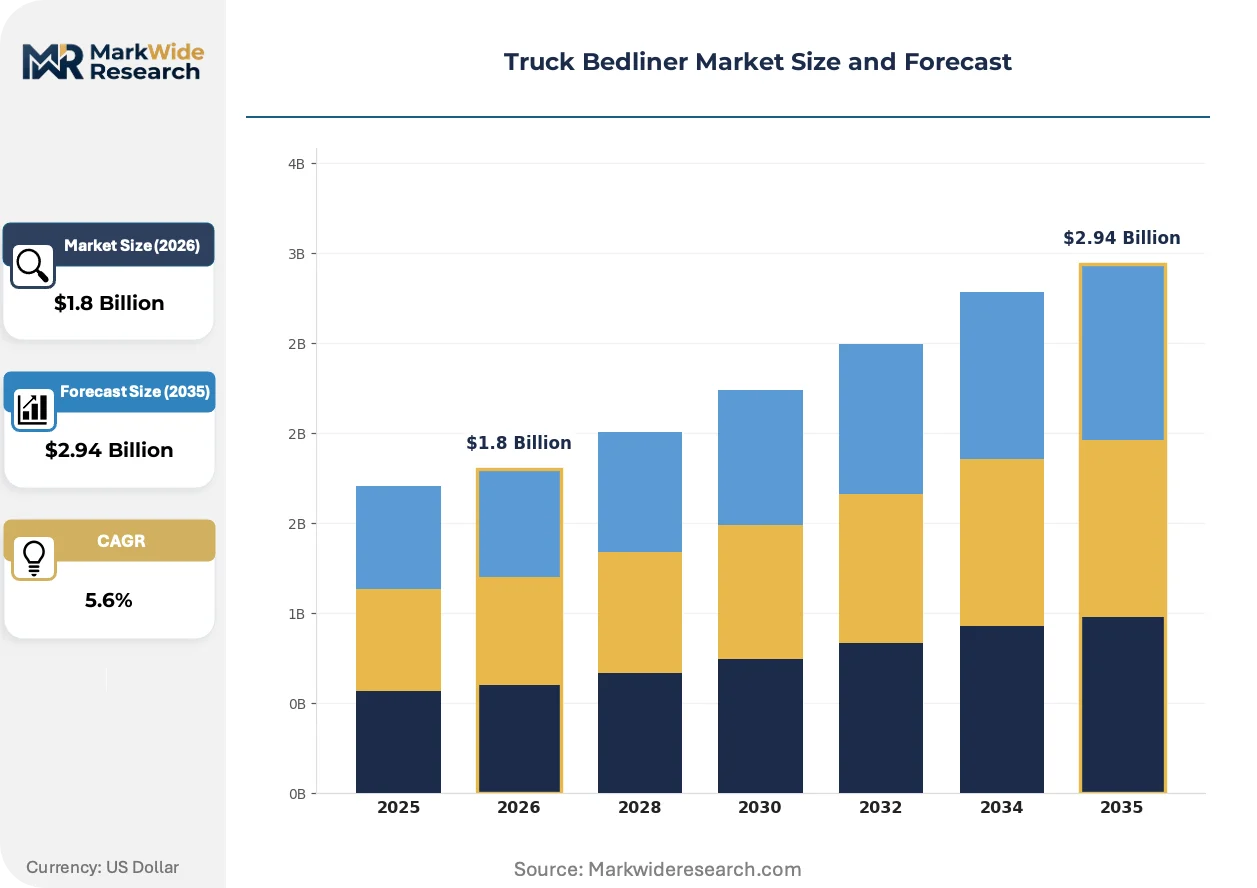
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray-On, Roll-On, Drop-In, Custom Fit Material: Polyurethane, Polyethylene, Rubber, Aluminum Vehicle Type: Light-Duty Trucks, Heavy-Duty Trucks, SUVs, Vans End User: Commercial Fleets, Individual Consumers, OEMs, Aftermarket Providers |
| Companies Covered | Rugged Liner, DualLiner, LINE-X, Scorpion Protective Coatings, Armadillo Liners, Rhino Linings, BedRug, WeatherTech, Penda Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Bedliner Market Emerging Trajectories
Formulation chemistry and application methodology are diverging simultaneously, with environmental compliance pressures and electric vehicle thermal requirements forcing parallel innovation tracks rather than sequential adoption curves.
Polyurea hybrid spray systems are consolidating market position as the dominant premium-tier chemistry, combining rapid cure times with VOC-compliant emission profiles. Commercial fleet procurement teams are specifying these formulations in multi-year service contracts, compressing residual demand for conventional polyurethane in the professional installation segment. The technology is consolidating application quality standards around factory-trained dealer networks, marginalizing independent operators lacking formulation access.
EPA emissions standards and state-level VOC regulations are tightening compliance windows for solvent-based spray formulations, pushing applicators toward capital-intensive equipment upgrades. Industrial consequence includes accelerated dealer network consolidation as smaller operators exit under compliance cost burdens. California and Texas markets exhibit the most pronounced regulatory response, with certified low-emission applicators capturing disproportionate fleet contract share.
Fleet procurement teams are unbundling bedliner specification from vehicle acquisition, creating standalone coating procurement decisions evaluated on total-cost-of-ownership metrics. This behavior is displacing OEM-installed liners as default configuration, redirecting volume toward aftermarket specialists with certified application infrastructure. The shift concentrates in commercial logistics verticals where cargo protection downtime costs exceed installation price differentials.
Truck Bedliner Market Segmentation
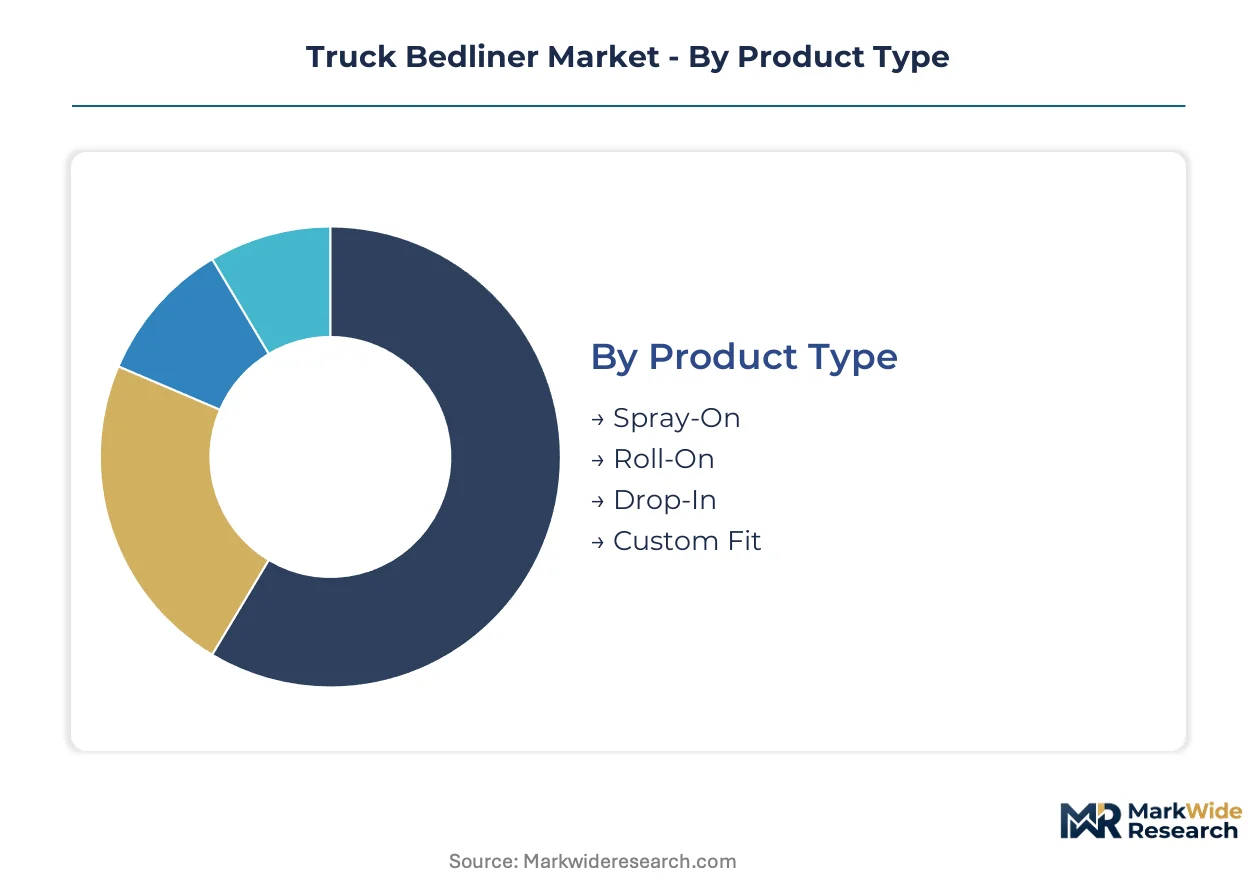
Bedliner procurement decisions fragment across multiple technical and commercial dimensions, with formulation chemistry and installation method determining regulatory compliance burden while vehicle architecture dictates thermal and adhesion specifications. Fleet managers and individual buyers evaluate segments through divergent lenses: total-cost-of-ownership for commercial operators versus removability and aesthetic preference for retail consumers.
Product Type:
Certification requirements cluster around spray-application systems, where EPA VOC compliance and OSHA isocyanate exposure standards mandate equipment upgrades and technician credentials that roll-on and drop-in alternatives bypass entirely.
- Spray-On:High-pressure polyurethane or polyurea formulations bond permanently to truck bed substrates, requiring certified applicator networks and specialized spray rigs. Demand concentrates among Texas and California commercial fleets where downtime costs justify premium installation spend and VOC-compliant equipment access.
- Drop-In:Thermoformed polyethylene or composite shells deliver instant protection without cure time or permanent modification. Individual consumers in Michigan and price-sensitive rural markets favor this segment for vehicle lease compliance and resale flexibility.
- Roll-On:Consumer-grade polyurethane kits enable DIY application with brush or roller, bypassing professional labor costs entirely.
- Custom Fit:Tailored solutions for specialized commercial configurations including utility bodies and service beds.
Leading the category by volume: Drop-In. Growing fastest: Spray-On.
Material:
Raw material selection determines thermal performance boundaries, with polyurethane and polyurea formulations requiring reformulation for battery-electric truck bed cooling integration while aluminum and rubber compounds face simpler specification paths.
- Polyurethane:The dominant spray-applied chemistry offering abrasion resistance and impact absorption through two-component reactive systems. Commercial fleet procurement in California and Texas increasingly specifies low-VOC polyurethane variants to satisfy CARB equipment rebate programs and EPA emissions mandates.
- Polyethylene:Thermoplastic resin forming drop-in liners through vacuum-forming or rotational molding processes. Michigan aftermarket channels and budget-conscious individual consumers drive volume for this segment given zero installation skill requirements and immediate deployment.
- Rubber:Vulcanized or thermoplastic elastomer compounds providing flexible impact protection and cargo grip.
- Aluminum:Sheet metal inserts offering structural rigidity and compatibility with extreme temperature cycling.
Polyethylene captures the largest volume share. Polyurethane climbs the fastest as fleet electrification demands thermal-adapted formulations.
Vehicle Type:
Application specifications diverge sharply between light-duty consumer pickups and heavy-duty commercial chassis, with bed geometry, payload rating, and duty cycle intensity driving material thickness and adhesion chemistry selection.
- Light-Duty Trucks:Half-ton and midsize pickup configurations dominate retail aftermarket volume, with spray-on polyurethane and drop-in polyethylene splitting demand between permanent protection seekers and lease-conscious buyers. California and Texas light-duty owners exhibit the highest spray-on penetration rates nationally.
- Heavy-Duty Trucks:Three-quarter and one-ton commercial configurations subject bedliners to aggregate hauling, tool loading, and equipment mounting stresses. Michigan construction fleets and Texas energy sector operators specify premium spray-on systems with extended warranty coverage.
- SUVs:Cargo area protection for sport utility vehicles with open or enclosed load spaces.
- Vans:Commercial cargo van interior protection for delivery and service applications.
Light-Duty Trucks lead category volume. Heavy-Duty Trucks gain share fastest on fleet standardization.
End User:
Procurement authority structures separate this dimension, with commercial fleets and OEMs wielding specification power over centralized purchasing decisions while individual consumers and aftermarket providers operate through fragmented retail channels.
- Commercial Fleets:Logistics, construction, and energy sector operators evaluating bedliner investments through total-cost-of-ownership models that weigh cargo damage downtime against upfront coating expenditure. California and Texas fleet managers are unbundling bedliner specification from vehicle acquisition, redirecting volume toward certified aftermarket applicators.
- Individual Consumers:Retail pickup owners selecting protection based on aesthetic preference, resale strategy, and DIY capability. Michigan individual consumers show elevated drop-in liner preference due to seasonal vehicle storage and lease return requirements.
- OEMs:Vehicle manufacturers offering factory-installed liner options as trim-level differentiators.
- Aftermarket Providers:Independent installation shops and mobile application services serving post-purchase demand.
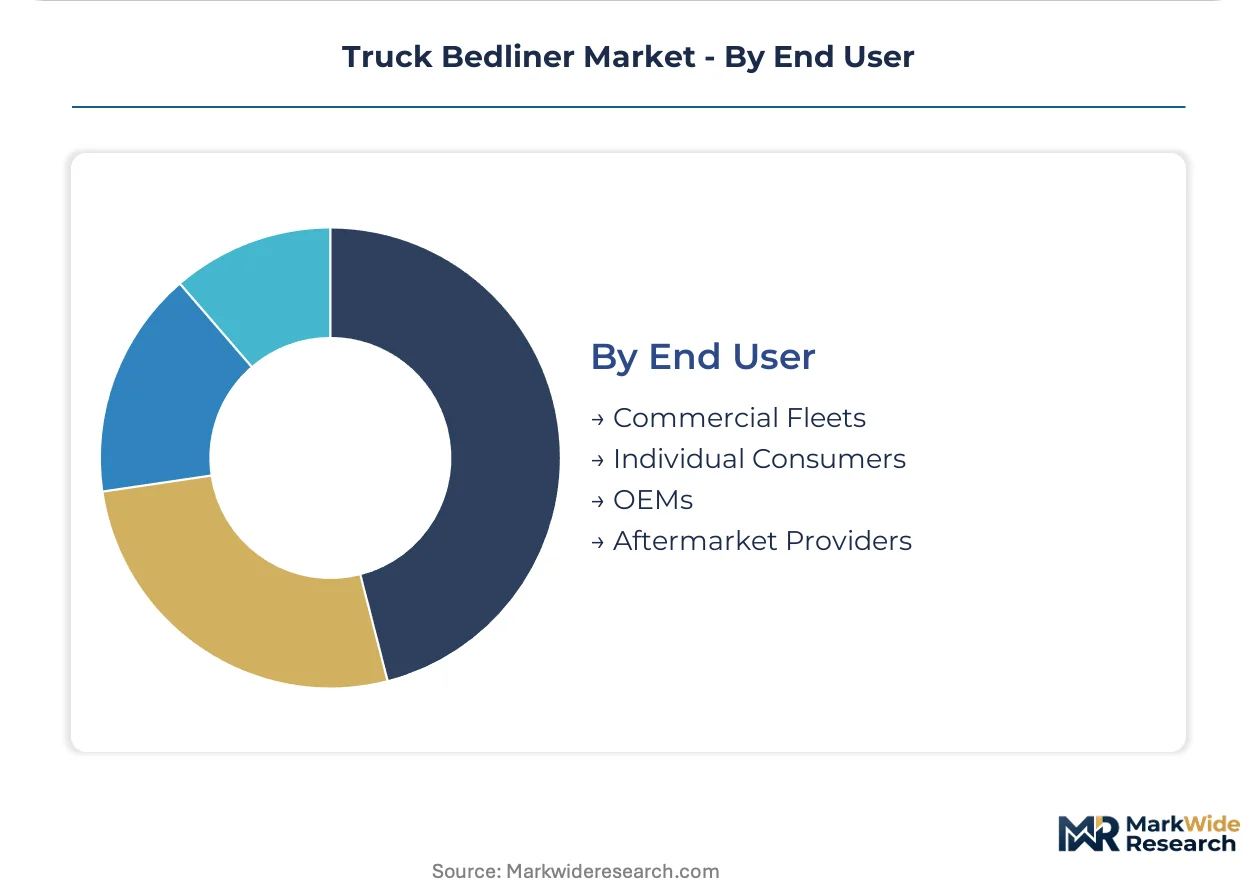
Individual Consumers dominate current volume. Commercial Fleets expand most quickly on procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane feedstock availability clusters along the Gulf Coast petrochemical corridor, anchoring North American bedliner manufacturing density. Texas and Louisiana host the dominant isocyanate production infrastructure that supplies spray-applied coating networks across the United States.
United States
Commercial fleet procurement in Texas and California drives premium spray-on volume, with logistics operators unbundling bedliner specification from vehicle acquisition. EPA VOC regulations and California Air Resources Board equipment rebate programs accelerate applicator migration toward low-emission polyurea systems. Houston and Dallas-Fort Worth sustain the densest certified dealer networks, capturing disproportionate fleet contract share.
Canada
Alberta energy sector fleets and Ontario construction operators generate heavy-duty bedliner demand through total-cost-of-ownership procurement models. Health Canada and PMRA chemical substance regulations govern coating formulations entering the Canadian market. Calgary and Edmonton industrial corridors concentrate specialized applicator services for oilfield service vehicle pools.
Mexico
Automotive assembly integration in Nuevo León and Baja California creates OEM bedliner specification opportunities for export-market pickup production. Mexico's national environmental regulator SEMARNAT enforces emissions standards for industrial coating operations. Monterrey anchors the northern Mexico aftermarket service density for cross-border fleet operators.
Germany
Commercial van and light commercial vehicle fleets in Bavaria and North Rhine-Westphalia generate cargo protection demand through standardized procurement programs. REACH chemical registration requirements and EU Green Deal sustainability mandates constrain formulation chemistry options. Stuttgart and Munich industrial clusters concentrate automotive supplier relationships that influence bedliner specification upstream.
China
Domestic pickup truck market expansion in Sichuan-Chongqing and Yangtze River Delta manufacturing zones creates aftermarket coating growth vectors. MEE emissions standards and GB quality certification requirements govern spray-applied polyurethane product registration. Chengdu and Chongqing automotive production hubs concentrate dealer network development for regional fleet operators.
Truck Bedliner Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent protective coating applications in commercial vehicle and industrial equipment segments. The vendor base stratifies around formulation technology ownership, with proprietary polyurea chemistry access determining premium-tier participation. Three archetypes dominate: captive resin manufacturers with certified dealer networks, franchise-model applicators controlling quality through training infrastructure, and material-neutral installation specialists serving price-sensitive demand pools. Competitive maneuvering concentrates on geographic expansion of certified application capacity and portfolio diversification into adjacent protective coating categories.
Within the proprietary formulation tier, LINE-X and Rhino Linings exemplify divergent network strategies for quality-controlled application scale. LINE-X operates through company-owned resin production supporting certified dealer infrastructure, while Rhino Linings leverages global franchise licensing to standardize application protocols across independent operators. BedRug occupies a differentiated position representing carpet-composite hybrid designs that serve consumers seeking cargo protection without permanent vehicle modification. These three anchors illustrate how technology ownership and distribution architecture combine to define competitive position in a market where application quality variance directly influences customer retention.
| Leading Market Players |
|---|
| Rugged Liner |
| DualLiner |
| LINE-X |
| Scorpion Protective Coatings |
| Armadillo Liners |
| Rhino Linings |
| BedRug |
| WeatherTech |
| Penda Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EPA-compliant polyurea applicators and uncertified independent operators manifests in both pricing power and supply chain access. Premium-tier dealers command bundled warranty-service packages while commodity operators compete on unbundled installation cost alone, with Texas and California fleet procurement teams paying material premiums for certified network access.
Pricing Analysis
Warranty bundling separates premium spray-on installations from economy drop-in alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification investment, with CARB-compliant polyurea systems commanding highest quotes. Price differentiation hinges on applicator credential tier and geographic service density. Cost compression in the DIY roll-on segment intensifies because polyethylene drop-in substitutes require zero labor certification. Individual consumers in Michigan exhibit highest price sensitivity; commercial fleets in Texas show lowest.
Supply Chain Analysis
Certification gating concentrates resin supply among Gulf Coast captive producers and licensed importers. Isocyanate feedstock production clusters in Texas, Louisiana, and along the Houston Ship Channel petrochemical corridor. Raw material dependencies include MDI precursors, polyether polyols, and specialized spray rig components. Single-source vulnerability runs through concentrated isocyanate reactor capacity. Distribution runs through factory-authorized dealer networks and franchise-certified applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The truck bedliner market sits in a formulation-transition phase as low-VOC polyurea chemistry displaces legacy solvent-based polyurethane systems. Battery-electric truck thermal requirements are accelerating this replacement cycle.
For Market Incumbents: Lock in fleet procurement relationships through multi-year service contracts before electrification specifications harden. Deepen backward integration into captive resin production to insulate margins from MDI price volatility. Priority defensive moves include expanding California CARB-certified capacity and securing OEM thermal-interface development partnerships.
For New Entrants and Emerging Players: The premium-economy price gap in mobile fleet-yard application services offers white-space entry. Target Texas energy sector operators with deployable spray rigs that bypass shop-based bottlenecks. Pursue state environmental incentive program qualification as the fastest certification path.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by protective coating conglomerates seeking spray-application capabilities. Long-term viability favors applicators with proprietary formulation access and certified network scale. Watch battery-electric truck platform launches as the inflection signal for thermal-adapted specification demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Low-VOC Equipment Upgrade | CARB rebate eligibility opens California fleet procurement access. |
| Mobile Application Unit Deployment | Deployable spray rigs capture fleet-yard service contracts bypassing fixed shops. |
| Polyurea Formulation Partnership | Proprietary chemistry access determines premium-tier participation rights. |
| Thermal Interface R&D Investment | Battery-electric cooling integration specifications remain uncontracted white space. |
| Franchise Network Consolidation | Certified dealer acquisition concentrates application quality control. |
Methodological Framework
Trade association filings, EPA emissions compliance databases, and automotive production statistics formed the secondary backbone of this study. Primary interviews with spray applicator network managers, fleet procurement directors, chemical formulation specialists, and aftermarket distribution executives combined with customs data and SEC filings for bottom-up and top-down triangulation.
Bottom-up modeling aggregated segment-level volume and value estimates across formulation chemistry, installation method, vehicle architecture, and end-user procurement authority. Top-down validation cross-checked aggregate figures against petrochemical feedstock consumption patterns and certified applicator network expansion rates. CAGR derivation incorporated fleet electrification timelines, state regulatory phase-in schedules, and thermal specification evolution across the projection horizon.
Inputs from primary fieldwork and regulatory filings were available through the study window; gaps in real-time fleet contract pricing introduce uncertainty bands around commercial segment estimates. Forecasts reflect documented assumptions regarding electrification adoption curves and VOC compliance enforcement intensity. A model refresh is warranted upon material change in battery-electric truck platform specifications or federal emissions standard revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
Utility Trucks Market
Heavy-Duty Trucks
Europe Medium and Heavy-Duty Commercial Vehicles Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Flatbed Truck Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market