
 Large Synchronous Motor Market | 2026-2036
Large Synchronous Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Large Synchronous Motor Market Outlook
Direct procurement channels between original equipment manufacturers and end-user utilities is reconfiguring as long-term service contracts replace transactional equipment sales. Siemens AG leverages its digital service platforms to lock in multi-decade maintenance relationships across European power utilities. ABB Ltd. anchors its competitive stance through backward integration into high-voltage insulation systems that reduce third-party dependency. WEG S.A. competes aggressively in Latin American mining electrification projects where local content rules favor regional suppliers.
Large synchronous motors are AC machines operating at constant speed synchronized with supply frequency, typically rated above 1 MW and employing wound-field or permanent-magnet rotor constructions for precision torque delivery in heavy industrial processes. High voltage synchronous motors dominate margin pools in power generation and LNG compression trains where reliability premiums outweigh capital costs. Variable speed technology segments are expanding fastest as digital control architectures enable synchronous motors to displace variable-frequency-driven induction units in pump and fan applications. Specialty motor configurations for marine propulsion remain niche but command substantial engineering premiums due to classification society certification requirements.
IEC 60034 efficiency standards and the EU Ecodesign Directive constrain market access for motors below specified performance tiers, while China's GB 18613 and GB 30254 standards enforce parallel efficiency escalations in the world's largest manufacturing base. The US Department of Energy administers comparable minimum efficiency regulations through 10 CFR 431 that shape North American procurement specifications. Stakeholders must monitor divergence between regional efficiency test methods and carbon-border adjustment mechanisms that could fragment certified product lines across jurisdictions.
Market Dynamics
Long-term service contracts are displacing transactional equipment sales across power generation and heavy industrial sectors, locking capital equipment vendors into multi-decade revenue streams anchored by predictive maintenance platforms and performance guarantees.
Growth Catalysts
- EU Ecodesign Directive:Efficiency mandates for motors above 1 MW are accelerating replacement cycles in European process industries and compressing payback periods for premium synchronous units.
- LNG compression trains:Baseload power demand from liquefaction facilities in Qatar and Australia is pulling high-reliability synchronous motors into cryogenic service applications.
- Grid-forming inverters:Synchronous condenser retrofits at retiring coal plants in Germany and Poland are creating replacement demand for rotating stability assets.
Market Restraints
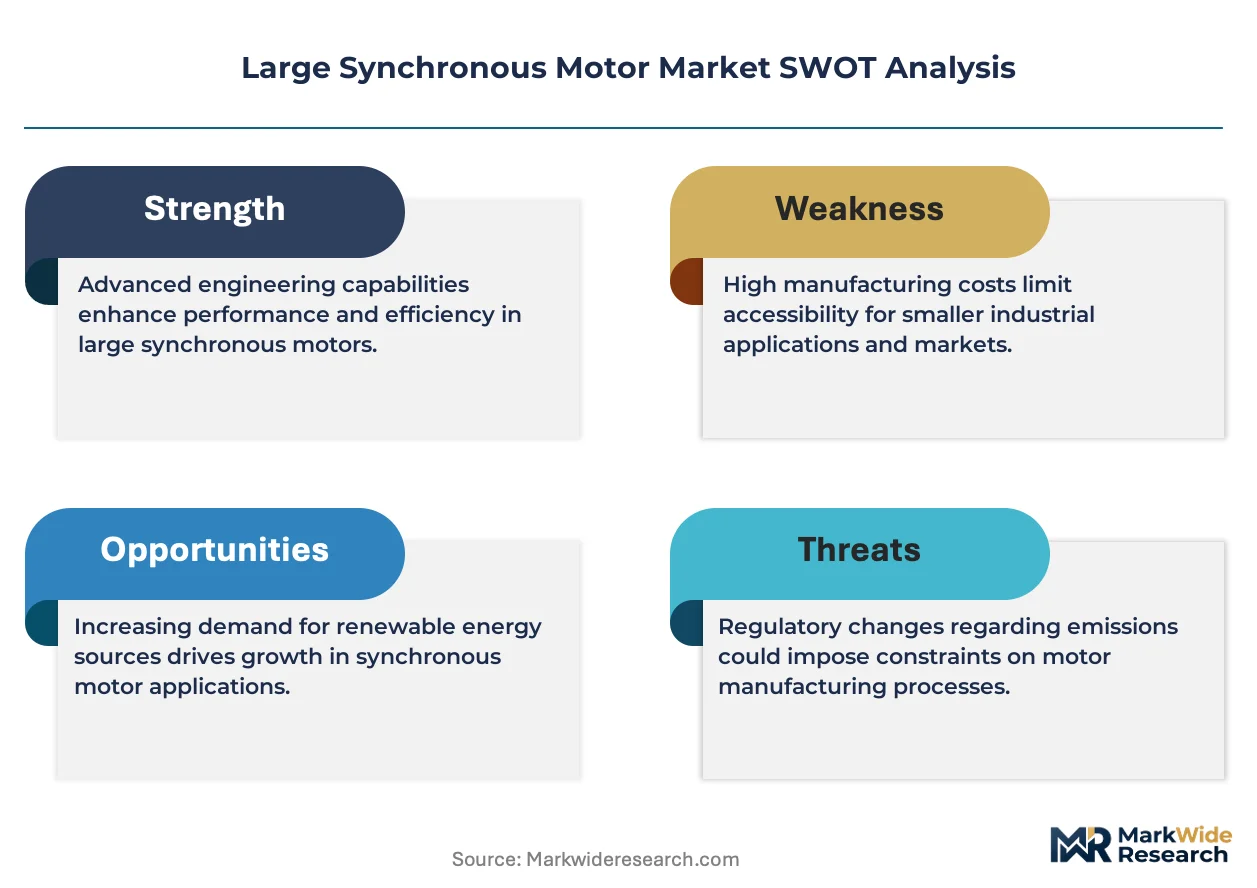
- Copper and electrical steel volatility:Wound-field rotor construction depends on commodity inputs with concentrated supply from Chilean mining operations and Japanese specialty steel mills.
- Permanent magnet supply concentration:Rare-earth processing capacity clusters in China's Jiangxi and Inner Mongolia provinces, exposing non-Chinese motor manufacturers to export control risks.
- Induction motor cost floor:Squirrel-cage induction units maintain capital cost advantages below 5 MW ratings in pump and fan applications where precision speed control remains secondary.
Strategic Opportunities
- India's western manufacturing corridors:Gujarat and Maharashtra state industrial policies favor capital goods localization, opening procurement access for joint-venture motor assembly operations.
- Marine electrification:Classification society certification for ice-class propulsion motors commands engineering premiums in Finnish and Korean shipyard contracts.
- Digital twin integration:Convergence of physics-based motor modeling with edge computing architectures enables predictive maintenance contracts that capture lifetime value from power utility customers.
Industry Challenges
- High-voltage insulation engineering:Specialized winding expertise for 6.6 kV and 11 kV ratings concentrates at a handful of European and Japanese technical centers, constraining workforce scalability.
- IEC 60034-27-3 compliance timelines:Partial discharge testing protocols for stator windings extend factory acceptance test durations and compress delivery schedules for project-driven orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Synchronous Motor Market |
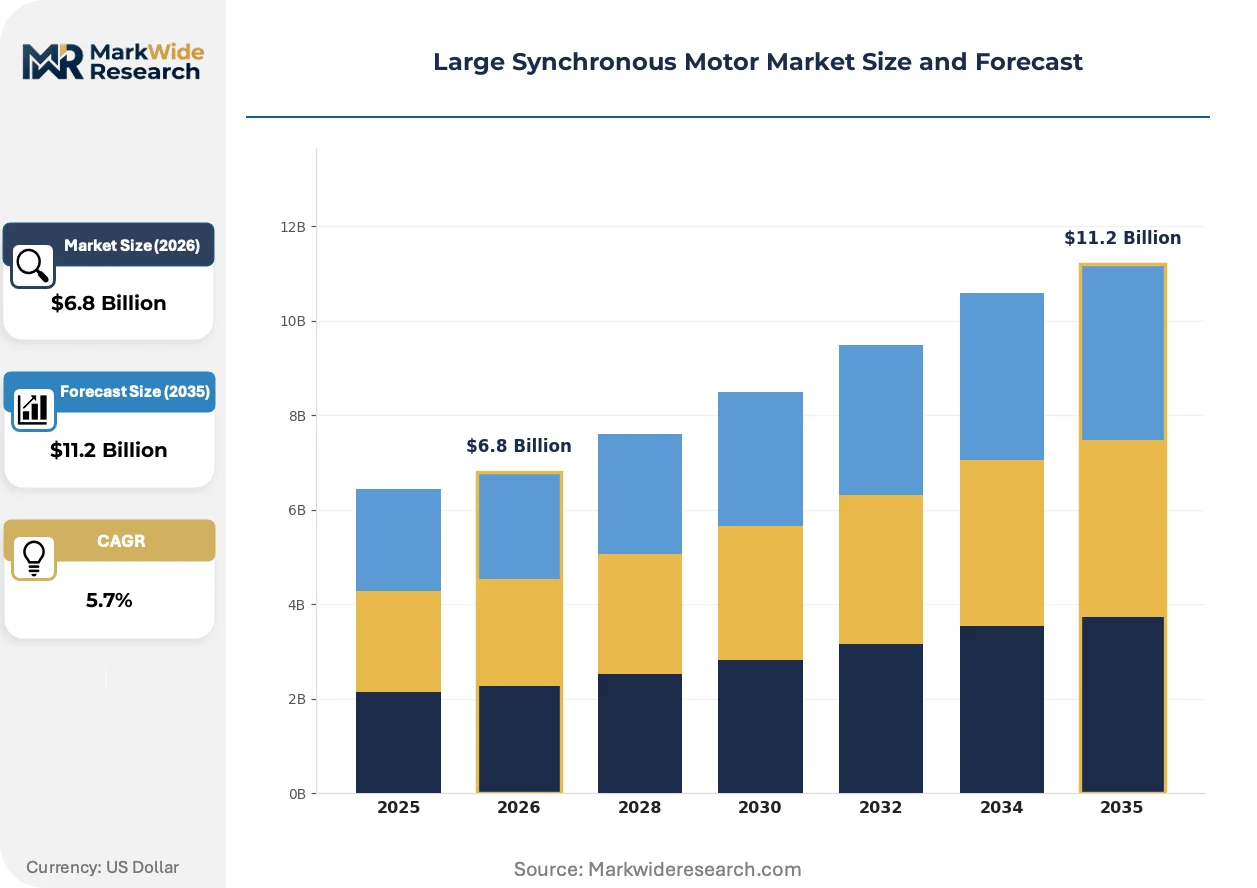
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Voltage, Medium Voltage, Low Voltage, Specialty Application: Power Generation, Oil & Gas, Mining, Marine End User: Utilities, Industrial Manufacturers, Mining Operations, Marine Operators Technology: Digital Control, Conventional, Torque Control, Variable Speed |
| Companies Covered | Nidec Corporation, TMEIC Corporation, ABB Ltd., HD Hyundai Electric Co., Ltd., GE Vernova, Siemens AG, Toshiba Corporation, VEM GmbH, WEG S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Synchronous Motor Market Strategic Shifts
Digital control architectures are collapsing the functional boundary between synchronous and induction motor applications, enabling precision torque delivery without mechanical gearbox intervention across pump, fan, and compressor duty cycles.
Permanent magnet rotor technology is collapsing the efficiency gap between synchronous and induction machines in variable-speed applications. Oil and gas operators in the North Sea and Permian Basin are retrofitting PM synchronous motors onto existing compressor skids to eliminate gearbox maintenance and reduce footprint. This substitution is collapsing lifecycle cost calculations that previously favored induction motors with variable frequency drives.
China's GB 18613 and GB 30254 efficiency standards are tightening performance thresholds for motors above 375 kW, forcing domestic manufacturers to abandon wound-field designs below IE4 efficiency tiers. Provincial procurement guidelines in Shandong and Jiangsu now require IE5-equivalent synchronous motors for new industrial park connections. European exporters must recertify test methods to demonstrate compliance with Chinese load-cycle protocols.
Power utilities are unbundling equipment procurement from long-term maintenance obligations, creating standalone service contracts that transfer operational risk to motor OEMs. This disintermediation of traditional EPC channels concentrates in German and French distribution grid modernization programs. Siemens and ABB now compete on guaranteed availability metrics rather than capital cost bids for synchronous condenser installations.
Large Synchronous Motor Market Segmentation
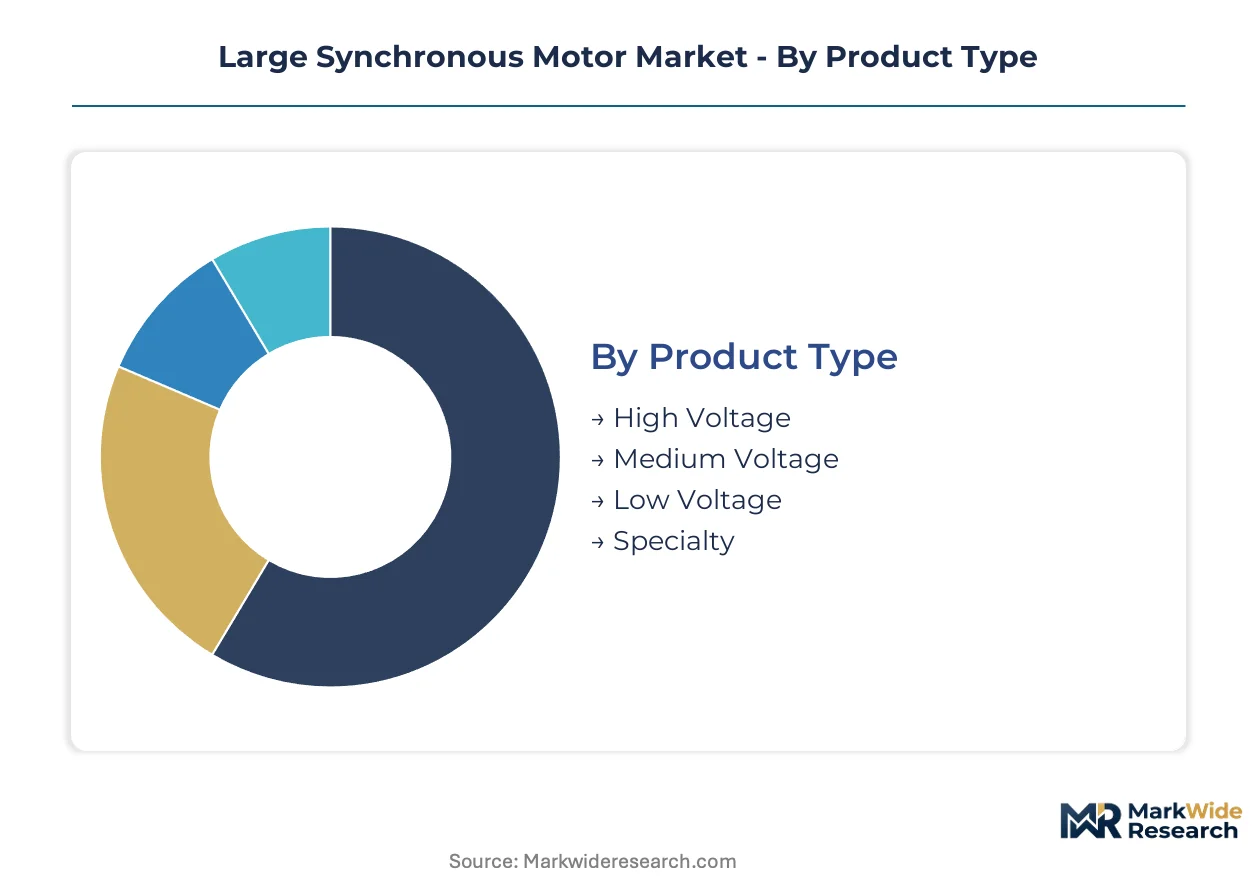
Segmentation in the Large Synchronous Motor Market reveals distinct margin profiles and service intensity patterns across voltage classes and duty cycles. Procurement specifications diverge sharply between utilities prioritizing reliability premiums and industrial operators optimizing lifecycle costs.
Product Type:
After-sales service intensity escalates with voltage rating as high-voltage units demand specialized winding maintenance and predictive diagnostics over multi-decade operational lifespans.
- High Voltage:Units rated 6.6 kV and above employ mica-based insulation systems and vacuum pressure impregnation for grid stability and LNG compression duty. European power utilities in Germany and Poland anchor replacement demand through synchronous condenser retrofits at retiring coal facilities.
- Medium Voltage:Motors between 1 kV and 6.6 kV serve process industries with wound-field or permanent-magnet rotors. China's Shandong and Jiangsu provincial procurement guidelines now mandate IE5-equivalent efficiency for new industrial park connections.
- Low Voltage:Compact synchronous designs below 1 kV target precision positioning in automated manufacturing lines.
- Specialty:Custom-engineered units for cryogenic or hazardous environments command extended factory acceptance testing.
By volume, Medium Voltage leads. By growth pace, High Voltage is ahead.
Application:
Capital deployment cycles stretch longest in marine propulsion where classification society certification extends order-to-delivery timelines beyond eighteen months.
- Power Generation:Grid-forming applications and synchronous condenser installations stabilize transmission networks against inverter-based renewable intermittency. German distribution grid modernization programs now unbundle equipment procurement from long-term maintenance obligations.
- Oil & Gas:LNG liquefaction trains in Qatar and Australia pull high-reliability motors into cryogenic service with guaranteed availability contracts replacing capital cost bids.
- Mining:Electrification projects in Latin American copper operations favor regional suppliers under local content rules.
- Marine:Ice-class propulsion motors for Finnish and Korean shipyards command substantial engineering premiums due to DNV and Korean Register certification requirements.
By installed base, Power Generation dominates. By margin expansion, Marine is climbing the fastest.
End User:
Procurement sophistication varies by balance-sheet capacity as utilities leverage long-term service contracts while mining operators prioritize capital cost containment.
- Utilities:Transmission system operators specify guaranteed availability metrics and predictive maintenance platforms for synchronous condenser installations. French and German unbundling of EPC channels concentrates operational risk transfer to motor OEMs.
- Industrial Manufacturers:Process industry procurement in India's Gujarat and Maharashtra states favors joint-venture assembly operations under localization policies.
- Mining Operations:Copper and iron ore electrification projects in Brazil and Chile specify ruggedized enclosures for dust-laden environments.
- Marine Operators:Cruise and cargo lines demand redundant excitation systems for single-failure-proof propulsion.
By contract value, Utilities anchor revenue. By localization requirements, Industrial Manufacturers are gaining share fastest.
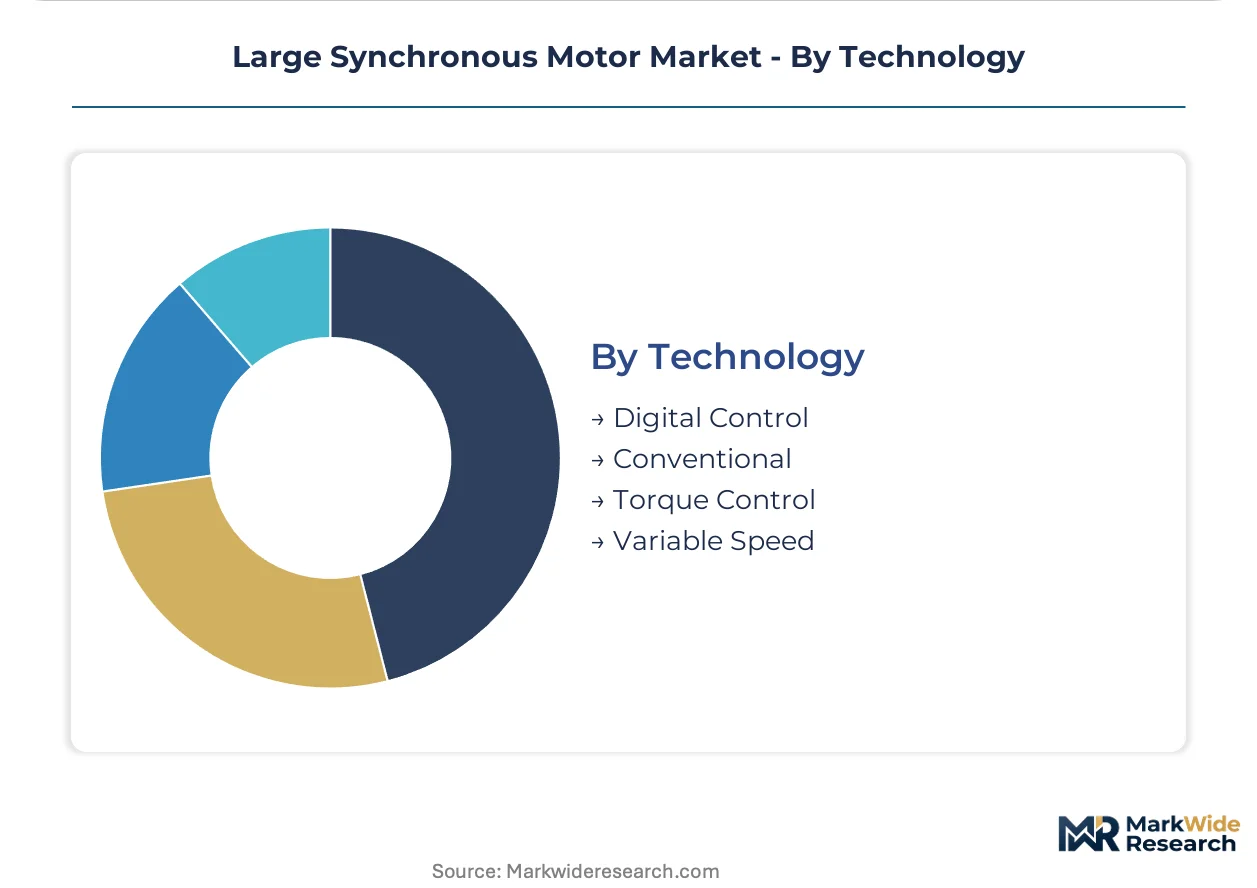
Technology:
Control architecture differentiation determines whether synchronous motors displace induction units in variable-speed pump and fan applications.
- Digital Control:Edge-computing-enabled motor management platforms collapse the functional boundary between synchronous and induction applications. Physics-based digital twin integration enables predictive maintenance contracts capturing lifetime value from power utility customers.
- Variable Speed:Permanent magnet rotor technology eliminates gearbox maintenance in North Sea and Permian Basin compressor retrofits. This substitution collapses lifecycle cost calculations that previously favored induction motors with variable frequency drives.
- Conventional:Wound-field designs with static excitation persist in cost-sensitive heavy industrial duty.
- Torque Control:Precision torque delivery architectures target rolling mill and extruder applications without mechanical gearbox intervention.
By deployment share, Conventional retains volume leadership. By substitution momentum, Variable Speed shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The East-West Power Interconnector underwrites Germany's role as Europe's grid stability hub, anchoring synchronous condenser demand at retiring coal sites. Qatar's North Field LNG expansion and Australia's Curtis Island liquefaction trains pull high-reliability motors into cryogenic compression service. India's Western Dedicated Freight Corridor electrification concentrates procurement in Gujarat and Maharashtra manufacturing belts.
Germany
Synchronous condenser retrofits at retiring lignite plants in Brandenburg and Saxony-Anhalt stabilize transmission networks against renewable intermittency. The EU Ecodesign Directive mandates IE4 efficiency minimums for motors above 1 MW, compressing replacement cycles. Grid operators in the Ruhr industrial cluster now unbundle equipment procurement from twenty-year maintenance contracts.
China
Provincial procurement guidelines in Shandong and Jiangsu mandate IE5-equivalent synchronous motors for new industrial park grid connections. GB 18613 and GB 30254 efficiency standards force domestic manufacturers to abandon wound-field designs below premium tiers. The Yangtze River Delta manufacturing belt concentrates demand from petrochemical complexes in Ningbo and integrated steelworks in Shanghai.
India
Gujarat and Maharashtra state industrial policies favor capital goods localization, opening procurement access for joint-venture motor assembly operations. The Central Electricity Authority mandates grid-forming assets for renewable-rich western states. The Mumbai-Pune manufacturing corridor anchors demand from cement plants and textile processing clusters seeking precision torque control.
Qatar
North Field LNG expansion trains pull high-reliability synchronous motors into cryogenic service with guaranteed availability contracts replacing capital cost bids. Qatar Petroleum's localization requirements favor suppliers with regional service infrastructure. Ras Laffan Industrial City concentrates compression duty applications for baseload liquefaction capacity.
Australia
Curtis Island LNG facilities in Queensland anchor demand for high-voltage units in gas turbine starter and refrigeration compressor duty. The Australian Energy Market Operator's system strength requirements drive synchronous condenser installations at weak grid nodes. The Pilbara mining region electrifies haul truck and conveyor systems, pulling medium-voltage motors into dust-laden environments.
Large Synchronous Motor Market Competitive Environment
On the supply side, the industry is consolidating around integrated electrical equipment conglomerates with captive high-voltage insulation capabilities. Tier-one vendors compete through backward integration into specialty steel laminations and rare-earth magnet supply chains. Strategic archetypes include full-service platform providers, regional mining electrification specialists, and component-integrated technology licensors. Dominant competitive moves span long-term service contract capture and predictive maintenance platform deployment.
Among Japanese electrical equipment conglomerates, Toshiba Corporation and Nidec Corporation occupy positions within the premium industrial motor tier, exemplifying integrated manufacturing depth. TMEIC Corporation anchors the variable-speed drive-motor system archetype. European-based ABB Ltd. and Siemens AG represent full-service platform providers competing on guaranteed availability metrics rather than capital cost bids. Brazilian WEG S.A. and Korean HD Hyundai Electric Co., Ltd. sit within regional specialist archetypes favored by local content rules in Latin American and Asian procurement frameworks respectively.
| Leading Market Players |
|---|
| Nidec Corporation |
| TMEIC Corporation |
| ABB Ltd. |
| HD Hyundai Electric Co., Ltd. |
| GE Vernova |
| Siemens AG |
| Toshiba Corporation |
| VEM GmbH |
| WEG S.A. |
| Others |
Value Chain & Pricing Dynamics
Jiangxi Province's rare-earth processing clusters anchor global permanent magnet supply, concentrating pricing power among integrated manufacturers who control upstream magnet alloy production. This geographic concentration cascades into motor OEM procurement costs, where magnet content drives 15-25% of variable production expenses and amplifies volatility exposure for non-Chinese assemblers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies synchronous motor procurement. Premium tiers command substantial engineering premiums for IEC 60034-27-3 certification and guaranteed availability contracts, while standard tiers optimize lifecycle cost for process industries. Price differentiation hinges on efficiency tier certification and after-sales bundling intensity. Cost compression in economy wound-field units is intensifying because Chinese domestic manufacturers abandon sub-IE4 designs under GB 18613 mandates. Mining operators exhibit highest price sensitivity, whereas European utilities prioritize reliability metrics over capital cost minimization.
Supply Chain Analysis
Contract manufacturing capacity for high-voltage insulation systems concentrates at European technical centers in Germany and Switzerland, with Japanese specialty producers holding secondary positions. Raw material flows draw from Chilean copper concentrate, Japanese electrical steel mills, and Chinese rare-earth separation facilities. Single-source vulnerability in heavy rare-earth elements presents structural risk for permanent magnet rotor supply chains. Distribution runs through direct OEM-utility procurement channels that disintermediate traditional EPC contractors, particularly in German and French grid modernization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbent positions. Efficiency standard compliance creates switching costs that lock utilities into established supplier relationships across multi-decade service horizons.
For Market Incumbents: Insulate margin positions through backward integration into high-voltage insulation winding capabilities and captive rare-earth magnet supply agreements. Siemens AG's digital service platform architecture demonstrates how predictive maintenance contracts transfer operational risk and capture lifetime value from European transmission operators. Capacity expansion in India's Gujarat joint-venture assembly corridors addresses localization mandates while preserving technical control. For New Entrants and Emerging Players: Build out regional service infrastructure in Latin American mining electrification corridors where Brazilian and Chilean local content rules favor regional suppliers over integrated conglomerates. Marine propulsion certification for ice-class applications presents penetrable white space where Finnish and Korean shipyards demand specialized engineering capabilities that incumbent platforms underweight. Target aftermarket retrofit opportunities in North Sea compressor installations where permanent magnet synchronous substitution eliminates gearbox maintenance burdens. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component-integrated specialists with captive high-voltage insulation expertise over pure-play motor assemblers. Long-term viability across the analysis window rests on digital twin platform deployment and guaranteed availability contract penetration. Acquisition screening should prioritize firms with IEC 60034-27-3 testing infrastructure and established utility maintenance relationships. The signal to watch is unbundling velocity in European EPC channels, where operational risk transfer to OEMs accelerates service revenue capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Captive rare-earth sourcing insulates Qingdao and Ningbo manufacturers from export control exposure. |
| Digital Twin Platform Deployment | Physics-based motor modeling enables predictive maintenance contracts with German transmission operators. |
| Joint Venture Assembly Localization | Gujarat and Maharashtra state policies favor regional production for western India industrial corridor demand. |
| Synchronous Condenser Retrofit Capture | Grid-forming asset installations at retiring Polish and German coal plants anchor replacement revenue streams. |
| Marine Certification Investment | DNV and Korean Register ice-class approval commands engineering premiums in Finnish shipyard contracts. |
Study Parameters
Desk research of IEC standard documentation, national efficiency regulation filings, and utility procurement databases preceded structured interviews with plant engineering directors, OEM procurement managers, aftermarket service heads, and grid planning officers at transmission system operators. Secondary validation drew from customs trade data, SEC equipment manufacturer filings, and power sector capital expenditure disclosures. Bottom-up unit deployment estimates were triangulated against top-down industrial electricity demand projections.
Assumptions regarding copper and electrical steel price stability, efficiency standard enforcement timelines, and renewable penetration rates were held fixed across baseline scenarios while tariff exposure and rare-earth export restriction probabilities were stress-tested. The analytical framework modeled deployment across voltage class, application duty cycle, rotor technology type, and regional regulatory cluster dimensions. CAGRs were derived from segment-level unit economics and replacement cycle compression under efficiency mandates.
Stress conditions across commodity input volatility, regulatory divergence between EU Ecodesign and Chinese GB test protocols, and grid interconnection project delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding synchronous condenser retrofit timelines and LNG liquefaction train commissioning schedules. Quarterly review of efficiency standard amendment proposals, rare-earth export license volumes, and utility unbundling policy developments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Motorcycle Lead Acid Battery Market
Electric Motor
North America Alternating Current (AC) Motor Market
Electric Motor
Smart E-Drive Market
Electric Motor
Europe Electric Motors for Electric Vehicle Market
Electric Motor
APAC Electric Drives Market
Electric Motor
Automotive Hub Motors Market
Electric Motor
Europe Alternating Current (AC) Motor Market
Electric Motor
Two Wheeler Electric Starter Magnet Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
UK Solar E-Bike Market
Electric Motor
Automotive Heater Fan Motor Market
Electric Motor
Electric Traction Motor Market
Electric Motor
Brush Motor Control Unit Market
Electric Motor
Global Automotive Heating Fan Motor Market
Electric Motor
Electric Vehicle Motor Control Unit Market
Electric Motor
Intelligent Motor Controller Market