
 Australia Mining Logistics Market | 2026-2036
Australia Mining Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Mining Logistics Market Outlook
Truck driver availability is collapsing across Western Australia's Pilbara mining corridors, forcing operators to accelerate autonomous rail and road solutions. Aurizon leverages its east-west rail network to sustain bulk iron ore haulage dominance. Qube anchors port logistics and intermodal services across multiple Australian mining jurisdictions. Pacific National competes on transcontinental rail capacity linking Bowen Basin coal fields to Gladstone export terminals.
Australia mining logistics encompasses the planning, execution, and control of material flows from extraction sites through processing facilities to export ports, typically involving bulk commodity trains of 30,000+ tonne capacity and specialized heavy-haul rail infrastructure designed for 40-tonne axle loads. The primary purpose is minimizing unit costs per tonne-kilometer while maintaining supply reliability for time-sensitive commodity contracts. Transportation services dominate value capture given rail and port infrastructure intensity, while third-party logistics models are expanding fastest as miners outsource non-core supply chain functions to specialist operators. Warehousing of spare parts and chemicals remains fragmented with lower barriers to entry and thinner margin pools concentrated near regional maintenance hubs.
TGA, the National Heavy Vehicle Regulator, and state-based rail safety regulators collectively shape equipment certification, driver fatigue rules, and autonomous vehicle trial permissions across Australian mining corridors. The Australian Rail Track Corporation's access pricing and corridor investment decisions directly influence route economics for bulk commodity movers. Stakeholders must monitor how evolving autonomous vehicle liability frameworks and carbon disclosure requirements under the National Greenhouse and Energy Reporting scheme reshape capital allocation between rail electrification and diesel automation.
Market Dynamics
Autonomous haulage systems are decomposing traditional labor-dependent operating models across Western Australia's Pilbara iron ore corridors, compressing cost structures while forcing wholesale reconfiguration of workforce deployment and capital allocation strategies.
Growth Catalysts
- Heavy Vehicle National Law amendments:TGA and state regulators are streamlining autonomous vehicle trial permissions, accelerating deployment timelines for driverless truck and rail fleets across Queensland and Western Australia mining corridors.
- Battery-electric haulage:Zero-emission truck and locomotive pilots are attracting capital as miners face National Greenhouse and Energy Reporting scheme disclosure pressures and scope 3 emissions scrutiny from Asian offtakers.
- Port terminal automation:Automated stacking cranes and unmanned vessel loading systems at Port Hedland and Dampier are lifting throughput capacity without proportional labor expansion, matching export demand from Chinese and Japanese steelmakers.
Market Restraints
- Diesel fuel price volatility:Heavy-haul rail and road fleets remain 85%+ diesel-dependent, exposing operators to bunker fuel price swings that rail access charges cannot fully hedge.
- Specialized maintenance labor scarcity:Remote Pilbara and Bowen Basin locations struggle to retain heavy diesel fitters and automation technicians, inflating wage premiums and contractor dependence.
- Single-corridor rail concentration:Aurizon and Pacific National control east-west and north-south bulk rail infrastructure, limiting third-party access and competitive rate negotiation for mid-tier miners.
Strategic Opportunities
- Intermodal containerization of bulk:Qube and specialist operators are piloting containerized iron ore and concentrate movements, opening door-to-door logistics contracts bypassing traditional bulk terminal queues.
- Regenerative braking and solar rail electrification:ARENA funding and state renewable mandates are creating capital subsidies for pilot electrification of Pilbara heavy-haul lines, displacing diesel locomotive capex cycles.
- Remote operations centers:Perth-based integrated remote operations hubs are consolidating dispatch, maintenance scheduling, and supply chain control for multi-site miners, reducing fly-in-fly-out headcount.
Industry Challenges
- Legacy fleet integration with autonomous systems:Mixed fleets of manned and driverless trucks require segregated haul road zones and complex traffic management protocols, slowing full-site automation.
- Functional safety certification delays:AS 61508 and rail-specific safety case approvals for autonomous haulage systems stretch 18-24 months, delaying revenue realization from automation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Mining Logistics Market |
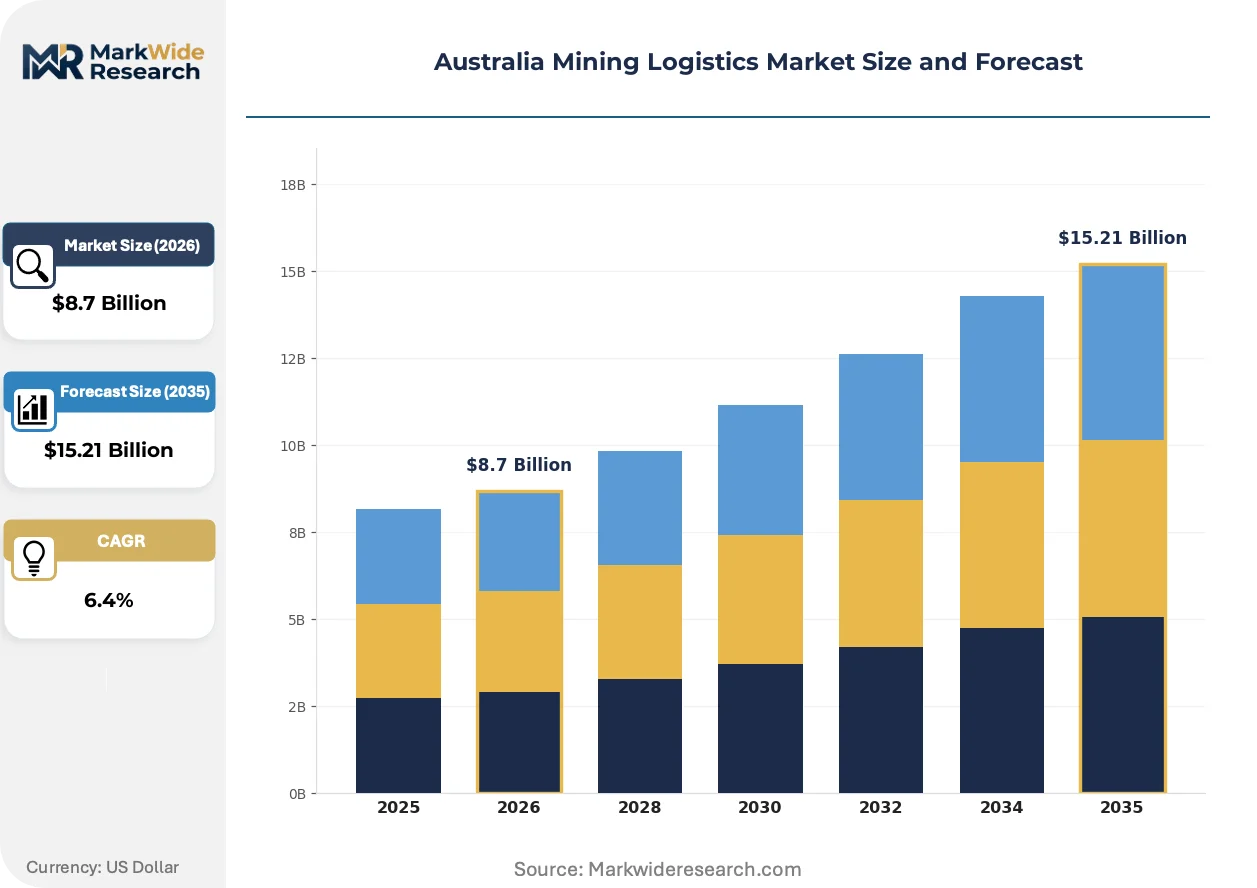
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Custom Clearance Logistics Model: Third-party Logistics, Fourth-party Logistics, In-house Logistics, Integrated Logistics Material Type: Raw Materials, Heavy Equipment, Spare Parts, Chemicals End User: Mining Companies, Suppliers, Contractors, Distributors |
| Companies Covered | Aurizon, Qube, BHP, Pacific National, Linfox, Rio Tinto, Toll Holdings, NRW Holdings, Fortescue Metals Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Mining Logistics Market Strategic Shifts
Digital twin technology and predictive maintenance platforms are penetrating Australian mining logistics, compressing equipment downtime and shifting maintenance from scheduled to condition-based intervention models.
Autonomous haul trucks operating on private mining roads are decomposing the traditional owner-operator employment model in Western Australia's Pilbara. Rio Tinto and BHP have deployed 500+ driverless haul trucks across Yandicoogina and Newman hubs, eliminating approximately 1,500 driving positions since 2018. This technology is decomposing labor cost structures while forcing logistics providers to retrain workforces into remote monitoring and maintenance roles.
TGA's evolving guidance on autonomous vehicle safety cases and the National Heavy Vehicle Regulator's fatigue exemption frameworks for single-driver long-haul combinations are reshaping operational compliance burdens. Western Australia and Queensland regulators have diverged on autonomous rail signaling standards, creating dual-track certification requirements for interstate operators. Heavy-haul rail segments face the steepest compliance adaptation costs as ARTC access agreements incorporate new safety technology mandates.
Miners are consolidating logistics procurement under enterprise-wide supply chain functions, displacing site-level contracting autonomy. BHP and Fortescue Metals Group have centralized rail and port logistics tendering through Melbourne and Perth headquarters, compressing supplier relationship management into fewer, larger framework agreements. This concentration is most visible in iron ore, where three miners control 90%+ of Pilbara export volume and negotiate rail access as bloc purchasers.
Australia Mining Logistics Market Segmentation
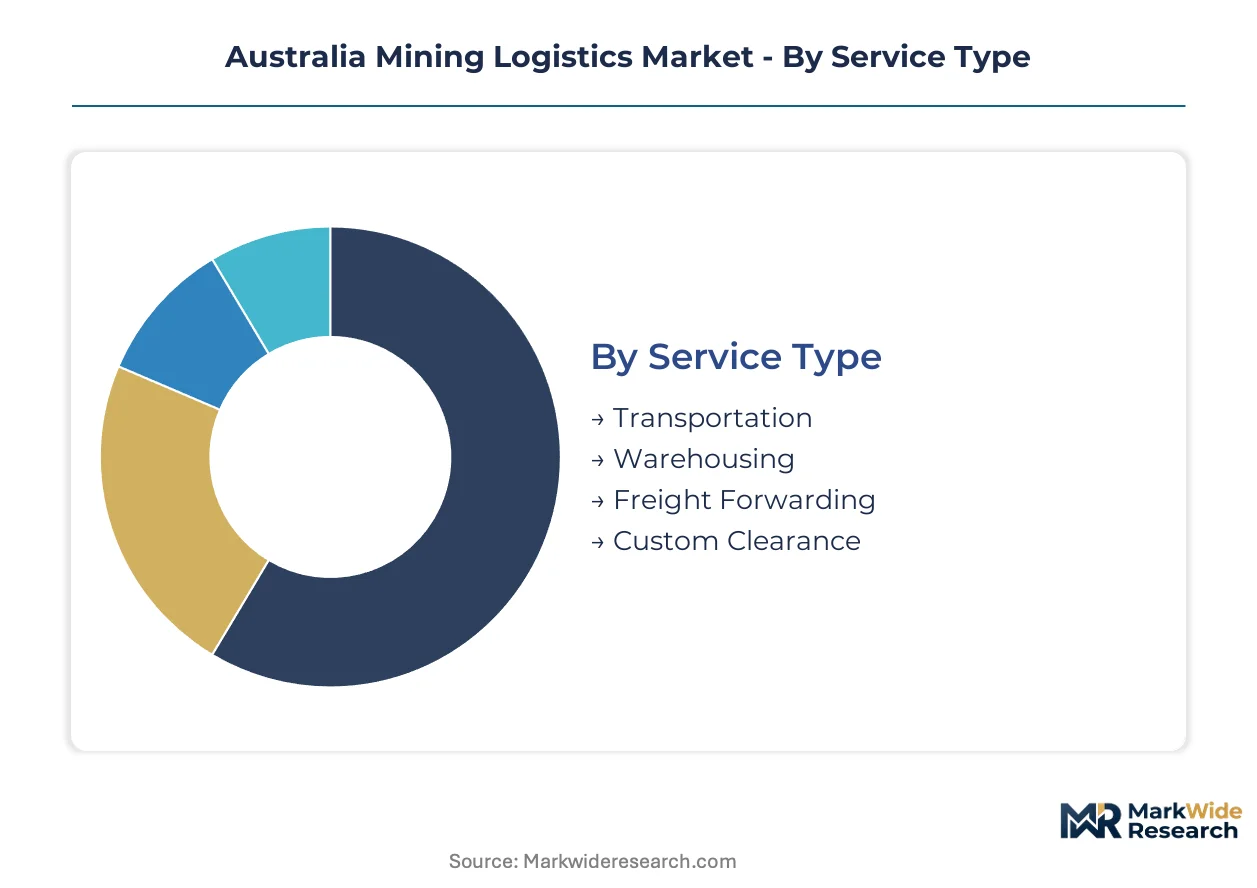
Segmentation in Australian mining logistics reveals how value capture concentrates around infrastructure-heavy service layers and outsourced supply chain control. Understanding these divisions exposes where rail access rights, port terminal capacity, and automation investments reshape competitive positioning.
Service Type:
Transportation commands the deepest margin pools given heavy-haul rail infrastructure scarcity and port terminal bottlenecks across Pilbara and Bowen Basin corridors.
- Transportation:Bulk commodity rail haulage and heavy-haul road movements dominate value capture. Iron ore trains of 30,000+ tonne capacity linking Pilbara mines to Port Hedland and Dampier terminals concentrate demand from BHP, Rio Tinto, and Fortescue Metals Group under long-term take-or-pay contracts.
- Warehousing:Remote maintenance hubs store spare parts and consumables near Newman, Tom Price, and Moranbah. Labor scarcity and fly-in-fly-out costs compress margins compared to transportation, with fragmentation across regional operators serving single-site contracts.
- Freight Forwarding:Documentation and customs coordination for export-bound concentrates and processed materials.
- Custom Clearance:Regulatory compliance and quarantine processing for cross-border equipment imports and chemical shipments.
Transportation holds installed capacity. Warehousing is rotating up the share rankings as miners consolidate maintenance procurement under enterprise-wide frameworks.
Logistics Model:
Cost tier stratification separates capital-intensive infrastructure operators from asset-light coordination services, with third-party models expanding fastest as miners shed non-core functions.
- Third-party Logistics:Specialist operators like Qube and Aurizon manage rail haulage, port logistics, and intermodal transfers under multi-year contracts. Asset ownership and corridor access rights create defensive moats against in-house alternatives.
- Fourth-party Logistics:Supply chain orchestration without direct asset control. Perth-based remote operations centers consolidate dispatch and planning across multi-site miners, gaining traction as automation reduces need for on-ground presence.
- In-house Logistics:BHP and Rio Tinto retain direct control over core rail and port infrastructure to protect volume commitments and operating cost visibility.
- Integrated Logistics:End-to-end contract structures combining transportation, warehousing, and freight forwarding under single accountability.
Third-party Logistics anchors current contract volumes. Fourth-party Logistics is climbing the fastest as remote operations technology matures.
Material Type:
Application criticality determines service intensity, with raw materials movements commanding dedicated infrastructure while chemicals require specialized handling certification.
- Raw Materials:Iron ore, metallurgical coal, and bauxite movements absorb the bulk of rail and port capacity. Western Australia's Pilbara region generates the heaviest flow volumes, with automated loading systems at Port Hedland matching Chinese steelmaker demand cycles.
- Heavy Equipment:Excavator, haul truck, and processing plant relocations between mine sites. Oversized load permits and specialized low-loader fleets create supplier concentration around Perth and Brisbane equipment hubs.
- Spare Parts:Critical component availability for autonomous haul fleets and rail locomotives.
- Chemicals:Explosives, reagents, and processing chemicals requiring TGA and state dangerous goods licensing.
Raw Materials holds installed capacity. Heavy Equipment is gaining share fastest as mine development cycles accelerate across Queensland lithium and rare earth projects.
End User:
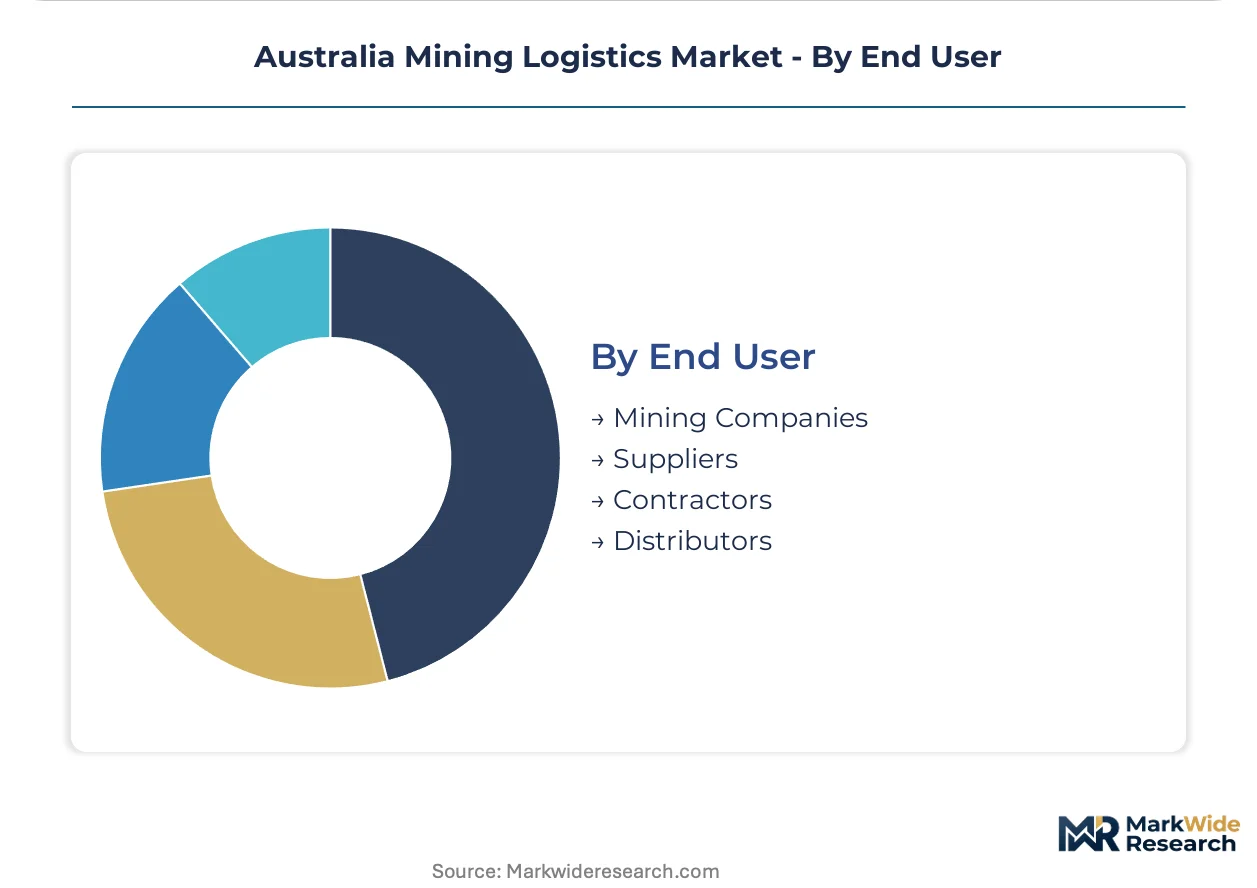
Customer concentration shapes contract structures, with mining companies leveraging volume scale for rail access preference while contractors fragment procurement across project timelines.
- Mining Companies:BHP, Rio Tinto, Fortescue, and Glencore negotiate rail and port access as bloc purchasers. Centralized procurement through Melbourne and Perth headquarters compresses supplier relationships into framework agreements spanning multiple sites.
- Suppliers:Equipment manufacturers and consumables providers managing inbound logistics to remote sites. Containerized delivery pilots by Qube are opening door-to-door contracts bypassing traditional bulk terminal queues.
- Contractors:Drilling, blasting, and construction services with project-based logistics needs.
- Distributors:Intermediate stockholders of spare parts and maintenance supplies.
Mining Companies hold installed capacity. Suppliers is expanding most quickly as original equipment manufacturers assume logistics responsibility for remote site delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TGA and state-based rail safety regulators anchor Western Australia's dominance in mining logistics infrastructure, with the National Heavy Vehicle Regulator coordinating autonomous vehicle trials across Queensland and New South Wales corridors.
Western Australia
Pilbara iron ore exports drive heavy-haul rail demand from Newman and Tom Price to Port Hedland and Dampier terminals. The Australian Rail Track Corporation's access pricing framework shapes route economics for bulk commodity movers. Perth-based remote operations centers consolidate dispatch control for autonomous haul fleets across Yandicoogina and Newman hubs.
Queensland
Bowen Basin metallurgical coal corridors link Moranbah and Blackwater mines to Gladstone export terminals serving Asian steelmakers. State rail safety regulators have diverged from Western Australian autonomous signaling standards, creating dual-track certification requirements. Heavy-haul infrastructure investment concentrates on the Goonyella and Blackwater rail systems.
New South Wales
Hunter Valley thermal coal logistics and emerging critical minerals movements from Broken Hill define regional demand. The National Heavy Vehicle Regulator's fatigue exemption frameworks for long-haul combinations reshape road freight compliance. Port Newcastle and Port Kembla anchor export capacity for diversified mineral flows.
Victoria
Specialized equipment manufacturing and Melbourne headquarters functions for mining logistics procurement concentrate service provider decision-making. Enterprise-wide supply chain centralization by major miners compresses supplier relationships into framework agreements negotiated from Victorian corporate offices. Containerized bulk pilots are emerging through Melbourne intermodal terminals.
South Australia
Olympic Dam copper and Olympic Dam logistics corridors, plus emerging rare earth projects, drive specialized heavy equipment movements. Remote site access challenges and maintenance hub scarcity inflate logistics costs compared to eastern corridors. Port Adelaide and Whyalla handle lower-volume but higher-value concentrate exports.
Australia Mining Logistics Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Australian mining logistics. The market structure concentrates around rail infrastructure owners and port terminal operators with corridor access rights, while road freight and warehousing segments fragment across regional specialists. Three archetypes dominate: heavy-haul rail incumbents with track access, integrated miners retaining in-house logistics control, and third-party specialists winning outsourced contracts. Competitive moves center on automation capital deployment and long-term take-or-pay contract renewal.
Within the rail infrastructure tier, Aurizon and Pacific National occupy positions as heavy-haul corridor gatekeepers. Qube represents the third-party logistics specialist archetype, anchoring port and intermodal service provision across multiple jurisdictions. Among integrated miners, BHP and Rio Tinto exemplify the in-house control model, retaining direct rail and port infrastructure ownership to protect volume commitments.
| Leading Market Players |
|---|
| Aurizon |
| Qube |
| BHP |
| Pacific National |
| Linfox |
| Rio Tinto |
| Toll Holdings |
| NRW Holdings |
| Fortescue Metals Group |
| Others |
Value Chain & Pricing Dynamics
TGA certification requirements and National Heavy Vehicle Regulator safety case frameworks gate both supplier qualification and price differentiation across Australian mining logistics corridors. Rail access rights and autonomous vehicle permits concentrate pricing power with infrastructure incumbents while forcing mid-tier miners into premium rate tiers for non-standard haulage.
Pricing Analysis
Pilbara-to-port haulage commands 15-25% premiums over Bowen Basin coal corridors due to longer distances and dedicated heavy-haul infrastructure scarcity. Contract-based long-term offtake dominates, with volume scale and automation certification tier driving price differentiation. Pricing pressure stems from diesel fuel volatility and Asian offtaker scope 3 emissions scrutiny. Mid-tier miners show highest price sensitivity, while BHP and Rio Tinto leverage bloc purchasing for rail access preference.
Supply Chain Analysis
Strategic stockpiling of critical spare parts dominates over just-in-time models given remote Pilbara and Bowen Basin locations and fly-in-fly-out cost structures. Supply concentrates in Australia for rail infrastructure and heavy equipment, with diesel engines and automation control systems sourced from USA, Germany, and Japan. Single-corridor rail concentration with Aurizon and Pacific National creates chokepoint vulnerability. Distribution runs through Perth-based remote operations centers consolidating multi-site dispatch control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Third-party logistics and fourth-party supply chain orchestration represent the fastest-expanding service-attach layers, outpacing pure transportation hardware as miners outsource non-core functions to specialist operators.
For Market Incumbents: Consolidate rail corridor access rights through long-term ARTC agreements to defend against emerging intermodal containerization threats. Expand backward integration into port terminal automation to capture stacking and vessel loading margins currently leaking to equipment vendors.
For New Entrants and Emerging Players: Remote maintenance hub scarcity in South Australia's Olympic Dam corridor offers white-space entry with lower incumbent density than Pilbara. Target containerized bulk pilots bypassing traditional terminal queues as the most penetrable wedge, leveraging Melbourne intermodal infrastructure for go-to-market scale.
For Investors and Strategic Acquirers: National Greenhouse and Energy Reporting scheme carbon disclosure mandates reshape the acquisition landscape toward electrification-ready rail assets and battery-electric haulage pilots. Long-term viability favors operators with ARENA-funded electrification pipelines and renewable rail corridor access. Watch ARENA funding allocation shifts as the inflection signal for capital rotation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Rail Electrification Pilot | ARENA subsidies displace diesel locomotive capex cycles across Pilbara heavy-haul lines. |
| Autonomous Haulage Deployment | TGA safety case streamlining accelerates driverless truck and rail fleet timelines. |
| Intermodal Containerization | Qube pilots open door-to-door contracts bypassing traditional bulk terminal queues. |
| Remote Operations Consolidation | Perth-based hubs reduce fly-in-fly-out headcount across multi-site miner networks. |
| Port Terminal Automation | Automated stacking cranes at Port Hedland match Chinese steelmaker demand cycles. |
Study Parameters
Operator-level perspectives from rail dispatch controllers, remote operations center managers, heavy diesel fitters, port terminal automation engineers, and ARTC access negotiators anchored the qualitative base. Primary interviews combined with secondary validation from Australian Bureau of Agricultural and Resource Economics trade data, ARTC corridor investment disclosures, TGA autonomous vehicle trial registers, and National Heavy Vehicle Regulator fatigue exemption frameworks. Bottom-up segment sizing and top-down macro constraint triangulation cross-checked volume estimates.
Sensitivity analysis tested forecast robustness across diesel price volatility bands, autonomous deployment acceleration scenarios, and electrification subsidy variation. Segmentation modeled service type, logistics model, material type, and end user dimensions alongside corridor-specific infrastructure capacity constraints. CAGRs derived from historical volume elasticities and projected automation penetration curves, with rail access charge trajectories and Asian offtaker contract renewal cycles as key inputs across the projection horizon.
Underlying assumptions cover autonomous safety case approval timelines, ARENA funding continuity, and Asian metallurgical coal demand stability, with deviation risk concentrated in regulatory divergence between Western Australia and Queensland signaling standards. Revision becomes warranted when autonomous vehicle liability frameworks cross litigation threshold uncertainty or carbon border adjustment mechanisms alter scope 3 emissions accounting.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Chile Air Freight Transport Market
Logistics and Shipping
Ocean Freight Software Market
Logistics and Shipping
UK Freight Forwarding Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
Asia Pacific Finished Vehicle Logistics Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Asia-Pacific Courier Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Spare Part Logistics Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
Brazil Freight and Logistics Market
Logistics and Shipping
New York Freight and Logistics Market