
 Turret Truck Market | 2026-2036
Turret Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Turret Truck Market Analytics
Premium-specification turret trucks with lithium-ion powertrains is bifurcating the competitive landscape into energy-efficient and conventional equipment tiers. Jungheinrich AG leverages its German manufacturing base to dominate European electric turret truck supply. KION Group AG sustains technology leadership through integrated automation software. Toyota Industries Corporation anchors Asian demand with scaled production of precision-guided narrow-aisle systems.
A turret truck is a specialized forklift variant featuring a rotating mast that turns 180 degrees within the chassis width, enabling pallet retrieval and depositing in aisles as narrow as 1.5 meters without truck repositioning. The machine employs wire or rail guidance systems with lift heights exceeding 12 meters to maximize cubic storage density in high-rack warehouses. Electric turret trucks now command the largest installed base as warehouse operators phase out internal combustion equipment under facility emissions rules. Telemetry-enabled units represent the fastest-expanding technology segment as fleet managers demand real-time battery monitoring and predictive maintenance analytics. Manual turret trucks occupy a shrinking but persistent niche in smaller facilities with limited capital budgets.
FCC radio equipment authorization governs wireless guidance frequencies in United States warehouse installations, while OSHA powered industrial truck standards mandate operator training and equipment inspection protocols. The EU Green Deal's industrial decarbonization timeline is forcing European logistics operators to accelerate electric fleet conversion ahead of binding emission thresholds. Stakeholders must monitor battery supply chain localization requirements and emerging autonomous navigation certifications that will determine equipment market access across major economies.
Market Dynamics
The EU Green Deal's industrial decarbonization timeline is compressing fleet replacement cycles as lithium-ion powertrains displace lead-acid systems across European cold chain warehousing, forcing operators to accelerate capital deployment ahead of binding emission thresholds.
Growth Catalysts
- EU Green Deal mandates:Binding emission thresholds under industrial decarbonization rules are compelling logistics operators to electrify narrow-aisle fleets before compliance deadlines.
- Cold chain warehousing expansion:Temperature-controlled logistics corridors between Düsseldorf and Hamburg are driving concentrated fleet orders for high-density storage equipment.
- Telemetry integration:Real-time battery monitoring and predictive maintenance analytics are reducing downtime costs for fleet managers operating 24-hour distribution cycles.
Market Restraints
- Lithium supply concentration:Cathode material processing capacity clusters in China creates vulnerability for European OEMs building localized battery supply chains.
- Wire guidance infrastructure costs:Retrofitting existing warehouses with embedded guidance rails demands substantial capital expenditure that smaller operators cannot absorb.
- Lead-acid residual value collapse:Secondary market prices for displaced battery systems are collapsing as recycling capacity fails to match retirement volumes.
Strategic Opportunities
- Autonomous navigation certification:Emerging safety standards for unmanned narrow-aisle operation will unlock new deployment models in high-labor-cost markets.
- Battery supply chain localization:European cell manufacturing incentives are creating opportunity for OEMs to establish captive lithium-ion assembly within the logistics corridor.
- Telemetry-as-a-service unbundling:Fleet data monetization through predictive analytics subscriptions represents a recurring revenue stream separate from equipment sales.
Industry Challenges
- Operator certification bottlenecks:OSHA powered industrial truck standards and equivalent EU directives require specialized training for narrow-aisle equipment that outpaces available instructor capacity.
- Legacy warehouse dimensional constraints:Pre-2000 facilities with 10-meter clear heights cannot accommodate modern turret truck lift specifications without structural reinforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turret Truck Market |
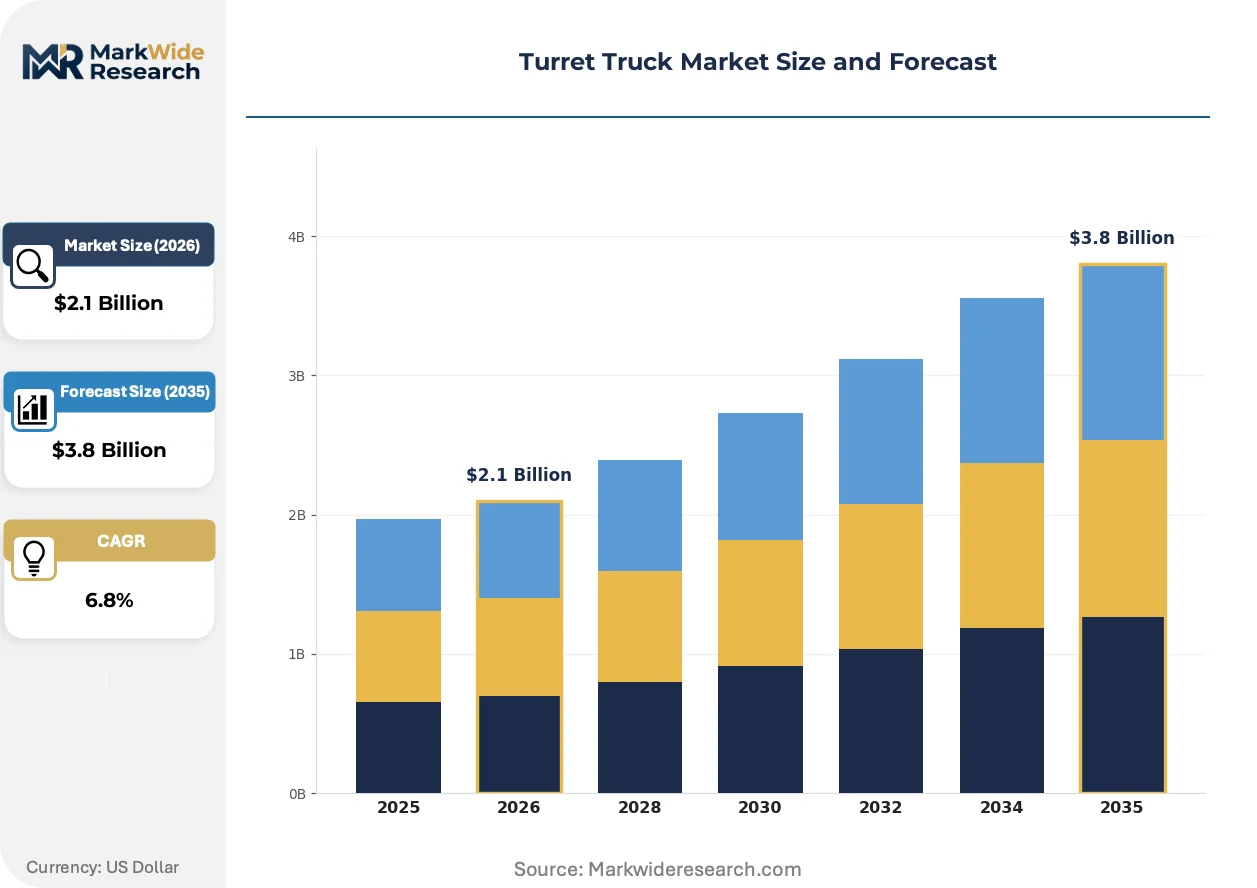
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Turret Trucks, Manual Turret Trucks, Hybrid Turret Trucks, Reach Trucks End User: Warehousing, Retail, Manufacturing, Logistics Capacity: 1-2 Tons, 2-3 Tons, 3-4 Tons, Above 4 Tons Technology: Automated Guided Vehicles, Radio Frequency Identification, Telemetry, IoT-Enabled |
| Companies Covered | Crown Equipment Corporation, Hyster-Yale Materials Handling, Jungheinrich AG, KION Group AG, Toyota Industries Corporation, Combilift Material Handling Solutions, Doosan Corporation, Godrej and Boyce Manufacturing Company Limited, Hangcha Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turret Truck Market Evolving Landscape
Wireless guidance and battery management systems are converging to reshape equipment specifications, with regulatory pressure and buyer behavior shifting procurement criteria toward total cost of ownership metrics rather than upfront capital expenditure.
Sensor arrays for real-time aisle positioning and obstacle detection are miniaturizing from discrete hardware modules to integrated chipsets. Cold chain operators in Germany's logistics corridor are specifying these systems on 80% of new orders. Component consolidation is miniaturizing guidance electronics while expanding telemetry bandwidth for predictive maintenance algorithms.
REACH chemical registration requirements and RoHS substance restrictions are tightening material compliance for battery enclosures and electronic assemblies. European OEMs are redesigning supply chains to eliminate restricted substances from wire guidance insulation and control housings. German manufacturers face the most immediate compliance pressure due to domestic enforcement intensity.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-sized third-party logistics providers. Leasing structures that bundle maintenance, battery replacement, and software updates are capturing preference in the Düsseldorf-Hamburg corridor. This shift concentrates vendor selection authority with procurement functions rather than warehouse operations teams.
Turret Truck Market Segmentation
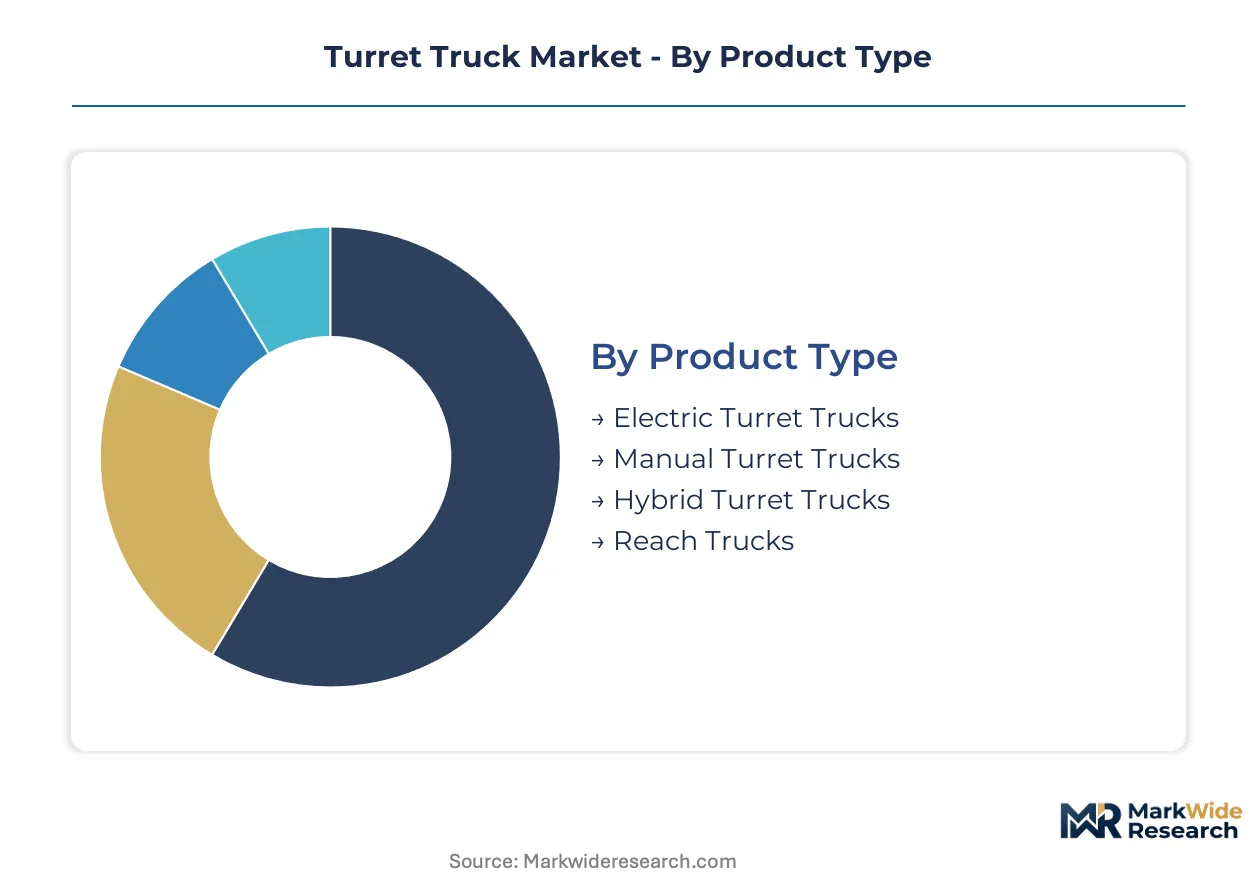
Turret truck segmentation reveals how procurement criteria are shifting from lift capacity toward energy efficiency and data integration. Buyers now evaluate total cost of ownership across battery chemistry, guidance precision, and telemetry capability rather than upfront equipment price alone.
Product Type:
Margin pools concentrate in electric powertrains as EU Green Deal mandates eliminate internal combustion alternatives from European warehouse specifications.
- Electric Turret Trucks:Lithium-ion battery systems now dominate new orders, with lift heights exceeding 12 meters and wire guidance compatibility standard. Cold chain operators between Düsseldorf and Hamburg specify these for 24-hour distribution cycles where emission compliance is non-negotiable.
- Manual Turret Trucks:Hand-operated units without powered mast rotation persist in smaller facilities with capital constraints below 50,000 euros annual equipment budget. Secondary market liquidity is collapsing as lead-acid residual values plummet, forcing owner-operators toward extended depreciation schedules.
- Hybrid Turret Trucks:Dual-power configurations blending battery and small combustion engines for outdoor yard transitions.
- Reach Trucks:Fixed-mast alternatives with forward-reaching forks rather than rotating turret mechanisms.
The dominant share belongs to Electric Turret Trucks, while Telemetry-enabled variants within this category are gaining share fastest.
End User:
Application intensity varies sharply across customer types, with third-party logistics providers driving specification standardization through fleet-scale procurement.
- Warehousing:High-rack cold storage facilities demand precision guidance systems with aisle widths below 1.6 meters. German logistics corridor operators are retrofitting legacy buildings with embedded rail guidance to accommodate 14-meter lift specifications.
- Logistics:Express distribution hubs prioritize rapid battery swap protocols and predictive maintenance dashboards. Telemetry integration is climbing fastest here as 24-hour sortation cycles leave zero tolerance for unplanned downtime.
- Retail:Back-of-store replenishment operations with lower rack heights and intermittent usage patterns.
- Manufacturing:Just-in-time component delivery within assembly plants requiring outdoor-to-indoor transition capability.
Warehousing commands the largest installed base, though Logistics is expanding most quickly as e-commerce fulfillment networks densify.
Capacity:
Load specification directly correlates with aisle width engineering and battery sizing economics.
- 1-2 Tons:Narrowest aisle compatibility with 1.5-meter clearances and compact chassis dimensions. Retail backroom operations in urban logistics clusters specify this tier for space-constrained facilities.
- 2-3 Tons:Balanced payload for standard pallet dimensions across European cold chain corridors. This midpoint captures volume concentration as warehouse operators standardize fleet specifications.
- 3-4 Tons:Heavy-duty applications in beverage and dense commodity storage.
- Above 4 Tons:Specialized industrial handling with reinforced mast structures.
The 2-3 Tons segment holds the dominant position, while 1-2 Tons is climbing fastest on urban warehouse densification trends.
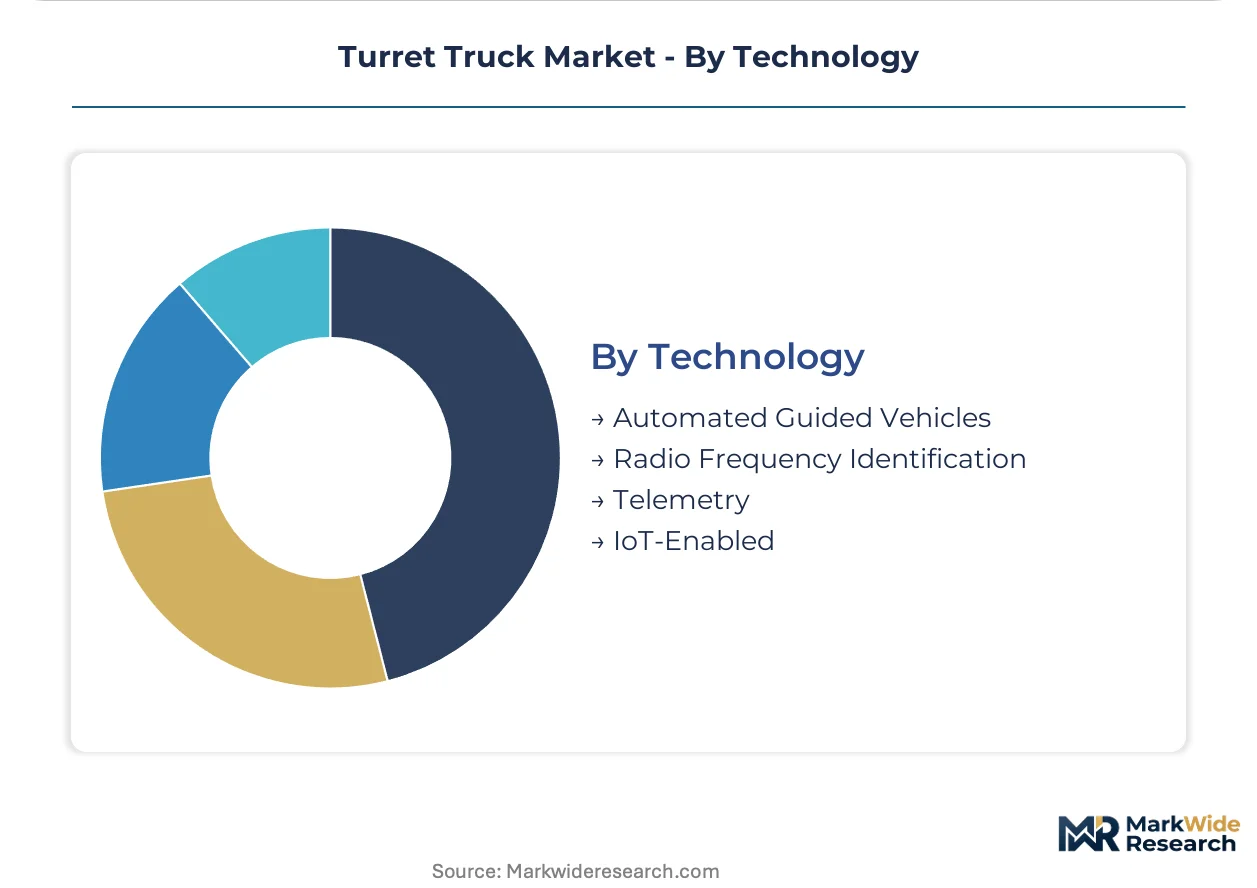
Technology:
Intelligence layer differentiation is becoming the primary vendor selection criterion as hardware commoditizes.
- Telemetry:Real-time battery state-of-charge monitoring and predictive maintenance algorithms are standard on 80% of new orders from German cold chain operators. FCC radio authorization governs wireless frequency allocation in US installations.
- Automated Guided Vehicles:Unmanned narrow-aisle operation with safety-certified navigation systems. Emerging EU standards for autonomous industrial vehicles are unlocking deployment in high-labor-cost markets.
- IoT-Enabled:Cloud-connected fleet management with over-the-air software updates.
- Radio Frequency Identification:Pallet-level tracking integration with warehouse management systems.
Telemetry-enabled units represent the largest current deployment, while Automated Guided Vehicles show the steepest expansion trajectory as labor costs rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German turret truck exports flow primarily into warehouse networks across the Benelux corridor and northern France, with Düsseldorf-Hamburg logistics operators serving as the primary demand anchor for narrow-aisle equipment specifications.
Germany
Cold chain warehousing between Düsseldorf and Hamburg drives concentrated fleet orders for lithium-ion powered units. EU Green Deal industrial decarbonization mandates compress replacement cycles ahead of binding emission thresholds. The North Rhine-Westphalia logistics corridor hosts retrofit programs embedding wire guidance rails in legacy facilities.
United States
E-commerce fulfillment networks densify last-mile distribution centers in the Midwest and Southeast. FCC radio equipment authorization governs wireless guidance frequency allocation for warehouse installations. Chicago and Atlanta metropolitan areas concentrate demand for telemetry-enabled fleet management systems.
China
Domestic battery cell manufacturing scales to serve intra-Asia warehouse automation demand. MIIT industrial equipment standards shape narrow-aisle vehicle certification requirements. Yangtze River Delta logistics hubs in Shanghai and Suzhou specify high-lift electric turret trucks for bonded warehouse operations.
France
Third-party logistics providers standardize fleet specifications across the Île-de-France distribution network. REACH chemical registration and RoHS substance restrictions tighten material compliance for battery enclosures and electronic assemblies. The Paris metropolitan logistics ring concentrates procurement authority for equipment-as-a-service contracts.
Japan
Precision manufacturing supply chains demand narrow-aisle storage density in just-in-time component delivery. METI energy efficiency standards accelerate displacement of lead-acid battery systems. Osaka-Kobe industrial corridor operators specify automated guided vehicle variants for unmanned high-rack operations.
Turret Truck Market Competitive Landscape
Listed leaders compete with private specialists across capital structure and geographic footprint, creating a tiered market where scale-driven OEMs battle regional fabricators for fleet procurement contracts. The vendor base clusters around three strategic archetypes: integrated automation software providers, German-centered electric equipment specialists, and Asian-scale precision manufacturers. Dominant competitive moves include captive lithium-ion battery assembly investments and telemetry platform unbundling into subscription revenue streams.
Within the European specialist tier, Jungheinrich AG and KION Group AG occupy positions defined by proximity to the Düsseldorf-Hamburg logistics corridor and integrated automation capabilities. Toyota Industries Corporation anchors the Asian-scale archetype with production concentration serving narrow-aisle demand across Pacific Rim warehouse networks. Crown Equipment Corporation represents the North American fabricator position with domestic manufacturing serving FCC-governed wireless guidance specifications.
| Leading Market Players |
|---|
| Crown Equipment Corporation |
| Hyster-Yale Materials Handling |
| Jungheinrich AG |
| KION Group AG |
| Toyota Industries Corporation |
| Combilift Material Handling Solutions |
| Doosan Corporation |
| Godrej and Boyce Manufacturing Company Limited |
| Hangcha Group |
| Others |
Value Network & Pricing Analysis
Long-term equipment-as-a-service contracts lock in lithium-ion battery supply access and price visibility for German cold chain operators navigating EU Green Deal compliance deadlines. These bundled structures tie monthly payments to telemetry uptime guarantees, shifting procurement authority from warehouse operations to corporate finance functions.
Pricing Analysis
Current-generation lithium-ion turret trucks command a 35-40% premium over prior-generation lead-acid configurations, with next-generation autonomous variants entering pilot pricing. Three-tier pricing structure across premium telemetry-enabled, standard electric, and economy manual equipment segments stratifies the market. Price differentiation rests on battery chemistry certification grade and after-sales service bundling. Cost compression in the lead-acid residual market is intensifying because recycling capacity fails to match retirement volumes. Third-party logistics providers show highest price sensitivity due to thin margins, while cold chain specialists prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Inventory lead times for lithium-ion battery packs have extended from 12 to 26 weeks as cathode material processing capacity concentrates in China. Manufacturing draws from German chassis assembly, Chinese cell production, and South Korean battery management system integration. Raw material dependencies span lithium carbonate, nickel sulfate, and copper busbar components. Single-source vulnerability in cathode precursor supply creates exposure to export licensing disruptions. Distribution runs through OEM-direct fleet procurement and third-party logistics equipment-as-a-service platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The turret truck market sits in early-cycle recovery as EU industrial decarbonization mandates force accelerated fleet replacement ahead of binding emission thresholds.
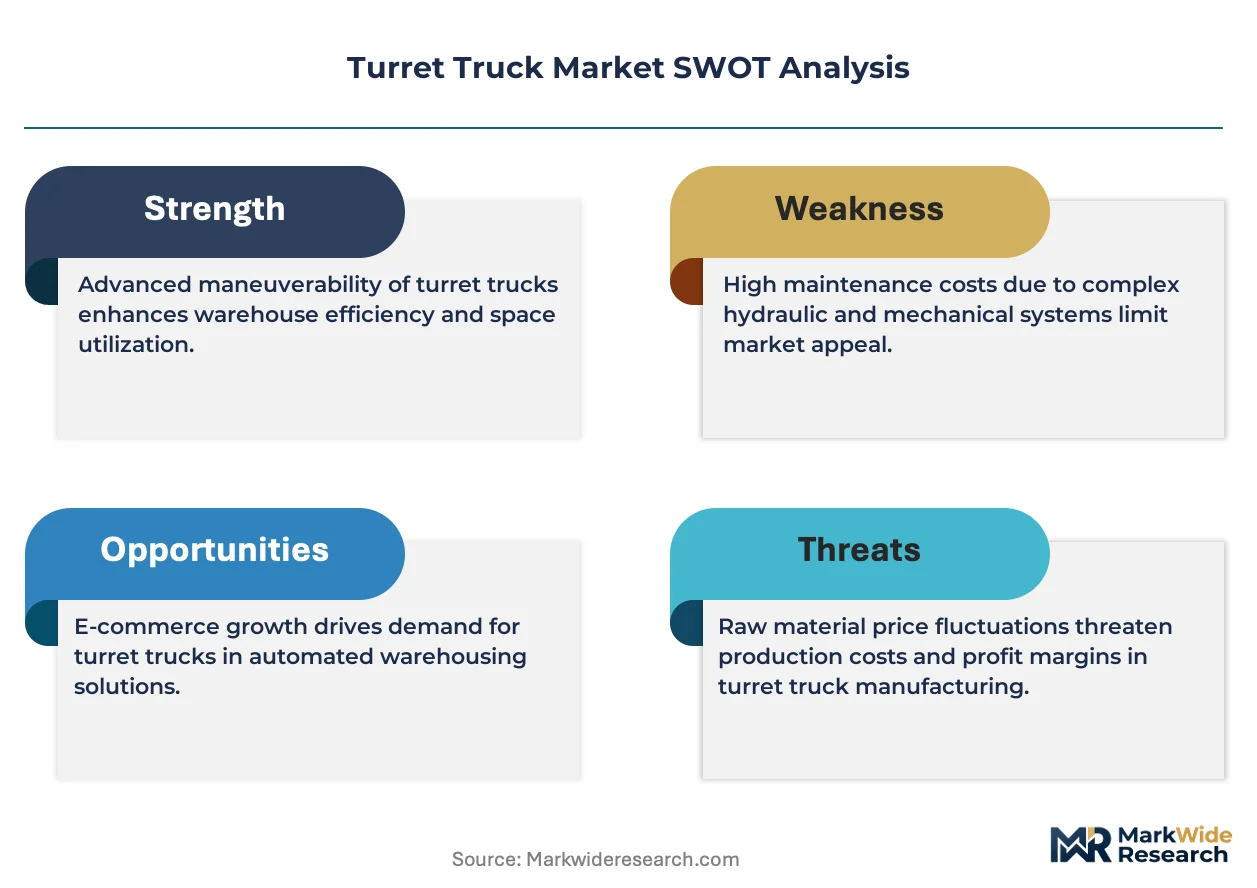
For Market Incumbents: Secure captive lithium-ion assembly capacity within the Düsseldorf-Hamburg logistics corridor before battery supply chain localization incentives expire. Deepen backward integration into battery management system firmware to differentiate telemetry platforms from hardware-commoditized competitors. Defend against emerging autonomous navigation specialists by accelerating safety certification investments ahead of EU standards finalization. For New Entrants and Emerging Players: Differentiate on telemetry-as-a-service unbundling, targeting mid-sized third-party logistics providers with subscription-based predictive maintenance analytics. White-space opportunity concentrates in 1-2 ton compact chassis segments for urban last-mile densification. Geographic entry should prioritize France's Île-de-France distribution network where equipment-as-a-service contracting is displacing capital purchase models. Go-to-market angle: outcome-based uptime guarantees rather than equipment specifications. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive battery assembly and established telemetry platforms serving the German cold chain corridor. Long-term viability favors OEMs controlling both hardware manufacturing and software subscription revenue streams. Acquisition target archetype: European electric equipment specialists with localized supply chains and automation software integration. Signal to watch: EU autonomous navigation certification timelines as inflection indicator for unmanned narrow-aisle deployment models.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Lithium-Ion Assembly Investment | Localizes battery supply chains within the Düsseldorf-Hamburg logistics corridor under EU Green Deal incentives. |
| Telemetry Platform Unbundling | Converts fleet data into recurring subscription revenue separate from equipment sales to third-party logistics. |
| Autonomous Navigation Certification | Unlocks unmanned narrow-aisle deployment in high-labor-cost markets under emerging EU safety standards. |
| Wire Guidance Infrastructure Retrofit | Enables 14-meter lift specifications in legacy cold chain facilities across Germany's North Rhine-Westphalia region. |
| Battery Supply Chain Localization | Reduces cathode material processing dependency on Chinese capacity clusters for European OEMs. |
Research Methodology
The analysis maps electric powertrain configurations, telemetry-enabled variants, manual equipment tiers, and autonomous navigation systems, each validated through fleet procurement managers, warehouse operations directors, OEM sales engineers, and aftermarket service heads. Primary interviews with cold chain operators and third-party logistics providers combined with secondary validation from EU Green Deal regulatory filings, MIIT industrial equipment standards, FCC radio authorization databases, and customs trade data. Bottom-up unit demand modeling and top-down market sizing triangulate volume estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by powertrain technology, end-use application intensity, load capacity tier, and intelligence layer capability. CAGRs derive from replacement cycle compression under emission mandates and cold chain warehousing expansion patterns. Forecast inputs include battery chemistry adoption curves and guidance system retrofit penetration rates.
Material uncertainties — battery supply chain localization delays, autonomous navigation certification timeline shifts, lead-acid residual value collapse acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about EU industrial decarbonization enforcement intensity and lithium-ion cost reduction trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Heavy Duty Truck Wash Market
Heavy-Duty Trucks
Poly Trucks Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Global Boom Truck Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Saudi Arabia Refrigerated Truck Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market