
 Heavy-Duty Truck Dashboard Switch Panel Systems Market | 2026-2036
Heavy-Duty Truck Dashboard Switch Panel Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Duty Truck Dashboard Switch Panel Systems Market Insights
The migration from mechanical to fully electronic architectures is narrowing the supplier base capable of meeting automotive-grade durability requirements. Continental leverages its integrated electronics portfolio to control high-volume supply agreements with European OEMs. Robert Bosch sustains technology leadership through in-house semiconductor capabilities for capacitive touch interfaces. Denso anchors its position in the Japanese market with application-specific designs for construction and mining vehicle segments.
Heavy-duty truck dashboard switch panel systems comprise electromechanical or solid-state control interfaces mounted within the operator cabin, typically rated for IP67 ingress protection and operating temperatures spanning minus forty to eighty-five degrees Celsius, serving to consolidate HVAC, lighting, power take-off, and diagnostic functions into a single ergonomic module. Electronic switch panels now dominate new platform designs, displacing mechanical alternatives in long-haul transportation applications where telematics integration has become standard. Hybrid switch panels retain relevance in construction vehicles and agricultural haulers where operators demand tactile feedback for critical safety functions alongside digital configurability.
The EPA and NHTSA jointly shape product requirements through emissions and safety mandates that mandate driver-alert systems and data-logging capabilities, directly expanding addressable content per vehicle. ECE R10 electromagnetic compatibility standards enforced by European type-approval authorities further filter supplier eligibility, favoring firms with captive EMC testing infrastructure. Fleet operators and OEM manufacturers must evaluate supplier roadmaps for software-defined configurability, as programmable switch modules are displacing fixed-function designs across all application tiers.
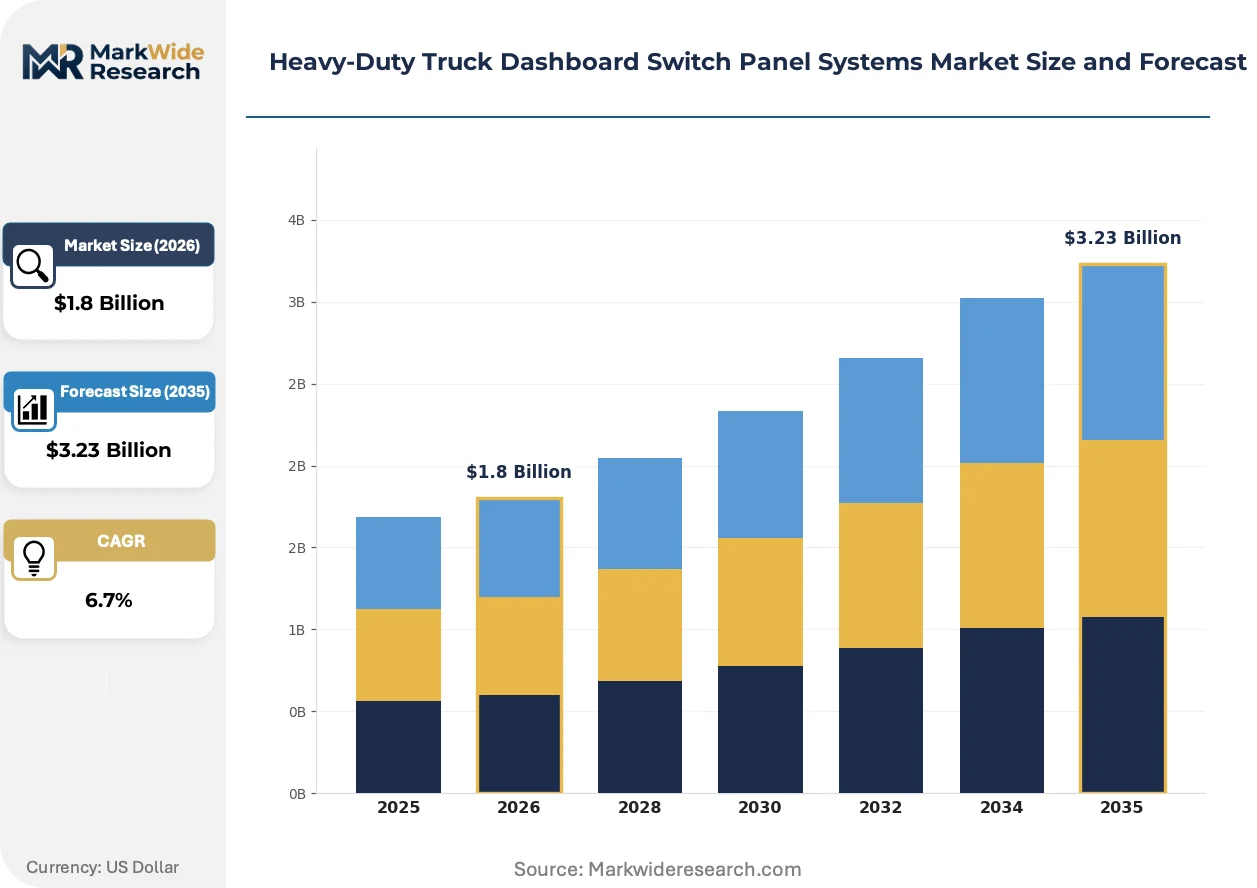
Market Dynamics
The migration from mechanical to fully electronic switch architectures is compressing the supplier base capable of meeting automotive-grade durability requirements. Long-haul fleet operators now mandate programmable modules that integrate telematics, HVAC, and diagnostic functions into single ergonomic units, forcing tier-two suppliers to invest in captive semiconductor capabilities or exit the market.
Growth Catalysts
- EPA Phase 3 Standards:The EPA's greenhouse gas mandates for heavy-duty vehicles are accelerating adoption of electronic switch panels that enable real-time fuel monitoring and driver-alert systems for compliance.
- Telematics Integration:Fleet management platforms now require CAN-bus compatible switch modules, pulling demand toward solid-state designs with embedded software configurability.
- Construction Vehicle Electrification:Mining and agricultural equipment manufacturers are specifying hybrid switch panels that combine tactile feedback with digital diagnostics for safety-critical functions.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea dominate automotive-grade microcontroller production, exposing switch panel assemblers to allocation volatility during capacity crunches.
- EMC Certification Burden:ECE R10 electromagnetic compatibility testing requires captive anechoic chambers and specialized engineering staff, filtering out sub-scale suppliers.
- Mechanical Switch Substitutes:Retrofit markets in emerging economies continue sourcing legacy electromechanical switches from Southeast Asian manufacturers at 40-60% lower unit cost.
Strategic Opportunities
- Software-Defined Configurability:Programmable switch modules allow fleet operators to reassign button functions over-the-air, reducing SKU complexity for OEMs and enabling subscription revenue streams.
- Aftermarket Digital Retrofit Kits:Independent service channels in Brazil and India are sourcing CAN-bus bridge modules that upgrade legacy mechanical panels without full dashboard replacement.
- Modular Platform Strategies:Tier-one suppliers are developing scalable switch architectures spanning light commercial vehicles through Class 8 trucks, amortizing R&D across volume tiers.
Industry Challenges
- Embedded Software Talent Scarcity:Functional safety engineering for ISO 26262 compliance requires specialized firmware developers, with competition intensifying from autonomous vehicle programs.
- Legacy System Integration Friction:Mixed-voltage architectures in refreshed truck platforms demand voltage level translators and protocol gateways, adding BOM cost and failure modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Duty Truck Dashboard Switch Panel Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Switch Panels, Electronic Switch Panels, Hybrid Switch Panels, Programmable Switch Modules Technology: Membrane Switch, Tactile Switch, Capacitive Touch, Rotary Switch, Toggle Switch Application: Long-Haul Transportation, Construction Vehicles, Mining Trucks, Agricultural Haulers, Emergency Response End User: Fleet Operators, Vehicle Assemblers, OEM Manufacturers, Aftermarket Providers |
| Companies Covered | Continental, Robert Bosch, Denso, Valeo, Preh, Marquardt, ZF Friedrichshafen, HELLA, Actia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Duty Truck Dashboard Switch Panel Systems Market Trends and Innovations
Capacitive touch interfaces and haptic feedback systems are redefining operator interaction paradigms in heavy-duty cabins. Three converging developments are compressing product lifecycles and reshaping supplier competitive position.
Solid-state capacitive switch arrays with force-sensing resistors are collapsing the traditional separation between control interfaces and display surfaces. Long-haul fleet operators in North America and Europe are specifying these modules for new platform launches, enabling manufacturers to eliminate mechanical button inventories and reduce wiring harness complexity by consolidating signals through single CAN-bus nodes.
The EPA's Phase 3 greenhouse gas standards and NHTSA's advanced driver-assistance mandates are mandating data-logging capabilities that mechanical switches cannot support. Heavy-duty OEMs must now source electronic panels with embedded non-volatile memory for event recording, with compliance timelines most compressed for Class 8 tractor-trailer platforms serving interstate commerce.
Fleet procurement departments are consolidating supplier relationships around full-stack cabin electronics providers rather than discrete component vendors. Large transportation operators in the United States are negotiating multi-year framework agreements that bundle switch panels with telematics hardware and predictive maintenance software, squeezing standalone switch specialists from approved vendor lists.
Heavy-Duty Truck Dashboard Switch Panel Systems Market Segmentation
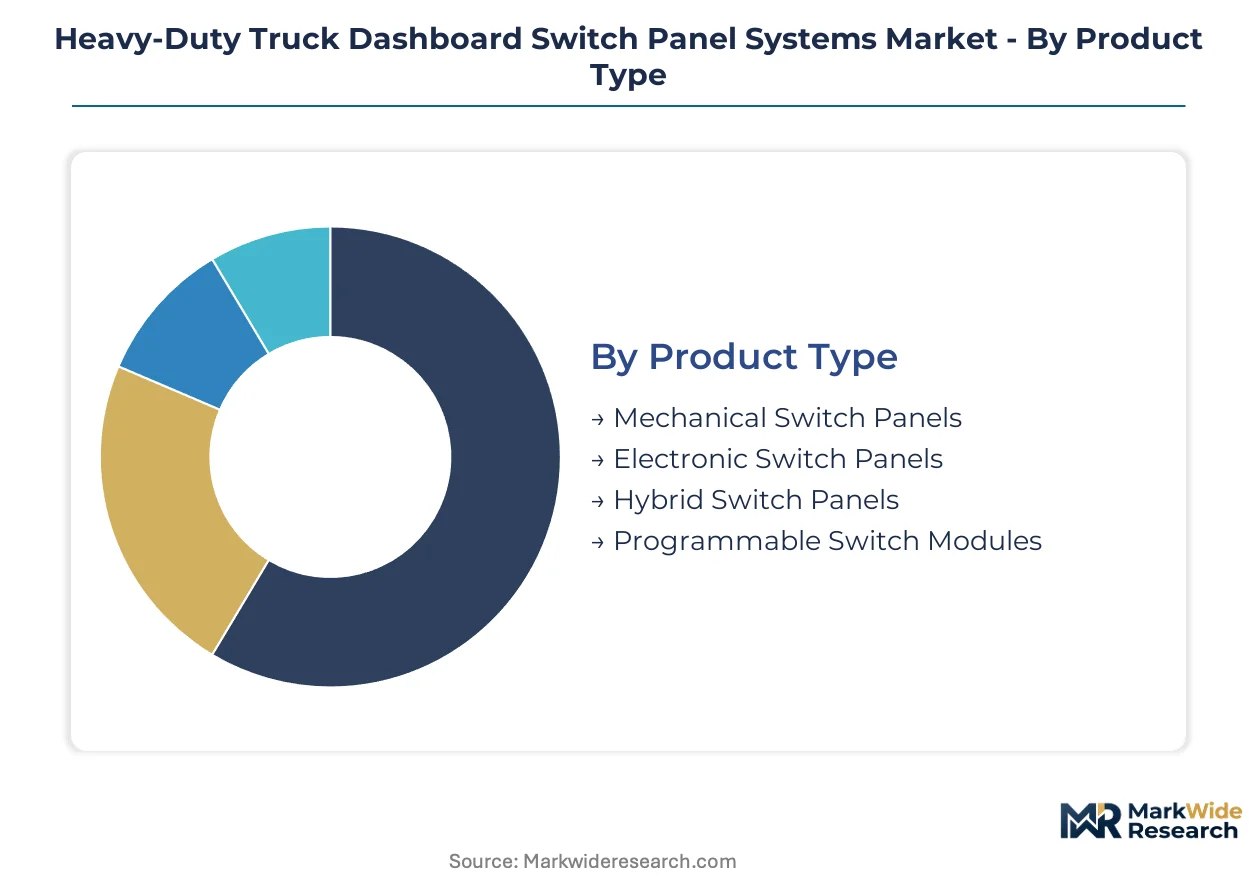
Heavy-duty truck dashboard switch panel systems fragment across four distinct dimensions that govern procurement patterns and supplier strategy. Product architecture determines replacement cycles and software upgrade paths. Application context dictates durability specifications and regulatory compliance requirements.
Product Type:
Replacement cycles vary dramatically across this category, with mechanical panels turning over every 8-12 years while programmable modules refresh every 3-5 years to capture software updates.
- Mechanical Switch Panels:Electromechanical assemblies with physical contacts rated for millions of actuation cycles. Demand concentrates in emerging economy retrofit markets where operators prioritize unit cost over telematics integration.
- Electronic Switch Panels:Solid-state architectures with embedded microcontrollers and CAN-bus connectivity. Long-haul fleets in the United States specify these for EPA Phase 3 compliance and real-time fuel monitoring capabilities.
- Hybrid Switch Panels:Combines tactile mechanical switches with digital diagnostic interfaces. Mining and construction vehicle manufacturers favor these for safety-critical functions requiring operator feedback.
- Programmable Switch Modules:Software-configurable interfaces allowing over-the-air function reassignment. Fleet operators adopt these to reduce SKU complexity across mixed vehicle platforms.
Mechanical switch panels anchor the volume base in aftermarket channels while programmable switch modules gain share at the steepest rate among new platform designs.
Technology:
Cost tiers separate mature electromechanical technologies from premium solid-state alternatives, with membrane and tactile switches occupying the economy tier and capacitive touch commanding premium positioning.
- Membrane Switch:Polyester or polycarbonate substrate with printed conductive traces, sealed to IP67 standards. Agricultural hauler manufacturers specify these for cost-sensitive cab configurations.
- Tactile Switch:Metal dome or polydome actuation mechanisms providing audible and physical feedback. Construction vehicle operators demand these for controls used with gloved hands.
- Capacitive Touch:Field-effect sensing arrays eliminating moving parts and enabling gesture recognition. European OEMs integrate these for cabin aesthetics and wiring harness reduction.
- Rotary Switch:Multi-position electromechanical selectors for HVAC and lighting functions. Emergency response vehicle upfitters specify these for intuitive operation under stress.
- Toggle Switch:Lever-actuated contacts for high-current power take-off circuits. Mining truck applications favor these for durability in vibration-intensive environments.
Membrane and tactile technologies dominate unit shipments while capacitive touch expands most quickly among premium long-haul specifications.
Application:
Volume concentration tracks with fleet scale and platform standardization, with interstate commerce operations driving procurement consolidation around single suppliers.
- Long-Haul Transportation:Class 8 tractor-trailers operating interstate routes with standardized cab designs. Fleet operators mandate telematics-compatible electronic panels for fuel efficiency compliance.
- Construction Vehicles:Excavators, loaders, and graders with exposed cabs and high vibration exposure. Hybrid switch panels with sealed tactile interfaces satisfy operator safety requirements.
- Mining Trucks:Ultra-class haulers operating in dust-intensive environments. Specifications demand IP6K9K ingress protection and extended temperature ranges.
- Agricultural Haulers:Grain trucks and livestock transporters with seasonal utilization patterns. Cost-sensitive procurement favors mechanical panels with minimal electronics.
- Emergency Response:Fire apparatus and ambulance cabs requiring intuitive controls under time pressure. Custom switch legends and backlighting configurations are standard.
Long-haul transportation anchors the revenue base while emergency response applications climb the fastest as municipal fleet electrification accelerates.
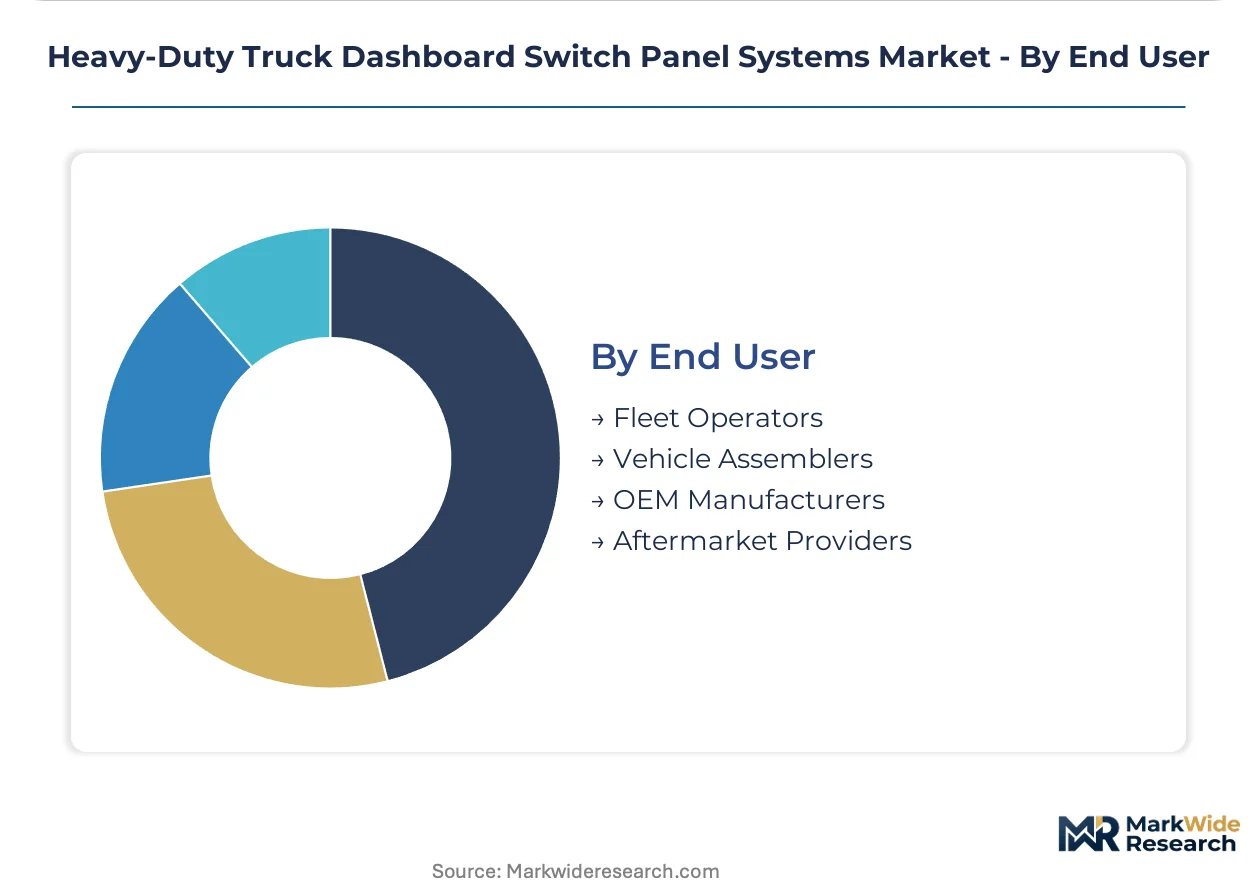
End User:
Customer type determines purchasing authority and technical specification involvement, with direct vehicle assemblers controlling design-in decisions and aftermarket channels serving replacement demand.
- Fleet Operators:Large transportation companies with dedicated procurement departments negotiating multi-year framework agreements. These buyers bundle switch panels with telematics and maintenance contracts.
- Vehicle Assemblers:Chassis manufacturers and body builders specifying panels during platform development. Design-in relationships lock suppliers into 5-7 year production cycles.
- OEM Manufacturers:Branded truck producers with captive electronics divisions or approved vendor lists. Technical roadmaps prioritize software-defined configurability.
- Aftermarket Providers:Independent distributors and service channels sourcing replacement panels for repair and refurbishment. Price sensitivity drives demand toward mechanical alternatives.
Vehicle assemblers anchor the specification authority while fleet operators gain influence fastest through consolidated procurement and direct supplier negotiations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in the United States drive the most concentrated procurement activity, with large transportation companies negotiating multi-year framework agreements that bundle switch panels with telematics systems and predictive maintenance software.
United States
Class 8 tractor-trailer fleets operating interstate routes mandate CAN-bus compatible electronic panels for EPA Phase 3 greenhouse gas compliance. The EPA and NHTSA jointly enforce driver-alert system requirements that expand addressable content per vehicle. Manufacturing clusters in Michigan and Ohio supply integrated cabin electronics to Detroit-based truck assemblers.
Germany
European OEMs specify capacitive touch interfaces to reduce wiring harness complexity and enable gesture recognition in premium long-haul configurations. ECE R10 electromagnetic compatibility standards enforced by German type-approval authorities filter supplier eligibility toward firms with captive EMC testing infrastructure. Stuttgart and Munich anchor development centers for automotive-grade solid-state switch architectures.
China
Domestic heavy-duty truck manufacturers source hybrid switch panels combining tactile feedback with digital diagnostics for construction and mining applications. MIIT regulations on vehicle networking security accelerate adoption of programmable modules with embedded authentication protocols. Manufacturing concentrates in the Yangtze River Delta around Shanghai and Jiangsu province suppliers.
Japan
Construction and mining equipment manufacturers favor application-specific designs with IP6K9K ingress protection for dust-intensive operating environments. METI industrial standards emphasize functional safety engineering for ISO 26262 compliance in safety-critical control interfaces. Nagoya-based suppliers anchor the domestic supply chain for ultra-class hauler specifications.
India
Cost-sensitive agricultural hauler procurement sustains demand for membrane switch technologies in seasonal utilization patterns. BIS certification requirements for automotive electronics create compliance barriers for imported assemblies. Manufacturing clusters in Maharashtra and Gujarat serve domestic truck assemblers and aftermarket refurbishment channels.
Heavy-Duty Truck Dashboard Switch Panel Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The supplier base compresses as programmable module requirements force tier-two firms to invest in captive semiconductor capabilities or exit. Three archetypes dominate: diversified electronics conglomerates with integrated portfolios, component specialists with automotive-grade durability expertise, and regional fabricators serving aftermarket price tiers. Competitive moves center on backward integration into microcontroller supply and multi-year framework agreements with fleet operators.
Within the diversified electronics tier, Continental and Robert Bosch exemplify integrated portfolio strategies, while Denso anchors Japanese market positioning through application-specific design capabilities. These firms represent the consolidation trajectory as mechanical switch volumes decline and software-defined configurability becomes mandatory for new platform procurement.
| Leading Market Players |
|---|
| Continental |
| Robert Bosch |
| Denso |
| Valeo |
| Preh |
| Marquardt |
| ZF Friedrichshafen |
| HELLA |
| Actia |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-to-Rotterdam maritime corridor anchors cost dynamics for heavy-duty truck dashboard switch panel systems, with freight rate volatility compressing margins for European OEMs while amplifying pricing power for Asian semiconductor suppliers. Concentration in automotive-grade microcontroller production across Taiwan and South Korea feeds downstream price differentiation between telematics-enabled electronic panels and legacy mechanical alternatives.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate procurement between Tier 1 assemblers and switch panel manufacturers. Price differentiation hinges on ISO 26262 functional safety certification tier and volume scale commitments from fleet operators. Pricing pressure stems from legacy mechanical switch imports from Southeast Asian fabricators undercutting solid-state alternatives. Aftermarket providers exhibit highest price sensitivity, while OEM manufacturers with captive electronics divisions absorb premium positioning for software-defined configurability.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for switch panel assemblers serving North American Class 8 platforms. Manufacturing concentrates in Germany, China, and Mexico, with raw material dependencies spanning automotive-grade polycarbonate substrates, copper alloy contacts, and silicon carbide microcontrollers. Single-source vulnerability in Taiwan-based foundry capacity threatens allocation stability. Distribution runs through Tier 1 cabin electronics integrators rather than standalone switch specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heavy-duty truck dashboard switch panel systems market constitutes a high-growth disruption driven by EPA Phase 3 greenhouse gas standards mandating telematics integration and real-time fuel monitoring capabilities that mechanical architectures cannot support.
For Market Incumbents: Entrench technology leadership through backward integration into microcontroller design capabilities, mirroring Robert Bosch's semiconductor captive strategy. Lock in multi-year framework agreements with large fleet operators bundling switch panels with predictive maintenance software to forestall standalone specialist competition. Prioritize EMC certification investment to filter sub-scale rivals from approved vendor lists.
For New Entrants and Emerging Players: Build out aftermarket digital retrofit kit capabilities for Brazil and India, where cost-sensitive agricultural hauler procurement sustains demand for CAN-bus bridge modules upgrading legacy mechanical panels. Target independent service channels with localized BIS certification compliance. Pursue white-label manufacturing partnerships with Yangtze River Delta electronics clusters to bypass captive infrastructure requirements.
For Investors and Strategic Acquirers: Application-specific design houses with ISO 26262 functional safety engineering capabilities and established mining equipment relationships represent the most defensible acquisition profile. Long-term viability hinges on software-defined configurability roadmaps displacing fixed-function designs across all application tiers. Watch for MIIT vehicle networking security mandates accelerating programmable module authentication protocol requirements as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Backward Integration | Captive microcontroller design insulates Tier 1 suppliers from Taiwan foundry allocation volatility. |
| Software-Defined Configurability Investment | Over-the-air function reassignment enables subscription revenue streams from fleet operators. |
| EMC Testing Infrastructure Expansion | In-house anechoic chamber capacity satisfies ECE R10 type-approval requirements for European OEM access. |
| Aftermarket Digital Retrofit Kit Development | CAN-bus bridge modules unlock emerging economy refurbishment channels without full dashboard replacement. |
| Multi-Year Fleet Framework Agreements | Bundled telematics and maintenance contracts consolidate procurement authority around full-stack cabin electronics providers. |
Research Methodology
Desk research of automotive production databases, EPA regulatory filings, and IHS Markit vehicle registration data preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distribution channel heads, and fleet maintenance directors. Primary fieldwork combined with secondary validation from SEC 10-K disclosures and customs trade records. Bottom-up unit shipment estimates triangulated against top-down OEM production forecasts across vehicle class and propulsion architecture segmentation.
Assumptions held fixed include EPA Phase 3 compliance timelines and ECE R10 electromagnetic compatibility enforcement stringency, while semiconductor supply allocation volatility and freight rate trajectories were stress-tested across scenarios. The analytical framework modeled product type, technology tier, application context, and end-user category dimensions across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns for electronic versus mechanical switch architectures, with fleet digitization investment cycles and regulatory compliance deadlines as primary demand drivers.
Stress conditions across foundry capacity utilization, maritime freight rates, and raw material input costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology substitution elasticities and procurement consolidation trajectories. Material shifts in EPA enforcement timelines or NHTSA advanced driver-assistance mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
United States Tank Trucking Market
Heavy-Duty Trucks
Digger Derrick Truck Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Malaysia Fire Truck Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
Platooning Trucks Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
Poly Trucks Market
Heavy-Duty Trucks
Fire Trucks Market
Heavy-Duty Trucks
Mexico Refrigerated Truck Market