
 Heavy Duty Truck Wash Market | 2026-2036
Heavy Duty Truck Wash Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Truck Wash Market Insights
Water reclamation technology is rewriting how heavy duty truck wash facilities manage throughput and compliance. InterClean Equipment leverages automated high-pressure architectures to sustain throughput rates across large fleet installations. FLEETWASH anchors a national service network that competes on route density and scheduled maintenance integration. Simple Green differentiates through biodegradable chemical formulations that navigate EPA discharge limits.
Heavy duty truck wash systems combine high-pressure water jets, chemical surfactants, and automated brush or touchless mechanisms to remove road film, grease, and corrosive de-icing agents from commercial vehicle exteriors, undercarriages, and engine compartments. Exterior wash dominates service type revenue due to frequency mandates and salt-belt corrosion prevention, while steam cleaning technology leads growth among operators targeting water-use restrictions. Fleet operators represent the deepest end user segment, with large fleets capturing disproportionate margin pools through volume contracts and standardized wash protocols.
EPA Clean Water Act discharge standards and state-level NPDES permits shape facility design, chemical selection, and wastewater handling investments across the United States. OSHA worker safety protocols and DOT vehicle inspection requirements further tighten operational standards for commercial wash providers. Stakeholders must monitor emerging state water reuse mandates and chemical disclosure rules that will determine capital allocation for next-generation wash infrastructure.
Market Dynamics
Water reclamation systems are compressing operating costs while EPA discharge permits force capital reinvestment cycles across the installed base of heavy duty truck wash facilities.
Growth Catalysts
- EPA NPDES Permit Compliance:Fleet operators face escalating penalties for untreated wastewater discharge, accelerating scheduled wash program adoption and facility modernization investments.
- Corrosion Prevention Protocols:Salt-belt logistics corridors mandate frequent exterior washing to preserve vehicle structural integrity and extend asset depreciation schedules.
- Touchless Automation:High-pressure touchless architectures reduce brush-related paint damage claims while sustaining throughput volumes for high-frequency fleet customers.
Market Restraints
- Specialized Equipment Supply Concentration:Automated reclaim system fabricators cluster in the Upper Midwest, creating procurement bottlenecks and extended lead times for coastal facility expansions.
- Input Cost Volatility:Biodegradable surfactant formulations depend on petroleum-derived feedstocks, exposing margin structures to crude price swings without pass-through contract mechanisms.
- Site Zoning Friction:Municipal land-use boards in dense logistics corridors restrict new wash pad construction near residential zones, capping greenfield capacity additions.
Strategic Opportunities
- Underpenetrated Intermodal Corridors:Texas and Florida interstate networks lack proportional wash infrastructure relative to freight tonnage, presenting first-mover site selection advantages.
- State Water Reuse Mandates:California's escalating freshwater restrictions will force adoption of closed-loop reclaim systems, creating retrofit demand among existing operators.
- Telematics Integration:Fleet management software convergence with wash scheduling platforms enables predictive maintenance tie-ins and automated service routing.
Industry Challenges
- Wastewater Chemistry Expertise Gap:Facility operators struggle to recruit technicians capable of balancing reclaim system pH levels while maintaining EPA discharge compliance.
- Legacy Pad Infrastructure Retrofit Costs:Older wash facilities require extensive concrete excavation and plumbing reconfiguration to accommodate closed-loop reclamation architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Truck Wash Market |
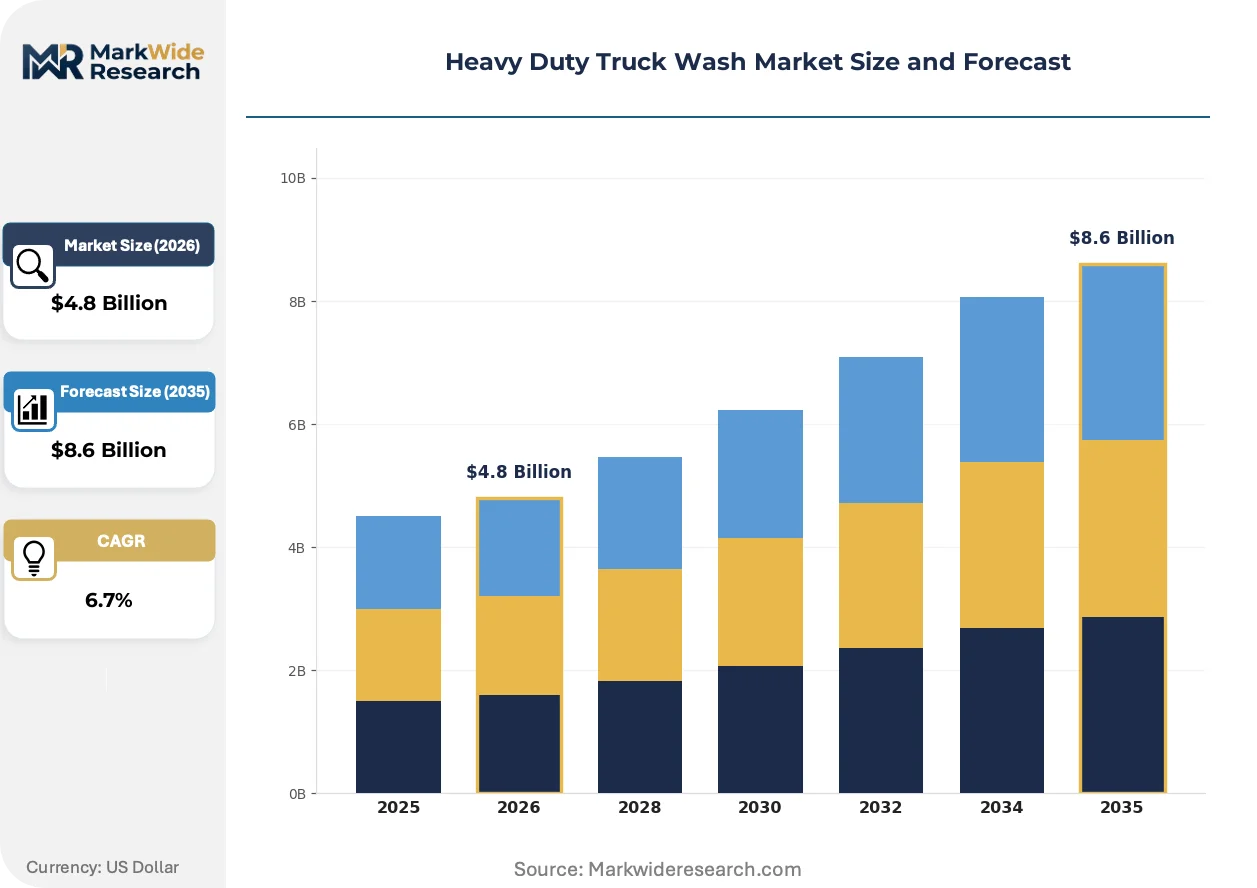
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exterior Wash, Interior Cleaning, Engine Cleaning, Maintenance Wash Technology: High-Pressure Water, Steam Cleaning, Automatic Systems, Chemical Application End User: Logistics Companies, Fleet Operators, Owner-Operators, Transportation Services Size: Small Fleets, Medium Fleets, Large Fleets, Independent Owners |
| Companies Covered | Chemtools, Simple Green, FLEETWASH, Total Coolants, Sinopec, InterClean Equipment, Josco, Armor All, Westmatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Truck Wash Market Trends and Innovations
Automation architectures and regulatory stringency are compressing the viable operating model for heavy duty truck wash facilities toward high-throughput, low-water-intensity configurations.
Sensor-driven wash cycle optimization is digitizing throughput management across large fleet installations. Advanced pressure transducers and chemical dosing algorithms adjust spray patterns in real-time based on vehicle soil load detection. Major fleet operators deploying these systems report reduced freshwater draw per wash without compromising cleaning efficacy.
EPA Clean Water Act enforcement intensification is tightening discharge permit renewal standards for commercial wash facilities. The agency's 2023 effluent limitation guidelines revision imposed stricter biological oxygen demand thresholds on industrial wastewater outfalls. Operators in Great Lakes states face the most aggressive compliance timelines, with Michigan and Ohio facilities already retrofitting biological treatment stages.
Scheduled maintenance bundling is displacing transactional wash purchasing among large fleet accounts. National logistics providers now negotiate integrated service contracts combining exterior washing with DOT inspection preparation and undercarriage corrosion treatment. This procurement consolidation concentrates volume with multi-site operators capable of standardized service delivery across dispersed terminal networks.
Heavy Duty Truck Wash Market Segmentation
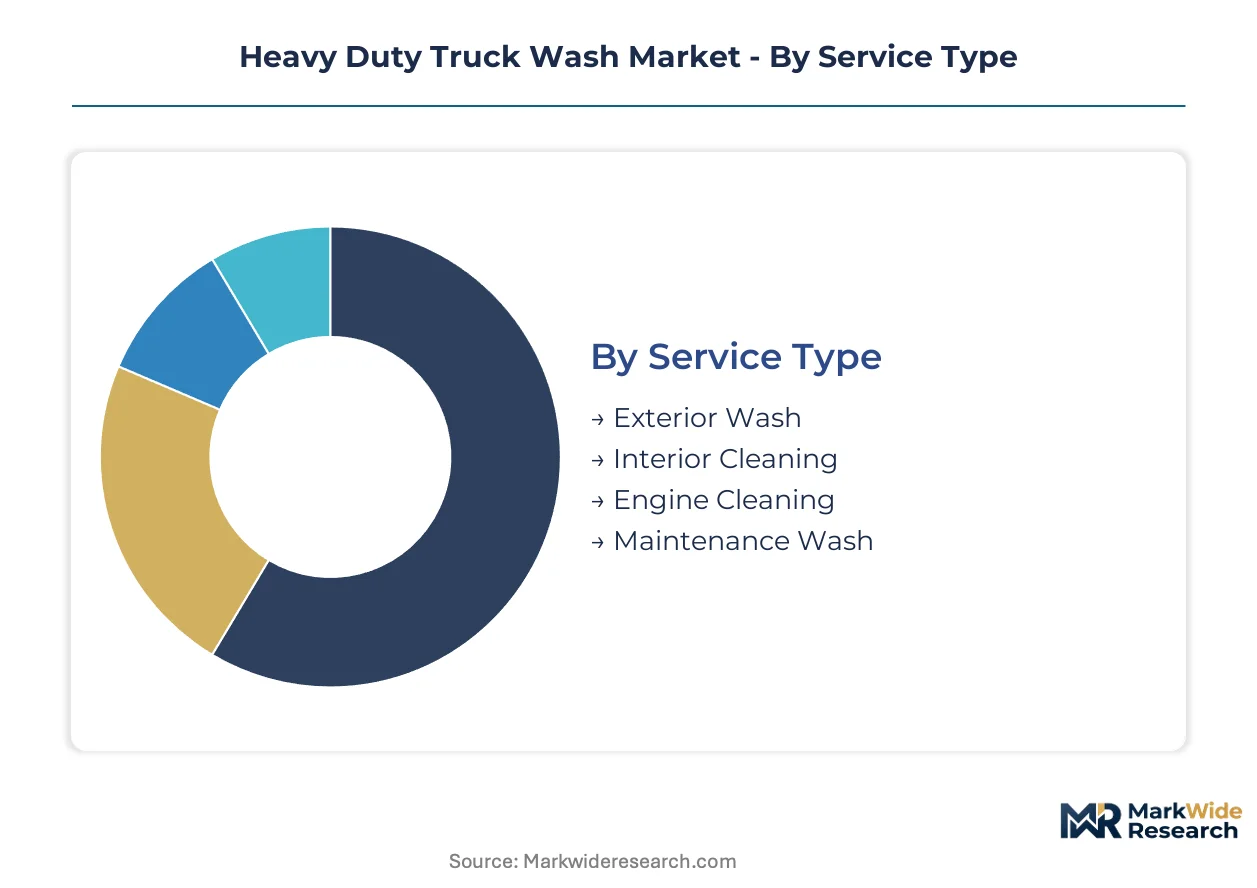
Heavy duty truck wash operators configure service portfolios around fleet scale, regulatory exposure, and throughput economics. Segment boundaries determine capital intensity, pricing architecture, and customer retention mechanics across the installed base.
Service Type:
Application intensity varies sharply across wash categories, with frequency mandates and corrosion risk defining revenue stability.
- Exterior Wash:High-pressure spray systems remove road film, salt accumulation, and corrosive de-icing agents from cab surfaces, trailers, and undercarriages. Salt-belt logistics corridors in Michigan and Ohio sustain the highest frequency schedules, driven by DOT inspection protocols and asset preservation mandates.
- Interior Cleaning:Cabin sanitization, dashboard treatment, and sleeper compartment maintenance address driver retention and hygiene standards. Large fleet operators with dispersed terminal networks concentrate procurement through national service contracts that bundle interior services with scheduled maintenance.
- Engine Cleaning:Degreasing and compartment washdown support thermal management and leak detection.
- Maintenance Wash:Scheduled programs integrate washing with DOT inspection preparation and corrosion prevention treatments.
Exterior wash commands the established base. The steepest expansion runs through maintenance wash bundling.
Technology:
Capital deployment and operating cost structures diverge across mechanization levels and water intensity.
- High-Pressure Water:Touchless spray architectures deliver 1,200-2,500 PSI cleaning force without brush contact, reducing paint damage claims. Automatic reclaim system integration in Great Lakes states cuts freshwater draw while sustaining EPA NPDES compliance.
- Steam Cleaning:Low-water vapor systems penetrate grease deposits and sanitize surfaces with minimal effluent generation. California operators facing escalating freshwater restrictions deploy steam as a closed-loop alternative to conventional wash pads.
- Automatic Systems:Conveyor-driven wash tunnels optimize throughput for high-volume fleet terminals.
- Chemical Application:Biodegradable surfactant dosing systems balance cleaning efficacy against EPA discharge limits.
High-pressure water retains the volume base. Steam cleaning climbs the fastest as water stress intensifies.
End User:
Customer scale dictates procurement sophistication, contract structure, and service integration depth.
- Fleet Operators:Multi-vehicle accounts negotiate standardized wash protocols across dispersed terminal networks, capturing volume discounts and predictive scheduling through telematics integration. National logistics providers in Texas and Florida interstate corridors drive expansion demand where infrastructure lags freight tonnage growth.
- Logistics Companies:Third-party transportation firms outsource vehicle maintenance to specialized wash providers, prioritizing route density and turnaround speed.
- Owner-Operators:Single-vehicle proprietors purchase transactional services with limited contract commitment.
- Transportation Services:Passenger and specialty haulage operators maintain appearance standards through scheduled programs.
Fleet operators anchor procurement volume. Logistics companies gain share fastest through outsourcing consolidation.
Size:
Fleet scale segments determine pricing tier access, service customization, and technology adoption timing.
- Large Fleets:Operators with 500+ vehicles deploy captive wash infrastructure or negotiate exclusive multi-site contracts with national service networks. Volume concentration enables reclaim system investments that compress per-wash operating costs below transactional market rates.
- Medium Fleets:50-500 vehicle operators balance cost control against capital constraints through third-party scheduled programs.
- Small Fleets:10-50 vehicle accounts purchase spot services with limited pricing leverage.
- Independent Owners:Single-vehicle operators represent price-sensitive, low-frequency demand.
Large fleets dominate contract value. Medium fleets expand most quickly as regional logistics providers scale vehicle counts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators concentrate procurement volume in logistics corridors where Interstate density and state inspection protocols intersect. Large vehicle accounts negotiate standardized wash programs across dispersed terminal networks, capturing volume discounts through multi-site contracts.
United States
Interstate corridor density in Michigan and Ohio sustains the highest wash frequency schedules, driven by salt-belt corrosion prevention and DOT inspection mandates. EPA NPDES permit enforcement tightens discharge standards for commercial wash facilities, accelerating reclaim system investments. Dallas-Fort Worth and Houston logistics hubs exhibit infrastructure lag relative to freight tonnage growth.
Germany
Autobahn freight corridors and strict commercial vehicle maintenance standards sustain consistent wash demand among Central European fleet operators. REACH chemical regulations and national water protection laws govern surfactant formulation and wastewater handling. The Ruhr industrial cluster hosts concentrated wash infrastructure serving cross-border logistics traffic.
China
Expanding e-commerce logistics networks and tightening MEE environmental discharge standards reshape facility economics across coastal manufacturing zones. Dual carbon goals accelerate water reclamation technology deployment in Yangtze River Delta freight terminals. Shenzhen and Guangzhou logistics hubs drive touchless automation adoption.
Canada
Trans-Canada Highway freight volumes and provincial environmental protection regulations sustain scheduled wash program adoption among cross-border operators. Health Canada and PMRA chemical oversight influences biodegradable surfactant selection. The Windsor-Quebec Corridor concentrates wash infrastructure serving US-Canada trade lanes.
Australia
Long-haul mining logistics and TGA chemical safety standards shape wash service procurement across remote corridor networks. Water scarcity in Western Australia drives steam cleaning and reclaim system deployment. Perth and Brisbane freight terminals exhibit rising automation investment.
Heavy Duty Truck Wash Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented national service networks and concentrated equipment fabrication clusters. The installed base splits between route-dense service operators and technology-integrated equipment suppliers. Three archetypes dominate: national fleet service networks, automated system fabricators, and biodegradable chemical formulators. Competitive moves center on telematics integration partnerships and reclaim system retrofit programs.
Within the national service tier, FLEETWASH anchors route density strategies across dispersed terminal networks. Among equipment specialists, InterClean Equipment occupies a position exemplifying high-pressure automation architecture. Simple Green represents the chemical formulation archetype navigating discharge compliance limits. These three companies illustrate how scale, technology integration, and regulatory adaptation define competitive positioning.
| Leading Market Players |
|---|
| Chemtools |
| Simple Green |
| FLEETWASH |
| Total Coolants |
| Sinopec |
| InterClean Equipment |
| Josco |
| Armor All |
| Westmatic |
| Others |
Pricing and Supply Chain Analysis
I-35 corridor freight economics compress margin structures for wash operators while concentrating procurement leverage among large fleet accounts. Salt-belt logistics density in Michigan and Ohio anchors premium pricing tiers for corrosion-prevention bundling, whereas Texas and Florida corridor expansions face infrastructure lag that suppresses regional price realization.
Pricing Analysis
Cost-plus contracts with crude-indexed surfactant pass-through clauses dominate large fleet agreements, insulating operators from petroleum feedstock volatility. Three-tier pricing structure across premium reclaim-integrated, standard high-pressure, and economy spot-wash levels separates contract value by EPA compliance tier and telematics integration depth. Pricing pressure stems from biodegradable chemical cost compression without full pass-through elasticity. Owner-operators exhibit acute price sensitivity; large fleets with captive infrastructure show inelastic demand for bundled maintenance programs.
Supply Chain Analysis
Supplier-financing facilities from Upper Midwest equipment fabricators extend payment terms to 180 days for reclaim system procurement, easing capital constraints for greenfield developments. Automated wash system fabrication concentrates in Ohio, Michigan, and Wisconsin; high-pressure pump assemblies draw from German and Japanese component suppliers. Supply chain risk centers on single-source vulnerability for pH-balanced surfactant precursors subject to EPA discharge rule changes. Distribution runs through national service networks with route-dense terminal coverage and third-party logistics partnerships for chemical supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heavy duty truck wash market fragmentation creates acquisition opportunities as telematics integration and water reuse mandates splinter service requirements across fleet scale tiers.
For Market Incumbents: Insulate contract retention by embedding wash scheduling into fleet management software platforms, neutralizing standalone equipment vendors. Secure backward integration into surfactant formulation to capture margin pools threatened by petroleum price volatility. Prioritize reclaim system retrofit programs in California and Great Lakes states ahead of EPA NPDES enforcement intensification. For New Entrants and Emerging Players: Build out underpenetrated Texas and Florida interstate corridors where freight tonnage growth outpaces wash infrastructure density. Target medium fleet operators scaling from 50 to 500 vehicles, a segment consolidating procurement through regional logistics providers. Deploy mobile wash units with closed-loop reclamation as a low-capex entry vector against fixed-pad incumbents. For Investors and Strategic Acquirers: Regional multi-site operators with established EPA permitting and route density in salt-belt corridors represent the most defensible acquisition archetype. Long-term viability hinges on water stress trajectory and reclaim technology depreciation cycles across the projection horizon. Monitor California MEE discharge standard harmonization with EPA guidelines as a regulatory inflection signal for nationwide retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Reclamation Retrofit | California freshwater restrictions and EPA NPDES enforcement compress payback periods for reclaim system investments. |
| Telematics Platform Integration | Fleet management software convergence enables predictive wash scheduling and automated service routing for large accounts. |
| Biodegradable Surfactant Backward Integration | Petroleum feedstock volatility threatens margin structures without captive formulation capacity or indexation clauses. |
| Salt-Belt Corridor Route Density Expansion | Michigan and Ohio DOT inspection mandates sustain highest-frequency wash demand with premium bundling potential. |
| Mobile Wash Unit Deployment | Low-capex entry model bypasses municipal zoning friction for greenfield pad construction in dense logistics corridors. |
Research Methodology
The analysis maps exterior wash, interior cleaning, engine washdown, and maintenance bundling service tiers, each validated through fleet operations managers, EPA compliance officers, equipment procurement leads, and chemical formulation specialists. Primary interviews with terminal network directors and reclaim system technicians combined with secondary validation from EPA effluent limitation guidelines, state NPDES permit databases, DOT inspection protocol documents, and customs trade data for surfactant imports. Bottom-up fleet count modeling and top-down logistics corridor freight tonnage estimates were triangulated against facility throughput surveys.
Assumption sets held regulatory enforcement trajectory and petroleum feedstock price bands fixed while varying fleet electrification penetration and water reuse mandate adoption speed across the projection horizon. Segmentation dimensions modeled include service type, technology mechanization level, end-user fleet scale, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and per-fleet wash frequency intensification. Forecast inputs incorporated Interstate corridor density projections and EPA Clean Water Act enforcement budget allocations.
Stress conditions across surfactant cost volatility, reclaim system capital availability, and municipal zoning approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet growth trajectories and regulatory implementation schedules. Macroeconomic freight demand contraction, abrupt EPA discharge standard revision, or breakthrough waterless cleaning technology commercialization would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Tipper Truck Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Mexico Refrigerated Truck Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
Bucket Trucks Market
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
Heavy-Truck Composite Component Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Heavy-Duty Truck Fleet Control Unit Architectures Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Digger Derrick Truck Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Truck Tank Market