
 Onboard Maintenance Systems Market | 2026-2036
Onboard Maintenance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Onboard Maintenance Systems Market Analytics
Market Context
Buyer concentration among full-service carriers and low-cost airlines is expanding as fleet operators consolidate maintenance contracts with fewer integrated platform providers. Honeywell International leverages its avionics heritage to dominate integrated health monitoring suites for narrow-body platforms. GE Aerospace anchors its position through embedded engine diagnostics that tie directly to digital thread analytics. Safran Aircraft Engines competes on proprietary sensor architectures that feed predictive algorithms for leap-engine fleets.
Technical Definition and Segment Structure
Onboard Maintenance Systems encompass integrated hardware-software architectures installed on vehicles to perform real-time fault detection, prognostic analysis, and maintenance scheduling without requiring ground-based intervention. These systems typically incorporate embedded processors, sensor fusion modules, and ARINC 429 or CAN bus interfaces to aggregate subsystem telemetry into centralized diagnostic engines. Monitoring Systems and AI-Based Systems capture the strongest margin pools as operators prioritize predictive capabilities over reactive repair workflows. Software Solutions represent the fastest-expanding segment as airlines shift from perpetual licenses to subscription-based fleet analytics platforms. Embedded Systems retain maturity in marine and rail applications where hardware refresh cycles lag aviation by several years.
Regulatory Framework and Outlook
FAA airworthiness standards under 14 CFR Part 25 and EASA CS-25 certification requirements mandate traceable maintenance records and fault isolation capabilities for transport-category aircraft. The EU AI Act introduces conformity obligations for machine-learning components within safety-critical maintenance software that European-registered operators must address. China's CAAC aligns with NMPA-equivalent processes for embedded medical device crossover components in specialized aviation applications. Stakeholders must monitor how emerging algorithmic transparency rules reshape development costs for AI-Based Systems across jurisdictions.
Market Dynamics
Airlines are consolidating maintenance contracts with fewer integrated platform providers, compressing vendor margins while elevating technical performance requirements for predictive analytics and real-time fault isolation across narrow-body and wide-body fleets.
Growth Catalysts
- FAA Airworthiness Directives:Mandates for traceable maintenance records and continuous monitoring capabilities are forcing fleet-wide upgrades of legacy diagnostic hardware.
- Sensor Fusion Architectures:Advances in ARINC 429 and CAN bus integration enable centralized telemetry aggregation that reduces unscheduled downtime.
- Low-Cost Carrier Expansion:Aggressive fleet growth in Southeast Asia and Latin America is generating concentrated demand for scalable, subscription-based maintenance platforms.
Market Restraints
- Semiconductor Supply Concentration:Embedded processor fabrication concentrates in Taiwan and South Korea, exposing aviation OEMs to geopolitical disruption risk.
- EASA Algorithmic Transparency Rules:The EU AI Act imposes conformity assessment burdens on machine-learning diagnostic software, extending certification timelines.
- Legacy Hardware Refresh Cycles:Marine and rail applications lag aviation by several years, constraining cross-platform R&D amortization for integrated system suppliers.
Strategic Opportunities
- India Fleet Modernization:DGCA regulatory alignment with ICAO standards is accelerating adoption of predictive maintenance among IndiGo and Air India operators.
- Digital Thread Convergence:Integration of engine diagnostics with MRO analytics platforms creates bundled service revenue streams.
- Subscription Platform Migration:Airlines are abandoning perpetual software licenses for fleet-wide analytics subscriptions, improving vendor recurring revenue visibility.
Industry Challenges
- Avionics Software Certification:DO-178C compliance for safety-critical diagnostic algorithms demands specialized engineering talent that remains scarce.
- Interoperability Friction:Proprietary sensor architectures from competing engine OEMs complicate unified fleet monitoring deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Onboard Maintenance Systems Market |
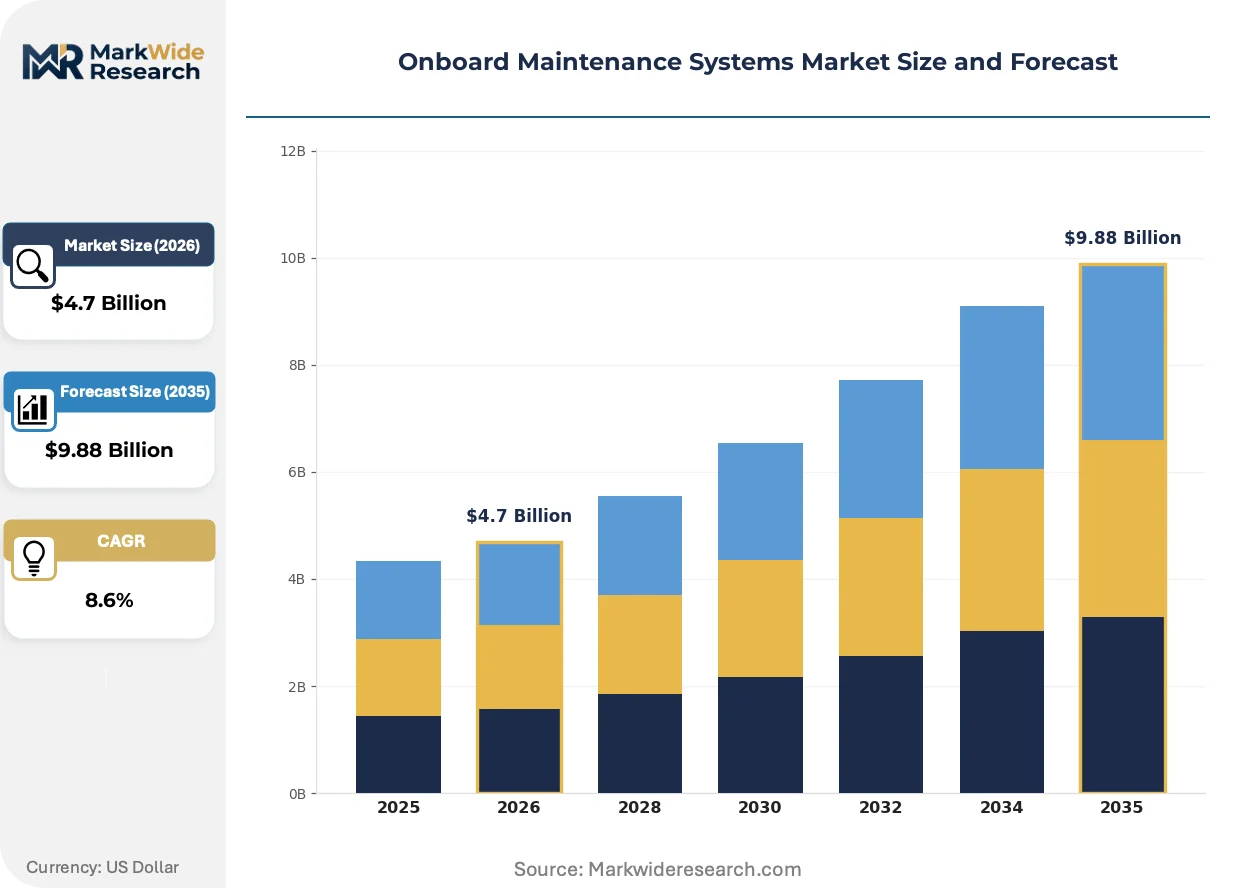
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tools, Monitoring Systems, Repair Kits, Software Solutions End User: Aerospace, Marine, Automotive, Railways Technology: IoT Solutions, AI-Based Systems, Cloud Platforms, Embedded Systems Application: Predictive Maintenance, Routine Checks, Component Replacement, Performance Optimization |
| Companies Covered | Honeywell International, GE Aerospace, AVIAGE SYSTEMS, Ramco Systems, Safran Aircraft Engines, ST Aerospace, Lufthansa Technik, Air France KLM Engineering & Maintenance, Pratt & Whitney, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Onboard Maintenance Systems Market Evolving Landscape
Predictive maintenance platforms are absorbing artificial intelligence capabilities that compress fault-to-resolution cycles. Three developments are restructuring competitive positioning.
Edge computing architectures are absorbing inference workloads previously routed to ground-based servers. Full-service carriers including Lufthansa and Delta are deploying onboard GPU clusters that process vibration and thermal data within 50 milliseconds. This compression is absorbing latency penalties that previously limited real-time prognostics to engine subsystems alone.
REACH substance restrictions and the EU AI Act are jointly reshaping hardware-software development cycles. EASA mandates for algorithmic explainability now require documentation trails for machine-learning fault classifications. European-registered operators are responding by demanding open-architecture diagnostic engines that permit regulator audit access.
Maintenance procurement is fragmenting across asset-light and asset-heavy models. Low-cost carriers are unbundling engine health monitoring from airframe MRO contracts, creating direct procurement relationships with sensor OEMs. This disintermediation is most visible in Southeast Asia, where VietJet and Cebu Pacific have separated predictive analytics purchasing from legacy airframe service agreements.
Onboard Maintenance Systems Market Segmentation
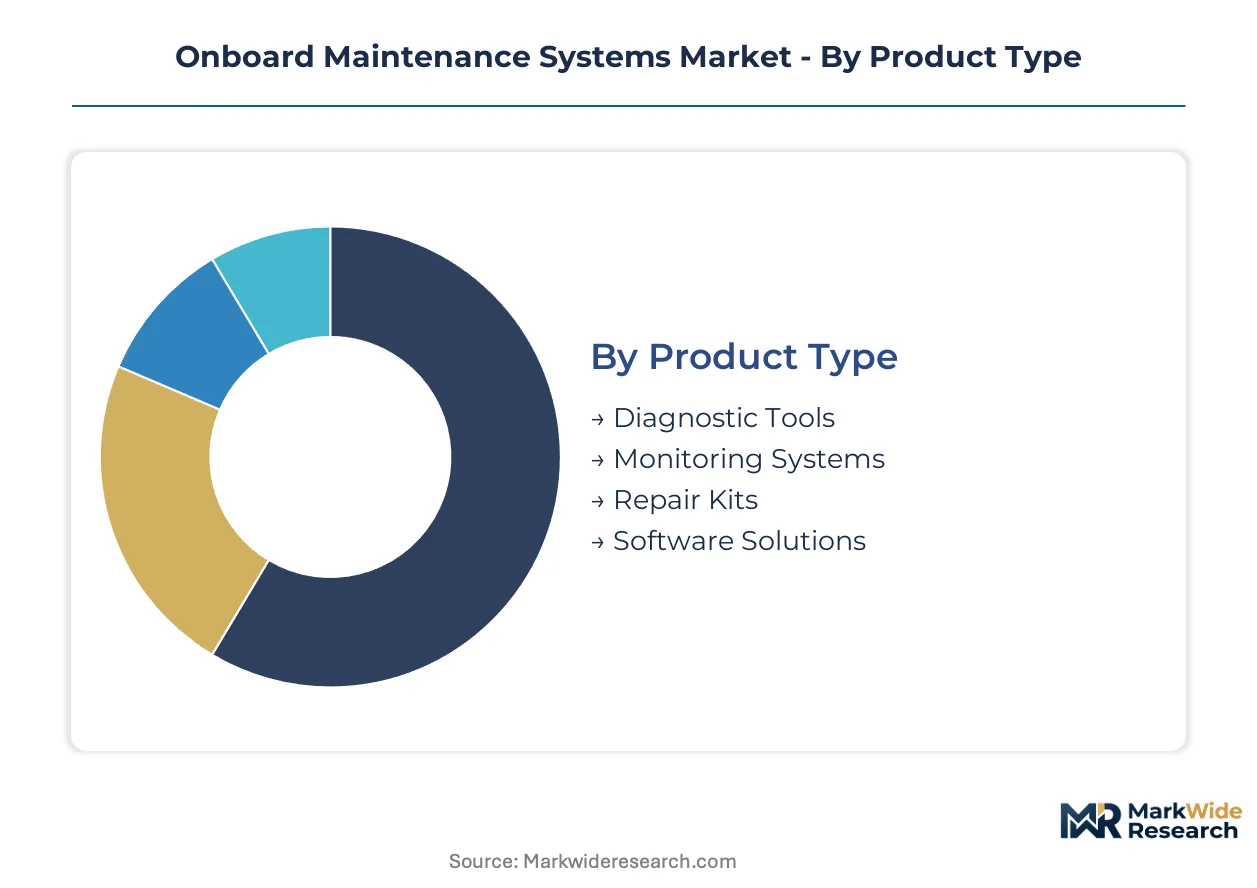
Segmentation in the Onboard Maintenance Systems Market reveals divergent technology maturity across transport modes. Product architecture, deployment environment, and maintenance philosophy each reshape procurement patterns and vendor margin structures differently.
Product Type:
Supply concentration in processor fabrication and sensor module sourcing elevates hardware-software integration as the primary vendor differentiator.
- Monitoring Systems:These architectures aggregate ARINC 429 and CAN bus telemetry into centralized diagnostic engines with embedded sensor fusion modules. Demand concentrates among narrow-body fleet operators in the United States and Germany where FAA and EASA mandates for continuous airworthiness documentation are tightening. Unscheduled downtime reduction drives airline procurement decisions.
- Software Solutions:Subscription-based fleet analytics platforms replace perpetual licenses through cloud-native deployment and API-first integration with MRO systems. Low-cost carriers in Southeast Asia and Latin America are migrating fastest to SaaS maintenance platforms. Scalability without hardware refresh cycles attracts asset-light operators.
- Diagnostic Tools:Portable fault isolation equipment for line maintenance operations.
- Repair Kits:Modular component replacement assemblies stocked for AOG scenarios.
Monitoring Systems absorb the bulk of installed capacity; Software Solutions is expanding most quickly.
End User:
Application environment dictates hardware ruggedization standards and certification burden intensity.
- Aerospace:DO-178C compliant diagnostic algorithms process engine vibration, thermal, and oil debris data through embedded GPU clusters. Full-service carriers including Lufthansa and Delta deploy edge computing architectures that compress fault-to-resolution cycles below 50 milliseconds. FAA airworthiness directives mandate traceable maintenance records across transport-category fleets.
- Marine:Salt-corrosion-resistant sensor housings and redundant data links serve container shipping and offshore supply vessels. Hardware refresh cycles lag aviation by several years due to classification society approval timelines. Embedded Systems retain dominance where connectivity infrastructure remains limited.
- Automotive:CAN-FD and Ethernet-based diagnostics for commercial vehicle fleets.
- Railways:Wayside and onboard condition monitoring for rolling stock and track infrastructure.
Aerospace commands the dominant revenue share; Marine offers the steepest expansion trajectory as classification societies modernize survey protocols.
Technology:
Development cost allocation shifts dramatically between edge inference and cloud training workloads.
- AI-Based Systems:Machine-learning fault classification algorithms face EASA conformity obligations under the EU AI Act for algorithmic explainability. European-registered operators now demand open-architecture diagnostic engines permitting regulator audit access. Development teams must document training data provenance and model decision boundaries.
- IoT Solutions:Wireless sensor networks with LPWAN or 5G backhaul connect distributed mechanical assets to centralized analytics platforms. Industrial operators in China leverage MIIT-licensed spectrum for private network deployments. Real-time telemetry streams enable condition-based maintenance triggers.
- Cloud Platforms:Fleet-wide data lakes aggregating historical failure patterns for pattern recognition.
- Embedded Systems:Hard-real-time processors executing deterministic diagnostic routines without external connectivity.
Embedded Systems retain maturity in safety-critical applications; AI-Based Systems are climbing the fastest as predictive capabilities displace reactive workflows.
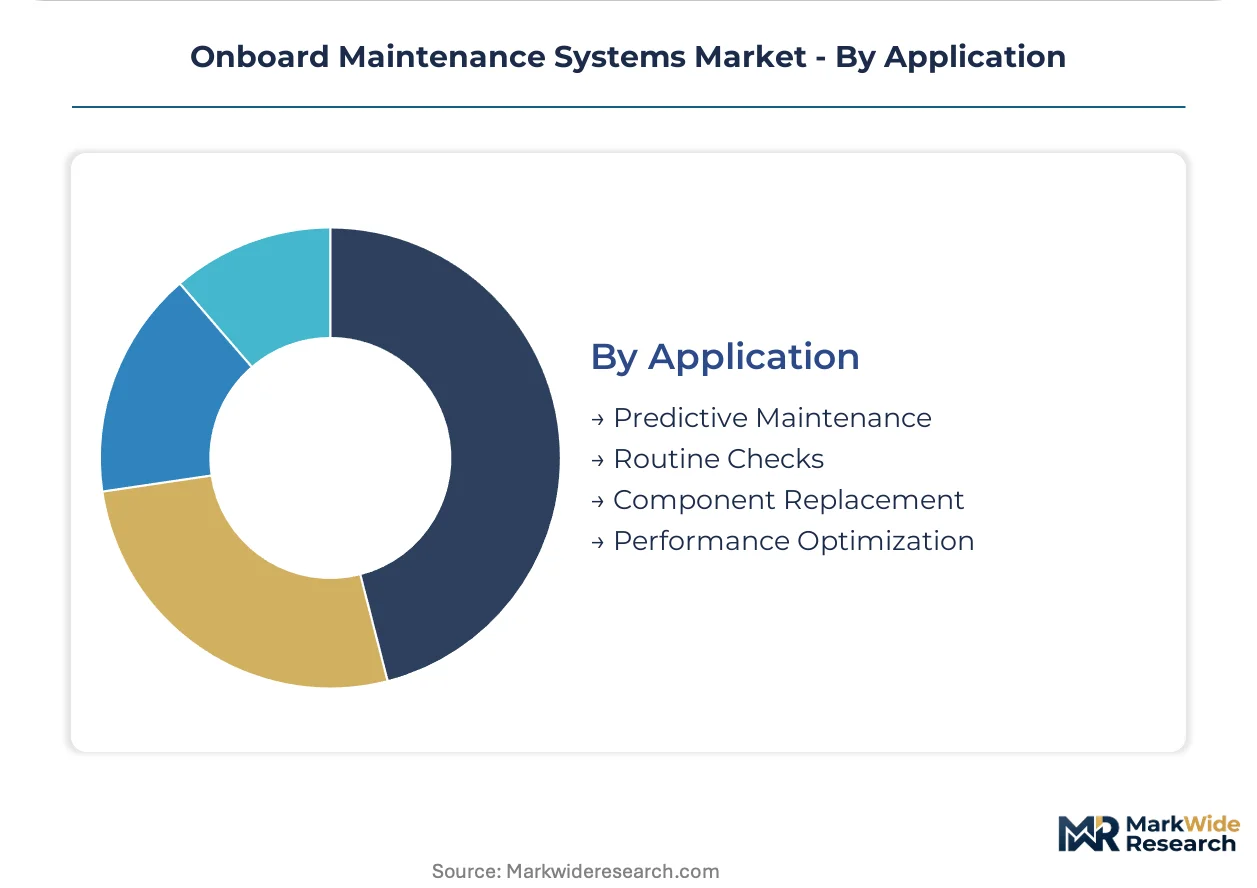
Application:
Maintenance philosophy restructures operator-vendor relationships from transactional spares to outcome-based service contracts.
- Predictive Maintenance:Prognostic algorithms estimate remaining useful life for rotating machinery and structural components. Airlines consolidate contracts with integrated platform providers, compressing vendor margins while elevating technical performance requirements. Sensor fusion architectures enable fault isolation before operational impact.
- Routine Checks:Scheduled inspection protocols digitized through mobile workforce applications and electronic logbooks.
- Component Replacement:Inventory optimization algorithms balancing parts availability against carrying cost.
- Performance Optimization:Fuel efficiency and emissions reduction through engine tuning recommendations.
Predictive Maintenance captures the dominant share of new platform investment; Performance Optimization is gaining share fastest as fuel cost pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Full-service carriers and low-cost airlines in the United States, Germany, and China concentrate procurement of predictive maintenance platforms, while regulatory tightening across multiple jurisdictions accelerates fleet-wide diagnostic upgrades.
United States
Delta Air Lines and United Airlines drive demand for edge computing architectures that process engine telemetry within 50 milliseconds. FAA airworthiness directives under 14 CFR Part 25 mandate traceable maintenance records and continuous monitoring capabilities across transport-category fleets. Seattle and Atlanta anchor the densest clusters of MRO infrastructure and OEM service network deployment.
Germany
Lufthansa Technik consolidates maintenance contracts for narrow-body and wide-body fleets, compressing vendor margins while elevating technical performance requirements. EASA CS-25 certification requirements and the EU AI Act impose conformity obligations for algorithmic explainability in machine-learning diagnostic software. Hamburg and Munich concentrate embedded processor integration facilities and sensor fusion module development.
China
CAAC regulatory alignment with ICAO standards accelerates adoption of predictive maintenance among Air China and China Eastern operators. MIIT-licensed spectrum enables private 5G network deployments for real-time telemetry streaming in industrial aviation applications. The Yangtze River Delta and Pearl River Delta host the principal clusters of avionics hardware fabrication and cloud-native analytics platform development.
India
IndiGo and Air India fleet modernization programs generate concentrated demand for subscription-based maintenance platforms without hardware refresh cycles. DGCA regulatory alignment with ICAO standards tightens documentation and real-time monitoring requirements for continuing airworthiness. Bangalore and Hyderabad anchor embedded systems engineering talent pools and software certification service providers.
Japan
ANA and JAL deploy AI-based prognostic algorithms for remaining useful life estimation on leap-engine fleets. METI industrial policy supports domestic sensor architecture development and edge inference workload processing capabilities. The Nagoya aerospace cluster and Tokyo metropolitan area concentrate avionics systems integration and MRO analytics platform partnerships.
Onboard Maintenance Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native analytics and unbundled sensor procurement relationships. The vendor base concentrates among integrated platform providers with avionics heritage and engine OEMs with embedded diagnostic capabilities. Three archetypes dominate: diversified aerospace conglomerates with full-stack health monitoring suites, specialized engine manufacturers with proprietary sensor architectures, and independent software vendors with SaaS fleet analytics platforms. Competitive moves center on strategic partnerships between sensor OEMs and low-cost carriers, plus portfolio diversification into subscription revenue models.
Within the diversified aerospace tier, Honeywell International and GE Aerospace exemplify integrated platform dominance, while Safran Aircraft Engines occupies a position among engine-centric diagnostic specialists. Honeywell leverages avionics heritage across narrow-body platforms. GE anchors through embedded engine diagnostics tied to digital thread analytics. Safran competes on proprietary sensor architectures feeding predictive algorithms. These three represent distinct strategic postures: full-stack integration, engine-native telemetry, and specialized sensor innovation.
| Leading Market Players |
|---|
| Honeywell International |
| GE Aerospace |
| AVIAGE SYSTEMS |
| Ramco Systems |
| Safran Aircraft Engines |
| ST Aerospace |
| Lufthansa Technik |
| Air France KLM Engineering & Maintenance |
| Pratt & Whitney |
| Others |
Value Network & Pricing Analysis
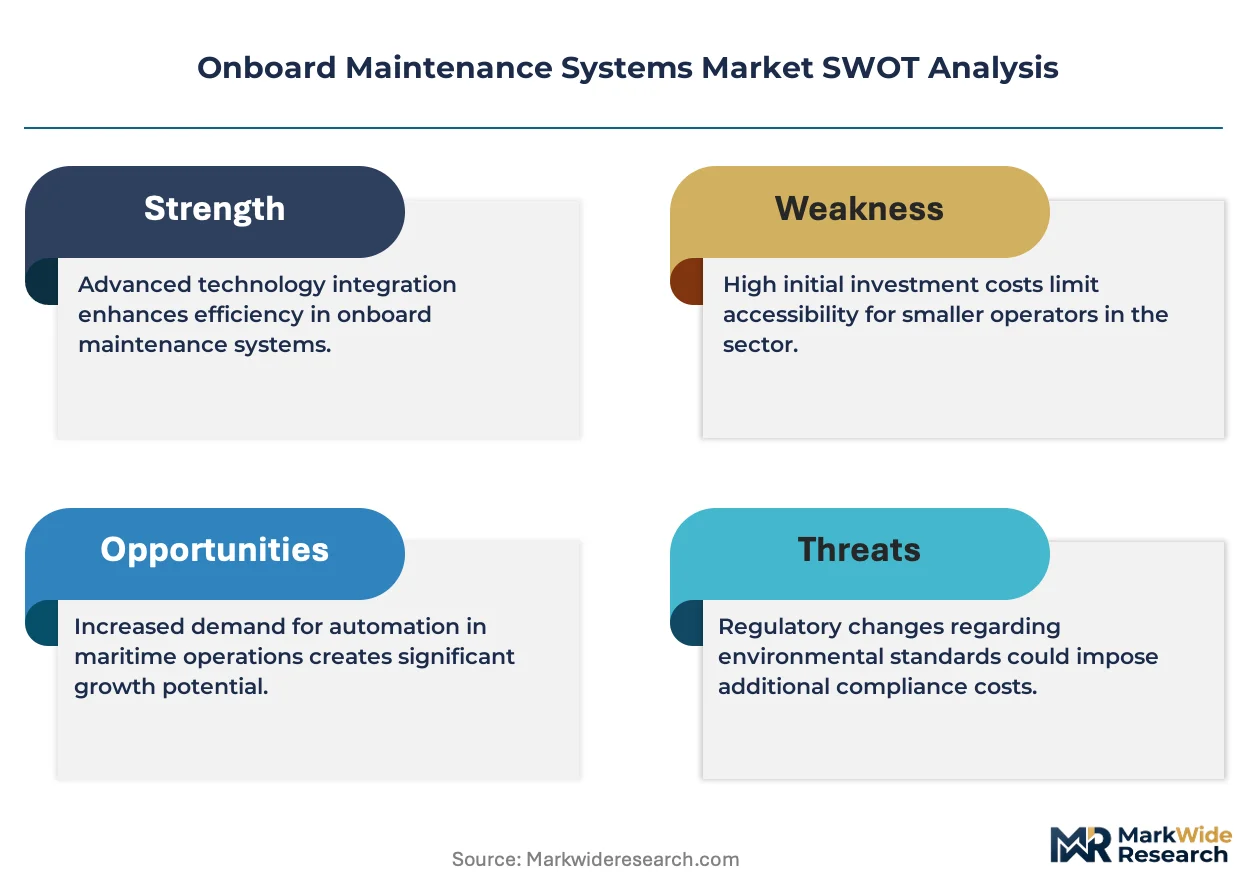
Private-equity-rolled-up MRO platform specialists have consolidated fragmented maintenance software vendors across North America and Europe, compressing vendor margins while elevating pricing discipline through bundled service contracts and multi-year subscription lock-ins.
Pricing Analysis
Volume concentrates in subscription-based SaaS tiers while margins pool in integrated hardware-software bundles. Three-tier pricing structure across premium, standard, and economy levels separates DO-178C certified predictive analytics from basic monitoring dashboards and legacy reactive tools. Pricing pressure stems from low-cost carriers unbundling engine health monitoring from airframe MRO contracts. Asset-light operators in Southeast Asia exhibit the highest price sensitivity; full-service carriers with fleet-wide standardization mandates show the least.
Supply Chain Analysis
Dual-sourcing requirements from Boeing and Airbus procurement mandates force avionics suppliers to qualify secondary sensor module vendors in Japan and Israel alongside Taiwanese primary sources. Embedded processor fabrication draws from Taiwan, South Korea, and the United States. Gallium nitride power components and ARINC 429 transceiver chips face single-source vulnerability from foundry concentration. Distribution runs through OEM-authorized service networks and independent MRO distributors with CAAC and EASA certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from FAA airworthiness directive compliance costs is forcing sub-scale diagnostic software vendors toward strategic exit or acquisition by integrated platform providers.
For Market Incumbents: Lock in fleet-wide exclusivity through digital thread integration that ties engine diagnostics to MRO analytics platforms, neutralizing emerging cloud-native entrants. Deepen backward integration into proprietary sensor architectures to defend against disintermediation by low-cost carriers pursuing direct sensor OEM relationships. Prioritize DO-178C certification investment as a barrier against unqualified software competitors. For New Entrants and Emerging Players: Edge computing inference workloads for real-time prognostics offer a technology-first wedge into narrow-body fleet retrofits where legacy vendors lack GPU cluster deployment expertise. Target India's DGCA-aligned fleet modernization programs where subscription-based platforms without hardware refresh cycles penetrate fastest. Pursue API-first integration partnerships with established MRO analytics platforms rather than competing for full-stack contracts. For Investors and Strategic Acquirers: EASA algorithmic transparency rule implementation is the leading indicator that open-architecture diagnostic engine developers will command scarcity premiums as European-registered operators demand regulator audit access. Focus acquisition screening on SaaS-native maintenance platforms with recurring revenue visibility above sixty percent and embedded systems engineering talent pools in Bangalore or Hyderabad. Watch for CAAC-MIIT private 5G network deployment acceleration as the signal that Chinese avionics hardware fabrication clusters are reaching scale efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Thread Integration | Bundles engine diagnostics with MRO analytics platforms, creating captive revenue streams at Delta and Lufthansa. |
| Edge Computing Deployment | Onboard GPU clusters processing vibration data within 50 milliseconds compress fault-to-resolution cycles for full-service carriers. |
| Subscription Platform Migration | Cloud-native fleet analytics replace perpetual licenses, improving recurring revenue visibility for asset-light operators in Southeast Asia. |
| Proprietary Sensor Architecture Development | Feeding predictive algorithms for leap-engine fleets defends against disintermediation by unbundling low-cost carriers. |
| Open-Architecture Certification Investment | EASA conformity for algorithmic explainability permits regulator audit access, creating compliance moats against unqualified competitors. |
Research Methodology
Independent corroboration across avionics systems engineers, airline fleet maintenance directors, and MRO procurement managers underwrites the qualitative findings. Primary interviews with platform engineering leads at full-service carriers and low-cost operators combined with secondary validation from FAA airworthiness directive filings, EASA certification databases, and CAAC regulatory alignment notices. Customs records for embedded processor imports and SEC 10-K disclosures from diversified aerospace conglomerates anchored supply-side assessment. Bottom-up fleet deployment estimates triangulated against top-down OEM service revenue segmentation.
Rate-of-change decomposition across the projection horizon separates installed base expansion from upgrade cycle acceleration and pricing mix shifts toward subscription platforms. Segmentation modeling incorporated product architecture, end-user fleet type, technology maturity tier, and application philosophy across narrow-body, wide-body, and regional jet deployments. CAGRs derived from regression against fleet growth projections, regulatory mandate implementation timelines, and hardware refresh cycle patterns. Industry-specific inputs included ARINC 429 integration adoption curves and EASA algorithmic transparency rule compliance cost estimates.
Several conditions sit outside the modeled scope, including geopolitical disruption of Taiwanese semiconductor fabrication, unilateral tariff imposition on avionics components, and catastrophic fleet grounding events triggering regulatory moratoria. Forecasts reflect assumptions about continued FAA-EASA regulatory convergence and sustained low-cost carrier expansion in Southeast Asia and Latin America. Deviation in semiconductor supply concentration or EASA certification timeline extension would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Automotive Quality Service Market
Automotive Services
Tow Truck Market
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
United States Automotive Dealership Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Mobile Car Wash Service Market
Automotive Services
Global Car Wash Market
Automotive Services
Motorsports Market
Automotive Services
ADAS Recalibration Services Market
Automotive Services
Europe Car Wash Market
Automotive Services
Global Street Sweeper Market
Automotive Services
North America Car Wash Market
Automotive Services
Luxury Car Rental Market
Automotive Services
Vehicle Analytics Market