
 Global Vocational Truck Market | 2026-2036
Global Vocational Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vocational Truck Market Outlook
Construction sector procurement is repositioning vocational truck demand toward higher-gross-vehicle-weight chassis with integrated power take-off systems. Daimler Truck AG leverages its North American manufacturing footprint to dominate severe-service segments. Volvo Group anchors European municipal and waste collection contracts through dedicated low-cab-forward platforms. PACCAR Inc competes in premium over-the-road derivatives repurposed for vocational duty cycles.
Vocational trucks are purpose-built commercial vehicles engineered with reinforced frames, specialized suspension ratings, and power take-off provisions to accommodate bodies such as dumps, tanks, cranes, or refuse packers. Gross vehicle weight ratings typically span Class 6 through Class 8, with frame rail tensile strength and axle capacity calibrated to sustained off-pavement operation. Dump trucks occupy the largest product type position due to universal infrastructure and mining applicability, while tanker trucks represent a concentrated margin pool where hazardous materials certification creates supply scarcity. Automatic transmission configurations are gaining fastest among municipal and delivery services as driver recruitment challenges intensify.
EPA Phase 3 standards, Euro VII frameworks, and China's MIIT fuel consumption regulations are forcing engine downsizing and hybridization investments across OEM development budgets. NHTSA braking and stability mandates for heavy trucks add compliance cost layers that favor scaled manufacturers with captive certification resources. Stakeholders must monitor how zero-emission powertrain mandates in California, Germany, and China's coastal provinces redefine chassis architecture and total cost of ownership calculations before committing fleet replacement schedules.
Market Dynamics
EPA Phase 3 greenhouse gas standards and Euro VII emission frameworks are compressing engine development cycles while forcing chassis redesigns for hybrid compatibility. Fleet operators now face accelerated replacement timelines as zero-emission mandates in California, Germany, and China's coastal provinces redefine total cost of ownership calculations.
Growth Catalysts
- Infrastructure spending acceleration:Public works programs in the United States, Germany, and China are expanding orders for dump trucks and concrete mixers. Municipal fleets require severe-service chassis with integrated power take-off systems for specialized body mounting.
- EPA Phase 3 compliance investments:Engine downsizing and hybridization R&D is creating demand for next-generation powertrain platforms. OEMs with captive certification resources capture fleet replacement schedules ahead of regulatory deadlines.
- Driver recruitment constraints:Automatic transmission configurations are penetrating municipal and delivery services at accelerated rates. Fleet managers specify Allison and Eaton automated manual units to expand eligible driver pools.
Market Restraints
- Steel and aluminum input volatility:Frame rail tensile strength requirements for Class 8 severe-service applications expose manufacturers to commodity price swings. Reinforced chassis specifications intensify material cost sensitivity.
- Emission certification concentration:EPA and CARB engine certification timelines favor scaled OEMs with dedicated regulatory affairs teams. Mid-tier assemblers face exclusion from California-compliant segments.
- Battery weight penalty:Zero-emission powertrain energy density limits payload capacity for vocational duty cycles. Electric refuse packers and dump trucks sacrifice operational efficiency for compliance.
Strategic Opportunities
- India infrastructure build-out:National highway expansion and smart city initiatives are creating demand for tipper trucks and transit mixers. Domestic chassis assemblers lack severe-service engineering depth.
- Telematics-PTO integration:Converging IoT sensors and hydraulic control systems enable usage-based maintenance contracts. Equipment rental fleets monetize uptime guarantees through real-time body equipment monitoring.
- EU Green Deal commercial vehicle incentives:Member state purchase subsidies for zero-emission trucks are compressing electric total cost of ownership gaps. Municipal waste collection contracts now specify battery-electric low-cab-forward platforms.
Industry Challenges
- Powertrain technician scarcity:High-voltage battery and fuel cell servicing requires certifications that vocational fleet maintenance depots lack. OEMs must fund dealer training programs to support warranty compliance.
- Chassis-body integration complexity:Modular electric platforms demand recalibrated frame rail drilling patterns and PTO mounting specifications. Body builders face rework costs when adapting legacy designs to new architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vocational Truck Market |
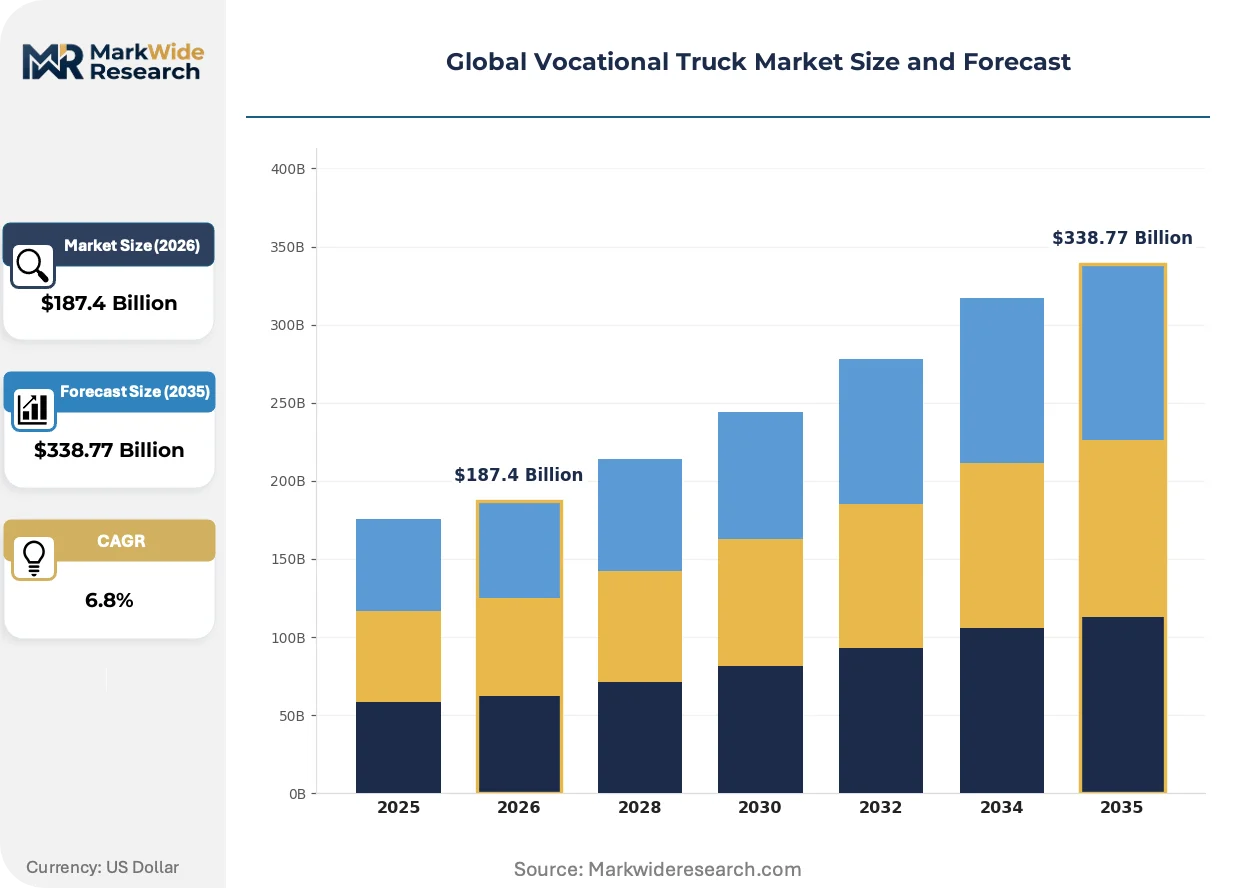
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dump Trucks, Tanker Trucks, Tow Trucks, Box Trucks Cylinder Capacity: 4-Cylinder, 6-Cylinder, 8-Cylinder, Others Transmission Type: Manual, Automatic, Semi-Automatic, Continuous Variable End User: Construction, Mining, Waste Management, Delivery Services |
| Companies Covered | Daimler Truck AG, Volvo Group, PACCAR Inc, Isuzu Motors Ltd, Hino Motors Ltd, Navistar International Corporation, Mitsubishi Fuso Truck and Bus Corporation, Scania AB, MAN SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vocational Truck Market Strategic Shifts
Powertrain electrification and automated transmission penetration are restructuring vocational truck specifications across construction, waste, and utility fleets. Regulatory compliance costs now dominate R&D allocation, compressing differentiation investment in traditional mechanical systems.
Automated manual transmissions are overtaking manual gearboxes in municipal and regional delivery applications. Waste management fleets in California and Germany specify Eaton Cummins Endurant and Allison 3000 series units to reduce driver qualification barriers. This shift is overtaking historical preferences for direct-drive mechanical reliability in severe-service segments.
Euro VII emission frameworks are mandating real-world emissions monitoring through onboard sensors and telematics reporting. Engine manufacturers must redesign aftertreatment systems for urban low-speed duty cycles. Refuse collection and urban delivery segments face the steepest hardware cost increases as they operate disproportionately in regulated air quality zones.
Fleet leasing and full-service maintenance contracts are displacing traditional equipment purchase models among mid-sized construction contractors. Rental companies like United Rentals and Ashtead Group are expanding vocational truck fleets with uptime-guaranteed offerings. This transition concentrates most visibly in the United States where contractor credit constraints and labor volatility amplify preference for operational expenditure treatment.
Global Vocational Truck Market Segmentation
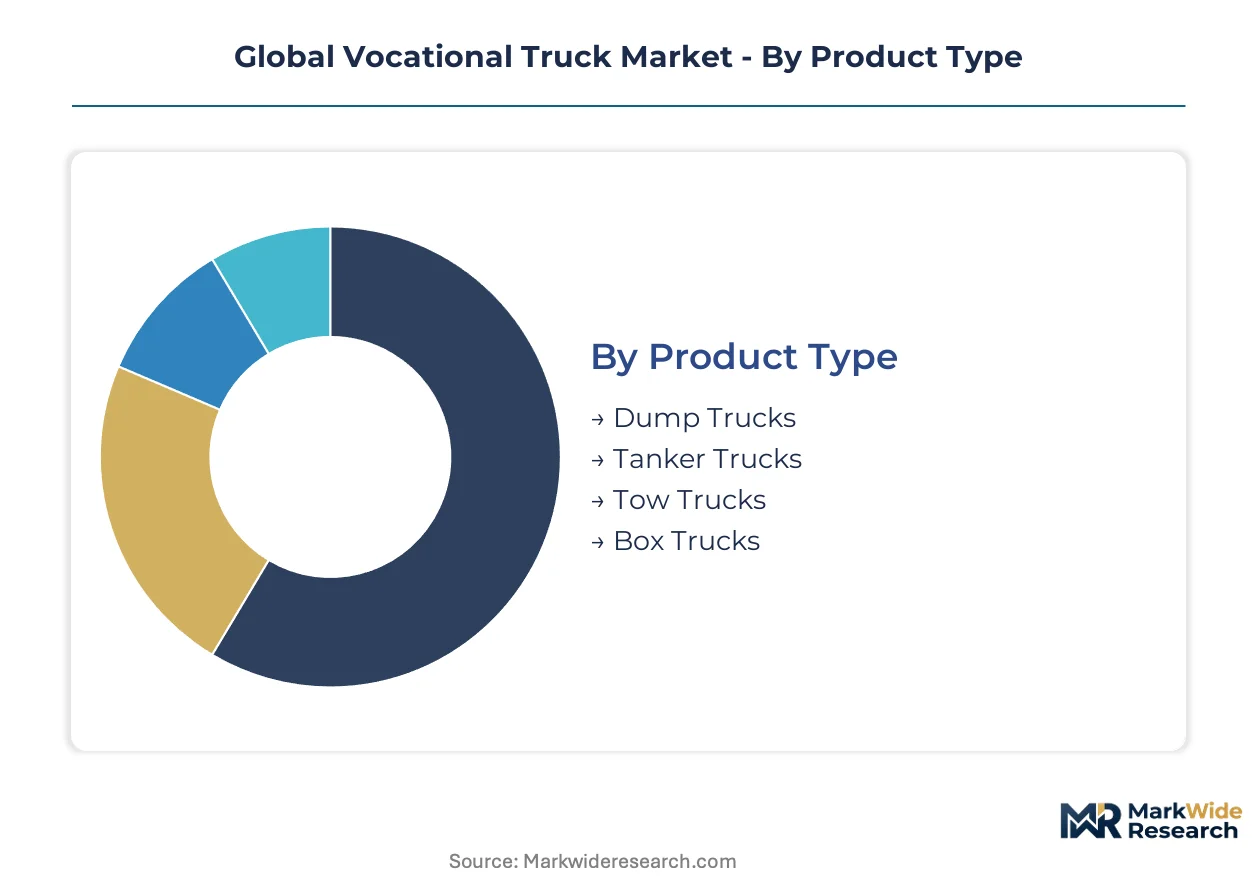
Vocational truck specification varies sharply across duty cycles, with chassis architecture, powertrain calibration, and body integration requirements diverging between construction haulage and urban refuse collection. Fleet procurement teams segment demand by payload capacity, terrain severity, and regulatory exposure rather than brand preference alone.
Product Type:
Application severity and body integration complexity drive chassis specification decisions across fleet procurement teams.
- Dump Trucks:Reinforced frame rails and high-tensile steel construction accommodate aggregate and mining payloads. Infrastructure spending in the United States, Germany, and China sustains order volumes for Class 8 severe-service configurations with integrated power take-off systems.
- Tanker Trucks:Hazardous materials certification requirements create supply scarcity in refined fuel and chemical transport segments. Specialized tank mounting and baffling specifications demand custom chassis engineering that limits qualified body builders.
- Tow Trucks:Recovery operators specify boom capacity ratings and underlift configurations matched to passenger vehicle versus heavy-duty commercial targets. Integrated wheel-lift and sling mechanisms require dedicated PTO hydraulic circuits.
- Box Trucks:Last-mile delivery fleets prioritize cube utilization and loading height over severe-service durability. Urban route density favors lighter Class 6 and 7 chassis with liftgate-compatible electrical systems.
Volume sits with dump trucks; growth tilts toward tanker trucks.
Cylinder Capacity:
Fuel economy regulations and payload requirements are compressing engine displacement preferences across vocational duty cycles.
- 6-Cylinder:Inline and V-configurations dominate Class 6 and 7 municipal applications where weight distribution and service access matter. EPA Phase 3 compliance investments favor medium-displacement architectures with integrated aftertreatment.
- 8-Cylinder:Heavy-haul and severe-service segments demand torque density for gradeability with full loads. Mining contractors in Australia and Canada specify these configurations for pit haulage and remote site access.
- 4-Cylinder:Light vocational and urban delivery applications specify compact diesels for maneuverability and fuel economy. European municipal fleets lead adoption for street-sweeper and small refuse body mounting.
- Others:Alternative configurations include inline-five and Wankel rotary hybrids in specialized airport and tunnel service vehicles. Niche applications limit production scale and parts availability.
Procurement concentrates on 6-cylinder architectures; electrification pressures are accelerating fastest among 4-cylinder segments.
Transmission Type:
Driver availability constraints and duty cycle efficiency are restructuring gearbox specification across fleet replacement schedules.
- Automatic:Allison and Eaton fully automatic units eliminate clutch operation for expanded driver pools. Waste management fleets in California and Germany specify these configurations to reduce recruitment barriers and training costs.
- Manual:Direct-drive mechanical reliability persists in owner-operator construction segments where capital constraints favor lower acquisition cost. Severe-service mining applications in South Africa and Brazil retain preference for driver-controlled gear selection.
- Semi-Automatic:Automated manual transmissions merge fuel efficiency with reduced operator fatigue. Regional delivery contractors in the United States specify Eaton Cummins Endurant units for highway-urban mixed routes.
- Continuous Variable:Hydrostatic and power-split architectures optimize engine speed for refuse packer and sweeper hydraulic demands. High cost and maintenance complexity limit adoption to municipal fleet specifications with captive service depots.
Manual transmissions retain volume leadership; automatic configurations are climbing the fastest.
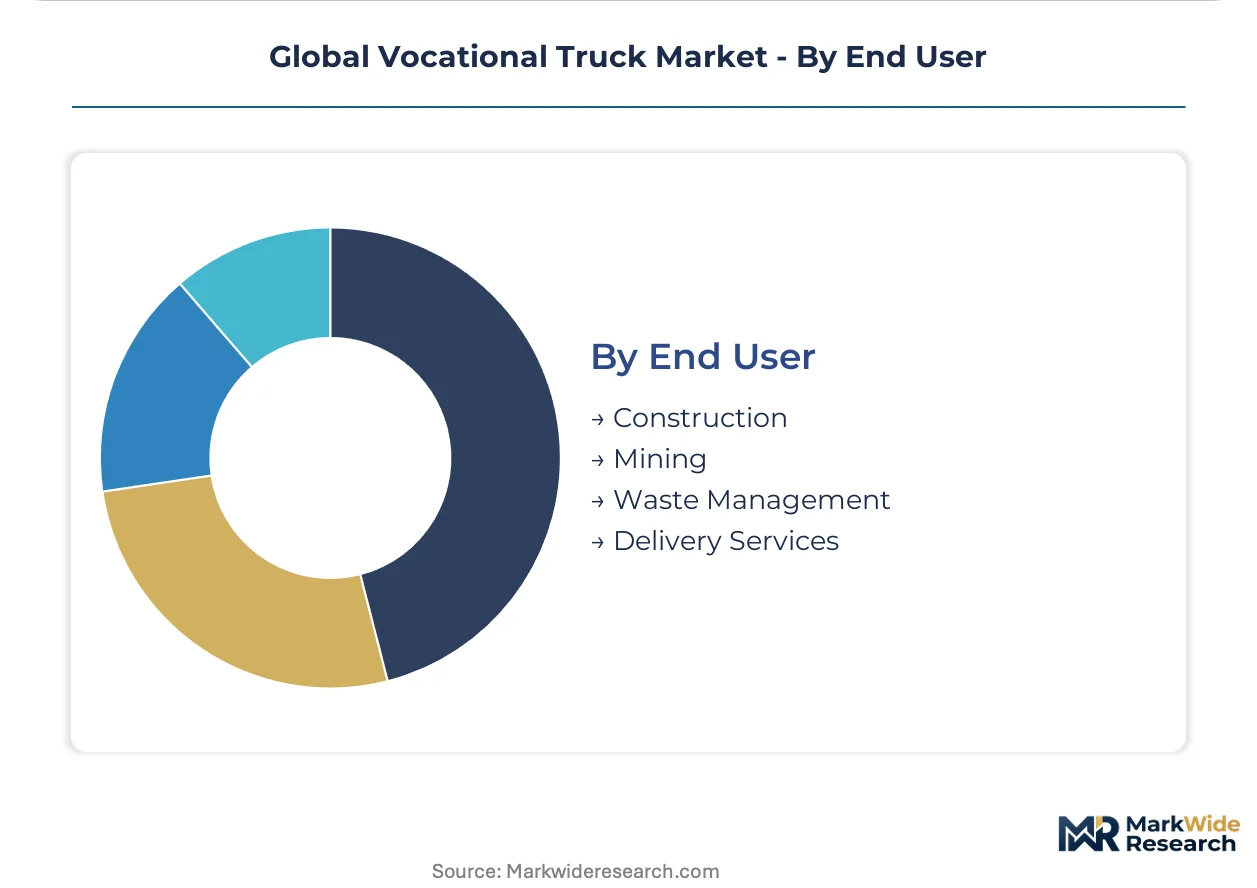
End User:
Regulatory exposure and fleet scale differentiate procurement behavior between capital-intensive extractive industries and municipal service operations.
- Construction:Contractor credit constraints and project-based demand volatility favor rental and lease structures over ownership. United States infrastructure spending programs are accelerating severe-service chassis replacement timelines.
- Waste Management:Zero-emission mandates in California, Germany, and China's coastal provinces are forcing battery-electric platform adoption. Refuse packer body integration with electric PTO systems demands redesigned chassis architecture.
- Mining:Remote site operation and payload maximization prioritize mechanical simplicity and field serviceability. Australian and Canadian open-pit operators specify highest GVWR ratings with minimal electronics exposure.
- Delivery Services:Urban route density and curb access requirements favor low-cab-forward configurations with tight turning radii. Last-mile operators specify automatic transmissions to minimize driver qualification barriers.
Construction commands current volume; waste management shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany, the United States, and Japan, while consumption gravitates toward infrastructure investment corridors in China, India, and the United States. Regulatory divergence between EPA Phase 3, Euro VII, and China's MIIT standards fragments certification requirements across major markets.
United States
Infrastructure spending authorized under federal highway programs accelerates dump truck and concrete mixer procurement. EPA Phase 3 greenhouse gas standards compress engine development timelines for Class 8 severe-service chassis. Manufacturing clusters in Michigan and Ohio anchor Daimler and PACCAR assembly operations serving North American contractor fleets.
Germany
Euro VII emission frameworks mandate real-world emissions monitoring through onboard sensors and telematics reporting. The EU Green Deal commercial vehicle incentives compress electric total cost of ownership gaps for municipal waste collection contracts. Baden-Württemberg and Bavaria host Volvo Group and MAN SE engineering centers developing low-cab-forward platforms for European urban applications.
China
National highway expansion and smart city initiatives generate demand for tipper trucks and transit mixers. MIIT fuel consumption regulations force engine downsizing and hybridization investments across OEM development budgets. Yangtze River Delta manufacturing corridors concentrate chassis assembly capacity serving domestic infrastructure build-out and Belt and Road export markets.
India
National highway expansion and urban sanitation programs create demand for severe-service chassis with integrated power take-off systems. Domestic chassis assemblers lack engineering depth for mining and construction duty cycles. Maharashtra and Gujarat industrial corridors attract joint venture investments from Japanese and European OEMs seeking local production footholds.
Japan
Isuzu Motors and Hino Motors anchor keiretsu supply networks for light and medium vocational platforms across Asia-Pacific export markets. METI carbon neutrality roadmaps accelerate hybrid powertrain development for urban delivery and refuse applications. Kanto and Chubu manufacturing regions concentrate transmission and axle component production for regional OEM supply.
Global Vocational Truck Market Competitive Environment
Top-tier vendors anchor premium severe-service segments, while mid-tier assemblers compete on price-sensitive municipal and light vocational applications. The vendor base stratifies across three archetypes: integrated global OEMs with captive powertrain and certification resources, regional specialists with body-builder integration expertise, and emerging electric-native challengers with modular platform architectures. Competitive moves concentrate on strategic partnerships for zero-emission powertrain sourcing and geographic expansion through local assembly joint ventures.
Among integrated global OEMs, Daimler Truck AG, Volvo Group, and PACCAR Inc exemplify scale-driven competitive positioning. Daimler leverages its North American manufacturing footprint to dominate severe-service segments requiring reinforced frame rails and integrated power take-off systems. Volvo anchors European municipal and waste collection contracts through dedicated low-cab-forward platforms with established body-builder certification networks. PACCAR competes in premium over-the-road derivatives repurposed for vocational duty cycles, occupying a position that bridges highway efficiency with construction-site durability requirements.
| Leading Market Players |
|---|
| Daimler Truck AG |
| Volvo Group |
| PACCAR Inc |
| Isuzu Motors Ltd |
| Hino Motors Ltd |
| Navistar International Corporation |
| Mitsubishi Fuso Truck and Bus Corporation |
| Scania AB |
| MAN SE |
| Others |
Value Chain & Pricing Dynamics
Captive powertrain production by integrated OEMs anchors both supply security and pricing power across severe-service chassis segments. Daimler Truck AG and Volvo Group leverage in-house engine certification resources to command premiums for EPA Phase 3 and Euro VII compliant platforms while mid-tier assemblers absorb margin compression from outsourced component sourcing.
Pricing Analysis
Lead-time premiums for short-cycle chassis delivery separate urgent-replacement procurement from scheduled fleet renewals. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier, after-sales service bundling, and geographic delivery cost. Cost compression in mid-tier municipal segments intensifies because domestic assemblers lack captive regulatory affairs teams. Small contractor fleets exhibit highest price sensitivity; mining operators with uptime-guaranteed maintenance contracts show lowest.
Supply Chain Analysis
Refurbished powertrain cores and remanufactured axle assemblies flow back through dealer networks to extend component life cycles and buffer new-part shortages. Manufacturing concentrates in Germany, the United States, and Japan. Frame rail tensile steel, aftertreatment catalyst substrates, and automated transmission control modules constitute critical input dependencies. Single-source vulnerability for specialized hydraulic PTO systems from Italian and German suppliers threatens chassis-body integration timelines. Distribution runs through OEM-owned dealer networks with body-builder certification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
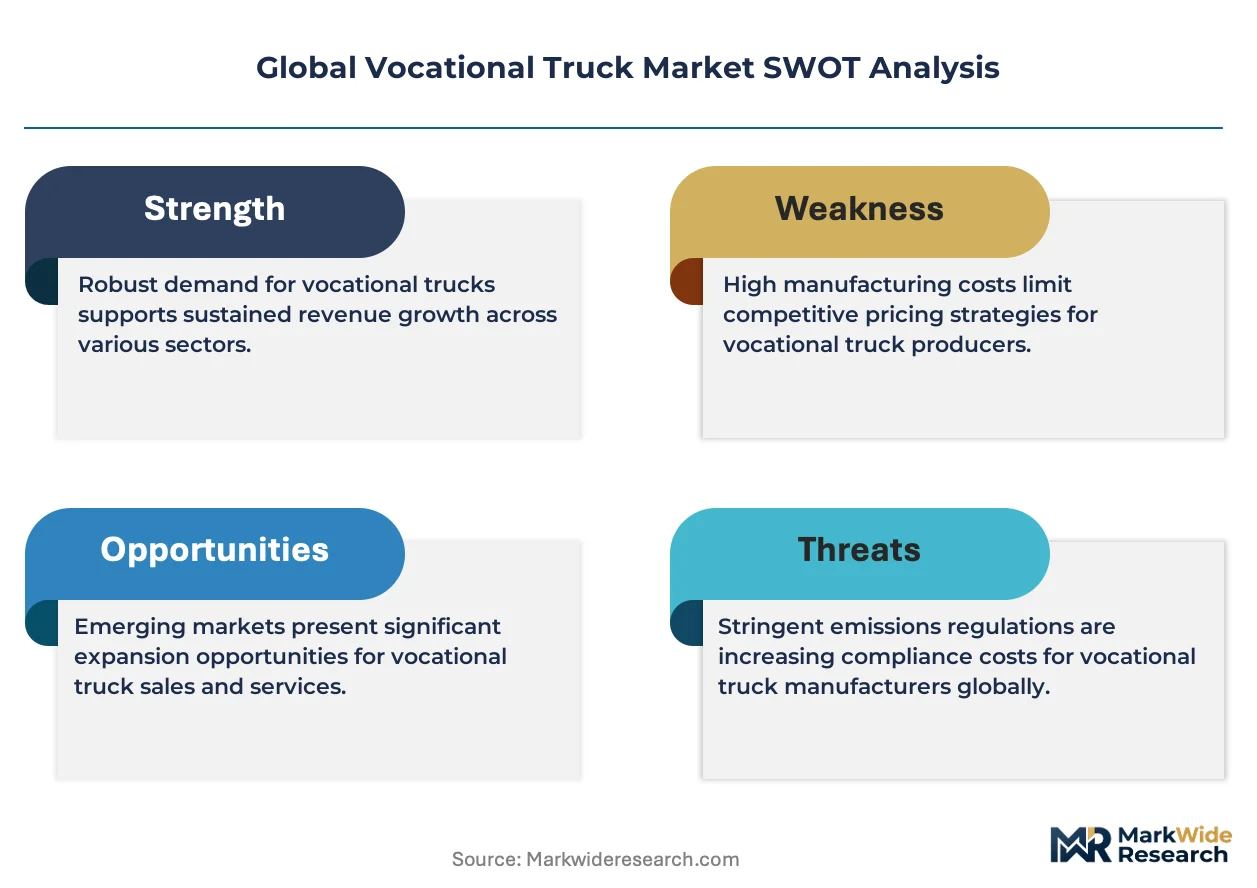
This market operates as a cost-of-compliance story where EPA Phase 3 and Euro VII certification timelines erect barrier-to-entry moats favoring scaled manufacturers with dedicated regulatory affairs infrastructure.
For Market Incumbents: Hedge emission certification concentration risk by expanding captive powertrain production into India and Brazil manufacturing corridors. Acquire specialized body-builder certification networks to lock in municipal waste collection contract specifications ahead of zero-emission mandate deadlines. Battery-electric platform R&D absorbs capital that compression-ignition heritage competitors cannot replicate. For New Entrants and Emerging Players: Begin with electric-native chassis architectures for urban refuse collection in California, Germany, and China's coastal provinces where purchase subsidies compress total cost of ownership gaps. Target mid-sized construction contractors migrating from ownership to full-service leasing models. Partner with established telematics providers to monetize usage-based maintenance contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated global OEMs seeking zero-emission powertrain capabilities and geographic manufacturing footholds. Long-term viability favors targets with established body-builder certification networks and municipal fleet relationships. Monitor California Air Resources Board zero-emission truck mandate enforcement timelines as inflection indicator for electric platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Powertrain Electrification Partnership | Battery supply agreements with CATL or LG Energy Solution secure cell allocation for electric refuse chassis programs. |
| Body-Builder Certification Network Expansion | Exclusive hydraulic PTO integration partnerships with McNeilus and Heil lock in municipal waste collection specifications. |
| Telematics-PTO Convergence Platform | Real-time body equipment monitoring enables uptime-guaranteed maintenance contracts for rental fleet operators. |
| India Manufacturing Joint Venture | Maharashtra and Gujarat production footholds capture national highway expansion tipper truck demand from domestic assemblers. |
| Aftertreatment System Scale-Up | Euro VII urban low-speed duty cycle hardware investments capture refuse collection segment margin pools. |
Study Parameters
Document review covered EPA certification filings, EU type-approval databases, and MIIT fuel consumption disclosures, complemented by interviews with fleet procurement managers, OEM platform engineers, body-builder technical directors, and aftermarket service heads. Secondary validation drew from NHTSA braking standard filings, SEC 10-K powertrain R&D disclosures, and IHS Markit vehicle registration data. Bottom-up chassis shipment tallies triangulated against top-down infrastructure spending allocation models.
Segment-level value outputs across the projection horizon reflect product type, cylinder capacity architecture, transmission configuration, and end-user duty cycle intensity. CAGRs derived from regression against historical infrastructure investment correlations and regulatory compliance cost absorption rates. Electric platform adoption curves incorporated California ZEV mandate enforcement schedules and EU Green Deal subsidy phase-out timelines.
Underlying measurement precision varies by segment; dump truck and tanker truck volumes carry tighter precision than emerging electric refuse chassis categories. Forecasts reflect assumptions on steel input price stabilization and semiconductor availability for transmission control modules. Practitioners should monitor EPA Phase 3 enforcement stringency and Euro VII real-world emissions monitoring implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
Bucket Trucks Market
Heavy-Duty Trucks
United States Refrigerated Trucking Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
Full Truckload Transportation Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
US Tanker Truck Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
High Performance Trucks Market