
 Automotive High Performance Trucks Market | 2026-2036
Automotive High Performance Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive High Performance Trucks Market Outlook
Heavy-duty towing specifications is redrawing competitive boundaries in the Automotive High Performance Trucks segment. Ford Motor Company leverages its Super Duty engineering heritage to anchor fleet loyalty in North American vocational channels. Daimler Truck AG sustains premium positioning through integrated powertrain architectures that span Mercedes-Benz and Freightliner badges. AB Volvo specializes in axle-load optimization for mining and logging configurations across Scandinavian and Brazilian terrains.
Automotive high performance trucks are commercial vehicles engineered for gross combined weight ratings exceeding standard light-duty thresholds, typically employing reinforced frame rails, upgraded cooling systems, and torque-optimized powertrains to sustain continuous operation under severe load cycles. Their primary purpose centers on vocational applications where payload capacity, gradeability, and thermal endurance determine operational uptime and total cost of ownership. Pickup trucks configured for heavy-duty towing generate the deepest margin pools due to retail price elasticity and accessory attach rates. Diesel engines retain structural dominance in long-haul and mining fleets where energy density and refueling infrastructure maturity outweigh electrification timelines. Hybrid engines represent the fastest-expanding engine type as operators in regulated urban corridors seek torque-fill benefits without full infrastructure dependency.
EPA Phase 3 standards, Euro VII frameworks, and China's MIIT fuel consumption regulations are compressing engine development timelines while elevating compliance costs for powertrain suppliers. NHTSA crashworthiness protocols and ECE braking directives further differentiate market access requirements between North American and European certification paths. Stakeholders must calibrate platform investments against divergent regulatory stringency curves rather than assuming convergent global product architectures.
Market Dynamics
EPA Phase 3 greenhouse gas standards and Euro VII emission frameworks are compressing powertrain development cycles while forcing simultaneous investments in diesel optimization and electrification pathways. Fleet operators now demand platform flexibility that accommodates regulatory divergence without full architectural redundancy.
Growth Catalysts
- EPA Phase 3 Standards:US fleet operators are accelerating procurement of compliant heavy-duty towing configurations ahead of 2027 enforcement deadlines. Vocational buyers prioritize thermal endurance specifications that maintain productivity under severe load cycles.
- Mining Sector Expansion:Brazilian and Australian open-pit operations are renewing haul truck fleets with axle-load-optimized configurations. Payload capacity requirements exceed standard commercial vehicle thresholds.
- Hybrid Torque-Fill Architectures:Urban corridor operators in Germany and China are adopting hybrid powertrains to access low-emission zones without full charging infrastructure dependency.
Market Restraints
- Steel and Aluminum Input Volatility:Reinforced frame rail fabrication faces raw material cost swings that compress margin pools on heavy-duty pickup configurations.
- European Powertrain Supplier Concentration:Critical emission control component manufacturing clusters in Germany and Italy create single-source vulnerability for Euro VII compliance hardware.
- Battery Energy Density Limitations:Lithium-ion cell gravimetric performance remains insufficient for mining-grade continuous operation cycles exceeding twelve hours.
Strategic Opportunities
- India Vocational Fleet Underpenetration:Construction and logistics operators in Maharashtra and Gujarat states are transitioning from light-duty imports to localized heavy-duty procurement.
- Carbon Border Adjustment Mechanism:EU importers of high-performance trucks face embedded emission accounting requirements that favor regional manufacturing with verified supply chain decarbonization.
- Telematics-Predictive Maintenance Convergence:Real-time thermal monitoring combined with machine learning uptime forecasting is enabling subscription-based service models for fleet operators.
Industry Challenges
- Powertrain Calibration Talent Scarcity:Engineers capable of optimizing diesel-electric hybrid control algorithms command premium compensation that strains mid-tier supplier R&D budgets.
- Dual Certification Timeline Compression:Simultaneous NHTSA crashworthiness and ECE braking directive validation requires parallel testing streams that extend product launch windows.
- Legacy Fleet Integration Complexity:Telematics retrofits for existing vocational assets face CAN bus protocol fragmentation across 2015-2022 model year installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive High Performance Trucks Market |
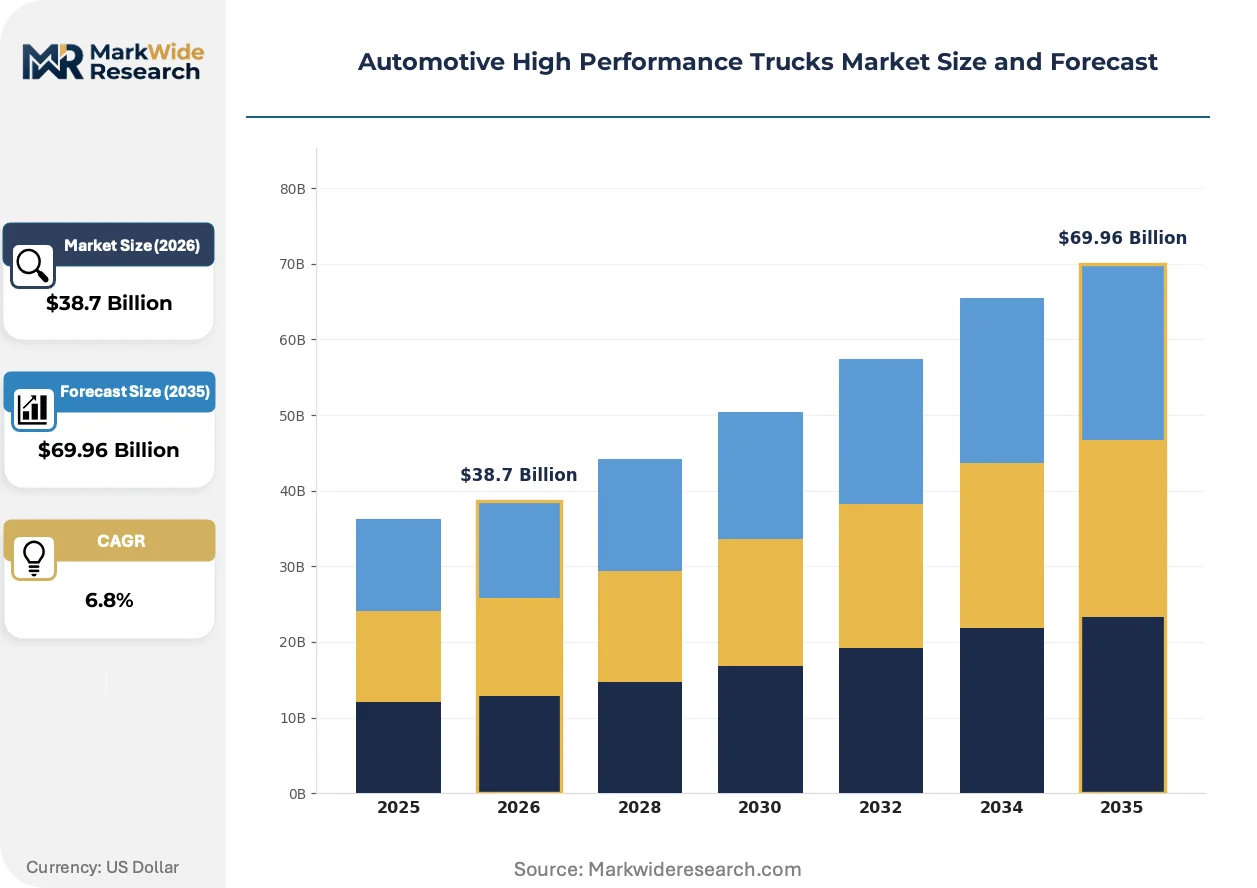
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Pickup Trucks, Flatbed Trucks, Crew Cab Trucks, Chassis Cab Trucks Engine Type: V6 Engines, V8 Engines, Diesel Engines, Hybrid Engines Usage Purpose: Commercial Use, Off-Road Enthusiasts, Heavy Duty Towing, Daily Commute Fuel Type: Gasoline, Diesel, Compressed Natural Gas, Electric |
| Companies Covered | Ford Motor Company, General Motors, AB Volvo, Daimler Truck AG, PACCAR Inc, MAN SE, Scania AB, Tesla, Inc., Toyota Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive High Performance Trucks Market Strategic Shifts
Powertrain electrification is fragmenting along duty-cycle boundaries rather than following a uniform transition timeline. Thermal management innovation and software-defined vehicle architectures are emerging as parallel competitive vectors.
High-voltage battery packs with silicon carbide inverters are displacing conventional 48V mild-hybrid systems in heavy-duty towing configurations. North American vocational fleet operators are specifying 800V architectures for accessory power take-off applications. This voltage transition is compressing supplier qualification timelines for cooling system component manufacturers.
Euro VII emission frameworks are mandating real-world driving emission monitoring with on-board portable measurement systems. Powertrain engineers must now calibrate engine maps for variable load conditions rather than standardized test cycles. German and Swedish manufacturers are responding with dual-mapping strategies that switch between certification and operational modes based on geofencing inputs.
Fleet procurement departments are consolidating specification authority previously dispersed across regional maintenance managers. Large construction and mining operators in the United States and Australia now centralize powertrain platform decisions at corporate engineering levels. This concentration is marginalizing dealer channel configuration influence and shifting volume toward direct OEM fleet agreements.
Automotive High Performance Trucks Market Segmentation
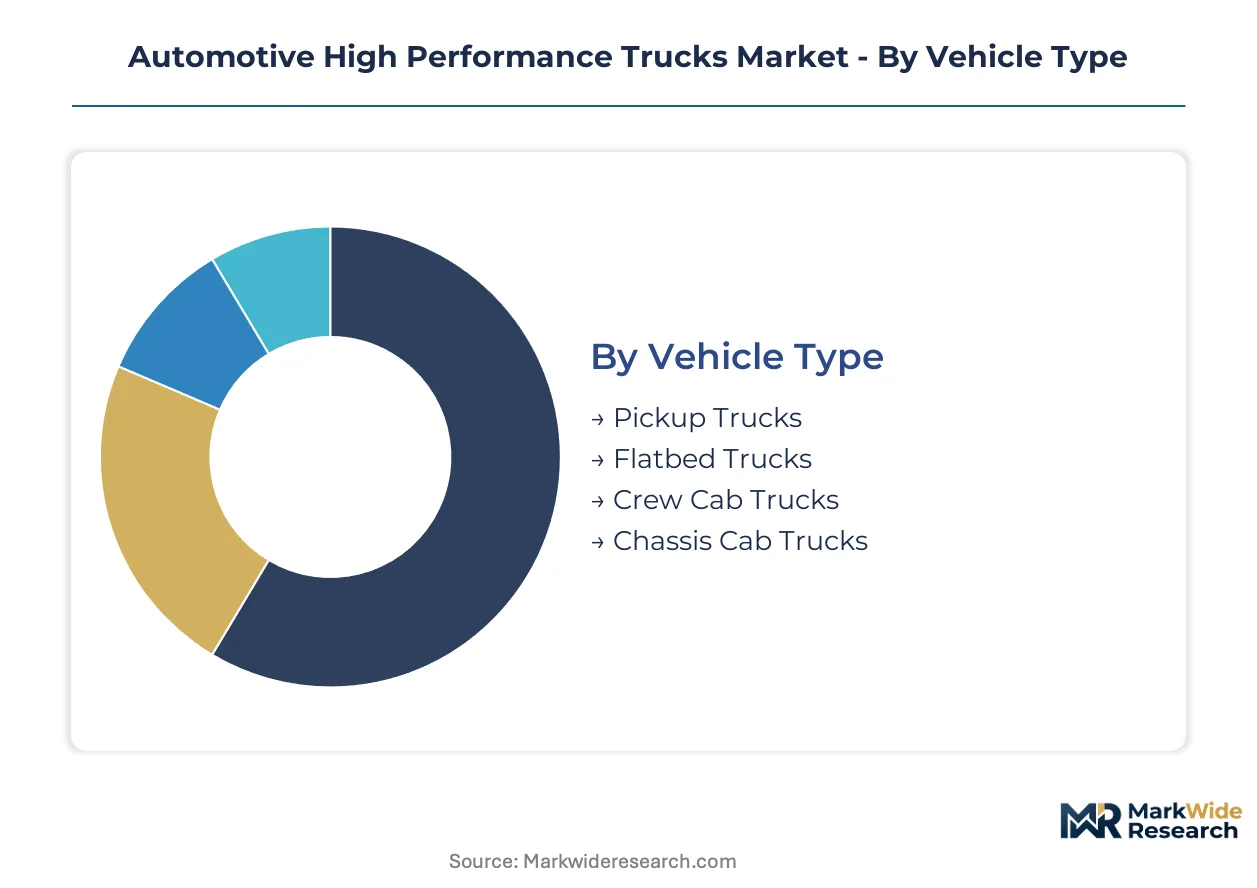
Segmentation in automotive high performance trucks determines specification authority, procurement channel influence, and aftermarket revenue attachment. Fleet buyers, retail consumers, and vocational operators each trigger distinct configuration requirements across powertrain, cab architecture, and towing capacity dimensions.
Vehicle Type:
Pickup trucks flow predominantly through franchised dealer networks with heavy accessory attach rates, while chassis cab configurations concentrate in direct OEM fleet agreements with upfitter integration.
- Pickup Trucks:These configurations employ reinforced frame rails and upgraded cooling systems to sustain gross combined weight ratings exceeding standard light-duty thresholds. Demand concentrates in the United States where retail price elasticity supports premium trim penetration and dealer channel accessory bundling.
- Crew Cab Trucks:Dual-row seating architectures dominate mining and logging fleet specifications across Brazilian and Australian terrains where operator transport efficiency determines shift productivity. Payload capacity requirements in these applications exceed conventional commercial vehicle thresholds.
- Flatbed Trucks:Open-deck configurations serve construction logistics with material handling flexibility.
- Chassis Cab Trucks:Incomplete vehicle platforms route through specialized upfitters for vocational body installation.
Pickup trucks dominate installed base. Chassis cab trucks are where expansion concentrates.
Engine Type:
Powertrain selection stratifies across customer type, with diesel retention in long-haul mining fleets and hybrid architectures gaining share fastest in regulated urban corridors.
- Diesel Engines:Compression-ignition architectures deliver energy density and thermal endurance for continuous operation cycles exceeding twelve hours. Mining operators in Australia and Brazil specify these powertrains where refueling infrastructure maturity outweighs electrification timelines.
- Hybrid Engines:Torque-fill architectures combine electric motor assistance with combustion baseload to access low-emission zones without full charging infrastructure dependency. German and Chinese fleet operators in regulated urban corridors are adopting these configurations most aggressively.
- V6 Engines:Six-cylinder gasoline architectures balance fuel efficiency with moderate towing capacity for light-commercial applications.
- V8 Engines:Large-displacement gasoline powertrains serve retail performance-oriented buyers in North American markets.
Diesel engines dominate installed base. Hybrid engines are where expansion concentrates.
Usage Purpose:
Application segmentation determines margin structure, with heavy duty towing generating deepest margin pools through price elasticity and commercial use concentrating volume through fleet procurement centralization.
- Heavy Duty Towing:Configurations specify upgraded cooling systems, reinforced hitches, and torque-optimized powertrains to sustain severe load cycles. United States fleet operators prioritize thermal endurance specifications that maintain productivity under continuous operation.
- Commercial Use:Vocational applications center on payload capacity and gradeability for operational uptime in construction and logistics. Large United States and Australian operators now centralize powertrain platform decisions at corporate engineering levels, shifting volume toward direct OEM agreements.
- Off-Road Enthusiasts:Recreational buyers prioritize axle articulation and traction systems for terrain capability.
- Daily Commute:Light-duty utilization patterns emphasize cab comfort and fuel efficiency over maximum towing capacity.
Commercial use dominates installed base. Heavy duty towing is where expansion concentrates.
Fuel Type:
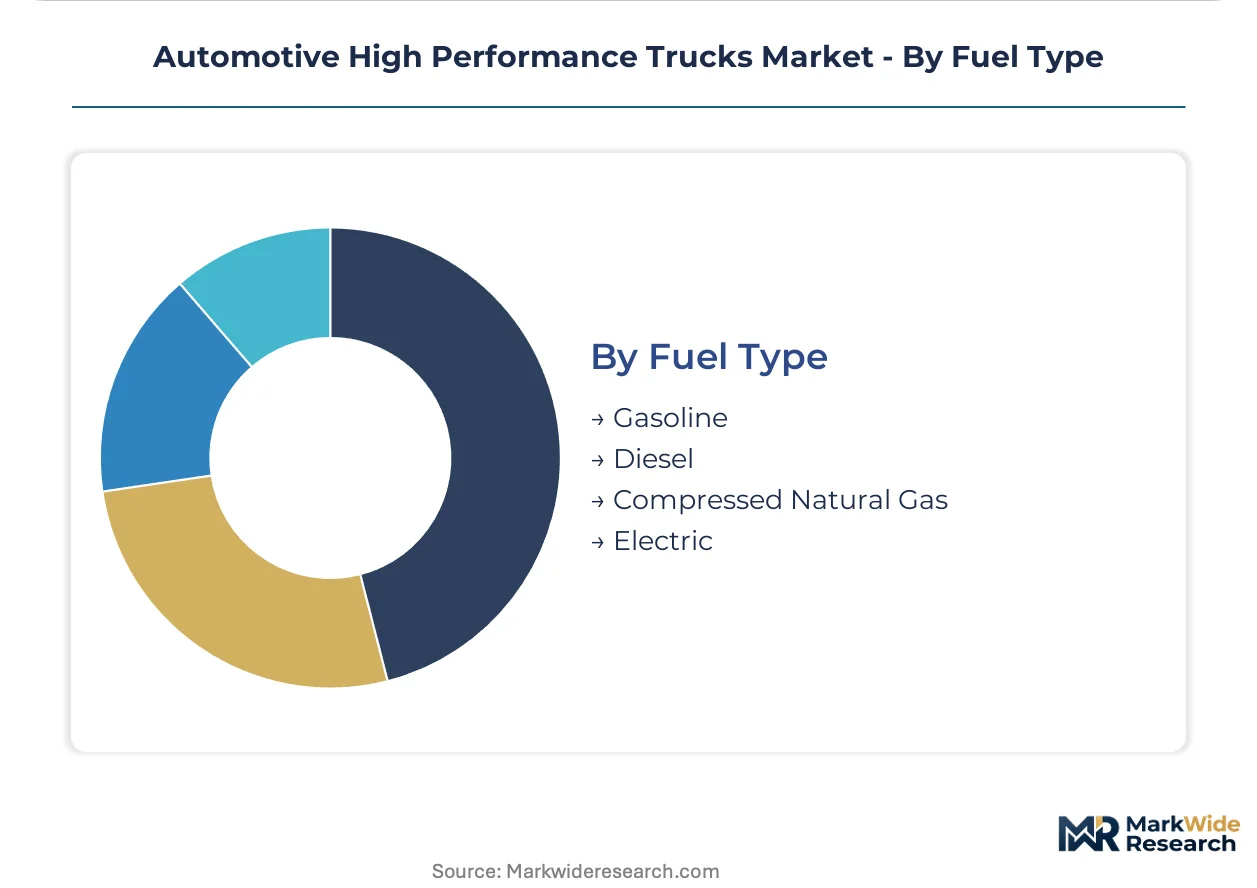
Energy source selection fragments along duty-cycle boundaries, with diesel retaining structural dominance in mining and electric architectures constrained by battery energy density limitations for continuous operation.
- Diesel:Distillate fuel architectures retain structural dominance in long-haul and mining fleets where energy density and refueling infrastructure maturity outweigh electrification timelines. EPA Phase 3 and Euro VII frameworks are compressing development cycles for optimization of these powertrains.
- Electric:Battery-electric configurations face lithium-ion cell gravimetric performance constraints for mining-grade continuous operation cycles exceeding twelve hours. High-voltage architectures with silicon carbide inverters are displacing mild-hybrid systems in heavy-duty towing specifications where 800V systems support accessory power take-off applications.
- Gasoline:Spark-ignition fuels serve retail and light-commercial applications with lower upfront powertrain cost.
- Compressed Natural Gas:Gaseous fuel architectures serve fleet operators with captive refueling infrastructure and emission reduction mandates.
Diesel dominates installed base. Electric is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail buyers in the United States demonstrate the highest price elasticity for premium trim configurations, while mining fleet operators in Australia and Brazil prioritize thermal endurance specifications over upfront cost compression.
United States
Vocational fleet operators are accelerating procurement of EPA Phase 3 compliant heavy-duty towing configurations ahead of enforcement timelines. NHTSA crashworthiness protocols differentiate certification requirements from European pathways. Detroit-based engineering clusters anchor powertrain development for Super Duty architectures serving construction and logistics channels.
Germany
Urban corridor operators are adopting hybrid torque-fill architectures to access low-emission zones without full charging infrastructure dependency. Euro VII emission frameworks mandate real-world driving emission monitoring with on-board portable measurement systems. Stuttgart and Munich manufacturing clusters concentrate integrated powertrain development spanning Mercedes-Benz and Freightliner badge engineering.
China
Construction and mining operators in regulated provinces are specifying high-voltage 800V architectures for accessory power take-off applications. MIIT fuel consumption regulations compress development cycles for domestic powertrain suppliers. Yangtze River Delta industrial corridors host silicon carbide inverter qualification programs for heavy-duty towing specifications.
Brazil
Open-pit mining operations are renewing haul truck fleets with axle-load-optimized configurations exceeding standard commercial vehicle thresholds. ANVISA and environmental licensing frameworks govern operational fleet standards in extractive sectors. Minas Gerais and Pará state mining corridors concentrate demand for crew cab architectures serving shift productivity requirements.
Australia
Large construction and mining operators centralize powertrain platform decisions at corporate engineering levels, shifting volume toward direct OEM agreements. State-level vehicle safety standards complement federal Australian Design Rules for heavy vehicle compliance. Western Australia Pilbara region anchors demand for diesel-dominant continuous operation cycles exceeding twelve hours.
Automotive High Performance Trucks Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated powertrain specialists commanding premium positioning while volume manufacturers optimize platform flexibility across regulatory jurisdictions. The market structure concentrates around legacy automotive conglomerates with vocational heritage and emerging electrification entrants challenging thermal management specifications. Three archetypes dominate: heritage truck manufacturers with frame rail engineering depth, integrated automotive groups with badge-engineered platform strategies, and battery-electric specialists targeting voltage architecture transitions. M&A activity centers on telematics-predictive maintenance convergence, while capacity expansion concentrates in regional manufacturing clusters serving carbon border adjustment compliance.
Among North American heritage manufacturers, Ford Motor Company and General Motors occupy positions anchored by Super Duty engineering lineage and dealer channel accessory bundling. Daimler Truck AG represents the integrated automotive group archetype, spanning Mercedes-Benz and Freightliner powertrain architectures. These three exemplify divergent strategic responses to EPA Phase 3 and Euro VII timeline compression.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors |
| AB Volvo |
| Daimler Truck AG |
| PACCAR Inc |
| MAN SE |
| Scania AB |
| Tesla, Inc. |
| Toyota Motor Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for silicon carbide inverters and high-grade steel lock in supply access and price visibility for OEMs navigating EPA Phase 3 and Euro VII compliance timelines. These contractual structures insulate fleet procurement departments from raw material volatility while compressing supplier qualification windows.
Pricing Analysis
EPA Phase 3 standards dictate the pricing tier structure across heavy-duty towing configurations, with compliance-grade powertrains commanding premium positioning over baseline architectures. Three-tier pricing structure across premium, standard, and economy levels separates thermal-endurance specifications from moderate-duty alternatives. Cost compression in reinforced frame rail fabrication is intensifying because steel and aluminum input volatility erodes margin pools on pickup configurations. Vocational fleet operators demonstrate lowest price sensitivity due to total cost of ownership calculations, while light-commercial buyers prioritize upfront acquisition cost.
Supply Chain Analysis
Germany and China anchor integrated powertrain manufacturing for emission control hardware and high-voltage battery architectures. Production draws from lithium-ion cell suppliers in South Korea and Japan for 800V system components. Single-source vulnerability clusters in Italian and German emission control component manufacturing create compliance risk for Euro VII hardware. Distribution runs through direct OEM fleet agreements that bypass dealer channel configuration influence for chassis cab configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification fragments along duty-cycle boundaries, creating specialization niches for suppliers capable of optimizing thermal management or software-defined vehicle architectures without full platform redundancy.
For Market Incumbents: Fortify integrated powertrain architectures through backward integration into silicon carbide inverter production and captive supply of reinforced frame rail capacity. Battery-electric specialists threaten premium positioning in heavy-duty towing segments where voltage architecture transitions accelerate. Certification investment in dual NHTSA-ECE validation streams preserves market access across regulatory jurisdictions. For New Entrants and Emerging Players: Lead with telematics-predictive maintenance convergence targeting mid-tier construction fleets in Maharashtra and Gujarat states where vocational fleet underpenetration creates white-space opportunity. India vocational procurement transitions from light-duty imports to localized heavy-duty specifications. Go-to-market through subscription-based uptime forecasting models bypasses capital-intensive manufacturing entry barriers. For Investors and Strategic Acquirers: Thermal management engineering boutiques with mining-sector calibration heritage represent priority acquisition targets for electrification timeline compression exposure. Long-term viability hinges on capability depth in severe load cycle optimization rather than commodity battery pack assembly. Watch for carbon border adjustment mechanism enforcement triggering regional manufacturing footprint reconfiguration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell capacity for 800V heavy-duty towing architectures from South Korean suppliers. |
| Software-Defined Vehicle Investment | Enables real-time thermal monitoring and predictive maintenance subscription models for fleet operators. |
| Backward Integration into Inverters | Captures silicon carbide component margin and compresses supplier qualification timelines for OEMs. |
| Geographic Manufacturing Footprint | Positions production within EU carbon border adjustment compliance zones for verified supply chain decarbonization. |
| Charging Infrastructure Partnership | Supports 800V accessory power take-off applications in North American vocational fleet specifications. |
Study Parameters
Desk research of vehicle production databases, EPA certification filings, and IHS Markit registration data preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet operations managers across construction and mining sectors. Primary fieldwork with vocational fleet buyers in the United States, Germany, and Brazil validated secondary estimates of powertrain platform adoption. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Variance decomposition across vehicle type, engine architecture, fuel category, and regional regulatory cluster shaped analytical framework construction over the projection horizon. CAGRs derived from logistic diffusion curves for electrification penetration and replacement cycle dynamics for diesel retention in mining applications. Modeled inputs incorporated MIIT fuel consumption trajectory assumptions and Euro VII enforcement probability weightings.
Forecasts assume regulatory continuity in EPA Phase 3, Euro VII, and China's MIIT frameworks; material policy shifts would require re-modeling compliance cost trajectories and powertrain platform investment returns. Recalibration cycles align with material shifts in battery energy density benchmarks and carbon border adjustment enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Truck Bedliner Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
High Performance Trucks Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
Garbage Collection Trucks Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Utility Trucks Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Fire Trucks Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Stacker Truck Market