
 Global Snow Sweeper Truck Market | 2026-2036
Global Snow Sweeper Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Global Snow Sweeper Truck Market Analysis
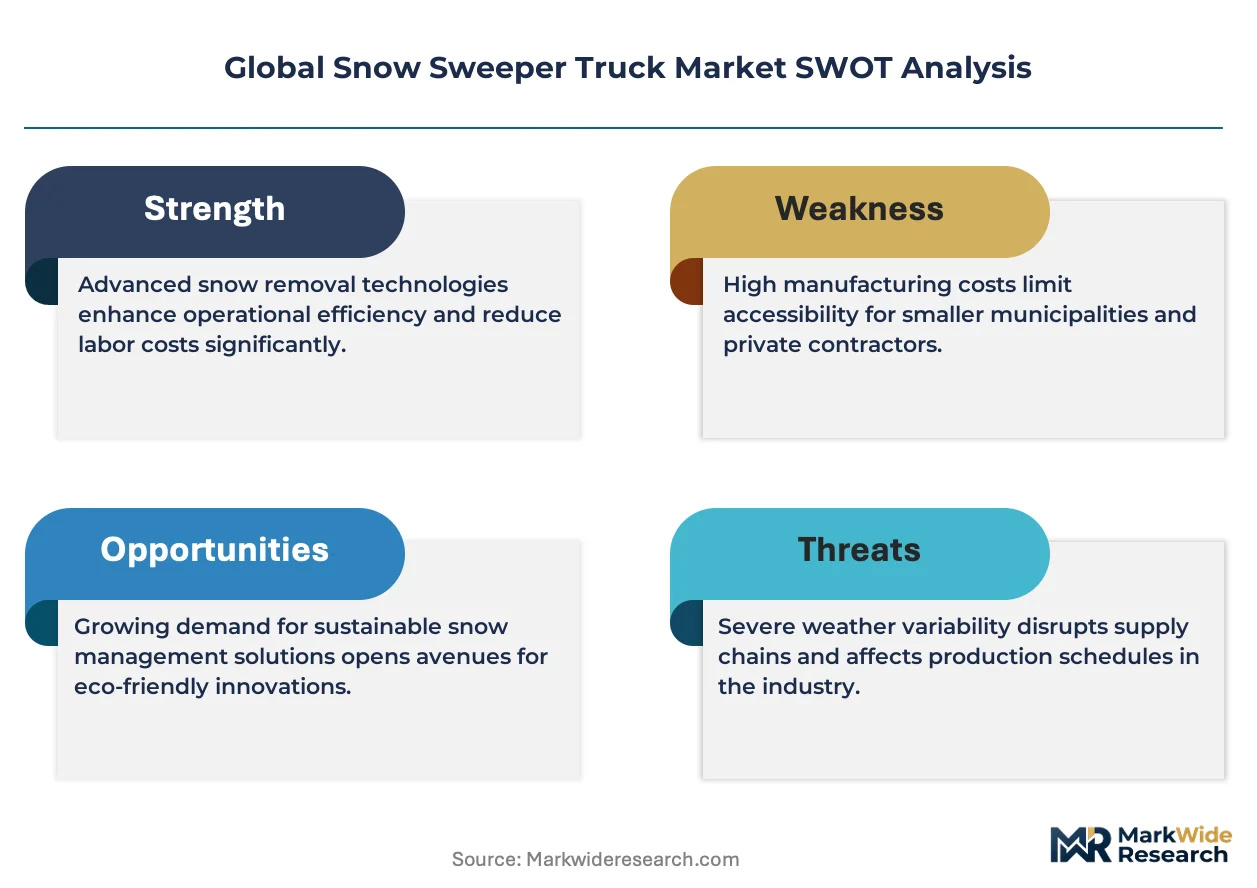
Telematics-enabled fleet management subscription services is repositioning how municipal buyers procure snow sweeper trucks, shifting capital expenditure toward operational expenditure models. Bucher Municipal leverages its European service network to sustain aftermarket revenue streams across Scandinavian contracts. Douglas Dynamics anchors North American distribution through captive dealer channels for private contractor segments. Boschung Group specializes in airport-grade multi-purpose vehicles with precision guidance systems.
Snow sweeper trucks combine reinforced chassis platforms with front-mounted rotary brooms, high-capacity auger-fed plow blades, and liquid de-icing distribution systems rated for sub-zero operational temperatures, purpose-built for continuous removal of accumulated precipitation from paved surfaces. Heavy-duty trucks dominate municipal highway contracts where blade widths exceed 3.5 meters and engine power ratings surpass 300 kW, while compact trucks capture fastest growth in constrained urban cores and pedestrian-zone clearing where maneuverability outweighs throughput capacity. Electric drive technology segments command premium positioning despite limited range in extreme cold, as facility management end users prioritize indoor air quality and noise ordinances over all-day runtime.
EPA Phase 3 greenhouse gas standards for heavy-duty vehicles and EU F-Gas Regulation on mobile air conditioning refrigerants constrain powertrain and cab climate system configurations available to manufacturers. NHTSA vehicle classification rules and CE marking under EU machinery directives shape market access thresholds for imported chassis and mounted equipment. Stakeholders must monitor battery thermal management breakthroughs and hydrogen fuel cell retrofit viability for extended-route rural deployment.
Market Dynamics
Telematics-enabled subscription procurement is compressing traditional equipment ownership cycles across municipal fleets, forcing manufacturers to restructure revenue recognition around recurring service streams rather than discrete chassis sales.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:Heavy-duty emissions mandates in the United States are accelerating powertrain electrification programs among state highway authorities seeking fleet compliance pathways.
- Airport precision guidance requirements:ICAO surface condition reporting protocols are mandating sensor-integrated sweeper fleets for Category III landing zone maintenance.
- Scandinavian fleet modernization:Swedish and Norwegian municipal procurement authorities are retiring legacy mechanical-drive units under accelerated replacement schedules.
Market Restraints
- Battery thermal management limitations:Lithium-ion chemistry performance degradation below minus twenty degrees Celsius constrains electric chassis deployment in subarctic highway routes.
- Steel and aluminum input volatility:Reinforced blade and chassis fabrication costs fluctuate with commodity exchange pricing, compressing OEM margin stability.
- EU F-Gas Regulation compliance:Mobile air conditioning refrigerant phase-down requirements are forcing costly cab climate system redesigns for CE-marked equipment.
Strategic Opportunities
- Canadian provincial highway outsourcing:British Columbia and Alberta maintenance authorities are expanding performance-based contractor agreements for rural route clearing.
- Hydrogen fuel cell retrofits:Extended-range rural deployment is opening for fuel cell range-extender integration with existing diesel chassis platforms.
- Indoor facility management electrification:Noise ordinance enforcement in German and Swiss urban centers is creating demand for zero-emission compact sweepers in logistics terminals.
Industry Challenges
- Mechatronics technician scarcity:Electric drivetrain and telematics system maintenance requires skill sets absent from traditional diesel mechanic training pipelines.
- CE marking and NHTSA dual certification:Chassis and mounted equipment manufacturers face divergent testing protocols for transatlantic product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Snow Sweeper Truck Market |
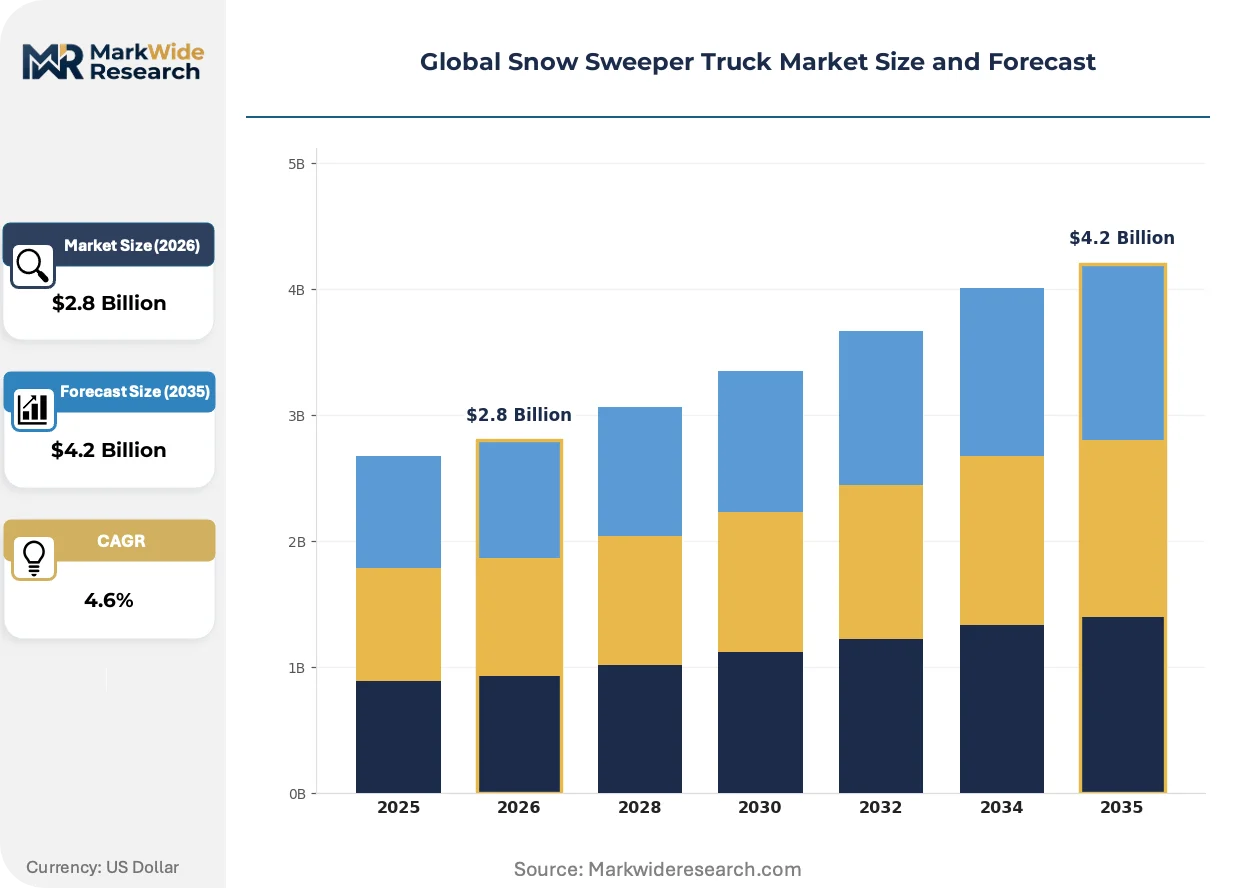
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Trucks, Heavy-Duty Trucks, Multi-Purpose Vehicles, Custom Units Application: Municipal Services, Airports, Parking Lots, Road Maintenance End User: Government Agencies, Private Contractors, Facility Management, Industrial Clients Technology: Automated Steering, Hydraulic Systems, Electric Drive, Hybrid Technology |
| Companies Covered | Bucher Municipal, Alamo Group, Dulevo International, M-B Companies, Boschung Group, Douglas Dynamics, ASH Group, Kahlbacher Machinery, Tennant Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Snow Sweeper Truck Market Emerging Trajectories
Equipment intelligence and powertrain electrification are converging to redefine operational economics across winter maintenance fleets, with sensor fusion and predictive analytics displacing reactive scheduling paradigms.
Autonomous guidance systems with centimeter-precision GNSS correction are consolidating operational control in airport and highway applications. Scandinavian municipal operators are deploying these platforms for lane-accurate de-icing distribution at speeds exceeding sixty kilometers per hour. The technology is consolidating route efficiency benchmarks by eliminating overlap waste and reducing liquid chemical consumption per lane-kilometer.
EU Green Deal decarbonization mandates are binding member state procurement specifications to lifecycle carbon accounting. Municipal tender documents now require embodied carbon declarations for chassis and mounted equipment combinations. German and Austrian highway authorities are weighting carbon intensity scores at fifteen percent of total evaluation criteria, disadvantaging conventional diesel powertrains.
Performance-based service agreements are displacing capital purchase models among Canadian provincial maintenance contractors. British Columbia and Quebec authorities now contract snow-free lane availability rather than equipment hours, transferring utilization risk to fleet operators. This restructuring concentrates contract awards with vertically integrated service providers capable of guaranteeing uptime through captive maintenance infrastructure.
Global Snow Sweeper Truck Market Segmentation
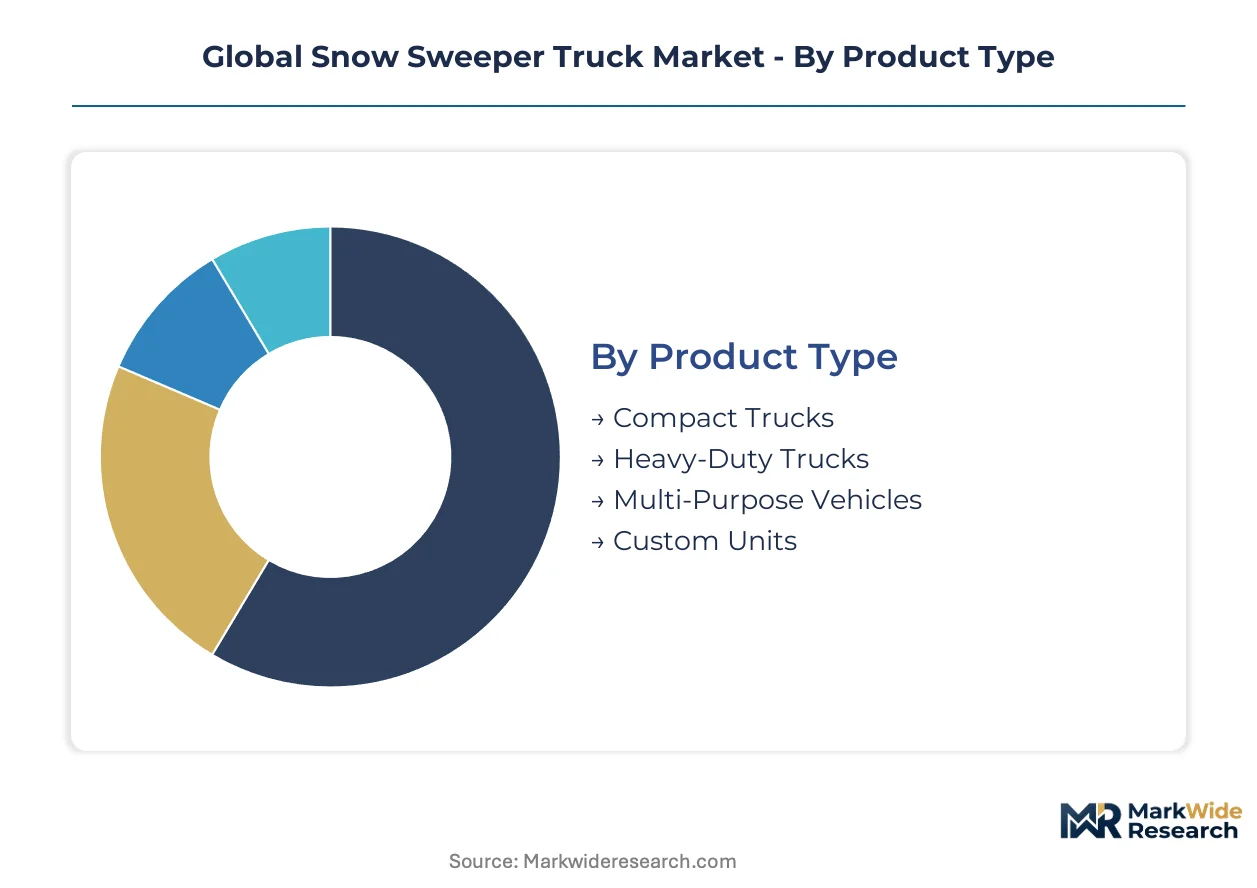
Segmentation in snow sweeper trucks separates chassis capabilities from operational environments, exposing where electrification investments concentrate and which procurement channels command premium pricing. Product architecture and powertrain choices diverge sharply between highway contractors requiring continuous runtime and urban facility managers prioritizing emissions compliance.
Product Type:
Supply concentration in chassis fabrication favors established OEMs with captive stamping and welding capacity, while specialized superstructure mounting fragments across regional equipment builders.
- Heavy-Duty Trucks:Reinforced frame rails and tandem axle configurations support blade widths exceeding 3.5 meters and engine ratings above 300 kW. Provincial highway authorities in Canada and state departments of transportation in the United States specify these units for interstate corridor maintenance where continuous operation across twelve-hour shifts is mandatory.
- Compact Trucks:Single-axle designs with sub-7.5-tonne gross vehicle weight ratings enable maneuverability in pedestrian zones, parking structures, and logistics terminals. German municipal procurement in Bavaria and Baden-Württemberg is expanding fastest here, driven by urban noise ordinances and indoor air quality mandates in freight hubs.
- Multi-Purpose Vehicles:Modular quick-attach systems permit rotary broom, plow blade, and liquid de-icing module interchange within fifteen minutes. Airport authorities in Switzerland and Austria specify these for year-round airfield maintenance.
- Custom Units:Purpose-built configurations for mining operations, railway yards, and military installations incorporate armor plating and extreme cold-start packages. Arctic extraction facilities in Norway and Russia represent concentrated demand.
Today's leader: Heavy-Duty Trucks. Tomorrow's challenger: Compact Trucks.
Application:
Cost tier separation between infrastructure-scale contracts and localized service agreements determines equipment specification intensity and aftermarket attachment rates.
- Municipal Services:City and county fleet departments operate standardized specifications with centralized parts warehousing. Swedish Transport Administration contracts specify lifecycle cost scoring that weights fuel consumption and maintenance intervals at thirty percent of award criteria.
- Airports:ICAO Category III landing zone protocols mandate sensor-integrated fleets with centimeter-precision guidance and automated surface condition reporting. Zurich Airport and Oslo Gardermoen have deployed these systems for simultaneous multi-lane clearing operations.
- Parking Lots:Retail and commercial property managers prioritize compact footprint and rapid deployment speed over throughput capacity. Private contractors in Quebec and Ontario dominate this segment through seasonal equipment leasing.
- Road Maintenance:Performance-based contracting in British Columbia and Alberta transfers utilization risk to operators, requiring guaranteed lane availability rather than equipment hours. This restructuring favors vertically integrated service providers with captive maintenance infrastructure.
Volume concentrates in Municipal Services. Margin expansion concentrates in Airports.
End User:
Customer type segmentation reveals divergent procurement rhythms, with government agencies operating multi-year capital cycles and private contractors responding to seasonal demand spikes through rental and lease structures.
- Government Agencies:State and provincial highway departments issue multi-year fleet replacement tenders with domestic content requirements. U.S. Buy America provisions and Canadian provincial preferences constrain eligible suppliers.
- Private Contractors:Performance-based agreements in Canadian provinces and U.S. Midwest states require equipment redundancy and 24-hour response guarantees. These operators maintain higher fleet utilization rates than municipal counterparts.
- Facility Management:Logistics terminals, hospital campuses, and university grounds departments prioritize zero-emission equipment for indoor and noise-sensitive environments. Swiss and German urban centers are expanding fastest here.
- Industrial Clients:Mining, forestry, and energy extraction operations require extreme-duty specifications with arctic-rated cabs and redundant heating systems. Norwegian oilfield services and Russian Siberian operations represent concentrated demand.
Procurement stability favors Government Agencies. Technology adoption speed favors Facility Management.
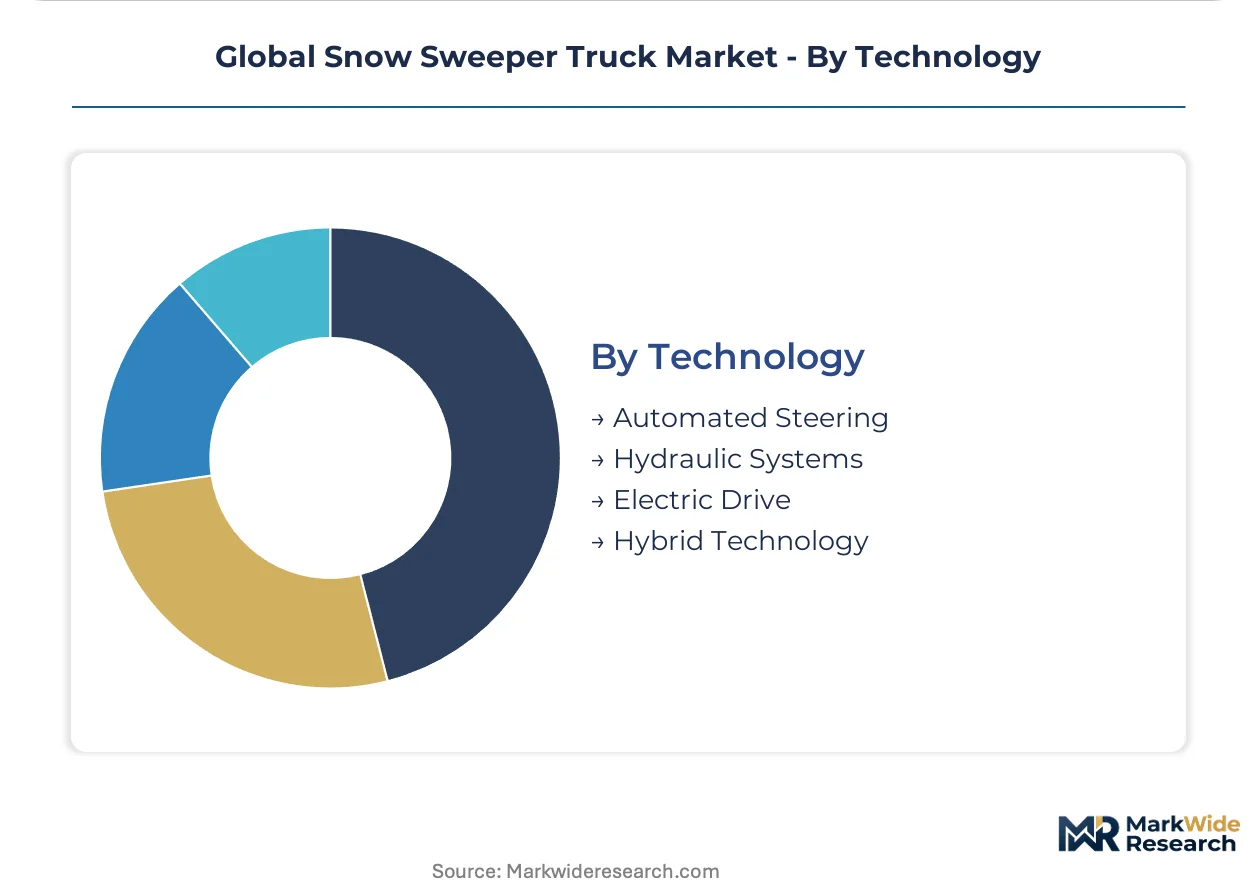
Technology:
Maturity gradients in powertrain electrification separate early-adopter urban applications from range-constrained highway deployment, with hybrid configurations bridging the gap in transitional markets.
- Electric Drive:Battery-electric chassis with liquid-cooled thermal management systems enable four-to-six-hour runtime in moderate cold. Indoor logistics terminals in Germany and airport apron operations in Switzerland are gaining share fastest, though lithium-ion performance degradation below minus twenty degrees Celsius constrains highway adoption.
- Hydraulic Systems:Conventional power take-off configurations dominate heavy-duty municipal highway contracts where blade actuation force and reliability under continuous load outweigh efficiency considerations. Swedish and Finnish fleet modernization programs still specify these for rural route coverage.
- Automated Steering:GNSS-corrected guidance systems with sub-10-centimeter accuracy enable lane-precise de-icing distribution at highway speeds. Scandinavian operators are deploying these for chemical consumption reduction and overlap elimination.
- Hybrid Technology:Diesel-electric range extenders and fuel cell auxiliary power units address electric range limitations in subarctic conditions. Alberta and British Columbia contractors are piloting these for extended rural route coverage.
Deployment scale currently favors Hydraulic Systems. Regulatory tailwinds favor Electric Drive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada commands the largest provincial highway maintenance fleets, while Germany drives compact electric adoption through urban noise ordinances. Municipal procurement patterns diverge sharply between North American performance-based contracting and European lifecycle carbon accounting.
United States
State departments of transportation in Minnesota, Wisconsin, and New York maintain the densest heavy-duty fleets for interstate corridor clearing. EPA Phase 3 greenhouse gas standards are binding procurement specifications to electrification pathways, with California Air Resources Board leading zero-emission mandates. Midwest equipment distributors anchor aftermarket service networks across the Great Lakes snowbelt.
Canada
British Columbia and Alberta highway authorities are expanding performance-based contractor agreements that transfer utilization risk to private operators. Provincial procurement preferences constrain eligible suppliers to domestic assembly or North American content compliance. Quebec municipal fleets are piloting telematics-enabled subscription models for seasonal capacity scaling.
Germany
Bavaria and Baden-Württemberg municipal procurement is expanding fastest in compact electric sweepers for logistics terminal and pedestrian zone applications. EU Green Deal decarbonization mandates weight lifecycle carbon intensity at fifteen percent of tender evaluation criteria. Stuttgart and Munich facility managers prioritize zero-emission equipment for indoor air quality compliance.
Sweden
Swedish Transport Administration contracts specify lifecycle cost scoring that weights fuel consumption and maintenance intervals at thirty percent of award criteria. Accelerated fleet modernization programs are retiring legacy mechanical-drive units under compressed replacement schedules. Stockholm and Gothenburg operators deploy GNSS-corrected guidance systems for lane-precise de-icing distribution.
Switzerland
Zurich Airport and Geneva Cointrin have deployed sensor-integrated sweeper fleets for ICAO Category III landing zone maintenance under automated surface condition reporting protocols. Alpine highway cantons specify multi-purpose vehicles with modular quick-attach systems for year-round airfield and mountain pass operations. Swiss urban noise ordinances in Basel and Bern are accelerating compact electric adoption for logistics terminals.
Global Snow Sweeper Truck Market Vendor Landscape
Top-tier vendors anchor municipal highway contracts through captive service networks, while mid-tier fabricators compete on regional customization speed. The vendor base stratifies across three tiers: integrated chassis-superstructure OEMs with captive distribution, specialized superstructure builders sourcing third-party chassis, and regional equipment assemblers serving private contractor segments. Two dominant competitive moves are restructuring revenue recognition around telematics-enabled subscription services and securing dual CE marking and NHTSA certification for transatlantic product launches.
Within the integrated OEM tier, Bucher Municipal and Douglas Dynamics exemplify contrasting geographic anchoring strategies. Boschung Group occupies a position as a precision guidance specialist serving airport-grade applications. Among European fabricators, Dulevo International and Kahlbacher Machinery represent the superstructure-specialist archetype sourcing reinforced chassis from third-party suppliers. Alamo Group sits within the diversified industrial equipment portfolio segment, leveraging cross-product service infrastructure.
| Leading Market Players |
|---|
| Bucher Municipal |
| Alamo Group |
| Dulevo International |
| M-B Companies |
| Boschung Group |
| Douglas Dynamics |
| ASH Group |
| Kahlbacher Machinery |
| Tennant Company |
| Others |
Supply Flow & Price Mechanics
Mechatronics technician scarcity in the Upper Midwest and Scandinavian maintenance hubs drives labor-cost differentials that widen pricing spreads between premium telematics-integrated fleets and standard hydraulic configurations. Municipal procurement officers in Canada and Germany face divergent total-cost-of-ownership calculations as skill premiums compound with EPA Phase 3 compliance investments.
Pricing Analysis
Capacity additions in Poland and Czech Republic are reshaping price floors for reinforced chassis fabrication, compressing margins for legacy European OEMs while creating entry space for regional fabricators. Pricing stratifies across premium, standard, and economy tiers based on telematics bundling intensity and CE-NHTSA dual certification status. Cost compression in economy-tier municipal highway contracts intensifies as provincial buyers consolidate award volumes. Private contractors in Alberta and Quebec exhibit highest price sensitivity due to performance-based risk transfer, while airport authorities in Switzerland show lowest sensitivity given precision-guidance mandates.
Supply Chain Analysis
Dual-sourcing requirements from Swedish Transport Administration and Ontario Ministry of Transportation mandate multi-supplier qualification for critical drivetrain components, fragmenting procurement leverage. Supply concentrates in Germany, Sweden, and Canada for reinforced chassis stamping, while battery cell production draws from South Korea and China. Steel and aluminum input volatility, combined with lithium-ion thermal management module lead times, creates single-source vulnerability in electric powertrain assembly. Distribution runs through captive dealer networks for municipal highway segments and direct-to-fleet telematics subscription channels for urban compact deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compounding from EU Green Deal decarbonization mandates and EPA Phase 3 standards is accelerating fleet replacement cycles beyond historical depreciation schedules.
For Market Incumbents: To counter battery thermal management performance degradation in subarctic deployment, deepen upstream control over thermal system engineering capacity in Nordic engineering clusters. Secure captive maintenance infrastructure through acquisition of regional service networks to guarantee uptime under performance-based Canadian contracts. Prioritize dual CE-NHTSA certification investment to defend transatlantic market access against emerging Asian chassis competitors. For New Entrants and Emerging Players: Autonomous guidance retrofit kits for existing municipal fleets represent the most penetrable white-space target, as Scandinavian operators seek lane-precision upgrades without full chassis replacement. Compact electric sweepers for German and Swiss logistics terminals offer fastest adoption curves given indoor air quality enforcement. Pursue telematics-native subscription positioning to bypass incumbent dealer channel control. For Investors and Strategic Acquirers: Industrial equipment conglomerates with captive municipal service networks are the most active acquirer in this space, seeking vertical integration into winter maintenance specialization. Target mid-tier superstructure fabricators with proven CE marking pathways and established Scandinavian municipal relationships. Monitor hydrogen fuel cell range-extender pilot results in Alberta as inflection indicator for extended-route electrification viability.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Enabled Subscription Launch | Repositions municipal procurement from capital expenditure toward operational expenditure models. |
| Dual Certification Investment | Unlocks transatlantic market access under divergent NHTSA and CE marking protocols. |
| Hydrogen Range-Extender Pilot | Addresses lithium-ion cold-weather limitations for Alberta and British Columbia rural routes. |
| Precision Guidance Integration | Meets ICAO Category III mandates at Zurich Airport and Oslo Gardermoen. |
| Compact Electric Platform Rollout | Captures German logistics terminal demand driven by urban noise ordinances. |
Methodological Framework
Coverage spans North America and Europe, with primary inputs from each region triangulated against secondary validation. Fleet managers at Swedish Transport Administration, maintenance directors at British Columbia highway authorities, procurement leads at Zurich Airport, and aftermarket service heads at Douglas Dynamics distributor networks contributed operational data. Secondary sources included EPA Phase 3 regulatory filings, EU Green Deal procurement guideline documents, FERC infrastructure disclosure records, and municipal tender databases. Bottom-up unit shipment estimates reconciled against top-down addressable market sizing.
Granularity-level modeling disaggregated volume and value across chassis weight class, powertrain architecture, end-user procurement type, and regional regulatory cluster. CAGRs derived from logistic curve fitting to adoption-phase transitions, with electric drive penetration rates calibrated against battery thermal management performance curves. Forecast inputs incorporated steel and aluminum commodity futures, lithium-ion cell production capacity announcements, and hydrogen fuel cell retrofit pilot timelines.
The model holds under stable regulatory enforcement timelines; deviation in EPA Phase 3 implementation delays or EU F-Gas Regulation phase-down acceleration would shift powertrain mix assumptions materially. Deviation in battery chemistry breakthroughs for sub-twenty-degree Celsius operation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Vacuum Truck Market
Heavy-Duty Trucks
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market
Heavy-Duty Trucks
Full Truckload Transportation Market
Heavy-Duty Trucks
Heavy Duty Truck Wash Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
North America Heavy Commercial Vehicle (HCV) TMPS Market
Heavy-Duty Trucks
Heavy-Truck Composite Component Market