
 Global Robot Cars and Trucks Market | 2026-2036
Global Robot Cars and Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Robot Cars and Trucks Market Intelligence
The available talent pool for autonomous vehicle development is bifurcating between software engineering specialists and traditional automotive hardware engineers. Waymo leverages its deep expertise in artificial intelligence and machine learning to refine its autonomous driving systems. In contrast, traditional automakers like General Motors and Ford Motor Company sustain their market position through extensive manufacturing scale and established dealer networks, integrating new technologies into existing platforms.
Robot cars and trucks are vehicles equipped with autonomous driving systems that use sensors, actuators, and complex algorithms to navigate without human input. These systems typically integrate a sensor suite including LIDAR for 3D mapping, computer vision for object recognition, and radar for distance measurement to achieve Level 4 or Level 5 autonomy. Within the technology segment, the fusion of LIDAR and computer vision is critical for robust performance, commanding significant R&D investment. Driverless trucks for freight transport and autonomous cars for ride-hailing represent the two largest application areas by projected deployment volume.
Regulatory frameworks from bodies like the NHTSA in the United States, Germany's KBA, and China's MIIT are establishing testing protocols and safety standards. These regulations directly influence vehicle design, operational domain limitations, and the requirements for market entry across different jurisdictions. Stakeholders must now decide whether to pursue a strategy of global platform standardization or regional adaptation to navigate the fragmented regulatory environment.
Market Dynamics
The central dynamic shaping the market is the strategic conflict between the need for global platform standardization to achieve economies of scale and the reality of fragmented regional regulations, such as the EU AI Act, which compel design adaptations.
Growth Catalysts
- Logistics Efficiency:Demand from the last-mile delivery and long-haul freight sectors for operational cost reduction and enhanced delivery speed provides a strong commercial pull for autonomous vehicle deployment, particularly for hub-to-hub transportation.
- Government Support in China:Proactive national policies and large-scale urban pilot projects in cities like Beijing and Shanghai create a favorable environment for rapid testing, data collection, and commercialization of robot cars and trucks.
- Sensor Technology Maturation:Continuous improvements in the performance and cost-effectiveness of key enabling technologies, specifically LIDAR and computer vision systems, are making Level 4 autonomy more commercially viable for fleet applications.
Market Restraints
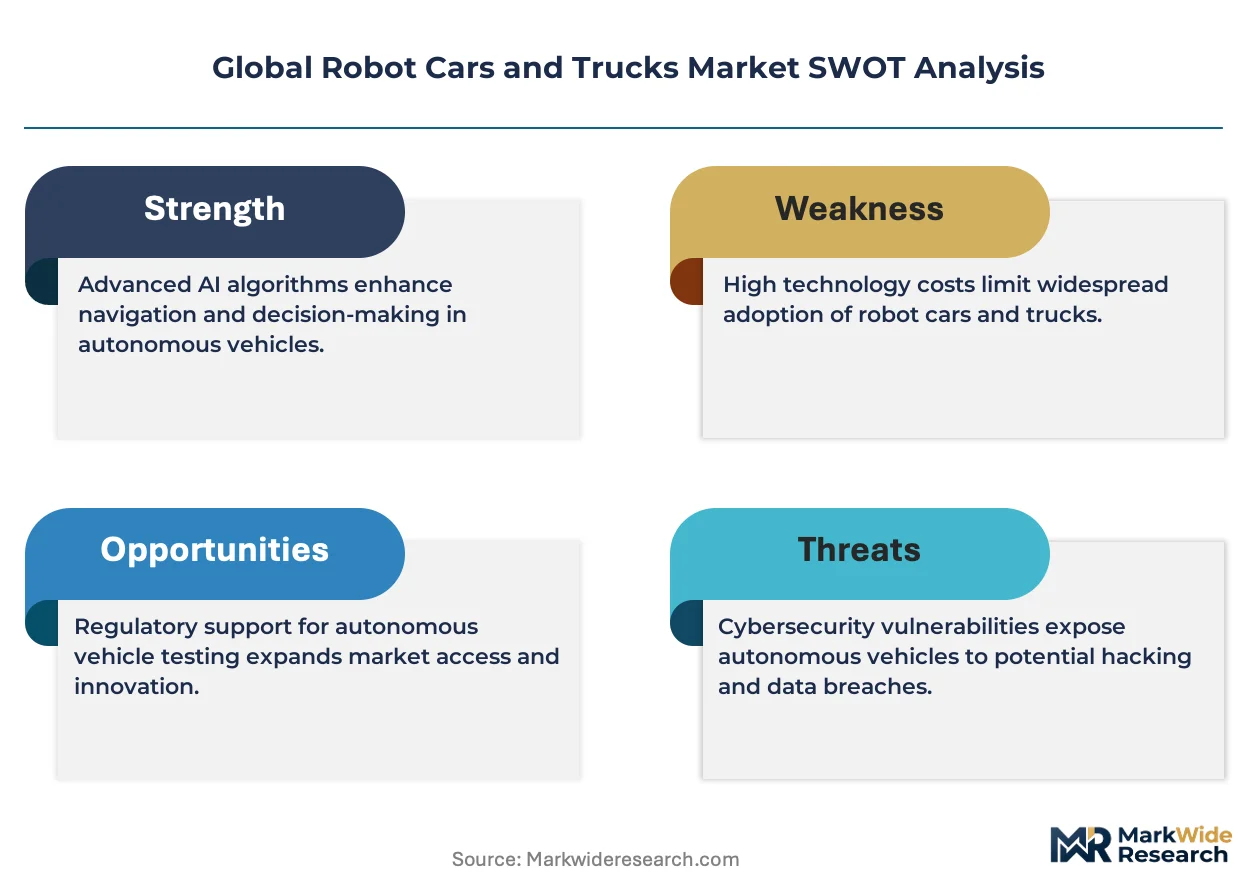
- High Sensor Suite Cost:The combined expense of LIDAR, high-resolution cameras, and advanced radar systems remains a significant barrier to mass-market adoption, limiting initial deployments to high-value commercial applications like freight and ride-hailing.
- Regulatory Fragmentation:Divergent safety standards and testing protocols from bodies like the NHTSA in the US, Germany's KBA, and China's MIIT create compliance complexity and slow down market entry for developers aiming for a single global vehicle platform.
- Technical Complexity of Sensor Fusion:Reliably integrating and interpreting data from multiple sensor modalities in all weather and lighting conditions presents a substantial engineering hurdle, demanding significant R&D investment and delaying robust all-domain performance.
Strategic Opportunities
- Specialized Off-Highway Applications:Significant white space exists in applying autonomous technology to controlled environments outside of public roads, such as in mining, agriculture, and port logistics, which have simpler operational domains and clearer ROI.
- Simulation and Digital Twins:Expanding the development of hyper-realistic simulation platforms allows for virtual testing and validation of autonomous driving algorithms, drastically reducing the cost and time associated with physical road testing and accelerating system refinement.
- Retrofit Kits for Commercial Fleets:Developing autonomous driving systems that can be retrofitted onto existing truck and van fleets offers a capital-efficient pathway for logistics companies to adopt autonomy without replacing their entire vehicle stock.
Industry Challenges
- Talent Integration:A persistent challenge is bridging the cultural and technical gap between software-centric AI specialists and traditional automotive hardware engineers, which is essential for producing safe and reliable integrated systems.
- Public Trust and Acceptance:Overcoming public skepticism regarding the safety and reliability of autonomous vehicles is a major operational hurdle that requires extensive public education, transparent safety reporting, and a near-perfect operational record.
- Cybersecurity Vulnerabilities:Ensuring the resilience of robot cars and trucks against malicious cyberattacks, which could compromise vehicle control or data integrity, requires developing new security architectures and ongoing threat monitoring protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Robot Cars and Trucks Market |
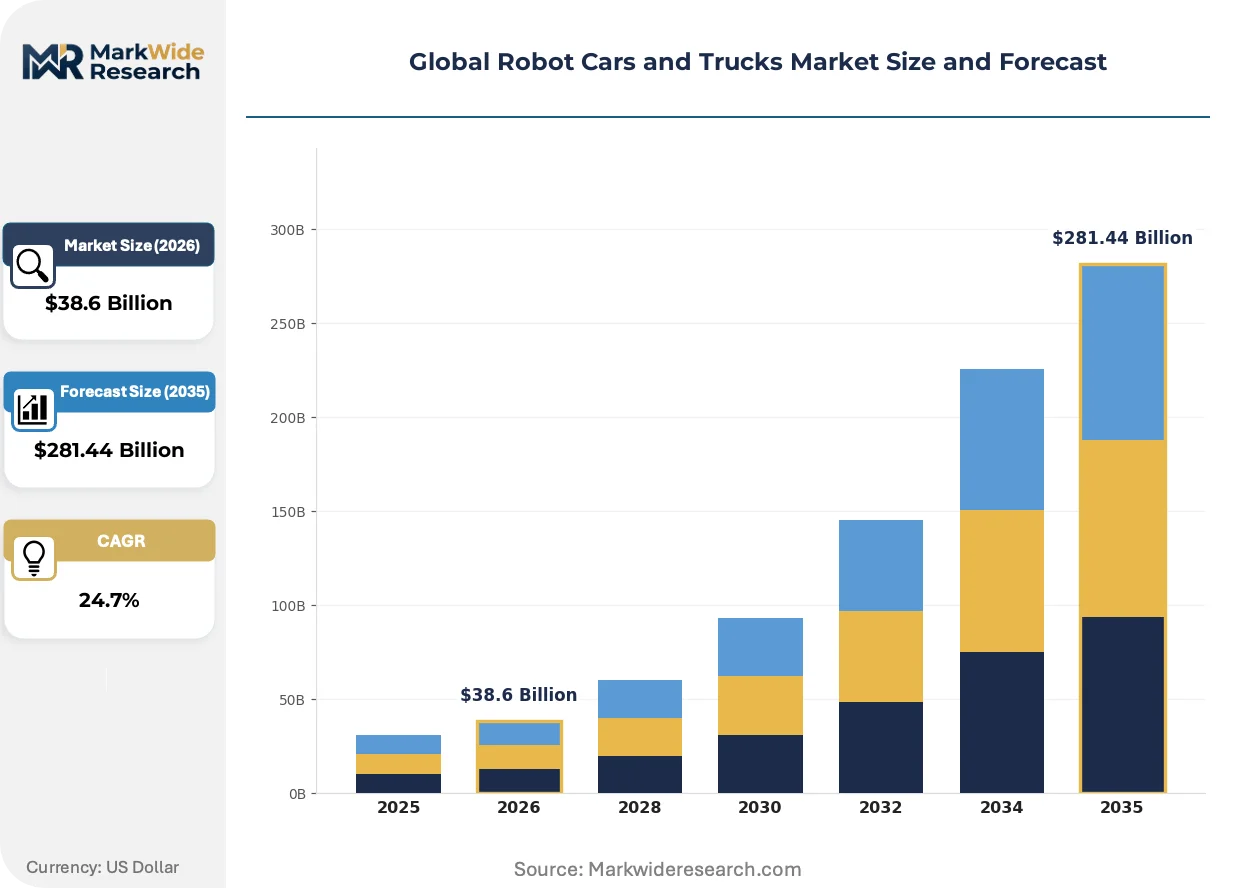
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $281.44 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Autonomous Cars, Driverless Trucks, Electric Robot Cars, Hybrid Robot Trucks, Delivery Drones Technology: LIDAR, Computer Vision, Radar, Ultrasonic Sensors, Artificial Intelligence, Machine Learning Application: Last-Mile Delivery, Freight Transport, Ride-Hailing, Public Transportation, Emergency Response, Agricultural Automation End User: Logistics Providers, Ride-Hailing Operators, Farming Enterprises, City Transit Authorities, Postal Services |
| Companies Covered | Tesla, Waymo, General Motors, TOYOTA MOTOR CORPORATION, BMW AG, Ford Motor Company, Mercedes-Benz, Volvo Group, Daimler Truck AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Robot Cars and Trucks Market Strategic Shifts & Innovations
A fundamental shift is underway from pure technological capability demonstration to proving operational viability and commercial scalability. The focus is now on integrating autonomous systems within complex logistical and regulatory environments, moving beyond controlled pilot projects.
Advanced sensor fusion software provides a unified perception layer by integrating inputs from LIDAR, radar, and cameras. Autonomous system developers and Tier-1 suppliers are rapidly adopting these platforms. This integrated software stack is supplanting the piecemeal approach of combining individual sensor data streams, which reduces development complexity and time-to-market.
The EU AI Act establishes a risk-based framework for artificial intelligence, classifying autonomous driving systems as high-risk. This legislation mandates stringent requirements for data quality, transparency, and human oversight throughout the vehicle's lifecycle. Vehicle software teams are most affected, now embedding legal and ethical compliance checks directly into their development sprints.
Consumption models for autonomous freight are transitioning toward transport-as-a-service. Logistics operators are increasingly opting for subscription or pay-per-mile agreements with technology providers rather than purchasing trucks outright, disrupting traditional dealer networks. This shift is most pronounced in the United States for long-haul freight routes connecting major logistics hubs.
Global Robot Cars and Trucks Market Segmentation
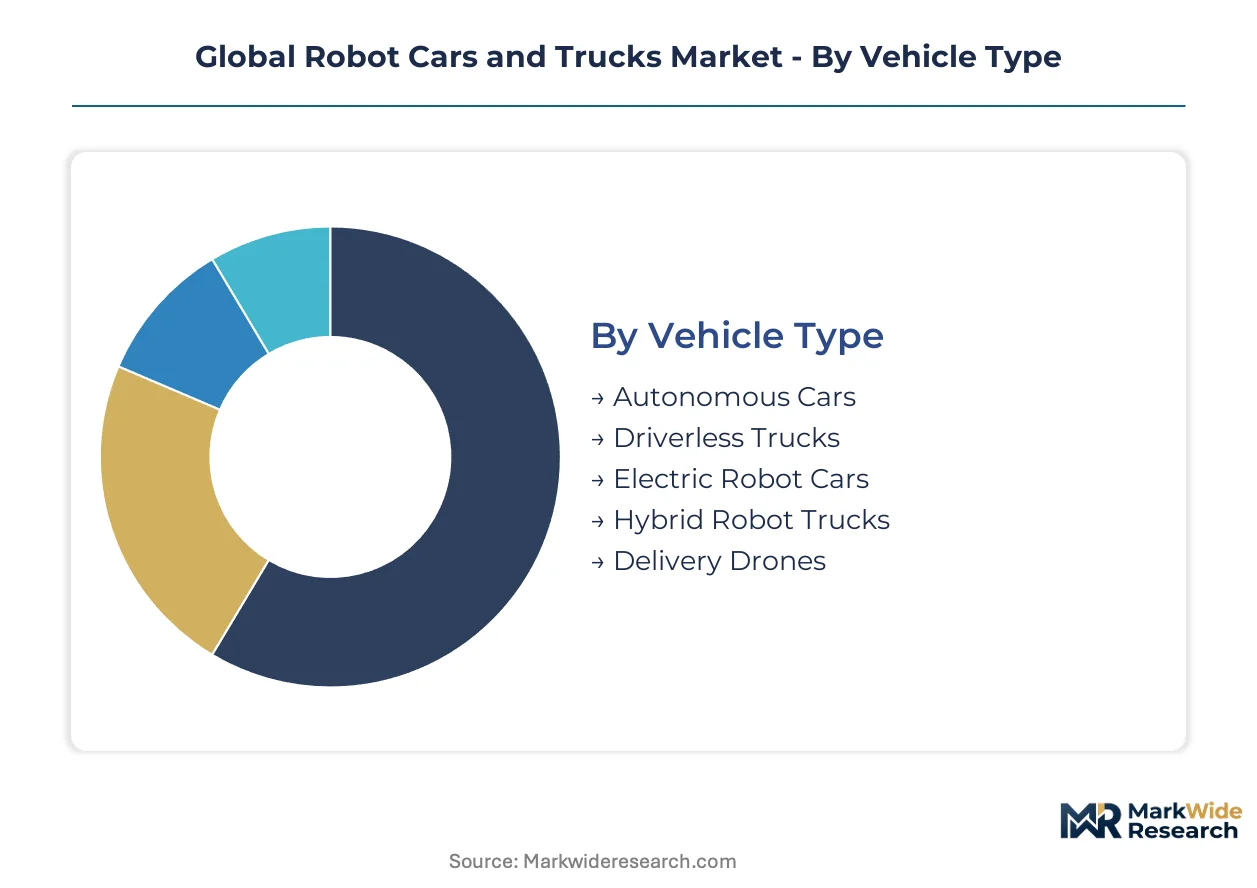
The market for robot cars and trucks is analyzed across key dimensions to reveal distinct operational characteristics and commercial viability. Understanding these segments helps stakeholders identify where technological advancements deliver the most impactful returns and where regulatory hurdles create market friction. This granular breakdown supports targeted investment and strategic planning.
Vehicle Type:
The vehicle type segmentation highlights varying degrees of substitution pressure from conventional human-driven vehicles, with certain autonomous categories facing less direct competition due to their specialized operational profiles.
- Driverless Trucks:These heavy-duty vehicles operate autonomously, primarily for long-haul freight transport and hub-to-hub logistics. Demand concentrates in the United States and China, driven by the need for labor cost reduction and improved supply chain efficiency.
- Autonomous Cars:Passenger vehicles equipped with Level 4 or Level 5 self-driving capabilities are designed for ride-hailing services and personal mobility. Their deployment is gaining traction in urban pilot projects across China and select US cities, focusing on safety and convenience.
- Electric Robot Cars:These battery-electric vehicles integrate autonomous driving systems, offering zero-emission operation for urban ride-hailing and delivery services.
- Hybrid Robot Trucks:Combining internal combustion engines with electric propulsion, these autonomous trucks provide extended range and fuel flexibility for freight operations.
- Delivery Drones:Unmanned aerial vehicles designed for autonomous last-mile package delivery, particularly in geographically challenging or low-density areas.
Driverless Trucks anchor the volume base while Autonomous Cars gains share at the steepest rate.
Technology:
Technology segmentation reveals distinct cost tiers and performance capabilities, with advanced sensor fusion components commanding higher investment due to their critical role in achieving Level 4 and Level 5 autonomy.
- LIDAR:This sensor uses pulsed laser light to measure distances and create precise 3D maps of the vehicle's surroundings. It is crucial for high-resolution environmental perception, with significant R&D investment in reducing its unit cost for broader deployment.
- Computer Vision:Utilizing cameras and image processing algorithms, computer vision systems detect and classify objects, pedestrians, and traffic signs. Its robust performance in varied lighting conditions drives its integration into perception stacks, especially in urban environments.
- Radar:Radar sensors emit radio waves to measure distance, speed, and direction of objects, performing reliably in adverse weather conditions.
- Ultrasonic Sensors:These short-range sensors use sound waves for proximity detection, aiding low-speed maneuvers and parking assistance.
- Artificial Intelligence:AI algorithms process sensor data, enabling decision-making, path planning, and behavioral prediction for autonomous vehicles.
- Machine Learning:A subset of AI, machine learning models continuously learn from data to improve perception, prediction, and control system performance.
LIDAR and Computer Vision technologies are experiencing the fastest expansion as sensor fusion capabilities mature.
Application:
The application areas delineate where autonomous vehicle technology is currently being deployed to address specific operational challenges and generate commercial value across various industries.
- Freight Transport:Autonomous trucks are deployed for long-haul and hub-to-hub logistics, addressing driver shortages and enhancing operational efficiency for logistics providers. This segment sees significant investment in the US and China due to large-scale transportation networks.
- Last-Mile Delivery:Robot cars and smaller autonomous vehicles deliver packages directly to consumers, aiming to reduce labor costs and improve delivery speed in urban and suburban areas. Demand is high from e-commerce companies and postal services.
- Ride-Hailing:Autonomous cars replace human drivers in taxi-like services, offering 24/7 availability and potentially lower per-mile costs for operators.
- Public Transportation:Driverless shuttles and buses operate on fixed routes, improving service frequency and accessibility in designated urban zones.
- Emergency Response:Autonomous vehicles assist in tasks like disaster relief, search and rescue, or transporting medical supplies in hazardous environments.
- Agricultural Automation:Self-driving tractors and equipment perform tasks like planting, spraying, and harvesting, optimizing farm productivity and resource use.
Freight Transport maintains a dominant market share, while Last-Mile Delivery applications show substantial growth potential.
End User:
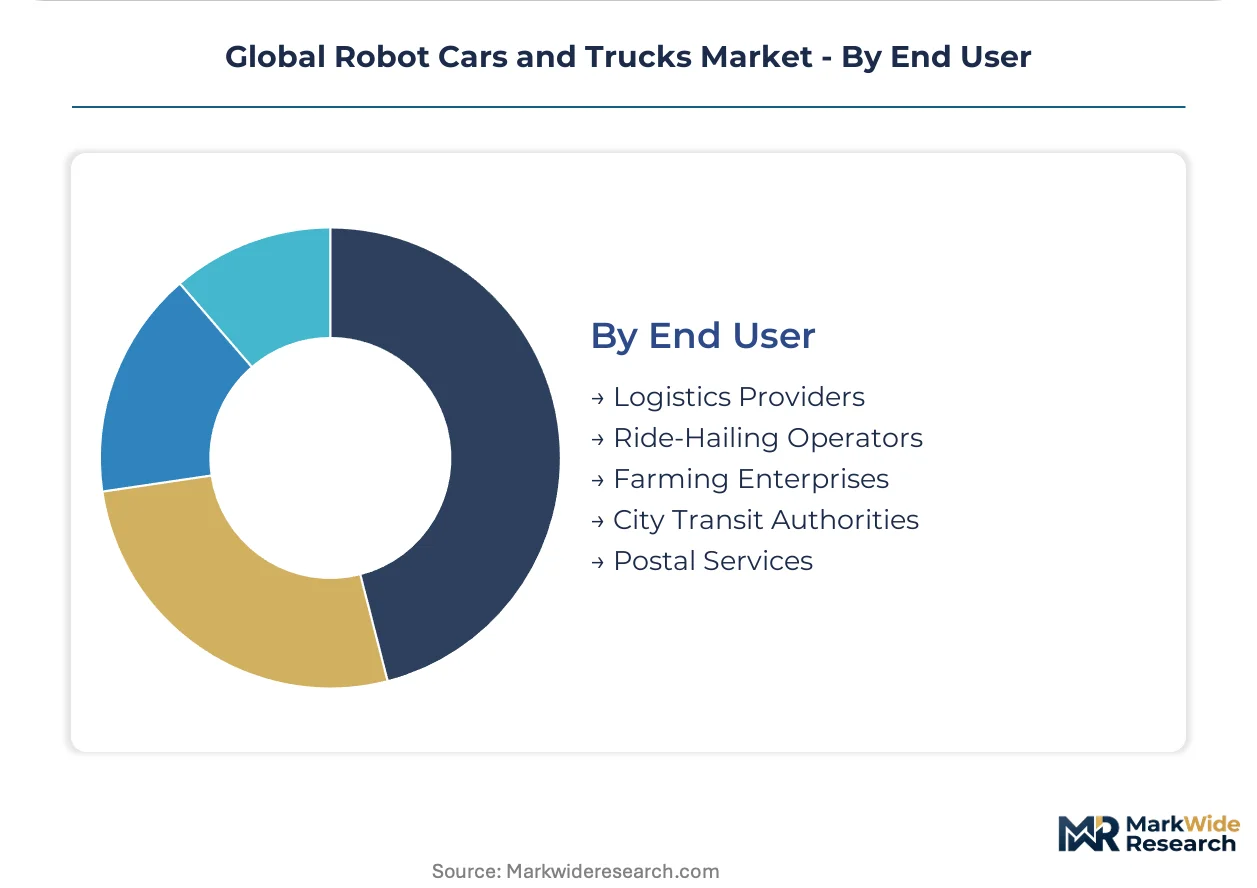
End user segmentation identifies the primary commercial entities adopting robot cars and trucks, reflecting distinct business models and operational requirements that drive autonomous system integration.
- Logistics Providers:These companies, including freight carriers and warehousing operators, adopt autonomous trucks and delivery vehicles to optimize supply chain operations. Their primary goal is to reduce operational costs and mitigate labor shortages, particularly in long-haul routes.
- Ride-Hailing Operators:Firms like Waymo and Cruise deploy autonomous cars to offer passenger transport services, aiming for increased vehicle utilization and reduced per-trip expenses. This segment is prominent in major urban centers where regulatory frameworks permit.
- Farming Enterprises:Agricultural businesses utilize autonomous tractors and equipment to enhance precision farming, improving efficiency and output in large-scale operations.
- City Transit Authorities:Municipal bodies deploy autonomous shuttles and buses to augment public transport networks, improving service reliability and coverage in urban areas.
- Postal Services:National and private postal organizations integrate autonomous vehicles for package sorting and last-mile delivery, streamlining their distribution networks.
Logistics Providers form the largest customer base, with Ride-Hailing Operators quickly expanding their fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for robot cars and trucks varies significantly across key geographies, reflecting distinct market maturities and regulatory priorities. China and the United States lead in autonomous vehicle deployment, but with differing emphases on freight versus passenger applications. European nations prioritize safety and ethical AI frameworks, influencing design adaptations for regional market entry.
United States
Demand for long-haul freight transport and ride-hailing services drives autonomous vehicle deployment across the country. The NHTSA establishes safety standards and testing protocols, influencing vehicle design and operational limits for market entry. Silicon Valley and Arizona are primary hubs for testing and commercialization, attracting significant R&D investment from technology companies.
China
Proactive national policies and large-scale urban pilot projects accelerate market growth for robot cars and trucks. The MIIT provides a favorable regulatory environment for rapid testing, data collection, and commercialization. Cities like Beijing and Shanghai lead in urban robotaxi and delivery drone deployments, supported by robust government incentives.
Germany
The nation's advanced automotive industry focuses on integrating high-level autonomy into existing vehicle platforms. Germany's KBA sets stringent safety standards and operational domain limitations for autonomous vehicles, particularly for public road use. Stuttgart and Munich serve as key research and development centers for traditional automakers and their autonomous divisions.
Japan
Demand for public transportation and logistics efficiency shapes autonomous vehicle development within the country. METI supports innovative solutions for aging populations and last-mile delivery challenges in urban and rural areas. Tokyo and other major metropolitan areas are exploring driverless shuttle services and automated delivery solutions to enhance urban mobility.
India
The country's vast logistics sector and urban congestion present significant opportunities for autonomous freight and public transport solutions. The government is exploring regulatory frameworks to support pilot projects for specialized applications in controlled environments. Bengaluru and Pune are emerging centers for AI and software development, contributing to autonomous driving stacks.
Global Robot Cars and Trucks Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the market structure for robot cars and trucks. The competitive environment is characterized by a blend of established automotive manufacturers, technology-first innovators, and specialized solution providers. Strategic partnerships and significant R&D investment represent dominant competitive moves among these archetypes.
Within the technology-first innovator archetype, Waymo exemplifies a software-centric approach, leveraging its deep artificial intelligence expertise to refine autonomous driving systems. General Motors, an established automotive manufacturer, integrates new technologies into its extensive production capabilities through its Cruise division. Tesla represents a vertically integrated electric vehicle manufacturer, focusing on in-house autonomous driving solutions and advanced driver-assistance systems.
| Leading Market Players |
|---|
| Tesla |
| Waymo |
| General Motors |
| TOYOTA MOTOR CORPORATION |
| BMW AG |
| Ford Motor Company |
| Mercedes-Benz |
| Volvo Group |
| Daimler Truck AG |
| Others |
Cost & Logistics Intelligence
The shift from human drivers to autonomous systems in robot cars and trucks reshapes both supply chain geography and operational pricing economics. This transition concentrates value in software and sensor components rather than traditional labor costs.
Pricing Analysis
Long-term contract-based agreements dominate commercial robot car and truck deployments, especially for freight transport and ride-hailing services. Performance tier and comprehensive after-sales service bundles drive price differentiation among technology providers. Cost compression in LIDAR and computer vision systems is intensifying due to increased manufacturing scale and component standardization. Logistics providers exhibit high price sensitivity for large fleet deployments, while ride-hailing operators prioritize system reliability and operational uptime, showing less initial price sensitivity.
Supply Chain Analysis
The specialized manufacturing of advanced sensor components, particularly LIDAR and AI processors, concentrates in China, South Korea, and Germany. This supply chain draws from a global network for semiconductors, high-resolution cameras, and specialized LIDAR emitters. Single-source vulnerability for specific AI processors represents a structural risk, impacting lead times and costs. Distribution runs through direct sales channels from technology providers to vehicle OEMs and large commercial fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robot cars and trucks market sits at a platform-economics inflection, driven by the emergence of standardized sensor fusion software platforms. This shift enables greater interoperability across vehicle types and accelerates ecosystem development.
For Market Incumbents: Compound existing manufacturing scale with deep software integration to counter technology-first entrants like Waymo. Invest heavily in AI talent acquisition and develop proprietary sensor fusion architectures to maintain a competitive edge. The rapid pace of software innovation from technology-first innovators represents a significant threat. Leverage established dealer networks for service and maintenance, providing a critical customer touchpoint.
For New Entrants and Emerging Players: Specialized off-highway applications represent a significant service-layer gap where incumbents under-serve due to lower volume. Develop autonomous solutions for mining, agriculture, or port logistics, where operational domains are more controlled. The agricultural automation segment offers a clear ROI and simpler operational domains, making it highly penetrable. Offer transport-as-a-service models to logistics providers, bypassing large upfront capital expenditures.
For Investors and Strategic Acquirers: The market sits at a commercialization phase that favors technology integrators with proven Level 4 autonomy systems. Long-term viability depends on achieving regulatory clarity and broad public acceptance across major economies like the United States and China. Target specialist software firms focusing on sensor fusion or AI prediction models for strategic acquisition. Watch for declining unit costs of LIDAR systems as a critical inflection indicator for mass-market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces development costs and accelerates market entry for autonomous driving systems across different vehicle types. |
| AI Talent Acquisition | Secures critical expertise in machine learning and computer vision, enhancing autonomous system performance and safety. |
| Simulation Platform Development | Drastically reduces physical testing costs and time, accelerating algorithm refinement and validation for autonomous vehicles. |
| Transport-as-a-Service Offering | Lowers capital barriers for logistics providers, driving adoption of autonomous freight solutions in the United States. |
| Cybersecurity Architecture Investment | Protects robot cars and trucks from malicious cyberattacks, ensuring operational integrity and public trust. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and robust secondary research. We engaged with automotive platform engineers, logistics fleet managers, AI software developers, and regulatory affairs specialists. Secondary data from NHTSA reports, MIIT policy documents, corporate financial filings, and industry association publications provided essential context. This approach combined bottom-up market sizing with top-down validation.
The forecast framework projects market evolution across the analysis window through a dynamic modeling approach. Segmentation dimensions included vehicle type, technology, application, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical data trends and projected adoption curves. Key inputs included sensor cost reduction trajectories and regulatory approval timelines.
Forecasts assume regulatory continuity in the United States, China, and Europe; material policy shifts would require re-modeling. Geopolitical tensions or unexpected technical breakthroughs present specific risk factors. Practitioners should keep alternative scenarios live as public trust and cybersecurity threats evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Vehicle Management Services Market
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
Australia Autonomous Navigation Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Luxury Autonomous Vehicle Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Self-Balancing Mobility Market
Autonomous Vehicles
Blind Spot Detection Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
Asia-Pacific Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market
Autonomous Vehicles
Autonomous Vehicles and Car Patent Market