
 Power Transmission Gearbox Market | 2026-2036
Power Transmission Gearbox Market Size, Share, and Industry Trends Forecast 2026-2036
Power Transmission Gearbox Market Analytics
ISO 6336-grade precision specifications is redrawing competitive requirements across heavy-duty industrial applications. SEW-Eurodrive leverages integrated drive systems to anchor its position in automated manufacturing lines. Siemens differentiates through digital twin integration for predictive maintenance in energy applications. Bonfiglioli Riduttori SpA specializes in compact planetary configurations for mobile equipment.
A power transmission gearbox is a mechanical assembly of gears, shafts, bearings, and housings designed to transmit torque between prime movers and driven equipment with specific speed ratios and load capacities, typically manufactured through case-hardened steel gear cutting, heat treatment, and precision grinding to achieve AGMA or DIN quality classes. Its primary purpose is to adapt rotational speed and multiply torque in industrial machinery, vehicles, and power generation systems. Planetary configurations command premium positioning in wind energy nacelles due to their torque density and compact axial footprint. Helical designs dominate manufacturing applications where smooth operation and load distribution justify higher initial outlays. Worm gearboxes retain cost advantages in low-speed, high-reduction conveying systems despite efficiency limitations.
The EU Green Deal and EPA efficiency standards tighten permissible losses in industrial power transmission equipment, compelling redesigns of lubrication systems and gear tooth profiles. China's GB standards and NMPA-equivalent machinery safety regulations enforce localized testing protocols for imported gearbox assemblies. REACH compliance in Europe restricts certain alloy compositions in bearing steels, altering supplier qualification pathways. Stakeholders must weigh regional certification divergence against platform standardization economics when configuring global product portfolios.
Market Dynamics
ISO 6336-grade precision specifications are compressing supplier margins while elevating technical barriers across heavy-duty industrial applications. Wind energy nacelle manufacturers now demand planetary configurations with torque densities exceeding conventional helical alternatives.
Growth Catalysts
- EU Green Deal efficiency mandates:Tightened permissible loss thresholds under EPA parallel standards compel lubrication system redesigns and gear tooth profile optimizations across North American and European installed bases.
- Utility-scale wind installations:China, Germany, and the United States concentrate demand for compact planetary gearboxes capable of handling multi-megawatt turbine torque loads in nacelle-constrained envelopes.
- Case-hardened steel advancement:Heat treatment and precision grinding improvements enable AGMA quality class 12+ achievement, extending service intervals in automated manufacturing lines.
Market Restraints
- Alloy composition restrictions:REACH compliance in Europe limits specific bearing steel chemistries, forcing supplier requalification and extended procurement timelines for precision-ground components.
- Supply concentration risk:Premium planetary gearbox production clusters in Germany and China, exposing buyers to logistics disruption and currency volatility in concentrated sourcing corridors.
- Worm gearbox efficiency ceiling:Inherent mechanical limitations below 90% efficiency restrict application expansion despite cost advantages in low-speed conveying systems.
Strategic Opportunities
- Digital twin convergence:Predictive maintenance platforms integrating real-time vibration analysis with gearbox digital twins create recurring revenue streams in energy sector contracts.
- Mobile equipment electrification:Compact planetary configurations for electric construction and agricultural machinery represent underpenetrated demand as hydraulic systems face displacement.
- GB standards localization:China's NMPA-equivalent machinery safety regulations incentivize domestic assembly partnerships for imported gearbox configurations.
Industry Challenges
- Precision grinding talent scarcity:Case-hardened steel finishing to ISO 6336 specifications requires specialized machinist expertise concentrated in aging workforce pools across European manufacturing clusters.
- Multi-certification complexity:Simultaneous AGMA, DIN, and GB standard compliance extends product development cycles and fragments platform economics for global portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Transmission Gearbox Market |
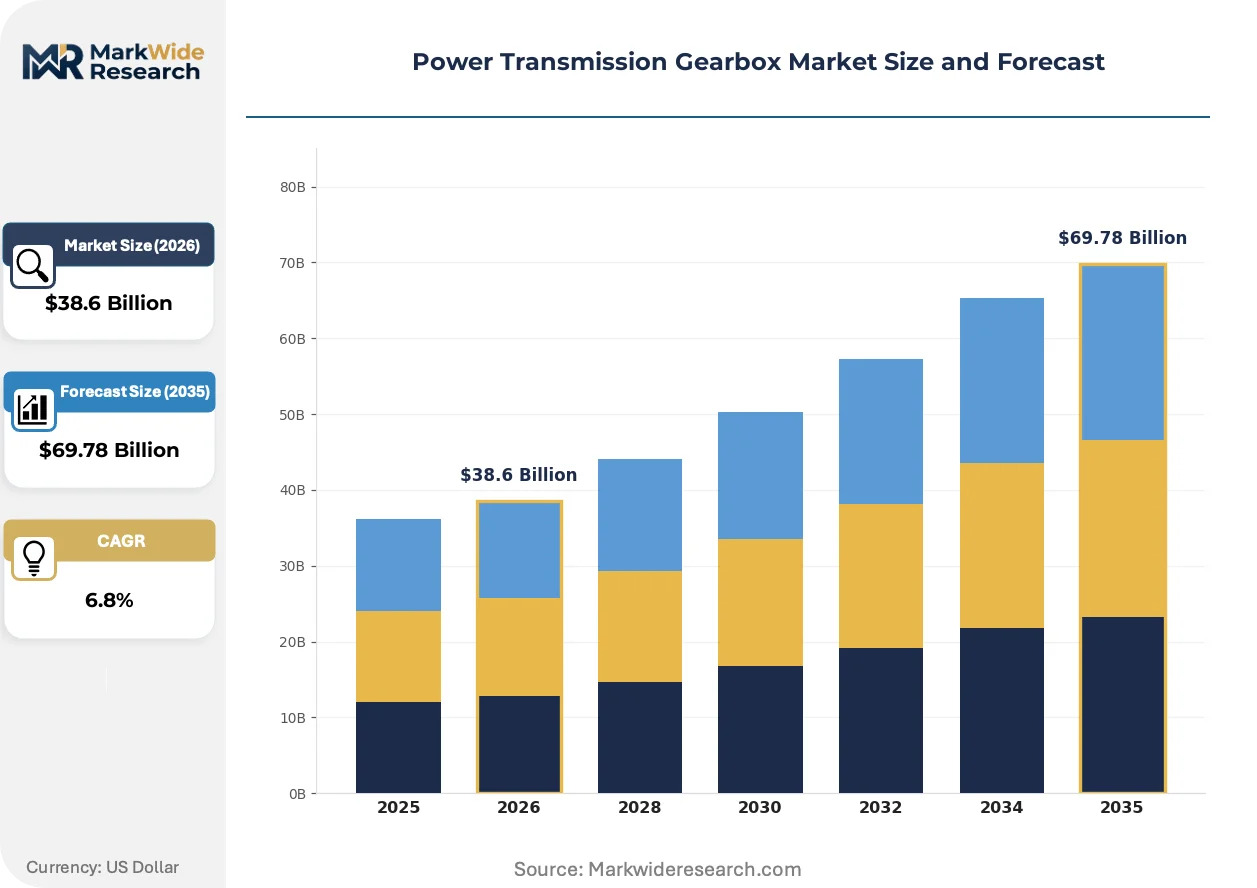
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helical, Bevel, Worm, Planetary End User: Automotive, Manufacturing, Marine, Aerospace Mounting Type: Horizontal, Vertical, Shaft-Mounted, Foot-Mounted Application: Wind Energy, Industrial Machinery, Construction Equipment, Mining |
| Companies Covered | ZF Friedrichshafen AG, SEW-Eurodrive, Bonfiglioli Riduttori SpA, Sumitomo Drive Technologies, Flender GmbH, Regal Rexnord Corporation, Siemens, Getriebebau NORD GmbH, Elecon Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Transmission Gearbox Market Evolving Landscape
Additive manufacturing of gear tooth profiles is penetrating prototype and low-volume production, compressing lead times for custom ratio configurations. Digital thread integration from design through field service is reshaping how manufacturers capture lifecycle value.
Integrated sensor-embedded gearboxes is supplanting externally mounted monitoring equipment in wind energy nacelles. Siemens and SEW-Eurodrive deploy torque and temperature sensing directly into planetary carrier assemblies. This convergence is compressing aftermarket service margins while shifting revenue toward predictive analytics subscriptions.
EPA efficiency standards and EU Green Deal loss thresholds are forcing lubrication architecture redesigns. Synthetic formulations with extended thermal stability replace mineral oils in high-load industrial applications. Gearbox OEMs in Germany and the United States respond with sealed-for-life units that eliminate maintenance intervals while meeting tightened emissions accounting.
After-sales service unbundling is fragmenting traditional distributor relationships. End-users in automated manufacturing now procure spare gear sets and bearing assemblies directly from component specialists, bypassing integrated drive system vendors. This pattern concentrates in the United States and China where procurement platforms enable transparent component sourcing.
Power Transmission Gearbox Market Segmentation
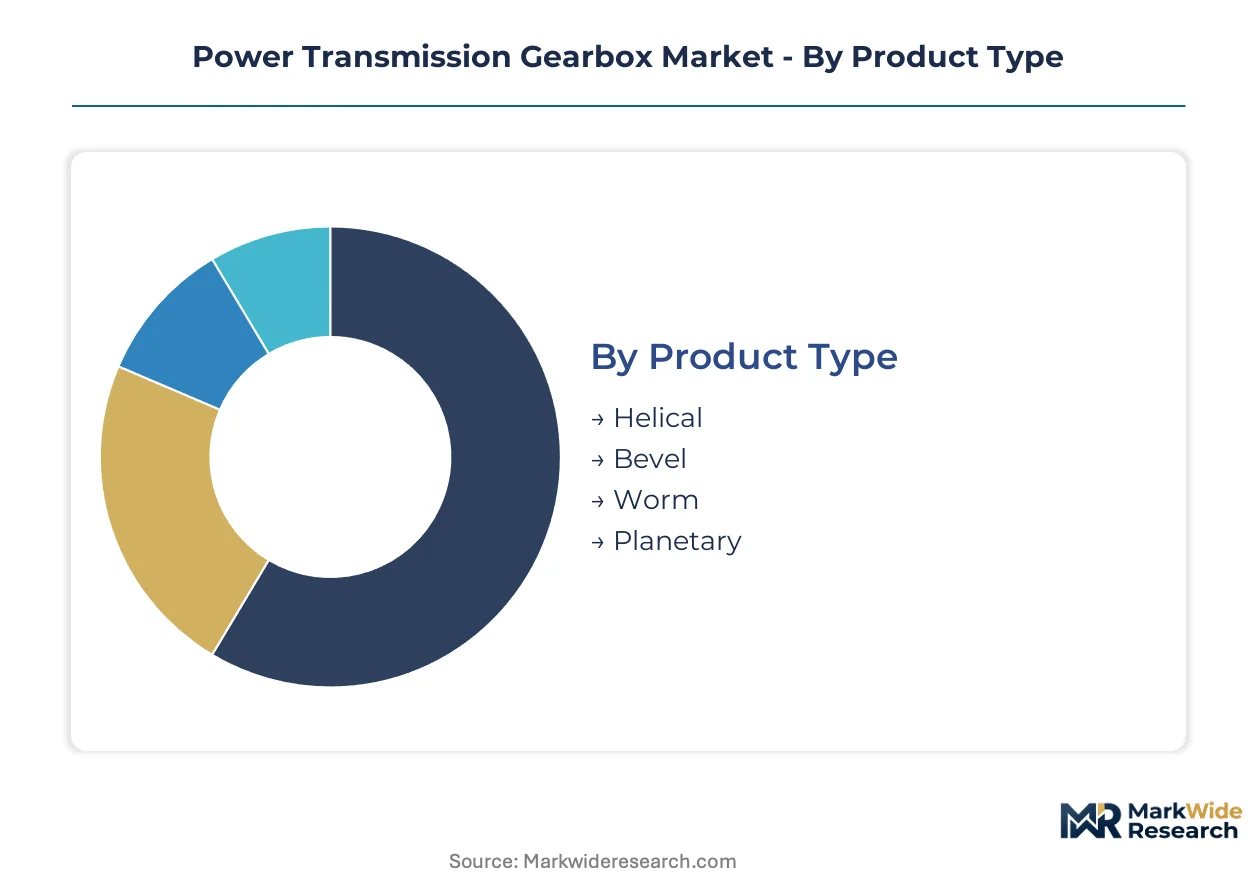
Segmentation in power transmission gearboxes reveals how torque density requirements, installation constraints, and duty cycle intensity fragment demand across divergent technical specifications. Margin pools concentrate where precision grinding capabilities intersect with multi-megawatt load handling.
Product Type:
Margin concentration follows torque density gradients, with premium positioning attaching to configurations that minimize envelope dimensions while maximizing load capacity.
- Planetary:Concentric gear arrangements distribute torque across multiple planet gears, achieving torque densities exceeding conventional alternatives. Wind energy nacelle manufacturers in Germany and China specify these for multi-megawatt turbine installations where axial footprint constraints dominate design tradeoffs. REACH-compliant bearing steels and ISO 6336 precision specifications elevate entry barriers.
- Helical:Angled tooth engagement delivers smooth operation and superior load distribution across tooth flanks. Automated manufacturing lines in the United States absorb volume for continuous-duty material handling systems where noise suppression and service interval extension justify cost premiums over spur alternatives.
- Bevel:Right-angle power transmission for intersecting shaft arrangements. Marine propulsion systems and heavy mobile equipment specify hardened spiral bevel sets.
- Worm:Single-enveloping or double-enveloping worm sets achieve high reduction ratios in compact envelopes. Low-speed conveying systems in mining and bulk material handling accept efficiency tradeoffs below 90% for acquisition cost advantages.
The dominant share belongs to Helical configurations, while Planetary is closing the gap fastest.
End User:
Application intensity and duty cycle predictability determine pricing power, with continuous-process industries commanding premium specifications over intermittent-use sectors.
- Manufacturing:Automated production lines demand AGMA quality class 12+ precision for synchronized motion control and extended maintenance intervals. SEW-Eurodrive and Siemens anchor positions through integrated drive systems and digital twin platforms. EPA efficiency mandates and EU Green Deal loss thresholds compel lubrication architecture redesigns across installed bases in the United States and Germany.
- Wind Energy:Nacelle-integrated gearboxes face torque loads exceeding 10 MN·m in utility-scale turbines. China, Germany, and the United States concentrate demand for compact planetary configurations with integrated sensor embedding for predictive maintenance.
- Automotive:Electric vehicle powertrain integration and commercial vehicle transmission manufacturing specify case-hardened precision sets. GB standards and NMPA-equivalent protocols enforce localized testing for imported assemblies.
- Marine:Classification society rules from Lloyd's Register and DNV govern material specifications and tooth contact pattern verification for propulsion and auxiliary systems.
- Aerospace:Superalloy gearing for auxiliary power units and flight control actuation demands NADCAP-accredited heat treatment and magnetic particle inspection protocols.
Manufacturing retains the largest installed base, though Wind Energy shows the steepest expansion trajectory as turbine ratings escalate.
Mounting Type:
Installation flexibility and structural load paths differentiate cost structures, with constrained-access applications commanding premium engineering.
- Foot-Mounted:Rigid baseplate installation transmits reaction torques through foundation bolts, dominating stationary industrial machinery in manufacturing plants across China and Germany.
- Shaft-Mounted:Direct coupling to driven equipment shafts eliminates baseplate requirements, penetrating mobile equipment and space-constrained conveying systems where rapid installation matters.
- Horizontal:Parallel shaft arrangements with oil bath lubrication serve conventional material handling and process equipment.
- Vertical:Thrust bearing integration and specialized sealing architectures address pump drives, cooling tower fans, and overhead crane applications.
Foot-Mounted configurations hold the greatest volume, yet Shaft-Mounted alternatives are gaining share fastest in mobile equipment electrification.
Application:
Environmental exposure severity and uptime criticality stratify specifications, with outdoor continuous-duty installations demanding the most robust corrosion protection and sealing systems.
- Wind Energy:Nacelle-integrated planetary gearboxes operate in temperature extremes and vibration environments without maintenance access for years. Multi-megawatt turbine OEMs in China and Germany specify torque densities and digital thread integration from commissioning through end-of-life.
- Industrial Machinery:Continuous-process manufacturing, packaging lines, and material handling systems absorb standardized helical and bevel configurations with AGMA quality class 10-12 precision.
- Construction Equipment:Compact planetary drives for electric excavators and loaders face hydraulic system displacement as OEMs electrify mobile fleets. Bonfiglioli Riduttori SpA specializes in envelope-constrained configurations for this transition.
- Mining:Girth gear drives for mills, conveyor head pulley reducers, and shovel swing drives encounter abrasive contamination and shock loading. Sealed-for-life synthetic lubrication architectures extend service intervals in remote operations.
Industrial Machinery maintains the broadest footprint, but Wind Energy commands the highest unit values and tightest specification convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gearbox trade flows tilt toward manufacturing surplus regions with precision grinding capabilities. Germany and China export finished planetary assemblies while importing raw alloy steels. The United States runs a deficit in compact nacelle configurations, offset by helical gearbox exports for automated lines.
Germany
Wind energy OEMs in Rostock and Bremerhaven source planetary gearboxes for multi-megawatt turbines. REACH compliance restricts bearing steel compositions, forcing heat treatment suppliers to requalify chemistries. Baden-Württemberg hosts SEW-Eurodrive and Flender GmbH operations serving automated manufacturing corridors.
China
Utility-scale wind installations in Jiangsu and Guangdong provinces absorb planetary configurations for 10+ MW turbines. GB standards and NMPA-equivalent machinery safety regulations mandate localized testing protocols for imported assemblies. The Yangtze River Delta concentrates precision grinding capacity for case-hardened steel finishing.
United States
EPA efficiency standards tighten loss thresholds for industrial power transmission equipment in Ohio and Michigan manufacturing belts. FERC grid interconnection rules influence wind farm gearbox specifications in Texas and Iowa. Synthetic lubrication architectures spread across Great Lakes industrial corridors to meet emissions accounting requirements.
Japan
Automotive powertrain electrification in Toyota City and Yokohama demands compact helical sets for electric commercial vehicles. METI carbon neutrality roadmaps accelerate gearbox efficiency benchmarks. The Nagoya industrial zone integrates precision gearing into robotics and machine tool exports.
India
Cement and steel producers in Gujarat and Maharashtra deploy girth gear drives for kiln and mill operations. BIS certification requirements extend product development timelines for European gearbox imports. The Pune-Nashik manufacturing belt attracts domestic assembly partnerships for planetary configurations.
Power Transmission Gearbox Market Competitive Landscape
Concentration sits with integrated drive system specialists and precision grinding houses. The vendor base splits between conglomerate industrial divisions and family-owned transmission engineers. Three archetypes dominate: diversified industrial technology groups, specialized planetary gearbox engineers, and regional helical gearbox fabricators. Capacity expansion and digital twin licensing represent the primary competitive vectors as efficiency mandates compress margins.
Among German industrial technology groups, SEW-Eurodrive, Siemens, and Flender GmbH exemplify the integrated drive system archetype. These conglomerate-anchored entities occupy positions spanning automated manufacturing lines and energy sector predictive maintenance platforms. SEW-Eurodrive represents the family-owned precision engineering tradition, while Siemens and Flender GmbH sit within broader electrification and industrial automation portfolios. Their collective positioning illustrates how digital thread integration and sensor-embedded configurations reshape revenue capture from hardware toward analytics subscriptions.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| SEW-Eurodrive |
| Bonfiglioli Riduttori SpA |
| Sumitomo Drive Technologies |
| Flender GmbH |
| Regal Rexnord Corporation |
| Siemens |
| Getriebebau NORD GmbH |
| Elecon Engineering |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between wind turbine OEMs and planetary gearbox suppliers lock in both supply access and price visibility across multi-year installation cycles, with China and Germany anchoring the contract concentration that shapes margin predictability for precision grinding houses serving utility-scale projects.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the power transmission gearbox market. Price differentiation rests on ISO 6336 precision certification grades and AGMA quality class ratings, with AGMA 12+ configurations commanding substantial premiums over class 10 alternatives. Cost compression in standard-tier helical configurations is intensifying because Chinese manufacturers are expanding case-hardened steel finishing capacity. Mining and bulk material handling sectors exhibit the highest price sensitivity, while wind energy nacelle manufacturers prioritize torque density over unit cost.
Supply Chain Analysis
Germany and China anchor precision planetary gearbox production, with Baden-Württemberg and the Yangtze River Delta hosting concentrated case-hardened steel grinding and heat treatment capabilities. Raw material flows draw from Swedish bearing steel suppliers and Japanese specialty alloy producers, creating dependencies on long-haul seaborne logistics. Single-source vulnerability concentrates in REACH-compliant bearing steel chemistries where European requalification timelines extend procurement cycles. Distribution runs through integrated drive system vendors and direct component procurement platforms fragmenting traditional aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized precision grinding expertise for ISO 6336-grade case-hardened steel finishing represents a binding constraint, with aging machinist pools in European manufacturing clusters creating acquisition targets for technical talent and captive heat treatment assets.
For Market Incumbents: Shield margin pools by deepening backward integration into case-hardened steel heat treatment and precision grinding capabilities, particularly in Germany where REACH compliance has forced supplier requalification. Capture digital twin licensing revenue streams from predictive maintenance platforms to offset hardware margin compression from EPA efficiency mandates and EU Green Deal loss thresholds. For New Entrants and Emerging Players: Anchor in mobile equipment electrification white space, specifically compact planetary configurations for electric construction and agricultural machinery facing hydraulic system displacement. Target China's Yangtze River Delta for domestic assembly partnerships that satisfy GB standards and NMPA-equivalent machinery safety regulations for imported configurations. Pursue component specialist positioning in direct spare gear set procurement channels bypassing integrated drive system vendors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision grinding houses with captive heat treatment assets and ISO 6336 certification capabilities. Long-term viability hinges on technical workforce access and digital thread integration platforms rather than pure manufacturing scale. Monitor REACH-compliant bearing steel requalification timelines as an inflection indicator for supplier margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captive case-hardened steel finishing reduces REACH compliance exposure and procurement cycle risk. |
| Digital Twin Licensing Platform | Predictive maintenance subscriptions shift revenue from hardware toward recurring analytics contracts with wind energy OEMs. |
| GB Standards Localization Partnership | Domestic assembly in China's Yangtze River Delta satisfies NMPA-equivalent testing protocols for imported configurations. |
| Precision Grinding Talent Acquisition | Technical workforce capture in aging European machinist pools secures ISO 6336-grade finishing capability. |
| Synthetic Lubrication Architecture Redesign | Sealed-for-life units meet EPA efficiency standards and EU Green Deal loss thresholds without maintenance intervals. |
Research Methodology
Operator-level perspectives from wind turbine nacelle engineers, automated manufacturing line maintenance directors, precision grinding machinists, and aftermarket procurement managers anchored the qualitative base for this study. Primary fieldwork combined with secondary validation from customs trade data, AGMA technical standards documentation, EPA efficiency filing records, and SEC 10-K disclosures from industrial technology groups. Bottom-up unit economics across planetary, helical, bevel, and worm configurations triangulated against top-down market sizing from end-use demand aggregation.
Sensitivity analysis tested forecast robustness across the analysis window against variables including utility-scale wind installation pace, REACH-compliant steel alloy availability, and precision grinding capacity expansion. Segmentation dimensions modeled encompass product type torque density requirements, end-user duty cycle intensity, mounting type installation constraints, and application environmental exposure severity. CAGRs derived from installed base replacement cycles and greenfield capacity additions in China, Germany, and the United States.
Material uncertainties — alloy composition restriction expansions under REACH, precision grinding talent attrition rates, and mobile equipment electrification adoption curves — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and technical workforce pipeline continuity. Recalibration cycles align with material shifts in EU Green Deal implementation timelines and GB standards enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive PTC Heaters Market
Powertrain
Automotive Drivetrain Market
Powertrain
Motor Vehicle Carburetors Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Sway Bar Bushing Market
Powertrain
Global Automotive Engine and Engine Mounts Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Europe Turbocharger Market
Powertrain
Clutch Hub Puller Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Automotive Turbo-Compounding System Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
Automotive Driveshaft Couplings Market